
 De-Icing Agents Market | 2026-2036
De-Icing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
De-Icing Agents Market Intelligence
Market Context
North American salt mine operators is decoupling from traditional seasonal production rhythms by investing in year-round liquid brine infrastructure. BASF leverages its integrated ethylene oxide chain to sustain cost advantages in glycol-based aviation de-icers. Compass Minerals anchors highway supply contracts across the Midwest through its Goderich mine network. Dow competes in premium liquid formulations for commercial aviation, where product certification requirements create defensive moats.
Technical Definition and Segments
De-icing agents are hygroscopic or exothermic chemical formulations, typically chloride salts or acetate-based organic compounds, applied to eliminate frozen precipitation or prevent ice nucleation on surfaces by depressing the freezing point of water. Calcium chloride generates heat through exothermic dissolution, making it effective at lower ambient temperatures than sodium chloride, while potassium acetate offers reduced corrosion profiles for sensitive aviation alloys. Sodium chloride occupies the largest volume share in road maintenance due to its low unit cost and abundant supply, though magnesium chloride is gaining traction in mining and industrial applications where dust suppression dual-use justifies premium pricing. Liquid formulations are expanding fastest in aviation as pre-wetting and anti-icing spray systems displace granular hand-application methods.
Regulatory Outlook
The EPA enforces National Pollutant Discharge Elimination System permits that limit chloride runoff into watersheds, compelling state DOTs to evaluate acetate and formate alternatives. FAA certification standards under SAE AMS 1431 and 1435 govern aviation de-icer performance, creating compliance barriers for uncertified suppliers. Stakeholders must monitor evolving state-level groundwater protection rules, as Vermont and New Hampshire have already imposed seasonal chloride load caps that foreshadow broader regulatory tightening.
Market Dynamics
Aviation sector procurement of potassium acetate formulations is expanding as airports prioritize runway safety and corrosion-sensitive alloy protection. EPA stormwater discharge regulations are pushing municipalities toward lower-corrosion chloride alternatives, reshaping formulation preferences across highway maintenance contracts.
Growth Catalysts
- SAE AMS 1431 Certification Mandates:FAA certification standards govern aviation de-icer performance, compelling airports to source certified liquid formulations and excluding uncertified suppliers from commercial contracts.
- Freeze-Thaw Cycle Intensity:The United States Great Lakes region drives seasonal volume spikes as state DOTs stockpile de-icing agents ahead of extreme weather events.
- Potassium Acetate Adoption:Airports are switching from urea-based formulations to potassium acetate for reduced environmental impact and improved low-temperature performance on runways.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Glycol-based aviation de-icers depend on ethylene oxide supply chains concentrated in Gulf Coast petrochemical complexes, exposing producers to hurricane disruption risk.
- Chloride Runoff Limits:Vermont and New Hampshire impose seasonal chloride load caps under state groundwater protection rules, constraining sodium chloride application volumes in municipal contracts.
- Magnesium Chloride Substitution Pressure:Mining and industrial dust suppression applications are diverting magnesium chloride volumes away from road maintenance channels.
Strategic Opportunities
- Pre-Wetting System Deployment:Liquid brine infrastructure investments enable year-round production decoupled from seasonal salt mine rhythms, capturing highway maintenance contracts.
- Acetate Formulation R&D:State DOT evaluation of acetate and formate alternatives under EPA NPDES permit pressure opens formulation substitution windows.
- Aviation Anti-Icing Automation:Spray system automation displaces granular hand-application methods, creating demand for precision-delivery liquid formulations.
Industry Challenges
- SAE Certification Timeline Compression:New entrants face extended laboratory testing and field validation periods to achieve AMS 1435 approval for commercial aviation supply.
- Legacy Brine Infrastructure Integration:Municipalities must retrofit existing salt storage and distribution networks to handle corrosive liquid acetate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | De-Icing Agents Market |
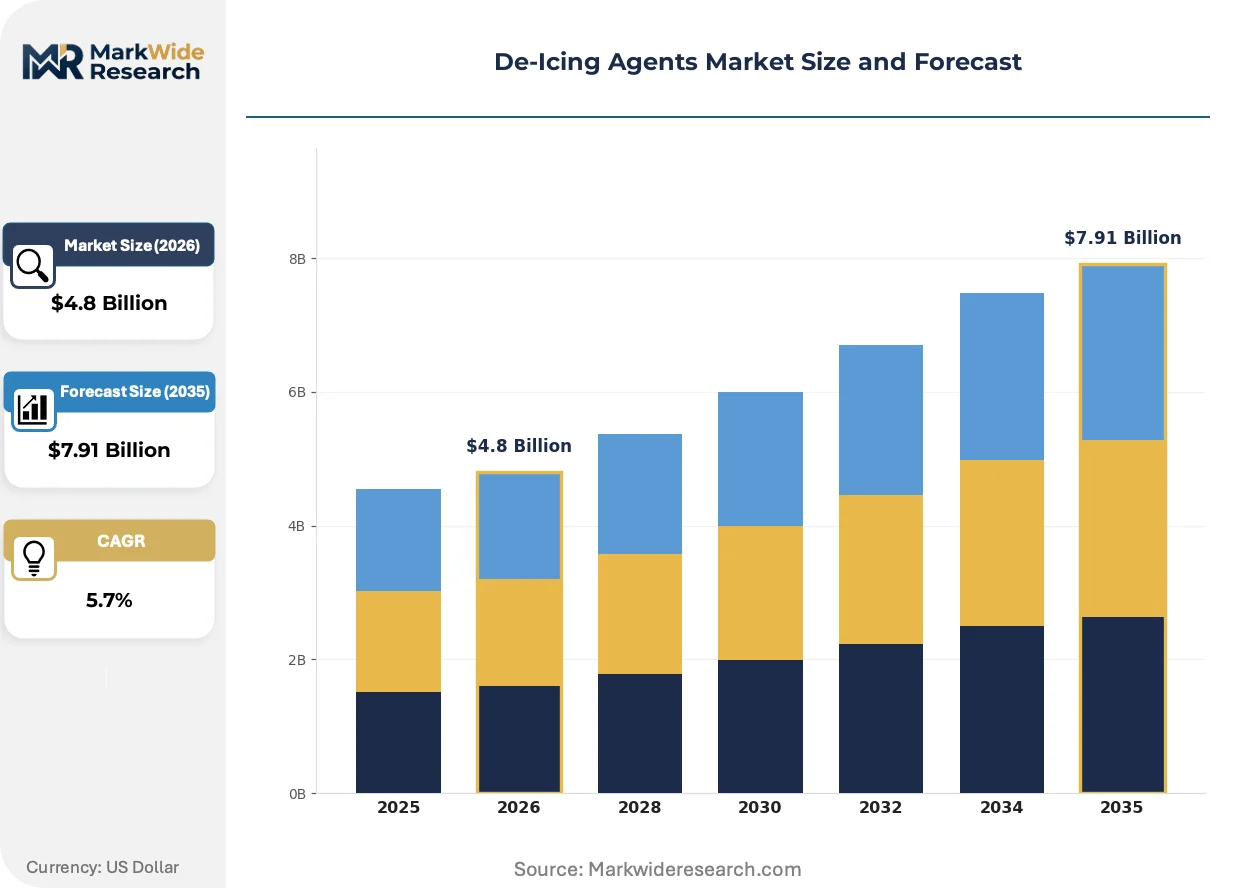
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sodium Chloride, Calcium Chloride, Potassium Acetate, Magnesium Chloride Application: Aviation, Road Maintenance, Industrial, Roofing Form: Liquid, Powder, Granular, Pellet End User: Transportation, Construction, Mining, Agriculture |
| Companies Covered | Clariant, BASF, Dow, Kilfrost, LyondellBasell Industries, Proviron Holding, Cryotech Deicing Technology, Inland Technologies, Compass Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
De-Icing Agents Market Strategic Shifts & Innovations
Formulation chemistry and application technology are converging to reduce environmental load while maintaining performance thresholds. Suppliers are repositioning around certification barriers and liquid delivery infrastructure.
Smart spray systems equipped with real-time weather sensors and automated calibration are integrating into airport ground operations. These systems enable precise application rates based on ambient temperature, wind speed, and precipitation type. Major hub airports in the United States and Germany are adopting these technologies to reduce chemical over-application and comply with environmental discharge permits.
The EPA enforces National Pollutant Discharge Elimination System permits that limit chloride runoff into watersheds, compelling state DOTs to evaluate acetate and formate alternatives. This regulatory pressure is accelerating formulation substitution in highway maintenance contracts. Municipalities in the Great Lakes region are piloting potassium acetate blends to preempt stricter seasonal load caps.
Airport procurement departments are consolidating supplier relationships around dual-certified providers capable of delivering both AMS 1431 and AMS 1435 compliant products. This consolidation reduces vendor management overhead but raises barriers for specialized single-product suppliers. The shift is most visible at major United States hub airports and select Canadian facilities undergoing infrastructure modernization.
De-Icing Agents Market Segmentation
De-icing agent procurement patterns diverge sharply across chemical types, application environments, and physical delivery forms. Understanding these fault lines reveals where formulation premiums command pricing power versus where commodity logistics dominate contract awards.
Type:
Cost sensitivity and corrosion tolerance separate buyers across chemical categories, with aviation alloys demanding premium acetate formulations while highway budgets prioritize bulk chloride economics.
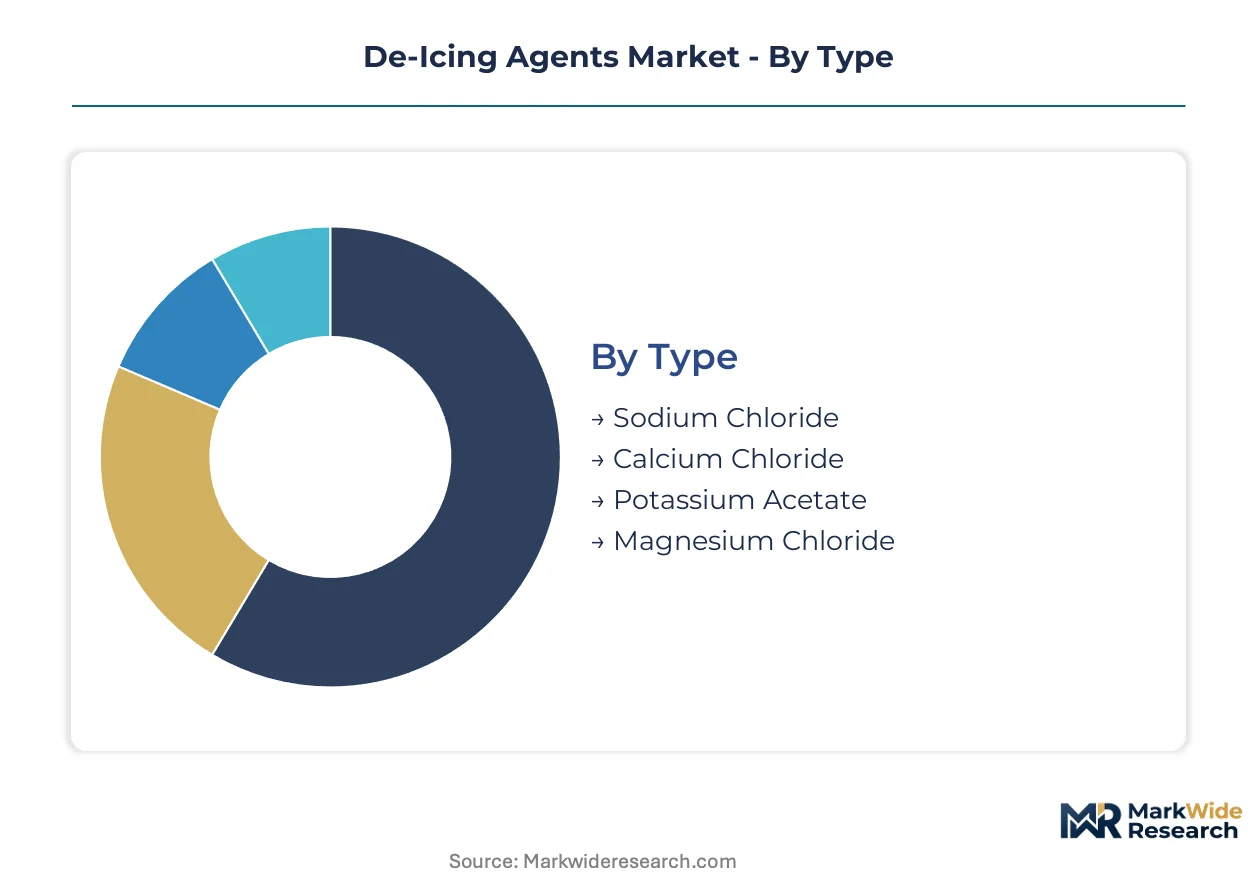
- Sodium Chloride:Rock salt remains the baseline formulation for municipal highway contracts, sourced from underground deposits across Ohio, New York, and Michigan. State DOTs in the Great Lakes region stockpile massive seasonal volumes ahead of freeze-thaw cycles, though EPA stormwater discharge permits are beginning to constrain application rates in watershed-sensitive zones.
- Potassium Acetate:Organic salt formulations command aviation sector premiums due to SAE AMS 1431 certification requirements and reduced corrosion profiles for airframe alloys. Runway safety managers at major hub airports are consolidating procurement around dual-certified liquid suppliers capable of delivering both anti-icing and de-icing specifications.
- Calcium Chloride:Exothermic dissolution properties extend effective temperature range below sodium chloride thresholds, justifying premium pricing for critical infrastructure applications.
- Magnesium Chloride:Hygroscopic characteristics suit mining dust suppression dual-use cases, diverting volumes from traditional road maintenance channels.
Volume sits with sodium chloride; growth tilts toward potassium acetate.
Application:
Regulatory certification intensity varies dramatically by surface type, with aviation facing FAA mandates while industrial users operate under lighter compliance burdens.
- Road Maintenance:Highway departments represent the largest absolute consumption channel, deploying granular and pre-wet liquid formulations across bridge decks, interstates, and municipal streets. Vermont and New Hampshire chloride load caps are forcing formulation experimentation ahead of anticipated broader tightening.
- Aviation:Commercial airports mandate SAE-certified liquid products for both anti-icing and de-icing operations, with automated spray systems displacing manual granular application. German hub airports and select Canadian facilities are piloting smart calibration technologies to reduce chemical over-application.
- Industrial:Mining operations and manufacturing facilities apply magnesium chloride for dust suppression alongside seasonal ice control, creating year-round demand stability absent in weather-dependent segments.
- Roofing:Residential and commercial building maintenance represents a niche channel with limited standardization and price-sensitive spot purchasing.
Contract value concentrates in aviation; expansion is steepest in road maintenance acetate substitution.
Form:
Physical state determines storage infrastructure requirements and application equipment compatibility, locking in customer relationships through capital investment cycles.
- Liquid:Brine formulations enable precision application through pre-wetting and spray systems, with North American salt operators investing in year-round production infrastructure to decouple from seasonal mining rhythms. Aviation sector automation is accelerating liquid displacement of legacy granular methods.
- Granular:Traditional rock salt dominates highway stockpiles due to established spreading equipment fleets and lowest unit procurement costs.
- Powder:Fine particle sizing suits specialized industrial blending and select roofing applications with limited volume scale.
- Pellet:Compressed formulations reduce bounce and scatter during highway application, improving material retention on road surfaces.
Granular holds installed base; liquid gains share fastest through aviation automation and pre-wet highway systems.
End User:
Budget authority and procurement sophistication range from centralized state DOT bidding to fragmented construction site purchasing.
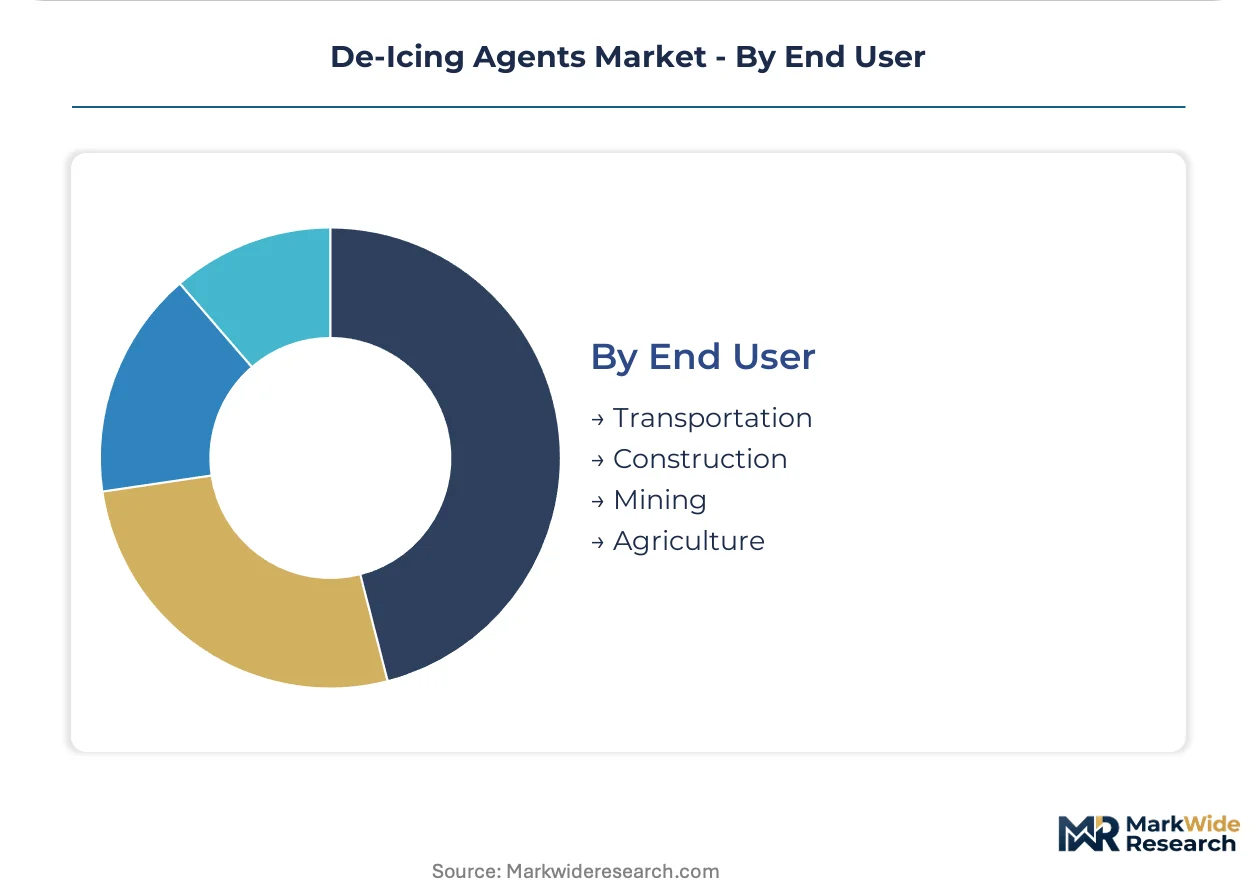
- Transportation:State and municipal departments aggregate the largest contract volumes, with multi-year highway maintenance agreements and airport procurement consolidation favoring established certified suppliers.
- Mining:Dust suppression dual-use justifies magnesium chloride premiums, with year-round consumption smoothing seasonal revenue volatility.
- Construction:Project-based purchasing concentrates in cold-climate commercial development, with limited loyalty to specific formulations.
- Agriculture:Farm and livestock operations represent a price-sensitive residual channel with minimal specification requirements.
Transportation commands procurement scale; mining offers the most stable demand profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salt deposits beneath the Great Lakes anchor North American supply chains, while European petrochemical corridors feed glycol production for aviation formulations. Demand clusters along freeze-thaw intensity gradients, with regulatory pressure reshaping procurement geography.
United States
State DOTs across the Great Lakes corridor stockpile sodium chloride ahead of extreme winter cycles, with Michigan and Ohio mines supplying bulk highway contracts. EPA stormwater discharge permits constrain chloride application rates in watershed-sensitive zones, pushing Vermont and New Hampshire toward seasonal load caps. Chicago O'Hare and Detroit Metro airports drive potassium acetate procurement for SAE-certified runway operations.
Canada
The Goderich mine network on Lake Huron feeds cross-border highway maintenance contracts, with liquid brine infrastructure investments decoupling production from seasonal rhythms. Environment and Climate Change Canada monitors chloride loading in the Great Lakes basin, pressuring Ontario municipalities to pilot acetate blends. Toronto Pearson and Calgary International anchor aviation formulation demand in the Prairie provinces.
Germany
Frankfurt and Munich hub airports deploy smart spray calibration systems to reduce chemical over-application under EU environmental discharge frameworks. The country's chemical industry supplies ethylene oxide derivatives for glycol-based aviation de-icers, with KBA transportation safety standards governing highway formulation approvals. Bavarian and North Rhine-Westphalian municipalities test potassium formate alternatives on critical bridge infrastructure.
China
MIIT standards govern industrial chemical deployment for mining dust suppression and seasonal road maintenance across northern provinces. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate demand for magnesium chloride dual-use applications. NMPA-aligned environmental regulators in Shandong and Liaoning impose runoff controls on chloride-intensive highway operations near coastal watersheds.
Japan
METI energy security frameworks prioritize domestic salt stockpiling for critical infrastructure resilience, with Hokkaido and Tohoku regions facing intensified freeze-thaw cycles. JIS standards specify corrosion limits for bridge deck applications, favoring calcium chloride formulations on critical expressway links. Narita and Haneda airports source SAE-compliant liquid products through specialized chemical trading houses in the Kanto region.
De-Icing Agents Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue certification-heavy aviation niches and acetate formulation specialization. The supplier base stratifies around feedstock access, with integrated petrochemical groups commanding glycol supply chains and regional salt operators anchoring highway bulk contracts. Three archetypes dominate: vertically integrated chemical conglomerates, mine-to-market mineral specialists, and aviation-certified formulation houses. Competitive intensity concentrates on SAE certification acquisition and liquid brine infrastructure deployment.
Among European chemical conglomerates, BASF and Clariant exemplify integrated supply chain positioning, while Dow occupies a North American anchor role in premium liquid formulations. Compass Minerals represents the mine-to-market archetype through its Goderich salt network. These three sit within distinct competitive vectors—petrochemical integration, certification depth, and mineral resource control—rather than direct product rivalry.
| Leading Market Players |
|---|
| Clariant |
| BASF |
| Dow |
| Kilfrost |
| LyondellBasell Industries |
| Proviron Holding |
| Cryotech Deicing Technology |
| Inland Technologies |
| Compass Minerals |
| Others |
Cost & Logistics Intelligence
Captive ethylene oxide production at Gulf Coast petrochemical complexes anchors BASF's cost position in glycol-based aviation de-icers while insulating pricing power from feedstock volatility. This upstream control separates integrated chemical conglomerates from formulation houses sourcing ethylene oxide on spot markets, creating durable margin structures in SAE-certified product tiers.
Pricing Analysis
Warranty and technical service bundling differentiates aviation-certified suppliers from commodity chloride producers, with SAE AMS 1431 validation included in premium liquid formulations. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified aviation suppliers from regional highway contractors and unbranded bulk salt distributors. Cost compression in sodium chloride highway contracts is intensifying because state DOTs face seasonal chloride load caps under EPA NPDES permits. Municipal procurement teams exhibit highest price sensitivity, while airport safety managers prioritize corrosion performance over unit cost.
Supply Chain Analysis
Direct-to-airport contracts handle commercial aviation demand, while distributor networks manage highway maintenance procurement across fragmented municipal buyers. Supply concentrates in the United States Great Lakes region, China, and Germany, with underground salt deposits anchoring chloride production and petrochemical corridors feeding glycol derivatives. Raw material flows draw from ethylene oxide, potassium carbonate, and magnesium-rich brine deposits. Single-source vulnerability runs through Gulf Coast ethylene oxide complexes exposed to hurricane disruption. Distribution runs through liquid brine terminals, bulk salt stockpiles, and specialized chemical trading houses serving aviation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAE certification capacity constraints prop pricing premiums, as laboratory validation timelines and field testing requirements limit qualified supplier expansion. This bottleneck sustains margin structures for incumbent certification holders.
For Market Incumbents: Extend certification coverage across both AMS 1431 and AMS 1435 specifications to capture airport procurement consolidation trends. Deepen backward integration into ethylene oxide or potassium carbonate feedstocks to defend against Gulf Coast supply disruption. Prioritize liquid brine infrastructure deployment in the Great Lakes corridor to decouple from seasonal mining rhythms and secure multi-year highway contracts. For New Entrants and Emerging Players: The price-point gap between SAE-certified aviation formulations and unbranded highway chloride creates white-space for acetate-based intermediate tiers targeting municipal bridge deck applications. Target Vermont and New Hampshire municipalities piloting potassium acetate blends under seasonal chloride load caps. Pursue co-manufacturing arrangements with established liquid formulation houses to bypass capital-intensive certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking aviation certification depth or mine-to-market mineral specialists expanding liquid formulation capabilities. Long-term viability favors suppliers with dual feedstock flexibility and established EPA compliance track records. Monitor state-level groundwater protection rule expansions beyond Vermont and New Hampshire as inflection indicators for acetate formulation substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| SAE Dual Certification Investment | AMS 1431 and 1435 validation unlocks airport procurement consolidation at Chicago O'Hare and Detroit Metro. |
| Liquid Brine Infrastructure Expansion | Year-round production decouples Compass Minerals from seasonal Goderich mine rhythms. |
| Acetate Formulation R&D Partnerships | State DOT evaluation of potassium acetate alternatives accelerates under EPA NPDES permit pressure. |
| Smart Spray System Integration | Automated calibration at Frankfurt and Munich airports reduces chemical over-application compliance costs. |
| Backward Integration into Ethylene Oxide | BASF's captive Gulf Coast supply insulates aviation de-icer margins from hurricane disruption risk. |
Research Approach
Document review covered EPA NPDES permit filings, FAA SAE certification databases, and state DOT procurement records, complemented by interviews with airport operations directors, highway maintenance procurement managers, and chemical plant technical leads. Secondary validation drew from customs trade data, ACC industry reports, and SEC 10-K disclosures of listed mineral and chemical producers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical consumption patterns with expert panel inputs on regulatory trajectory shaped the projection framework. Segmentation dimensions included chemical type, application environment, physical form, and end-user procurement sophistication. CAGRs were derived through regression analysis of freeze-thaw cycle intensity, certification mandate adoption curves, and chloride runoff constraint propagation. Industry-specific inputs incorporated SAE validation pipeline backlogs and liquid brine infrastructure deployment timelines.
Inputs from airport procurement databases and state DOT contract registries were available through the study window; gaps in real-time inventory positioning introduce uncertainty bands around seasonal volume spike timing. Forecasts reflect assumptions about EPA enforcement consistency and state-level groundwater rule diffusion. Practitioners should monitor Vermont and New Hampshire chloride load cap enforcement outcomes and Great Lakes basin freeze-thaw frequency anomalies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Glycol Ether Market
Chemicals
Tin Chemicals Market
Chemicals
Europe Biguanide Market
Chemicals
Morpholine Market
Chemicals
Diethyl Sulfate Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Heptaldehyde Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Fine Chemicals Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Guaiazulene Market
Chemicals
Aluminum Phosphide Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Hydrophobing Agents Market