
 Imaging Chemicals and Materials Market | 2026-2036
Imaging Chemicals and Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Imaging Chemicals and Materials Market Foresight
EU REACH chemical registration requirements is consolidating supplier qualification protocols across the imaging chemicals value chain. BASF SE leverages its integrated pigment and polymer portfolio to sustain European photoresist supply security. FUJIFILM Holdings Corporation anchors medical film chemical production through captive silver halide refining capabilities in Japan. DuPont de Nemours competes in semiconductor-grade photoresists with proprietary resin synthesis platforms serving leading foundries.
Imaging chemicals and materials encompass formulated substances including photoresists, developers, etchants, and fixers engineered with controlled molecular weights, purity grades exceeding 99.99 percent for semiconductor applications, and tailored spectral sensitivity profiles. These materials enable pattern transfer in lithography, image fixation in photographic processing, and display panel fabrication across industrial manufacturing systems. Photoresists command the dominant value share within product type segmentation due to irreplaceable roles in sub-7 nanometer chip production, while developers and etchants track closely behind driven by wafer processing intensity. Application segmentation tilts heavily toward semiconductors where margin pools concentrate, with printing plates representing a mature, volume-stable category and LCD applications experiencing selective growth from OLED transition effects.
EMA chemical safety assessments, EPA toxic substance reporting under TSCA, and Japan's METI chemical management frameworks collectively elevate compliance costs while restricting non-compliant market access. REACH substance authorization and EPA PFAS scrutiny specifically target fluorinated photoresist components, forcing reformulation investments across European and North American supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate material substitution timelines and qualification bottlenecks.
Market Dynamics
Semiconductor lithography node advancement below 7 nanometers is compressing qualification cycles for photoresist suppliers while concentrating procurement decisions among Taiwan, South Korea, and Netherlands-based foundry operators.
Growth Catalysts
- Advanced Lithography Nodes:Sub-7nm chip fabrication in Taiwan and South Korea is pulling EUV-grade photoresist volumes. Foundry capital expenditure cycles align with chemical qualification timelines.
- EU F-Gas Regulation:Fluorinated gas phase-out mandates are redirecting display panel etchant demand toward alternative chemistries. European suppliers are capturing reformulation contracts.
- Silver Halide Medical Imaging:Diagnostic film stockpiling in Japan and Germany is sustaining emulsion demand despite digital transition. Hospital procurement committees maintain dual-modality infrastructure.
Market Restraints
- Silver Price Volatility:Medical film emulsion costs track London Bullion Market Association spot prices. Manufacturers lack pass-through mechanisms in fixed-price hospital contracts.
- Photoresist Supply Concentration:Japan and US-based resin synthesis capabilities dominate semiconductor-grade polymer feedstocks. European formulators face single-source dependencies.
- PFAS Regulatory Friction:EPA TSCA reporting and REACH authorization timelines are extending fluorinated photoresist qualification periods. Reformulation R&D cycles now exceed 36 months.
Strategic Opportunities
- India Semiconductor Mission:Gujarat and Tamil Nadu fabrication incentives are creating first-mover photoresist qualification windows. Domestic chemical parks offer tariff advantages.
- OLED Encapsulation Layers:Ink-jet printable barrier materials for flexible displays represent unaddressed formulation demand. Korean panel makers are soliciting development partnerships.
- Green Chemistry Procurement Mandates:EU Green Deal public procurement rules favor bio-based developers and low-VOC fixers. Municipal hospital systems in Germany and France are piloting substitution programs.
Industry Challenges
- EUV Resist Synthesis Expertise:Polymer chemistry PhD scarcity in European universities is constraining R&D team expansion. BASF and Merck KGaA compete for identical talent pools.
- Multi-Jurisdiction Registration Burden:Simultaneous REACH, TSCA, and METI new chemical notifications are stretching regulatory affairs capacity. Smaller formulators defer market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Imaging Chemicals and Materials Market |
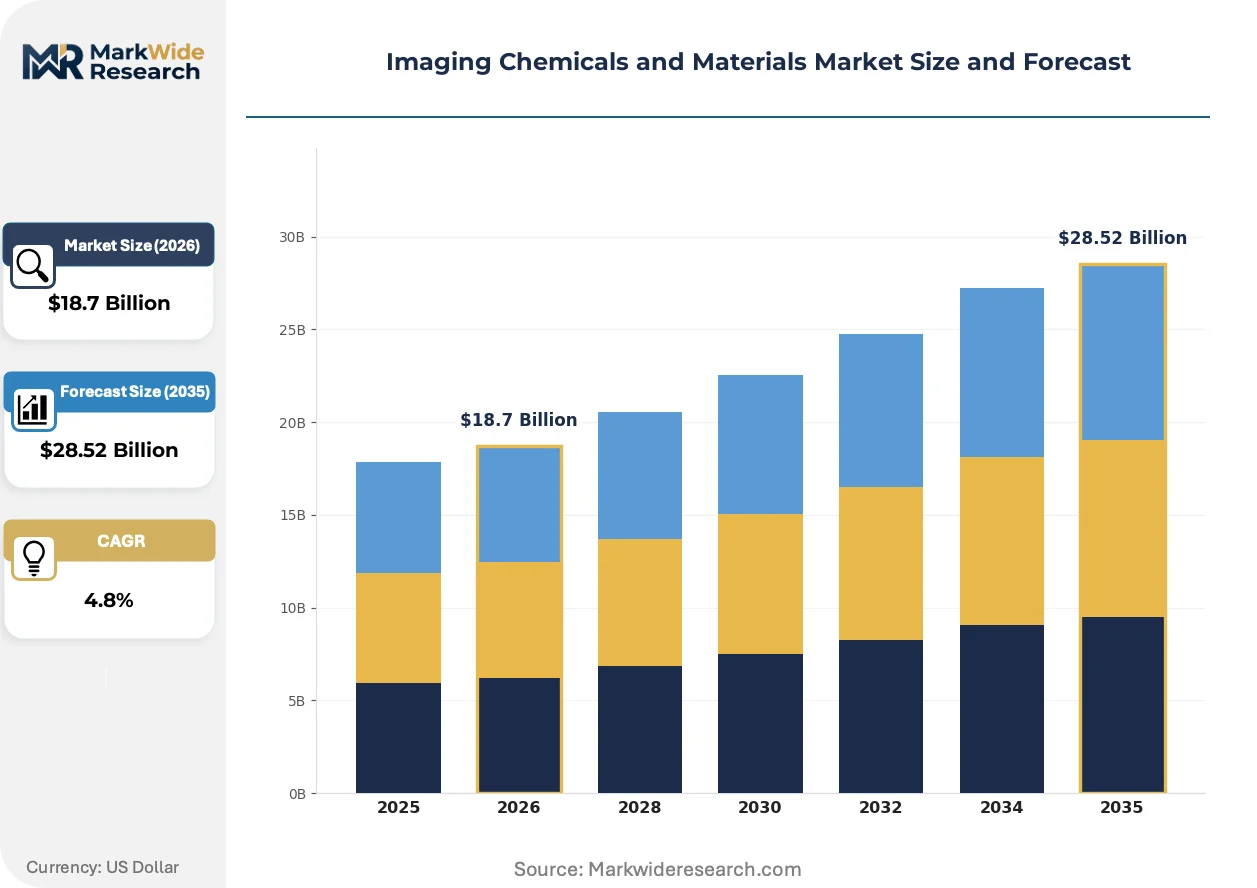
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoresists, Developers, Etchants, Fixers Application: Semiconductors, Printing Plates, Photographic Films, LCDs End Use Industry: Consumer Electronics, Healthcare, Automotive, Aerospace Packaging Type: Drums, Bottles, Sachets, Bulk Containers |
| Companies Covered | BASF SE, FUJIFILM Holdings Corporation, DuPont de Nemours, DIC Corporation, Agfa-Gevaert Group, Kao Corporation, Honeywell International Inc., Merck KGaA, JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Imaging Chemicals and Materials Market Shifts & Advancements
Photoresist architecture is fragmenting into application-specific formulations as lithography equipment divergence between EUV and DUV systems accelerates material specialization requirements.
Metal oxide resists incorporating tin-oxo clusters are modularizing patterning capability for high-NA EUV systems. Intel and Samsung Foundry are qualifying these platforms for 2nm node risk production. The technology is modularizing supplier tiers by separating molecular design houses from formulation integrators.
REACH substance authorization for per- and polyfluoroalkyl substances is forcing photoresist component substitution across European semiconductor supply chains. ECHA's 2023 restriction proposal covers fluorinated surfactants used in topcoat layers. German chemical distributors are stockpiling legacy inventories while qualifying silicone-based alternatives.
Foundry direct procurement of photoresist raw materials is bypassing traditional distributor channels in Taiwan and South Korea. TSMC and Samsung are negotiating polymer resin supply agreements directly with Japanese monomer producers. This pattern is most visible in Hsinchu and Pyeongtaek cluster procurement offices where chemical distributor margins are compressing.
Imaging Chemicals and Materials Market Segmentation
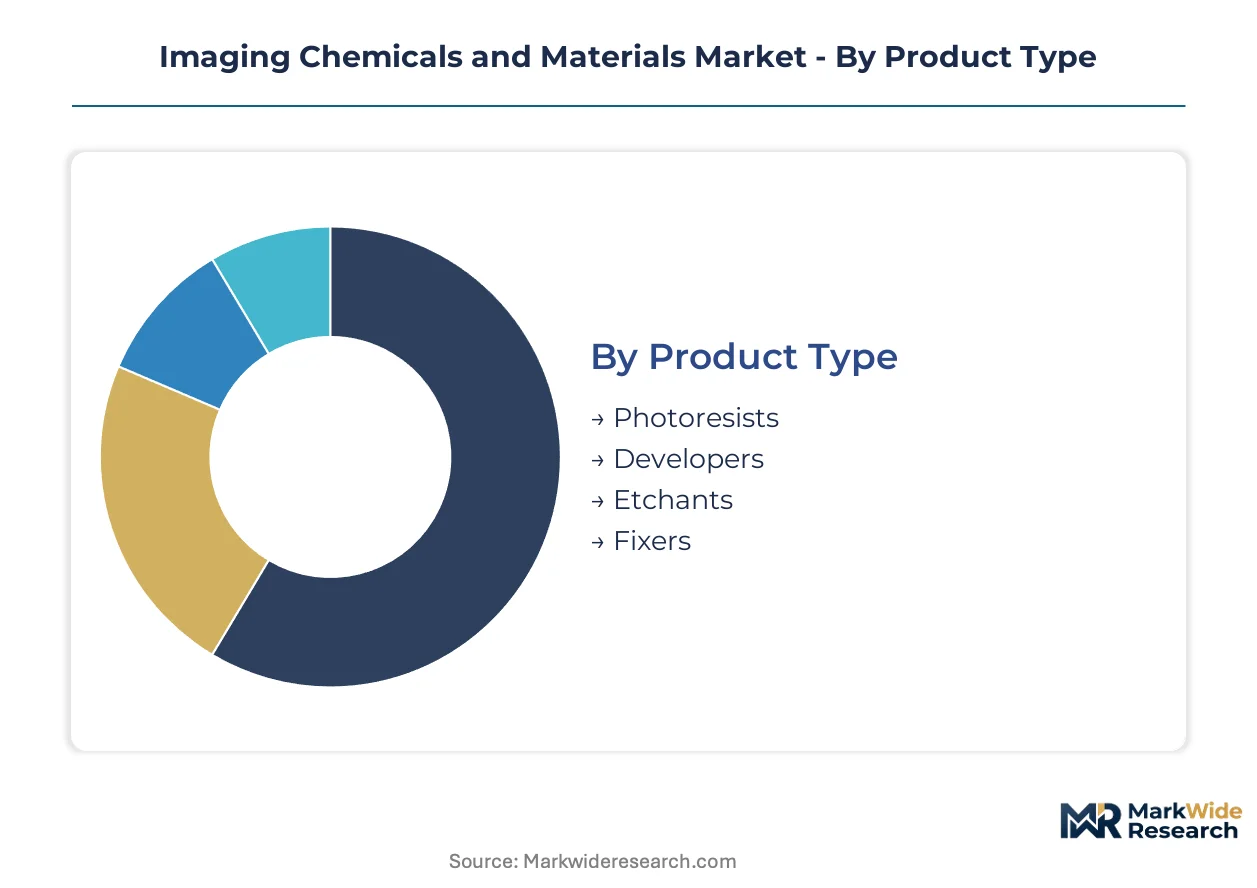
Imaging chemicals and materials fragment across four distinct segmentation axes that determine procurement economics, regulatory exposure, and margin capture. Buyers prioritize purity specifications, volume scale, and hazardous material handling requirements differently across these categories.
Product Type:
Cost tier differentiation separates commodity formulations from precision-engineered semiconductor-grade materials.
- Photoresists:Light-sensitive polymer formulations with molecular weight control and sub-ppm metallic impurity specifications. Demand concentrates in Taiwan and South Korea where TSMC and Samsung Foundry qualify EUV-grade resists for sub-7nm production nodes.
- Developers:Alkaline aqueous solutions containing tetramethylammonium hydroxide or sodium carbonate that selectively dissolve exposed resist regions. Procurement in Japan and Germany tracks lithography equipment installation cycles at foundry and display panel facilities.
- Etchants:Acidic or oxidative formulations for substrate material removal.
- Fixers:Thiosulfate-based solutions stabilizing photographic silver halide images.
Photoresists lead volumes today; developers are gaining share fastest.
Application:
Volume scale separates wafer-processing intensity from mature, replacement-driven categories.
- Semiconductors:Pattern transfer applications spanning logic, memory, and power device fabrication. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek complex drive specialty chemical consumption through advanced node migration.
- Printing Plates:Offset lithography plate sensitization and development chemistries. European commercial print markets in Germany and France sustain demand despite digital substitution pressures.
- Photographic Films:Medical and industrial X-ray emulsion processing.
- LCDs:Thin-film transistor array patterning and color filter fabrication.
Semiconductors lead volumes today; LCD applications are expanding most quickly.
End Use Industry:
Customer type determines specification stringency and qualification timeline tolerance.
- Consumer Electronics:Smartphone, tablet, and wearable device component manufacturing. Korean and Chinese OEM supply chains in Shenzhen and Seoul drive photoresist specifications for display driver ICs.
- Healthcare:Diagnostic imaging infrastructure and medical device sensor fabrication. Japanese hospital procurement committees in Tokyo and Osaka maintain silver halide film stocks alongside digital radiology systems.
- Automotive:Advanced driver-assistance system sensor and power electronics manufacturing.
- Aerospace:Satellite imaging systems and avionics display fabrication.
Consumer electronics leads volumes today; healthcare is climbing the fastest.
Packaging Type:
Supply concentration and hazardous material logistics shape procurement patterns across container formats.
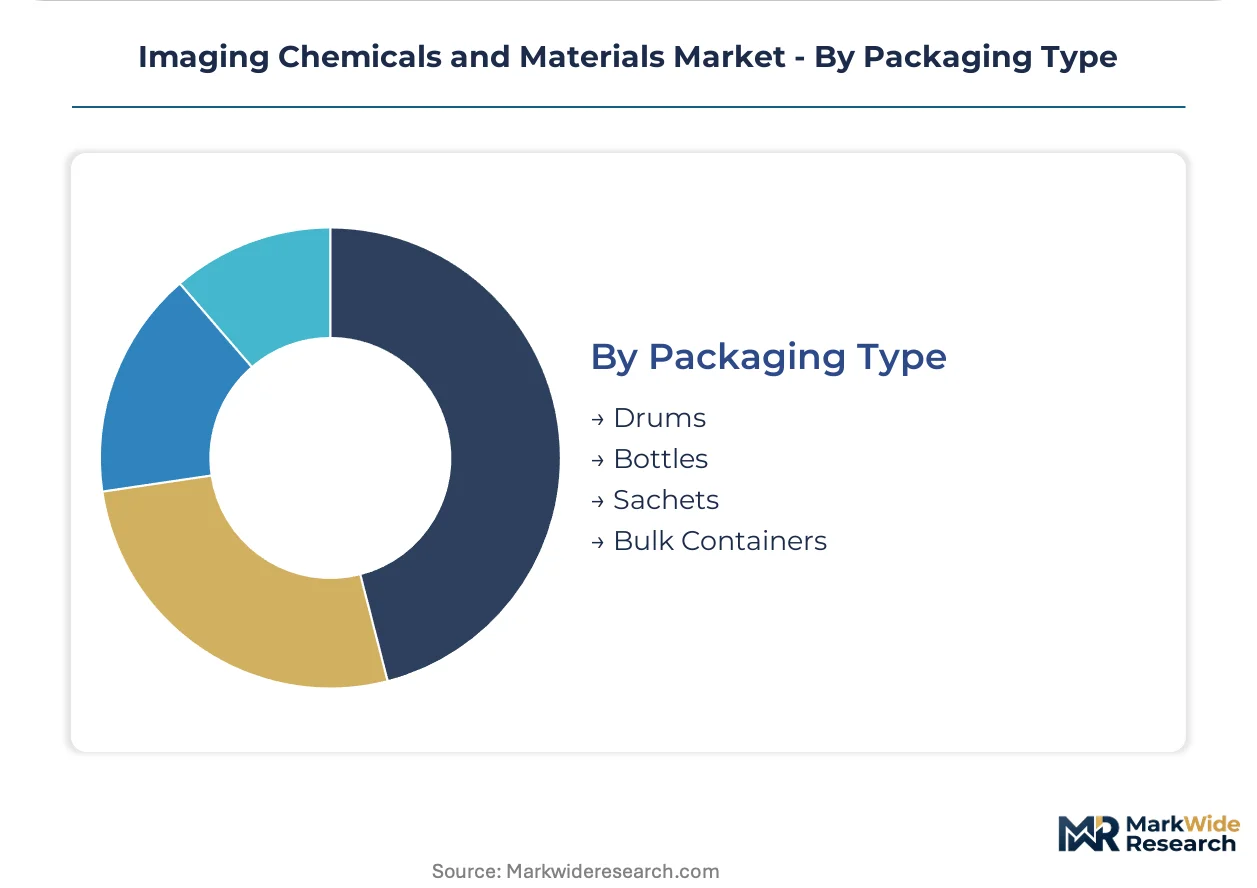
- Drums:Standard 200-liter steel or polyethylene containers for mid-volume semiconductor chemical delivery. Japanese suppliers in Kawasaki and Yokkaichi dominate drum fabrication for photoresist transport.
- Bottles:Amber glass or fluoropolymer bottles for analytical-grade developer and etchant storage. German laboratory supply chains in Düsseldorf specify DIN-certified packaging for research quantities.
- Sachets:Single-use flexible packaging for photographic processing chemicals.
- Bulk Containers:Intermediate bulk containers and tank trucks for foundry-scale photoresist delivery.
Drums lead volumes today; bulk containers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor fabrication clusters established the foundational demand architecture for imaging chemicals. Taiwan and South Korea now concentrate advanced lithography chemical consumption. European regulatory frameworks and North American medical imaging infrastructure sustain mature demand segments.
Taiwan
TSMC's Hsinchu Science Park operations pull EUV-grade photoresist volumes for sub-7nm node production. The National Development Council's semiconductor initiative accelerates chemical supplier qualification timelines. Kaohsiung's emerging 2nm fab cluster is negotiating direct polymer resin procurement agreements with Japanese feedstock producers.
South Korea
Samsung Foundry's Pyeongtaek complex drives specialty photoresist consumption through advanced node migration. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program channels investment into domestic chemical formulation capabilities. Yongin's semiconductor materials R&D zone hosts collaborative qualification labs for EUV resist architectures.
Japan
Silver halide emulsion demand persists through hospital procurement committees maintaining dual-modality diagnostic infrastructure. METI's chemical management frameworks elevate purity specifications for semiconductor-grade materials. Kawasaki and Yokkaichi industrial corridors concentrate photoresist resin synthesis and drum packaging fabrication.
Germany
BASF SE leverages integrated pigment and polymer portfolios to sustain European photoresist supply security. REACH substance authorization and EU F-Gas Regulation compliance requirements consolidate supplier qualification protocols. Düsseldorf laboratory supply chains specify DIN-certified packaging for research-scale developer and etchant distribution.
United States
EPA TSCA reporting requirements and PFAS scrutiny extend fluorinated photoresist qualification periods. DuPont de Nemours competes in semiconductor-grade photoresists through proprietary resin synthesis platforms. Arizona and Texas fab clusters concentrate foundry procurement decisions for North American lithography chemical demand.
Imaging Chemicals and Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade and qualification-timeline dimensions. The supplier base concentrates around integrated chemical conglomerates with captive resin synthesis capabilities and specialized photoresist formulators serving foundry-direct procurement channels. Three archetypes dominate: diversified chemical majors with backward integration into polymer feedstocks, Japanese specialists with lithography-specific formulation expertise, and regional formulators competing on regulatory compliance proximity. Competitive moves center on foundry qualification acceleration and multi-jurisdiction registration capacity expansion.
Among diversified chemical conglomerates, BASF SE and Merck KGaA exemplify the integrated-archetype positioning through combined pigment, polymer, and formulation portfolios. Japanese specialists including FUJIFILM Holdings Corporation and JSR Corporation occupy positions anchored by captive silver halide refining and lithography-specific resin synthesis capabilities. DuPont de Nemours represents the North American premium-tier vector through semiconductor-grade photoresist platforms. These three archetypes—integrated majors, Japanese specialists, and regional premium players—collectively structure competitive dynamics across qualification-dependent procurement channels.
| Leading Market Players |
|---|
| BASF SE |
| FUJIFILM Holdings Corporation |
| DuPont de Nemours |
| DIC Corporation |
| Agfa-Gevaert Group |
| Kao Corporation |
| Honeywell International Inc. |
| Merck KGaA |
| JSR Corporation |
| Others |
Supply & Pricing Matrix
Foundry procurement committees in Taiwan and South Korea operate on long-term contract frameworks that compress spot-market volatility for EUV-grade photoresists while amplifying price leverage for volume commitments. This buyer concentration tilts pricing power toward semiconductor manufacturers with multi-year qualification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade photoresists from display panel etchants and photographic fixers. Price differentiation hinges on metallic impurity certification and foundry qualification status rather than raw material costs alone. Cost compression in standard-tier developers is intensifying because Korean panel makers are consolidating supplier panels. Hospital procurement committees in Japan and Germany exhibit lowest price sensitivity for silver halide emulsions due to dual-modality infrastructure lock-in.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers for polymer resin feedstocks, with formulation integration concentrated in Germany and the United States. Key inputs include naphthalene derivatives, photoacid generators, and fluorinated surfactants facing REACH authorization scrutiny. Single-source vulnerability runs through Japanese monomer production clusters in Kawasaki and Yokkaichi. Distribution runs through foundry-direct procurement channels in Hsinchu and Pyeongtaek, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor lithography node advancement below 7 nanometers provides a stable compounding force, pulling specialty chemical volumes through predictable foundry capital expenditure cycles.
For Market Incumbents: Extend qualification acceleration programs to capture TSMC and Samsung Foundry 2nm node ramp timelines. Deepen backward integration into photoacid generator synthesis to offset fluorinated component substitution costs driven by EPA PFAS scrutiny. Secure polymer resin supply agreements directly with Japanese feedstock producers before foundry procurement committees consolidate supplier panels further. For New Entrants and Emerging Players: EU F-Gas Regulation phase-out mandates in Europe open a window for alternative etchant chemistry formulators to capture reformulation contracts from German and French display panel manufacturers. Target India's Gujarat and Tamil Nadu fabrication incentives for first-mover photoresist qualification windows. Pursue municipal hospital system pilot programs for bio-based developer substitution under EU Green Deal procurement rules. For Investors and Strategic Acquirers: Chemical conglomerates with captive resin synthesis capabilities are the most active acquirer in this space, consolidating formulation specialists to secure foundry-direct channels. Five-to-ten year viability hinges on multi-jurisdiction registration capacity expansion. Watch for ECHA restriction proposal finalization on fluorinated surfactants as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Synthesis | BASF and Merck KGaA secure feedstock autonomy against Japanese monomer supply concentration. |
| EUV Resist Qualification Acceleration | JSR Corporation and DuPont compress foundry approval timelines for 2nm node risk production. |
| Green Chemistry Reformulation Investment | European suppliers capture EU Green Deal procurement preference for bio-based developers. |
| Direct Foundry Procurement Channel Development | TSMC and Samsung negotiate polymer supply agreements bypassing distributor margin capture. |
| Multi-Jurisdiction Registration Capacity Expansion | Formulators secure simultaneous REACH, TSCA, and METI compliance for market access. |
Research Methodology
Bottom-up semiconductor fabrication modeling reconciled against top-down specialty chemical production tracking forms the analytical core of this study. Primary interviews with photoresist formulation directors, foundry procurement managers, hospital purchasing committee chairs, and regulatory affairs specialists at chemical distributors were validated against customs trade data, SEMI equipment spending reports, SEC 10-K filings, and ECHA substance authorization databases. Triangulation across these sources ensures volume estimates align with actual procurement patterns.
Historical trendline analysis of lithography equipment installation cycles and silver halide emulsion consumption patterns established baseline growth trajectories. Segmentation modeling across product type, application, end-use industry, and packaging format dimensions generates granular forecasts. CAGRs were derived from correlation analysis between foundry capital expenditure announcements and chemical qualification timelines, incorporating node migration intensity and regulatory substitution effects.
Revisions become necessary when ECHA restriction proposals on fluorinated substances materialize or when foundry construction delays in Taiwan and South Korea alter equipment installation schedules. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Linear Mercaptans Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Aluminium Chloride Market
Chemicals
Lead Tetracetate Market
Chemicals
Cyclopentylamine Market
Chemicals
Valeryl Chloride Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Fireworks Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Guanidine Carbonate Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Global Hydrogen Fluoride Market