
 5 Dinitroaniline Market | 2026-2036
5 Dinitroaniline Market Size, Share, and Industry Trends Forecast 2026-2036
5 Dinitroaniline Market Outlook
Chinese specialty chemical producers is pivoting toward captive dinitroaniline output to serve domestic agrochemical formulators. BASF SE leverages integrated nitration infrastructure across its European manufacturing network to sustain cost-competitive intermediate supply. Lanxess AG anchors its position through backward integration into nitrobenzene feedstocks, while Eastman Chemical Company differentiates via specialized purification protocols for pharmaceutical-grade material.
5 Dinitroaniline refers to a nitroaromatic compound synthesized through controlled nitration of aniline derivatives, typically yielding a yellow crystalline solid with melting points near 180-190°C depending on isomeric purity, primarily employed as a chemical intermediate for herbicidal active ingredients and azo dye precursors. Herbicides dominate product type demand as pre-emergent weed control formulations consume the majority of merchant volume, while intermediate chemicals represent the fastest-expanding category as pharmaceutical and fine chemical applications diversify beyond traditional agrochemical offtake. Agricultural chemicals application leads absolute consumption, though specialty chemicals channels command superior margin pools due to stringent purity certifications.
EPA registration requirements under FIFRA govern herbicide precursor commerce in the United States, while REACH authorization processes in Europe constrain non-compliant import volumes and elevate documentation burdens for downstream formulators. China's MEE enforces wastewater discharge standards that elevate capital costs for nitration facilities, effectively consolidating production among scaled operators capable of tertiary treatment investments. Stakeholders must monitor evolving residue tolerance thresholds in major importing jurisdictions to preempt reformulation demands and secure long-term supply contracts.
Market Dynamics
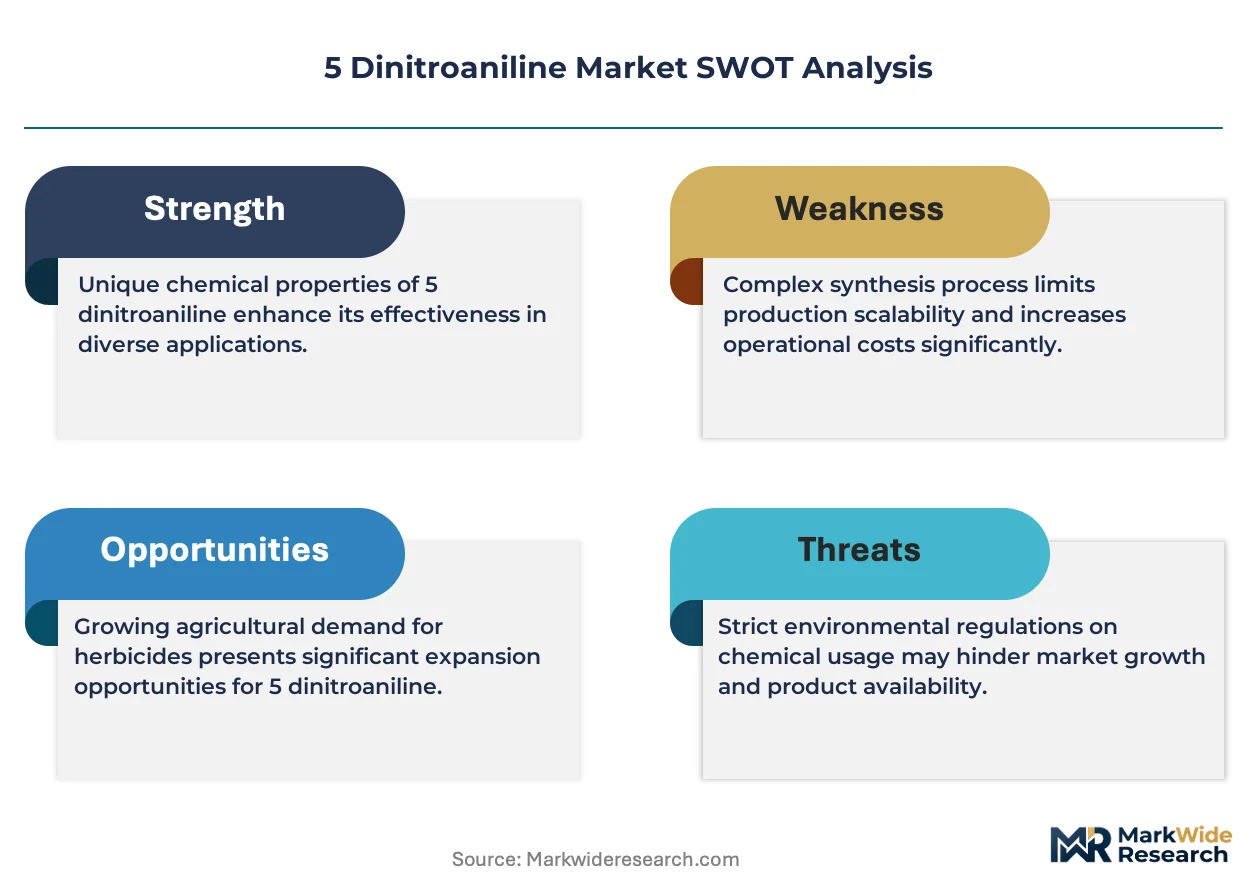
REACH compliance in Europe is tightening purity specifications for agrochemical intermediates, forcing dinitroaniline producers to upgrade purification infrastructure or exit merchant supply. This regulatory compression is concentrating viable production among scaled operators with integrated nitration and tertiary treatment capabilities.
Growth Catalysts
- Herbicide demand in Brazil:Pre-emergent weed control formulations consume the majority of merchant volume as soybean and corn cultivation expands.
- REACH authorization processes:European regulatory constraints on non-compliant imports elevate documentation burdens that favor established suppliers with certified supply chains.
- Captive production scaling:Chinese specialty chemical producers are pivoting toward in-house dinitroaniline output to serve domestic agrochemical formulators.
Market Restraints
- Nitrobenzene feedstock volatility:Input cost fluctuations from benzene-nitric acid coupling compress margin predictability for non-integrated producers.
- China production concentration:Domestic manufacturing scales rapidly, creating import substitution pressure and price compression in export markets.
- Substitution by alternative chemistries:Glyphosate-tolerant crop systems and bioherbicide development threaten traditional dinitroaniline-based pre-emergent demand.
Strategic Opportunities
- Pharmaceutical-grade purification:Stringent purity certifications for fine chemical applications command superior margin pools beyond agrochemical offtake.
- India specialty chemicals channel:CDSCO-regulated pharmaceutical intermediate demand offers underpenetrated growth as domestic formulators diversify supply sources.
- MEE wastewater standards:China's environmental enforcement consolidates production among scaled operators capable of tertiary treatment investments, creating acquisition targets.
Industry Challenges
- Nitration safety engineering talent:Specialized process safety expertise for exothermic nitration operations faces acute scarcity, constraining capacity expansion timelines.
- EPA FIFRA registration timelines:Herbicide precursor commerce documentation burdens extend certification cycles, freezing working capital and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5 Dinitroaniline Market |
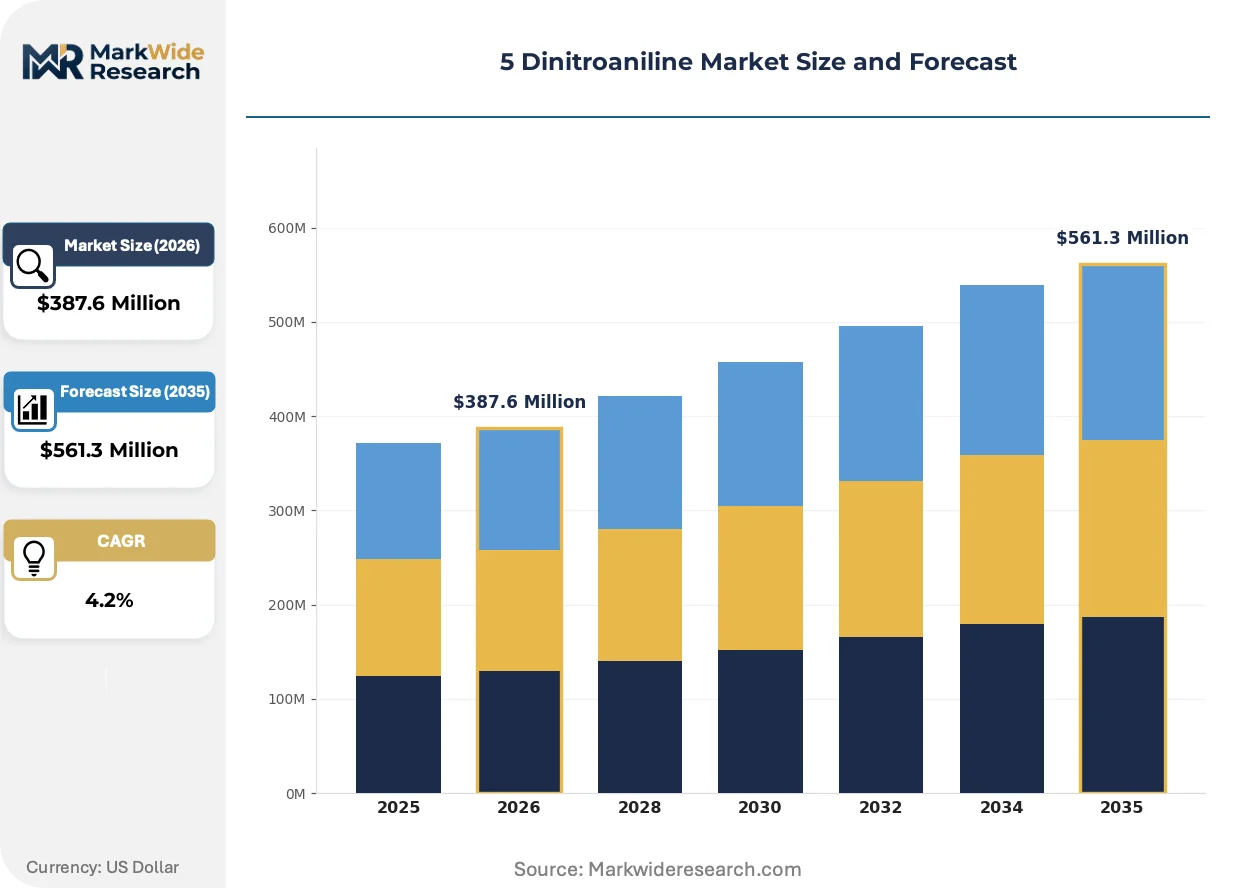
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $561.3 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Intermediate Chemicals, Dyes, Agrochemicals Application: Agricultural Chemicals, Industrial Chemicals, Specialty Chemicals, Pharmaceuticals Packaging Type: Drums, Bags, Containers, Bulk End User: Agriculture, Manufacturing, Research Institutions, Chemical Distributors |
| Companies Covered | BASF SE, Lanxess AG, Eastman Chemical Company, Dow Chemical Company, Huntsman Corporation, Merck KGaA, Tokyo Chemical Industry, Aarti Industries, Mitsubishi Gas Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5 Dinitroaniline Market Strategic Shifts
Process intensification and regulatory digitization are actively rewriting how dinitroaniline producers compete, compressing the viable supplier set while opening premium tiers for certified specialty grades.
Continuous flow nitration technology is rewriting production economics for dinitroaniline synthesis. Agrochemical formulators in China and India are adopting modular flow reactors at pilot scale to replace batch nitration. This shift is compressing capital requirements for entry while elevating safety and yield consistency barriers for incumbent batch operators.
REACH authorization digitization through ECHA's SCIP database is mandating granular substance tracking across European supply chains. Downstream formulators must now document full article composition, elevating documentation burdens for non-integrated importers. Specialty chemical distributors in Germany and France are responding by consolidating supplier panels to pre-certified integrated producers.
Certification-driven procurement consolidation is reshaping buyer-supplier relationships in agricultural chemicals channels. Large-scale herbicide manufacturers are unbundling spot purchasing in favor of multi-year supply agreements with integrated producers holding ISO 14001 and Responsible Care certifications. This pattern is most visible in Brazil and Argentina, where ANVISA-aligned residue tolerance documentation requirements favor pre-qualified supply relationships over price-driven spot markets.
5 Dinitroaniline Market Segmentation
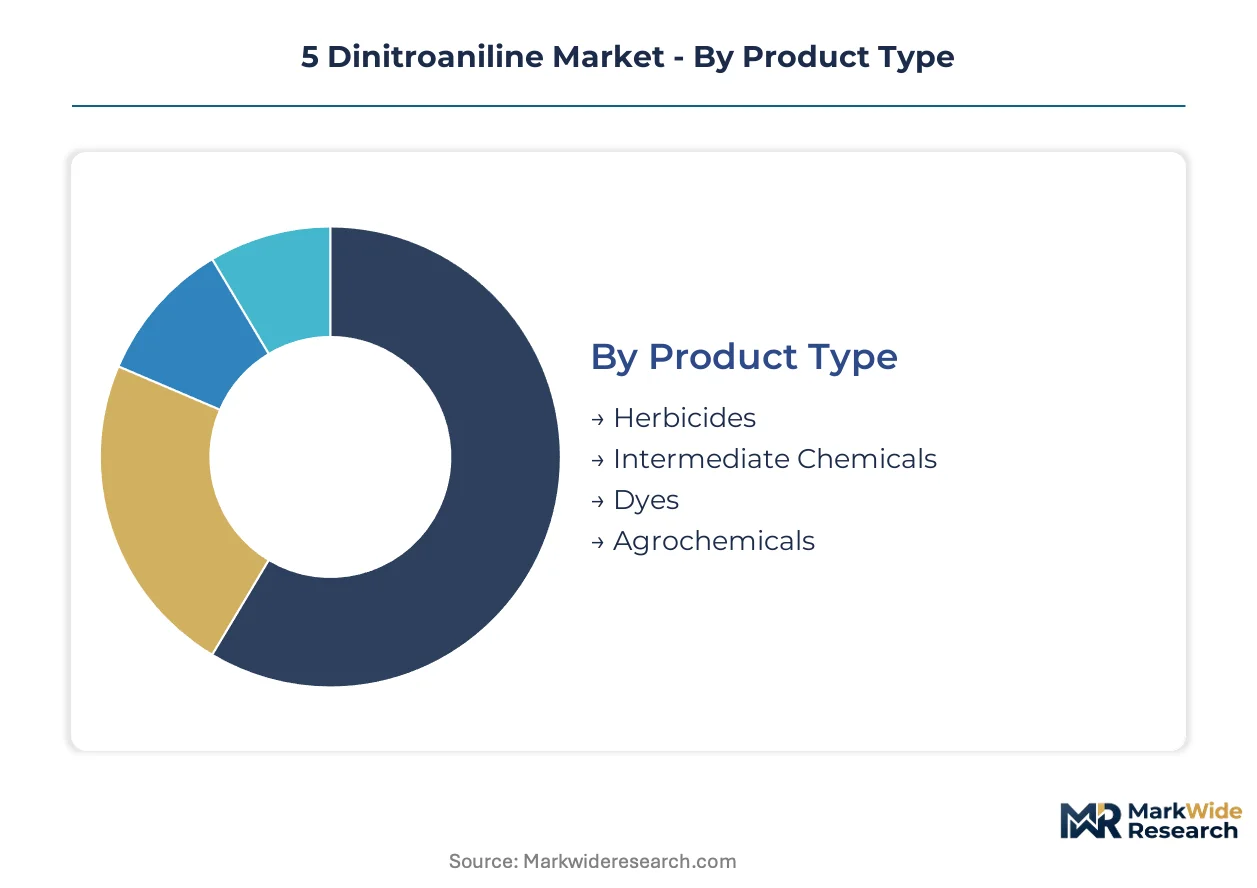
5 Dinitroaniline procurement patterns diverge sharply across product grades and end-use channels. Certification requirements for pharmaceutical versus agrochemical applications create tiered pricing structures that reshape supplier selection criteria.
Product Type:
REACH authorization and EPA FIFRA registration demands vary substantially across product grades, with pharmaceutical specifications commanding the most stringent documentation burdens.
- Herbicides:Technical-grade material with 98-99% purity serves pre-emergent weed control formulations. Brazilian soybean and corn cultivators absorb the majority of volume, though glyphosate-tolerant crop systems exert substitution pressure on traditional dinitroaniline-based chemistry.
- Intermediate Chemicals:Higher-purity grades for downstream synthesis of azo compounds and active pharmaceutical ingredients. Chinese specialty chemical producers are pivoting toward captive output to serve domestic formulators, compressing merchant market opportunities.
- Dyes:Technical material for azo pigment precursors in textile applications.
- Agrochemicals:Broad-spectrum crop protection intermediate grades for integrated formulators.
Leading the category by volume: Herbicides. Growing fastest: Intermediate Chemicals.
Application:
Margin structures align with purity thresholds, with pharmaceutical and specialty chemical channels capturing premium spreads over commodity agricultural offtake.
- Agricultural Chemicals:Dominant consumption channel for pre-emergent herbicide synthesis. ANVISA-aligned residue tolerance documentation in Brazil and Argentina favors pre-qualified supply relationships over spot purchasing.
- Specialty Chemicals:Fine chemical applications with ISO 14001 and Responsible Care certification requirements. CDSCO-regulated pharmaceutical intermediate demand in India offers underpenetrated expansion potential.
- Industrial Chemicals:Process chemicals and polymer additives for manufacturing sectors.
- Pharmaceuticals:GMP-compliant grades for active ingredient synthesis with EMA and FDA validation requirements.
Agricultural Chemicals holds the volume lead. Specialty Chemicals climbs the fastest on certification premiums.
Packaging Type:
Logistics configuration tracks customer scale and regulatory jurisdiction, with bulk formats concentrated among integrated formulators and drum specifications serving distributed procurement networks.
- Bulk:Tanker and railcar delivery for large-scale herbicide manufacturers with on-site storage infrastructure. Chinese MEE wastewater enforcement consolidates viable supply among scaled operators capable of tertiary treatment investments.
- Drums:Standard 200-liter steel packaging for mid-volume chemical distributors and regional formulators. REACH SCIP database mandates elevate documentation burdens for non-integrated European importers.
- Bags:Multi-wall paper or FIBC formats for solid-grade material.
- Containers:Intermediate bulk containers for flexible handling requirements.
Bulk leads on tonnage moved. Drums expand most quickly on distributor channel growth.
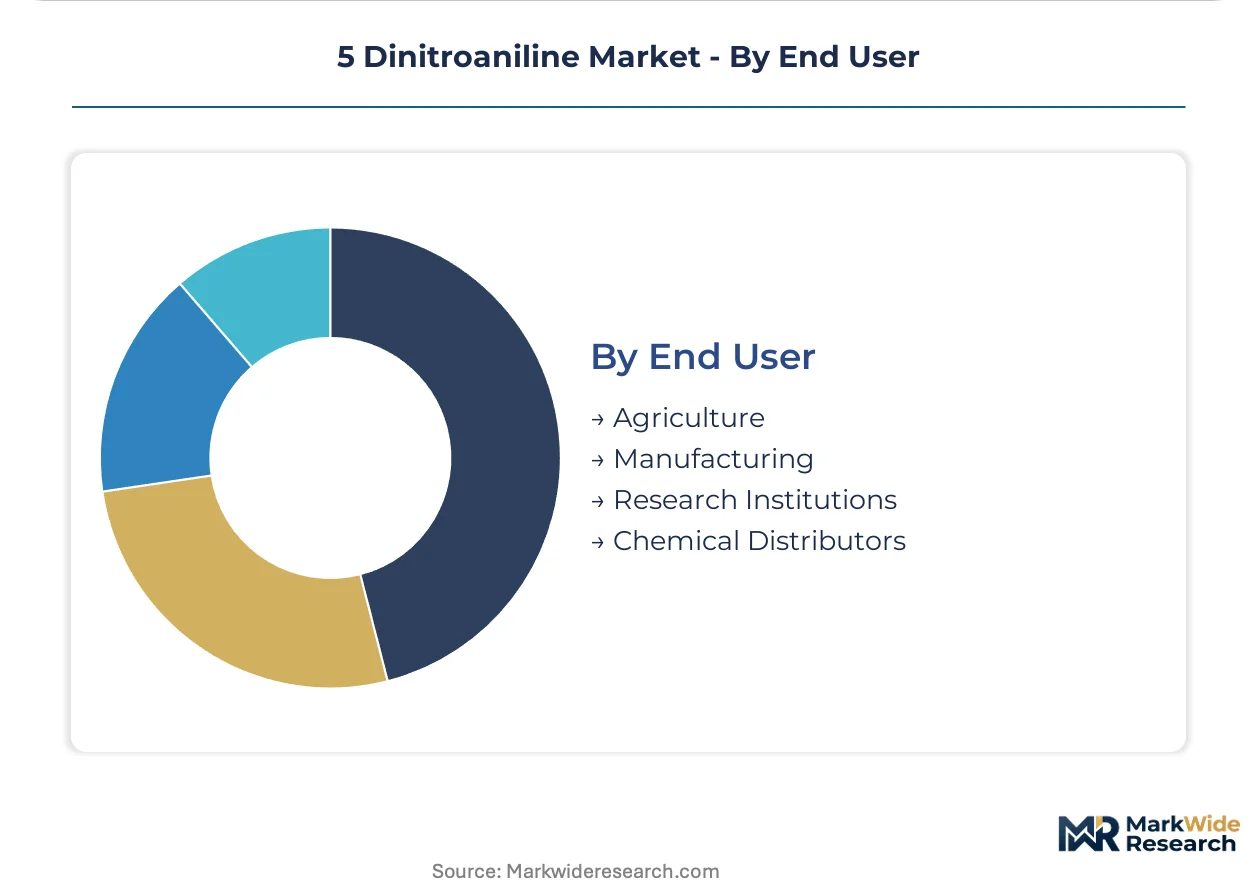
End User:
Customer concentration patterns reflect backward integration trends, with agriculture and manufacturing sectors consolidating procurement around certified integrated producers.
- Agriculture:Herbicide formulators and crop protection companies in Brazil, Argentina, and the US. BASF SE leverages integrated nitration infrastructure to sustain cost-competitive supply against Chinese captive production scaling.
- Manufacturing:Dye and pigment producers, polymer additive compounders. Lanxess AG anchors position through upstream control over nitrobenzene feedstocks.
- Chemical Distributors:Merchant intermediaries serving fragmented regional formulators.
- Research Institutions:Laboratory-scale procurement for pharmaceutical and materials science R&D.
Agriculture dominates absolute offtake. Manufacturing gains share fastest on specialty chemical diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nitrobenzene feedstock availability in the Rhine-Ruhr corridor anchors European production, while benzene refining capacity along the US Gulf Coast underpins North American supply chains. Chinese nitration infrastructure clusters in the Yangtze River Delta and Shandong Peninsula.
China
Domestic agrochemical formulators in Jiangsu and Shandong provinces drive captive production scaling for herbicide intermediates. MEE wastewater discharge standards enforce tertiary treatment investments that consolidate viable supply among operators with environmental compliance infrastructure. The Nantong chemical industrial zone hosts scaled nitration facilities serving downstream crop protection manufacturers.
Brazil
Soybean and corn cultivation expansion in Mato Grosso and Paraná generates pre-emergent herbicide demand that absorbs technical-grade dinitroaniline volumes. ANVISA residue tolerance documentation requirements favor pre-qualified supply relationships over spot purchasing for import clearance. São Paulo state anchors formulation and distribution infrastructure for South American agrochemical markets.
Germany
Integrated chemical producers in North Rhine-Westphalia leverage nitration infrastructure for cost-competitive intermediate supply to European formulators. REACH authorization processes through ECHA constrain non-compliant import volumes and elevate documentation burdens for downstream users. The Leverkusen chemical cluster maintains purification capabilities for pharmaceutical-grade material certification.
United States
Gulf Coast petrochemical complexes in Texas and Louisiana provide benzene-nitric acid coupling for nitrobenzene feedstock integration. EPA FIFRA registration timelines govern herbicide precursor commerce, extending certification cycles for active ingredient approval. Houston-area chemical distributors manage inventory positioning for agricultural chemical channels.
India
CDSCO-regulated pharmaceutical intermediate demand in Gujarat and Maharashtra offers specialty chemical channel expansion beyond traditional agrochemical offtake. BIS quality standards for chemical imports create certification barriers that favor domestic producers with laboratory accreditation. The Ankleshwar industrial estate hosts fine chemical manufacturers diversifying into azo compound precursors.
5 Dinitroaniline Market Competitive Environment
Global majors compete with regional champions across nitration infrastructure and feedstock integration. The supplier base concentrates around integrated chemical conglomerates with backward control over nitrobenzene supply, while merchant specialists occupy purification-intensive specialty grades. Three archetypes dominate: benzene-nitrobenzene integrated producers, agrochemical-forward formulators with captive intermediate output, and fine chemical specialists serving pharmaceutical certification channels. Competitive dynamics center on M&A consolidation of environmental-compliant assets and capacity expansion in low-cost nitration jurisdictions.
Among integrated chemical conglomerates, BASF SE and Lanxess AG exemplify the feedstock-integrated archetype with European nitration network leverage. Eastman Chemical Company occupies a position within the specialty purification tier. Aarti Industries represents the India-based merchant specialist segment. These anchors illustrate how competitive positioning stratifies across integration depth and certification capability rather than scale alone.
| Leading Market Players |
|---|
| BASF SE |
| Lanxess AG |
| Eastman Chemical Company |
| Dow Chemical Company |
| Huntsman Corporation |
| Merck KGaA |
| Tokyo Chemical Industry |
| Aarti Industries |
| Mitsubishi Gas Chemical Company |
| Others |
Value Chain & Pricing Dynamics
MEE wastewater discharge standards in China gate qualified supply access and premium-tier pricing for dinitroaniline producers, consolidating viable merchant capacity among operators with tertiary treatment infrastructure while pharmaceutical-grade certifications command margin spreads beyond commodity agrochemical offtake.
Pricing Analysis
Documentation-bundling separates REACH-certified supply from spot-market material with unbundled compliance costs. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels tracks purity thresholds and certification burdens. Price differentiation hinges on ISO 14001 and Responsible Care credentials versus basic technical specifications. Price erosion runs through technical-grade herbicide intermediates as Chinese captive production scales, while pharmaceutical channels exhibit lowest price sensitivity due to CDSCO and EMA validation requirements.
Supply Chain Analysis
Direct-to-formulator channels handle Brazilian agrochemical demand through pre-qualified supply agreements, while merchant distributors serve fragmented European and Indian procurement networks. Production gravity centers on China, Germany, and India, with nitration infrastructure clustering in the Yangtze River Delta, North Rhine-Westphalia, and Gujarat chemical corridors. Nitrobenzene, aniline derivatives, and nitric acid feedstock supply draws from benzene refining complexes in Texas, Rotterdam, and Singapore. Single-source vulnerability concentrates in Chinese nitration capacity for merchant-market supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward control over nitrobenzene feedstocks determines cost-competitive positioning against Chinese captive production scaling.
For Market Incumbents: Hedge substitution risk from glyphosate-tolerant crop systems by deepening pharmaceutical-grade purification capabilities and securing multi-year offtake agreements with Brazilian formulators holding ANVISA pre-qualification. Anchor cost position through nitration infrastructure consolidation in Rhine-Ruhr or US Gulf Coast corridors with integrated benzene supply.
For New Entrants and Emerging Players: Capture CDSCO-regulated pharmaceutical intermediate demand in Gujarat and Maharashtra by acquiring BIS-accredited laboratory capabilities and targeting fine chemical formulators diversifying beyond Chinese supply dependence. Lead with modular continuous-flow nitration technology to compress capital requirements versus incumbent batch operations.
For Investors and Strategic Acquirers: REACH authorization digitization through ECHA's SCIP database is the leading indicator that supplier-panel consolidation will accelerate, favoring integrated producers with pre-certified supply chains over merchant importers. Target nitration assets with tertiary treatment compliance in China or backward integration into nitrobenzene feedstocks in Europe. Monitor MEE enforcement intensity as the signal for Chinese capacity rationalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Control over nitrobenzene feedstocks insulates margin from benzene-nitric acid coupling volatility. |
| Continuous Flow Nitration Scale-Up | Modular reactor deployment compresses capital requirements while elevating safety barriers for batch incumbents. |
| Pharmaceutical-Grade Certification | EMA and FDA validation unlocks premium pricing tiers beyond commodity agrochemical offtake. |
| Long-Term Supply Agreement | Multi-year contracts with Brazilian formulators secure volume against Chinese captive production substitution. |
| Tertiary Treatment Investment | MEE compliance infrastructure consolidates viable Chinese supply among scaled environmental-compliant operators. |
Study Parameters
Trade databases, chemical industry association filings, and regulatory submission records formed the secondary backbone, cross-referenced with primary interviews involving nitration plant managers, agrochemical procurement leads at Brazilian formulators, distribution channel partners in European specialty chemicals, and technical R&D directors at Indian fine chemical manufacturers. Bottom-up volume triangulation against top-down value estimates validated segment-level outputs.
Historical trendline analysis of nitration capacity additions, feedstock cost movements, and regulatory enforcement intensity informed projection modeling across the analysis window. Segmentation dimensions included product grade tier, end-use application channel, packaging format, and regional production hub cluster. CAGRs derived from elasticity-adjusted demand curves incorporating herbicide formulation trends and pharmaceutical intermediate certification pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese environmental enforcement intensity, Brazilian crop rotation patterns, and glyphosate-tolerant seed adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Integrated Chemistry Systems Market
Chemicals
Flatting Agents Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Deicing Fluid Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Tromethamine Market
Chemicals
Acid Anhydrides Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
South Korea Methanol Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Pentanedione Market
Chemicals
Sodium Methoxide Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Cyclopentylamine Market
Chemicals
South America Construction Chemicals Market
Chemicals
Phenothiazine Market