
 Coagulant Market | 2026-2036
Coagulant Market Size, Share, and Industry Trends Forecast 2026-2036
Coagulant Market Intelligence
The European Union's REACH regulation, combined with EPA rules on sludge disposal in the United States, is realigning the total cost of ownership for water treatment chemicals. Kemira leverages its extensive portfolio of both inorganic and polymeric coagulants to serve diverse municipal and industrial clients. SNF Group specializes in polyacrylamide-based products, dominating the high-performance polymer segment through massive production scale. Ecolab competes by integrating its chemical offerings with water management services for industrial end-users.
Coagulants are chemical agents designed to destabilize colloidal particles suspended in liquids, primarily water. Their primary function involves charge neutralization, which allows fine particles to aggregate into larger, settleable flocs. Traditional inorganic products like alum and ferric chloride represent a mature, high-volume segment, while polymeric coagulants command higher prices for specialized performance. While municipal water treatment remains the largest application, industrial wastewater treatment offers significant growth, particularly in the paper manufacturing and mining sectors.
Global standards for potable water, set by organizations like the WHO, establish a baseline for coagulant use in municipal systems. National bodies such as the US EPA and China's Ministry of Ecology and Environment (MEE) enforce stringent limits on industrial discharge, directly influencing coagulant selection and dosage. Stakeholder decisions will increasingly center on balancing the performance of synthetic polymers against the sustainability profile and lifecycle cost of emerging bio-based alternatives.
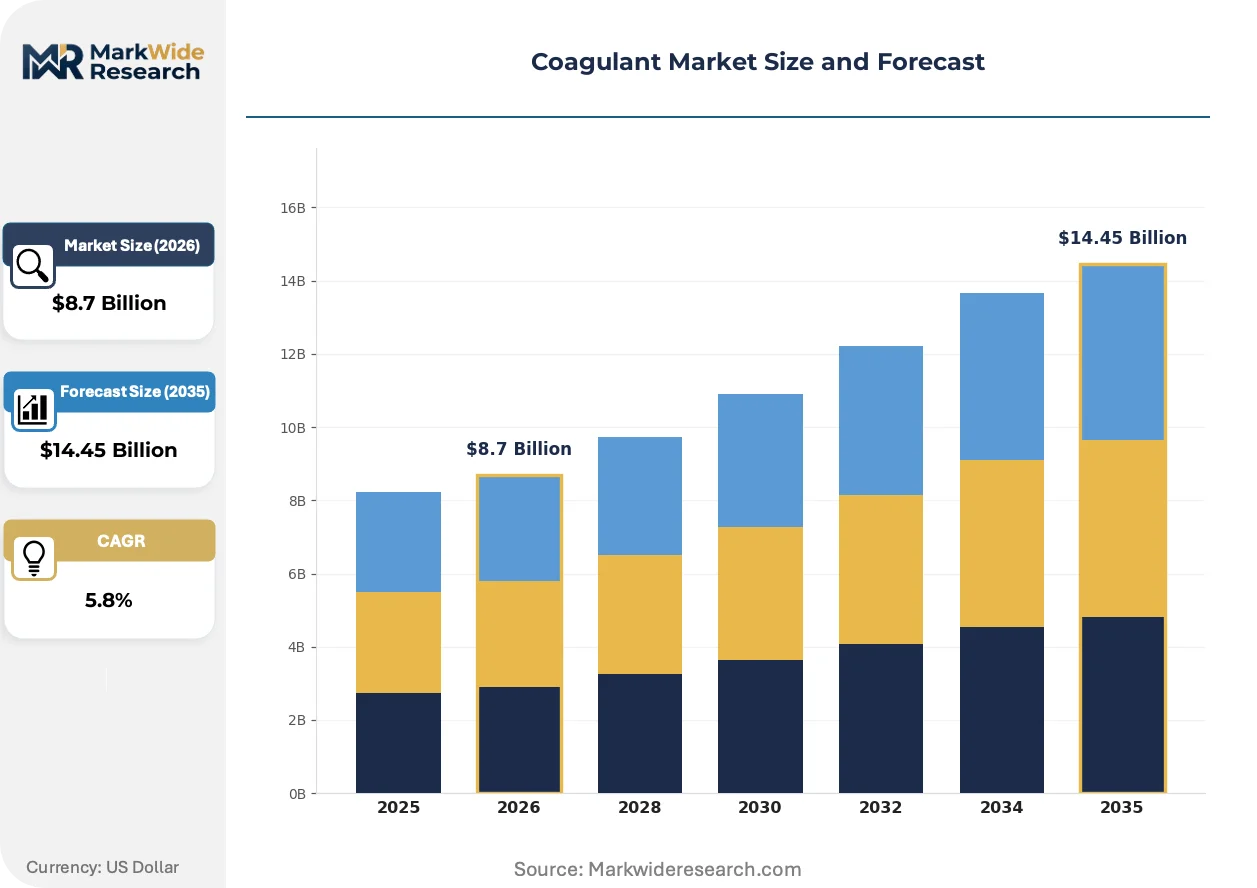
Market Dynamics
The coagulant market's structure is defined by the tension between high-volume inorganic salts and high-performance polymers. Stricter global effluent discharge standards are forcing a re-evaluation of chemical selection based on total treatment cost and sludge management.
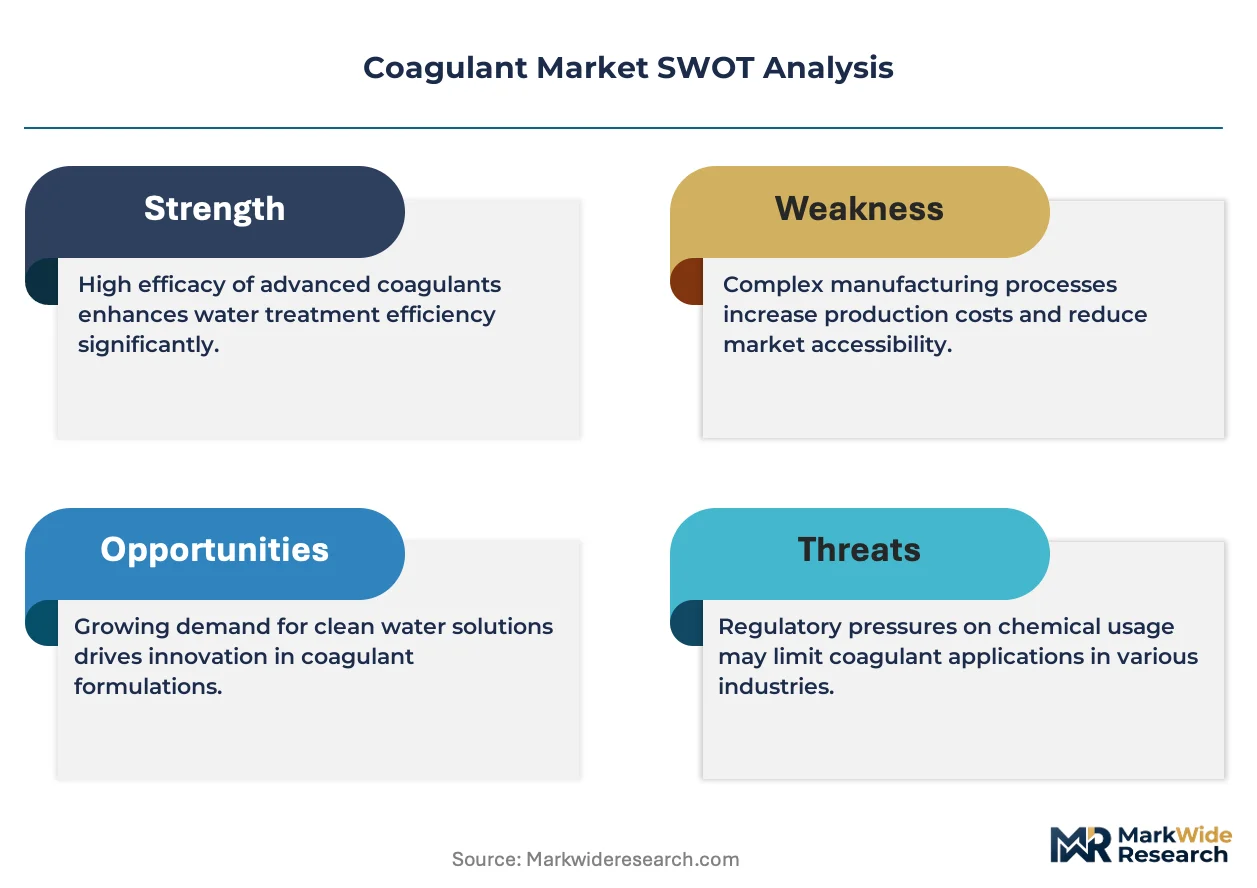
Growth Catalysts
- Industrial Policy:China's MEE policies targeting heavy industry pollution mandate advanced coagulation to meet stringent wastewater discharge limits.
- Urbanization:Municipal infrastructure projects in nations like India to expand access to potable water create sustained demand for foundational coagulants.
- Process Optimization:The paper industry's need for specialized organic polymers to control wet-end chemistry impacts machine efficiency and final product quality.
Market Restraints
- Input Cost Volatility:Prices for inorganic coagulants are directly linked to volatile raw material markets, including bauxite for alum and industrial acids.
- Technology Substitution:Membrane filtration systems can reduce or eliminate the need for chemical coagulation in certain high-purity water treatment applications.
- Logistics Inefficiency:The high water content of liquid coagulants makes long-distance transport economically unviable, increasing landed costs for remote end-users.
Strategic Opportunities
- Bio-Based Alternatives:Coagulants from renewable sources like chitosan and plant starches meet sustainability goals and can create value from agricultural byproducts.
- Sludge Management:Products designed for sludge dewatering help operators meet disposal regulations, such as those set by the US EPA, and reduce transport costs.
- Geographic Expansion:Markets in Southeast Asia represent significant growth potential as investment in water treatment infrastructure accelerates.
Industry Challenges
- Regulatory Compliance:Navigating the complex chemical registration and approval process under frameworks like the EU's REACH can delay market entry for new products.
- System Integration:Integrating advanced polymer dosing systems with legacy infrastructure in older municipal treatment plants often requires significant capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coagulant Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alum, Ferric Chloride, Polymeric Coagulants, Calcium Hydroxide Application: Water Treatment, Wastewater Treatment, Paper Manufacturing, Oil Recovery End User: Municipalities, Industrial Facilities, Agriculture, Mining Delivery Mode: Liquid, Powder, Granular, Tablets |
| Companies Covered | Solenis, Feralco, Kemira, Buckman, Veolia, BASF, SNF Group, Kurita Water Industries, Ecolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coagulant Market Strategic Shifts & Innovations
The evolution of coagulants is increasingly shaped by a dual focus on lifecycle performance and environmental impact. This shift influences product development, regulatory priorities, and the service models through which chemicals are delivered to end-users.
Bio-based coagulants derived from materials like tannins and chitosan function by flocculating suspended solids via natural polymer chains. Food and beverage processors and municipalities are adopting these alternatives to improve their sustainability profile. This technology is expanding into applications historically dominated by synthetic polymers, especially where sludge toxicity and disposal are primary concerns.
Europe's Urban Waste Water Treatment Directive mandates stricter removal of nutrients and micropollutants from municipal effluent. This policy forces treatment plants to upgrade chemical dosing systems, often requiring more advanced coagulants for compliance. The tertiary treatment segment is most affected, driving demand for high-charge cationic polymers to achieve new performance standards.
A transition from simple product sales to total water management service contracts is gaining traction among industrial clients. End-users in sectors like power generation and mining now often outsource chemical management to guarantee water quality outcomes and simplify compliance. This model is most prominent in North America and Europe where operational efficiency pressures are highest.
Coagulant Market Segmentation
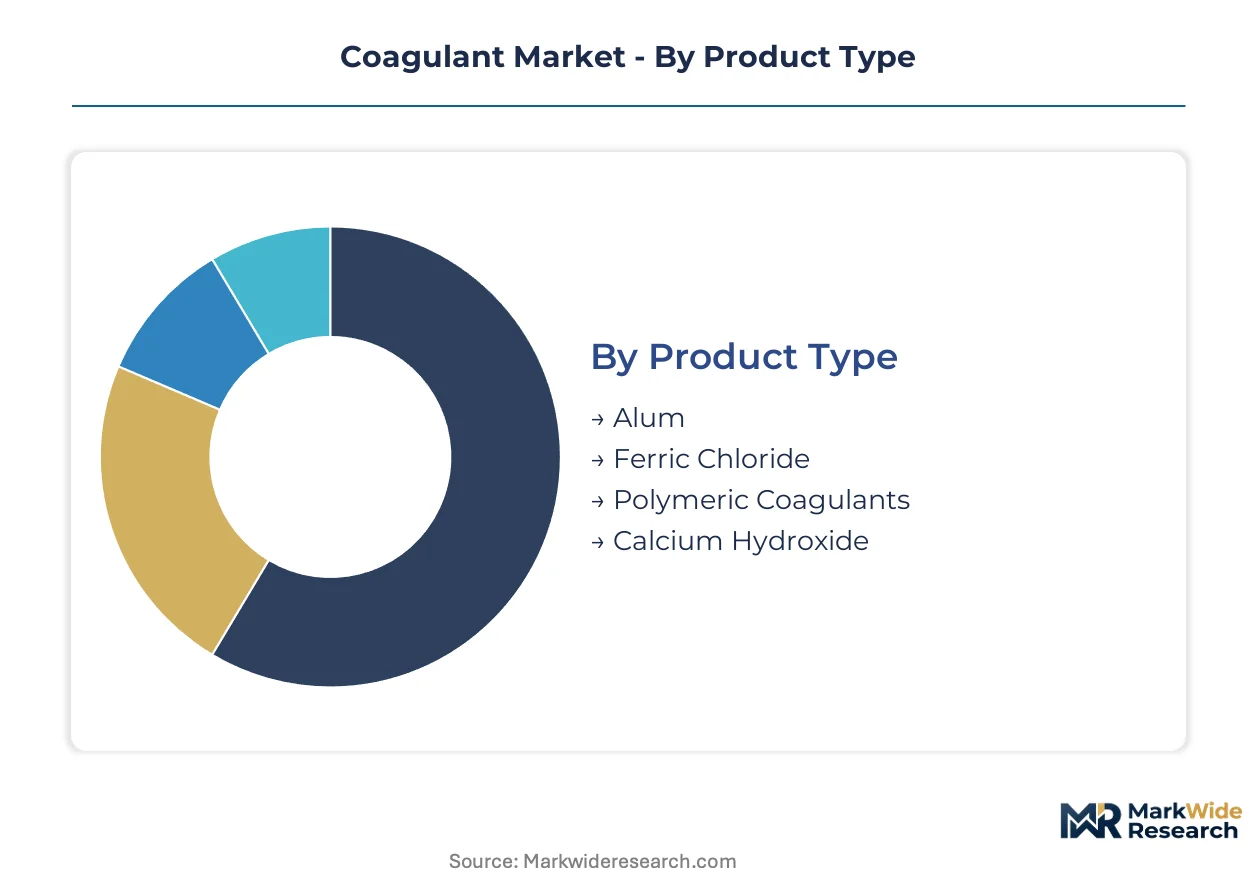
The coagulant market's structure reflects the diverse requirements of water treatment processes across various industries and municipal services. Understanding these distinct segments illuminates the specific product innovations, application challenges, and end-user demands that shape chemical development and delivery.
Product Type:
The supply of coagulants concentrates around established chemical production hubs that can efficiently process raw materials for both inorganic and polymeric compounds. Regional availability of bauxite for alum and iron ore for ferric chloride influences local production capabilities.
- Alum:Aluminum sulfate, a traditional inorganic coagulant, forms aluminum hydroxide flocs and is widely used in municipal potable water treatment for turbidity and phosphorus removal. Its cost-effectiveness makes it a foundational chemical in many water systems, particularly in India's expanding infrastructure projects.
- Ferric Chloride:An inorganic iron salt, ferric chloride offers broad pH effectiveness and produces dense, fast-settling flocs, making it suitable for both municipal and industrial wastewater applications. Its strong performance in sludge dewatering is particularly valued by operators meeting US EPA disposal regulations.
- Polymeric Coagulants:These synthetic organic polymers, including polyacrylamides, offer superior charge neutralization and bridging capabilities for specialized industrial wastewater treatment. SNF Group dominates this high-performance segment through massive production scale.
- Calcium Hydroxide:Commonly known as hydrated lime, this inorganic compound adjusts pH and aids in softening water by precipitating hardness minerals, finding use in both municipal and industrial settings.
Ferric Chloride absorbs the bulk of installed capacity; Polymeric Coagulants are expanding most quickly.
Application:
Coagulant applications exhibit distinct cost tiers, with potable water production often prioritizing performance over raw chemical cost, while industrial processes balance efficiency and budget. Each application faces unique regulatory and operational pressures.
- Water Treatment:This segment encompasses the purification of raw water sources for potable use, adhering to global standards set by organizations like the WHO. Municipalities in nations like India utilize foundational coagulants to ensure safe drinking water access for urban populations.
- Wastewater Treatment:Addressing industrial and municipal effluent, this application focuses on removing suspended solids, organic matter, and nutrients to meet stringent discharge limits, such as those imposed by China's MEE. Advanced coagulants are crucial for tertiary treatment under the EU's Urban Waste Water Treatment Directive.
- Paper Manufacturing:Specialized organic polymers control wet-end chemistry, improving drainage, retention, and filler distribution for enhanced machine efficiency and product quality within paper mills.
- Oil Recovery:Coagulants assist in separating oil from water in produced water treatment and industrial processes, reducing environmental impact and enabling water reuse.
Wastewater Treatment applications consistently require higher chemical dosages, while Oil Recovery presents niche, high-value opportunities.
End User:
End-user segments define the volume profiles for coagulant procurement, with large-scale operations driving bulk purchases and specialized needs dictating smaller, premium orders. Operational scale and regulatory oversight vary significantly across these user types.
- Municipalities:These entities manage public water and wastewater treatment plants, serving urban and rural populations. Their demand for coagulants is stable, driven by infrastructure expansion and consistent water quality regulations, such as those from the US EPA.
- Industrial Facilities:This broad category includes diverse sectors like manufacturing, chemicals, and food processing, all generating process wastewater. Stringent industrial effluent regulations in China drive demand for advanced coagulation in these facilities.
- Agriculture:Coagulants are used in agricultural runoff treatment to remove suspended solids and phosphorus, protecting water bodies from eutrophication.
- Mining:Mining operations utilize coagulants for tailings management and process water clarification, reducing water consumption and meeting environmental discharge standards.
Industrial Facilities represent a diverse demand base for specialized coagulants, while Municipalities offer stable, long-term procurement contracts.
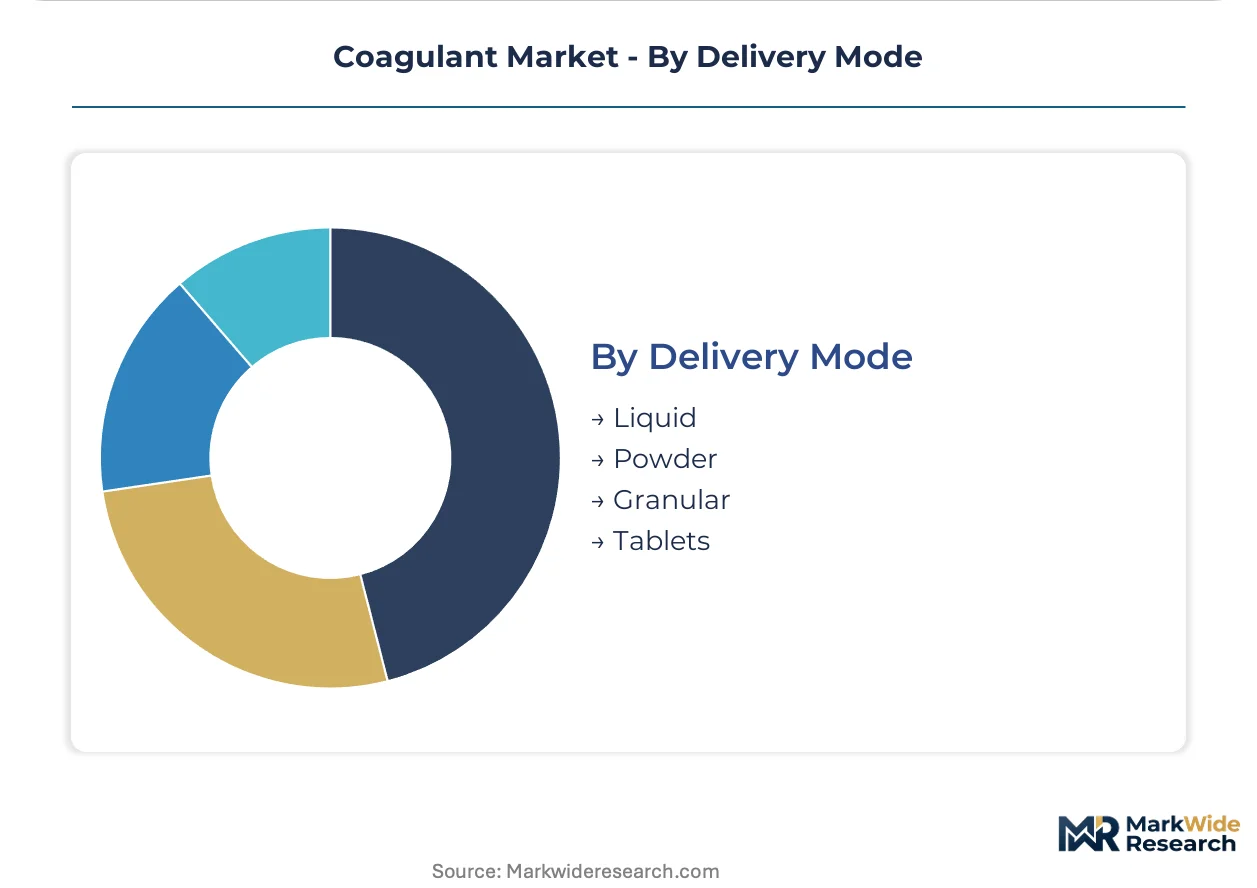
Delivery Mode:
Different delivery modes cater to specific customer types, from large industrial plants requiring bulk liquid deliveries to smaller, remote operations preferring concentrated powder or tablet forms. Logistics and storage capabilities heavily influence selection.
- Liquid:Coagulants delivered in liquid form are common for large-scale users due to ease of dosing and handling in automated systems. However, high water content increases transport costs for remote end-users.
- Powder:Powdered coagulants offer higher concentration, reducing transport weight and storage volume, particularly beneficial for facilities with limited space or remote locations.
- Granular:Granular forms provide a balance between solubility and ease of handling, often used in specific industrial applications requiring controlled dissolution.
- Tablets:Tablet forms offer precise dosing for small-scale applications or specialized maintenance, minimizing waste and simplifying manual application.
Liquid delivery remains prevalent for high-volume users, while Powder forms are gaining traction due to logistical advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Asia, particularly China's industrial parks, drive concentrated demand for advanced coagulants. These regions host extensive manufacturing and mining operations requiring stringent wastewater treatment. Expanding urban centers globally also necessitate significant investments in municipal water infrastructure.
China
China's industrial sector presents substantial demand for coagulants, driven by manufacturing and mining operations. The Ministry of Ecology and Environment (MEE) enforces strict wastewater discharge limits for these facilities. Industrial clusters like the Yangtze River Delta actively implement advanced coagulation to achieve compliance.
India
Municipal infrastructure projects across India create sustained demand for foundational coagulants. The country's initiatives to expand potable water access for urban populations are significant. Major cities such as Delhi-NCR continuously upgrade water treatment plants to meet growing demand.
United States
Stringent US EPA rules on sludge disposal and industrial effluent drive coagulant selection in the United States. Industrial facilities, particularly in the chemicals and manufacturing sectors, prioritize effective wastewater treatment. The Gulf Coast region, with its dense petrochemical industry, requires advanced solutions for process water.
Germany
Germany's industrial sector faces rigorous environmental standards, including the EU's Urban Waste Water Treatment Directive. This necessitates the use of advanced coagulants for industrial effluent and municipal wastewater. The Rhine-Ruhr industrial region leads in adopting tertiary treatment technologies for compliance.
Brazil
Brazil's mining industry and agricultural sector generate significant demand for water treatment chemicals. National environmental regulations compel mining operations to clarify process water and manage tailings effectively. The state of Minas Gerais, a major mining hub, implements coagulants for water reuse and discharge compliance.
Coagulant Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the coagulant market. This market structure features a mix of large chemical manufacturers offering broad portfolios and specialized water treatment solution providers. Strategic archetypes include global chemical giants, regional niche players, and technology-driven innovators developing sustainable alternatives. Dominant competitive moves involve portfolio diversification and targeted capacity expansion to serve specific end-user requirements.
Within the high-performance polymer segment, SNF Group exemplifies a scale-driven specialist, dominating polyacrylamide-based products through massive production capabilities. Kemira occupies a position as a diversified portfolio provider, leveraging its extensive range of both inorganic and polymeric coagulants to serve municipal and industrial clients. Ecolab represents a service-oriented approach, integrating its chemical offerings with comprehensive water management services for industrial end-users. These companies collectively illustrate the varied strategic approaches to market penetration and value creation within the coagulant industry.
| Leading Market Players |
|---|
| Solenis |
| Feralco |
| Kemira |
| Buckman |
| Veolia |
| BASF |
| SNF Group |
| Kurita Water Industries |
| Ecolab |
| Others |
Cost & Logistics Intelligence
Municipalities, with their stable, long-term procurement contracts, often drive contract-based pricing in the coagulant market. This demand profile influences supply chain investments, particularly for high-volume inorganic products.
Pricing Analysis
Short lead times for urgent municipal or industrial water treatment needs command premium pricing for coagulants. The dominant pricing structure is a hybrid of contract-based long-term offtake for foundational chemicals and value-based pricing for specialized polymers. Price differentiation stems from product performance, such as floc settling speed, and geographic delivery costs. Pricing pressure stems from volatile raw material costs, particularly for bauxite and industrial acids. Industrial facilities are often the most price-sensitive segment, while municipalities prioritize consistent performance.
Supply Chain Analysis
Dual-sourcing requirements for critical water treatment chemicals are common, ensuring supply resilience for municipal and industrial operators. Geographic supply concentration for inorganic coagulants centers on China, India, and the United States, driven by raw material availability like bauxite and iron ore. Key raw material dependencies include bauxite for alum and industrial acids for ferric chloride production. A structural risk is logistics inefficiency, as high water content in liquid coagulants makes long-distance transport costly. Distribution runs through a network of specialized chemical distributors and direct sales channels to large end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coagulant market remains a supply-constrained story, particularly for high-performance polymeric compounds. Limited production capacity for specialized polyacrylamides props up pricing in the advanced treatment segment.
For Market Incumbents:
Extend existing product portfolios with bio-based alternatives to meet evolving sustainability goals and regulatory pressures from EU's REACH. Invest in capacity expansion for high-charge cationic polymers, particularly in Southeast Asia, to counter the threat of new entrants and address growing demand for tertiary wastewater treatment. Deepen vertical integration into key raw materials like bauxite to mitigate input cost volatility.
For New Entrants and Emerging Players:
Price-point gaps exist between premium synthetic polymers and traditional inorganic coagulants, creating opportunities for bio-based alternatives. Target industrial wastewater treatment in China, focusing on sectors like mining and manufacturing, which face stringent MEE discharge limits. A direct-to-customer sales model, bundled with technical support, can penetrate segments where legacy suppliers offer less specialized service.
For Investors and Strategic Acquirers:
The window for entry favors vertically integrated mid-cap specialists with strong intellectual property in bio-based coagulants. Long-term viability over a 5-10 year horizon depends on controlling raw material inputs and securing regional distribution channels. Acquisition targets should possess advanced sludge management technologies or proprietary polymeric formulations. A signal to watch is the increasing investment in water reuse infrastructure in arid regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expand production of high-performance polymers in Southeast Asia to meet accelerating water treatment infrastructure demand. |
| Green Manufacturing Transition | Develop and commercialize bio-based coagulants from agricultural byproducts, targeting food and beverage processors. |
| Long-term Supply Agreement | Secure multi-year contracts for key raw materials like bauxite to stabilize inorganic coagulant production costs. |
| Joint Venture | Form partnerships with water management service providers to offer integrated chemical and operational solutions to industrial clients. |
| Regulatory Approval Pathway | Streamline chemical registration processes for new products under frameworks like the EU's REACH to accelerate market entry. |
Research Approach
Independent corroboration across industry association reports, regulatory body publications, and academic research underwrites the qualitative findings of this study. Primary interviews with plant managers, procurement leads, R&D directors, and environmental compliance officers provided granular insights. This was triangulated with secondary data from trade statistics, company annual reports, and technical journals. A combination of bottom-up volume analysis and top-down market sizing ensures data integrity.
Rate-of-change decomposition across application, product type, and end-user segments informed the forecast model throughout the projection horizon. The analytical framework integrated historical growth patterns with anticipated future trends. CAGRs were derived from a multi-variable regression analysis, accounting for regulatory shifts and infrastructure investments. Key forecast inputs included projected industrial output growth and municipal water consumption rates.
Inputs from publicly available financial reports and industry surveys were available through the study window; gaps in real-time raw material pricing data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption. Deviation in global economic growth or raw material supply chain disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Europe Biguanide Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Global Phenoxyethanol Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Vinyl Acetate Market
Chemicals
Iso Nonanol Market
Chemicals
Elemental Fluorine Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Spirodiclofen Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
3-Iodoaniline Market