
 Malonic Acid Market | 2026-2036
Malonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Malonic Acid Market Outlook
Price-performance divergence between fermentation-derived and petrochemical-sourced grades is recalibrating supplier tiering in the malonic acid landscape. Lonza Group leverages its bioprocessing infrastructure to anchor premium positioning in pharmaceutical-grade supply. Hefei TNJ Chemical Industry Co. Ltd. competes on synthetic acid scale, while Lygos Inc. differentiates through bio-based pathway development.
Malonic acid is a dicarboxylic acid with the formula CH2(COOH)2, typically manufactured via cyanoacetic acid hydrolysis or emerging fermentation routes, and functions primarily as a chemical intermediate for pharmaceutical active ingredients and polymer synthesis. Synthetic malonic acid still occupies the largest volume share, though specialty malonic acid commands the strongest margin pool due to purity requirements in regulated end uses. Pharmaceutical applications lead value generation, while agrochemicals represent the fastest-growing demand segment as crop protection formulators seek alternative acid precursors.
EPA oversight of chemical manufacturing emissions and REACH registration requirements for industrial substances shape product standards and market access conditions for malonic acid producers. China's SAMR enforces GB standards on food-grade acid purity, creating additional compliance layers for exporters. Stakeholders must monitor regulatory divergence between bio-based certification schemes and conventional petrochemical standards when allocating capacity investments.
Market Dynamics
The divergence between fermentation-derived and petroleum-sourced malonic acid production pathways is restructuring supplier hierarchies and procurement criteria across pharmaceutical and specialty chemical value chains.
Growth Catalysts
- REACH petrochemical restrictions:ECHA registration requirements for industrial substances are compelling German pharmaceutical formulators to certify bio-based acid feedstocks.
- Agrochemical precursor demand:Crop protection manufacturers are substituting conventional acid intermediates with malonic acid derivatives for novel herbicide synthesis.
- China eastern corridor concentration:Specialty chemical clusters in Jiangsu and Zhejiang provinces are scaling malonic acid derivative capacity for polymer export markets.
Market Restraints
- Acetonitrile feedstock volatility:Cyanoacetic acid synthesis depends on acetonitrile pricing tied to acrylic fiber production cycles.
- Fermentation yield ceilings:Microbial strain productivity limits currently cap bio-based acid output at pilot-to-small-commercial scale.
- Propionic acid substitution:Some pharmaceutical intermediates can substitute malonic acid with propionic acid derivatives in less purity-critical applications.
Strategic Opportunities
- EPA bio-preference programs:Federal procurement mandates for biobased products are opening pharmaceutical-grade supply contracts to certified renewable producers.
- India agrochemical formulation:Domestic crop protection manufacturers represent underpenetrated demand for acid precursor imports.
- Continuous flow reactor adoption:Integration of flow chemistry with biosynthetic pathways is enabling real-time quality control for pharmaceutical customers.
Industry Challenges
- Pharmaceutical GMP certification timelines:FDA and EMA validation protocols for new bio-based acid facilities extend 18-24 months beyond construction completion.
- Synthetic biology talent scarcity:Strain engineering and bioprocess optimization expertise concentrates at limited research institutions and specialized contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malonic Acid Market |
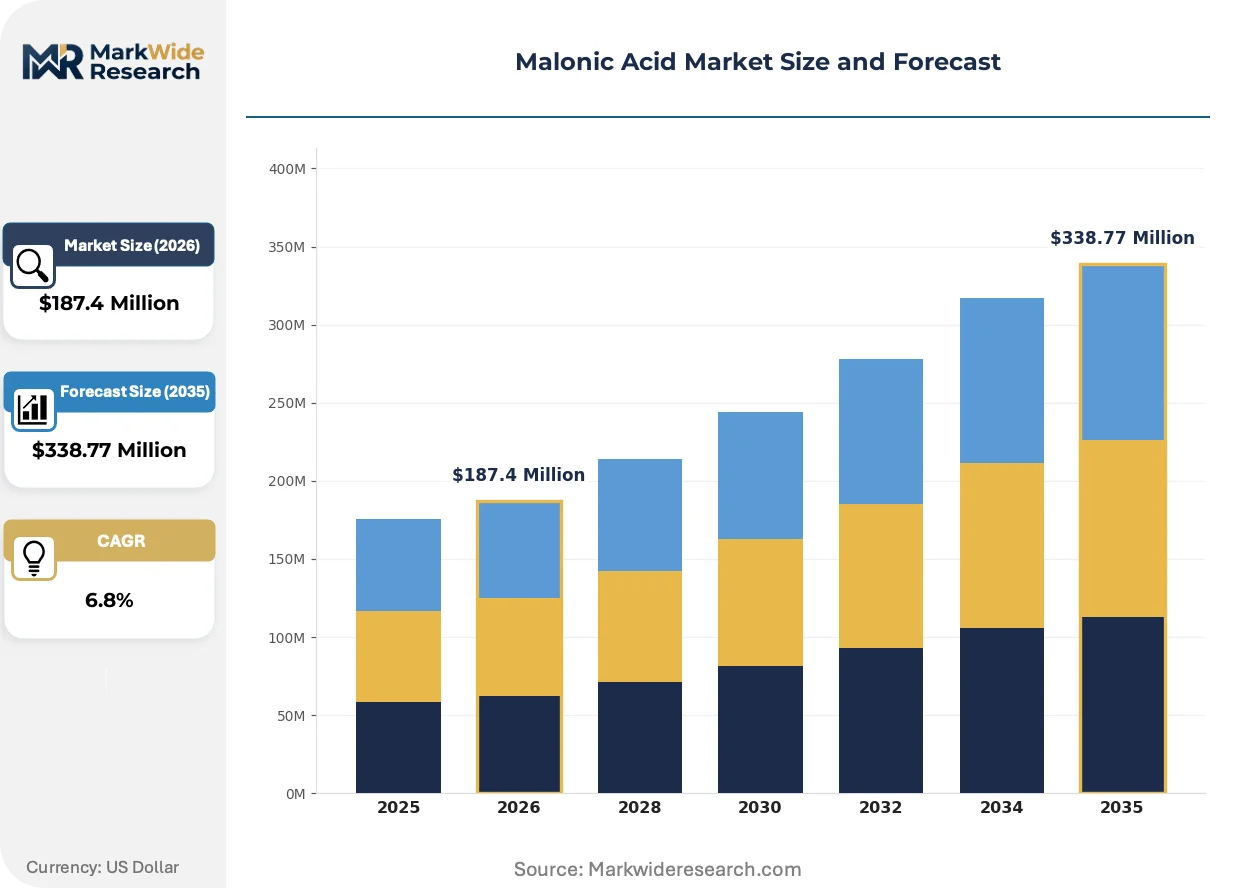
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Malonic Acid, Synthetic Malonic Acid, Malonic Acid Derivatives, Specialty Malonic Acid Application: Pharmaceuticals, Agrochemicals, Food Preservatives, Dyes End User: Chemical Manufacturers, Food Industry, Research Laboratories, Agricultural Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Columbus Chemical Industries Inc., J&K Scientific Ltd., Lonza Group, Lygos Inc., Hefei TNJ Chemical Industry Co. Ltd., Shanghai Nanxiang Reagent Co. Ltd., Trace Zero LLC, Tateyama Kasei Co. Ltd., Wuhan Kemi-Works Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malonic Acid Market Strategic Shifts
Fermentation pathway engineering and regulatory bio-certification schemes are converging to redefine production economics and customer qualification requirements in malonic acid supply.
Cell-free enzymatic synthesis is integrating purified enzyme cascades with immobilized reactor systems to bypass whole-cell fermentation constraints. Pharmaceutical manufacturers are piloting this approach for high-purity acid batches requiring trace-metal specifications below fermentation-grade thresholds. The technology is integrating continuous processing architectures that compress batch cycle times from days to hours.
EPA's Green Chemistry Challenge framework and ECHA's bio-based substance guidance are creating parallel certification tracks for renewable acid feedstocks. Chemical manufacturers must now maintain dual documentation systems for petrochemical and fermentation-derived product lines. Pharmaceutical excipient suppliers face the steepest compliance burden as they qualify alternative sourcing for ANDA submissions.
Direct supplier relationships are displacing distributor intermediaries in pharmaceutical-grade acid procurement. Large formulators are establishing dedicated supply agreements with fermentation specialists to secure batch traceability for regulatory filings. This pattern is most visible in United States and German markets where FDA and EMA inspection protocols favor single-source documentation chains over fragmented purchasing.
Malonic Acid Market Segmentation
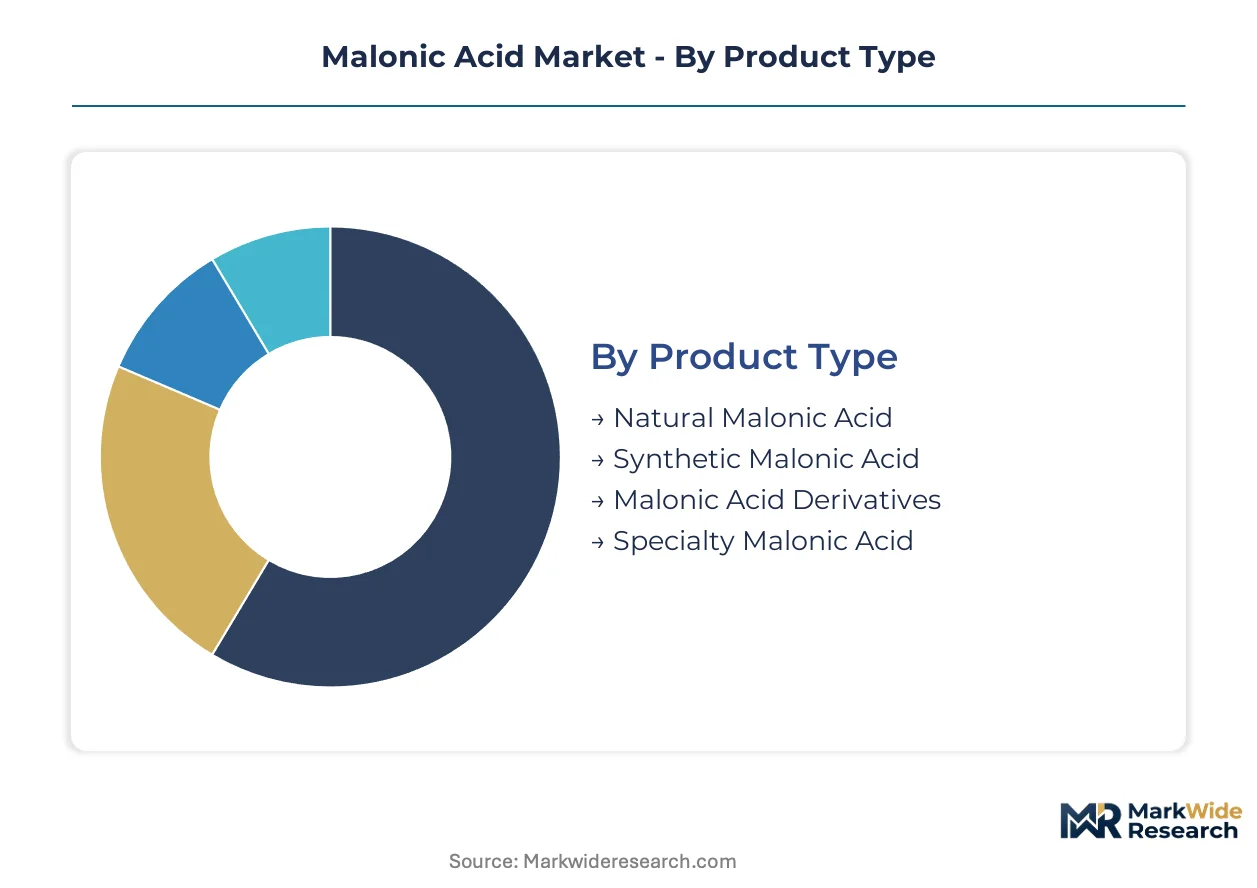
Malonic acid segmentation reflects divergent compliance burdens across pharmaceutical, food, and industrial applications. Certification requirements for GMP, food-grade purity, and REACH registration create distinct margin tiers that reshape supplier positioning.
Product Type:
Certification intensity varies sharply across production pathways, with pharmaceutical-grade fermentation batches demanding FDA and EMA validation that synthetic routes bypass entirely.
- Natural Malonic Acid:Fermentation-derived grades achieve 99.5%+ purity through microbial strain optimization. Pharmaceutical formulators in Germany and the United States prioritize this segment for ANDA submissions requiring bio-based documentation.
- Synthetic Malonic Acid:Cyanoacetic acid hydrolysis produces cost-competitive volumes for polymer and dye intermediates. China's eastern manufacturing corridor dominates capacity, though acetonitrile feedstock volatility constrains margin stability.
- Malonic Acid Derivatives:Esterified and amidated variants serve agrochemical precursor applications with modified solubility profiles.
- Specialty Malonic Acid:Ultra-high purity batches for electronic materials and analytical standards command premium positioning through limited qualified suppliers.
Synthetic Malonic Acid sits at the top of the volume ranking, with Natural Malonic Acid climbing the fastest.
Application:
End-use economics separate into regulated pharmaceutical workflows versus price-sensitive industrial formulations, with agrochemicals emerging as the pivot point for capacity allocation decisions.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and excipient applications require batch-level traceability for FDA and EMA inspections. Barbiturate derivatives and vitamin B6 precursors anchor demand concentration in United States and German markets.
- Agrochemicals:Novel herbicide and fungicide intermediates are expanding most quickly as crop protection manufacturers seek alternatives to restricted acid precursors. Jiangsu province formulators represent concentrated import demand.
- Food Preservatives:SAMR GB standards and FDA GRAS listings impose dual compliance layers on exporters serving China and United States markets simultaneously.
- Dyes:Textile and pigment intermediate applications tolerate broader purity specifications, sourcing predominantly from synthetic acid supply.
Pharmaceuticals generates the highest value per kilogram, while Agrochemicals expands most quickly.
End User:
Customer scale determines procurement modality, with large chemical manufacturers bypassing intermediaries while fragmented agricultural buyers rely on distributor networks.
- Chemical Manufacturers:Integrated polymer and pharmaceutical producers negotiate direct supply agreements for multi-tonne annual volumes. Continuous flow reactor adoption favors suppliers with dedicated technical service capabilities.
- Food Industry:Preservative compounders require SAMR GB 1886 compliance documentation for China market access, extending qualification timelines.
- Research Laboratories:Gram-scale purchases of analytical-grade material flow through specialized distributors with cold-chain logistics.
- Agricultural Sector:Domestic crop protection formulators in India represent underdeveloped demand for acid precursor imports.
Chemical Manufacturers command the largest procurement volumes, with Agricultural Sector gaining share fastest.
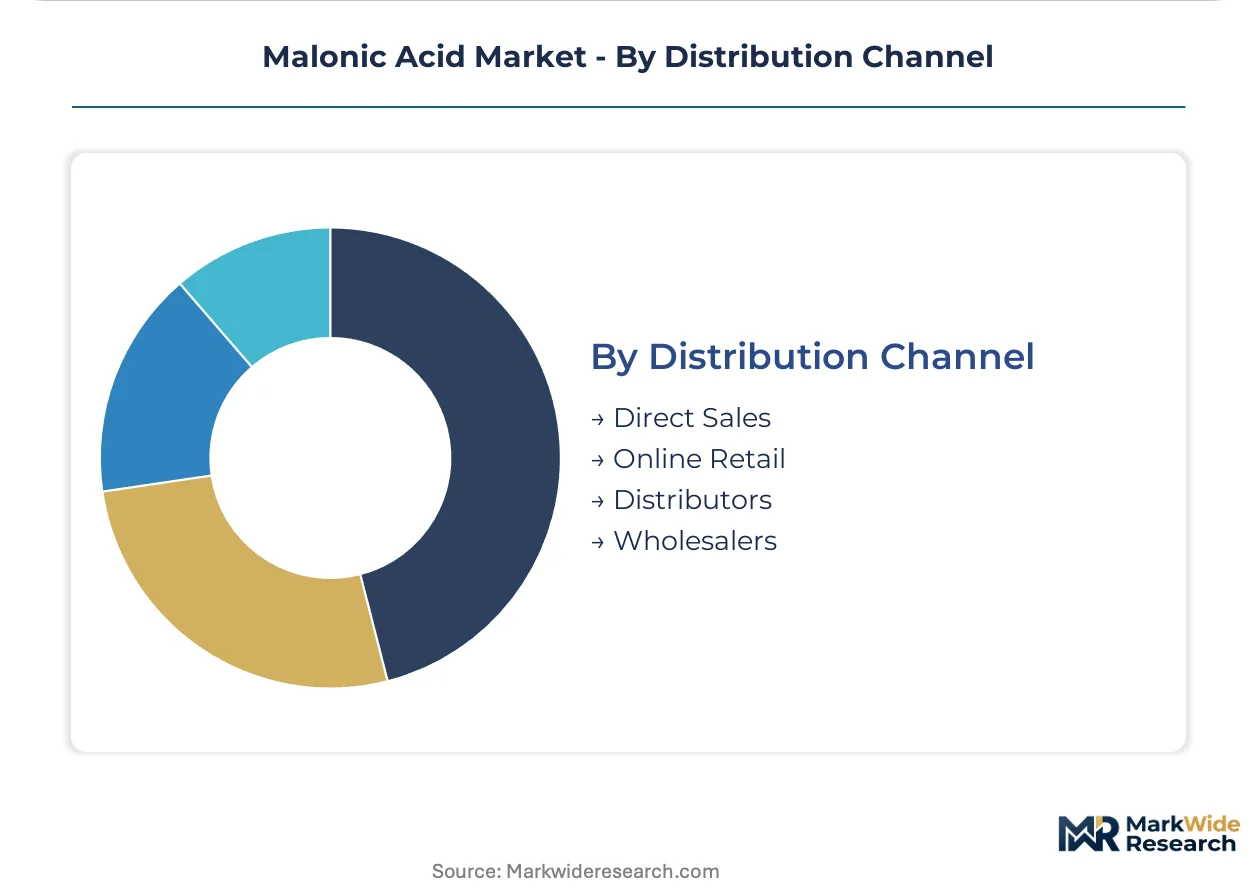
Distribution Channel:
Channel selection tracks customer size and documentation requirements, with regulatory filing needs pushing pharmaceutical buyers toward direct relationships.
- Direct Sales:Multi-year supply agreements with fermentation specialists provide batch traceability for FDA and EMA submissions. Large United States and German formulators dominate this channel.
- Online Retail:Research-grade and small-batch industrial sales consolidate through specialized chemical marketplaces with digital COA verification.
- Distributors:Regional intermediaries manage inventory and compliance documentation for mid-scale chemical manufacturers across fragmented geographies.
- Wholesalers:Bulk synthetic acid volumes for dye and polymer applications flow through price-focused trading networks.
Direct Sales leads in value throughput, with Online Retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strain engineering specialists cluster around Basel, Boston, and Shanghai, anchoring regional bio-based acid development. These talent pools shape local production economics and regulatory compliance capabilities.
United States
Pharmaceutical formulators in New Jersey and Massachusetts drive fermentation-grade acid procurement for ANDA submissions. EPA bio-preference programs open federal supply contracts to certified renewable producers. Greater Boston hosts Lygos Inc. and adjacent synthetic biology startups advancing cell-free enzymatic pathways.
Germany
REACH petrochemical restrictions compel Ludwigshafen and Leverkusen-based chemical manufacturers to certify bio-based feedstocks. ECHA registration requirements extend validation timelines for new acid facilities. The country's national pharmaceutical regulator enforces GMP protocols that favor single-source documentation chains.
China
Jiangsu and Zhejiang province formulators scale malonic acid derivative capacity for polymer export markets. SAMR GB standards impose dual compliance layers on food-grade acid exporters serving domestic and United States markets simultaneously. The eastern manufacturing corridor concentrates synthetic acid production tied to acetonitrile feedstock availability.
India
Domestic crop protection manufacturers in Gujarat and Maharashtra represent underpenetrated demand for acid precursor imports. The country's national pharmaceutical regulator aligns with ICH guidelines for intermediate qualification. Mumbai-Pune chemical clusters are expanding formulation capacity for novel herbicide synthesis.
Japan
Electronic materials manufacturers in Osaka and Nagoya procure ultra-high purity acid batches for analytical standards. METI carbon neutrality roadmaps incentivize fermentation pathway investment. The Kansai region maintains specialty chemical infrastructure serving precision electronics supply chains.
Malonic Acid Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the malonic acid landscape. Synthetic acid manufacturers with captive petrochemical feedstock integration face margin pressure from fermentation specialists leveraging bioprocessing infrastructure. Three archetypes dominate: integrated pharmaceutical-grade suppliers, scale-driven synthetic producers, and venture-backed bio-pathway developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure GMP certification or lock in acetonitrile supply agreements.
Within the pharmaceutical-grade tier, Lonza Group exemplifies integrated bioprocessing infrastructure, while Hefei TNJ Chemical Industry Co. Ltd. occupies a position among scale-driven synthetic manufacturers. Lygos Inc. represents the venture-backed archetype advancing bio-based pathway development. Chinese producers including Shanghai Nanxiang Reagent Co. Ltd. and Wuhan Kemi-Works Chemical Co. Ltd. anchor regional supply networks. Tateyama Kasei Co. Ltd. sits within the Japanese specialty chemical segment serving electronic materials applications.
| Leading Market Players |
|---|
| Columbus Chemical Industries Inc. |
| J&K Scientific Ltd. |
| Lonza Group |
| Lygos Inc. |
| Hefei TNJ Chemical Industry Co. Ltd. |
| Shanghai Nanxiang Reagent Co. Ltd. |
| Trace Zero LLC |
| Tateyama Kasei Co. Ltd. |
| Wuhan Kemi-Works Chemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Large pharmaceutical formulators in New Jersey and Massachusetts anchor pricing power through multi-year direct contracts with fermentation specialists, compressing margins for distributors serving fragmented agrochemical buyers.
Pricing Analysis
Service bundling separates fermentation-grade suppliers offering batch traceability and regulatory documentation from unbundled synthetic acid traders. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels tracks certification intensity and purity thresholds. Cost compression in synthetic routes is intensifying because acetonitrile feedstock volatility erodes margin stability for cyanoacetic acid hydrolysis producers. Agrochemical formulators exhibit highest price sensitivity, while electronic materials manufacturers tolerate premium positioning for ultra-high purity specifications.
Supply Chain Analysis
Synthetic biology talent scarcity in Jiangsu province and acetonitrile processing expertise in Germany's chemical corridor constrain capacity expansion timelines for both fermentation and petrochemical pathways. Supply concentrates in China for synthetic acid, the United States for pharmaceutical-grade fermentation batches, and Japan for specialty electronic materials grades. Production draws from acetonitrile, microbial feedstocks, and purified enzyme cascades as core inputs. Single-source vulnerability around Chinese acetonitrile supply creates structural exposure for European dye intermediate manufacturers. Distribution runs through direct sales agreements for pharmaceutical customers and regional distributor networks for industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH petrochemical restrictions and EPA bio-preference programs are accelerating demand migration toward certified fermentation-derived supply.
For Market Incumbents: Deploy GMP certification investment to lock in pharmaceutical-grade supply relationships before FDA validation timelines extend further. Synthetic acid producers should secure captive acetonitrile supply agreements to defend margin position against feedstock volatility. Fermentation specialists must expand bioprocessing infrastructure in Basel and Boston talent clusters to preempt strain engineering bottlenecks. For New Entrants and Emerging Players: Capture underpenetrated demand among Gujarat and Maharashtra crop protection formulators seeking acid precursor imports for novel herbicide synthesis. India's domestic agrochemical sector offers the most penetrable geography, with technical service partnerships representing the optimal go-to-market angle for establishing qualification credentials. For Investors and Strategic Acquirers: Pharmaceutical-grade chemical manufacturers are the most active acquirer in this space, targeting fermentation specialists with validated ANDA documentation capabilities. Five-to-ten year viability hinges on bio-based pathway cost convergence with petrochemical routes. Monitor EPA bio-preference procurement mandate expansion as the critical inflection signal for renewable acid demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Jiangsu province derivative production scales for polymer export markets. |
| Backward Integration | Captive acetonitrile supply secures margin stability for synthetic producers. |
| GMP Certification Investment | FDA and EMA validation timelines extend competitive moats for early movers. |
| Long-term Supply Agreement | Direct contracts with Massachusetts formulators displace distributor intermediaries. |
| Joint Venture | Boston-Basel synthetic biology partnerships accelerate cell-free enzymatic pathways. |
Study Parameters
Multiple input streams — fermentation technology directors, pharmaceutical procurement leads, agrochemical formulators, and specialty chemical distributors — were reconciled against customs trade data, ECHA registration filings, SEC 10-K disclosures, and SAMR GB standard documentation. Bottom-up volume modeling across production pathways and top-down demand validation from end-use industries were cross-checked for consistency.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of regulatory timeline impacts. Segmentation dimensions included production pathway, grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from demand elasticity modeling and supply constraint analysis, with fermentation yield improvement curves and acetonitrile price volatility serving as industry-specific forecast inputs across the analysis window.
Feedstock price shocks, regulatory certification delays, and microbial strain productivity breakthroughs are the dominant revision risks for forecast outputs. Material deviation in these triggers warrants pause and re-evaluation of capacity investment assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Acetic Anhydride Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Europe Biguanide Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Glyoxylic Acid Market
Chemicals
Chemical As a Service Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Sodium Methoxide Market
Chemicals
United Kingdom Methanol Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Methoprene Market
Chemicals
Flooring Chemicals Market
Chemicals
Triethylaluminum Market
Chemicals
Elemental Fluorine Market
Chemicals
Europe Hydrazine Market