
 Global Radiant Floor Heating Market | 2026-2036
Global Radiant Floor Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiant Floor Heating Market Foresight
Residential building retrofits is broadening the addressable base for radiant floor heating as homeowners replace aging radiator networks with energy-efficient underfloor alternatives. Uponor Corporation leverages its polymer piping expertise to dominate hydronic system supply across Nordic markets. Robert Bosch GmbH anchors its position through integrated boiler-to-thermostat control architectures. Danfoss A/S specializes in manifold and mixing valve technologies that optimize water temperature distribution.
Radiant floor heating distributes thermal energy through embedded pipes, cables, or panels within floor structures, typically operating at fluid temperatures of 35–45°C in hydronic configurations to achieve uniform surface warmth. Electric systems employ resistive cable or thin-film elements suited for retrofit zones where boiler infrastructure is unavailable. Hydronic radiant heating leads installed capacity in new European construction due to compatibility with heat pump sources. Electric radiant heating captures faster growth in North American renovation activity where minimal structural disruption matters. Modular panels occupy a premium niche in commercial fit-outs demanding rapid deployment and tenant flexibility.
The EU Green Deal and F-Gas Regulation are tightening permissible heating system emissions across member states, directly elevating heat pump-compatible hydronic specifications. The EPA ENERGY STAR program and ASHRAE 90.1 standards in the United States establish minimum efficiency thresholds that favor low-temperature radiant distribution over conventional forced-air alternatives. China's GB standards and dual carbon goals are mandating building energy intensity reductions that align with radiant floor integration. Stakeholders must monitor how national heat pump subsidy programs reshape the competitive balance between electric and hydronic system architectures.
Market Dynamics
The EU F-Gas Regulation and building energy codes in Germany, China, and the United States are compressing permissible heating system temperatures, forcing a wholesale migration from conventional radiators toward low-temperature hydronic distribution compatible with heat pump sources.
Growth Catalysts
- EU Green Deal retrofit mandates:Member states must renovate building stock to near-zero emissions by 2050, expanding the addressable base for underfloor replacement of aging radiator networks.
- Heat pump compatibility:Hydronic radiant systems operate at 35–45°C fluid temperatures, matching the efficiency sweet spot of air-source and geothermal heat pumps displacing gas boilers.
- China:GB standards and dual carbon goals mandate building energy intensity reductions that align with radiant floor integration in new residential construction.
Market Restraints
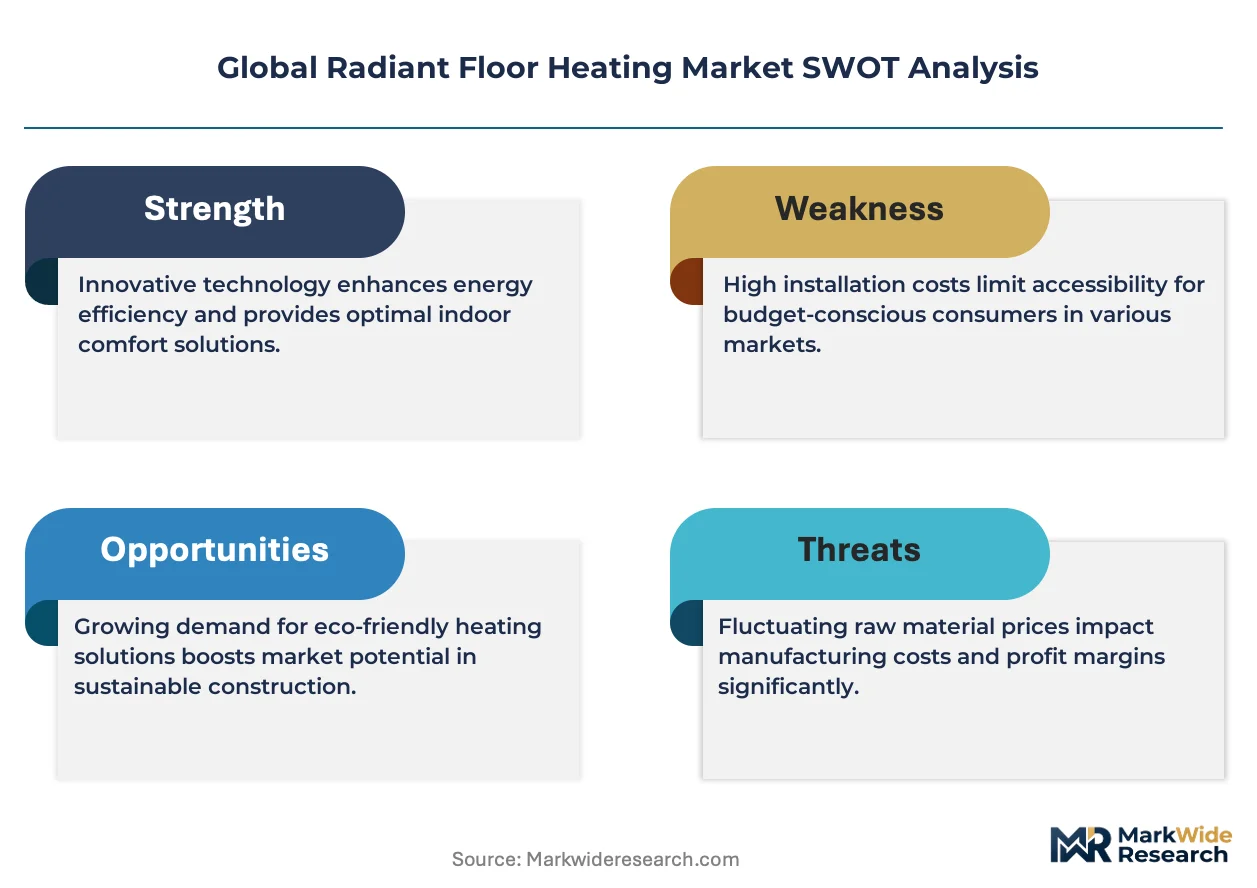
- Copper and polymer input volatility:Cross-linked polyethylene pipe and manifold assemblies face raw material price swings that compress installer margins and delay project commitments.
- Specialized installer scarcity:Hydronic system commissioning requires certified technicians trained in manifold balancing and mixing valve calibration, creating supply-side bottlenecks in fragmented construction labor markets.
- Electric resistance substitution:Thin-film electric mats and cables capture renovation segments where boiler infrastructure is unavailable, capping hydronic penetration in retrofit applications.
Strategic Opportunities
- US residential renovation channel:Electric radiant systems with minimal structural disruption are capturing bathroom and kitchen retrofit demand where full hydronic conversion is cost-prohibitive.
- Heat pump subsidy programs:National incentive schemes in Germany and France are reshaping the competitive balance between electric and hydronic architectures by covering system conversion costs.
- Modular panel systems:Dry-installation panels with pre-pressed aluminum diffusion layers enable rapid commercial fit-outs and tenant reconfiguration without wet screed curing delays.
Industry Challenges
- Commissioning complexity:Proper hydronic system balancing requires specialized manifold tuning and flow rate verification that extends project timelines and demands skilled technician availability.
- Integration with legacy controls:Smart thermostat and zone valve interoperability with existing building management systems creates firmware compatibility testing burdens for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiant Floor Heating Market |
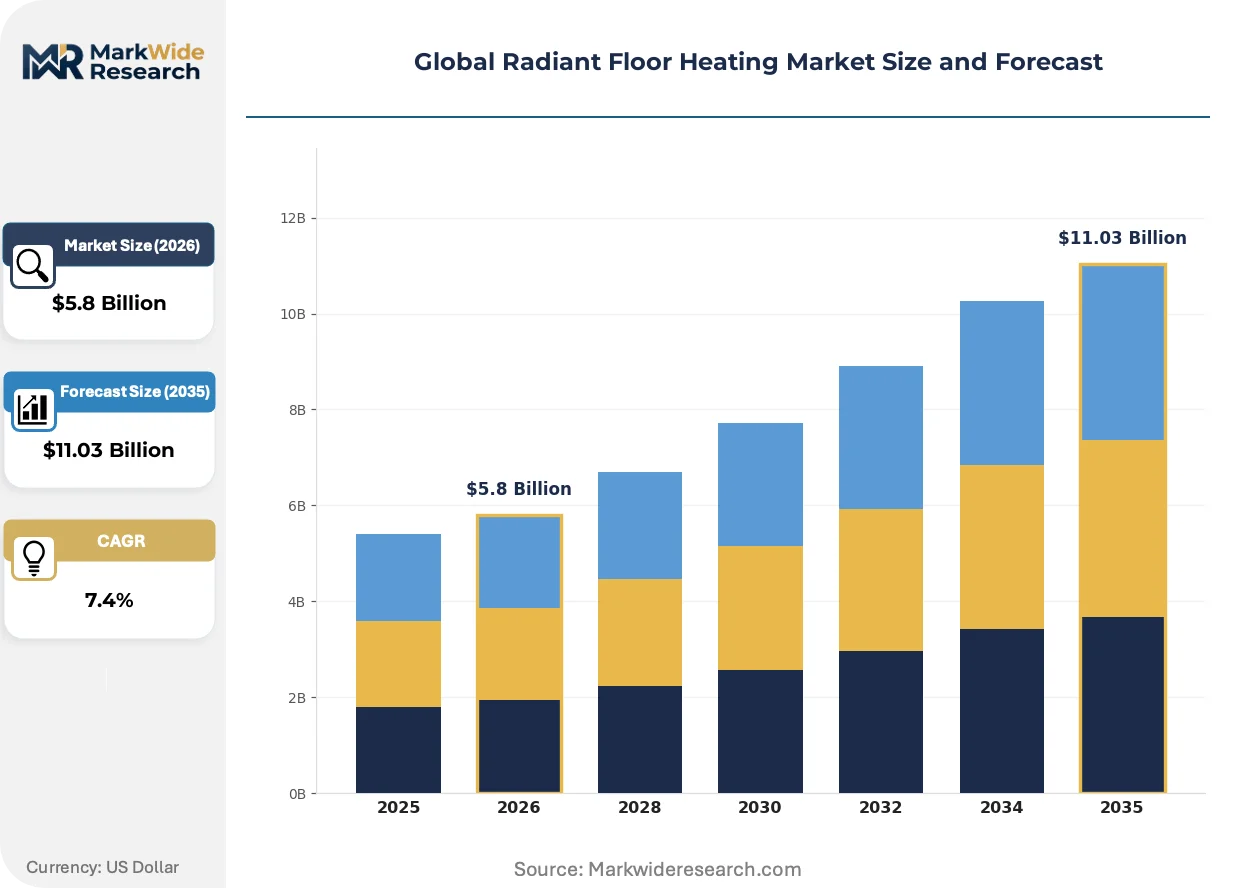
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Radiant Heating, Hydronic Radiant Heating, Air-Heated Radiant Systems, Modular Panels Application: Residential Buildings, Commercial Complexes, Educational Institutions, Hospitality Facilities, Recreational Centers Installation Type: New Construction, Retrofit Projects, Under Tile, Under Wood Flooring, Concrete Slab Integration End User: Homeowners, Facility Managers, Property Developers, Architects, Construction Firms |
| Companies Covered | Uponor Corporation, Robert Bosch GmbH, Danfoss A/S, Siemens AG, Mitsubishi Electric Corporation, Honeywell International Inc., nVent Electric Plc, Warmup PLC, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiant Floor Heating Market Shifts & Advancements
Technology convergence between low-temperature heat sources and intelligent zone controls is compressing the traditional gap between residential comfort systems and building energy management platforms.
Phase-change material (PCM) thermal mass layers embedded within floor assemblies are extending heat release duration and reducing cycling frequency for heat pump sources. Multi-family developers in Germany and the Netherlands are specifying PCM-enhanced screeds to buffer intermittent renewable electricity supply. This thermal storage innovation is converging with dynamic electricity pricing algorithms to shift heating loads toward off-peak hours.
The EPA ENERGY STAR program and ASHRAE 90.1 standards in the United States establish minimum efficiency thresholds that favor low-temperature radiant distribution over forced-air alternatives. Commercial building operators in California and New York are retrofitting underfloor systems to comply with state-level building performance standards. The regulatory pressure is accelerating specification of hydronic systems with integrated demand-response capability.
Homeowner specification behavior is fragmenting across digital channels, with direct-to-consumer configurators displacing traditional contractor-led sales in residential renovation segments. Online platforms in North America now offer room-by-room heat load calculators and material take-off tools that bypass distributor showrooms. This channel shift is most pronounced in single-family bathroom and basement retrofits where project scale suits self-managed procurement.
Global Radiant Floor Heating Market Segmentation
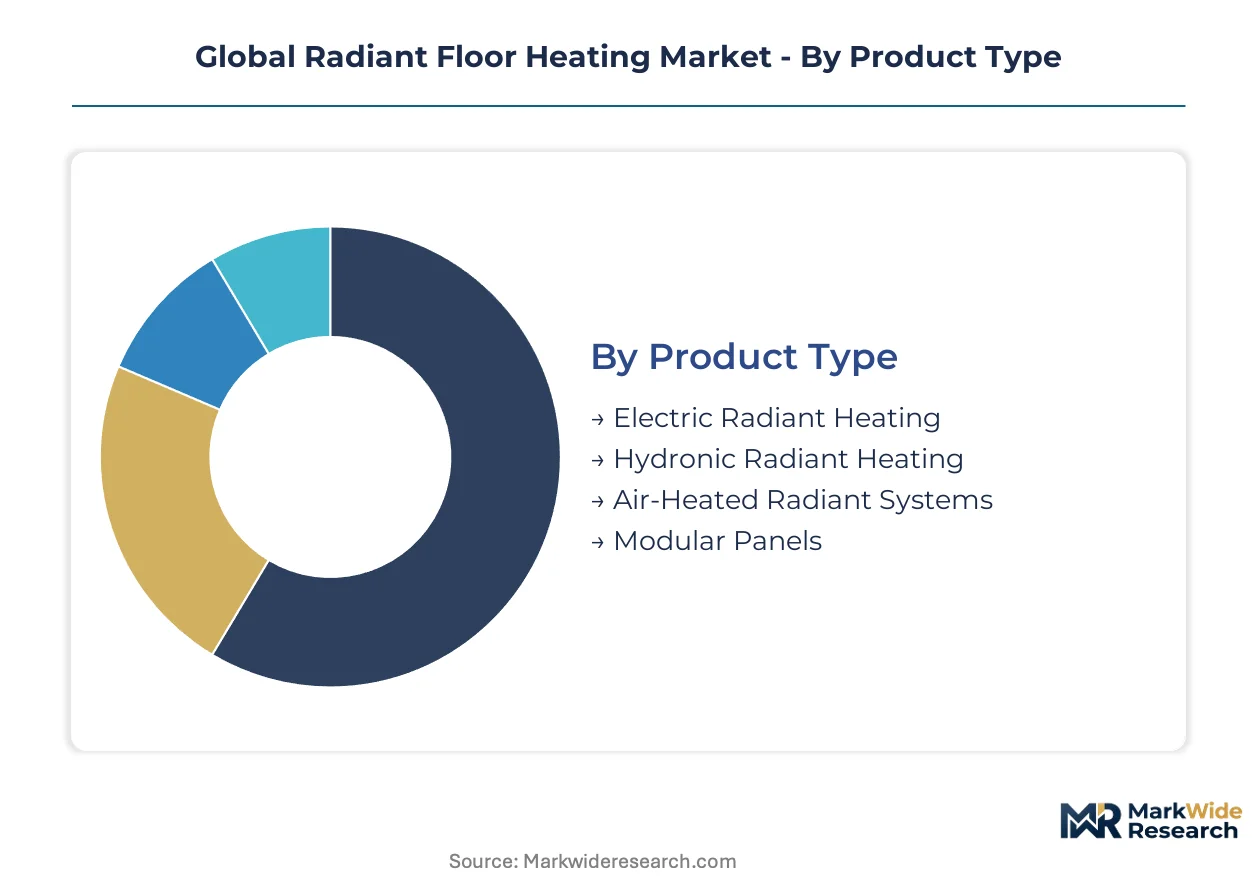
Radiant floor heating technologies diverge sharply across thermal source architectures, installation constraints, and procurement decision-makers. Each segmentation axis reveals distinct margin profiles, technical standards, and channel access requirements that shape competitive positioning.
Product Type:
Technology specifications determine thermal efficiency, infrastructure compatibility, and retrofit feasibility across building archetypes.
- Hydronic Radiant Heating:Cross-linked polyethylene piping circulates fluid at 35–45°C temperatures, matching heat pump efficiency curves mandated by EU F-Gas Regulation. German and Dutch residential construction favors this architecture for new multi-family developments integrating geothermal sources.
- Electric Radiant Heating:Resistive cable and thin-film elements deploy without boiler infrastructure, capturing North American bathroom and kitchen retrofits where structural disruption must stay minimal. Faster installation cycles offset higher operating costs in low-usage zones.
- Modular Panels:Pre-pressed aluminum diffusion layers enable dry-installation commercial fit-outs with tenant reconfiguration flexibility.
- Air-Heated Radiant Systems:Forced-air thermal mass distribution occupies niche applications in industrial warehousing with high ventilation loads.
Hydronic systems lead on installed scale; electric configurations gain share fastest in renovation channels.
Application:
Building use case dictates thermal load profiles, zoning complexity, and regulatory compliance intensity.
- Residential Buildings:Single-family and multi-family housing drives volume through new construction energy codes and deep retrofit mandates under EU Green Deal building renovation targets. Homeowner specification behavior increasingly fragments across direct-to-consumer digital channels.
- Commercial Complexes:Office and retail fit-outs demand demand-response capability for utility incentive programs in California and New York state-level building performance standards. Underfloor systems reduce mechanical ceiling space allocation.
- Hospitality Facilities:Hotels prioritize guest thermal comfort consistency and acoustic benefits over forced-air alternatives.
- Educational Institutions:School districts specify low-temperature distribution for child safety and reduced allergen circulation.
- Recreational Centers:Swimming pool decks and gymnasiums require moisture-resistant encapsulation and rapid surface drying.
Residential applications anchor volume concentration; commercial complexes expand most quickly through regulatory pressure.
Installation Type:
Project phase and substrate compatibility determine labor skill requirements, material specifications, and timeline risk.
- New Construction:Wet screed embedding of hydronic loops during concrete pour minimizes incremental labor cost and enables phase-change material thermal mass integration. German developers specify PCM-enhanced screeds for renewable electricity load shifting.
- Retrofit Projects:Thin-profile electric mats and low-buildup panel systems bypass structural modifications, capturing aging housing stock renovation in the United States where boiler replacement is cost-prohibitive.
- Concrete Slab Integration:Thermal mass storage optimization for heat pump cycling efficiency dominates Nordic ground-source applications.
- Under Tile:Electric cable systems with waterproof membranes target bathroom wet zones.
- Under Wood Flooring:Low-temperature hydronic specifications prevent dimensional instability in engineered timber substrates.
New construction commands the largest project scale; retrofit installations climb fastest as building renovation mandates tighten.
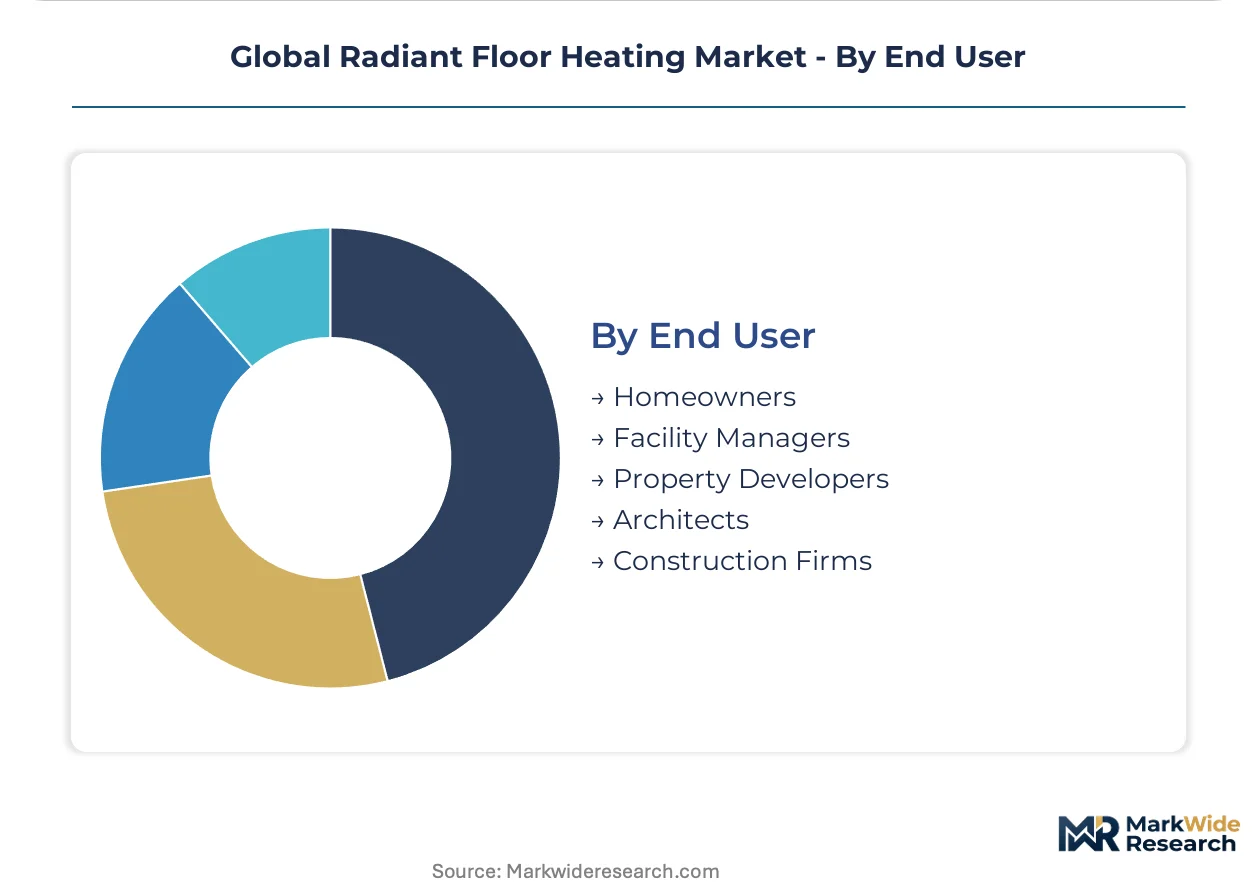
End User:
Procurement authority varies across project scale, technical sophistication, and channel access patterns.
- Property Developers:Multi-project volume procurement of standardized hydronic specifications for energy code pre-certification in Germany, China, and the United States. Developer decisions lock in system architecture before tenant occupancy.
- Homeowners:Single-project renovation demand concentrates in bathroom and basement zones, with digital configurators displacing traditional distributor showrooms for material take-off and room-by-room heat load calculation.
- Construction Firms:General contractors manage subcontractor coordination for manifold balancing and mixing valve calibration in hydronic commissioning.
- Facility Managers:Commercial building operators prioritize zone-level demand response integration with existing building management systems.
- Architects:Design-phase specification influence wanes as developer-led procurement consolidates system selection authority.
Property developers concentrate the largest contract values; homeowners fragment procurement across the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with favorable heat pump compatibility standards and subsidy density. Compliance cost differentials between the EU F-Gas Regulation and ASHRAE 90.1 thresholds are accelerating cross-border equipment sourcing.
Germany
Multi-family developers in Berlin and Hamburg are specifying PCM-enhanced screeds for renewable electricity load shifting. The national heat pump subsidy program (BAFA) covers system conversion costs for hydronic retrofits. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate manifold and mixing valve manufacturing for Nordic export markets.
United States
California and New York building performance standards are mandating demand-response capability in commercial retrofits. The EPA ENERGY STAR program establishes efficiency thresholds favoring low-temperature radiant distribution. Pacific Northwest metropolitan areas anchor electric radiant mat production for bathroom renovation channels.
China
Property developers in the Yangtze River Delta are integrating hydronic specifications for GB standard energy intensity compliance. Dual carbon goals mandate building efficiency reductions that align with underfloor systems in new residential construction. Manufacturing concentration in Shandong Province supplies cross-linked polyethylene piping for domestic and Southeast Asian markets.
Netherlands
Amsterdam and Rotterdam municipal renovation programs are replacing aging radiator networks with heat pump-compatible hydronic loops. The EU Green Deal building renovation targets compress project timelines for near-zero emissions compliance. Eindhoven-region engineering firms specialize in zone control firmware for integrated thermostat architectures.
France
Île-de-France social housing operators are deploying modular panel systems for rapid tenant reconfiguration without wet screed delays. National heat pump subsidy schemes are reshaping competitive balance between electric and hydronic architectures. Auvergne-Rhône-Alpes clusters concentrate aluminum diffusion layer fabrication for dry-installation commercial fit-outs.
Global Radiant Floor Heating Market Competitive Landscape
Strategic partnerships dominate the current landscape as component suppliers align with controls specialists to deliver integrated boiler-to-thermostat architectures. The vendor base fragments across three tiers: polymer piping specialists, integrated system providers, and controls-focused electronics manufacturers. Two archetypes define positioning: full-stack providers capturing developer-led procurement, and component specialists penetrating distributor channels. Competitive moves concentrate on technology licensing for zone control interoperability and geographic expansion through regional boiler manufacturer alliances.
Among Nordic-based polymer specialists, Uponor Corporation exemplifies the piping-centric archetype through captive supply of cross-linked polyethylene infrastructure. German integrated engineering groups including Robert Bosch GmbH and Danfoss A/S occupy positions spanning manifold calibration through mixing valve distribution optimization. These three anchors represent divergent strategic postures: materials specialization, full-system integration, and precision hydronics engineering.
| Leading Market Players |
|---|
| Uponor Corporation |
| Robert Bosch GmbH |
| Danfoss A/S |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| nVent Electric Plc |
| Warmup PLC |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access for hydronic system components, compressing permissible heating temperatures and forcing manufacturers to certify low-temperature compatibility. German and Chinese producers holding heat pump-aligned certifications command 15-20 point margin premiums over uncertified competitors, while uncertified suppliers face relegation to electric mat segments with compressed pricing power.
Pricing Analysis
Distributor margins in the 25-35 percent range dominate the hydronic segment, where specialized manifold and mixing valve assemblies pass through HVAC wholesaler networks before reaching installation contractors. Three-tier pricing structure across premium, standard, and economy levels separates Uponor-certified polymer piping from regional Asian cross-linked polyethylene and commodity electric cable imports. Pricing pressure stems from copper and polymer raw material volatility that compresses installer margins and delays project commitments. Property developers exhibit lowest price sensitivity due to multi-project volume procurement and energy code pre-certification requirements, while single-family homeowners in renovation channels demonstrate highest sensitivity and shift toward direct-to-consumer digital configurators.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Illinois anchor hub-and-spoke patterns for hydronic component fulfillment, with 72-hour coverage radii for major metropolitan construction markets. Manufacturing concentration centers on Germany for manifold and mixing valve precision engineering, China for cross-linked polyethylene piping extrusion, and the United States for electric radiant mat assembly. Raw material dependencies span copper for manifold castings, cross-linked polyethylene resin for piping, and aluminum for modular panel diffusion layers. Single-source vulnerability in specialized polymer formulations creates supply chain risk during petrochemical feedstock disruptions. Distribution runs through HVAC wholesaler networks for hydronic systems and direct-to-consumer digital channels for electric retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Radiant Floor Heating Market functions as a stable compounder, with regulatory mandates for building decarbonization and heat pump compatibility ensuring steady specification growth across new construction and deep retrofit cycles.
For Market Incumbents: Deepen backward integration into cross-linked polyethylene resin production to buffer against petrochemical feedstock volatility and secure margin stability. Incumbent suppliers should expand certified technician training programs in fragmented construction labor markets to alleviate commissioning bottlenecks that delay project timelines. The threat of electric resistance substitution in renovation segments demands defensive positioning through integrated boiler-to-thermostat control architectures that lock in system-level specification authority. For New Entrants and Emerging Players: Launch via direct-to-consumer digital configurators targeting single-family bathroom and basement retrofit demand in North America, where minimal structural disruption requirements favor thin-film electric mat penetration. White-space concentration sits in modular panel systems for commercial fit-outs demanding rapid deployment and tenant reconfiguration flexibility, particularly in French social housing and Dutch municipal renovation programs. The most penetrable segment is PCM-enhanced screed specification for multi-family developers in Germany and the Netherlands seeking renewable electricity load-shifting capability. For Investors and Strategic Acquirers: Valuations sit cheapest among controls-focused electronics manufacturers lacking integrated system architectures, presenting acquisition targets for private equity seeking platform consolidation. Long-term viability over the five-to-ten year window rests on heat pump subsidy program durability and EU Green Deal building renovation target enforcement. The signal to watch is national heat pump subsidy program expansion or contraction in Germany and France, which reshapes competitive balance between electric and hydronic system architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captive supply of cross-linked polyethylene raw material buffers German manufacturers against petrochemical volatility. |
| Certified Technician Training Programs | Manifold balancing and mixing valve calibration skills alleviate supply-side bottlenecks in fragmented construction labor markets. |
| Direct-to-Consumer Digital Configurator Launch | Room-by-room heat load calculators bypass distributor showrooms and capture North American renovation procurement shifts. |
| PCM-Enhanced Screed Specification Partnership | Thermal mass integration with German multi-family developers enables renewable electricity load-shifting and demand-response capability. |
| Zone Control Firmware Licensing | Interoperability agreements with existing building management systems reduce integration testing burdens for commercial facility managers. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down polymer piping and controls manufacturer tracking forms the analytical core of this study. Primary interviews with hydronic system installers, HVAC distributor procurement managers, multi-family property developers, and building energy code officials combined with secondary validation from EU F-Gas Regulation implementation reports, EPA ENERGY STAR certification databases, and national heat pump subsidy program disclosures. Triangulation across bottom-up project pipeline tracking and top-down production capacity analysis ensures segment-level accuracy.
Historical trendline analysis of installed system volumes across new construction and retrofit channels established baseline growth patterns without reliance on single-source projections. Segmentation dimensions modeled include thermal source architecture, installation type, building application, and procurement decision-maker authority, with regional regulatory cluster overlays for EU F-Gas, ASHRAE 90.1, and GB standards compliance. CAGRs derive from regression analysis of policy-driven retrofit mandate acceleration and heat pump adoption curves. Industry-specific forecast inputs incorporate phase-change material thermal mass adoption rates and dynamic electricity pricing algorithm penetration.
Several conditions sit outside the modeled scope, including abrupt subsidy program cancellations, copper and polymer commodity price shocks beyond historical volatility bands, and construction labor market disruptions affecting certified technician availability. Forecasts reflect assumptions about regulatory enforcement continuity and heat pump technology cost trajectories. Stakeholders should weight assumptions against their own operating context and regional policy exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Air Humidifier and Dehumidifier Market