
 Global Large Conveyor Chain Market | 2026-2036
Global Large Conveyor Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Large Conveyor Chain Market Outlook
Maintenance-as-a-service is expanding the recurring revenue base for large conveyor chain suppliers, shifting contracts from pure equipment sales to uptime guarantees and predictive replacement schedules. Tsubakimoto Chain Co., Ltd. leverages its Japanese manufacturing depth to anchor premium positioning in corrosion-resistant alloy formulations. SKF competes through integrated bearing-and-chain packages that reduce field assembly complexity for mining OEMs. Donghua sustains cost leadership via captive steel forging capacity in Zhejiang province.
Large conveyor chains are engineered power transmission and bulk material handling components, typically constructed from heat-treated carbon or alloy steel with pin-and-bushing joints rated for multi-tonne loads and continuous operation in abrasive environments. Their primary purpose is to move heavy raw materials, finished goods, or mineral ores through integrated production and logistics systems without slippage or elongation failure. Roller chains dominate installed base volumes due to standardized pitch dimensions and universal interchangeability across OEM platforms. Alloy steel formulations command margin premiums where thermal cycling and chemical exposure degrade standard carbon grades in cement and smelting applications. Stainless steel variants are gaining traction in food processing end uses where FDA and EFSA sanitary mandates prohibit surface corrosion and particulate contamination.
OSHA in the United States enforces guarding and lockout-tagout standards that dictate chain cover designs and maintenance access protocols, directly influencing product development cycles for North American suppliers. REACH and RoHS in Europe restrict hexavalent chromium coatings and certain alloy additives, compelling reformulation of corrosion protection layers across the supply base. China's GB standards and SAMR oversight harmonize domestic safety coefficients with export certification requirements. Stakeholders must monitor how divergent regional compliance timelines reshape sourcing geography and capital deployment priorities.
Market Dynamics
The EU F-Gas Regulation is forcing lubricant and sealant reformulation across the installed base, while Australian and Chilean mining expansions pull heavy-duty chain specifications toward higher load ratings and abrasive-environment durability.
Growth Catalysts
- EU F-Gas Regulation:Mandates lower-emission lubrication technologies in industrial equipment, accelerating demand for fluorinated-gas-free sealing systems in cement and steel applications.
- China's industrial corridor cities:Concurrent scaling of steel production and port logistics in clusters like Tangshan and Ningbo-Zhoushan is concentrating procurement volumes for multi-tonne conveying systems.
- Heat-treated alloy formulations:Thermal cycling resistance in smelting operations is displacing standard carbon grades, expanding margin pools for corrosion-resistant material suppliers.
Market Restraints
- Alloy steel input volatility:Nickel and molybdenum price swings compress margin predictability for heat-treatment-intensive manufacturers.
- Supply concentration in Zhejiang province:Captive forging capacity dependencies create geographic risk exposure for cost-optimized procurement strategies.
- REACH substance restrictions:Hexavalent chromium coating bans under ECHA oversight force corrosion-protection layer reformulation with unproven field durability.
Strategic Opportunities
- Maintenance-as-a-service models:Uptime guarantees and predictive replacement schedules are converting equipment sales into recurring revenue streams with higher lifetime value capture.
- Food processing sanitary mandates:FDA and EFSA surface-contamination prohibitions are opening stainless steel variant penetration in protein handling and dairy operations.
- Integrated bearing-chain packages:Field assembly complexity reduction for mining OEMs is creating specification lock-in through bundled component sourcing.
Industry Challenges
- Weld qualification and heat-treatment certification:Multi-jurisdictional pressure-vessel and lifting-equipment codes extend compliance timelines for new alloy introductions.
- Legacy pin-and-bushing interoperability:Decades of standardized pitch dimensions constrain proprietary design differentiation while fragmenting aftermarket capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Large Conveyor Chain Market |
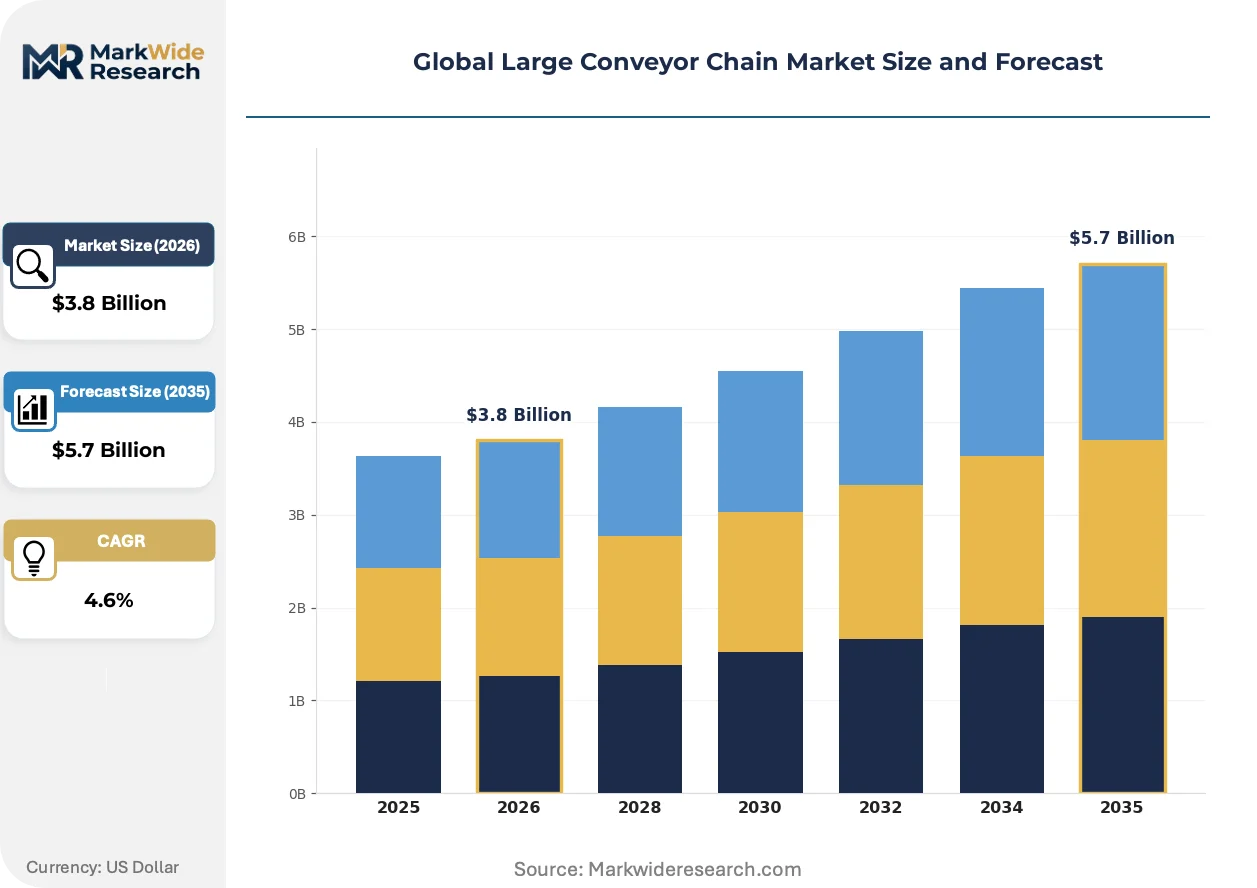
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Chains, Leaf Chains, Forklift Chains, Belt Chains Material: Stainless Steel, Carbon Steel, Plastic, Alloy Steel End User: Manufacturing, Food Processing, Mining, Automotive Installation: Fixed, Modular, Portable, Custom |
| Companies Covered | Timken, U.S. Tsubaki Inc., Rexnord, SKF, Regal Rexnord, Tsubakimoto Chain Co., Ltd., Iwis, Donghua, Renold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Large Conveyor Chain Market Strategic Shifts
Digital condition monitoring and predictive analytics are embedding into chain systems, converting mechanical components into data-generating assets that enable outcome-based service pricing and inventory optimization.
Self-lubricating polymer bushing inserts are consolidating maintenance intervals in remote mining installations. Rio Tinto and BHP specify these formulations for Pilbara iron ore conveyors where grease access points are kilometers apart. The technology is consolidating supplier value capture from lubricant sales toward higher-margin component replacement cycles.
REACH authorization requirements under ECHA oversight are eliminating hexavalent chromium conversion coatings from European supply chains. Manufacturers are trialing trivalent chromium and zinc-nickel alternatives with accelerated salt-spray validation protocols. Stainless steel roller chains are gaining specification share in German automotive press lines where RoHS compliance is non-negotiable.
Buyer consolidation among mining OEMs and integrated steel producers is compressing vendor qualification cycles and unbundling after-sales service from equipment procurement. Tier-one miners in Western Australia now mandate five-year total-cost-of-ownership guarantees that shift failure risk onto chain suppliers. This restructuring is visible in Pilbara and Carajás contract terms where uptime penalties exceed equipment purchase values.
Global Large Conveyor Chain Market Segmentation
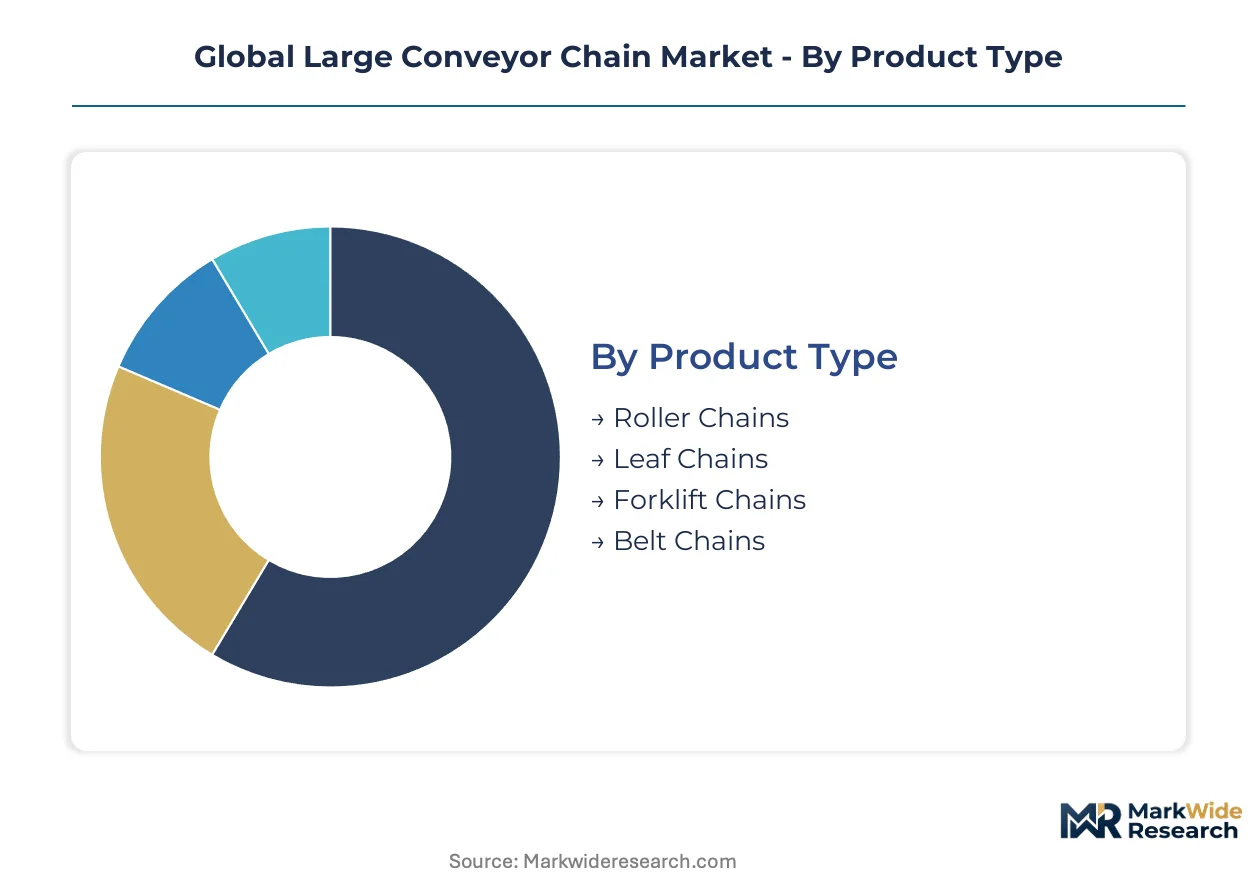
Segmentation in large conveyor chains maps directly to load-bearing requirements, environmental exposure, and maintenance access constraints. Procurement specifications diver sharply between continuous-duty mining installations and intermittent manufacturing lines. Understanding these divisions clarifies where margin pools concentrate and which material formulations command specification premiums.
Product Type:
Technology differentiation in chain architecture determines interchangeability, field serviceability, and load distribution characteristics across OEM platforms.
- Roller Chains:Pin-and-bushing joints with cylindrical rollers reduce friction in multi-tonne conveying applications. Standardized pitch dimensions enable universal interchangeability across mining OEM platforms in Australia and Chile. Demand concentrates in iron ore and copper bulk handling where continuous operation cycles exceed 8,000 hours annually.
- Leaf Chains:Stacked link plates without rollers provide high tensile strength in lifting and counterbalance applications. Forklift mast assemblies and overhead crane systems in German automotive press lines specify these for vertical load handling. Heat-treated alloy formulations are displacing carbon grades where thermal cycling from welding operations degrades standard materials.
- Forklift Chains:Hardened pin and bushing assemblies rated for mast lifting cycles in material handling equipment.
- Belt Chains:Hybrid designs integrating chain tensile members with rubber or polymer conveying surfaces for bulk material transport.
Mature deployment sits with Roller Chains. Newer deployment is concentrated in Belt Chains where hybrid designs reduce spillage in food processing sanitary environments.
Material:
Cost tier and performance durability separate procurement specifications across abrasive, corrosive, and sanitary operating environments.
- Carbon Steel:Heat-treated through-hardened grades dominate installed base volumes where capital constraints prioritize initial acquisition cost over lifecycle replacement. Standard formulations face displacement in cement and smelting applications where thermal cycling accelerates elongation failure. Chinese steel production corridors in Tangshan specify these for high-volume, low-margin conveying infrastructure.
- Alloy Steel:Nickel-molybdenum formulations deliver thermal cycling resistance and abrasive wear durability in continuous-duty mining environments. Pilbara iron ore conveyors and Chilean copper operations mandate these specifications for 50,000-hour design life. REACH substance restrictions on hexavalent chromium coatings are forcing reformulation of corrosion protection layers with unproven field durability.
- Stainless Steel:Austenitic and martensitic grades satisfy FDA and EFSA sanitary mandates prohibiting surface corrosion in protein handling operations.
- Plastic:Self-lubricating polymer formulations reduce maintenance intervals in remote installations where grease access points are kilometers apart.
Volume concentration rests with Carbon Steel. Steepest expansion trajectory belongs to Stainless Steel as food processing sanitary mandates proliferate across European and North American protein handling operations.
End User:
Application severity and uptime penalty structures reshape supplier contract terms and material specification thresholds.
- Mining:Pilbara and Carajás contract terms now mandate five-year total-cost-of-ownership guarantees with uptime penalties exceeding equipment purchase values. Heavy-duty specifications pull toward higher load ratings and abrasive-environment durability as Australian and Chilean expansions accelerate.
- Manufacturing:Automotive press lines and steel production facilities in China's industrial corridor cities concentrate procurement volumes for multi-tonne conveying systems. OSHA guarding standards and lockout-tagout protocols directly influence chain cover designs for North American automotive assembly plants.
- Food Processing:FDA and EFSA surface-contamination prohibitions are opening stainless steel variant penetration in dairy and protein handling operations.
- Automotive:Just-in-time assembly lines require standardized pitch dimensions for rapid field replacement without line stoppage.
Established specification dominance belongs to Mining. Emerging specification growth centers on Food Processing as regulatory mandates tighten across European and North American sanitary environments.
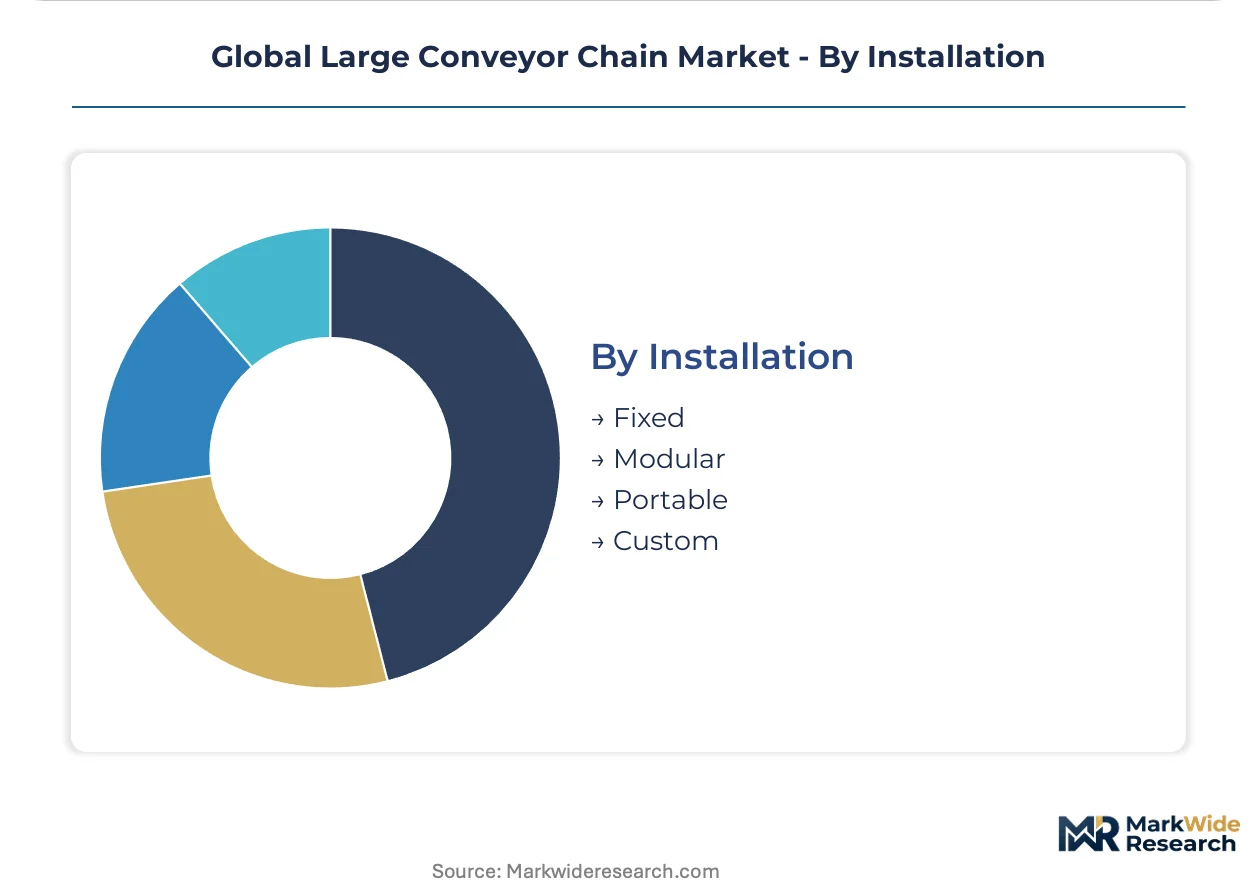
Installation:
Capital deployment flexibility and relocation frequency determine whether procurement favors permanent foundations or reconfigurable architectures.
- Fixed:Permanent anchoring systems for continuous-duty bulk material handling in mining and integrated steel production. Australian iron ore operations and Chinese port logistics clusters in Ningbo-Zhoushan specify these for 20-year design life infrastructure.
- Modular:Pre-engineered sections enabling rapid reconfiguration as production layouts shift in contract manufacturing and automotive assembly.
- Portable:Skid-mounted or trailer-based systems for temporary construction aggregate processing and remote exploration drilling support.
- Custom:Engineered-to-order configurations for unique geometric constraints in ship loading and specialized smelting furnace feed systems.
Capital deployment concentration sits with Fixed installations. Procurement momentum is shifting fastest toward Modular systems as contract manufacturers prioritize line reconfiguration flexibility over permanent infrastructure commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of large conveyor chain tonnage while Australia and Chile consume the heaviest-duty specifications for mining. Production capacity clusters in Zhejiang province serve export markets across Asia-Pacific and Europe. Demand pull concentrates in iron ore belts and industrial corridor cities where steel production and port logistics scale simultaneously.
Australia
Pilbara iron ore operations mandate five-year total-cost-of-ownership guarantees with uptime penalties exceeding equipment purchase values. TGA oversight harmonizes pressure-equipment safety coefficients with ISO standards for mining infrastructure. Perth-based procurement offices coordinate specification standards for BHP and Rio Tinto conveyor networks across Western Australia.
China
Tangshan steel production corridors and Ningbo-Zhoushan port logistics clusters concentrate procurement volumes for multi-tonne conveying systems. SAMR enforcement of GB standards tightens safety coefficients for domestic and export certification alignment. Zhejiang province forging capacity supplies cost-optimized chain to Southeast Asian cement and smelting operations.
Germany
Automotive press lines in Bavaria and Baden-Württemberg specify stainless steel roller chains where RoHS compliance eliminates hexavalent chromium coatings. REACH authorization under ECHA oversight forces trivalent chromium and zinc-nickel corrosion protection trials. Ruhr Valley steel production facilities source heat-treated alloy formulations for thermal cycling resistance in continuous-duty environments.
United States
OSHA guarding standards and lockout-tagout protocols dictate chain cover designs for North American automotive assembly plants. EPA emissions guidelines intersect with state-level industrial equipment regulations in California and Texas manufacturing corridors. Great Lakes steel production and Appalachian coal handling operations pull heavy-duty specifications toward abrasive-environment durability.
Chile
Copper mining expansions in the Atacama Desert pull chain specifications toward higher load ratings and extreme abrasion resistance. National mining regulator SERNAGEOMIN aligns equipment safety protocols with international pressure-vessel codes. Antofagasta and Calama industrial clusters concentrate maintenance infrastructure for Codelco and Anglo American conveying systems.
Global Large Conveyor Chain Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent margin structures in the large conveyor chain market. Integrated foundry operators capture alloy formulation premiums while specialized fabricators focus on modular assembly and aftermarket service contracts. Three archetypes dominate: Japanese and European precision manufacturers, Chinese cost-optimized forging operations, and integrated bearing-and-chain bundlers. Competitive moves center on predictive maintenance service contracts and captive steel supply consolidation.
Among Japanese precision manufacturers, Tsubakimoto Chain Co., Ltd. and U.S. Tsubaki Inc. exemplify the premium-tier archetype anchored in corrosion-resistant alloy expertise. Donghua occupies a position within the Chinese cost-leadership tier leveraging Zhejiang-based captive forging capacity. SKF represents the integrated bundler archetype where bearing-and-chain packages reduce field assembly complexity for mining OEMs.
| Leading Market Players |
|---|
| Timken |
| U.S. Tsubaki Inc. |
| Rexnord |
| SKF |
| Regal Rexnord |
| Tsubakimoto Chain Co., Ltd. |
| Iwis |
| Donghua |
| Renold |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating fluorinated-gas-free sealing systems, forcing reformulation costs onto manufacturers while concentrating procurement among certified suppliers. Buyers in cement and steel applications now face tiered qualification barriers that stratify pricing power across compliant and non-compliant supply bases.
Pricing Analysis
Margin tightening in standard carbon steel grades reflects nickel and molybdenum price volatility compressing heat-treatment-intensive manufacturers. Three-tier pricing structure across premium, standard, and economy levels differentiates by alloy formulation and REACH certification status. Cost-down pressure on alloy formulations accelerates because REACH hexavalent chromium bans force corrosion-protection layer trials with unproven durability. Mining OEMs in Western Australia exhibit lowest price sensitivity due to uptime penalty structures, while Chinese steel corridor procurement offices show highest sensitivity to initial acquisition cost.
Supply Chain Analysis
REACH and RoHS certification gating restricts European supply base participation while concentrating qualified forging capacity in China, Japan, and Germany. Raw material dependencies draw from nickel-molybdenum alloy feedstock, heat-treatment energy inputs, and specialized corrosion-resistant coating chemistries. Single-source vulnerability concentrates in Zhejiang province captive forging operations serving cost-optimized procurement strategies. Distribution runs through mining OEM procurement offices, integrated steel producer technical specifications, and aftermarket service depots in Pilbara and Carajás clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive steel forging capacity determines margin capture and specification lock-in. Players pursue upstream control over alloy formulation and heat-treatment certification to defend positioning against integrated bearing-and-chain bundlers.
For Market Incumbents: Extend predictive maintenance service contracts to convert equipment sales into recurring revenue streams with higher lifetime value capture. Defend against SKF-style integrated bundlers by deepening in-house production of corrosion-resistant alloy formulations and securing TGA-recognized weld qualification certifications for Australian mining contracts.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in stainless steel food processing variants offers white-space entry as FDA and EFSA mandates proliferate across European and North American protein handling operations. Target modular installation architectures in contract manufacturing where line reconfiguration flexibility commands specification premiums. Pursue go-to-market partnerships with dairy equipment OEMs seeking RoHS-compliant supply alternatives.
For Investors and Strategic Acquirers: Five-year total-cost-of-ownership guarantee adoption by Pilbara miners is the leading indicator that failure-risk transfer to suppliers is restructuring contract economics toward service-heavy revenue models. Long-term viability favors vertically integrated specialists with captive forging and certified heat-treatment infrastructure. Watch for SERNAGEOMIN alignment with international pressure-vessel codes as the inflection signal for Chilean copper expansion procurement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive nickel-molybdenum capacity insulates margin from raw material volatility in Pilbara contracts. |
| Predictive Maintenance Service Launch | Uptime guarantees convert BHP and Rio Tinto equipment sales into recurring revenue with penalty-backed pricing. |
| REACH-Compliant Coating Certification | Trivalent chromium validation opens German automotive press line specifications closed to hexavalent alternatives. |
| Modular Installation Platform Development | Pre-engineered reconfigurable sections capture contract manufacturing demand in China's industrial corridor cities. |
| Stainless Steel Variant Scale-Up | FDA-compliant surface finishes penetrate dairy and protein handling operations under tightening EFSA oversight. |
Study Parameters
Multi-period observation of mining expansion capital deployment, REACH regulatory compliance timelines, and alloy steel price indices anchored the trend analysis, supplemented by interviews with maintenance directors at Pilbara iron ore operations, OEM procurement teams in German automotive press lines, plant engineers in Tangshan steel corridors, and aftermarket service heads in Chilean copper clusters. Secondary validation drew from customs and trade data, SEC filings of listed chain manufacturers, ECHA substance restriction databases, and SAMR GB standards documentation. Bottom-up segmentation sizing and top-down market triangulation cross-verified volume and value estimates.
The input-output matrix framed demand modeling across product type, material grade, end-use severity, and installation permanence dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate blending anchored to mining capital expenditure cycles and food processing regulatory mandate adoption curves. Industry-specific forecast inputs incorporated thermal cycling resistance specifications in smelting applications and self-lubricating polymer bushing penetration rates in remote mining installations.
Inputs from maintenance service contract databases and regulatory filing repositories were available through the study window; gaps in real-time alloy steel spot pricing and undisclosed OEM qualification timelines introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding REACH enforcement consistency and mining expansion commitment durability. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or SERNAGEOMIN equipment safety protocol alignment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Vibrating Feed Conveyors Market