
 Tooling Market | 2026-2036
Tooling Market Size, Share, and Industry Trends Forecast 2026-2036
Tooling Market Intelligence
The EU Green Deal's embodied-carbon tracking mandate for industrial equipment is rebalancing procurement criteria toward energy-efficient machining platforms. DMG Mori leverages its integrated spindle and control architecture to capture premium positioning in climate-accounted purchasing. Sandvik Coromant anchors its competitive stance through captive cemented-carbide supply and tool-recycling infrastructure. Kennametal differentiates by specializing in wear-resistant grades for hard-turning applications in automotive transmission lines.
Tooling encompasses the design, fabrication, and maintenance of precision implements — including cutting tools, molds, dies, jigs, and fixture systems — typically engineered from high-speed steel, cemented carbide, or ceramic matrix composites to tolerances of micrometers. These implements enable dimensional accuracy in subtractive and formative manufacturing processes across metalworking, plastics forming, and composite fabrication industries. CNC Machines command the largest product-type revenue pool due to capital intensity and replacement cycles, while Additive Manufacturing tooling for conformal-cooled mold inserts represents the fastest-expanding technology segment. Among end users, Aerospace and Medical Devices concentrate the highest margin opportunities because of certification-driven supplier stickiness and low-volume, high-mix production economics.
EMA's machinery safety directives, EPA metalworking effluent standards, and China's GB/T precision-tool certification framework collectively elevate compliance costs for market entry. These regimes favor incumbents with established testing protocols and traceable supply chains. Stakeholders must weigh regulatory certification timelines against product development cycles when allocating R&D budgets across geographies.
Market Dynamics
Electric powertrain platforms are forcing automotive OEMs to retool entire production lines, triggering a wave of precision tooling demand that concentrates around Stuttgart and Aachen in Germany's machine tool cluster. This platform shift compresses replacement cycles and elevates tolerance requirements simultaneously.
Growth Catalysts
- REACH Compliance:Europe's tightening material composition mandates for cutting tools are accelerating certified supplier consolidation, favoring producers with traceable cemented-carbide supply chains.
- Electric Powertrain Expansion:Automotive OEMs in Germany and China are launching dedicated tooling programs for motor housing and battery tray machining, creating sustained demand for five-axis machining centers.
- Ceramic Matrix Composites:Aerospace heat shield and turbine blade applications are pulling diamond-coated tooling into high-temperature machining environments previously dominated by carbide.
Market Restraints
- Tungsten Supply Concentration:China controls roughly 80% of global tungsten ore processing, exposing cemented-carbide producers to export quota volatility and geopolitical supply risk.
- GB Standards Certification:China's precision-tool certification framework imposes 12-18 month testing timelines that lock out unestablished foreign entrants from defense and medical device supply chains.
- Additive Manufacturing Substitution:Metal powder bed fusion for mold inserts is capturing low-volume conformal cooling applications that previously required machined tool steel cores.
Strategic Opportunities
- Tool-Recycling Infrastructure:EU Green Deal embodied-carbon tracking creates first-mover advantage for producers offering closed-loop carbide reclamation with verified Scope 3 reductions.
- Medical Device Micro-Machining:ISO 13485-certified tooling for orthopedic implant finishing represents an underpenetrated margin pool with 10-year supplier lock-in typical of FDA PMA device categories.
- India PLI Scheme:Production-linked incentives for precision manufacturing are drawing machine tool investments to Pune and Bangalore, creating localized tooling demand without import duty exposure.
Industry Challenges
- CAM Programming Talent:Shortage of operators capable of five-axis toolpath optimization for freeform mold surfaces is extending job setup times and constraining spindle utilization rates.
- Legacy Control Integration:Retrofitting Industry 4.0 data collection onto 1990s-era FANUC and Siemens CNC architectures requires custom middleware development that fragments IIoT rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tooling Market |
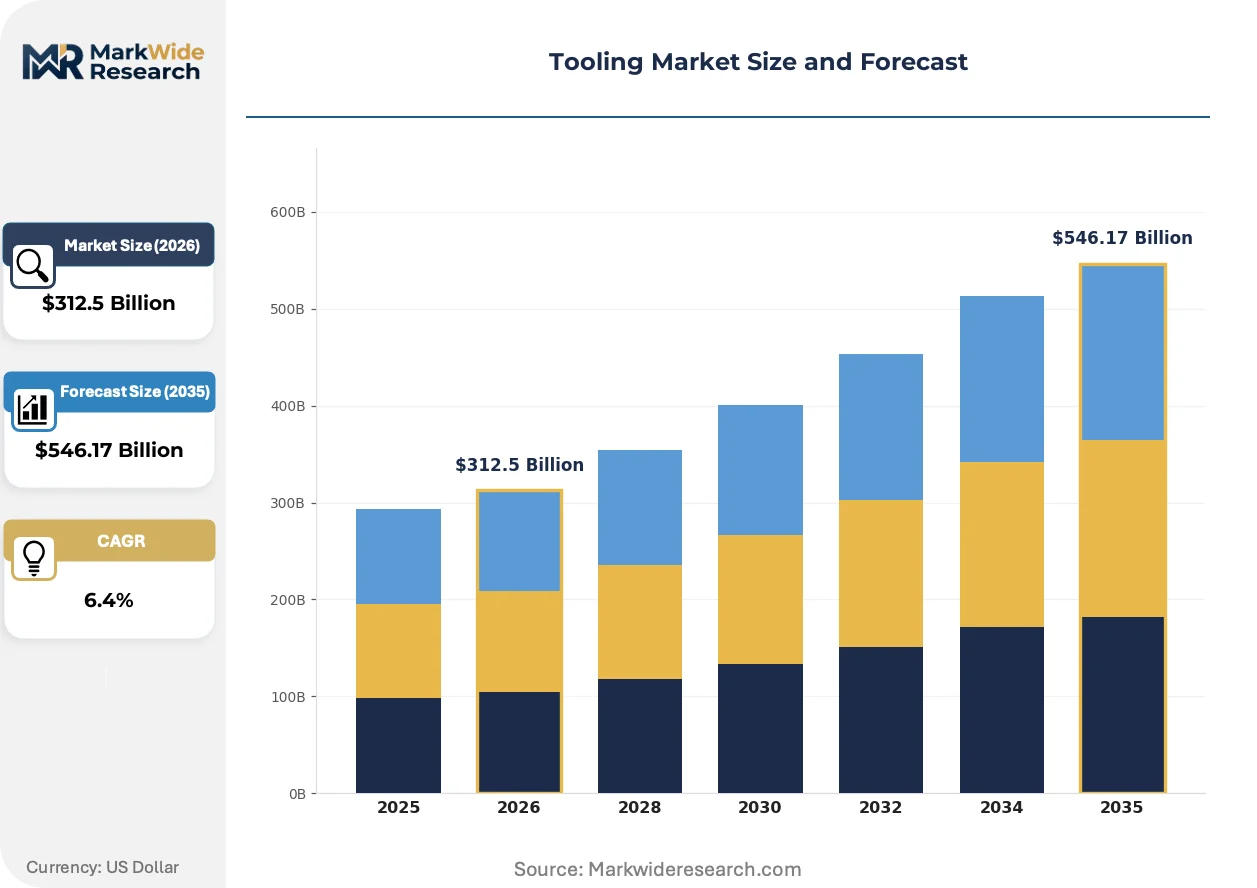
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $546.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Machines, Molds, Dies, Jigs End User: Aerospace, Automotive, Electronics, Medical Devices Technology: Additive Manufacturing, Subtractive Manufacturing, Laser Cutting, 3D Printing Application: Prototyping, Production, Maintenance, Tool Repair |
| Companies Covered | Doosan Machine Tools, DMG Mori, Sandvik Coromant, Mitsubishi Materials Corporation, Carlson Tool & Manufacturing Corp., Bharat Forge Limited, Kennametal Inc., Kyocera Corporation, Yamazaki Mazak Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tooling Market Strategic Shifts & Innovations
Digital twin workflows and embedded sensor architectures are compressing tool life prediction from statistical estimation to real-time physics-based modeling. This shift reconfigures maintenance economics and supplier value capture.
Hybrid manufacturing platforms combining directed energy deposition with five-axis machining is modularizing mold repair and modification workflows. Die casters in automotive supply chains are adopting these systems to extend die life rather than replacing worn inserts. The technology is compressing lead times for engineering change orders from weeks to days.
EPA metalworking effluent standards are forcing aqueous coolant system overhauls across US Midwest machining clusters. Facilities are migrating to minimum quantity lubrication and cryogenic cooling to eliminate wastewater treatment capex. Medical device manufacturers in Minnesota and Connecticut are most affected due to tight particulate discharge limits near municipal watersheds.
Buyer consolidation among tier-one automotive suppliers is unbundling after-sales service contracts from initial tooling purchases. Procurement teams at German transmission specialists now negotiate tool life guarantees separately from cutting tool supply, shifting performance risk to manufacturers. This pattern is most visible in powertrain machining contracts where spindle hour costs dominate total cost of ownership calculations.
Tooling Market Segmentation
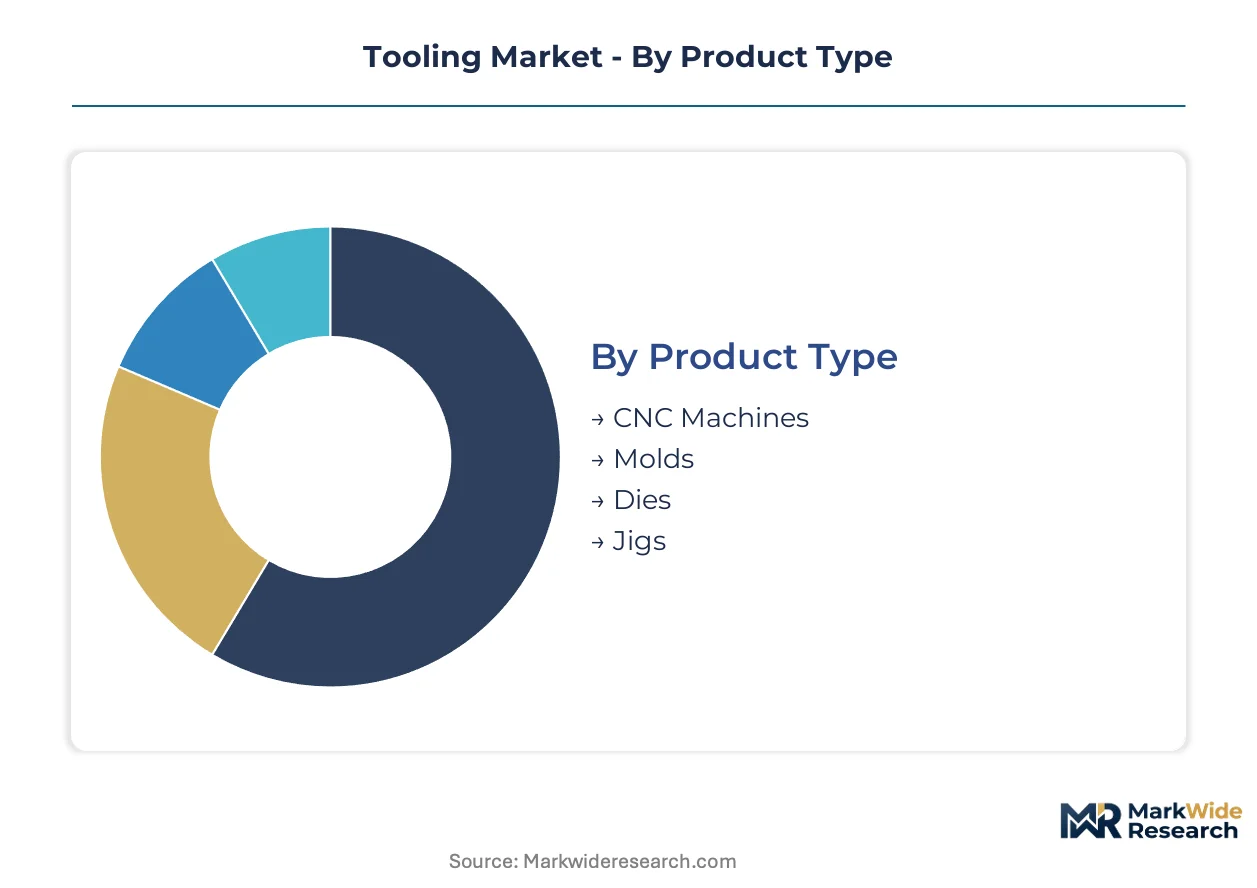
Tooling procurement decisions hinge on matching capital intensity against production economics. Buyers weigh spindle-hour costs, certification requirements, and platform flexibility when allocating budgets across product categories and end-use verticals.
Product Type:
Capital deployment cycles and tolerance specifications drive buyer selection across equipment categories.
- CNC Machines:Five-axis machining centers with integrated spindle and control architectures dominate capital expenditure pools. Demand concentrates in Stuttgart and Aachen for electric powertrain housing production, where REACH-compliant coolant systems are becoming mandatory.
- Molds:Conformal-cooled tool steel and aluminum injection molds enable complex geometries for automotive interior panels. Electronics manufacturers in China's Pearl River Delta are retooling for thinner-wall smartphone housing production.
- Dies:Progressive and transfer dies for high-volume stamping operations, typically engineered from tool steel with PVD coatings. Automotive transmission lines in Germany specify wear-resistant grades for hard-turning applications.
- Jigs:Precision fixturing systems for assembly line repeatability, fabricated from aluminum or carbon fiber composites. Medical device manufacturers in Minnesota prioritize ISO 13485-certified jig suppliers for orthopedic implant finishing.
Volume sits with CNC Machines; growth tilts toward Additive Manufacturing-integrated mold inserts.
End User:
Certification barriers and production economics create divergent margin profiles across customer verticals.
- Aerospace:Heat shield and turbine blade machining pulls diamond-coated tooling into high-temperature environments previously dominated by carbide. EASA and FAA certification requirements lock in supplier relationships for 7-10 year contract cycles.
- Automotive:Electric powertrain platforms are forcing complete production line retooling, compressing replacement cycles and elevating tolerance requirements simultaneously. OEMs in Germany and China are launching dedicated tooling programs for motor housing and battery tray machining.
- Electronics:Miniaturization trends drive demand for micro-machining centers capable of sub-micron positioning. China's GB/T precision-tool certification framework governs defense and medical device supply chain access.
- Medical Devices:Orthopedic implant finishing and surgical instrument production require FDA PMA-aligned process validation. Minnesota and Connecticut facilities face tight EPA particulate discharge limits near municipal watersheds.
Revenue concentrates in Automotive; margin expansion is steepest in Medical Devices.
Technology:
Process selection balances geometric complexity against throughput requirements and material constraints.
- Subtractive Manufacturing:Conventional milling, turning, and grinding operations using cemented-carbide or ceramic cutting tools. Germany's machine tool cluster anchors global demand for five-axis platforms with real-time tool wear monitoring.
- Additive Manufacturing:Metal powder bed fusion for conformal-cooled mold inserts captures low-volume applications that previously required machined tool steel cores. Aerospace heat management applications are expanding fastest.
- Laser Cutting:High-power fiber and CO2 systems for sheet metal processing, with beam delivery optimized for reflective materials. Automotive OEMs specify these for electric vehicle battery tray fabrication.
- 3D Printing:Polymer and metal deposition systems for rapid prototyping and bridge tooling. Electronics manufacturers use these for smartphone housing design validation before hard tooling commitment.
Installed base favors Subtractive Manufacturing; capability investment flows toward Additive Manufacturing.
Application:
Lifecycle stage determines equipment specification, with maintenance economics gaining procurement attention.
- Production:High-volume manufacturing with automated tool change and in-process measurement. Tier-one automotive suppliers now negotiate tool life guarantees separately from cutting tool supply, shifting performance risk to manufacturers.
- Maintenance:Scheduled tooling replacement and spindle refurbishment to prevent unplanned downtime. Digital twin workflows are compressing maintenance intervals from statistical estimation to real-time physics-based modeling.
- Prototyping:Low-volume validation runs using soft tooling or additive methods before hard tooling capital commitment. Medical device developers in FDA PMA categories require 10-year supplier lock-in from prototype through production.
- Tool Repair:Hybrid manufacturing platforms combining directed energy deposition with five-axis machining modularize mold repair workflows. Die casters are adopting these to extend die life rather than replacing worn inserts.
Capital allocation prioritizes Production; hybrid repair platforms are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global precision tooling demand through its concentration of automotive OEMs retooling for electric powertrain platforms. Germany's machine tool cluster generates sustained orders for five-axis machining centers and certified cutting tool systems.
United States
EPA metalworking effluent standards are forcing coolant system overhauls across Midwest machining clusters. Minnesota and Connecticut medical device manufacturers face tight particulate discharge limits near municipal watersheds. Aerospace heat shield programs in California and Washington pull diamond-coated tooling into high-temperature machining environments.
China
GB standards certification imposes 12-18 month testing timelines that govern defense and medical device supply chain access. The country's dual carbon goals accelerate demand for energy-efficient machining platforms in motor housing production. Pearl River Delta electronics manufacturers retool for thinner-wall smartphone housing fabrication.
Japan
METI industrial policy supports ceramic matrix composite tooling development for turbine blade applications. JIS standards certification maintains supplier stickiness in aerospace and medical device verticals. Nagoya's automotive supply chain concentrates demand for wear-resistant hard-turning grades.
India
PLI scheme production-linked incentives draw machine tool investments to Pune and Bangalore without import duty exposure. BIS standards compliance elevates entry barriers for precision-tool certification. Gujarat and Tamil Nadu automotive component clusters expand captive tooling capabilities.
South Korea
Busan-Ulsan shipbuilding and automotive corridors generate demand for large-format five-axis platforms. MFDS medical device regulations align tooling validation requirements with FDA PMA standards. Seoul Capital Area semiconductor equipment manufacturers specify sub-micron positioning systems.
Tooling Market Key Industry Players
The competitive structure tilts toward integrated spindle and control architecture specialists. Cemented-carbide producers with captive tungsten supply chains and established tool-recycling infrastructure command premium positioning. Two strategic archetypes dominate: full-platform machine tool builders and specialized cutting tool material scientists. Consolidation proceeds through vertical integration into carbide powder processing and strategic partnerships for conformal-cooled mold insert development.
Among Japanese machine tool builders, Yamazaki Mazak Corporation and Mitsubishi Materials Corporation occupy positions emphasizing integrated platform architectures. DMG Mori exemplifies the European archetype combining machine tool production with climate-accounted procurement positioning. Sandvik Coromant anchors the specialized cutting tool tier through cemented-carbide material science dominance.
| Leading Market Players |
|---|
| Doosan Machine Tools |
| DMG Mori |
| Sandvik Coromant |
| Mitsubishi Materials Corporation |
| Carlson Tool & Manufacturing Corp. |
| Bharat Forge Limited |
| Kennametal Inc. |
| Kyocera Corporation |
| Yamazaki Mazak Corporation |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's embodied-carbon tracking mandate gates both qualified supply and premium-tier pricing access, forcing tooling producers to invest in closed-loop carbide reclamation infrastructure before bidding on climate-accounted procurement contracts. Buyers in Germany's machine tool cluster now require verified Scope 3 reductions as table stakes, compressing margins for suppliers without captive recycling capabilities while rewarding first movers with pricing power.
Pricing Analysis
Tool life guarantees tied to spindle-hour throughput anchor value-based pricing for cutting tool contracts in automotive powertrain machining. Pricing stratifies across certified premium grades with REACH-compliant material traceability, standard grades for general metalworking, and economy tiers for non-critical prototyping applications. Cost compression in economy carbide inserts is intensifying because Chinese powder metallurgy producers are expanding export volumes. Tier-one automotive suppliers exhibit lowest price sensitivity due to total cost of ownership calculations that weight downtime risk above unit tool cost.
Supply Chain Analysis
Tungsten ore processing rests on Chinese state-controlled refiners that command roughly four-fifths of global supply, exposing cemented-carbide producers to export quota volatility and geopolitical disruption. Tool steel feedstock draws from German and Austrian specialty mills, while ceramic matrix composite precursors feed from Japanese chemical producers. Single-source vulnerability concentrates in tungsten concentrate supply, where alternative African and Vietnamese mine development lags demand growth. Distribution runs through authorized distributor networks for certified cutting tools, with direct OEM supply relationships dominating five-axis machining center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated spindle and control architecture specialists, with REACH compliance timelines and captive tungsten supply requirements forcing capital-constrained regional players toward exit or acquisition.
For Market Incumbents: Acquire captive cemented-carbide powder processing assets to secure tungsten supply chain resilience against Chinese export quota volatility. Expand tool-recycling infrastructure in Germany to capture EU Green Deal procurement premiums. Additive manufacturing substitution for conformal-cooled mold inserts threatens traditional tool steel core machining volumes, requiring hybrid manufacturing platform investments to defend service revenue streams. For New Entrants and Emerging Players: Digital tooling-as-a-service platforms offer a route to bypass capital-intensive machine tool manufacturing while capturing aftermarket value through predictive maintenance subscriptions. Target medical device micro-machining in Minnesota and Connecticut, where ISO 13485 certification barriers deter established automotive-focused competitors. Lead with five-axis CAM programming talent acquisition to differentiate on job setup time reduction. For Investors and Strategic Acquirers: DMG Mori's climate-accounted procurement positioning is the leading indicator that energy-efficient machining platforms will command valuation premiums across the European supply base. Five-to-ten year viability favors specialized cutting tool material scientists with captive tungsten supply and established recycling infrastructure over pure-play machine tool assemblers. Watch for GB standards certification backlog clearance as a signal that Chinese defense and medical device supply chain access is opening to foreign entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tungsten Supply Integration | Backward integration into ore processing mitigates Chinese export quota exposure for carbide producers. |
| Closed-Loop Carbide Reclamation | Verified Scope 3 reductions unlock EU Green Deal procurement contracts in Stuttgart and Aachen clusters. |
| Hybrid Manufacturing Platform Deployment | Directed energy deposition plus five-axis machining compresses mold repair lead times for die casters. |
| ISO 13485 Certification Investment | FDA PMA-aligned process validation enables 10-year supplier lock-in for orthopedic implant finishing. |
| Five-Axis CAM Programming Talent Acquisition | Toolpath optimization expertise extends spindle utilization rates and reduces job setup times. |
Research Approach
Multi-period observation of electric powertrain platform retooling cycles, REACH compliance certification timelines, and tungsten export quota patterns anchored the trend analysis, supplemented by interviews with plant engineers at automotive OEMs, procurement leads at Tier 1 transmission suppliers, aftermarket service heads at machine tool distributors, and technical R&D directors at cemented-carbide producers. Secondary validation drew from SEC filings of listed machine tool builders, ECHA REACH registration databases, German machinery association order intake statistics, and Chinese customs tungsten concentrate trade data. Bottom-up tooling demand estimates triangulated against top-down manufacturing capital expenditure forecasts.
Segment-weighting across CNC machines, molds, dies, and jigs by end-use vertical combined with technology splits between subtractive and additive manufacturing informed the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles and platform shift acceleration effects. Modeled dimensions included product type capital intensity, end-user certification requirements, and regional regulatory cluster stringency. Forecast inputs incorporated electric vehicle production ramp schedules and GB standards certification backlog assumptions.
The model holds under stable tungsten supply and gradual REACH compliance phase-in; deviation in Chinese export quota severity or EU carbon border adjustment timing would shift tooling demand geography and margin distribution. Forecasts reflect documented assumptions about powertrain platform transition rates and certification timeline elasticity. A small set of named triggers—tungsten supply disruption, GB standards acceleration, and additive manufacturing cost parity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Post Drivers Market
Tools
Thickness Planers Market
Tools
Riveting Tools Market
Tools
Fine Blanking Tools Market
Tools
Woodworking Circular Saw Blades Market
Tools
Spray Painting Machine Market
Tools
Global Scarifiers Market
Tools
Reamer Market
Tools
Landscaping Tools Market
Tools
Mallets and Sledgehammers Market
Tools
Air Drills Market
Tools
Stationary Wood Planer Market
Tools
Tool Boxes Market
Tools
Tool Hammer Market
Tools
Spindle Shaper Market
Tools
Handheld Engraving Machine Market