
 Lever Hoist Market | 2026-2036
Lever Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Lever Hoist Market Analytics
Industrial distribution is narrowing as specialized lifting-equipment distributors consolidate shelf space around certified brands. Columbus McKinnon leverages its vertical integration across forged alloy chain and braking systems to control cost and delivery reliability. KITO Corporation anchors its position through precision manufacturing in Japan and deep stock positions in Southeast Asia. Harrington Hoists differentiates via compact lever designs aimed at utility and entertainment rigging segments where headroom constraints dominate specification.
A lever hoist is a portable, manually or power-operated lifting device that uses a ratchet and pawl mechanism to multiply force through a lever arm, typically handling loads from 500 kg to 3,000 kg with hardened alloy steel chain. Its primary purpose is to lift, pull, or position heavy materials in confined spaces where electric overhead cranes cannot operate. Manual lever hoists still command the largest volume base due to their independence from power sources and minimal maintenance, though electric variants capture expanding share in repetitive manufacturing workflows. Chain lever hoists concentrate margin pools in the 2,000–3,000 kg capacity band where mining and heavy construction specify proof-tested components.
OSHA, ASME B30.21, and ISO 12100 collectively govern load testing, ergonomic design, and machinery safety integration for lever hoists sold into North American and export markets. These frameworks compel manufacturers to maintain traceable calibration records and third-party certification, raising barriers for uncertified imports. Stakeholders must monitor how impending updates to ASME B30 standards address powered lever hoist electrification and remote-operation safety protocols.
Market Dynamics
OSHA and ASME B30.21 compliance mandates are forcing wholesale replacement of uncertified lever hoists across North American industrial facilities, compressing procurement cycles and redistributing volume toward proof-tested suppliers with traceable calibration records.
Growth Catalysts
- Utility Infrastructure Modernization:Grid hardening programs across the United States require compact lever hoists for transformer installation and transmission line maintenance in remote terrain where powered equipment cannot access.
- ASME B30.21 Load Testing Mandates:Third-party certification requirements for manual lifting equipment eliminate gray-market imports and consolidate demand around documented proof-test protocols.
- Mining Sector Mechanization:Underground operations in Australia and Canada specify hardened alloy chain lever hoists for ventilation shaft maintenance and mobile equipment repair in confined headings.
Market Restraints
- Alloy Steel Input Volatility:Nickel and chromium price swings compress margin predictability for forged chain manufacturers dependent on spot-market raw material procurement.
- Single-Source Forging Concentration:Southeast Asian heat-treatment capacity bottlenecks create delivery risk for North American distributors requiring rapid replacement cycles.
- Electric Winch Substitution:Repetitive manufacturing workflows increasingly specify variable-frequency drive hoists that eliminate manual operator fatigue in high-cycle environments.
Strategic Opportunities
- Entertainment Rigging Penetration:Concert touring and permanent venue installation in Germany and the United Kingdom demand compact headroom lever designs for truss positioning above audience areas.
- Wind Turbine Maintenance Access:Nacelle gearbox replacement protocols require portable manual hoists for blade pitch system repair at heights where electrical supply is unreliable.
- India BIS Certification Gap:Domestic infrastructure contractors face mandatory Bureau of Indian Standards compliance for public works lifting equipment, creating first-mover advantage for certified import suppliers.
Industry Challenges
- Non-Destructive Testing Technician Scarcity:Magnetic particle inspection certification for alloy chain defect detection limits throughput at third-party validation facilities.
- Legacy Inventory Obsolescence:Distributors holding pre-ASME B30.21 revision stock must absorb write-downs or retrofit costs to meet current load-rating documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lever Hoist Market |
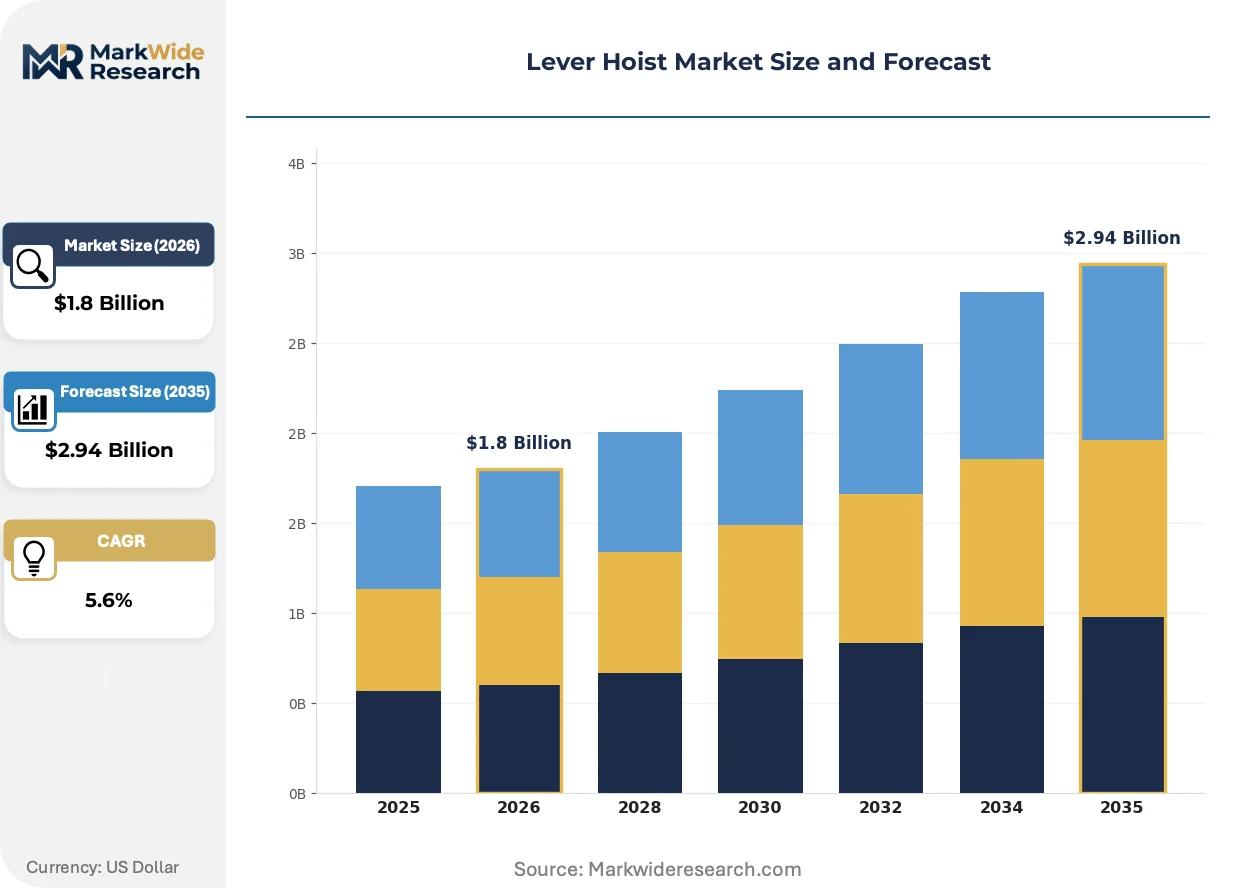
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Lever Hoists, Electric Lever Hoists, Pneumatic Lever Hoists, Chain Lever Hoists End User: Construction, Manufacturing, Mining, Shipping Capacity: 500 kg, 1000 kg, 2000 kg, 3000 kg Installation: Portable, Permanent, Fixed, Adjustable |
| Companies Covered | Columbus McKinnon, KITO Corporation, The David Round Co., Inc., Ingersoll Rand, Dawson Group Ltd., Tiger Lifting, JET Tools, Harrington Hoists, Carl Stahl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lever Hoist Market Evolving Landscape
Electrification of manual lifting mechanisms is compressing the boundary between traditional lever hoists and powered positioning equipment, while regulatory digitization demands real-time traceability across calibration and inspection workflows.
Lithium-ion battery integration is migrating from peripheral accessory power toward primary motive force in compact lever designs. Wind turbine technicians and railway maintenance crews are adopting battery-assisted units for repetitive load positioning where pure manual operation induces cumulative strain injury. This migration from muscle-powered to hybrid-assist architectures is enabling single-operator deployment in previously two-person lifting scenarios.
REACH substance restriction updates are compelling European manufacturers to eliminate hexavalent chromium from surface finishing processes on load chain and hook assemblies. The industrial consequence is accelerated adoption of zinc-nickel plating and ceramic-based corrosion protection systems. German automotive stamping plants and Dutch shipyards are most affected, with procurement specifications now requiring full material disclosure documentation.
Rental and short-term deployment models are displacing outright purchase for intermittent-use segments. Construction subcontractors and event production houses increasingly source lever hoists through equipment rental networks that bundle inspection, certification, and liability coverage. This pattern is most visible in United Kingdom infrastructure projects and Australian mining services contracting, where asset-light balance sheet management dominates procurement philosophy.
Lever Hoist Market Segmentation
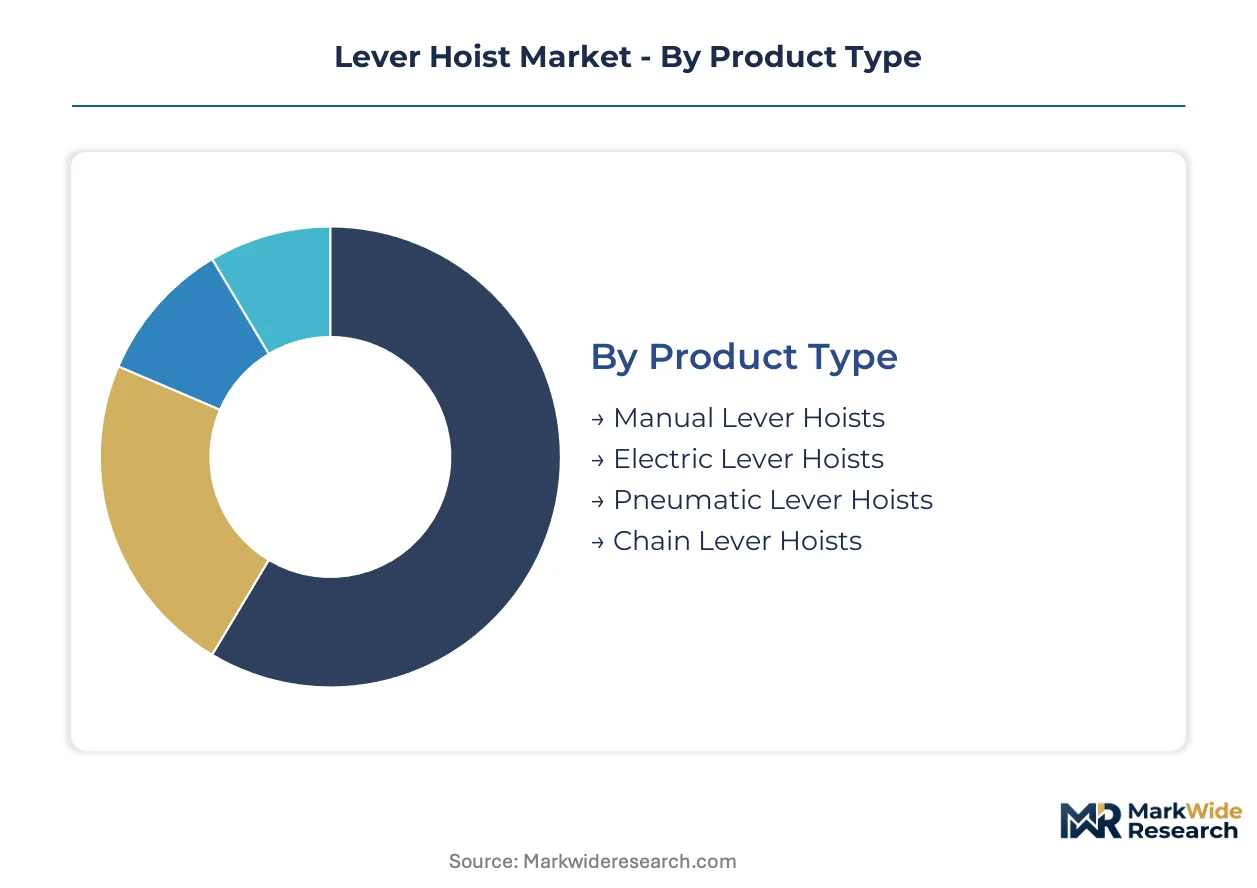
Lever hoist segmentation reveals distinct aftermarket service profiles across equipment categories. Service intensity varies sharply by motive power and duty cycle, reshaping distributor inventory strategies and manufacturer warranty structures.
Product Type:
After-sales service intensity diverges dramatically across motive technologies, with powered variants demanding scheduled maintenance contracts while manual units rely on periodic inspection protocols.
- Manual Lever Hoists:Ratchet and pawl mechanisms with hardened alloy steel chain require minimal field service beyond annual load testing. Mining contractors in Australia specify these for remote ventilation shaft maintenance where power access is unreliable and technician dispatch costs are prohibitive.
- Electric Lever Hoists:Brushed or brushless motor drives with integrated limit switches and thermal protection demand preventive maintenance programs. German automotive stamping plants specify these for repetitive die-change workflows where downtime costs exceed service contract premiums.
- Pneumatic Lever Hoists:Compressed air motors with moisture-resistant housings suit explosion-risk environments. Offshore platforms in the North Sea deploy these for deck equipment positioning where electrical ignition hazards are regulated.
- Chain Lever Hoists:Forged alloy chain with calibrated link pitch concentrates margin in heavy-capacity bands. Underground operations in Canada specify proof-tested components for mobile equipment repair in confined headings.
Manual lever hoists hold the largest share; momentum sits with electric variants as manufacturing automation accelerates.
End User:
Application-specific duty cycles determine replacement frequency and spare parts attach rates across customer segments.
- Construction:Intermittent use with high environmental exposure drives rental model adoption. Infrastructure contractors in the United Kingdom source through equipment networks bundling inspection and liability coverage.
- Manufacturing:High-cycle repetitive operations favor powered variants with predictive maintenance integration. Japanese automotive assembly lines specify compact electric units for just-in-time component positioning.
- Mining:Abrasive dust and shock loading accelerate wear component consumption. Australian hard-rock operations maintain captive spare chain inventories to minimize heading downtime.
- Shipping:Salt corrosion and irregular usage patterns favor stainless or plated finishes. Dutch shipyards now require full material disclosure documentation under REACH substance restrictions.
Construction commands the greatest volume; manufacturing exhibits the steepest expansion trajectory as electrification penetrates assembly workflows.
Capacity:
Proof-test documentation requirements intensify with rated load, creating compliance cost tiers that filter supplier participation.
- 500 kg:Light-duty aluminum or stamped steel construction suits entertainment rigging and maintenance shops. Concert touring crews in Germany specify compact headroom designs for truss positioning above audience areas.
- 1000 kg:Mid-range forged components balance portability with industrial durability. Utility maintenance crews across the United States deploy these for transformer installation in remote terrain.
- 2000 kg:Hardened alloy chain with magnetic particle inspection certification anchors mining and heavy construction specifications. Canadian distributors face inventory write-downs on pre-ASME B30.21 revision stock lacking current load-rating documentation.
- 3000 kg:Maximum manual leverage ratios demand ergonomic handle design and operator training protocols. Wind turbine nacelle gearbox replacement protocols require these for blade pitch system repair at heights with unreliable electrical supply.
The 2000 kg band captures the densest margin pool; 500 kg units are climbing the fastest as entertainment and utility segments expand.
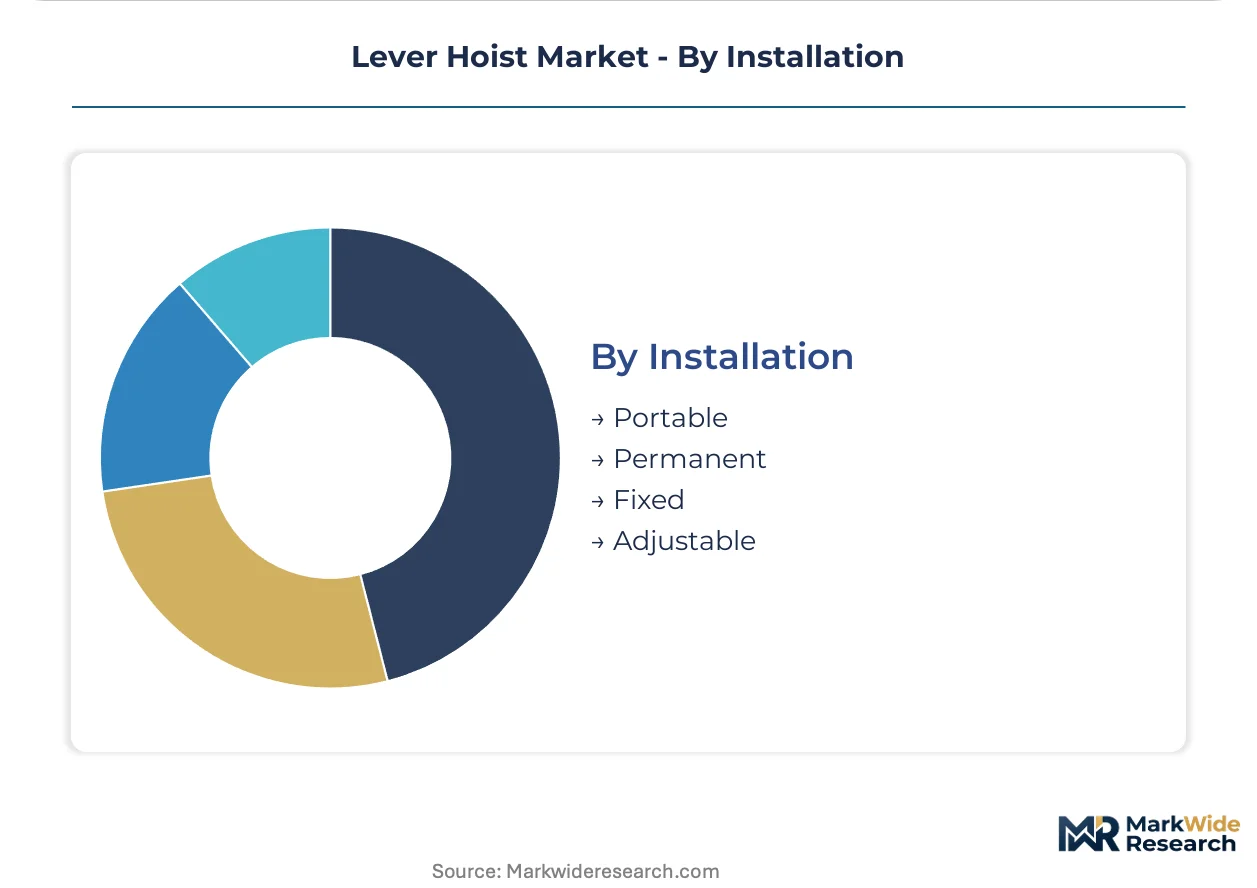
Installation:
Mounting configuration determines transport logistics, setup labor, and regulatory inspection intervals across deployment scenarios.
- Portable:Suspension hook or trolley mount enables rapid relocation between work zones. Railway maintenance crews are adopting battery-assisted portable units for repetitive load positioning.
- Permanent:Fixed anchor points with dedicated rigging infrastructure suit continuous production environments. Indian infrastructure contractors face mandatory BIS compliance for public works lifting equipment.
- Fixed:Structural integration with building steel or engineered foundations requires certified installation. ASME B30.21 mandates traceable calibration records for fixed installations in North American facilities.
- Adjustable:Variable reach or height configurations accommodate multi-tasking workflows. Southeast Asian heat-treatment capacity bottlenecks create delivery risk for adjustable beam clamp components.
Portable configurations dominate unit volume; adjustable systems are gaining share fastest as asset-light procurement philosophy spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Alaska Pipeline System and Appalachian natural gas transmission corridors sustain North American demand for portable lifting equipment in remote maintenance environments.
United States
Grid hardening programs across the Midwest and Southeast require compact lever hoists for transformer installation in terrain inaccessible to powered equipment. OSHA 1910.179 and ASME B30.21 mandate traceable calibration records for all manual lifting devices in industrial facilities. Houston-Galveston petrochemical clusters specify corrosion-resistant units for turnaround maintenance in salt-air environments.
Germany
Automotive stamping plants in Bavaria and Baden-Württemberg deploy electric lever hoists for repetitive die-change workflows where downtime costs dominate procurement decisions. REACH substance restrictions compel elimination of hexavalent chromium from surface finishing processes. The Port of Hamburg and surrounding shipyards now require full material disclosure documentation for all lifting equipment procurement.
Japan
Precision manufacturing in Aichi Prefecture and Kanagawa drives specification of compact lever designs for just-in-time component positioning in confined assembly cells. METI industrial safety guidelines and JIS B 8815 standards govern load testing protocols for manual hoisting equipment. Osaka-based forging clusters maintain captive heat-treatment capacity for alloy chain supply security.
Australia
Hard-rock mining operations in Western Australia and Queensland specify hardened alloy chain lever hoists for ventilation shaft maintenance and mobile equipment repair in remote headings. The country's national workplace safety regulator mandates periodic inspection and proof-testing for all lifting equipment in extractive industries. Perth engineering services clusters coordinate rapid replacement logistics for mine site procurement.
India
Domestic infrastructure contractors face mandatory Bureau of Indian Standards compliance for public works lifting equipment, creating certification barriers for uncertified imports. The Dedicated Freight Corridor and associated rail electrification projects generate concentrated demand for portable hoisting equipment. Maharashtra and Gujarat industrial corridors drive specification of mid-capacity units for manufacturing facility construction.
Lever Hoist Market Competitive Landscape
On the supply side, the industry is moderately consolidated around forged alloy chain specialists and diversified industrial equipment manufacturers. Three strategic archetypes dominate: vertically integrated chain-forging operations controlling upstream material inputs, precision-focused Japanese manufacturers emphasizing manufacturing tolerances, and regional fabricators serving price-sensitive construction segments. Capacity expansion in Southeast Asian heat-treatment facilities and strategic distribution partnerships with industrial equipment rental networks represent the dominant competitive vectors.
Among North American diversified industrial equipment manufacturers, Columbus McKinnon and Ingersoll Rand occupy positions anchoring the premium certified-equipment tier through established distribution relationships with utility and heavy industrial accounts. Japanese precision manufacturers exemplified by KITO Corporation sit within the quality-focused archetype, leveraging domestic forging expertise and deep stock positions in Asia-Pacific markets. These three entities collectively represent the competitive structure: diversified industrial conglomerates, specialized lifting-equipment pure-plays, and regional fabrication specialists.
| Leading Market Players |
|---|
| Columbus McKinnon |
| KITO Corporation |
| The David Round Co., Inc. |
| Ingersoll Rand |
| Dawson Group Ltd. |
| Tiger Lifting |
| JET Tools |
| Harrington Hoists |
| Carl Stahl |
| Others |
Value Network & Pricing Analysis
Osaka-based forging clusters anchor alloy chain supply for lever hoist manufacturers, with captive heat-treatment capacity translating directly into pricing power for Japanese precision producers serving North American utility accounts. This geographic concentration creates asymmetric leverage where upstream bottlenecks in Southeast Asian heat-treatment facilities transmit cost volatility downstream to distributors holding pre-certification inventory.
Pricing Analysis
Volume-discount tiering structures separate proof-tested certified units from gray-market alternatives, with ASME B30.21 compliance documentation commanding premium positioning against uncertified imports. Price differentiation hinges on magnetic particle inspection certification and traceable calibration records, with mining contractors in Australia exhibiting lowest price sensitivity due to downtime costs, while construction subcontractors in the United Kingdom drive hardest bargain through rental network aggregation. Cost compression in the economy tier intensifies as nickel and chromium spot volatility squeezes forged chain margins.
Supply Chain Analysis
Extended payment terms from Japanese forging houses to Southeast Asian distributors stabilize working capital for heat-treatment-dependent component flows. Supply concentrates in Japan, China, and Germany for precision-forged alloy chain, with raw material dependencies on nickel, chromium, and high-grade steel scrap. Single-source vulnerability in Southeast Asian heat-treatment capacity creates delivery risk for North American replacement cycles. Distribution runs through specialized lifting-equipment distributors consolidating shelf space around certified brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lever hoist market fragmentation creates entry niches as electrification splits demand between manual muscle-powered units and battery-assisted hybrid architectures. Rental model proliferation across construction and entertainment segments fragments procurement authority away from traditional capital-equipment buyers.
For Market Incumbents: Harden certification moats by accelerating third-party proof-test documentation investments before impending ASME B30 standard updates address powered lever hoist electrification. Secure captive Southeast Asian heat-treatment capacity through equity partnerships or long-term offtake agreements to defend margin position against nickel price volatility. Channel control through industrial equipment rental network exclusivity locks out gray-market competitors.
For New Entrants and Emerging Players: Mid-market Indian infrastructure contractors facing mandatory BIS certification gaps represent the most penetrable entry point for certified import suppliers with documented calibration protocols. German entertainment rigging and concert touring segments demand compact headroom designs underserved by incumbent utility-focused portfolios. Direct specification relationships with wind turbine maintenance service providers bypass distributor consolidation barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-forging specialists with backward integration into alloy chain production and established calibration laboratory relationships. Long-term viability rests on electrification transition capture and regulatory digitization readiness for real-time inspection traceability. Watch lithium-ion battery cost curves as inflection indicator for hybrid-assist architecture adoption rates displacing pure manual units.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Alloy Chain | Columbus McKinnon's captive supply secures cost predictability against nickel volatility for North American utility accounts. |
| Certification Investment in BIS Compliance | First-mover documentation advantage captures Indian Dedicated Freight Corridor procurement specifications. |
| Rental Network Partnership Expansion | Equipment-as-a-service bundling locks construction subcontractors into inspection-inclusive contract structures. |
| Battery-Assist Product Line Development | Hybrid architectures address wind turbine technician cumulative strain injury liability in nacelle maintenance. |
| REACH-Compliant Surface Finishing Transition | Zinc-nickel plating adoption preserves German automotive stamping plant supplier status under substance restrictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across maintenance directors at mining and utility operations, plant engineers specifying hoisting equipment, OEM procurement teams at construction equipment manufacturers, aftermarket service heads at industrial distributors, and regulatory compliance officers. Secondary validation drew from OSHA enforcement databases, ASME B30.21 revision dockets, customs trade records for alloy chain imports, and SEC filings from listed industrial equipment manufacturers. Bottom-up unit demand estimates triangulated against top-down construction and mining capital expenditure trends.
Calibration against historical replacement cycle patterns and regulatory compliance mandate timelines anchored projections across the analysis window. Segmentation dimensions modeled include motive power technology, end-use industry duty cycle, rated load capacity tier, and mounting configuration portability. CAGRs derived from regression of equipment stock aging curves against mandated inspection intervals. Industry-specific forecast inputs incorporated wind turbine installed base growth and grid hardening program appropriations.
Practitioners should monitor ASME B30 standard revision timing, battery energy density cost curves, and Southeast Asian heat-treatment capacity expansion announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Water Hose Market