
 HVAC Air Quality Monitoring Market | 2026-2036
HVAC Air Quality Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Air Quality Monitoring Market Intelligence
Sensor engineering talent is rotating toward IoT-enabled calibration and edge-computing architectures, tightening the labor pool for legacy electrochemical design. Honeywell International Inc. leverages its building automation installed base to bundle air quality modules into integrated HVAC contracts. Testo SE & Co. KGaA sustains competitiveness through handheld diagnostic specialization that feeds upstream into fixed monitoring networks. Siemens AG anchors European project pipelines with building management software that ingests real-time particulate and VOC streams.
HVAC air quality monitoring encompasses distributed sensor networks that measure particulate matter, carbon dioxide, volatile organic compounds, and thermal parameters within mechanical ventilation systems, typically operating at detection thresholds of 0.3 microns for PM2.5 and 1 ppm accuracy for CO2 to enable automated damper and filtration responses. These systems serve commercial and industrial facilities by triggering ventilation adjustments that maintain ASHRAE-compliant indoor environments while minimizing energy waste. Carbon dioxide sensors occupy the largest product volume share due to universal deployment in commercial buildings for demand-controlled ventilation, while volatile organic compound detectors represent the fastest-expanding category as WELL Building Standard and LEED v4.1 certifications elevate awareness of off-gassing from furnishings and cleaning chemicals. Electrochemical technology leads the installed base for CO and NO2 detection in transportation hubs and parking structures, though optical methods are displacing legacy approaches in particulate measurement because laser scattering arrays deliver simultaneous PM1, PM2.5, and PM10 readouts without consumable electrolytes.
The EPA's National Ambient Air Quality Standards and OSHA's indoor air quality enforcement letters shape product specifications by mandating documented pollutant thresholds and calibrated response protocols for commercial and industrial employers. CE marking under the EU's Radio Equipment Directive and the F-Gas Regulation additionally constrain sensor hardware sold into European building automation channels, particularly for infrared-based refrigerant leak detection bundled with air quality suites. Stakeholders must monitor how emerging state-level ventilation mandates in California and New York interact with federal minimum efficiency standards to determine whether specification divergence will fragment procurement requirements or drive modular platform adoption.
Market Dynamics
The convergence of EPA enforcement letters and WELL Building Standard certification requirements is compressing upgrade cycles for commercial building operators, forcing simultaneous sensor deployment across ventilation, filtration, and damper control systems.
Growth Catalysts
- OSHA Indoor Air Quality Enforcement:Documented violation penalties above $15,000 per incident are compelling facility managers to install continuous monitoring networks before scheduled inspections.
- LEED v4.1 Credit Expansion:The updated certification framework awards points for real-time VOC and particulate disclosure, driving procurement in Class A office developments.
- Edge Computing Architectures:On-device processing is reducing latency for automated damper responses, enabling sub-second ventilation adjustments in high-occupancy transit hubs.
Market Restraints
- MEMS Sensor Input Volatility:Silicon wafer pricing fluctuations and foundry capacity constraints in Taiwan are elevating bill-of-materials uncertainty for electrochemical sensor manufacturers.
- Calibration Labor Scarcity:Certified technicians capable of NIST-traceable CO2 recalibration are concentrating in metropolitan districts, leaving secondary markets underserved.
- Optical Sensor Substitution:Laser scattering arrays are capturing particulate measurement share from legacy beta attenuation monitors, stranding capital in installed electrochemical bases.
Strategic Opportunities
- Retrofit-First Procurement in Germany:The EU F-Gas Regulation and national building codes are mandating refrigerant leak detection integration with air quality suites in existing commercial stock.
- Healthcare Ventilation Upgrades:ASHRAE Standard 170 compliance deadlines for hospital surgical suites are creating concentrated demand for pressure-differential monitoring with real-time alerting.
- Sensor-as-a-Service Models:Subscription-based hardware provisioning with bundled calibration and cloud analytics is penetrating multi-site retail and hospitality portfolios.
Industry Challenges
- IoT Firmware Integration Complexity:BACnet and Modbus protocol fragmentation across legacy building management systems is extending deployment timelines and elevating commissioning costs.
- WELL Performance Certification Timelines:Third-party validation requirements for VOC and PM2.5 documentation are creating 90-120 day gaps between sensor installation and operational certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Air Quality Monitoring Market |
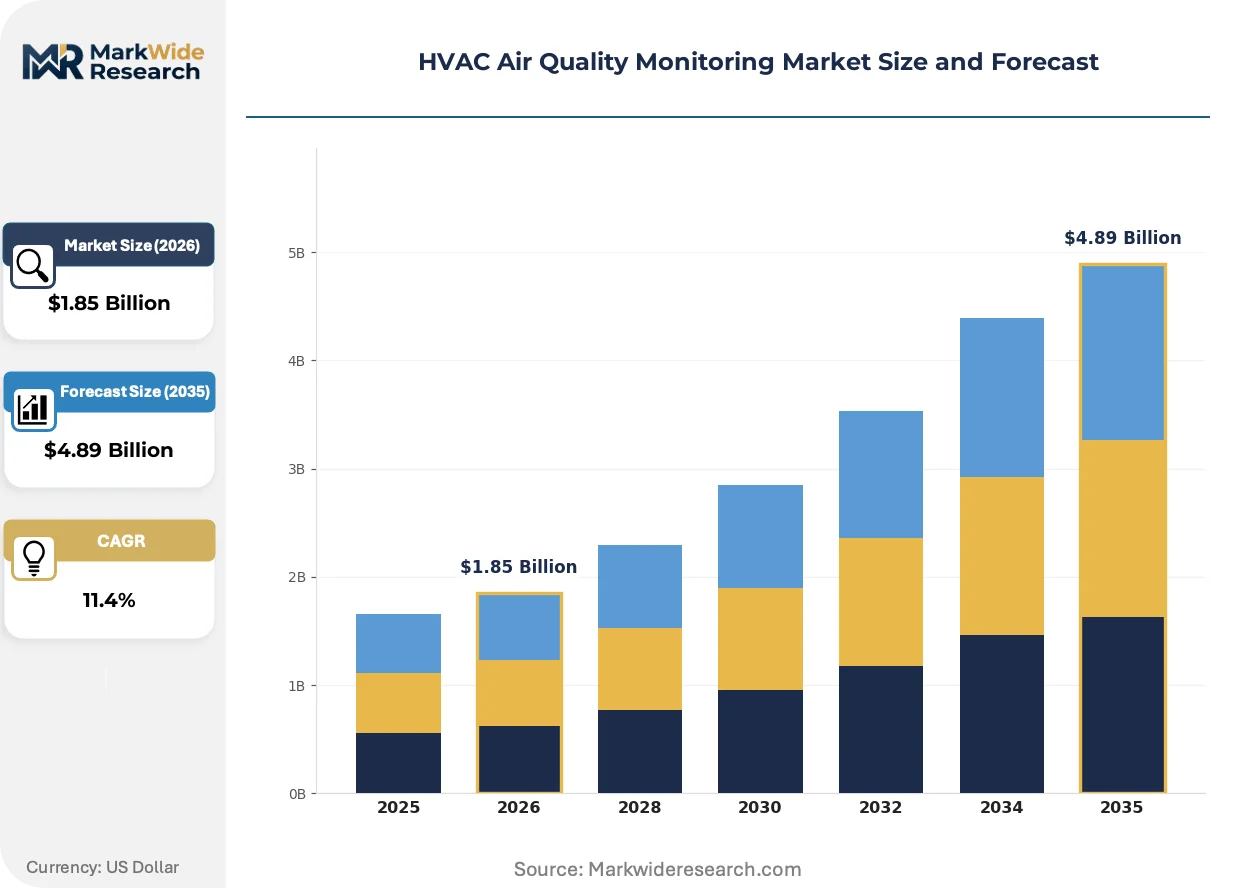
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Dioxide Sensors, Particulate Matter Sensors, Volatile Organic Compound Detectors, Temperature & Humidity Sensors Application: Commercial Buildings, Industrial Facilities, Educational Institutions, Transportation Hubs Technology: Electrochemical, Optical, Metal-Oxide Semiconductor, Photoionization Detection, Infrared Sensing End User: Facility Management Companies, Building Automation Firms, Environmental Consultants, Safety Compliance Auditors |
| Companies Covered | Thermo Fisher Scientific Inc., Teledyne Technologies, Honeywell International Inc., Testo SE & Co. KGaA, TSI Incorporated, Siemens AG, PerkinElmer Inc., Vaisala Oyj, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Air Quality Monitoring Market Strategic Shifts & Innovations
Sensor engineering is pivoting toward multi-parameter fusion and predictive maintenance algorithms, compressing the functional gap between diagnostic handhelds and permanent monitoring infrastructure.
Laser scattering particulate sensors are displacing legacy optical particle counters in commercial building deployments. Property technology managers in Class A office towers are specifying simultaneous PM1, PM2.5, and PM10 readouts without filter replacement cycles. This displacement is compressing maintenance contracts and elevating vendor stickiness through embedded calibration subscriptions.
California's Title 24 Building Energy Efficiency Standards now mandate demand-controlled ventilation with CO2 setpoints in nonresidential construction. The regulation is accelerating specification of networked sensor arrays with automated fault detection. School districts and community college systems represent the most affected procurement segment, bundling air quality monitoring with HVAC replacement cycles.
Facility managers are unbundling sensor hardware from long-term service agreements, compressing initial capital outlays while elevating recurring software spend. This shift is disrupting traditional bundled contracts from controls integrators. The pattern is most visible in United States multi-site retail and quick-service restaurant portfolios, where corporate sustainability teams centralize data aggregation while decentralizing hardware ownership to franchise operators.
HVAC Air Quality Monitoring Market Segmentation
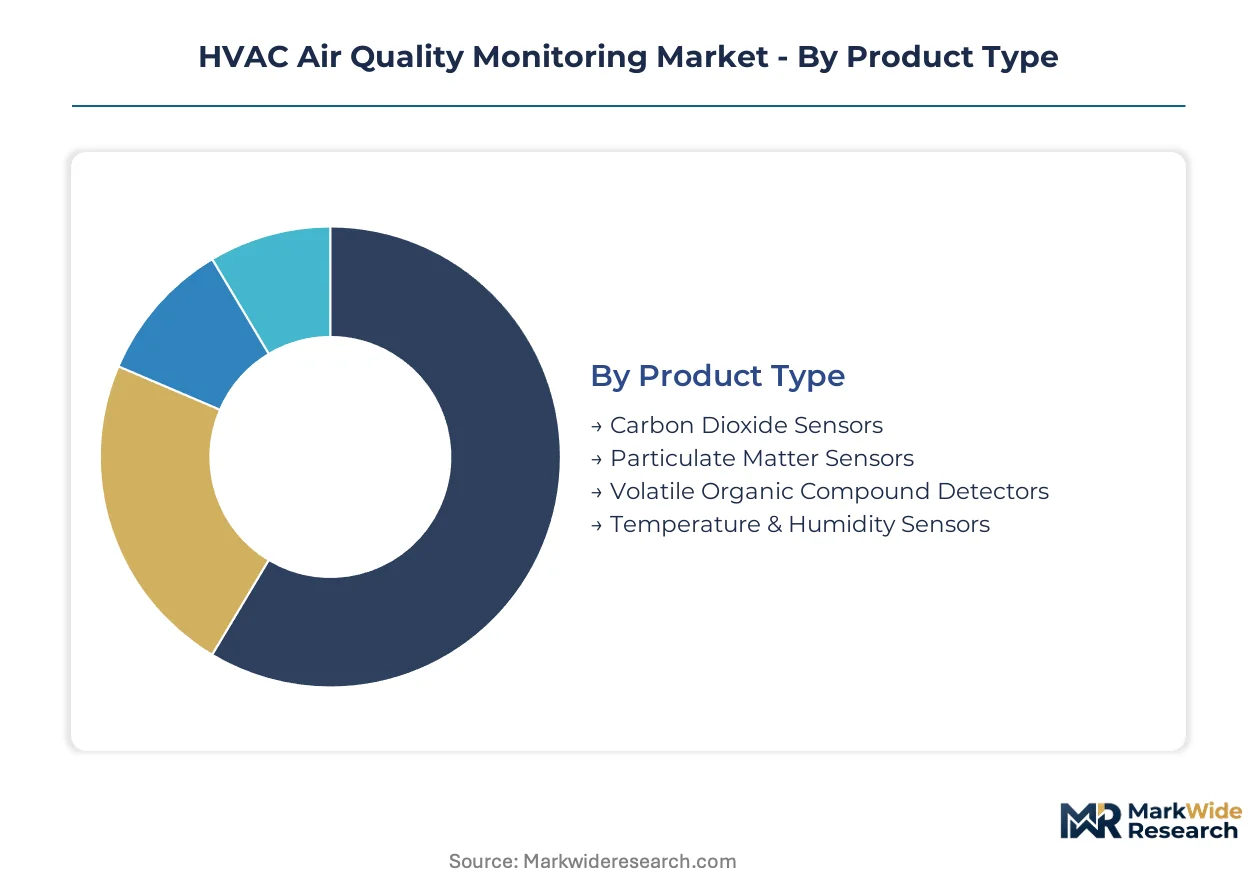
Segmentation in HVAC air quality monitoring reveals how sensor specifications diverge across building types and regulatory environments. Procurement patterns cluster around certification requirements rather than price sensitivity alone.
Product Type:
Carbon dioxide sensors dominate domestic retrofit cycles in the United States, while particulate and VOC detectors concentrate in export-led green building certification projects.
- Carbon Dioxide Sensors:Non-dispersive infrared cells measure ambient CO2 at 1 ppm resolution to trigger demand-controlled ventilation. Deployment concentrates in California school districts responding to Title 24 mandates for automated damper control.
- Particulate Matter Sensors:Laser scattering arrays detect PM1, PM2.5, and PM10 simultaneously without filter replacement. Demand clusters in WELL-certified office towers in New York and London where real-time disclosure requirements elevate specification standards.
- Volatile Organic Compound Detectors:Metal-oxide and photoionization technologies target formaldehyde and benzene off-gassing from furnishings.
- Temperature & Humidity Sensors:MEMS-based thermal probes integrate with CO2 modules for psychrometric calculations in mixed-mode ventilation.
Carbon dioxide sensors hold the largest share; momentum sits with volatile organic compound detectors.
Application:
Commercial buildings absorb premium-tier pricing for certification-linked installations, while educational institutions drive volume procurement through state-funded replacement cycles.
- Commercial Buildings:Class A offices and retail portfolios deploy networked sensor arrays with cloud dashboards for tenant wellness marketing. LEED v4.1 credit expansion in United States metropolitan districts accelerates specification of multi-parameter fusion systems.
- Industrial Facilities:Manufacturing plants and warehousing operations prioritize refrigerant leak detection bundled with air quality monitoring. Germany's F-Gas Regulation mandates retrofit integration in existing commercial stock.
- Educational Institutions:K-12 districts and universities represent concentrated procurement through bond-funded HVAC modernization.
- Transportation Hubs:Airports and rail terminals require high-density CO2 monitoring for high-occupancy spaces with variable ventilation loads.
Commercial buildings command the highest revenue per installation; educational institutions are expanding most quickly through public funding channels.
Technology:
Electrochemical methods retain cost advantages in legacy parking structure deployments, while optical approaches capture specification share in new construction.
- Electrochemical:Amperometric cells for CO and NO2 detection dominate transportation hub and parking garage installations where OSHA enforcement targets combustion exhaust exposure.
- Optical:Laser scattering and nondispersive infrared methods displace legacy approaches in particulate and CO2 measurement. Taiwan foundry constraints on MEMS substrates create input volatility for electrochemical manufacturers.
- Metal-Oxide Semiconductor:Tin dioxide films detect reducing gases at lower cost than PID alternatives for broad-spectrum VOC screening.
- Photoionization Detection:Ultraviolet lamp ionization delivers parts-per-billion sensitivity for hazardous air pollutant identification in industrial hygiene applications.
- Infrared Sensing:NDIR benches target refrigerant and CO2 detection with zero consumable requirements.
Electrochemical technology anchors the installed base; optical methods gain share fastest through maintenance cost advantages.
End User:
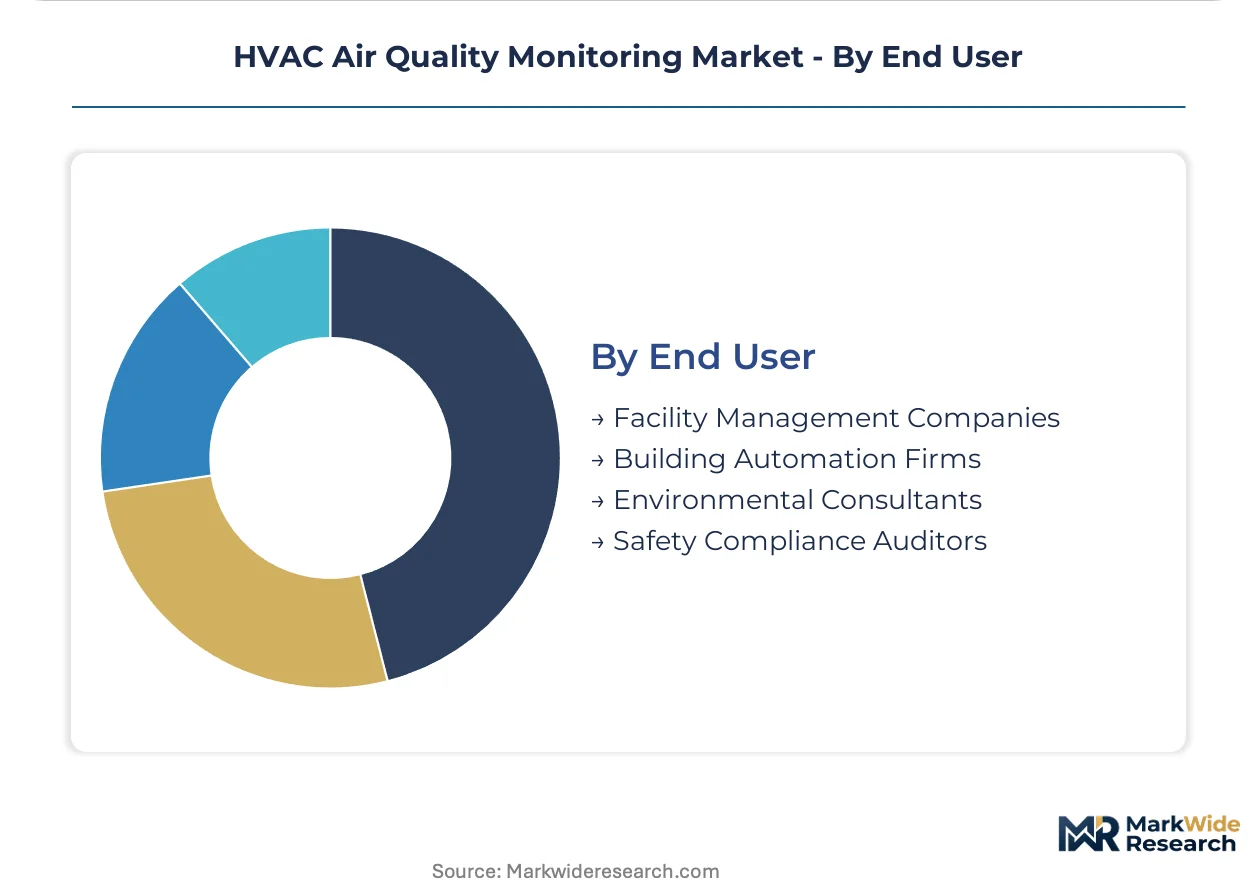
Facility management companies centralize procurement for multi-site portfolios, while environmental consultants drive specification influence without direct hardware ownership.
- Facility Management Companies:Third-party operators bundle sensor-as-a-service contracts across retail and hospitality portfolios. United States quick-service restaurant chains decentralize hardware ownership to franchisees while centralizing data aggregation.
- Building Automation Firms:Controls integrators face margin pressure as facility managers unbundle hardware from long-term service agreements.
- Environmental Consultants:Third-party validation for WELL Performance Certification creates 90-120 day gaps between installation and operational signoff.
- Safety Compliance Auditors:OSHA inspection preparation drives preemptive sensor deployment in industrial facilities facing documented violation penalties above $15,000 per incident.
Facility management companies generate the largest contract values; building automation firms face the steepest pricing pressure from unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German retrofit markets while procurement volume clusters in United States state-funded educational cycles. This asymmetry shapes capital allocation across the analysis window.
United States
California school districts drive CO2 sensor volume through Title 24 mandates for demand-controlled ventilation. OSHA enforcement letters targeting indoor air quality violations above $15,000 per incident accelerate preemptive deployment in industrial corridors. New York City Class A office towers concentrate WELL-certified installations with real-time particulate disclosure requirements.
Germany
The EU F-Gas Regulation mandates refrigerant leak detection integration with air quality monitoring in existing commercial building stock. CE marking under the Radio Equipment Directive constrains sensor hardware specifications for building automation channels. Bavaria's industrial manufacturing belt concentrates procurement of multi-parameter fusion systems for warehouse and production facility retrofits.
China
GB standards for indoor air quality in commercial construction elevate specification thresholds for new office developments. The Ministry of Ecology and Environment enforces dual carbon goals that compress HVAC replacement cycles in municipal buildings. Yangtze River Delta manufacturing clusters absorb premium-tier optical sensors for semiconductor cleanroom applications.
United Kingdom
London's commercial real estate sector prioritizes sensor-as-a-service models for multi-site portfolio standardization. The Building Safety Regulator's documentation requirements for ventilation system performance extend commissioning timelines. Scotland's public sector estate modernization programs bundle air quality monitoring with energy efficiency retrofits.
Japan
METI efficiency standards for commercial buildings accelerate networked sensor deployment in mixed-use developments. JIS certification requirements for measurement accuracy elevate procurement costs for imported hardware. Tokyo's transit hub operators deploy high-density CO2 monitoring for variable ventilation loads in underground commercial spaces.
HVAC Air Quality Monitoring Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the HVAC air quality monitoring market. Consolidation pressure concentrates among building automation integrators facing margin compression from unbundled hardware procurement. Three archetypes dominate: diversified industrial conglomerates with installed base leverage, specialized sensor manufacturers with calibration expertise, and controls integrators with software platform integration. Strategic moves center on sensor-as-a-service contract structures and edge computing architecture partnerships that reduce latency for automated ventilation responses.
Among diversified industrial conglomerates, Honeywell International Inc. and Siemens AG exemplify archetypes leveraging building automation installed bases to bundle air quality modules into integrated contracts. Testo SE & Co. KGaA occupies a position within the specialized tier, sustaining competitiveness through diagnostic equipment expertise that feeds upstream into fixed monitoring networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Teledyne Technologies |
| Honeywell International Inc. |
| Testo SE & Co. KGaA |
| TSI Incorporated |
| Siemens AG |
| PerkinElmer Inc. |
| Vaisala Oyj |
| Emerson Electric Co. |
| Others |
Cost & Logistics Intelligence
Foundry scale economies in Taiwan's MEMS substrate production concentrate optical sensor supply among three dominant wafer suppliers, compressing margin buffers for electrochemical manufacturers while elevating price floors for NDIR and laser scattering modules. This concentration feeds forward into differentiated pricing power across calibration-intensive versus maintenance-free product tiers.
Pricing Analysis
The customization-premium spread separates standard CO2 sensors from multi-parameter fusion systems configured for WELL Building Standard documentation. Subscription-based sensor-as-a-service models now command 40-60% recurring revenue premiums over transactional hardware sales. Price differentiation rests on certification grade (ASHRAE 62.1 compliance vs. WELL Performance validation) and bundled calibration labor. Cost compression in standard electrochemical tiers is intensifying because MEMS input volatility elevates bill-of-materials uncertainty. Educational institutions exhibit highest price sensitivity due to bond-funded procurement cycles, while Class A office developers absorb premium pricing for real-time disclosure dashboards.
Supply Chain Analysis
Taiwan Strait logistics chokepoints threaten MEMS wafer delivery schedules for optical sensor arrays, compressing inventory buffers for manufacturers serving California Title 24 retrofit deadlines. Taiwan, South Korea, and Japan anchor global supply for laser diodes and photodetector components. Raw material dependencies span silicon wafers, infrared source lamps, and metal-oxide semiconductor substrates. Single-source vulnerability concentrates in Taiwan's foundry capacity for edge-computing chipsets. Distribution runs through building automation integrators and direct OEM channels to facility management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility management companies consolidating multi-site procurement, fragmenting the vendor base as unbundling trends compress integrator margins. This concentration among buyers elevates pricing leverage for subscription-based contract structures.
For Market Incumbents: Compound defensive positioning through backward integration into MEMS foundry partnerships and captive calibration service networks. Optical sensor substitution threatens electrochemical installed bases in parking structures and transportation hubs. Certification investment in WELL Performance validation capabilities secures stickiness in Class A office procurement cycles.
For New Entrants and Emerging Players: Anchor in Germany's F-Gas Regulation retrofit pipeline, where refrigerant leak detection integration creates white-space demand unclaimed by legacy electrochemical suppliers. K-12 educational institutions in California represent the most penetrable volume segment through Title 24 mandate compliance. Lead with sensor-as-a-service go-to-market models that transfer calibration risk from understaffed facility managers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized sensor manufacturers with calibration expertise over diversified conglomerates facing margin compression from hardware unbundling. Long-term viability rests on edge-computing architecture partnerships and predictive maintenance algorithm development. Watch for inflection signals in OSHA enforcement letter frequency and state-level ventilation mandate expansion beyond California and New York.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Partnership | On-device processing reduces damper response latency below one second in transit hubs. |
| Sensor-as-a-Service Contract Structure | Recurring revenue models penetrate multi-site retail portfolios with decentralized hardware ownership. |
| Backward Integration into MEMS Foundry | Captive wafer supply buffers Taiwan capacity constraints for optical sensor production. |
| WELL Performance Certification Investment | Third-party validation capabilities compress 90-120 day gaps between installation and operational signoff. |
| Predictive Maintenance Algorithm Development | AI-driven calibration scheduling elevates vendor stickiness through embedded software subscriptions. |
Research Approach
Initial hypotheses were tested against primary input from building automation engineers, facility management procurement directors, HVAC controls integrators, and environmental compliance consultants and refined through secondary validation against EPA enforcement letter databases, OSHA violation records, ASHRAE standard documentation, and green building certification registries. Bottom-up and top-down triangulation reconciled sensor shipment data with building permit filings and HVAC replacement cycle tracking.
Variance decomposition across product type, application, technology, and end-user segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators and regulatory mandate timelines. Modeled inputs incorporated Title 24 compliance deadlines, F-Gas Regulation retrofit schedules, and WELL Building Standard adoption curves.
Material uncertainties — MEMS foundry capacity allocation shifts, OSHA enforcement intensity variation, and state-level ventilation mandate divergence — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pace and substitution technology cost curves. Practitioners should keep alternative scenarios live as EPA indoor air quality standard revisions and edge-computing chipset availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Blowers Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
US Commercial Water Heater Market