
 Americas Plastic Bags and Sacks Market | 2026-2036
Americas Plastic Bags and Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Plastic Bags and Sacks Market Outlook
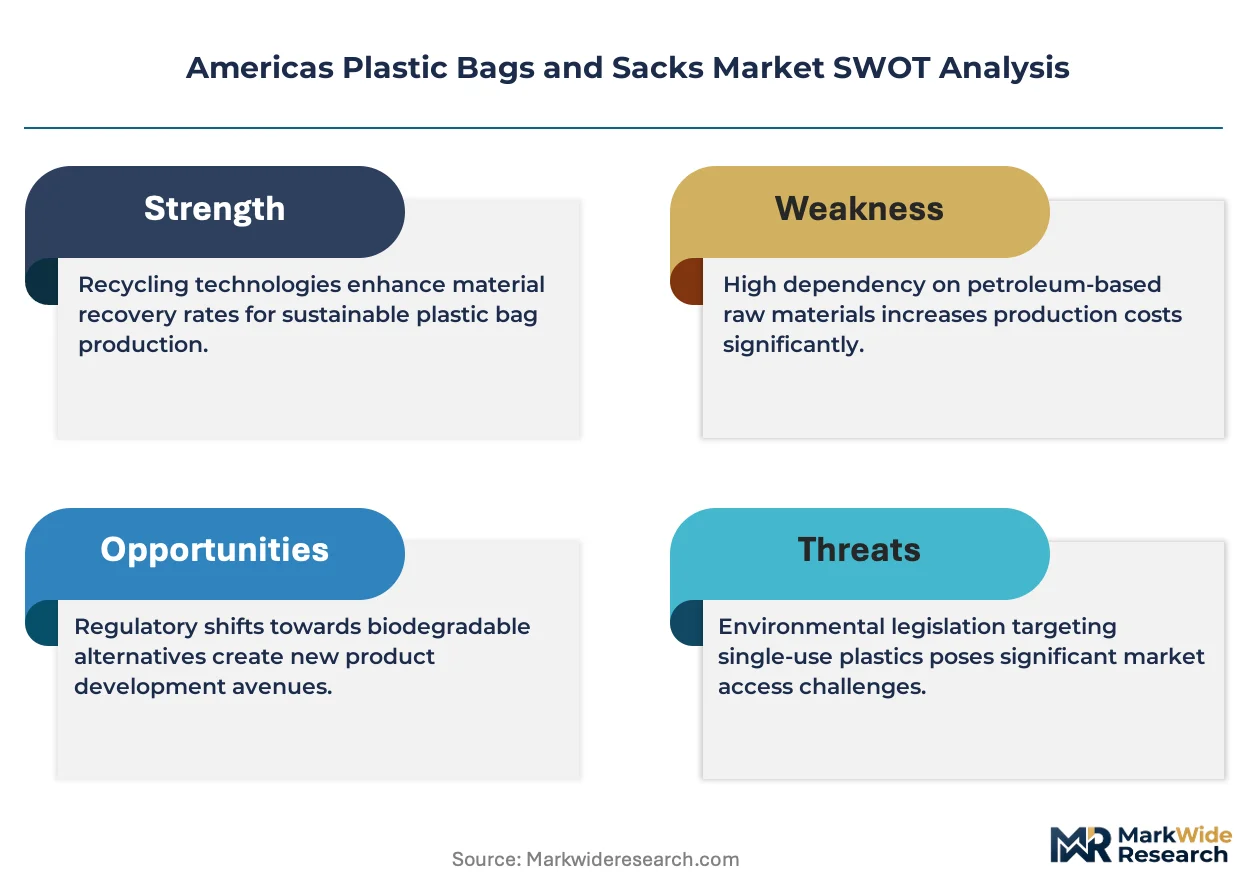
Polyethylene is rebalancing cost structures across the Americas Plastic Bags and Sacks Market as post-consumer recycled content mandates elevate rPET and rHDPE pricing relative to virgin resins. Berry Global leverages captive resin compounding capacity across multiple U.S. states to sustain margin stability amid feedstock volatility. Novolex Holdings anchors North American supply through its integrated film extrusion and converting network. Mondi PLC competes via specialized kraft-plastic hybrid constructions that navigate Latin American pulp availability constraints.
Plastic bags and sacks constitute flexible packaging fabricated from blown or cast film extrusion, typically ranging from 0.5 to 6.0 mils in thickness, designed for containment, transport, and shelf-life extension of consumer and industrial goods. Gusseted bags and block bottom bags dominate margin pools in food packaging applications where stand-up stability and palletization efficiency command specification premiums. T-shirt bags remain structurally mature in retail channels across Central America and the Caribbean, while biodegradable plastics represent the fastest-growing material category as municipal composting infrastructure expands in Brazil and Colombia.
The U.S. EPA regulates manufacturing emissions under Clean Air Act provisions, while state-level regulators in California and New York enforce single-use plastic restrictions that reshape product specifications and channel access. Health Canada and PMRA oversee food-contact compliance for polyethylene films entering Canadian retail distribution. Stakeholders must monitor how patchwork subnational regulations across the Americas fragment standardization efforts and force regional SKU proliferation.
Market Dynamics
State-level single-use plastic bans across the United States and extended producer responsibility frameworks in Canada are fragmenting product specifications and forcing regional SKU proliferation among converters serving grocery and industrial channels.
Growth Catalysts
- Compostable certification mandates:California and New York regulations redirect procurement toward certified alternatives, opening specification windows for bio-based film producers.
- Export manufacturing clusters:Mexico's industrial corridor states generate concentrated demand for heavy-duty sacks serving automotive and electronics assembly operations.
- Municipal composting buildout:Brazilian and Colombian infrastructure expansion creates offtake certainty for biodegradable plastic bag producers.
Market Restraints
- Post-consumer recycled resin premiums:rPET and rHDPE pricing volatility compresses converter margins when virgin polyethylene supply tightens.
- Latin American pulp constraints:Kraft-plastic hybrid construction faces raw material availability limits in regional pulp markets.
- Film extrusion capacity concentration:North American blown film infrastructure clusters in specific Midwest states, creating geographic supply risk.
Strategic Opportunities
- Central American retail penetration:T-shirt bag demand in Guatemala and Honduras remains structurally underpenetrated relative to population density.
- Block bottom bag specification:Food packaging applications in Brazil's protein export sector favor stand-up stability formats with palletization premiums.
- Extended producer responsibility credits:Canadian provincial frameworks create financial incentives for recycled content integration above baseline mandates.
Industry Challenges
- Composting facility certification alignment:ASTM D6400 and EN 13432 testing timelines delay product launches by 12-18 months.
- Legacy extrusion equipment retrofit:Bio-based resin processing requires screw and die modifications that strain mid-tier converter capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Plastic Bags and Sacks Market |
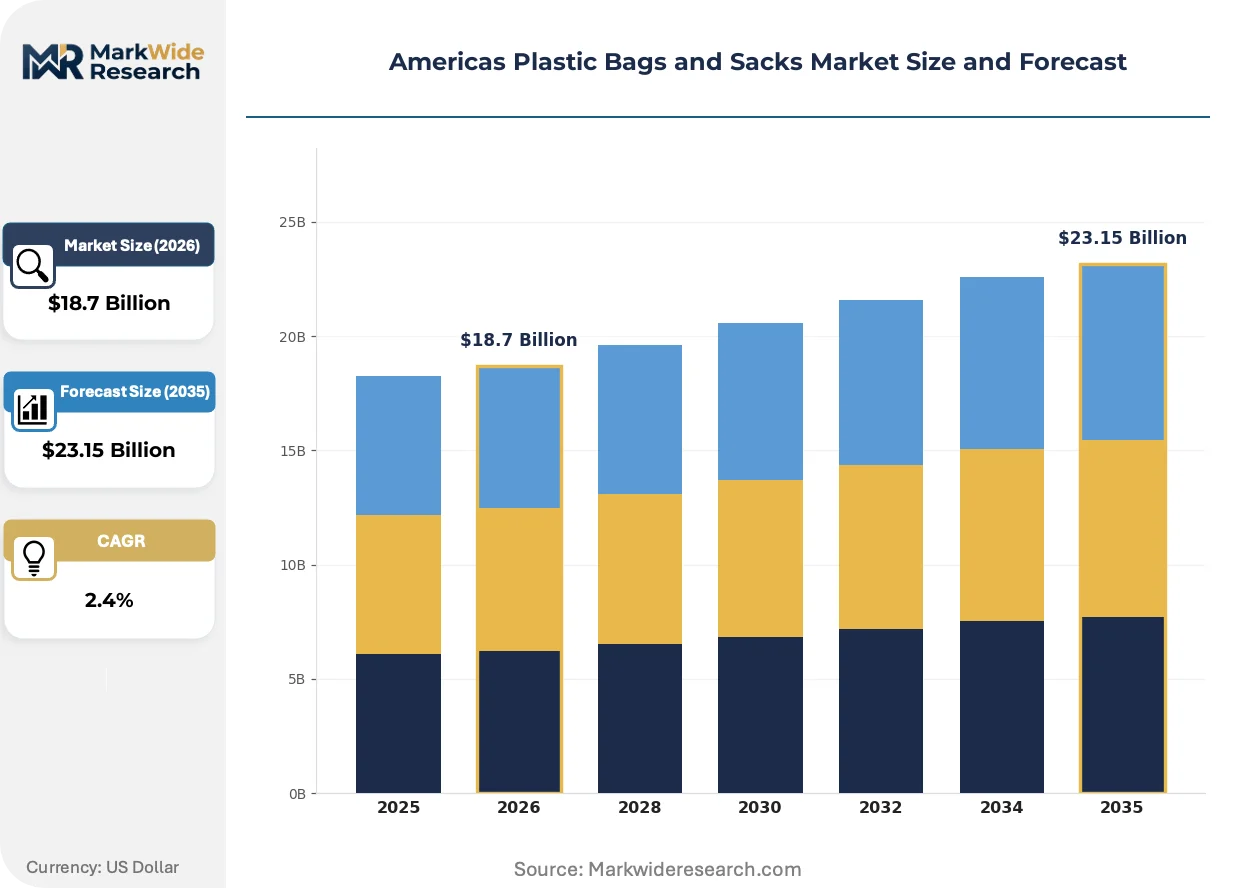
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, T-Shirt Bags, Block Bottom Bags Material: HDPE, LDPE, LLDPE, Biodegradable Plastics End Use: Retail, Food Packaging, Industrial, Healthcare Thickness: Lightweight, Medium-duty, Heavy-duty, Extra Heavy-duty |
| Companies Covered | ProAmpac LLC, Berry Global, Mondi PLC, Novolex Holdings, The Buckeye Bag Company, Inteplast Group, AEP Industries Inc., International Plastics Inc., LC Packaging International BV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Plastic Bags and Sacks Market Strategic Shifts
Material science advances and regulatory fragmentation are forcing simultaneous evolution across resin formulations, conversion equipment, and end-of-life infrastructure across the Americas.
Biodegradable polymer alloys incorporating PLA and PBAT are rewriting performance benchmarks for compostable carry bags. Brazilian supermarket chains are specifying these materials for private-label packaging programs. The technology is rewriting competitive positioning by enabling premium pricing where municipal composting infrastructure exists.
California's SB 54 and New York's bag ban amendments are tightening recycled content thresholds and expanding product scope to include reusable bag definitions. Converters must reformulate film layers and redesign thickness specifications to maintain channel access. Food-contact applications face the steepest compliance curves as Health Canada and PMRA evaluate new material safety profiles.
Consolidated grocery procurement in Mexico and Colombia is compressing supplier qualification cycles and unbundling legacy distributor relationships. Direct mill relationships are displacing regional bag wholesalers in major metropolitan markets. The shift is most visible in São Paulo and Mexico City, where retail chains centralize specification authority at headquarters level.
Americas Plastic Bags and Sacks Market Segmentation
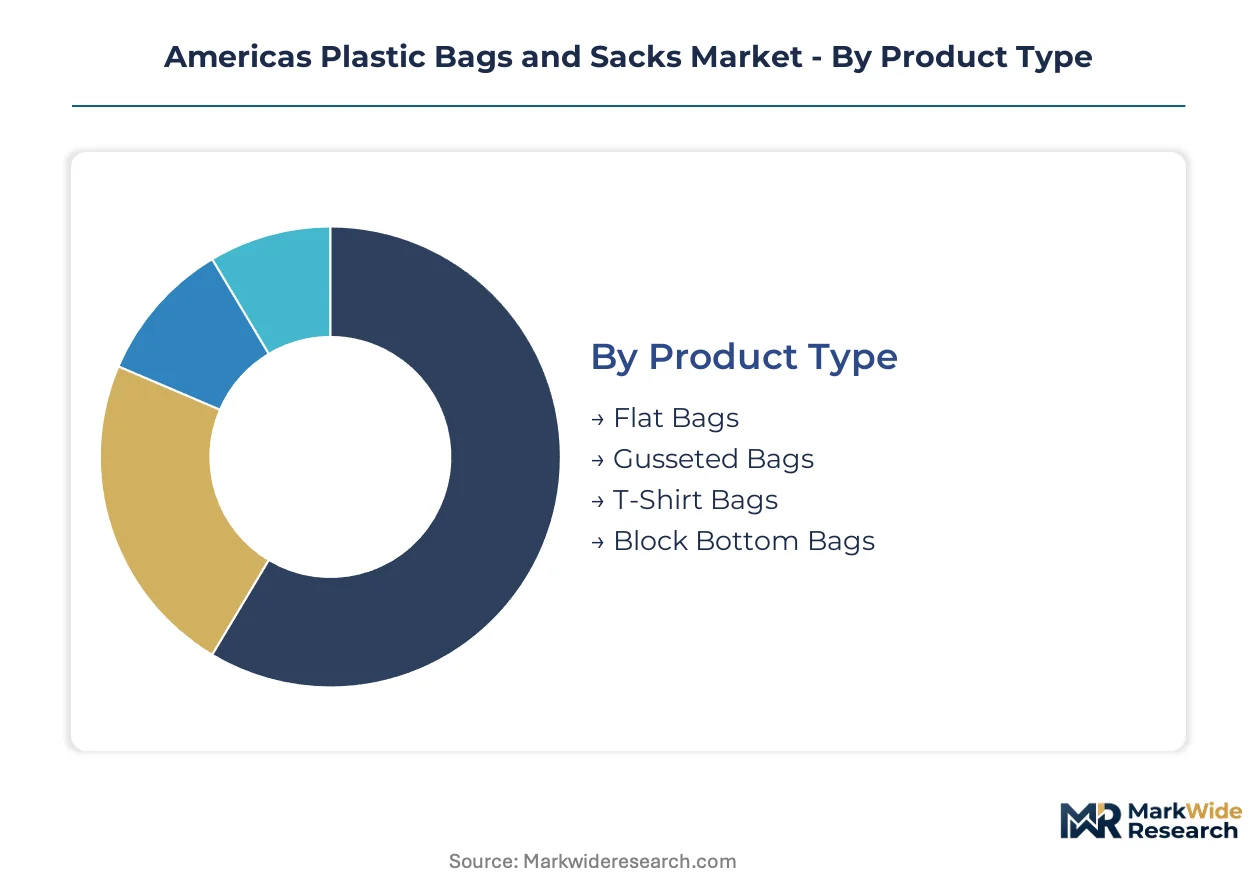
Product differentiation in the Americas Plastic Bags and Sacks Market follows end-use performance requirements rather than commodity logic. Specification upgrades in food safety and load-bearing capacity drive replacement cycles across converter operations.
Product Type:
Upgrade cycles vary dramatically by format, with stand-up stability and palletization efficiency commanding premium replacement schedules in food and industrial channels.
- Flat Bags:Simple two-dimensional construction without side or bottom expansion, typically specified for basic containment of apparel and soft goods. Retail distribution in Central American markets sustains volume placements for this mature format.
- Gusseted Bags:Side-folded expansion panels increase cubic capacity without additional material, optimizing pallet cube utilization in industrial shipping. Demand concentrates in Mexico's automotive corridor states where export assembly operations require standardized export packaging.
- T-Shirt Bags:Die-cut handle construction with reinforced shoulder design for retail carry applications. Guatemala and Honduras represent structurally underpenetrated territory relative to population density.
- Block Bottom Bags:Heat-sealed rectangular base enables vertical stand-up display and stable pallet stacking. Brazil's protein export sector favors this format for refrigerated container shipments.
Volume placements concentrate in T-Shirt Bags; the faster expansion belongs to Block Bottom Bags.
Material:
Cost tier stratification separates virgin polyethylene formulations from certified alternatives, with post-consumer recycled mandates forcing reformulation investments.
- HDPE:High-density formulation delivers stiffness and moisture resistance for retail carry bags and industrial liners. State-level bag bans in California and New York redirect procurement toward certified compostable alternatives, compressing HDPE's growth trajectory in regulated channels.
- LDPE:Low-density branching structure provides clarity and heat-sealability for food-contact applications. Canadian food-contact compliance under Health Canada and PMRA oversight governs specification requirements for retail distribution.
- LLDPE:Linear low-density copolymer balances puncture resistance and drawdown efficiency in blown film extrusion. Heavy-duty sack demand in Mexico's industrial corridor states favors this material for export-oriented manufacturing clusters.
- Biodegradable Plastics:PLA-PBAT polymer alloys designed for municipal composting infrastructure. Brazilian and Colombian composting buildout creates offtake certainty for certified film producers.
Cost-sensitive applications favor LLDPE; specification premiums accrue to Biodegradable Plastics where infrastructure exists.
End Use:
Customer type determines margin structure, with industrial procurement consolidating around direct mill relationships while retail fragments across distributor networks.
- Retail:High-volume carry bag and merchandise bag applications serving supermarkets, convenience stores, and apparel chains. Consolidated grocery procurement in São Paulo and Mexico City compresses supplier qualification cycles.
- Food Packaging:FDA and Health Canada food-contact compliance requirements govern film specifications for protein, produce, and processed goods. Gusseted and block bottom formats dominate this segment for stand-up stability.
- Industrial:Heavy-duty sacks and liners for chemicals, minerals, and automotive components. Export manufacturing clusters in Mexico generate concentrated demand for palletization-optimized formats.
- Healthcare:Sterile barrier and waste containment applications with bioburden control requirements. Specialized film specifications command qualification premiums in this regulated channel.
Industrial procurement delivers volume concentration; food packaging commands the steepest specification premiums.
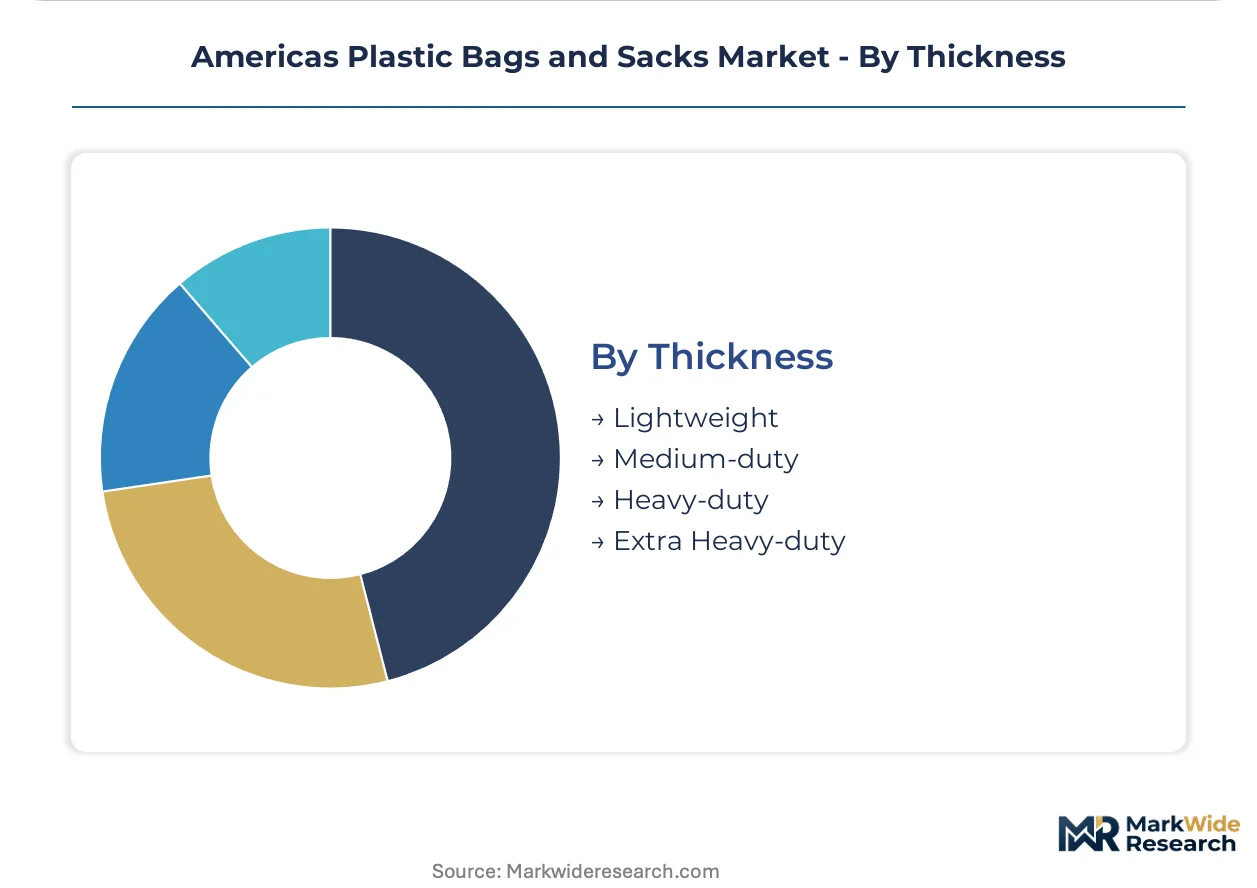
Thickness:
Application severity dictates gauge selection, with load-bearing requirements and regulatory minimums defining category boundaries.
- Lightweight:Sub-0.75 mil construction for single-use retail carry applications. California and New York state-level restrictions reshape minimum thickness specifications.
- Medium-duty:0.75-2.0 mil range balancing cost and durability for general merchandise and food service. This tier captures the broadest cross-application demand.
- Heavy-duty:2.0-4.0 mil formulation for industrial shipping and construction materials. Mexico's export-oriented manufacturing clusters specify this grade for automotive and electronics assembly.
- Extra Heavy-duty:Above 4.0 mil construction for abrasive contents and extended outdoor exposure. Mining and agricultural chemical applications in Brazil and Colombia sustain niche demand.
Medium-duty specifications dominate unit volume; heavy-duty grades capture expanding share in export manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Mexico's industrial corridor states, Brazil's protein export belt, and the U.S. coastal regulatory zones where state-level procurement rules diverge sharply. Canada anchors certified compostable adoption through provincial extended producer responsibility frameworks. Central American retail penetration remains structurally underdeveloped relative to population density.
United States
State-level bag bans in California and New York redirect grocery procurement toward certified compostable alternatives, compressing conventional polyethylene channels. The EPA regulates manufacturing emissions under Clean Air Act provisions while FDA oversees food-contact compliance. Midwest blown film infrastructure clusters in Illinois and Ohio create geographic supply concentration for industrial sack demand.
Mexico
Export-oriented automotive and electronics assembly operations in Nuevo León and Jalisco generate concentrated demand for heavy-duty palletization-optimized formats. Federal environmental standards under SEMARNIT interact with state-level industrial permitting. The Bajío Region's manufacturing corridor specifications favor LLDPE formulations for cross-border shipping compliance.
Brazil
Protein export sector demand in São Paulo and Paraná favors block bottom bags with stand-up stability for refrigerated container shipments. ANVISA governs food-contact film specifications entering retail distribution. Municipal composting infrastructure buildout in Rio de Janeiro and Minas Gerais creates offtake certainty for PLA-PBAT certified film producers.
Canada
Provincial extended producer responsibility frameworks in Ontario and Quebec create financial incentives for recycled content integration above baseline mandates. Health Canada and PMRA oversee food-contact compliance for polyethylene films. Prairie Provinces agricultural chemical applications sustain niche demand for extra heavy-duty construction.
Colombia
Consolidated grocery procurement in Bogotá compresses supplier qualification cycles and displaces legacy distributor relationships. National environmental licensing under ANLA shapes converter facility siting decisions. Medellín's industrial valley generates emerging demand for medium-duty food service specifications.
Americas Plastic Bags and Sacks Market Competitive Environment
Capacity expansion dominates the current landscape as converters retrofit legacy extrusion equipment for bio-based resin processing. The vendor base stratifies across integrated resin compounders, specialized film extruders, and regional converters serving fragmented retail channels. Three archetypes define competitive positioning: captive resin producers with backward integration into compounding, hybrid material specialists navigating pulp-plastic construction, and scale-driven extruders optimizing blown film throughput. M&A activity concentrates on geographic whitespace in Central America, while strategic partnerships with municipal composting operators secure offtake certainty for certified film producers.
Among North American integrated players, Berry Global exemplifies the captive resin archetype through multi-state compounding capacity, while Novolex Holdings anchors the scale-driven extrusion tier with integrated film and converting networks. Mondi PLC occupies a position within the hybrid material specialization vector, navigating Latin American pulp availability constraints through kraft-plastic construction expertise.
| Leading Market Players |
|---|
| ProAmpac LLC |
| Berry Global |
| Mondi PLC |
| Novolex Holdings |
| The Buckeye Bag Company |
| Inteplast Group |
| AEP Industries Inc. |
| International Plastics Inc. |
| LC Packaging International BV |
| Others |
Value Chain & Pricing Dynamics
Bio-based resin processing retrofits across North American blown film extrusion lines are simultaneously elevating capital intensity and concentrating supply among converters with captive compounding infrastructure. This technology transition compresses mid-tier margins while rewarding integrated players who control upstream resin formulation.
Pricing Analysis
Volume placements in T-shirt bags and flat bags compete on thin margins, while block bottom bags and certified compostable alternatives capture specification premiums. Price differentiation separates virgin polyethylene grades from post-consumer recycled content tiers and bio-based certified formulations. Cost compression in conventional HDPE channels is intensifying because state-level bag bans in California and New York restrict channel access. Retail procurement in Central America demonstrates the highest price sensitivity, whereas food packaging buyers in Brazil's protein export sector prioritize performance over unit cost.
Supply Chain Analysis
Domestic-content mandates under California's SB 54 and New York's bag ban amendments are reshaping sourcing toward certified compostable film producers with regional manufacturing footprints. Geographic supply concentration centers on the United States Midwest, Mexico's industrial corridor states, and Brazil's São Paulo-Paraná manufacturing belt. Raw material dependencies draw from virgin polyethylene resins, post-consumer recycled rPET and rHDPE, and PLA-PBAT polymer alloys. Single-source vulnerability in blown film extrusion equipment creates supply chain risk. Distribution runs through direct mill relationships displacing legacy regional wholesalers in major metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating across the Americas Plastic Bags and Sacks Market as regulatory compliance costs and bio-based retrofit investments force sub-scale converters toward exit or acquisition.
For Market Incumbents: Hedge against margin erosion by securing captive resin compounding capacity across multiple U.S. states to buffer feedstock volatility. Accelerate certification investment for ASTM D6400 and EN 13432 compliance to maintain channel access in California and New York. Control distribution by displacing legacy wholesalers with direct relationships to consolidated grocery procurement headquarters in São Paulo and Mexico City.
For New Entrants and Emerging Players: Begin with Central American retail penetration in Guatemala and Honduras, where T-shirt bag demand remains structurally underpenetrated relative to population density. Target municipal composting infrastructure partnerships in Brazilian and Colombian markets to secure offtake certainty for certified film production. Enter through private-label packaging programs with supermarket chains specifying PLA-PBAT polymer alloys.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated resin compounders given extended producer responsibility frameworks creating financial incentives for recycled content integration above baseline mandates. Long-term viability favors converters with backward integration into compounding and geographic diversification across multiple regulatory jurisdictions. Monitor composting facility certification alignment timelines as the inflection signal for certified film producer valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of rPET and rHDPE buffers converters against virgin polyethylene price volatility. |
| Certification Investment for Compostable Standards | ASTM D6400 and EN 13432 compliance secures channel access in California and New York regulated markets. |
| Geographic Expansion into Central America | T-shirt bag demand in Guatemala and Honduras offers whitespace penetration relative to population density. |
| Municipal Composting Infrastructure Partnership | Offtake agreements with Brazilian and Colombian operators create demand certainty for PLA-PBAT film producers. |
| Direct Mill Relationship Development | Headquarters-level procurement in São Paulo and Mexico City displaces legacy distributor intermediaries. |
Study Parameters
Independent corroboration across primary interviews with blown film extrusion plant managers, resin procurement leads at downstream converters, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from U.S. EPA emissions filings, state-level regulatory databases, Health Canada food-contact compliance records, and ANVISA submission data. Bottom-up capacity assessments and top-down demand triangulation reconcile volume estimates across the analysis window.
Rate-of-change decomposition across material grade tiers, product format specifications, end-use industry channels, and regional regulatory clusters structures the forecast framework. CAGRs derive from segment-level growth trajectory modeling incorporating compostable certification adoption curves, post-consumer recycled content mandate implementation timelines, and export manufacturing cluster expansion patterns. Industry-specific inputs include municipal composting infrastructure buildout schedules and state-level bag ban enforcement calendars.
Underlying measurement precision varies by segment; biodegradable plastics and certified compostable alternatives carry tighter precision than conventional polyethylene categories due to emerging infrastructure visibility. Forecasts reflect documented assumptions regarding regulatory implementation pace and resin technology cost curves. Raw material price volatility and patchwork subnational regulation fragmentation present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Drum Liners Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Laser Scored Bags Market