
 Europe Single-Use Packaging Market | 2026-2036
Europe Single-Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Single-Use Packaging Market Insights
Packaging engineering talent shortages across Central Europe are reorganizing how converters allocate automation investments. Amcor Group GmbH leverages its continental manufacturing footprint to sustain supply continuity for branded food clients. Huhtamaki Oyj anchors its position through molded fiber specialization, while Berry Global Inc competes via rigid plastic container scale in dairy and prepared meals.
Single-use packaging comprises disposable vessels, wraps, and utensils engineered for one-cycle product protection and consumer convenience, typically manufactured through thermoforming, injection molding, or pulp pressing with barrier coatings ranging from 12 to 50 micrometers. Its primary purpose is to extend shelf stability, ensure hygiene, and enable portion-controlled distribution across foodservice and retail channels. Plastic material type still leads volume but faces margin compression from EPR fees, whereas paper and biodegradable grades capture expanding quick-service restaurant specifications. Food containers dominate product category value pools, while food delivery services within the end-user dimension represent the fastest structural expansion as dark kitchens proliferate.
REACH, the EU Packaging and Packaging Waste Regulation, and national EPR schemes across Germany, France, and Italy are reshaping material compliance costs and recyclability mandates, forcing converters to certify recycled content thresholds or absorb extended producer responsibility levies. ECHA substance restrictions further limit certain polymer additives, redirecting formulation R&D toward approved chemical inventories. Stakeholders must monitor how the EU Green Deal's packaging minimization targets interact with food safety requirements under EFSA guidelines to determine viable material transitions.
Market Dynamics
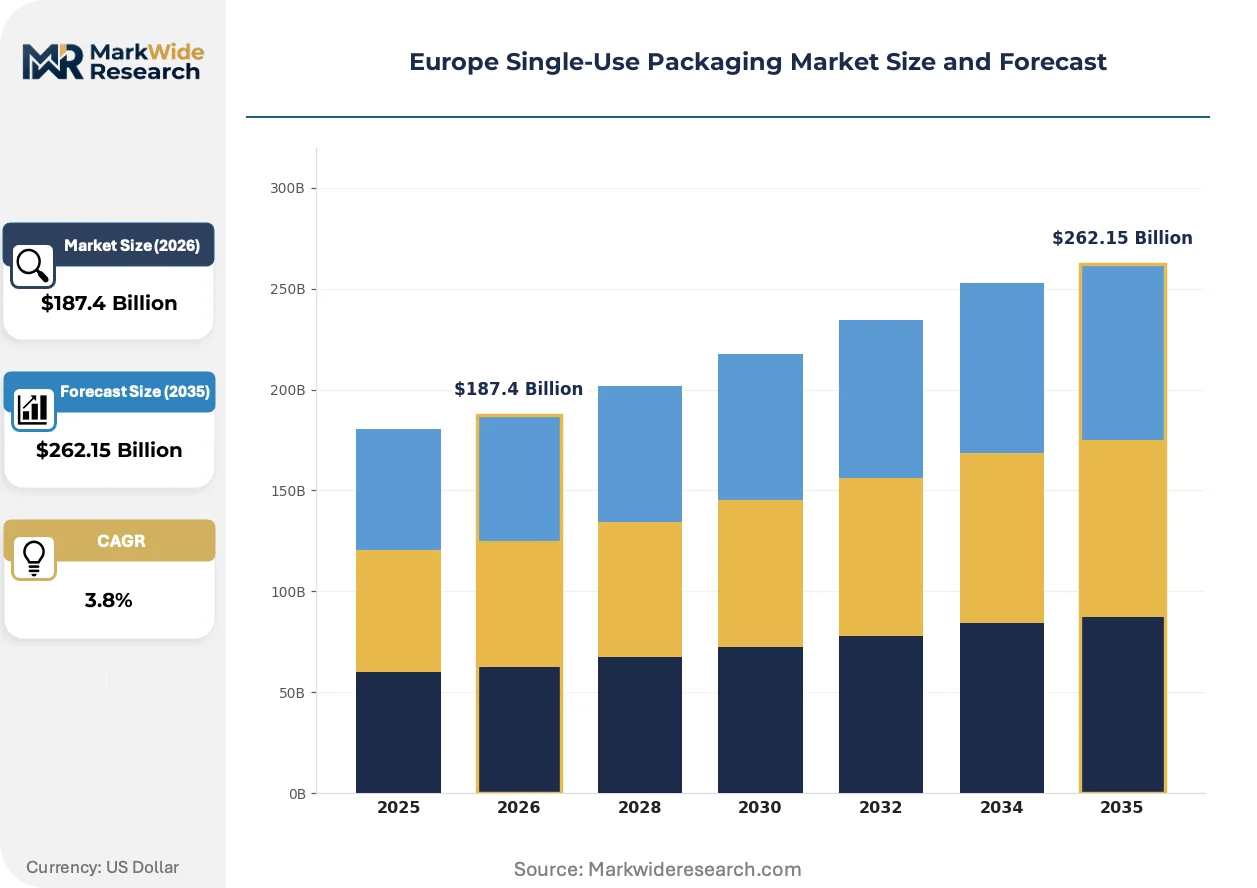
The EU Packaging and Packaging Waste Regulation is compressing polymer volumes while accelerating fiber-based substitution across foodservice supply chains. Converters must simultaneously certify recycled content thresholds and absorb extended producer responsibility levies, restructuring margin profiles and procurement specifications simultaneously.
Growth Catalysts
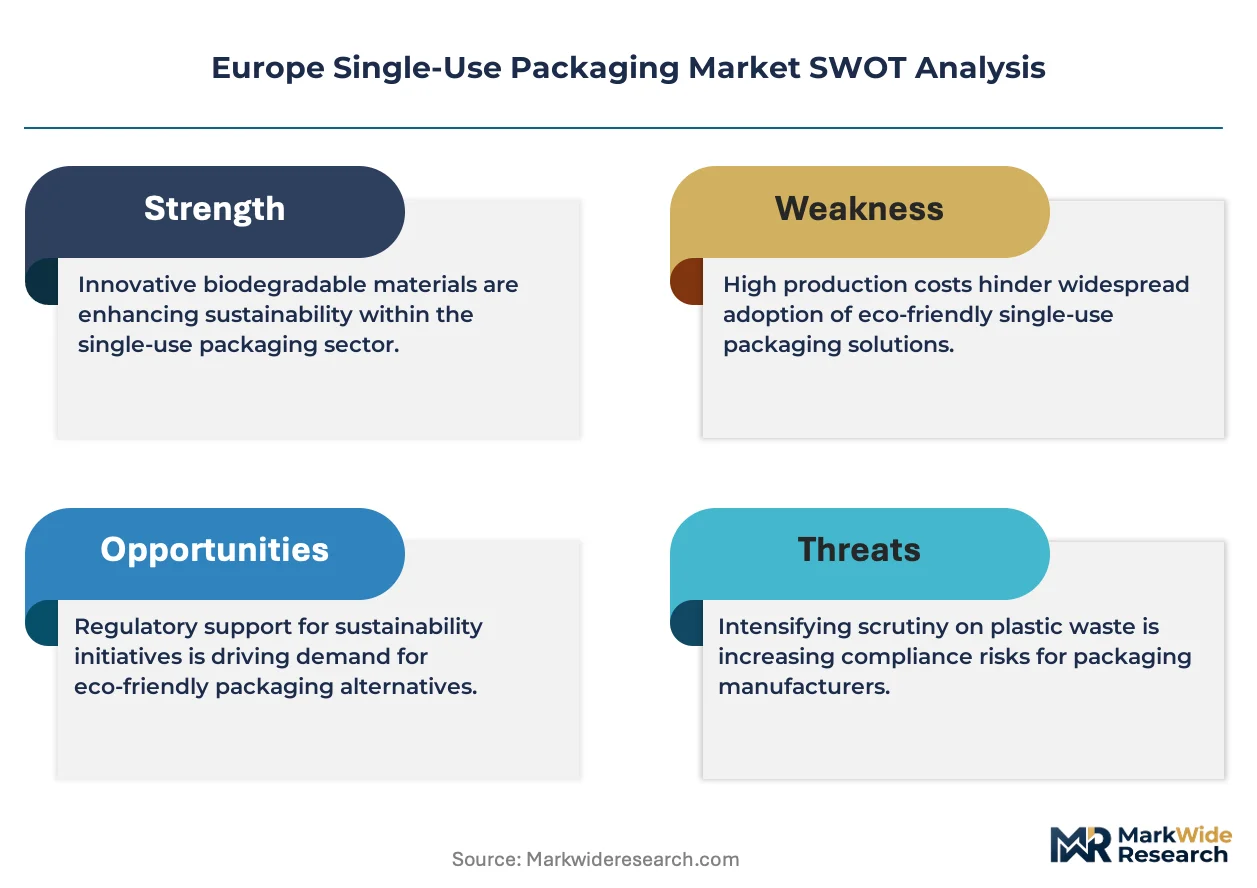
- Dark Kitchen Proliferation:Food delivery services across Germany, France, and the United Kingdom are expanding insulated bag and disposable container procurement. Meal-kit platforms require portion-controlled packaging with thermal stability.
- REACH Chemical Compliance:ECHA substance restrictions on polymer additives redirect formulation R&D toward approved chemical inventories. Approved barrier coatings now penetrate molded fiber substrates at commercial scale.
- Quick-Service Restaurant Specifications:Western European QSR chains are restructuring procurement toward biodegradable grades. Molded fiber specialization captures expanding cold-chain and hot-hold applications.
Market Restraints
- EPR Fee Compression:Extended producer responsibility levies in Germany, France, and Italy raise per-unit compliance costs. Rigid plastic containers face margin erosion against fiber alternatives.
- Pulp Input Volatility:Nordic pulp supply concentration exposes molded fiber converters to price swings. Energy-intensive pressing operations amplify cost sensitivity.
- Barrier Performance Gap:Biodegradable coatings at 12-50 micrometers struggle with grease resistance in prepared meals. Dairy applications retain polymer dependence.
Strategic Opportunities
- Central European Automation Gap:Packaging engineering talent shortages across Poland and Czechia create acquisition targets. Automation investments can capture labor-constrained capacity.
- EU Green Deal Tailwind:Packaging minimization targets interact with EFSA food safety guidelines. Certified fiber solutions gain preferential retailer listing.
- Retail Pharmacy Cold Chain:Temperature-sensitive pharmaceutical distribution in Benelux markets requires validated insulated packaging. Biodegradable thermal liners represent unpenetrated specification.
Industry Challenges
- Molded Fiber Tooling Lead Times:Pulp pressing die fabrication requires 16-24 week cycles. Converter capex commitments strain balance sheets ahead of demand confirmation.
- Multimaterial Separation Infrastructure:Coated fiber containers confuse municipal sorting streams. Recyclability claims face verification complexity under national EPR schemes.
- Barrier Coating Migration Testing:EFSA compliance timelines for novel biodegradable chemistries extend 18-36 months. Food contact notification bottlenecks delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Single-Use Packaging Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Biodegradable, Foam Product Category: Food Containers, Beverage Bottles, Utensils, Bags End User: Restaurants, Retailers, Food Delivery Services, E-commerce Application: Food & Beverage, Personal Care, Medical, Household |
| Companies Covered | Graphic Packaging International LLC, Novolex, Amcor Group GmbH, Nutripack SAS, Hotpack Packaging Industries LLC, Huhtamaki Oyj, Dart Container Corporation, Caterline Limited, Berry Global Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Single-Use Packaging Market Trends and Innovations
Active material substitution is compressing legacy polymer specifications while digital traceability requirements reshape converter technical roadmaps. Three forces dominate the innovation landscape.
Barrier-coated molded fiber is decomposing rigid plastic dominance in prepared meal containers. Quick-service restaurant chains in France and Germany are specifying fiber-based clamshells for ambient and chilled applications. The technology is decomposing historical polymer volume commitments as converters retool thermoforming lines toward pulp pressing.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from food contact applications. ECHA's restriction proposals force reformulation toward silicone and bio-based alternatives. Prepared meal segments across Italy and Spain face the steepest compliance timelines.
Buyer consolidation among grocery retailers is compressing supplier qualification cycles. Centralized procurement functions at German and French retail cooperatives now mandate recycled content certificates and carbon footprint disclosures. Private-label packaging specifications in the Benelux region are rotating fastest toward fiber-based alternatives.
Europe Single-Use Packaging Market Segmentation
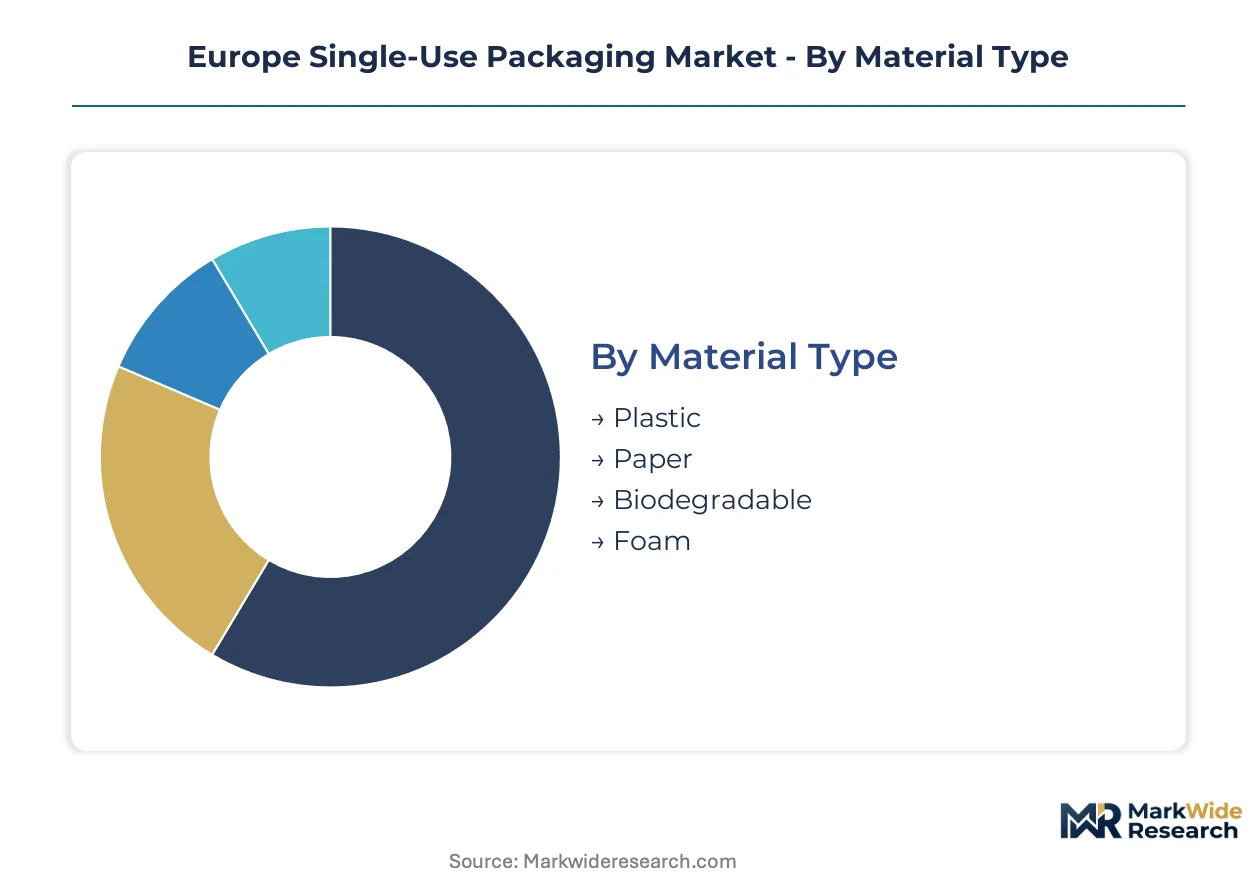
Material specifications across Europe are diverging as EPR schemes and REACH compliance force converters to rebalance portfolios. Segmentation reveals where fiber substitution is compressing polymer volumes and which end-use channels are restructuring procurement fastest.
Material Type:
Plastic grades still dominate domestic production across Germany and France, while biodegradable alternatives attract cross-border investment from Nordic pulp suppliers.
- Plastic:Thermoformed PET and PP containers retain scale in dairy and prepared meal segments across Italy and Spain. EPR fee compression in Germany and France is eroding margin profiles against fiber alternatives.
- Paper:Barrier-coated molded fiber from Nordic pulp mills is capturing quick-service restaurant specifications in France and Germany. EFSA compliance timelines for novel grease-resistant chemistries extend commercialization cycles.
- Biodegradable:PLA and PHA grades from Central European compounders serve export markets prioritizing compostability certifications. Dark kitchen procurement in the United Kingdom is testing thermal stability limits.
- Foam:Expanded polystyrene insulated containers face substance restrictions under ECHA proposals. Cold-chain pharmaceutical distribution in Benelux retains limited specification.
Plastic holds the largest share; momentum sits with paper.
Product Category:
Volume concentration varies by channel: foodservice drives container demand, while retail restructuring accelerates bag substitution.
- Food Containers:Clamshells and trays dominate quick-service restaurant procurement across Western Europe. REACH restrictions on PFAS grease-resistant coatings force reformulation toward silicone alternatives in prepared meal segments.
- Beverage Bottles:rPET content thresholds under EU Packaging and Packaging Waste Regulation strain supply availability. German retail cooperatives mandate carbon footprint disclosures for bottled water specifications.
- Utensils:Molded fiber cutlery from Polish converters serves export demand from French meal-kit platforms. Barrier coating migration testing delays EFSA approval for hot-liquid contact.
- Bags:Insulated delivery pouches with biodegradable thermal liners represent unpenetrated specification in Benelux pharmacy cold chains. Dark kitchen proliferation across the United Kingdom expands procurement scale.
Food containers command the value pool; bags are climbing the fastest.
End User:
Channel concentration is restructuring: food delivery services expand fastest while retailers consolidate supplier qualification.
- Restaurants:Quick-service chains in France and Germany specify fiber-based clamshells for ambient and chilled applications. Procurement functions mandate recycled content certificates.
- Retailers:Centralized buying at German and French cooperatives compresses supplier cycles. Private-label packaging in Benelux rotates fastest toward biodegradable grades.
- Food Delivery Services:Dark kitchens across Germany, France, and the United Kingdom drive insulated bag and disposable container procurement. Meal-kit platforms require portion-controlled packaging with thermal stability.
- E-commerce:Protective wrapping demand concentrates in Polish and Czech fulfillment hubs. Automation investments target labor-constrained capacity.
Restaurants retain the largest procurement volume; food delivery services are gaining share fastest.
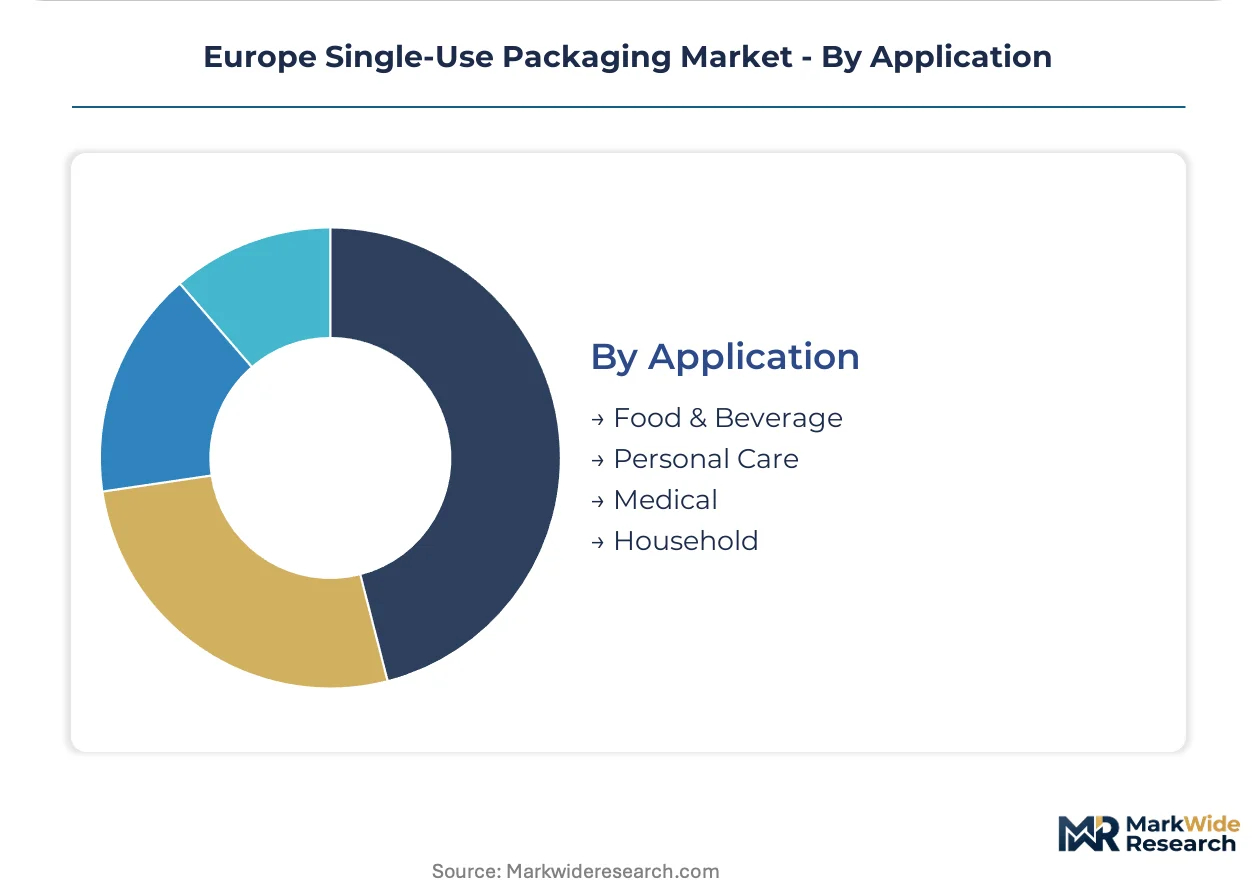
Application:
End-use diversification is accelerating as medical and personal care segments adopt foodservice-proven barrier technologies.
- Food & Beverage:Prepared meals and dairy retain polymer dependence where grease resistance exceeds fiber capabilities. EPR schemes raise per-unit compliance costs.
- Personal Care:Biodegradable sachets for single-dose cosmetics attract investment from Italian converters. ECHA substance restrictions limit legacy polymer additives.
- Medical:Temperature-sensitive pharmaceutical distribution requires validated insulated packaging. Retail pharmacy cold chains in Benelux test biodegradable thermal liners.
- Household:Cleaning product pods face multimaterial separation challenges in municipal sorting streams. Recyclability claims face verification complexity under national EPR schemes.
Food and beverage dominates application value; medical shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU Packaging and Packaging Waste Regulation anchor compliance frameworks across Germany, France, and Italy, where EPR schemes and recycled content mandates are restructuring converter economics and procurement specifications.
Germany
Quick-service restaurant chains in Bavaria and North Rhine-Westphalia are mandating fiber-based clamshells with recycled content certificates. The national EPR scheme raises per-unit compliance costs for rigid plastic containers. Converter investments concentrate in Hamburg and Berlin-Brandenburg to serve dark kitchen procurement clusters.
France
Meal-kit platforms in Île-de-France are expanding portion-controlled packaging procurement with thermal stability requirements. ANSM and EFSA guidelines on barrier coating migration testing extend commercialization timelines for novel biodegradable chemistries. Molded fiber specialization accelerates in Auvergne-Rhône-Alpes around Lyon-based pulp pressing operations.
United Kingdom
Dark kitchen proliferation across Greater London and Manchester drives insulated bag and disposable container demand. The UK's post-Brexit packaging regulations maintain alignment with EU Green Deal minimization targets. Retail pharmacy cold chains in the Southeast test biodegradable thermal liners for temperature-sensitive distribution.
Italy
Prepared meal segments in Lombardy and Emilia-Romagna face steep compliance timelines for PFAS-free grease-resistant coatings under ECHA restrictions. Dairy applications in Piedmont retain polymer dependence where barrier performance gaps persist. Italian converters attract investment for single-dose cosmetic sachets in personal care packaging.
Netherlands
Retail cooperatives in the Randstad region mandate carbon footprint disclosures and recycled content certificates for private-label packaging. Benelux pharmacy cold chains require validated insulated packaging with emerging biodegradable specifications. Rotterdam and Amsterdam logistics hubs concentrate protective wrapping demand from e-commerce fulfillment networks.
Europe Single-Use Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding continental manufacturing footprints and the lower tier competing on molded fiber or rigid plastic specialization. Strategic archetypes include pan-European converters with backward integration into pulp supply, regional specialists in barrier-coated fiber substrates, and scale-driven rigid plastic container fabricators. Dominant competitive moves center on thermoforming line retooling toward pulp pressing and strategic partnerships to secure EFSA-compliant barrier coating formulations.
Among Nordic- and German-based fabricators, Huhtamaki Oyj and Amcor Group GmbH exemplify the integrated leader archetype, while Berry Global Inc occupies a position within the scale-driven rigid plastic tier. These three companies represent distinct strategic postures: molded fiber specialization, continental supply continuity, and polymer container scale respectively.
| Leading Market Players |
|---|
| Graphic Packaging International LLC |
| Novolex |
| Amcor Group GmbH |
| Nutripack SAS |
| Hotpack Packaging Industries LLC |
| Huhtamaki Oyj |
| Dart Container Corporation |
| Caterline Limited |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
Sixteen-to-twenty-four week pulp pressing die fabrication cycles concentrate converter capex commitments ahead of demand confirmation, amplifying pricing power for Nordic pulp suppliers while compressing margins for molded fiber specialists absorbing EPR levies.
Pricing Analysis
Price spreads between German and Italian converters reflect divergent EPR scheme intensity, with per-unit compliance costs in Germany running higher than Mediterranean markets. Pricing stratifies across premium EFSA-certified barrier coatings, standard recycled-content fiber grades, and economy rigid plastic tiers. Cost compression in rigid plastic containers intensifies as fiber alternatives capture quick-service restaurant specifications. Meal-kit platforms in France exhibit lowest price sensitivity due to thermal stability requirements, while Polish e-commerce fulfillment hubs drive hardest bargain on protective wrapping volumes.
Supply Chain Analysis
Finland and Sweden anchor Nordic pulp supply concentration for molded fiber substrates, while Germany and Poland host thermoforming and injection molding capacity for rigid plastic containers. Raw material dependencies center on bleached kraft pulp, recycled PET flake, and bio-based barrier coating chemistries. Single-source vulnerability concentrates in Nordic pulp mill networks exposed to energy price volatility. Distribution runs through centralized procurement functions at German and French retail cooperatives, with dark kitchen clusters in Greater London and Manchester pulling insulated bag inventory through third-party logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as fiber-based packaging displaces polymer specifications across foodservice procurement, forcing incumbents to retool capacity or surrender share to Nordic pulp-integrated competitors.
For Market Incumbents: Fortify backward integration into pulp supply or captive barrier coating formulation capabilities to defend against Huhtamaki Oyj's molded fiber specialization. Accelerate EFSA compliance timelines for novel biodegradable chemistries before PFAS restrictions eliminate legacy grease-resistant coatings. Priority lever rests on securing 18-36 month food contact notification approvals ahead of competitor submissions. For New Entrants and Emerging Players: Differentiate on biodegradable thermal liner technology for Benelux pharmacy cold chains, where validated insulated packaging specifications remain underpenetrated. Target dark kitchen procurement clusters in Manchester and Birmingham with portion-controlled packaging engineered for meal-kit thermal stability. Go-to-market angle emphasizes compostability certifications aligned with UK post-Brexit packaging regulations maintaining EU Green Deal alignment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across molded fiber pressing operations as 16-24 week tooling lead times strain balance sheets. Long-term viability favors acquiring Polish or Czech converters with automation-ready footprints and packaging engineering talent pipelines. Signal to watch: EFSA approval bottlenecks clearing for silicone-based barrier coatings, which would accelerate fiber substitution timelines and revalue pulp-integrated assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic pulp mill partnerships secure input cost stability against EPR-driven fiber demand surges. |
| EFSA Barrier Coating Certification | Novel silicone-based grease-resistant chemistries unlock prepared meal segments facing PFAS restrictions. |
| Automation Investment in Central Europe | Polish and Czech pressing operations capture labor-constrained capacity as engineering talent shortages bite. |
| Dark Kitchen Supply Agreement | Insulated bag procurement clusters in Greater London offer volume anchoring through meal-kit platform expansion. |
| Retail Pharmacy Cold Chain Validation | Biodegradable thermal liner specifications in Benelux open pharmaceutical distribution to fiber-based alternatives. |
Research Methodology
Operator-level perspectives from converter plant managers, quick-service restaurant procurement directors, retail cooperative category buyers, and EFSA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation compliance filings, ECHA substance restriction proposals, national EPR scheme levy schedules, and Nordic pulp mill production disclosures. Bottom-up volume estimates from individual converter capacity announcements triangulated against top-down procurement spend analysis at German and French retail cooperatives.
Sensitivity analysis tested fiber substitution velocity against varying EPR fee trajectories and REACH compliance timeline assumptions across the projection horizon. Segmentation dimensions modeled include material type, product category, end-user channel, and application, with cross-cutting analysis of regional regulatory cluster intensity. CAGRs derived from weighted average of historical volume trends and forward procurement specification shifts, incorporating dark kitchen proliferation rates and meal-kit platform expansion curves as demand-side inputs.
Material uncertainties — EFSA notification bottlenecks extending commercialization cycles, Nordic pulp supply disruptions from energy price spikes, and post-Brexit UK regulatory divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EPR scheme harmonization and PFAS restriction implementation pacing. Recalibration cycles align with material shifts in EU Green Deal packaging minimization targets and ECHA substance restriction finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
Strip Pack Market