
 Transformer Tap Changers and Voltage Control Relay Market | 2026-2036
Transformer Tap Changers and Voltage Control Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Tap Changers and Voltage Control Relay Market Analytics
Copper winding assemblies is pivoting toward silver-plated contact systems in high-current tap changer designs, reducing maintenance cycles and contact erosion. Reinhausen Group leverages captive production of vacuum interrupters to anchor its European installed base. Siemens Energy competes through integrated digital monitoring packages bundled with its on-load tap changer portfolio. ABB dominates the North American utility retrofit segment with factory-refurbished units that extend transformer service life.
Transformer tap changers and voltage control relays are electromechanical or solid-state devices that adjust transformer winding ratios to maintain output voltage within specified tolerances, typically operating across voltage classes from distribution-level 11 kV to extra-high-voltage 765 kV systems. Their primary purpose is to stabilize grid voltage against load fluctuations, thereby protecting downstream equipment and ensuring power quality for industrial and commercial consumers. On-load tap changer installations lead the product mix due to their ability to regulate voltage without interrupting power flow, while smart control technology represents the fastest-expanding technology segment as utilities deploy IEC 61850-compliant intelligent electronic devices for remote diagnostics. Relay systems for voltage protection command premium margins where nuclear and data center applications require SIL-rated redundancy.
FERC Order 2222 and the EU Green Deal's network investment targets are reshaping procurement specifications for grid-connected voltage regulation equipment in the United States and Europe. IEC 60214-1 and IEEE C57.131 define mechanical endurance and dielectric withstand requirements that determine product qualification timelines and factory testing protocols. India's CEA mandates periodic insulation resistance testing for tap changers above 66 kV, creating aftermarket service demand for diagnostic relay upgrades. Stakeholders must weigh the capital efficiency of mechanical refurbishment against the operational analytics enabled by electronic smart control architectures as grid operators prioritize predictive maintenance over scheduled outage windows.
Market Dynamics
Grid operators are retiring mechanical tap changer fleets ahead of failure curves while IEC 61850-compliant intelligent electronic devices compress commissioning timelines for voltage control relay retrofits.
Growth Catalysts
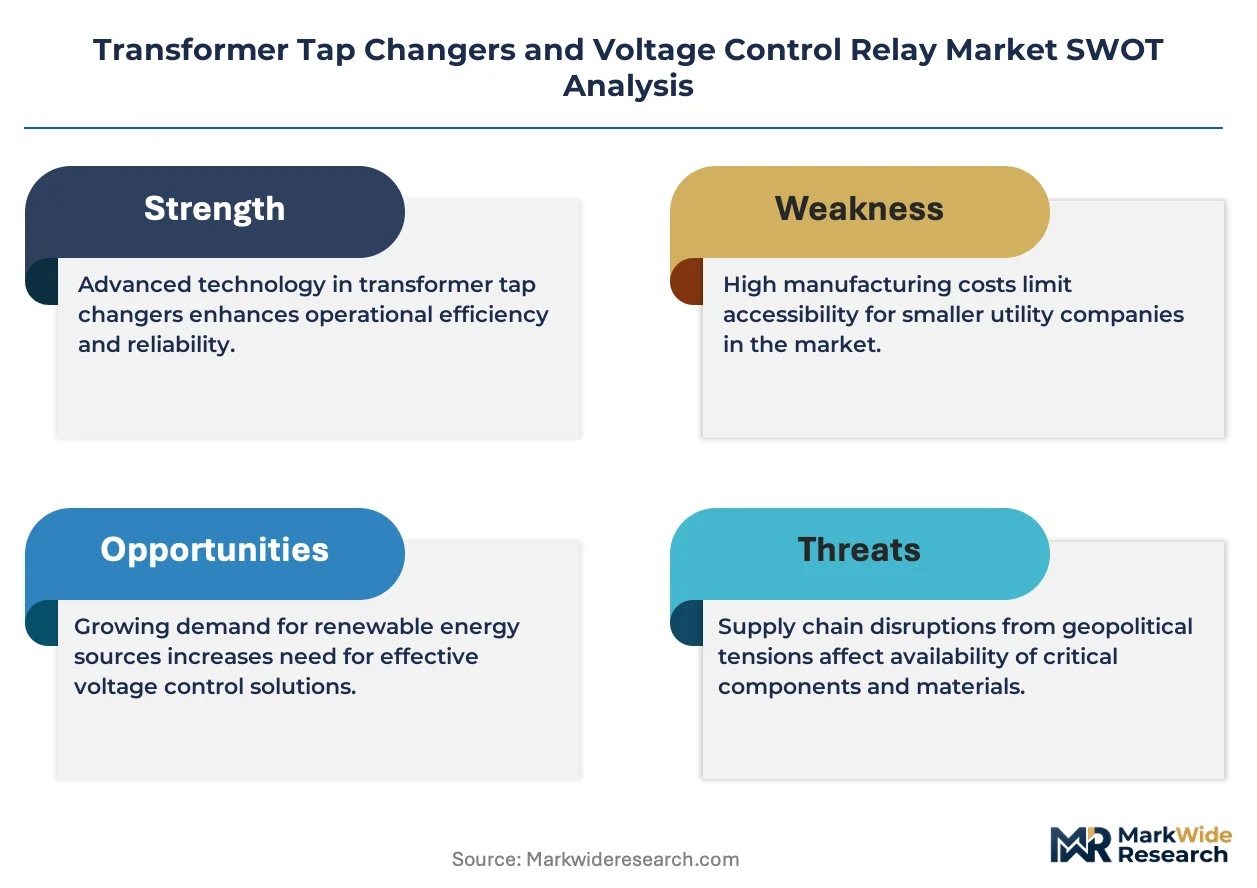
- India CEA Testing Mandates:Periodic insulation resistance requirements for tap changers above 66 kV create aftermarket demand for diagnostic relay upgrades and predictive maintenance contracts.
- China Transmission Buildout:State Grid Corporation deploys hybrid electronic-mechanical units at scale across ultra-high-voltage corridors, normalizing smart control architectures.
- Silver-Plated Contact Systems:Copper winding assemblies pivot toward silver-plated designs in high-current tap changer applications, reducing maintenance cycles and contact erosion.
Market Restraints
- Vacuum Interrupter Supply Concentration:Captive production of vacuum interrupters anchors European supply chains, creating bottlenecks for non-integrated manufacturers.
- IEC 60214-1 Qualification Timelines:Mechanical endurance and dielectric withstand requirements extend factory testing protocols, delaying product commercialization.
- Solid-State Relay Substitution:Thyristor-based voltage regulators threaten electromechanical relay share in data center and nuclear applications requiring SIL-rated redundancy.
Strategic Opportunities
- US FERC Order 2222:Distributed energy resource aggregation rules reshape procurement specifications for grid-connected voltage regulation equipment, opening utility-scale retrofit windows.
- EU Green Deal Network Targets:Investment mandates accelerate transformer fleet modernization across Germany, France, and Italy, prioritizing efficiency upgrades.
- Digital Monitoring Convergence:Integration of IEC 61850 protocols with edge analytics platforms enables remote diagnostics and predictive maintenance service models.
Industry Challenges
- IEC 61850 Integration Complexity:Legacy transformer assets require protocol bridging and cybersecurity hardening to accept intelligent electronic device retrofits.
- Specialized Field Technician Scarcity:On-load tap changer maintenance demands expertise in both mechanical adjustment and digital calibration, constraining service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Tap Changers and Voltage Control Relay Market |
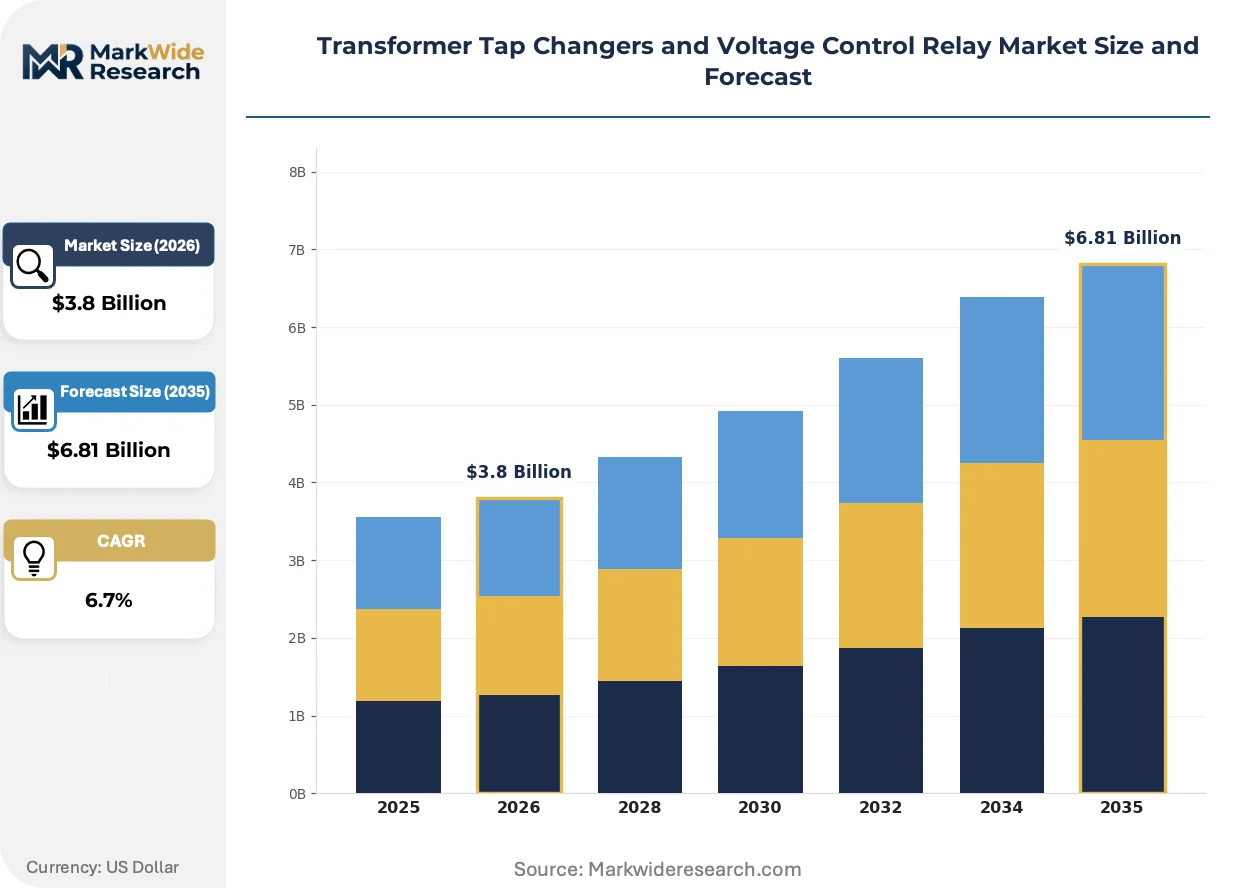
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-load Tap Changer, Off-load Tap Changer, Voltage Regulator, Relay System Technology: Mechanical, Electronic, Hybrid, Smart Control Application: Power Generation, Transmission, Distribution, Industrial End User: Utilities, Renewable Energy Providers, Industrial Plants, Commercial Buildings |
| Companies Covered | GE Vernova, Schneider Electric, Reinhausen Group, Howard Industries, Maschinenfabrik Reinhausen GmbH, ABB, Eaton, Mitsubishi Electric Corporation, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Tap Changers and Voltage Control Relay Market Evolving Landscape
Electromechanical tap changer architectures are yielding to hybrid designs that embed real-time monitoring, while regulatory pressure on grid resilience accelerates relay intelligence requirements.
Hybrid electronic-mechanical tap changers combine vacuum interrupter durability with microprocessor-controlled switching precision. State Grid Corporation and European transmission operators deploy these units across 400 kV and 765 kV systems. This convergence is unifying maintenance schedules and diagnostic data streams into single-platform asset management.
FERC Order 2222 and the EU Green Deal's network investment targets are tightening performance specifications for grid-connected voltage regulation equipment. Procurement tenders now mandate IEC 61850 compliance and predictive maintenance capability. North American utilities respond by bundling digital monitoring packages with on-load tap changer contracts.
Service unbundling separates hardware supply from predictive maintenance contracts, compressing traditional outage-based revenue cycles. Industrial and data center buyers now procure voltage control relays through energy service companies rather than direct OEM relationships. This shift concentrates in the United States and Germany where third-party asset management has achieved regulatory acceptance.
Transformer Tap Changers and Voltage Control Relay Market Segmentation
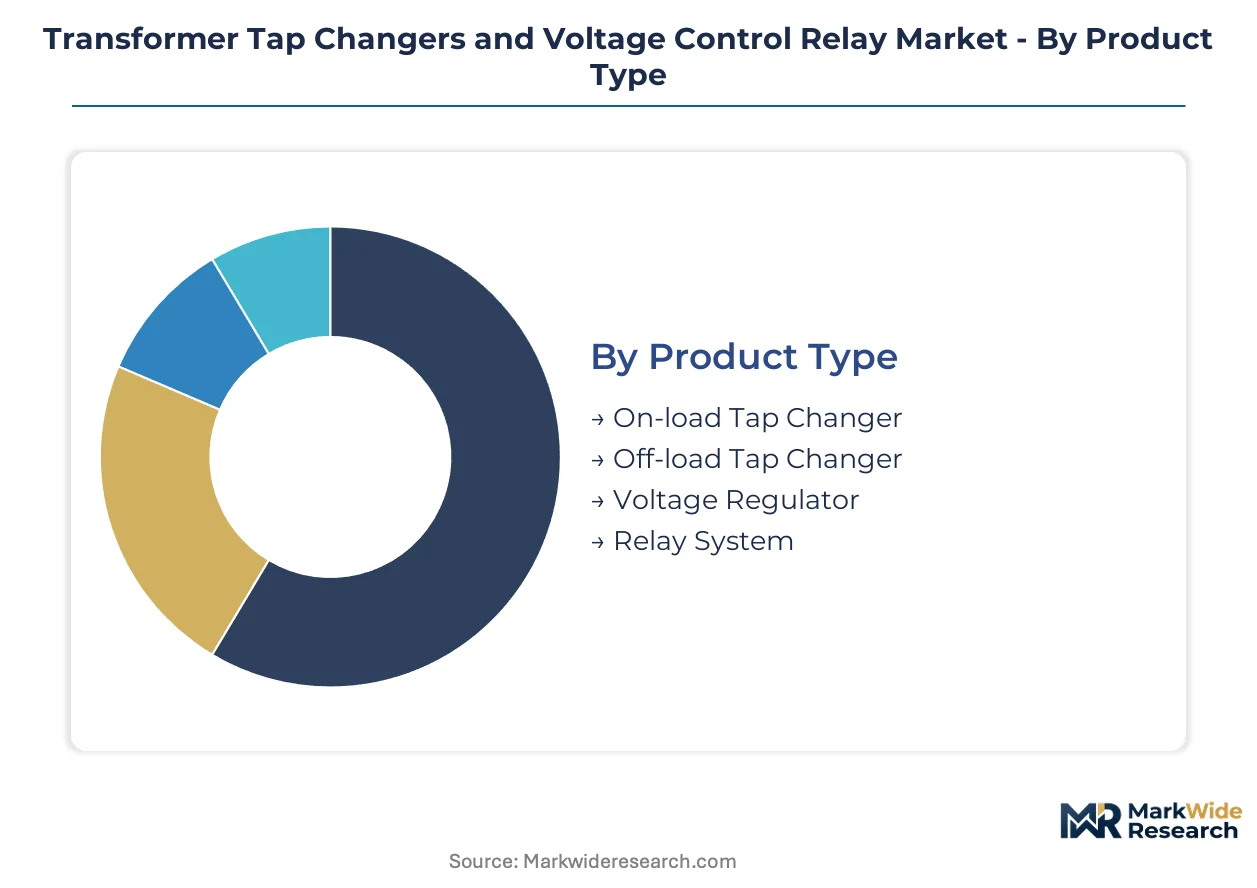
Transformer tap changer and voltage control relay procurement hinges on voltage class, switching duty, and interoperability mandates. Each segment carries distinct certification burdens and lifecycle cost profiles that shape vendor selection and retrofit timing.
Product Type:
IEC 60214-1 and IEEE C57.131 impose divergent mechanical endurance testing protocols across product categories, with on-load designs facing the most stringent dielectric withstand verification.
- On-load Tap Changer:Electromechanical or vacuum interrupter-based units switch winding ratios without service interruption. State Grid Corporation deploys these across 765 kV corridors in China, with hybrid electronic-mechanical architectures normalizing smart control integration.
- Relay System:Intelligent electronic devices and electromechanical protection relays monitor voltage thresholds and trigger tap adjustments. Nuclear and data center applications in Germany and the United States command SIL-rated redundancy premiums where FERC Order 2222 reshapes grid interconnection rules.
- Off-load Tap Changer:De-energized switching devices for distribution transformers and maintenance windows.
- Voltage Regulator:Standalone autotransformer units for feeder-level voltage support in rural distribution networks.
On-load Tap Changer sits at the top of the volume ranking, with Relay System climbing the fastest.
Technology:
Capital deployment patterns split sharply between refurbishment-heavy mechanical segments and greenfield electronic installations.
- Smart Control:IEC 61850-compliant intelligent electronic devices with edge analytics and remote diagnostics. European transmission operators and India's state utilities prioritize these for predictive maintenance contracts under CEA testing mandates.
- Hybrid:Vacuum interrupter durability fused with microprocessor-controlled switching precision. Reinhausen Group and Siemens Energy compete here across 400 kV systems in Germany and extra-high-voltage corridors in China.
- Mechanical:Traditional cam-operated and resistor-transition tap changers dominating legacy installed base.
- Electronic:Solid-state thyristor-based regulators threatening electromechanical share in data center applications.
Mechanical retains the largest installed base, though Smart Control is expanding most quickly as utilities retire aging fleets.
Application:
End-use concentration determines maintenance scheduling intensity and spare parts inventory requirements.
- Transmission:Extra-high-voltage corridors from 220 kV to 765 kV requiring continuous voltage regulation. China's State Grid Corporation and European TSOs drive specification tightening for hybrid unit deployment.
- Distribution:Feeder-level voltage support across 11 kV to 66 kV networks. India's CEA mandates periodic insulation resistance testing above 66 kV, creating aftermarket demand for diagnostic upgrades.
- Power Generation:Generator step-up transformer regulation at nuclear, coal, and renewable plant interconnections.
- Industrial:Steel, chemical, and mining operations requiring tight voltage tolerance for motor protection.
Transmission commands the highest unit values, with Distribution showing the steepest expansion trajectory amid grid modernization programs.
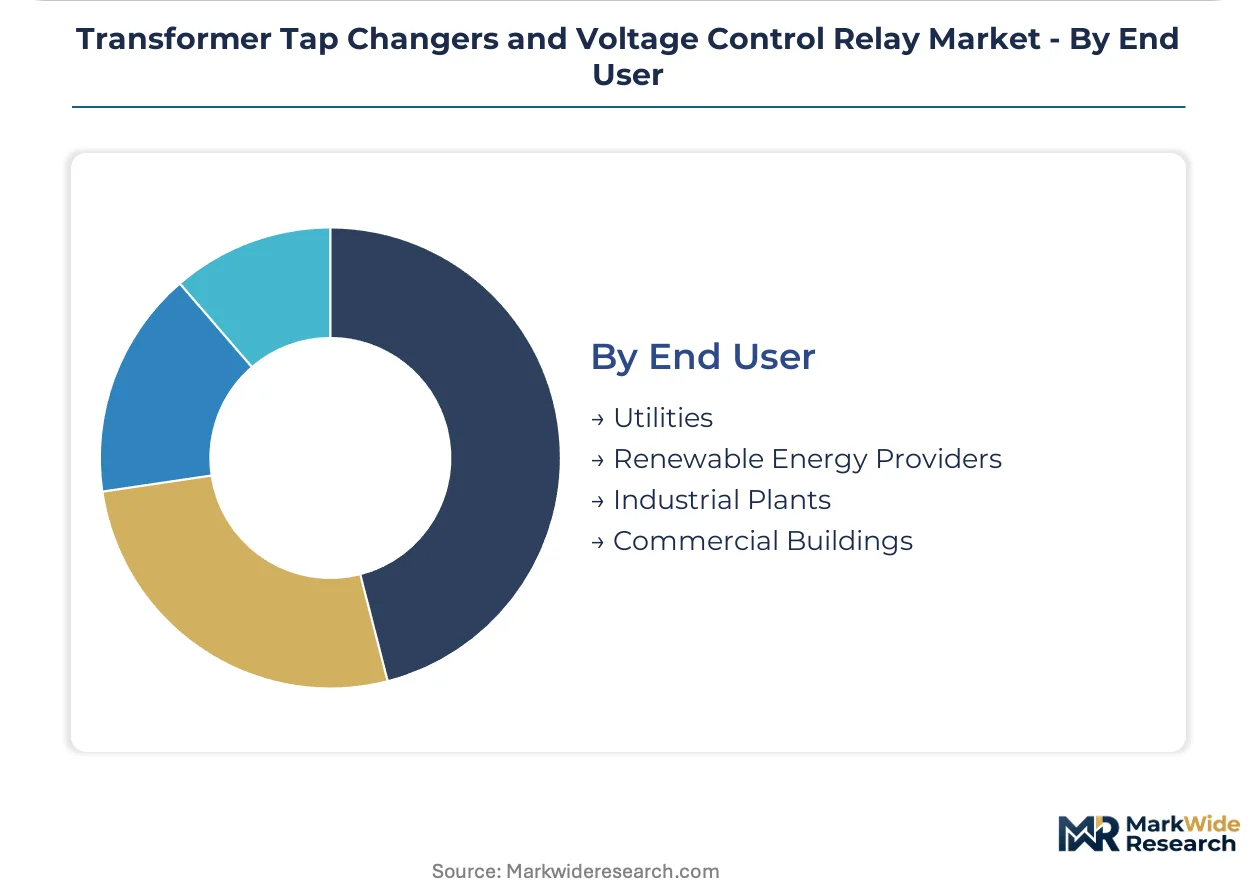
End User:
Procurement authority and lifecycle service expectations vary substantially across customer categories.
- Utilities:Transmission and distribution operators with centralized asset management platforms. ABB dominates North American utility retrofit segments with factory-refurbished units extending transformer service life.
- Industrial Plants:Steel mills, petrochemical complexes, and mining operations requiring customized voltage tolerance specifications.
- Renewable Energy Providers:Wind and solar farm interconnections facing variable generation voltage fluctuation challenges.
- Commercial Buildings:Data centers and large facility managers procuring through energy service companies rather than direct OEM relationships.
Utilities anchor procurement volume, while Renewable Energy Providers are gaining share fastest as variable generation penetration climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State Grid Corporation's ultra-high-voltage corridors anchor procurement volume for hybrid electronic-mechanical tap changers. Grid modernization mandates across multiple jurisdictions reshape specification requirements for voltage control equipment. Regulatory divergence between IEC and IEEE standards creates distinct qualification pathways by geography.
China
State Grid Corporation deploys hybrid units across 765 kV transmission corridors spanning the Yangtze River Delta and Pearl River Delta. The National Energy Administration enforces GB standards for smart grid equipment interoperability. Shenzhen and Chengdu clusters concentrate manufacturing capacity for vacuum interrupter components serving domestic and export demand.
United States
FERC Order 2222 drives utility-scale retrofit windows for distributed energy resource aggregation infrastructure. The Federal Energy Regulatory Commission mandates grid interconnection standards that compress commissioning timelines for intelligent electronic devices. Texas and California transmission operators lead procurement of digital monitoring packages bundled with on-load tap changer contracts.
Germany
European TSOs accelerate transformer fleet modernization under EU Green Deal network investment targets. The Bundesnetzagentar enforces grid resilience standards that tighten performance specifications for voltage regulation equipment. Bavaria and North Rhine-Westphalia industrial zones concentrate demand for SIL-rated relay systems protecting chemical and automotive manufacturing loads.
India
State utilities expand grid modernization programs across Maharashtra and Gujarat transmission networks. The Central Electricity Authority mandates periodic insulation resistance testing for tap changers above 66 kV, creating aftermarket demand for diagnostic relay upgrades. Tamil Nadu and Karnataka renewable energy zones drive voltage regulator procurement for variable solar and wind generation interconnection.
Japan
Tokyo Electric Power and regional utilities retrofit aging mechanical tap changer fleets ahead of failure curves. METI's grid resilience directives prioritize predictive maintenance capability in procurement specifications. The Kansai industrial corridor around Osaka maintains concentrated demand for tight-voltage-tolerance equipment serving precision manufacturing operations.
Transformer Tap Changers and Voltage Control Relay Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance mechanical refurbishment services against electronic smart control development. The vendor base separates into three tiers: integrated multinationals with captive component production, regional specialists focused on aftermarket service, and emerging electronics firms attacking solid-state relay segments. Strategic archetypes include vacuum interrupter integrators, digital monitoring platform bundlers, and factory-refurbishment service providers. Technology licensing agreements and backward integration into critical components represent the dominant competitive moves reshaping supply chain control.
Among European-integrated manufacturers, Maschinenfabrik Reinhausen GmbH and Reinhausen Group exemplify the vacuum interrupter captive-production archetype, anchoring service capacity across continental transmission operator installed bases. Siemens Energy occupies a position within the digital convergence tier, while ABB represents the North American utility retrofit specialist model. GE Vernova and Mitsubishi Electric Corporation sit within the scale-driven multinational tier, competing through geographic coverage and standards compliance breadth rather than component-level integration.
| Leading Market Players |
|---|
| GE Vernova |
| Schneider Electric |
| Reinhausen Group |
| Howard Industries |
| Maschinenfabrik Reinhausen GmbH |
| ABB |
| Eaton |
| Mitsubishi Electric Corporation |
| Siemens Energy |
| Others |
Value Network & Pricing Analysis
Silver-plated copper contact assemblies flow from German and Japanese metallurgical suppliers through tiered pricing structures that separate IEC 61850-compliant smart control units from mechanical refurbishment offerings. Vacuum interrupter captive production by Reinhausen Group and Siemens Energy anchors premium tier pricing power, while spot-market copper sourcing pressures margins in standard-grade electromechanical segments.
Pricing Analysis
Input-cost pass-through from silver and copper commodity volatility stratifies pricing across premium, standard, and economy tiers. IEC 61850 certification and SIL-rated redundancy for nuclear applications command 40-60% premiums over baseline electromechanical units. Pricing pressure stems from solid-state thyristor substitution in data center voltage regulation, compressing electromechanical relay margins. Industrial utilities show highest price sensitivity, prioritizing refurbishment cycles over smart control upgrades, while transmission operators absorb premium pricing for predictive maintenance bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand from State Grid Corporation and European TSOs, while regional distributors serve aftermarket retrofit markets. Manufacturing concentrates in Germany, China, and Japan, with vacuum interrupter production anchored in Bavarian and Shenzhen industrial clusters. Raw material dependencies center on copper winding stock, silver contact plating, and epoxy resin insulation systems. Single-source vulnerability runs through captive vacuum interrupter supply chains controlled by integrated European manufacturers. Distribution runs through factory-authorized service networks for warranty compliance, supplemented by third-party energy service companies in North American and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where grid modernization mandates and IEC 61850 interoperability requirements shift procurement toward premium smart control specifications. Buyers now prioritize predictive maintenance capability over lowest-first-cost mechanical alternatives.
For Market Incumbents: Deploy backward integration into vacuum interrupter production to defend margin structure against solid-state relay substitution. Reinhausen Group's captive component model demonstrates supply security value. Incumbents must accelerate IEC 61850 protocol bridging solutions for legacy transformer retrofit markets, as field technician scarcity constrains service capacity expansion. Certification investment in SIL-rated redundancy systems protects nuclear and data center premium positioning. For New Entrants and Emerging Players: The 30-40% price-point gap between premium hybrid units and economy mechanical refurbishment creates entry space for mid-tier electronic control specialists. India's CEA-mandated diagnostic upgrade market above 66 kV offers the most penetrable geography, with state utilities expanding grid modernization programs across Maharashtra and Gujarat. A software-centric go-to-market model bundling edge analytics with third-party hardware integration bypasses captive vacuum interrupter barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional service providers lack IEC 61850 digital capability and predictive maintenance platform infrastructure. Long-term viability favors integrated manufacturers with backward component control and recurring service revenue streams. Acquisition targets should display factory-refurbishment expertise married to smart control retrofit capability. The signal to watch is FERC Order 2222 implementation velocity, as distributed energy resource aggregation rules reshape utility procurement specifications and accelerate replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Protocol Integration | Enables remote diagnostics for State Grid Corporation and European TSO predictive maintenance contracts. |
| Vacuum Interrupter Capacity Expansion | Secures supply security for hybrid tap changer production serving 765 kV transmission corridors. |
| Factory Refurbishment Service Scaling | Extends transformer service life for North American utilities under FERC Order 2222 retrofit windows. |
| SIL-Rated Redundancy Certification | Unlocks premium pricing in German nuclear and United States data center voltage protection applications. |
| Edge Analytics Platform Development | Supports CEA-mandated diagnostic contracts for Indian state utilities above 66 kV installations. |
Research Methodology
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each market. The research combines interviews with utility planning officers, transformer maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation from IEC standards documentation, IEEE C57.131 technical specifications, FERC filings, and CEA regulatory mandates. Bottom-up unit deployment estimates triangulate against top-down transmission infrastructure investment data from national grid operators.
Granularity-level modeling disaggregates volume and value across product type, technology architecture, voltage class, and end-user procurement authority throughout the forecast period. CAGRs derive from segmented growth rate analysis applied to baseline installed base retirement curves and greenfield deployment pipelines. Forecast inputs incorporate State Grid Corporation ultra-high-voltage corridor buildout schedules, EU Green Deal network investment allocation trajectories, and India's renewable energy zone interconnection timelines.
Caveats apply where commodity price volatility in copper and silver markets, vacuum interrupter supply disruptions, or accelerated solid-state relay substitution could materially shift the outlook. Forecasts reflect assumptions regarding IEC 61850 adoption velocity and regulatory mandate enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
DC Power Supplies Market
Power Systems
Charge Pumps Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Charge Controller System Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Global Excitation Systems Market
Power Systems
Thyristor Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Traction Inverter Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Converter Modules Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Laptop Battery Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market