
 Europe Shunt Reactors Market | 2026-2036
Europe Shunt Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Shunt Reactors Market Foresight
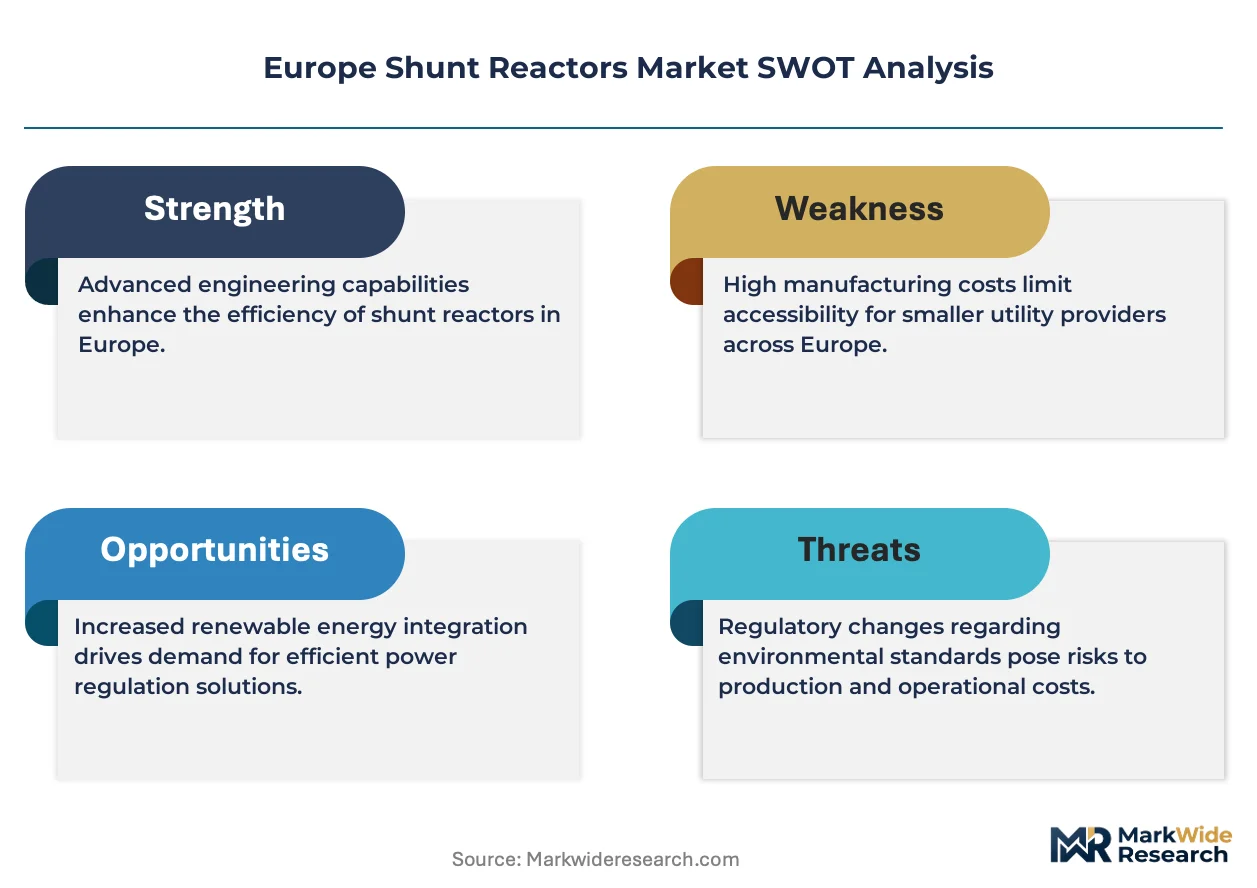
Aftermarket service revenue is tilting toward predictive maintenance contracts as grid operators extend asset life cycles. Siemens AG leverages its digital services portfolio to capture recurring revenue from reactive power infrastructure. ABB Ltd anchors its position through integrated control systems that bundle shunt reactors with FACTS devices. CG Power and Industrial Solutions Limited specializes in compact oil-immersed designs for space-constrained European substations.
Shunt reactors are inductive devices designed to absorb reactive power and stabilize grid voltage, typically rated from tens to hundreds of megavolt-amperes with core or coreless construction depending on thermal and acoustic constraints. Their primary purpose is to compensate for capacitive effects in long transmission lines and cable networks, preventing overvoltage conditions that degrade insulation and trip protection systems. Oil-immersed reactors retain dominance in extra-high-voltage applications where thermal dissipation demands exceed dry-type capabilities, while dry-type and resin-insulated variants gain share in urban indoor installations constrained by fire safety codes. Power utilities represent the most mature end-user segment with replacement-driven procurement, whereas renewable energy developers constitute the fastest-growing demand pool as offshore wind farms require dynamic reactive compensation at point of interconnection.
The EU Green Deal and Ecodesign Directive frame product efficiency mandates, compelling manufacturers to reduce no-load losses and document lifecycle environmental impacts through CE conformity assessments. ECHA's REACH restrictions on mineral oil additives are pushing resin-insulated alternatives into mainstream specifications for environmentally sensitive zones. Grid codes issued by national regulators in Germany, France, and Italy mandate specific reactive power capabilities that directly determine reactor sizing and switching control requirements. Stakeholders must monitor evolving network code harmonization and carbon border adjustment mechanisms that could reshape sourcing economics for core steel and winding copper.
Market Dynamics
Reactive power compensation demand from offshore wind interconnection is compressing procurement cycles across transmission system operators, forcing reactor manufacturers to accelerate dry-type development timelines while managing legacy oil-immersed replacement obligations under tightening EU Ecodesign thresholds.
Growth Catalysts
- EU Ecodesign Directive:Mandated efficiency upgrades are forcing premature retirement of mineral-oil units, creating replacement volume in Germany and Poland.
- Offshore wind clustering:North Sea corridor projects in Denmark, the Netherlands, and Germany require dynamic reactive compensation at 220-400 kV interconnection points.
- Resin-insulated technology:Urban substation operators facing fire safety codes are specifying cast-resin reactors for indoor installations.
Market Restraints
- Grain-oriented electrical steel concentration:Core material sourcing depends on a narrow supplier base concentrated in East Asian metallurgical capacity.
- ECHA REACH additive restrictions:Mineral oil formulations face progressive chemical bans, complicating spare parts availability for installed base.
- Extra-high-voltage thermal physics:Dry-type designs cannot yet match oil-immersed thermal dissipation above 400 kV, limiting substitution.
Strategic Opportunities
- Polish grid modernization:PSE's transmission expansion program represents underpenetrated procurement volume for 400 kV reactive compensation.
- Digital twin integration:Convergence of reactor assets with SCADA-enabled predictive maintenance platforms creates recurring service revenue.
- EU Green Deal financing:Just Transition Mechanism funds are accelerating brownfield substation upgrades in coal-dependent regions.
Industry Challenges
- HV equipment engineering scarcity:Specialized magnetic design expertise for gapped-core reactors is concentrating among retiring practitioner cohorts.
- Type-test certification timelines:KEMA and CESI laboratory queues for 420 kV reactor validation extend project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Shunt Reactors Market |
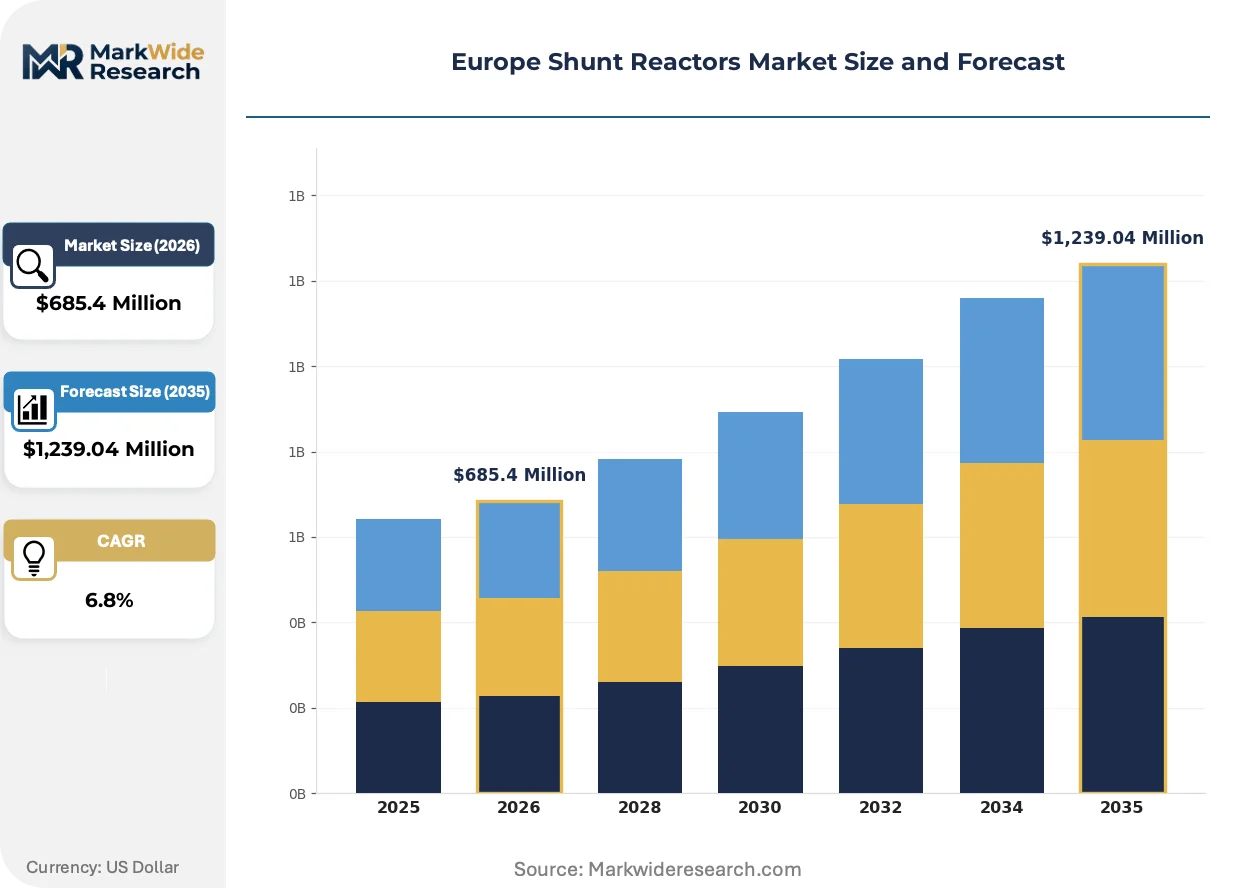
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Core, Oil-Immersed, Resin-Insulated, Dry-Type End User: Power Utilities, Industrial Plants, Renewable Energy, Transmission Companies Voltage Level: High Voltage, Medium Voltage, Extra High Voltage, Low Voltage Installation Type: Indoor, Outdoor, Pole-Mounted, Pad-Mounted |
| Companies Covered | Siemens AG, CG Power and Industrial Solutions Limited, Mitsubishi Electric Corporation, Fuji Electric Co., Hyosung Corporation, ABB Ltd, Alstom, Hitachi Ltd, Hyundai Heavy Industries Co Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Shunt Reactors Market Shifts & Advancements
Digitalization of grid assets is reconfiguring how reactive power infrastructure is specified, monitored, and monetized across European transmission networks. Three concurrent developments are compressing traditional equipment procurement models.
Digital reactor monitoring is virtualizing condition assessment that previously required scheduled outages. Transmission operators in Germany and the Netherlands are deploying sensor-embedded windings for real-time hot-spot detection. This capability is virtualizing maintenance scheduling, collapsing the distinction between preventive and corrective intervention models.
EU F-Gas Regulation amendments are restricting sulfur hexafluoride use in switchgear paired with shunt reactors. Manufacturers must redesign tap-changer and breaker integration for alternative insulation media. The dry-type segment faces the most acute redesign pressure as resin systems compete with fluoronitrile-based alternatives.
Service unbundling is fragmenting traditional EPC contracts. Grid operators now separate reactor supply from installation and commissioning, then layer predictive maintenance as a distinct procurement lot. This pattern is most visible in Danish offshore wind connections, where TenneT and Energinet have pioneered multi-vendor asset management frameworks.
Europe Shunt Reactors Market Segmentation
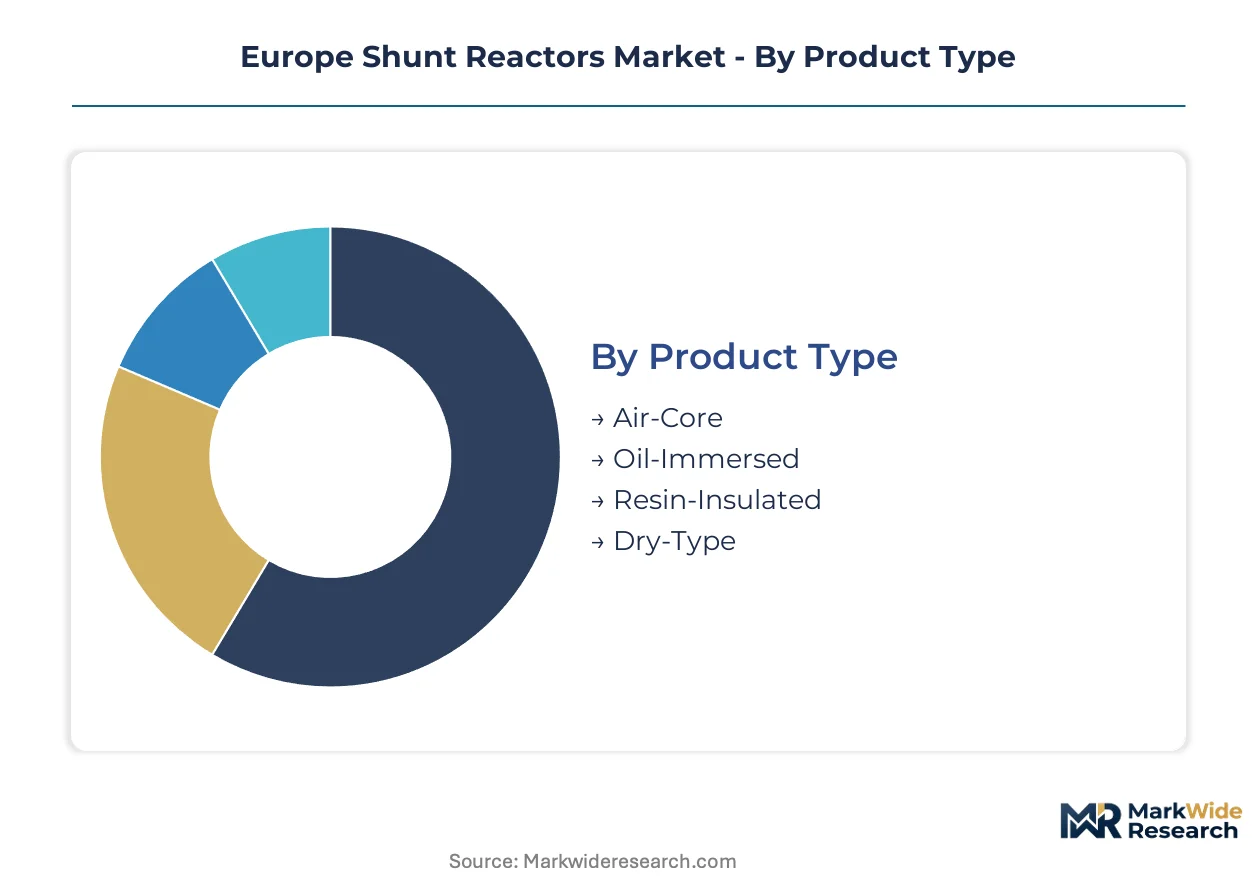
Segmentation in the Europe Shunt Reactors Market reveals how technical specifications, installation constraints, and end-use requirements fragment procurement patterns across transmission networks. Understanding these divisions clarifies why oil-immersed designs dominate extra-high-voltage corridors while dry-type alternatives capture urban substation retrofits.
Product Type:
Use-case spectrum spans coastal offshore wind interconnections requiring thermal resilience, urban indoor installations facing fire safety codes, and legacy grid corridors with established maintenance protocols.
- Oil-Immersed:Mineral-oil cooling enables continuous thermal dissipation for units rated above 400 kV in German and Polish transmission corridors. Ecodesign Directive efficiency mandates are accelerating replacement cycles for aging installations while preserving technology dominance in extra-high-voltage applications where dry-type thermal physics remain inadequate.
- Resin-Insulated:Cast-resin winding insulation eliminates fire risk and mineral-oil containment requirements for indoor urban substations in the Netherlands and Denmark. ECHA REACH restrictions on oil additives are pushing this technology into mainstream specifications for environmentally sensitive zones near North Sea wind clusters.
- Air-Core:Coreless magnetic design reduces acoustic signature and eliminates core saturation risks for specialized applications requiring linear reactance characteristics.
- Dry-Type:Resin-impregnated or vacuum-pressure-impregnated windings serve medium-voltage distribution networks where oil containment infrastructure is economically prohibitive.
Established volume favors Oil-Immersed; emerging adoption favors Resin-Insulated.
End User:
Customer archetypes range from state-mandated transmission system operators with decade-long asset cycles to renewable developers compressing procurement timelines for offshore project commissioning.
- Power Utilities:Incumbent grid operators across Germany, France, and Italy manage replacement-driven procurement for aging 220-400 kV infrastructure under national regulatory frameworks. Their procurement cycles extend 18-36 months due to integrated control system requirements and KEMA-type certification queues.
- Renewable Energy:Offshore wind developers in Danish, German, and Dutch North Sea zones require dynamic reactive compensation at point of interconnection with accelerated delivery schedules. This segment is expanding most quickly as EU Green Deal financing compresses project development timelines.
- Transmission Companies:TenneT, Energinet, and PSE operate as regulated entities with procurement transparency obligations under EU public procurement directives.
- Industrial Plants:Steel, chemical, and automotive facilities specify medium-voltage units for captive power quality management in manufacturing clusters.
Replacement obligations anchor Power Utilities; capacity expansion drives Renewable Energy.
Voltage Level:
Technical segmentation follows insulation coordination standards and thermal dissipation physics that constrain material selection across the voltage hierarchy.
- Extra High Voltage:Units rated 220 kV and above serve backbone transmission corridors interconnecting national grids across the North Sea corridor. Oil-immersed construction retains mandatory status here due to dielectric stress and thermal management requirements that exceed dry-type capabilities.
- High Voltage:66-220 kV applications span inter-regional transmission and large renewable interconnection points where resin-insulated designs are gaining specification share.
- Medium Voltage:Distribution network applications favor dry-type and resin-insulated alternatives for substations serving urban load centers.
- Low Voltage:Specialized industrial power quality applications represent limited procurement volume concentrated in manufacturing facility upgrades.
Technology lock-in preserves Extra High Voltage; substitution elasticity concentrates in High Voltage.
Installation Type:
Physical deployment constraints determine enclosure specifications, fire safety compliance, and maintenance access protocols across European grid infrastructure.
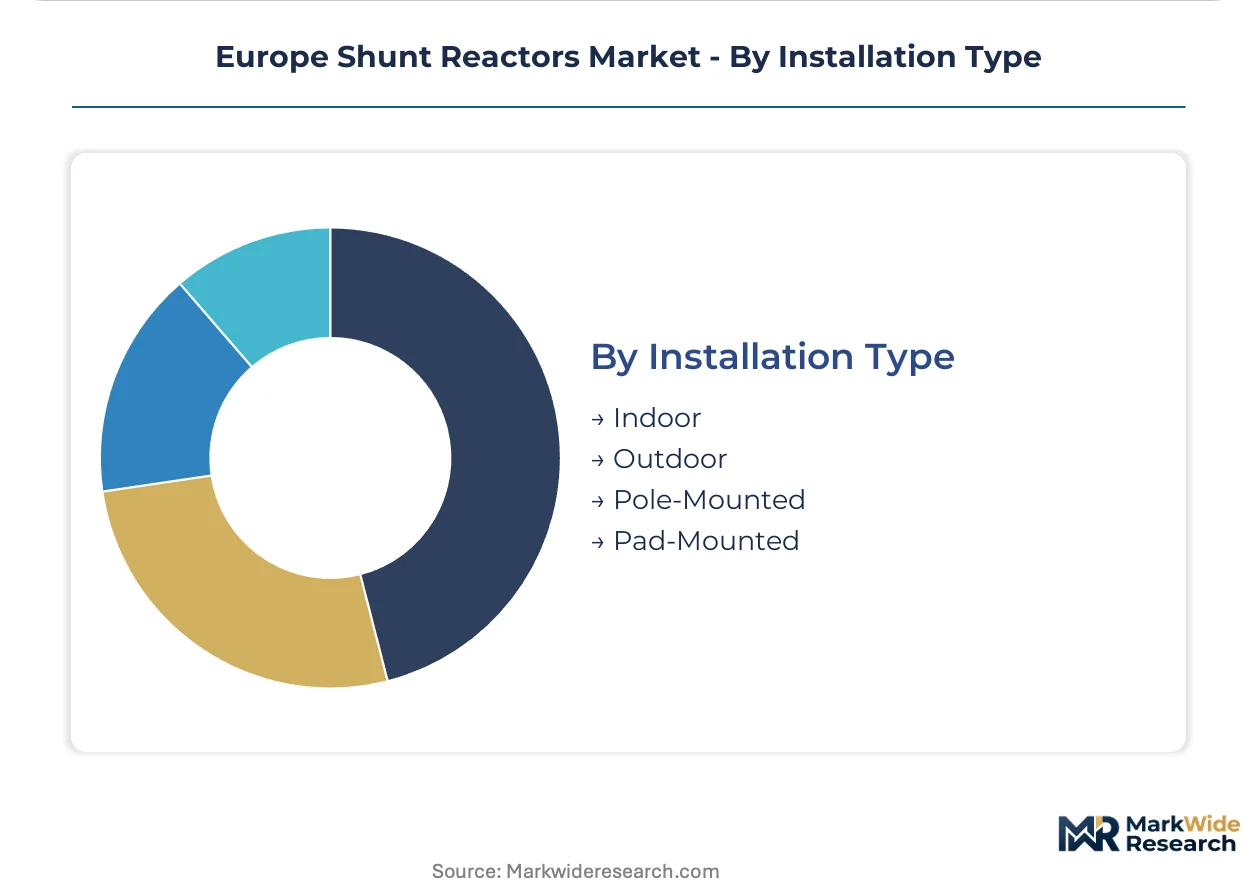
- Outdoor:Open-air substations in German and Polish transmission corridors accommodate large oil-immersed units with integrated containment and fire suppression systems. These installations dominate extra-high-voltage capacity expansion tied to offshore wind integration.
- Indoor:Urban substations in Dutch and Danish city centers specify resin-insulated or dry-type designs to satisfy fire safety codes and eliminate oil containment infrastructure. Space constraints and environmental permits favor compact, low-maintenance alternatives.
- Pad-Mounted:Ground-level enclosures serve medium-voltage distribution networks in suburban and industrial park settings.
- Pole-Mounted:Elevated installations address space-constrained rural distribution applications with limited procurement volume in European markets.
Capacity expansion favors Outdoor; regulatory pressure favors Indoor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes shunt reactors through transmission corridor expansion, while Poland deploys them through grid modernization catch-up. The Netherlands and Denmark favor indoor resin-insulated units for urban constraints, diverging from German and Polish outdoor oil-immersed preferences.
Germany
TenneT and 50Hertz drive reactive power procurement for North Sea offshore wind clusters. The EU Ecodesign Directive mandates efficiency thresholds that accelerate retirement of aging mineral-oil installations. Hamburg and Lower Saxony host manufacturing and testing facilities serving 400 kV transmission projects.
Poland
PSE's transmission expansion program creates concentrated demand for extra-high-voltage compensation capacity. National grid codes aligned with EU network codes determine reactor sizing and switching specifications. The Pomeranian corridor connecting Baltic offshore zones to the national backbone anchors procurement volume.
Netherlands
Randstad urban density enforces strict fire safety codes that exclude oil-immersed designs from indoor substations. The F-Gas Regulation restricts sulfur hexafluoride in associated switchgear, forcing insulation media redesigns. Rotterdam and Eindhoven regions concentrate resin-insulated specification activity.
Denmark
Energinet's offshore interconnection program compresses procurement timelines for dynamic reactive compensation. REACH restrictions on mineral oil additives push cast-resin alternatives for environmentally sensitive coastal zones. The North Sea corridor linking Esbjerg to German interconnectors anchors installation activity.
France
RTE manages replacement-driven procurement for aging 225-400 kV infrastructure under national regulatory frameworks. The EU Green Deal financing mechanisms accelerate brownfield substation upgrades in former coal-dependent regions. The Hauts-de-France corridor connecting Belgian and German grids concentrates interconnection investment.
Europe Shunt Reactors Market Competitive Landscape
Capability concentration sits with specialized magnetic design houses; scale advantage sits with diversified industrial conglomerates. The European shunt reactor market exhibits tiered structure where engineering-intensive extra-high-voltage units command premium positioning against commoditized medium-voltage alternatives. Strategic archetypes include integrated grid solution providers, reactor-focused specialists, and diversified heavy electrical manufacturers. Competitive moves center on digital service bundling and dry-type technology migration to capture Ecodesign-driven replacement cycles.
Among Germany-based industrial conglomerates, Siemens AG occupies a position exemplifying integrated control system bundling. ABB Ltd represents the diversified electrical equipment archetype with cross-border European presence. CG Power and Industrial Solutions Limited sits within the specialist tier focused on compact design configurations for space-constrained installations.
| Leading Market Players |
|---|
| Siemens AG |
| CG Power and Industrial Solutions Limited |
| Mitsubishi Electric Corporation |
| Fuji Electric Co. |
| Hyosung Corporation |
| ABB Ltd |
| Alstom |
| Hitachi Ltd |
| Hyundai Heavy Industries Co Ltd |
| Others |
Supply & Pricing Matrix
East Asian metallurgical clusters anchor grain-oriented electrical steel production, concentrating upstream pricing power among a narrow supplier base and compressing margins for European reactor manufacturers facing REACH-mandated material substitutions.
Pricing Analysis
Long-term offtake contracts dominate procurement between transmission system operators and reactor manufacturers, insulating buyers from spot volatility in copper and magnetic steel. Price differentiation separates EHV oil-immersed units with KEMA-type certification from standard medium-voltage dry-type alternatives. Cost compression in the resin-insulated tier is intensifying as REACH restrictions on mineral oil additives accelerate demand for cast-resin alternatives. Renewable energy developers exhibit the highest price sensitivity due to compressed project timelines, while incumbent utilities prioritize lifecycle cost over upfront capital.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for core steel procurement. Manufacturing capacity concentrates in China, Japan, and South Korea for grain-oriented electrical steel, with secondary winding copper sourcing from Chile and Zambia. Raw material dependencies rest on rare earth additives for magnetic performance optimization and epoxy resin systems for insulation. Single-source vulnerability characterizes 420 kV gapped-core engineering expertise. Distribution runs through EPC contractors and direct utility procurement channels with extended type-test certification queues at KEMA and CESI laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive and F-Gas Regulation amendments are reshaping competitive positioning through forced technology migration and insulation media redesign, creating asymmetric opportunities across the value chain.
For Market Incumbents: Insulate core margins by accelerating dry-type development timelines to capture Ecodesign-driven replacement volume while maintaining oil-immersed dominance above 400 kV where thermal physics preserve technology lock-in. Secure long-term offtake agreements with PSE and TenneT to defend against Asian competitors leveraging cost advantages in standard-grade resin-insulated units. Prioritize digital twin integration to build recurring service revenue streams that offset commoditization pressure in equipment supply. For New Entrants and Emerging Players: Polish 400 kV transmission expansion represents the most penetrable entry point for specialized magnetic design houses seeking to bypass saturated German procurement channels. Urban indoor substations in Dutch Randstad corridors offer white-space demand for compact resin-insulated configurations compliant with fire safety codes. Partner with Energinet's multi-vendor asset management frameworks to establish reference installations before scaling across North Sea offshore wind clusters. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure replacement play because EU network code harmonization and carbon border adjustment mechanisms will sustain procurement velocity regardless of macroeconomic cyclicality. Target acquisition candidates with captive gapped-core engineering expertise and established KEMA-type certification records. Monitor ECHA REACH amendment schedules as the critical signal for inflection in mineral oil substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Sourcing | Mitigates East Asian supply concentration risk for German and Polish manufacturers facing REACH compliance costs. |
| Digital Twin Platform Development | Enables Siemens and ABB to capture recurring predictive maintenance revenue from TenneT and Energinet contracts. |
| Resin-Insulated Technology Licensing | Accelerates dry-type substitution in Dutch urban substations constrained by F-Gas Regulation amendments. |
| Joint Venture with PSE | Secures preferential positioning for 400 kV Polish transmission corridor expansion against Asian competitors. |
| Green Certification Program | Documents lifecycle environmental impacts for CE conformity assessments under EU Green Deal financing mechanisms. |
Research Methodology
Initial hypotheses were tested against primary input from transmission planning officers, EPC contractor procurement leads, reactor manufacturing R&D directors, and aftermarket service managers, then refined through secondary validation against TSO investment plans, ECHA regulatory filings, EU network code harmonization documents, and customs trade data for grain-oriented electrical steel. Bottom-up unit economics triangulated with top-down market sizing across voltage level and installation type segments.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeled by product type, end user archetype, voltage tier, and installation environment. CAGRs were derived from installed base replacement cycles and offshore wind interconnection pipelines. Forecast inputs incorporated Ecodesign Directive efficiency threshold schedules and national grid code reactive power mandates from Germany, Poland, and Denmark.
Macroeconomic conditions sit as an overlay; deviation in EU Green Deal financing disbursement rates or carbon border adjustment mechanism implementation timelines would shift the trajectory of brownfield substation upgrade demand. Forecasts reflect documented assumptions regarding REACH restriction phase-in schedules and type-test certification queue durations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
HVDC Converters Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Power Inverter Market
Power Systems
Global Flexible Batteries Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
String Inverter Market
Power Systems
Integrated UPS Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Global Plasma Generators Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Global Gan Power Device Market
Power Systems
Telecom Battery Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Converter Modules Market
Power Systems
MCR Based Static VAR Compensator Market