
 Thermoelectric Coolers Market | 2026-2036
Thermoelectric Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoelectric Coolers Market Analysis
China is reshaping thermoelectric cooler supply dynamics through expanded domestic production of bismuth telluride substrates and module assembly lines. Ferrotec Corporation leverages its integrated semiconductor materials division to control substrate quality from raw refinement through finished module. Laird Thermal Systems anchors its position in medical and analytical instrument thermal management through specialized cold plate designs. II-VI Incorporated competes in high-reliability aerospace and defense applications with hermetically sealed multi-stage configurations.
Thermoelectric coolers are solid-state heat pumping devices that exploit the Peltier effect to transfer heat across semiconductor junctions, typically achieving temperature differentials of 40-70°C in single-stage configurations depending on ceramic substrate thermal conductivity and element geometry. Their primary purpose is precision temperature stabilization where compressor-based refrigeration fails due to size, vibration, or orientation constraints. Multi-stage modules command premium positioning in medical devices and photonics where deep cooling below ambient drives system performance, while single-stage units dominate electronics cooling for laser diodes and CMOS sensors where moderate ΔT suffices. Integrated systems deployment is gaining traction in automotive battery thermal management as OEMs seek compact distributed cooling architectures.
The EPA enforces energy efficiency standards that constrain power consumption in consumer-facing cooling applications, while the FDA regulates thermal stability in diagnostic and therapeutic devices where temperature drift compromises measurement accuracy. REACH in Europe restricts hazardous substances in ceramic substrates and solder materials, forcing reformulation of traditional module constructions. Stakeholders must monitor evolving semiconductor material regulations and solid-state cooling efficiency benchmarks as jurisdictions tighten environmental performance requirements for thermal management systems.
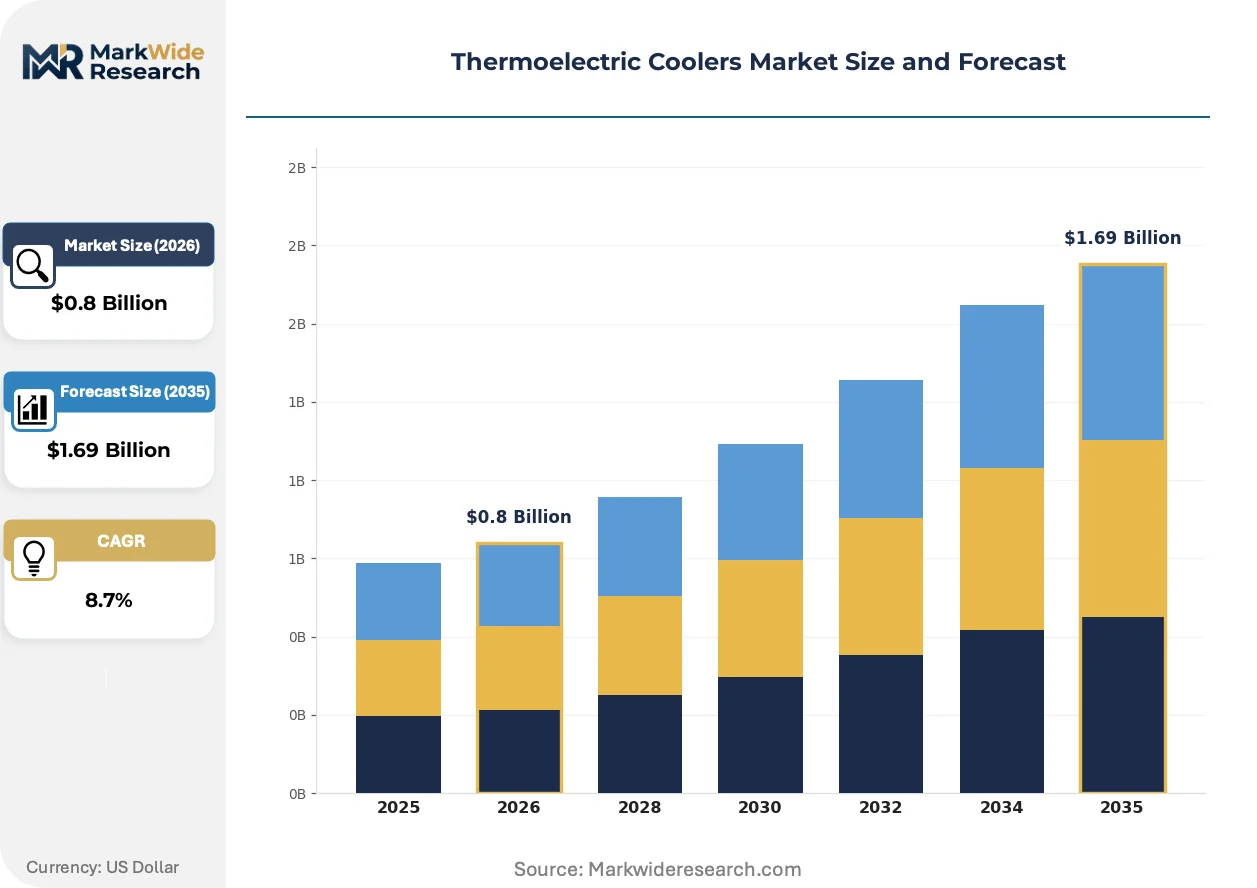
Market Dynamics
Semiconductor fabrication equipment procurement in China is compressing lead times and forcing substrate suppliers to localize bismuth telluride refining capacity, reshaping global sourcing patterns for thermoelectric module manufacturers.
Growth Catalysts
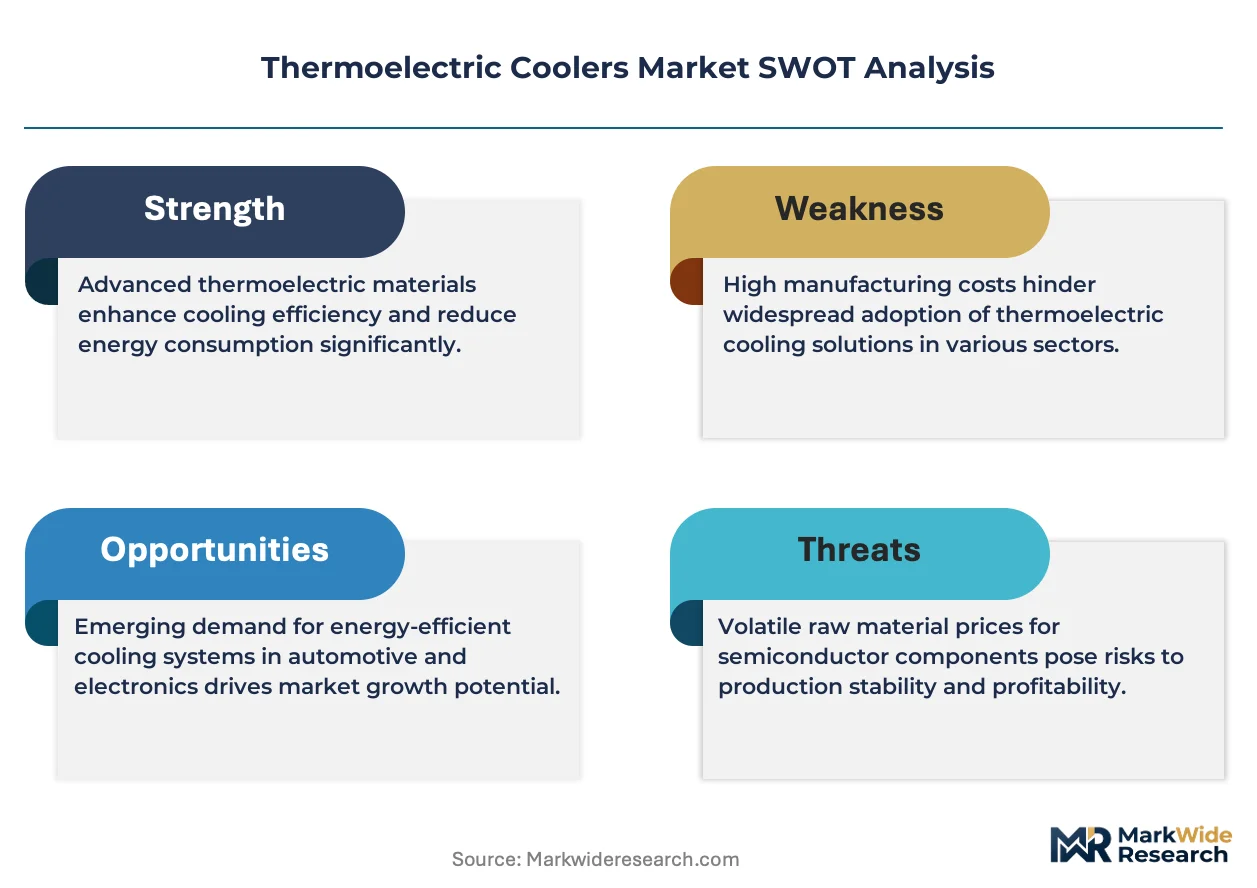
- Medical device thermal stability mandates:FDA diagnostic equipment regulations require precise temperature control in PCR systems and blood analyzers, expanding module integration into clinical instrumentation.
- Automotive battery distributed cooling architectures:OEMs in Germany and the United States are embedding thermoelectric modules into EV battery management systems for cell-level temperature equalization.
- Photonics deep cooling requirements:Infrared detector and laser diode manufacturers in Japan specify multi-stage configurations for sub-ambient operation in defense and telecommunications hardware.
Market Restraints
- Bismuth telluride supply concentration:Raw material refining capacity clusters in Chinese state-controlled enterprises, exposing non-Chinese module assemblers to input cost volatility and export licensing uncertainty.
- Coefficient of performance ceiling:Single-stage thermoelectric devices face fundamental thermodynamic limits around 5-10% efficiency, constraining adoption in high-heat-flux electronics cooling where vapor compression remains superior.
- REACH substance restrictions:ECHA regulations on lead-based solders and cadmium-containing ceramics force reformulation of traditional module interconnects, extending qualification timelines for European medical device suppliers.
Strategic Opportunities
- Indian pharmaceutical cold chain expansion:CDSCO temperature-controlled storage requirements for vaccines and biologics are creating procurement pull for portable thermoelectric cooling units in rural distribution networks.
- Silicon-germanium thermoelectric convergence:Thin-film deposition techniques adapted from semiconductor wafer processing are enabling high-temperature modules for automotive exhaust heat recovery applications.
- South Korean semiconductor equipment localization:METI-equivalent industrial policies are incentivizing domestic module assembly for lithography tool thermal management, bypassing Chinese substrate suppliers.
Industry Challenges
- Multi-physics simulation expertise scarcity:Module design requires simultaneous optimization of electrical, thermal, and mechanical properties, creating hiring bottlenecks for finite element analysis specialists in North American and European engineering teams.
- Medical device biocompatibility certification timelines:FDA 510(k) submissions for implantable or patient-contact cooling systems require 18-24 month validation cycles, compressing product development windows.
- Legacy compressor refrigeration retrofit complexity:Industrial equipment buyers face integration friction when replacing mechanical cooling with solid-state alternatives due to control system incompatibility and power supply redesign requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoelectric Coolers Market |
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Miniature, High Power Application: Medical Devices, Automotive Systems, Electronics Cooling, Industrial Refrigeration End User: Consumer Electronics, Healthcare, Automotive Manufacturers, Aerospace Deployment: Portable Units, Integrated Systems, Custom Solutions, Standard Modules |
| Companies Covered | Ferrotec Corporation, II-VI Incorporated, Laird Thermal Systems, TE Technology, Applied Thermoelectric Solutions LLC, Adcol Electronics, Crystal Ltd, Kryotherm, TEC Microsystems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoelectric Coolers Market Emerging Trajectories
Material science advances and regulatory pressure on refrigerant-based cooling are accelerating solid-state thermal management adoption across precision instrumentation and mobility applications.
Thin-film thermoelectric generators are migrating from laboratory prototypes to commercial deployment in wearable medical devices and IoT sensors. Japanese electronics manufacturers are integrating these micro-scale modules into continuous glucose monitors and skin-patch drug delivery systems. The technology is migrating from research-phase demonstration to volume production, compressing pricing for sub-watt cooling applications and displacing battery-powered micro-fans in portable diagnostics.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of ceramic substrate binders and solder alloys in European-sourced modules. Industrial consequences include 12-18 month material requalification cycles and supplier consolidation around compliant chemistry providers. Medical device OEMs in Germany and Switzerland are most affected, responding by dual-sourcing from Asian module houses with pre-certified green material streams.
Buyer consolidation among semiconductor capital equipment manufacturers is compressing vendor qualification cycles and unbundling after-sales service contracts. Applied Materials and ASML procurement teams now specify module-level mean-time-between-failure data and demand direct technical support bypassing distributor channels. This pattern is most visible in Dutch and German lithography tool supply chains, where module suppliers must embed field service engineers at customer fabs.
Thermoelectric Coolers Market Segmentation
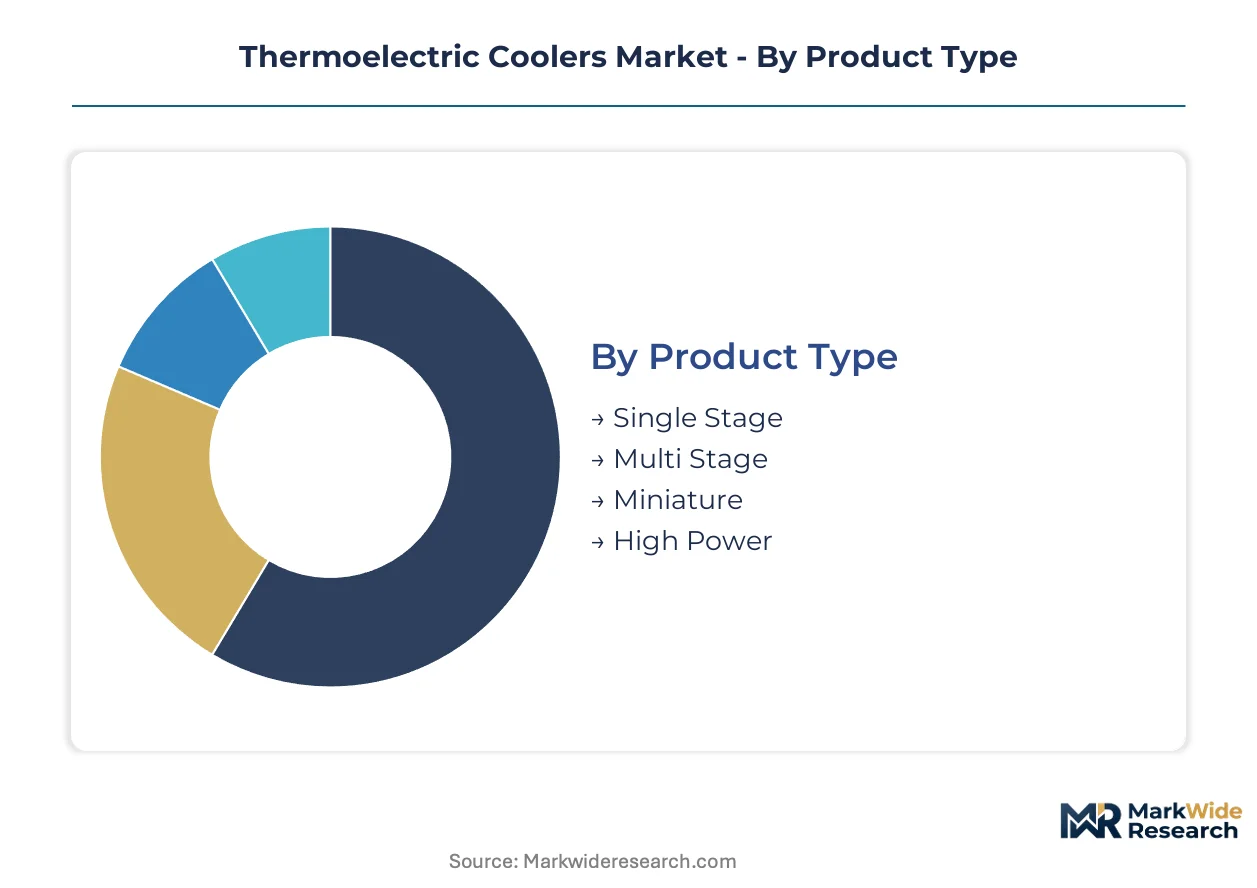
Thermoelectric cooler segmentation reveals distinct performance-cost tradeoffs across thermal management architectures. Product configuration determines achievable temperature differentials, while application verticals impose divergent reliability and precision requirements.
Product Type:
Mature single-stage designs dominate unit economics, yet emerging multi-stage architectures command premium positioning in precision instrumentation.
- Multi Stage:Stacked semiconductor junctions achieve temperature differentials exceeding 100°C through cascaded Peltier elements. Medical device manufacturers in Germany and Japan specify these configurations for PCR thermal cyclers and infrared detector cooling where sub-ambient stability determines diagnostic accuracy.
- Single Stage:Basic bismuth telluride couples on alumina substrates deliver 40-70°C ΔT for moderate cooling loads. Electronics manufacturers in Shenzhen and Seoul integrate these modules into laser diode packages and CMOS sensor assemblies where cost sensitivity outweighs deep cooling requirements.
- Miniature:Sub-watt thin-film devices target wearable medical diagnostics and IoT sensor nodes.
- High Power:Large-area modules with enhanced ceramic substrates address industrial heat pumping above 100W thermal load.
Single Stage retains volume leadership; Multi Stage holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity electronics cooling from regulated medical and automotive thermal management.
- Medical Devices:FDA-mandated temperature stability in diagnostic equipment drives module integration into blood analyzers, DNA sequencers, and imaging systems. Swiss and German OEMs specify hermetic sealing and biocompatible materials for patient-contact applications.
- Automotive Systems:EV battery cell-level temperature equalization demands distributed solid-state cooling architectures. German and US automakers embed modules into battery management systems where vibration resistance and orientation independence outweigh efficiency penalties.
- Electronics Cooling:Telecom infrastructure and data center applications favor thermoelectric modules for precise laser diode temperature control.
- Industrial Refrigeration:Niche deployments in semiconductor fabrication equipment and analytical instruments require custom thermal solutions.
Electronics Cooling captures the highest unit volumes; Automotive Systems demonstrates the most aggressive capacity expansion.
End User:
Customer type determines procurement sophistication, with healthcare and aerospace buyers imposing qualification regimes that exclude commodity suppliers.
- Healthcare:Hospital systems and diagnostic laboratories demand ISO 13485-certified modules with documented mean-time-between-failure data. European notified body oversight extends supplier qualification cycles to 18-24 months.
- Aerospace:Defense contractors and satellite manufacturers specify MIL-STD-883 tested configurations for extreme environment operation. Hermetic sealing and radiation-hardened materials distinguish this segment.
- Consumer Electronics:Price-sensitive buyers prioritize unit cost over thermal performance specifications.
- Automotive Manufacturers:Tier-1 suppliers manage module procurement for integrated thermal management systems.
Consumer Electronics maintains shipment dominance; Healthcare commands the most favorable margin structure.
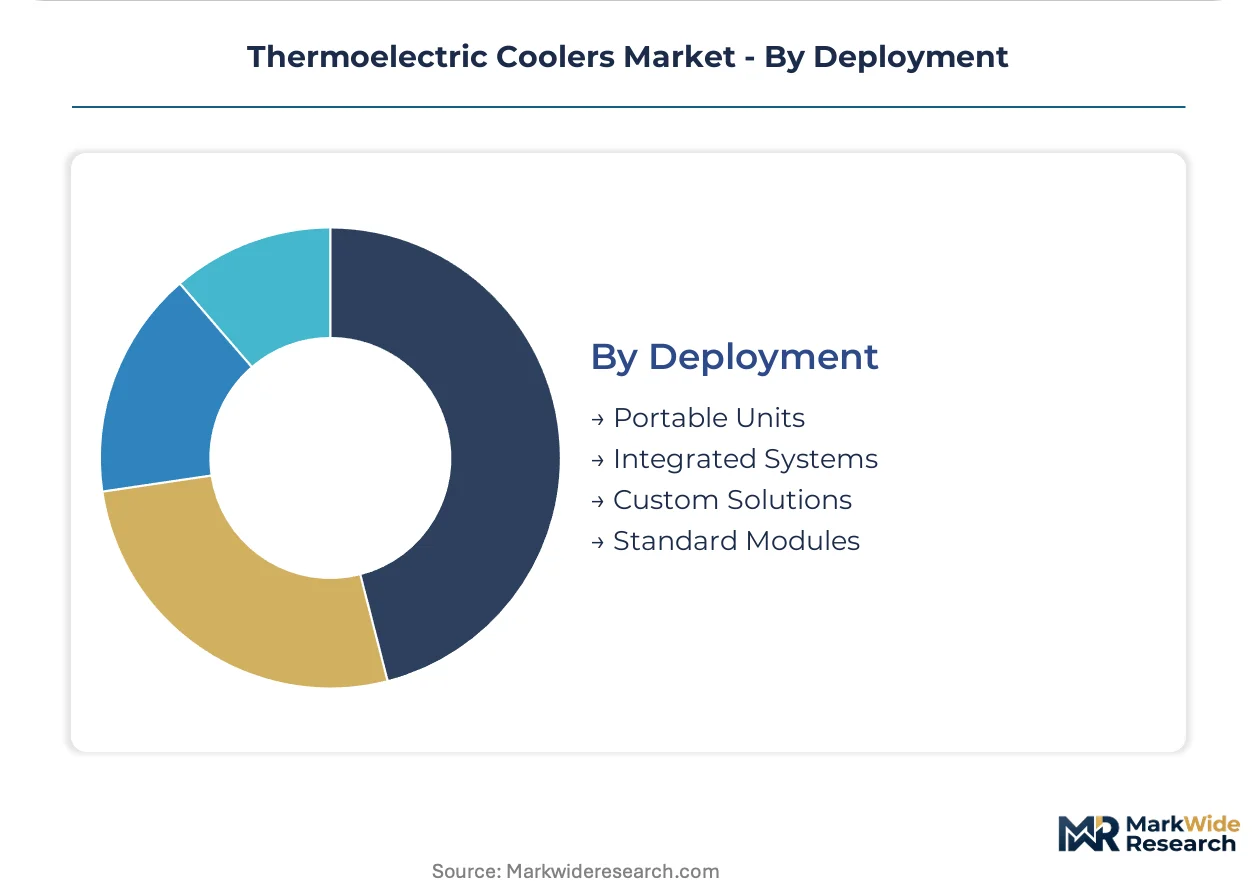
Deployment:
Supply concentration favors integrated system architectures as semiconductor equipment manufacturers consolidate vendor bases.
- Integrated Systems:Module-cold plate-controller assemblies reduce customer engineering burden. ASML and Applied Materials procurement teams specify complete thermal subsystems with embedded field service support.
- Custom Solutions:Application-specific module geometries and electrical configurations address non-standard thermal loads. Medical device OEMs in Switzerland and Japan drive demand for patient-matched cooling architectures.
- Standard Modules:Off-the-shelf rectangular configurations serve high-volume electronics cooling applications.
- Portable Units:Battery-powered thermoelectric coolers target pharmaceutical cold chain and field diagnostics.
Standard Modules sustain the broadest addressable market; Integrated Systems delivers the fastest value-per-unit growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bismuth telluride refining capacity clusters in Chinese state-controlled enterprises, forcing module assemblers elsewhere to localize substrate production or absorb input cost volatility. This supply-side concentration is reshaping procurement patterns across precision thermal management applications.
China
Electronics manufacturing clusters in Shenzhen and Dongguan drive module procurement for semiconductor fabrication equipment, while domestic bismuth telluride substrate production expands under MIIT industrial policy guidance. SAMR enforces GB standards on energy efficiency in consumer-facing cooling products. Yangtze River Delta fabrication facilities are scaling multi-stage module assembly lines for medical device export markets.
United States
Medical device manufacturers in Massachusetts and Minnesota integrate precision thermal management modules into PCR systems and blood analyzers to meet FDA diagnostic equipment regulations. EPA energy efficiency standards constrain power consumption in consumer cooling applications. Greater Boston's analytical instrumentation cluster demands hermetically sealed configurations for laboratory-grade thermal stability.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg embed thermoelectric modules into EV battery management systems for cell-level temperature equalization. ECHA REACH restrictions on lead-based solders force reformulation of traditional module interconnects. Stuttgart's automotive engineering ecosystem is qualifying distributed solid-state cooling architectures for next-generation electric platforms.
Japan
Infrared detector and laser diode manufacturers in Tokyo and Osaka specify multi-stage configurations for sub-ambient operation in defense and telecommunications hardware. METI industrial policies incentivize domestic module assembly for lithography tool thermal management. Kyushu's semiconductor materials sector is developing thin-film deposition techniques for high-temperature thermoelectric applications.
Switzerland
Medical device OEMs in Basel and Zurich demand ISO 13485-certified modules with documented mean-time-between-failure data for diagnostic instrumentation. Swissmedic oversees biocompatibility requirements for patient-contact cooling systems. The country's precision engineering cluster is driving procurement of custom thermal solutions for implantable device applications.
Thermoelectric Coolers Market Vendor Landscape
Vertically integrated materials specialists and modular thermal solution providers split the market along substrate control versus application engineering lines. The vendor base concentrates around three strategic archetypes: captive bismuth telluride refiners, medical-grade cold plate designers, and aerospace hermetic sealing specialists. Competitive dynamics center on backward integration into raw material supply and forward integration into subsystem assembly with embedded field service support.
Within the materials-integrated tier, Ferrotec Corporation occupies a position exemplifying substrate-to-module vertical control, while II-VI Incorporated anchors the high-reliability aerospace and defense segment. Laird Thermal Systems represents the medical and analytical instrument specialization archetype, with TEC Microsystems GmbH sitting within the European precision engineering cluster. These named entities illustrate how geographic proximity to end-use clusters—Japanese electronics, German automotive, Swiss medical devices—shapes competitive positioning more than scale economies alone.
| Leading Market Players |
|---|
| Ferrotec Corporation |
| II-VI Incorporated |
| Laird Thermal Systems |
| TE Technology |
| Applied Thermoelectric Solutions LLC |
| Adcol Electronics |
| Crystal Ltd |
| Kryotherm |
| TEC Microsystems GmbH |
| Others |
Supply Flow & Price Mechanics
Chinese state-controlled bismuth telluride export licensing uncertainty determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic reconfiguration of substrate sourcing networks. Module assemblers outside China absorb input cost volatility through dual-sourcing premiums or captive refining investments, compressing margins in the standard tier while insulating premium medical-grade suppliers.
Pricing Analysis
REACH Annex XVII restrictions on lead-based solders and cadmium-containing ceramics dictate the pricing tier structure across European medical device procurement. Price differentiation separates ISO 13485-certified hermetic modules with documented mean-time-between-failure data from commodity single-stage units, with certification tier and after-sales service bundling as primary drivers. Cost compression in the economy electronics tier intensifies because Shenzhen-based laser diode manufacturers negotiate volume contracts against multiple module houses. Healthcare buyers in Switzerland and Germany demonstrate the lowest price sensitivity due to 18-24 month qualification cycles that lock in supplier relationships.
Supply Chain Analysis
Extended payment terms from semiconductor capital equipment manufacturers to module suppliers are restructuring working capital requirements across the value chain. Raw material refining capacity clusters in China, with secondary substrate production scaling in Japan and South Korea under METI-equivalent industrial policies. Bismuth telluride ingots, alumina ceramic substrates, and lead-free solder alloys constitute critical input dependencies. Single-source vulnerability to Chinese export licensing exposes non-captive assemblers to supply interruption. Distribution runs through direct technical support contracts with ASML and Applied Materials procurement teams, bypassing traditional distributor channels for lithography tool thermal management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among semiconductor capital equipment manufacturers and automotive OEMs is shifting procurement power toward direct subsystem specifications with embedded field service requirements. Applied Materials and ASML now unbundle after-sales contracts and demand module-level reliability data, fragmenting vendor bases around integrated thermal solution capabilities.
For Market Incumbents: Pre-empt margin erosion in standard single-stage modules by securing captive bismuth telluride refining capacity or joint-venture substrate production in South Korea under METI incentive programs. Defend medical-grade positioning through ISO 13485 certification maintenance and hermetic sealing technology investment before European notified body oversight extends qualification timelines. Address emerging thin-film thermoelectric convergence in Japanese wearable diagnostics through R&D partnerships with Kyushu semiconductor materials specialists. For New Entrants and Emerging Players: Rural pharmaceutical cold chain distribution networks in India represent the most penetrable entry point, with CDSCO temperature-controlled storage requirements creating procurement pull for portable thermoelectric cooling units underserved by established medical-grade suppliers. Silicon-germanium thermoelectric modules for automotive exhaust heat recovery applications offer second white-space targeting, leveraging thin-film deposition techniques adapted from semiconductor wafer processing. Go-to-market execution should prioritize field validation partnerships with Indian vaccine logistics operators and German Tier 1 automotive thermal management suppliers. For Investors and Strategic Acquirers: The market sits at a materials-integration consolidation phase that favors vertically controlled substrate-to-module specialists over pure-play assemblers. Long-term viability across the analysis window hinges on backward integration into bismuth telluride refining or forward integration into subsystem assembly with embedded field service. Acquisition target archetypes include European precision engineering clusters with ISO 13485 medical certification and Japanese thin-film deposition capabilities. Monitor South Korean semiconductor equipment localization policy implementation as inflection indicator for substrate supply reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bismuth Telluride Refining | Captive substrate production insulates margin structure from Chinese export licensing volatility. |
| Hermetic Sealing Technology Investment | FDA 510(k) pathway acceleration for implantable cooling systems requires validated sealing processes. |
| Thin-Film Deposition Capability Buildout | Silicon-germanium module development for automotive exhaust heat recovery applications leverages semiconductor wafer processing. |
| Embedded Field Service Engineer Deployment | ASML and Applied Materials procurement specifications demand direct technical support bypassing distributor channels. |
| ISO 13485 Certification Maintenance | Swissmedic and European notified body oversight extends medical device supplier qualification cycles to 18-24 months. |
Methodological Framework
The analysis maps single-stage, multi-stage, miniature, and high-power module configurations, each validated through procurement managers at semiconductor capital equipment manufacturers, thermal management engineers at automotive OEMs, regulatory affairs specialists at medical device companies, and materials scientists at bismuth telluride refiners. Primary interview intelligence combined with secondary validation from EPA energy efficiency filings, FDA 510(k) submission databases, ECHA REACH restriction updates, and METI industrial policy disclosures. Bottom-up unit economics and top-down market sizing triangulation anchored volume estimates.
Assumptions held fixed include regulatory enforcement timelines for REACH Annex XVII restrictions and MIIT industrial policy continuity for Chinese substrate production expansion. Segmentation dimensions modeled encompass product type, application vertical, end-user procurement sophistication, and deployment architecture across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated semiconductor fabrication equipment procurement cycles and EV battery thermal management system adoption curves.
Practitioners should monitor Chinese export licensing policy shifts, REACH substance restriction expansion, and thin-film thermoelectric commercialization milestones for early signals of supply reconfiguration or technology substitution. Forecasts reflect documented assumptions regarding bismuth telluride price stability and medical device certification timeline continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Shunt Capacitor Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Solid State Power Controller Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Synchronous Condenser Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Global Data Center Transformer Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Power Semiconductor Market
Power Systems
Semiconductor Rectifier Market
Power Systems
Harmonic Generators Market
Power Systems
Wireless Battery Monitoring System Market