
 Temperature Controlled Container Market | 2026-2036
Temperature Controlled Container Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Controlled Container Market Outlook
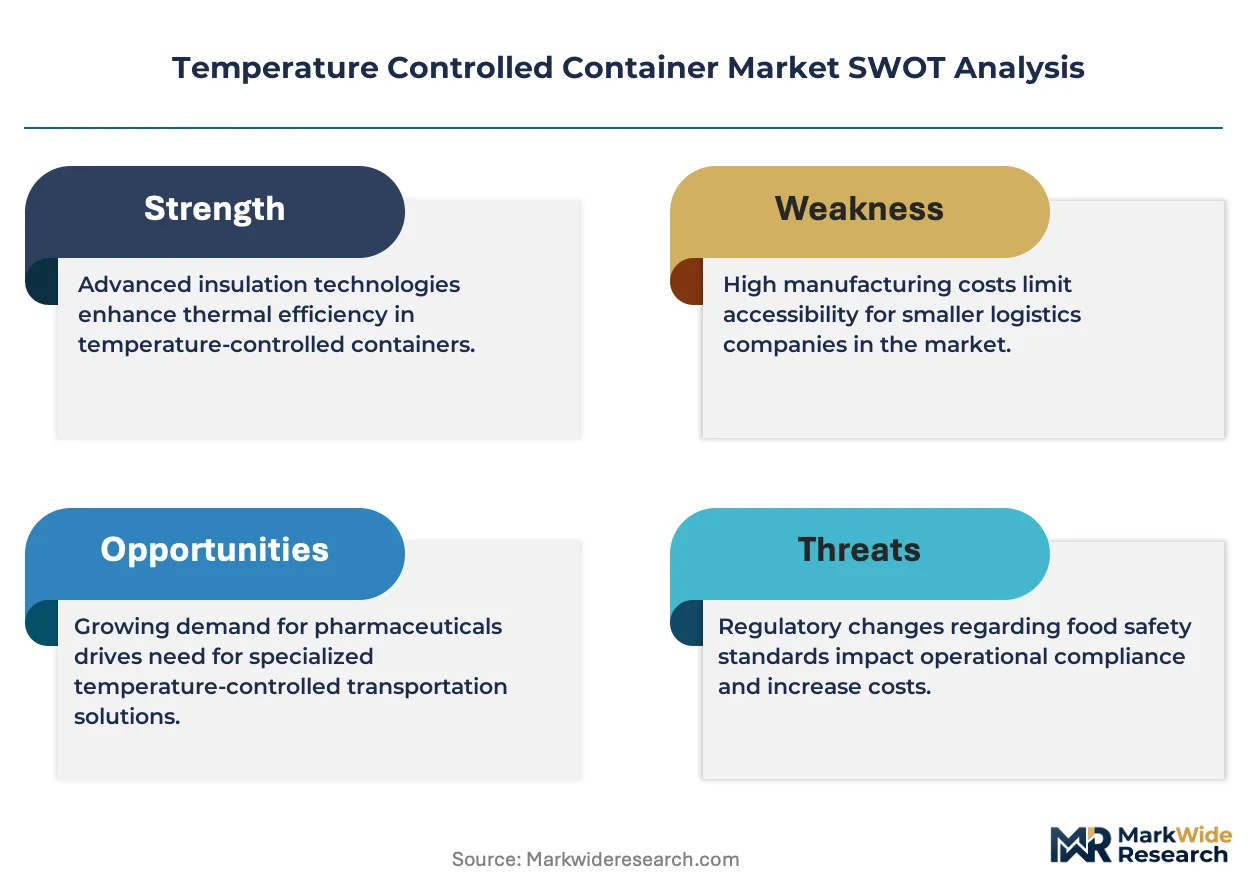
Good Distribution Practice certification is collapsing the vendor landscape as smaller container makers fail validation audits. Pelican BioThermal leverages in-house testing laboratories to sustain compliance across European and North American pharma lanes. Va-Q-Tec AG anchors its position through vacuum-insulated panel technology leadership, while Envirotainer competes via dedicated air-fleet partnerships with major cargo carriers.
Temperature controlled containers are engineered enclosures maintaining specified thermal ranges through insulated walls, active compressor units, or phase change material packs, typically sustaining 2-8°C, -20°C, or cryogenic -150°C conditions for biological cargo integrity. Cryogenic Containers command premium margins due to ultra-low temperature engineering complexity and limited qualified suppliers. Passive Cooling systems lead volume across last-mile pharmaceutical distribution, while Hybrid Systems are gaining fastest in intercontinental lanes where modal shifts demand adaptive thermal protection.
FDA cold-chain validation rules, EU Good Distribution Practice, and IATA CEIV Pharma certification collectively determine market access and procurement eligibility for container vendors. These frameworks mandate continuous temperature logging, thermal packaging qualification, and documented chain-of-custody protocols that directly shape R&D priorities and manufacturing investments. Stakeholders must monitor evolving pharmacopeial standards for cell and gene therapies that will redefine container performance thresholds.
Market Dynamics
EU Good Distribution Practice certification requirements are collapsing the vendor landscape as smaller container makers fail validation audits, concentrating procurement eligibility among laboratories with in-house thermal testing capabilities.
Growth Catalysts
- Biologics Cold-Chain Expansion:mRNA vaccine manufacturing clusters in Germany and Belgium are demanding validated 2-8°C and cryogenic -150°C shipping infrastructure for cell and gene therapies.
- FDA Cold-Chain Validation Rules:Continuous temperature logging mandates for biological cargo integrity are disqualifying non-compliant container vendors from US pharmaceutical logistics procurement.
- Vacuum-Insulated Panel Technology:Phase change material packs with extended thermal duration are displacing compressor-based active cooling in last-mile distribution lanes.
Market Restraints
- Qualified Supplier Concentration:Cryogenic -150°C engineering complexity limits certified container production to a handful of European and North American manufacturers.
- Input Cost Volatility:Specialized polyurethane foam and VIP core materials face price pressure from aerospace and construction sector demand competition.
- IATA CEIV Pharma Certification Friction:Documented chain-of-custody protocol requirements extend sales cycles by 12-18 months for new market entrants.
Strategic Opportunities
- Indian Pharmaceutical Export Hubs:CDSCO cold-chain guidelines for biosimilar exports are creating first-mover advantages for validated container leasing networks.
- Hybrid System Modal Adaptation:Intercontinental lanes with air-sea freight shifts favor containers combining passive insulation with active compressor backup.
- Cell Therapy Distribution Innovation:Ultra-low temperature requirements for CAR-T logistics are opening premium service tiers beyond traditional vaccine cold-chain specifications.
Industry Challenges
- Thermal Engineering Talent Scarcity:PhD-level expertise in cryogenic heat transfer and phase change material formulation concentrates in aerospace and medical device sectors.
- Validation Timeline Compression:Pharmacopeial standard updates for cell and gene therapies outpace container qualification protocols, forcing parallel R&D and regulatory submission tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Controlled Container Market |
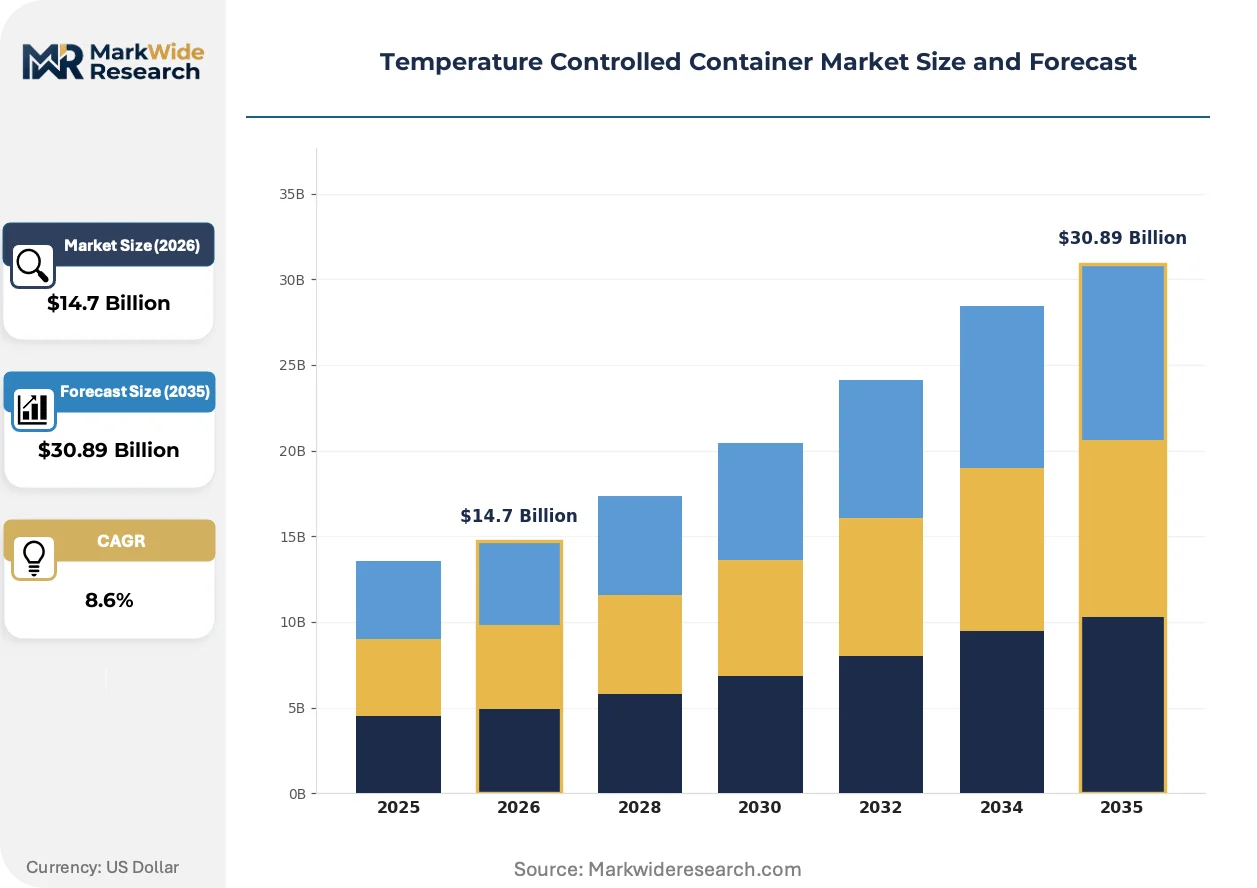
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Refrigerated Trucks, Temperature Controlled Pallets, Cryogenic Containers Industry Vertical: Pharmaceuticals, Food & Beverage, Chemicals, Biotechnology Technology: Active Cooling, Passive Cooling, Phase Change Materials, Hybrid Systems Delivery Mode: Air Freight, Sea Freight, Land Transportation, Express Shipping |
| Companies Covered | Cold Chain Technologies, Sonoco Products Company, Va-Q-Tec AG, Pelican BioThermal, Envirotainer, Softbox Systems, DGP Intelsius, Cryopak Industries, SOFRIGAM GROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Controlled Container Market Strategic Shifts
Container architecture is fragmenting into modular subsystems as pharmaceutical logistics operators demand swapable thermal cores compatible with multiple transport modes.
Phase change material packs with programmable melting points are decomposing the traditional active-versus-passive cooling dichotomy. Biologics shippers in the Netherlands and Switzerland are adopting hybrid cores that switch thermal mechanisms based on lane duration. This flexibility is decomposing fleet specialization requirements and enabling asset pooling across vaccine and cell therapy applications.
REACH regulation amendments on fluorinated greenhouse gases are restricting hydrofluorocarbon-based refrigerants in active compressor units. German container manufacturers are retrofitting air-cycle cooling systems to maintain EU market access. Cryogenic container segments face the steepest compliance redesign costs due to ultra-low temperature engineering constraints.
Air-cargo carriers are unbundling container leasing from freight forwarding contracts. Direct relationships between pharmaceutical manufacturers and specialized cold-chain asset providers are displacing general logistics intermediaries in high-value biologics lanes. This disintermediation is most visible in Belgium and Singapore, where vaccine export hubs negotiate dedicated container allocations bypassing traditional freight consolidators.
Temperature Controlled Container Market Segmentation
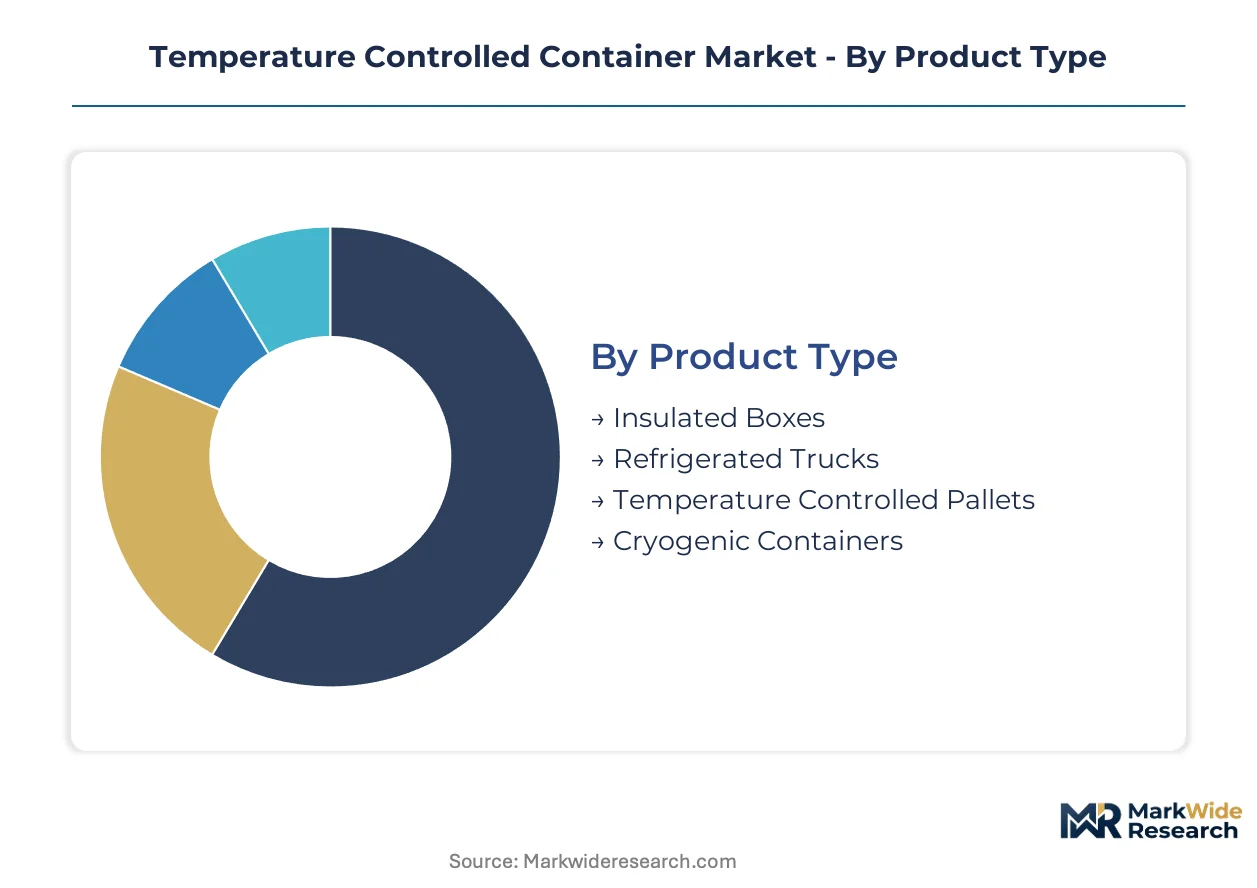
Container selection in temperature-controlled logistics hinges on cargo value, lane duration, and regulatory stringency. Pharmaceutical shippers prioritize validated thermal performance over capital cost, while food distributors optimize for unit economics across shorter distribution cycles.
Product Type:
Domestic pharmaceutical distribution favors reusable insulated enclosures, while cryogenic systems concentrate in export corridors serving cell therapy manufacturing clusters.
- Cryogenic Containers:Vacuum-insulated vessels sustain -150°C conditions through liquid nitrogen or mechanical refrigeration for CAR-T cell preservation. Demand clusters at Belgian and German export hubs shipping to North American treatment centers under FDA cold-chain validation protocols.
- Refrigerated Trucks:Compressor-based mobile units with multi-zone temperature control serve high-volume pharmaceutical distribution between manufacturing plants and regional depots. Fleet operators in the Netherlands and Switzerland are retrofitting air-cycle cooling to comply with EU F-Gas Regulation amendments.
- Insulated Boxes:Polyurethane-foam enclosures with gel pack inserts dominate last-mile vaccine delivery.
- Temperature Controlled Pallets:Bulk shipment platforms with integrated thermal mass protect palletized biologics during air freight.
Cryogenic Containers hold the largest share; momentum sits with Insulated Boxes as passive cooling gains ground in cost-sensitive lanes.
Industry Vertical:
Cost tiers separate premium-validated pharmaceutical applications from commodity food logistics, with biotechnology commanding the highest performance premiums.
- Pharmaceuticals:GDP-validated containers with continuous temperature logging serve vaccine and insulin distribution under EU and FDA mandates. German manufacturers require IATA CEIV Pharma certification for export eligibility to North American markets.
- Biotechnology:Cell and gene therapy producers demand cryogenic infrastructure with documented chain-of-custody protocols. Singapore and Belgian manufacturing clusters are driving fastest adoption of hybrid thermal systems for intercontinental clinical trial material shipments.
- Food & Beverage:Modified-atmosphere containers preserve perishables through controlled humidity and gas composition.
- Chemicals:Temperature-sensitive reagents and active pharmaceutical ingredients require hazardous-material-rated thermal packaging.
Pharmaceuticals holds the largest share; biotechnology is expanding most quickly as cell therapy pipelines mature.
Technology:
Volume concentrates in passive systems for short-haul distribution, while hybrid architectures capture modal-shift applications.
- Hybrid Systems:Configurations combining vacuum insulation with active compressor backup adapt to air-sea freight transitions without cargo repackaging. Logistics operators in Belgium and Singapore deploy these for vaccine export lanes with uncertain routing.
- Phase Change Materials:Programmable melting-point packs switch thermal mechanisms based on ambient exposure duration. Swiss and Dutch biologics shippers are adopting PCM cores that bridge the gap between passive duration limits and active system cost.
- Active Cooling:Compressor-based units dominate long-haul pharmaceutical distribution.
- Passive Cooling:Insulated enclosures with thermal mass sustain temperature without power input.
Passive Cooling holds the largest share; momentum sits with Hybrid Systems as modal flexibility becomes critical.
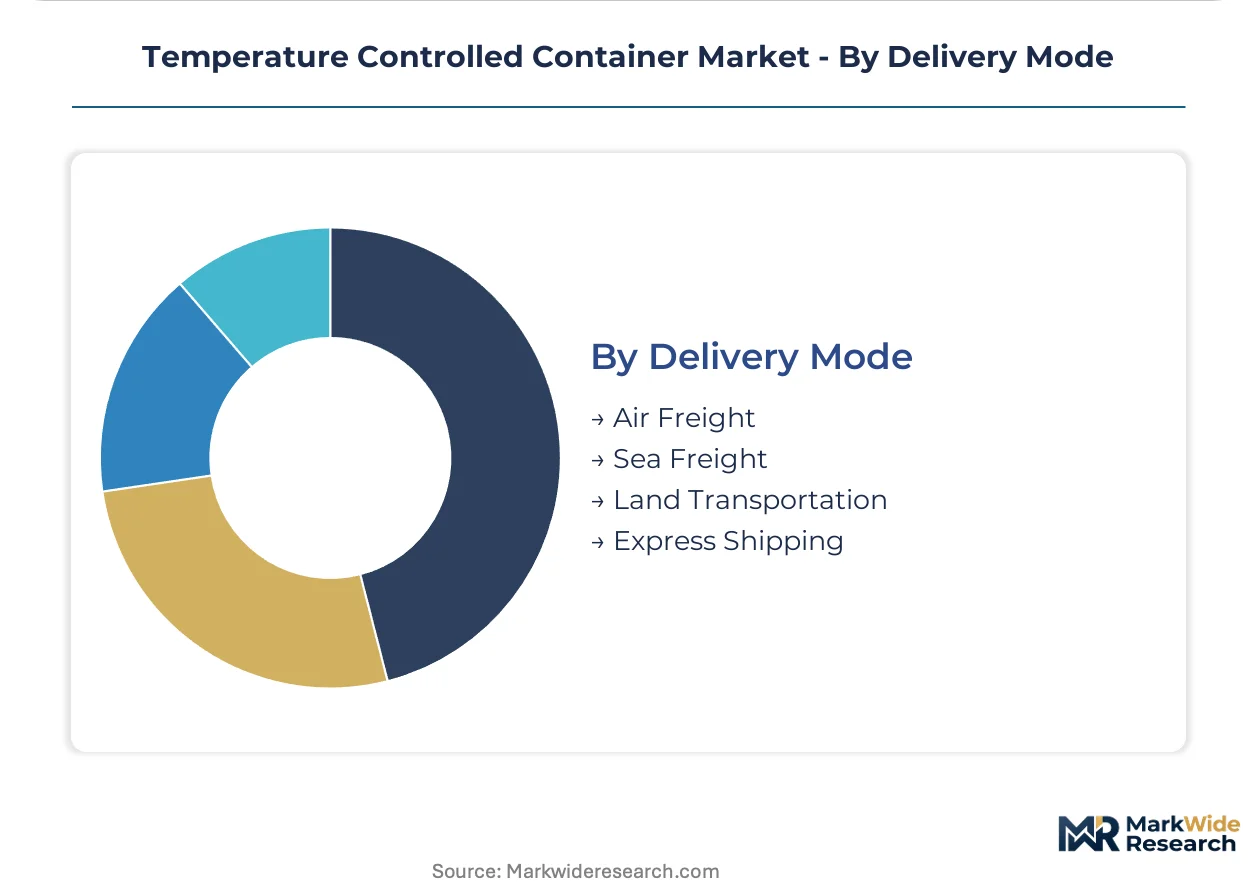
Delivery Mode:
Air freight commands premium container specifications, while sea freight expansion drives demand for extended-duration passive systems.
- Air Freight:Unit-load devices with rapid thermal recovery protect high-value biologics through tarmac exposure and altitude pressure changes. Direct leasing relationships between pharmaceutical manufacturers and specialized cold-chain asset providers are displacing freight forwarders in Belgian and Singapore vaccine export hubs.
- Sea Freight:Refrigerated containers with extended passive duration serve biosimilar exports from Indian manufacturing clusters under CDSCO cold-chain guidelines. Ocean lanes favor phase change material systems over compressor-based units due to power reliability constraints.
- Land Transportation:Truck-mounted and pallet-based systems serve regional distribution networks.
- Express Shipping:Time-definite services with dedicated container allocation support clinical trial logistics.
Air Freight holds the largest share; sea freight is gaining share fastest as pharmaceutical ocean lanes professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Good Distribution Practice certification and FDA cold-chain validation rules are concentrating procurement eligibility among validated container vendors across major pharmaceutical export corridors. National regulators in Germany, Belgium, Singapore, India, and the United States are tightening thermal performance standards for biologics logistics.
Germany
mRNA vaccine manufacturing clusters in Marburg and Mainz are demanding cryogenic -150°C shipping infrastructure for cell and gene therapy exports. The country's national pharmaceutical regulator enforces EU GDP guidelines that disqualify non-validated container vendors from pharmaceutical logistics procurement. Frankfurt and Munich anchor dedicated cold-chain asset networks serving North American clinical trial material shipments.
Belgium
Antwerp and Brussels host vaccine export hubs negotiating direct container leasing relationships with pharmaceutical manufacturers. REACH regulation amendments on fluorinated greenhouse gases are restricting hydrofluorocarbon-based refrigerants in active compressor units. Belgian logistics operators are deploying hybrid thermal systems for intercontinental lanes with uncertain air-sea freight routing.
Singapore
Cell therapy manufacturing clusters are driving fastest adoption of hybrid thermal systems for clinical trial material shipments to North American treatment centers. The country's national pharmaceutical regulator aligns with IATA CEIV Pharma certification requirements for export eligibility. Changi cargo infrastructure supports dedicated container allocations bypassing traditional freight consolidators.
India
CDSCO cold-chain guidelines for biosimilar exports are creating first-mover advantages for validated container leasing networks. The national pharmaceutical regulator mandates continuous temperature logging for biological cargo integrity. Mumbai and Hyderabad pharmaceutical manufacturing clusters require advanced temperature-controlled shipping infrastructure for export compliance.
United States
FDA cold-chain validation rules mandate documented chain-of-custody protocols that extend sales cycles for new market entrants. The national pharmaceutical regulator requires thermal packaging qualification for vaccine and insulin distribution eligibility. Boston and San Francisco biotech corridors anchor demand for cryogenic infrastructure serving CAR-T cell preservation logistics.
Temperature Controlled Container Market Competitive Environment
Player mix skews toward specialized cold-chain asset providers with in-house thermal testing capabilities. The vendor landscape concentrates around European and North American manufacturers capable of sustaining GDP and FDA validation compliance across pharmaceutical lanes. Three archetypes dominate: vacuum-insulation technology specialists, dedicated air-fleet partners, and modular subsystem integrators. Competitive dynamics center on strategic partnerships with cargo carriers and certification timeline acceleration through captive laboratory infrastructure.
Within the European specialist tier, Va-Q-Tec AG and Envirotainer occupy positions anchored by distinct technical approaches to thermal protection. Pelican BioThermal represents the North American validation-heavy archetype, sustaining compliance through integrated testing infrastructure. Cold Chain Technologies and Sonoco Products Company exemplify diversified packaging conglomerates with cold-chain divisions. These named entities serve as reference points for understanding how regulatory concentration rewards players with captive compliance capabilities rather than modular outsourcing strategies.
| Leading Market Players |
|---|
| Cold Chain Technologies |
| Sonoco Products Company |
| Va-Q-Tec AG |
| Pelican BioThermal |
| Envirotainer |
| Softbox Systems |
| DGP Intelsius |
| Cryopak Industries |
| SOFRIGAM GROUP |
| Others |
Value Chain & Pricing Dynamics
Sixteen-to-twenty-four month container qualification timelines concentrate procurement leverage among GDP-validated vendors, compressing price elasticity for pharmaceutical buyers while amplifying margin capture for certified manufacturers. This lead-time band shapes tiered pricing structures where thermal performance certification outweighs unit cost in buyer calculus.
Pricing Analysis
Certification level (EU GDP/FDA-grade/IATA CEIV) creates the primary spread between container tiers, with validated cryogenic systems commanding premium positioning against commodity passive units. Three-tier pricing structure across premium-validated, standard-compliant, and economy-unvalidated levels segments buyer archetypes by cargo value and regulatory exposure. Cost compression in economy passive cooling is intensifying because REACH F-Gas amendments are disqualifying refrigerant-dependent active units from EU lanes. Biotechnology shippers exhibit lowest price sensitivity due to CAR-T cargo value concentration, while generic vaccine distributors drive hardest unit-economics negotiations.
Supply Chain Analysis
Strategic stockpiling of vacuum-insulated panel cores and specialized polyurethane foam dominates inventory strategy as aerospace and construction sector demand competition strains input availability. Manufacturing concentrates in Germany, Belgium, and the United States where thermal engineering talent clusters and regulatory validation infrastructure anchors production. Supply chains draw from petrochemical feedstocks for foam insulation, rare-earth elements for PCM formulations, and precision-machined components for compressor assemblies. Single-source vulnerability in cryogenic vessel fabrication threatens container availability for cell therapy logistics. Distribution runs through dedicated cold-chain asset networks that bypass traditional freight forwarders in high-value biologics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container architecture fragmentation across modular thermal subsystems is proliferating niche specialization opportunities as pharmaceutical logistics operators demand swapable cores compatible with multiple transport modes.
For Market Incumbents: Shield validated market position by accelerating in-house thermal testing laboratory capacity additions in Germany and Belgium to compress GDP certification timelines for cell therapy container variants. Deepen backward integration into vacuum-insulated panel core production to secure input supply against aerospace sector demand competition. Counter emerging modular subsystem integrators through exclusive air-fleet partnership extensions with major cargo carriers operating Frankfurt and Changi hubs. For New Entrants and Emerging Players: Differentiate on hybrid thermal system architecture for Indian pharmaceutical export corridors where CDSCO cold-chain guidelines are creating first-mover windows for validated container leasing networks. Target biosimilar distribution lanes from Mumbai and Hyderabad manufacturing clusters with PCM-based passive systems that bridge cost and performance gaps. Pursue direct relationships with pharmaceutical manufacturers in Singapore cell therapy clusters to bypass entrenched freight forwarder intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming cold-chain divisions lacking captive thermal testing infrastructure. Long-term viability hinges on regulatory compliance capability concentration rather than manufacturing scale alone. Monitor IATA CEIV Pharma certification backlog durations as inflection indicator for vendor landscape consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CEIV Pharma Certification Acceleration | Shortens sales cycles for new container variants entering Belgian and Singapore vaccine export lanes. |
| Hybrid Thermal System Development | Captures modal-shift demand from air-sea freight transitions in intercontinental biologics corridors. |
| Backward Integration into VIP Core Production | Secures supply of vacuum-insulated panel materials against aerospace and construction sector competition. |
| Direct Manufacturer Leasing Relationships | Displaces freight forwarder intermediaries in high-value CAR-T and mRNA vaccine distribution networks. |
| PCM Formulation R&D Partnership | Enables programmable melting-point packs that bridge passive duration limits and active system cost barriers. |
Study Parameters
Initial hypotheses were tested against primary input from cold-chain logistics directors, pharmaceutical quality assurance leads, thermal packaging engineers, and cargo carrier procurement managers and refined through secondary validation. Primary fieldwork combined structured interviews with FDA and EU GDP compliance officers at container manufacturing facilities with observational research at Frankfurt and Changi pharmaceutical cargo terminals. Secondary sources encompassed IATA CEIV Pharma certification databases, EMA Good Distribution Practice guidance documents, customs trade data for temperature-controlled container movements, and SEC filings from diversified packaging conglomerates with cold-chain divisions. Bottom-up container demand estimates by pharmaceutical vertical were triangulated against top-down cold-chain infrastructure investment projections.
Variance decomposition across the projection horizon isolates volume drivers by technology segment, regulatory certification tier, and modal application to anchor CAGR derivation in observable deployment patterns. Segmentation modeling incorporated container type, industry vertical, cooling technology, and delivery mode dimensions alongside pharmaceutical pipeline stage-specific thermal requirements. Cryogenic container adoption curves for cell therapy logistics and hybrid system penetration rates in modal-shift lanes served as industry-specific forecast inputs alongside REACH F-Gas Regulation compliance cost assumptions.
Material uncertainties — pharmacopeial standard updates outpacing container qualification protocols, input cost volatility in specialized foam and VIP materials, and air-cargo carrier unbundling of leasing contracts — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained EU GDP and FDA cold-chain validation stringency and IATA CEIV Pharma certification expansion timelines. Revision becomes warranted when regulatory validation backlog durations or REACH refrigerant restriction amendments cross thresholds that alter vendor landscape concentration dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Solar Fan Market
Cooling Systems
Portable Chiller Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Cryosystem Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Offshore Air Handling Units Market