
 Continuous Positive Airway Pressure (CPAP) Interface Devices Market | 2026-2036
Continuous Positive Airway Pressure (CPAP) Interface Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Positive Airway Pressure (CPAP) Interface Devices Market Outlook
Aftermarket service revenue from mask cushion replacement and tubing refurbishment is tilting toward home care channels and direct-to-patient subscription models. ResMed Inc. leverages its cloud-connected device ecosystem to lock in recurring interface purchases through automated resupply programs. Fisher & Paykel Healthcare Ltd. anchors its position with humidification-integrated mask systems that reduce nasal dryness complaints and improve therapy adherence. Koninklijke Philips N.V. competes across multiple price tiers with modular mask platforms compatible with third-party CPAP motors.
Continuous Positive Airway Pressure interface devices are patient-worn respiratory accessories—typically constructed from medical-grade silicone cushions, polycarbonate frames, and elastic headgear—that create a sealed pneumatic pathway between a positive pressure generator and the user's airway. These devices maintain therapeutic air pressure measured in centimeters of water pressure to prevent upper airway collapse during sleep. Nasal masks dominate unit volume in sleep apnea treatment due to lower facial contact and reduced claustrophobia, while full face masks command premium positioning for high-pressure bi-level therapy where oral leakage would compromise efficacy. Adaptive pressure technology interfaces are gaining fastest in home care settings as algorithms adjust mask fit notifications in real time.
FDA 510(k) clearance requirements and ISO 10993 biocompatibility testing govern material selection and skin contact safety for all US-distributed interfaces, while the EU MDR reclassification of Class IIa respiratory devices has extended notified body review timelines for European market access. Japan's PMDA enforces JIS T 0601 electromagnetic compatibility standards that interface manufacturers must satisfy for reimbursement eligibility under universal health coverage. Stakeholders should monitor how decentralized sleep diagnostic approvals and remote patient monitoring reimbursement codes reshape channel economics between durable medical equipment suppliers and direct e-commerce platforms.
Market Dynamics
Reimbursement pathway restructuring is fragmenting CPAP interface distribution, as insurers in the United States and Germany tighten prior authorization requirements while Japan's universal health coverage accelerates automated resupply enrollment for elderly patients.
Growth Catalysts
- ISO 10993 biocompatibility mandates:Medical-grade silicone cushion testing protocols are elevating material standards across all FDA 510(k) submissions, filtering out marginal suppliers and consolidating procurement toward certified manufacturers.
- Home care channel expansion:Durable medical equipment suppliers in Germany are building direct-to-patient logistics networks that bypass traditional respiratory clinics, shortening replacement cycles for nasal mask cushions.
- Adaptive pressure algorithms:Real-time mask fit notification systems are reducing therapy abandonment rates among claustrophobia-prone patients who previously rejected full face interfaces.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production clusters in Germany and Japan create vulnerability to petrochemical feedstock volatility affecting cushion manufacturing costs.
- EU MDR Class IIa reclassification:Extended notified body review timelines for respiratory devices are delaying European market entry for modular mask platforms, compressing revenue recognition windows.
- Oral appliance substitution:Mandibular advancement devices for mild-to-moderate sleep apnea are capturing price-sensitive patients who would otherwise initiate CPAP therapy with nasal masks.
Strategic Opportunities
- India diagnostic screening expansion:The country's national health mission is funding portable polysomnography units in tier-2 cities, creating first-time CPAP interface demand from undiagnosed sleep apnea populations.
- Humidification-integrated mask convergence:Combination systems that embed heated humidification directly into mask frames are reducing nasal dryness complaints that drive therapy discontinuation.
- Remote patient monitoring reimbursement codes:New CMS billing categories in the United States are compensating providers for cloud-connected adherence tracking, subsidizing smart interface upgrades.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in pneumatic seal design and facial anthropometry is concentrating among a handful of respiratory device veterans, constraining R&D velocity for mid-tier competitors.
- Legacy device interoperability:Proprietary hose connectors and pressure sensing protocols from established CPAP motor manufacturers are fragmenting mask compatibility standards, forcing interface makers to engineer multiple adapter variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Positive Airway Pressure (CPAP) Interface Devices Market |
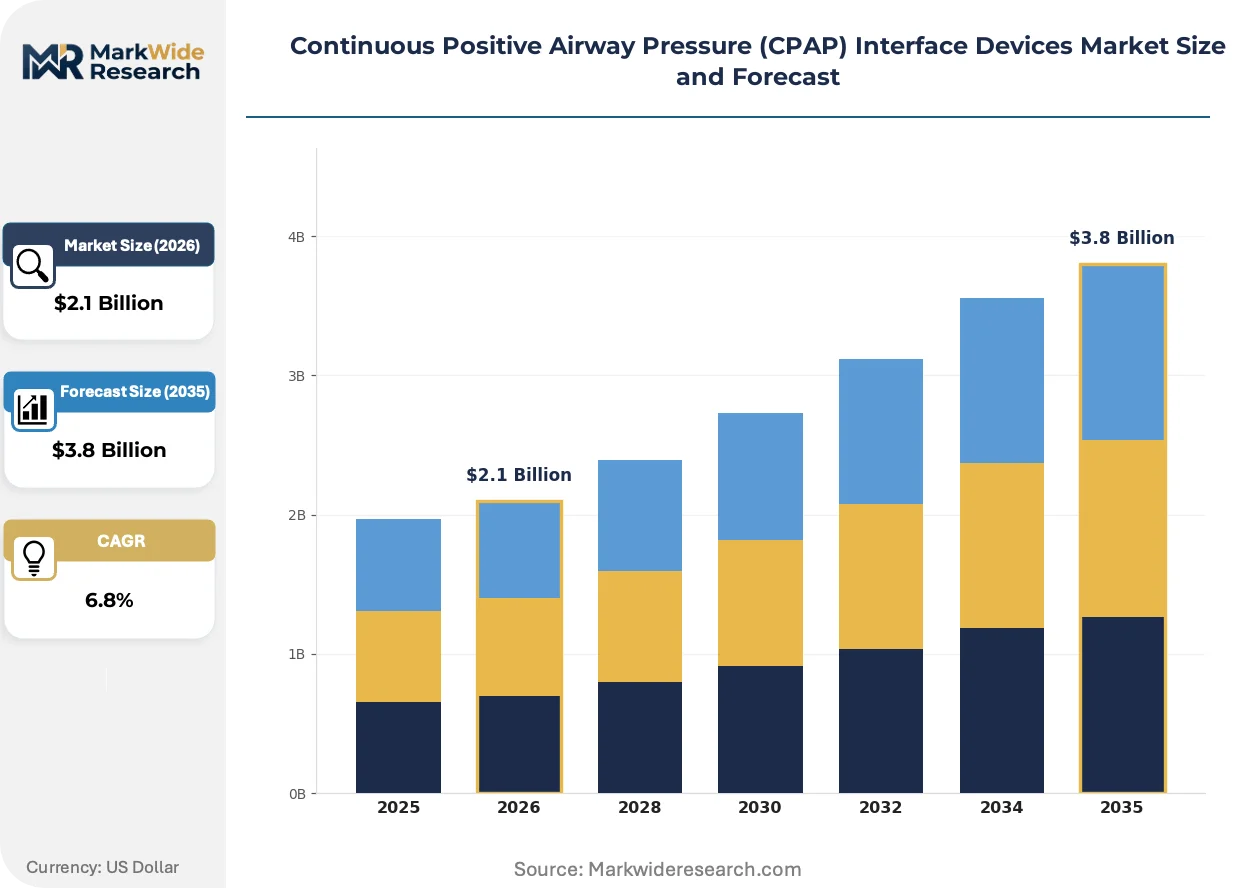
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasal Masks, Full Face Masks, Disposable Interfaces, Ventilation Tubes Technology: Automatic Adjusting, Fixed Pressure, Bi-Level, Adaptive Pressure Application: Sleep Apnea Treatment, Hospital Ventilation, Home Care, Emergency Services End User: Hospitals, Home Care Providers, Nursing Facilities, Sleep Clinics |
| Companies Covered | ResMed Inc., Fisher & Paykel Healthcare Ltd., Koninklijke Philips N.V., Teleflex Inc., Invacare Inc., Salter Labs, BMC Medical Co Ltd, Circadiance, medin Medical Innovations GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Positive Airway Pressure (CPAP) Interface Devices Market Strategic Shifts
Digital integration is redefining how CPAP interfaces capture and transmit adherence data, with cloud architecture displacing local storage and algorithmic personalization replacing fixed pressure settings.
Silicone gel composite cushions are virtualizing traditional foam-and-seal designs by embedding pressure-mapping sensors directly into skin-contact layers. Home care providers in Japan are piloting these interfaces for high-pressure bi-level therapy patients who require dynamic seal adjustment. The technology is virtualizing conventional fitting protocols that relied on static sizing templates and in-person clinician adjustments.
The EU MDR's extended clinical evidence requirements for Class IIa respiratory devices are compressing European product launch timelines and elevating documentation costs for interface manufacturers. Small-to-mid-sized suppliers are responding by withdrawing from notified body applications and redirecting inventory toward United States and Asian markets with lighter regulatory burdens. Full face mask categories face the steepest compliance headwinds due to higher skin contact surface area triggering stricter biocompatibility scrutiny.
Subscription-based resupply enrollment is displacing episodic Durable Medical Equipment billing for mask cushion replacements among United States Medicare Advantage plans. Patients in Florida and Arizona retirement corridors are receiving automated quarterly shipments triggered by cloud-connected usage data rather than self-reported wear indicators. This behavioral shift is concentrating purchasing authority with payers and eroding traditional durable medical equipment supplier margins.
Continuous Positive Airway Pressure (CPAP) Interface Devices Market Segmentation
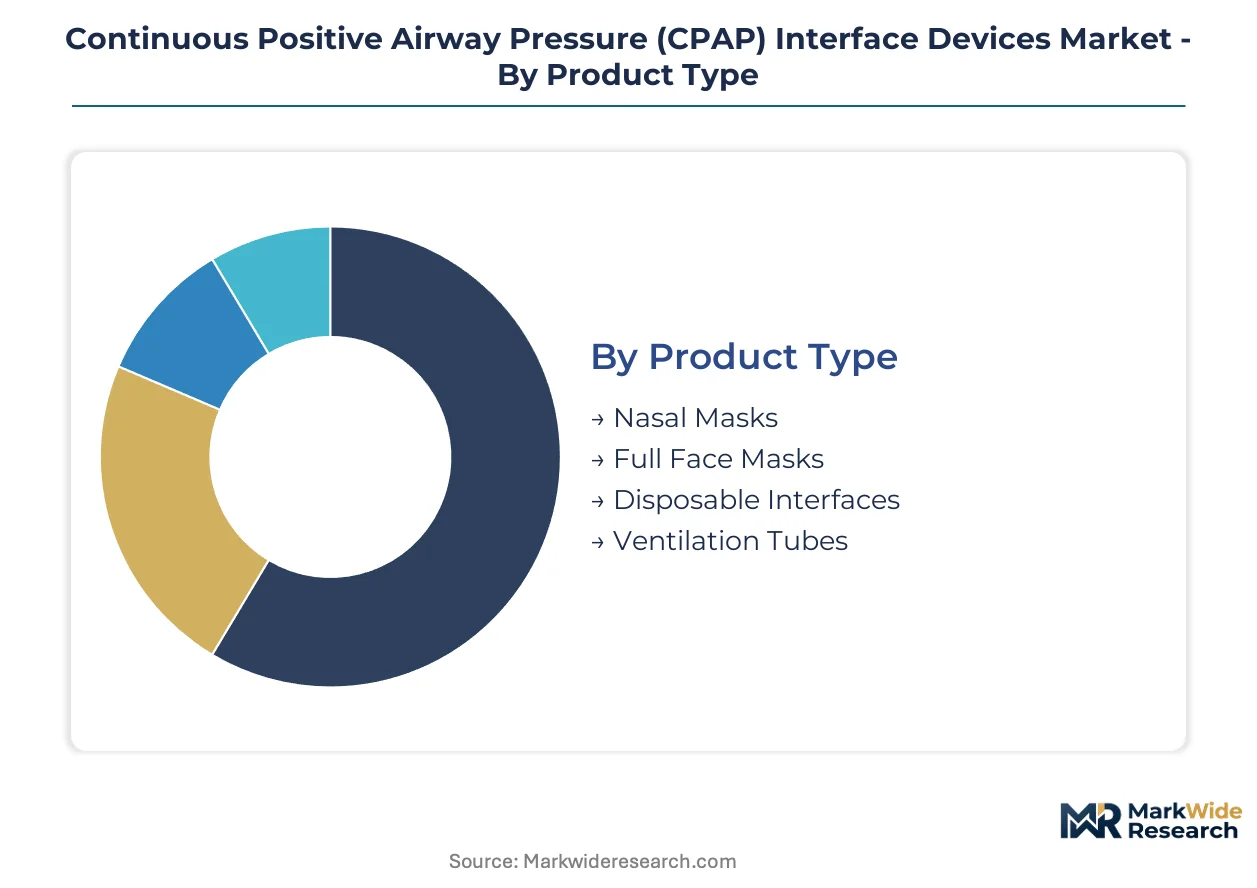
CPAP interface purchasing cycles vary dramatically by clinical setting and patient acuity. Understanding replacement velocity across product categories and end-user channels enables suppliers to calibrate inventory and service models to actual consumption patterns rather than assumed uniform demand.
Product Type:
Nasal masks and disposable interfaces turn over fastest due to cushion degradation and infection protocols, while ventilation tubes and full face masks persist longer in service.
- Nasal Masks:Medical-grade silicone cushions bonded to polycarbonate frames create minimal facial contact for claustrophobia-prone patients. Home care providers in the United States and Germany are accelerating replacement cycles through automated resupply programs tied to cloud-connected adherence data.
- Full Face Masks:These interfaces seal across both nasal and oral airways using dual-zone gel cushions for high-pressure bi-level therapy. Japan's elderly patient population drives steady demand where oral leakage would compromise therapeutic efficacy.
- Disposable Interfaces:Single-use designs eliminate cross-contamination risk in acute care settings. Hospitals prioritize these for emergency ventilation scenarios requiring rapid deployment.
- Ventilation Tubes:Flexible polymer conduits connect mask assemblies to CPAP motors. Extended service life concentrates procurement with durable medical equipment suppliers managing multi-year equipment leases.
Nasal masks dominate installed base. Disposable interfaces are where expansion concentrates.
Technology:
Cost tiers separate adaptive pressure systems commanding premium positioning from fixed-pressure alternatives competing on accessibility.
- Automatic Adjusting:Algorithms modulate delivered pressure based on real-time airflow resistance detected through mask-mounted sensors. Sleep clinics in the United States are standardizing on these systems to reduce manual titration appointments.
- Adaptive Pressure:Machine learning models predict airway collapse probability and preemptively adjust pressure curves. Home care channels show steepest adoption trajectory as cloud infrastructure enables remote algorithm updates.
- Bi-Level:Independent inspiratory and expiratory pressure settings support patients with comorbid respiratory insufficiency. Nursing facilities specify these for patients transitioning from hospital ventilation.
- Fixed Pressure:Constant delivery simplifies device architecture and reduces manufacturing cost. Price-sensitive markets and initial therapy protocols continue absorbing volume despite technology migration.
Fixed pressure systems dominate installed base. Adaptive pressure is where expansion concentrates.
Application:
Volume concentrates in sleep apnea treatment where patient populations scale into millions, while hospital ventilation and emergency services operate on sporadic, high-acuity demand.
- Sleep Apnea Treatment:Chronic therapy requiring nightly interface use drives recurring cushion replacement revenue. Diagnostic screening expansion in Japan and Germany is pulling first-time patients into continuous positive airway pressure protocols.
- Home Care:Decentralized therapy delivery shifts technical support burden to patients and family caregivers. Remote patient monitoring reimbursement codes in the United States are subsidizing smart interface upgrades for this channel.
- Hospital Ventilation:Acute respiratory support demands rapid interface availability across intensive care units. Procurement concentrates through group purchasing organizations negotiating multi-year supply agreements.
- Emergency Services:Pre-hospital ventilation requires ruggedized interfaces compatible with portable oxygen delivery systems. Ambulance services prioritize disposability over durability given contamination exposure.
Sleep apnea treatment dominates installed base. Home care is where expansion concentrates.
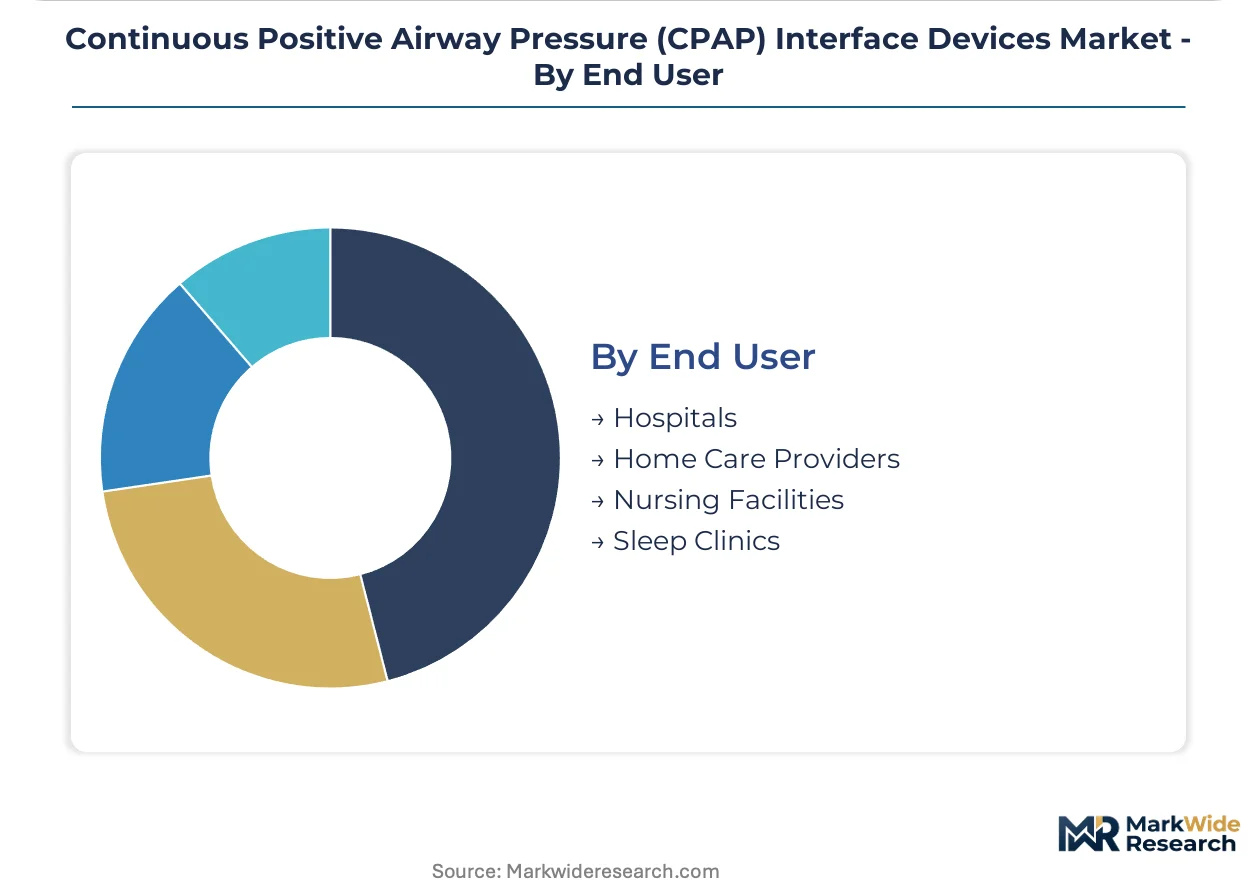
End User:
Customer type determines purchasing authority and replacement cadence, with home care providers and sleep clinics controlling recurring revenue streams while hospitals concentrate capital equipment decisions.
- Home Care Providers:Durable medical equipment suppliers manage patient relationships across multi-year therapy courses. Direct-to-patient logistics networks in Germany are bypassing traditional respiratory clinic intermediaries.
- Sleep Clinics:Diagnostic and titration services generate initial interface prescriptions and follow-up fittings. United States Medicare Advantage plans are consolidating purchasing authority with payers rather than clinic operators.
- Hospitals:Acute care facilities maintain centralized respiratory therapy departments managing diverse ventilation modalities. FDA 510(k) clearance requirements govern all procurement decisions.
- Nursing Facilities:Long-term care settings manage patients with complex comorbidities requiring bi-level therapy support. Staff turnover creates persistent training gaps affecting interface compliance rates.
Home care providers dominate installed base. Sleep clinics are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States Medicare Advantage plans drive automated resupply enrollment with minimal patient cost friction, while Indian patients in tier-2 cities face substantial out-of-pocket exposure for first-time CPAP interface procurement.
United States
Sleep apnea diagnostic screening expansion and aging demographics in Florida and Arizona retirement corridors accelerate replacement cycles for nasal mask cushions. FDA 510(k) clearance requirements and new CMS remote patient monitoring reimbursement codes subsidize cloud-connected interface upgrades. Home care providers in the Southeast are consolidating purchasing authority through direct-to-patient logistics networks that bypass traditional durable medical equipment suppliers.
Germany
Universal health coverage mechanisms and humidification-integrated mask adoption reduce therapy discontinuation among elderly patients with nasal dryness complaints. EU MDR Class IIa reclassification extends notified body review timelines for respiratory devices, compressing revenue recognition windows for modular mask platforms. Specialty elastomer production clusters in the Ruhr region concentrate medical-grade silicone supply for cushion manufacturing.
Japan
PMDA enforcement of JIS T 0601 electromagnetic compatibility standards governs reimbursement eligibility under universal health coverage for elderly populations. High-pressure bi-level therapy demand stabilizes full face mask procurement where oral leakage would compromise efficacy. Tokyo-based home care channels pilot silicone gel composite cushions with embedded pressure-mapping sensors for dynamic seal adjustment.
India
The national health mission funds portable polysomnography units in tier-2 cities, creating first-time CPAP interface demand from undiagnosed sleep apnea populations. CDSCO medical device regulations govern import and distribution of patient-worn respiratory accessories. Maharashtra diagnostic screening hubs concentrate procurement activity for nasal masks targeting price-sensitive initial therapy protocols.
United Kingdom
NHS procurement frameworks consolidate purchasing authority for sleep clinic networks managing multi-year therapy courses. MHRA post-Brexit regulatory autonomy maintains alignment with ISO 10993 biocompatibility standards for silicone cushion safety testing. London and Southeast England respiratory therapy departments standardize on adaptive pressure systems to reduce manual titration appointment backlogs.
Continuous Positive Airway Pressure (CPAP) Interface Devices Market Competitive Environment
Vertically integrated respiratory device conglomerates and specialized interface fabricators split the market between ecosystem-locked recurring revenue and modular compatibility plays. Three to five multinational holdings control the majority of cloud-connected adherence tracking infrastructure, while mid-tier suppliers compete on price-accessible mask platforms for emerging market penetration. Strategic archetypes include full-stack therapy ecosystem operators, component-specialist interface manufacturers, and regional value-tier assemblers. Competitive moves concentrate on automated resupply program enrollment and humidification-integrated mask system convergence.
Within the ecosystem-operator tier, ResMed Inc. and Fisher & Paykel Healthcare Ltd. exemplify contrasting strategic positions. ResMed anchors cloud-connected device infrastructure with automated resupply lock-in, while Fisher & Paykel occupies humidification-integrated positioning that reduces nasal dryness complaints. Koninklijke Philips N.V. sits within the modular-platform archetype, competing across multiple price tiers with third-party CPAP motor compatibility. These three holdings collectively represent the dominant competitive vectors shaping procurement authority concentration between payers and durable medical equipment suppliers.
| Leading Market Players |
|---|
| ResMed Inc. |
| Fisher & Paykel Healthcare Ltd. |
| Koninklijke Philips N.V. |
| Teleflex Inc. |
| Invacare Inc. |
| Salter Labs |
| BMC Medical Co Ltd |
| Circadiance |
| medin Medical Innovations GmbH |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone supply concentration in Germany and Japan creates dual vulnerability to petrochemical feedstock volatility and determines both cushion manufacturing cost spreads and procurement network architecture across premium and economy mask tiers.
Pricing Analysis
Aftermarket cushion replacement revenue drives lifetime value for interface manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and humidification integration. Cost compression in economy nasal masks intensifies because Indian and Southeast Asian suppliers compete on material substitution. Sleep clinics and hospital systems show lowest price sensitivity given reimbursement pass-through, while direct-to-patient channels in emerging markets absorb highest sensitivity.
Supply Chain Analysis
Export-control restrictions on pressure-sensor microelectronics limit component flows to certain manufacturing jurisdictions. Specialty elastomer production clusters in Germany, Japan, and the United States anchor cushion supply. Raw material dependencies center on medical-grade silicone polymers, polycarbonate resins, and woven headgear textiles. Single-source vulnerability concentrates in German chemical suppliers for platinum-cured silicone. Distribution runs through durable medical equipment suppliers and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CPAP interface markets sit in early-cycle expansion as diagnostic screening penetration in India and Southeast Asia pulls first-time patients into therapy protocols previously limited to developed markets.
For Market Incumbents: Entrench cloud-connected ecosystem lock-in through automated resupply algorithms that trigger cushion replacements before patient-reported failure. Deepen backward integration into medical-grade silicone compounding to offset petrochemical volatility exposure. Defend against humidification-integrated mask convergence by accelerating FDA 510(k) submissions for combination systems. For New Entrants and Emerging Players: Tier-2 Indian cities with newly deployed polysomnography units represent the most penetrable entry point for price-accessible nasal mask platforms. Southeast Asian home care channels lacking established durable medical equipment relationships offer white-space for direct logistics partnerships. Pursue CDSCO registration pathways to capture national health mission procurement windows. For Investors and Strategic Acquirers: EU MDR Class IIa reclassification reshapes the acquisition landscape by compressing European revenue timelines and elevating documentation costs that strain mid-tier suppliers. Target interface fabricators with established notified body relationships and ISO 10993 testing infrastructure. Watch decentralized sleep diagnostic reimbursement approvals as inflection signal for home care channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Resupply Program Enrollment | Cloud-connected adherence data triggers replacement shipments before patient-reported cushion degradation. |
| Humidification-Integrated Mask Development | Embedded heated humidification reduces nasal dryness complaints that drive therapy abandonment. |
| FDA 510(k) Submission Acceleration | Biocompatibility testing protocols for silicone gel composites filter out marginal competitors. |
| Direct-to-Patient Logistics Network | German home care channels bypass respiratory clinic intermediaries to shorten replacement cycles. |
| ISO 10993 Certification Investment | Extended notified body review timelines under EU MDR compress windows for uncertified entrants. |
Study Parameters
The analysis maps nasal mask, full face mask, disposable interface, and ventilation tube sub-sectors, each validated through respiratory therapists, biomedical engineers, hospital purchasing committees, and durable medical equipment procurement managers. Primary interviews with home care provider executives and sleep clinic operators combined with secondary validation from FDA 510(k) filings, CMS reimbursement code databases, GPO contract repositories, and EU MDR notified body registries. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Assumptions held diagnostic screening expansion rates and reimbursement pathway structures fixed while varying raw material cost trajectories and regulatory review timelines across the projection horizon. Segmentation dimensions modeled include product type, pressure technology tier, clinical application setting, and end-user channel authority. CAGRs derived from replacement cycle velocity analysis and patient adherence curve modeling. Forecast inputs incorporated cloud-connected device penetration rates and humidification integration adoption thresholds.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing or universal health coverage reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory review timelines and patient screening penetration. Material shifts in EU MDR enforcement intensity or silicone supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Stethoscope Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Liposuction Devices Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
North America Pen Needles Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market