
 Trail Mix Market | 2026-2036
Trail Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Trail Mix Market Analysis
EU Green Deal sustainability criteria is pivoting ingredient sourcing toward certified organic nuts and dried fruits in European supply chains. Kellanov leverages its direct farm partnerships in Turkey and California to secure non-GMO almond supplies. PepsiCo competes through its Gatorade-affiliated performance snack portfolio, while Mondelez International anchors its position via premium dark chocolate inclusion lines. General Mills controls distribution density through its Nature Valley retail shelf space agreements.
Trail mix denotes a blended snack combining dried fruits, nuts, seeds, and confectionery pieces, typically shelf-stable for 6-12 months and packaged under nitrogen flush to preserve lipid integrity. Manufacturers roast nuts at 140-160°C to develop Maillard flavor compounds while monitoring moisture content below 4% to prevent rancidity. Nut-Based formulations occupy the largest margin pool due to commodity hedging advantages and premium positioning. Single-Serve Packs represent the fastest-growing packaging format as convenience retailers expand grab-and-go sections. Health-Conscious Shoppers drive reformulation toward reduced sodium and no-added-sugar variants.
FDA enforces allergen disclosure under FALCPA for tree nuts and peanuts, forcing reformulation or segregated production lines. USDA organic certification shapes ingredient procurement premiums and retail placement access. ISO 22000 HACCP frameworks govern foreign object control in bulk nut handling operations. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their extraterritorial impact on sourcing transparency requirements.
Market Dynamics
Clean-label reformulation is compressing formulation cycles as Health-Conscious Shoppers reject artificial preservatives and synthetic flavor enhancers across retail channels. Manufacturers must reconfigure roasting protocols and nitrogen-flush packaging lines to maintain lipid integrity without chemical stabilizers.
Growth Catalysts
- FDA Nutritional Labeling Requirements:FALCPA allergen disclosure mandates are forcing facility segregation investments that favor scaled producers with multi-line HACCP certifications. This regulatory pressure consolidates shelf access for compliant brands.
- Pacific Northwest Demand Cluster:Urban centers in Oregon and Washington generate disproportionate velocity for organic and non-GMO trail mix SKUs. Regional retailers prioritize local suppliers with direct farm partnerships.
- Nitrogen Flush Packaging:Modified atmosphere technology extends shelf stability to 12 months without synthetic antioxidants. Equipment upgrades are spreading from premium tiers into mid-market production lines.
Market Restraints
- Almond Price Volatility:California drought cycles and water allocation disputes create input cost instability. Manufacturers lack effective hedging instruments for organic nut commodities.
- Turkish Supply Concentration:Premium dried fruit sourcing clusters in Turkey's Aegean region. Geopolitical friction or currency instability disrupts just-in-time procurement for European and North American processors.
- EU Deforestation-Free Supply Chain Regulations:Extraterritorial traceability requirements impose documentation burdens on non-EU exporters. Compliance costs disadvantage smaller importers without dedicated sustainability teams.
Strategic Opportunities
- Single-Serve Convenience Channel:Grab-and-go sections at airport terminals and urban transit hubs remain underpenetrated by premium trail mix brands. Vending machine and micro-market formats offer margin expansion.
- Performance Snack Crossover:Electrolyte-infused and protein-fortified variants target endurance athletes and outdoor recreation segments. Formulation convergence with sports nutrition creates pricing headroom.
- USDA Organic Certification Tailwinds:Federal procurement preferences and school nutrition program expansions favor certified suppliers. Early certification investments secure institutional contract eligibility.
Industry Challenges
- Maillard Reaction Control Talent:Precise roasting temperature management at 140-160°C requires specialized food engineering expertise. Recruitment competition from coffee and craft chocolate sectors elevates compensation costs.
- ISO 22000 HACCP Implementation:Foreign object detection systems for bulk nut handling demand capital-intensive X-ray and optical sorting equipment. Smaller processors face financing constraints for compliance upgrades.
- Moisture Content Monitoring Integration:Real-time rancidity prevention requires sensor deployment across distributed production networks. Legacy facilities lack ethernet infrastructure for IoT-enabled quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trail Mix Market |
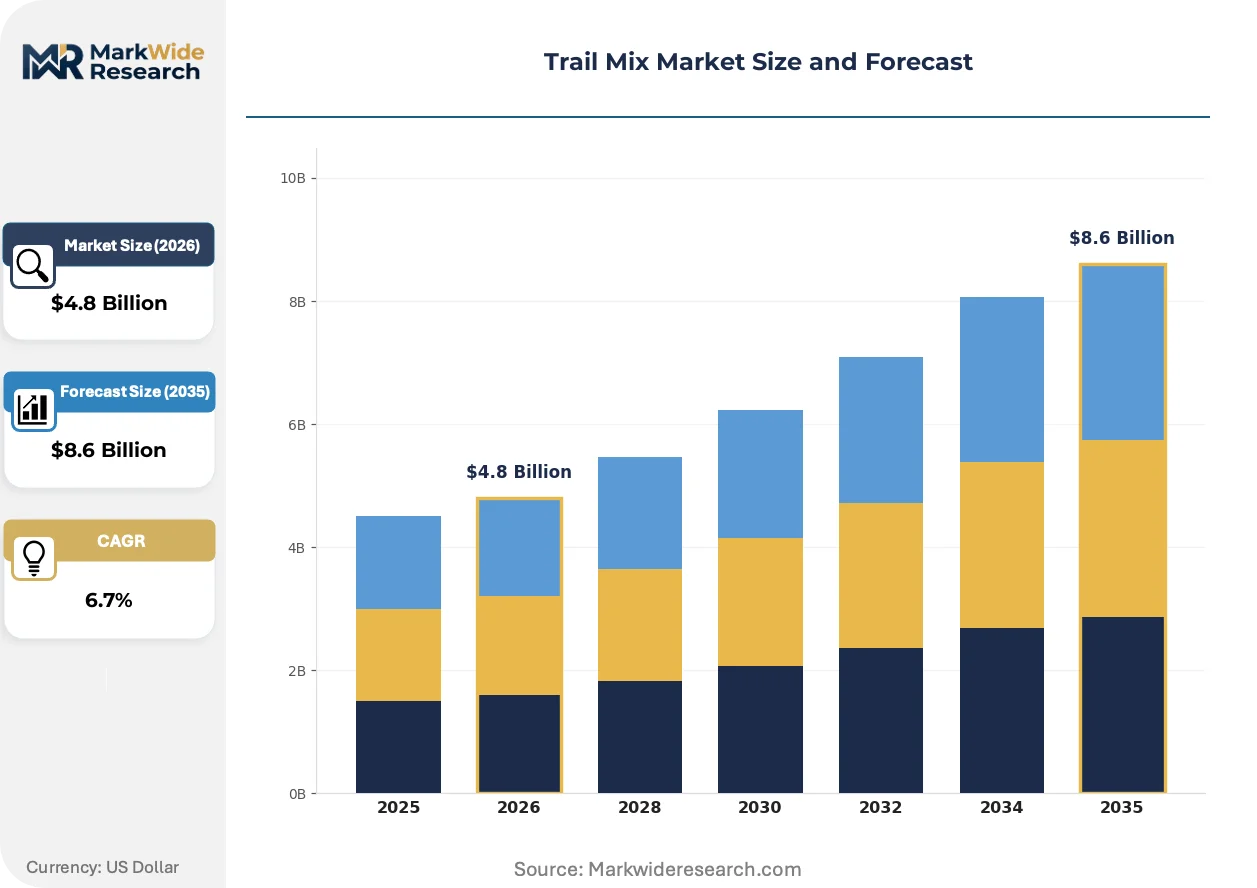
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Seed-Based, Fruit-Based, Chocolate-Covered Packaging Type: Bags, Boxes, Single-Serve Packs, Bulk Containers End User: Retail Consumers, Fitness Enthusiasts, Outdoor Adventurers, Health-Conscious Shoppers Flavor Profile: Sweet, Savory, Spicy, Tropical |
| Companies Covered | Kellanov, The J.M. Smucker Company, PepsiCo Inc., Mondelez International Inc., Second Nature Brands, General Mills Inc., The Kraft Heinz Company, Happilo International Pvt. Ltd., Mars Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trail Mix Market Emerging Trajectories
Active reformulation is replacing legacy recipes as consumer scrutiny intensifies on added sugars and sodium levels. Three distinct vectors are compressing development timelines and reshaping competitive positioning.
Precision roasting control systems are overtaking conventional batch ovens in mid-capacity facilities. These systems modulate heat curves to optimize Maillard compound development while constraining acrylamide formation. Health-Conscious Shoppers and premium private-label buyers are specifying equipment certifications in supplier audits. The technology is compressing quality variation and enabling consistent clean-label claims without flavor sacrifice.
EU Green Deal sustainability criteria are redirecting procurement toward certified organic nuts and dried fruits with documented chain-of-custody. European supply chains now require satellite-verified deforestation-free sourcing documentation. Organic certification premiums are widening between compliant and conventional suppliers. California's Central Valley and Turkey's Aegean cooperatives are investing in blockchain traceability to maintain market access.
Convenience retailers are consolidating shelf space around protein-forward and reduced-sugar formulations. Traditional confectionery-heavy trail mix SKUs are losing velocity to functional alternatives with seed blends and adaptogen inclusions. Urban professional segments and outdoor recreation enthusiasts are driving the pivot. The shift is most visible in California's organic food corridor and Pacific Northwest metropolitan markets.
Trail Mix Market Segmentation
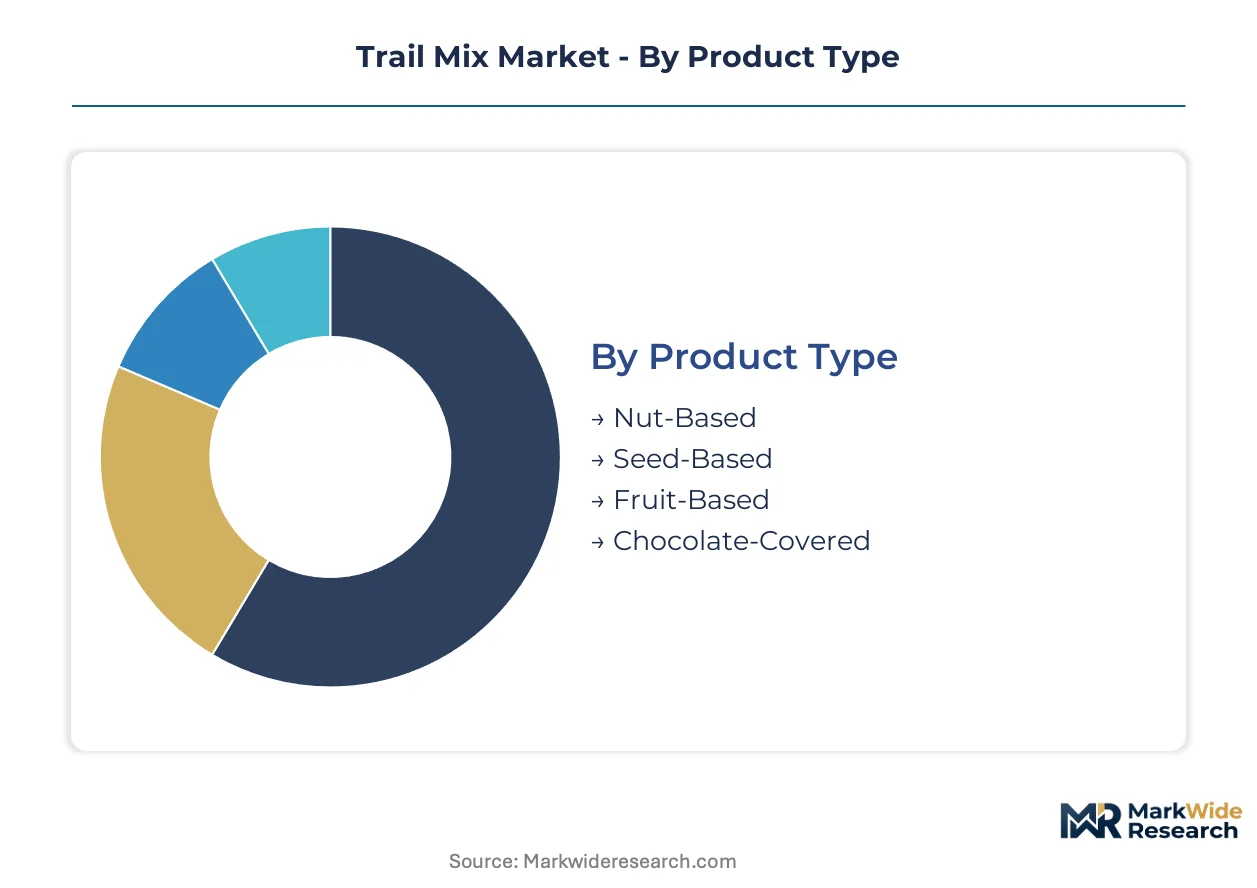
Trail mix manufacturers configure production lines around distinct consumption occasions and ingredient cost structures. Segmentation decisions determine roasting protocols, nitrogen-flush packaging investments, and shelf placement negotiations with convenience retailers.
Product Type:
Customization intensity spans from commodity nut blends to premium chocolate inclusions, with formulation complexity driving margin stratification across manufacturing tiers.
- Nut-Based:Almond, cashew, and walnut formulations dominate commercial output, with California Central Valley sourcing anchoring supply security. Health-Conscious Shoppers in Oregon and Washington generate disproportionate velocity for organic nut SKUs, though almond price volatility from drought cycles compresses hedging effectiveness.
- Seed-Based:Pumpkin and sunflower seed blends target allergen-sensitive segments and school nutrition programs. These formulations bypass FALCPA tree nut disclosure requirements, opening institutional procurement channels where peanut-free certification is mandatory.
- Fruit-Based:Dried cranberry, mango, and apricot combinations emphasize natural sweetness without added sugars.
- Chocolate-Covered:Premium dark chocolate inclusions command retail price premiums through positioning as indulgence-permissible snacks.
Leading the category by volume: Nut-Based. Growing fastest: Seed-Based.
Packaging Type:
Cost tier separation runs from bulk foodservice formats to precision-portioned retail units, with equipment amortization schedules dictating strategic focus.
- Single-Serve Packs:Modified atmosphere pouches with nitrogen flush extend shelf stability to 12 months without synthetic antioxidants. Airport terminals and urban transit hubs remain underpenetrated by premium brands in this format, creating margin expansion opportunities for compliant producers.
- Bulk Containers:Foodservice and institutional buyers favor 5-25 pound pails for cafeteria and hospitality applications. These formats prioritize moisture content below 4% and lipid integrity preservation through vacuum sealing rather than individual portion control.
- Bags:Resealable stand-up pouches dominate club store and conventional grocery placement.
- Boxes:Gift-oriented and seasonal assortments utilize rigid packaging for premium positioning.
Widest distribution footprint: Bags. Steepest expansion trajectory: Single-Serve Packs.
End User:
Application context determines ingredient ratios, with performance nutrition specifications diverging sharply from casual snacking occasions.
- Health-Conscious Shoppers:Clean-label scrutiny drives reformulation toward no-added-sugar and reduced-sodium variants. California's organic food corridor and Pacific Northwest metropolitan markets concentrate demand for certified organic and non-GMO SKUs with documented chain-of-custody.
- Fitness Enthusiasts:Protein-fortified and electrolyte-infused variants target endurance athletes, with formulation convergence toward sports nutrition creating pricing headroom. Gatorade-affiliated performance snack portfolios compete directly in this segment.
- Retail Consumers:Mass-market buyers prioritize convenience and value, accepting conventional ingredient sourcing.
- Outdoor Adventurers:Shelf-stable, calorie-dense formulations emphasize portability and environmental durability.
Largest absolute volume: Retail Consumers. Gaining share fastest: Health-Conscious Shoppers.
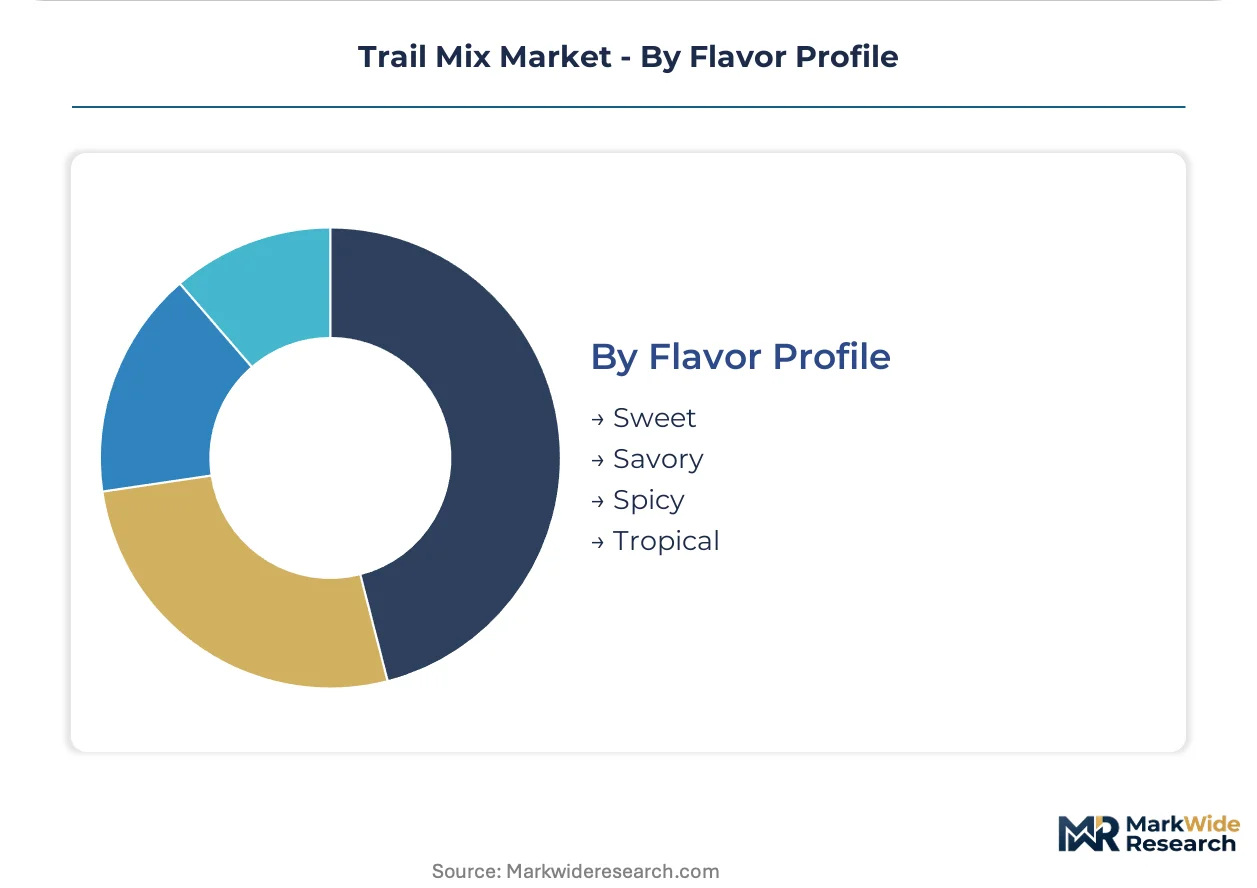
Flavor Profile:
Customer type alignment separates indulgence-oriented from functional-positioned offerings, with regional taste preferences influencing regional SKU allocation.
- Sweet:Honey-glazed nuts and dried fruit combinations remain the default formulation for mass-market penetration.
- Savory:Herb-infused and sea salt varieties target reduced-sugar positioning without sacrificing palatability.
- Spicy:Chili-lime and wasabi-pea inclusions capture adventurous snacking occasions in Southwestern US markets.
- Tropical:Coconut, pineapple, and macadamia blends command premium positioning through exotic ingredient sourcing.
Highest velocity in conventional retail: Sweet. Most rapid niche expansion: Savory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley supplies the bulk of global almond inputs while consumption clusters in urban organic corridors across three continents. Manufacturing capacity concentrates near raw nut sources to minimize moisture exposure during transport.
United States
Health-Conscious Shoppers in Oregon and Washington generate disproportionate velocity for organic and non-GMO SKUs. FDA nutritional labeling requirements under FALCPA force facility segregation investments that favor scaled producers. The Pacific Northwest metropolitan markets prioritize local suppliers with direct farm partnerships.
Turkey
Premium dried fruit sourcing clusters in the Aegean region for European and North American processors. Geopolitical friction or currency instability disrupts just-in-time procurement schedules. Aegean cooperatives are investing in blockchain traceability to maintain EU market access under deforestation-free regulations.
Germany
EU Green Deal sustainability criteria redirect procurement toward certified organic nuts with documented chain-of-custody. REACH compliance shapes packaging material specifications for nitrogen-flush pouch imports. The country's central European logistics position anchors distribution for continental private-label programs.
China
Domestic consumption of shelf-stable snacks expands in tier-one cities as urban professional segments prioritize convenience. SAMR food safety standards govern imported nut contamination limits and labeling requirements. Yangtze River Delta manufacturing hubs process re-export blends for Southeast Asian markets.
India
FSSAI mandatory fortification guidelines and allergen disclosure rules reshape formulation standards for domestic brands. School nutrition program expansions favor certified suppliers with peanut-free production lines. Maharashtra-based processors leverage port access for Middle East export contracts.
Trail Mix Market Vendor Landscape
The competitive structure tilts toward diversified snack conglomerates with existing retail shelf space agreements. Mid-cap organic specialists compete through direct farm partnerships and clean-label positioning. Three archetypes dominate: scaled CPG houses with multi-category leverage, vertically integrated nut processors, and private-label co-manufacturers. Capacity expansion and portfolio diversification represent the dominant competitive moves as brands chase single-serve convenience channel placement.
Within the scaled CPG tier, Kellanov leverages direct farm partnerships in Turkey and California to secure non-GMO almond supplies. PepsiCo competes through its Gatorade-affiliated performance snack portfolio. Mondelez International anchors its position via premium dark chocolate inclusion lines. General Mills controls distribution density through its Nature Valley retail shelf space agreements.
| Leading Market Players |
|---|
| Kellanov |
| The J.M. Smucker Company |
| PepsiCo Inc. |
| Mondelez International Inc. |
| Second Nature Brands |
| General Mills Inc. |
| The Kraft Heinz Company |
| Happilo International Pvt. Ltd. |
| Mars Incorporated |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in California's Central Valley and Turkey's Aegean region anchor supply discipline through generational farm partnerships, translating water allocation scarcity and currency exposure into premium pricing power for organic nut and dried fruit inputs. Their refusal to dilute equity for rapid expansion preserves margin integrity across volatile commodity cycles.
Pricing Analysis
Margin tightening in organic SKUs reflects California drought-driven almond cost escalation and Turkish lira instability on dried fruit procurement. Three-tier pricing structure across premium, standard, and economy levels separates certified organic with blockchain traceability from conventional blends and private-label commodity tiers. Price differentiation hinges on USDA organic certification and nitrogen-flush packaging equipment investments. Health-Conscious Shoppers in the Pacific Northwest show lowest price sensitivity, while mass-market retail buyers drive cost-down pressure on conventional formulations.
Supply Chain Analysis
Dual-sourcing mandates from EU importers require qualified suppliers in both California and Turkey to satisfy deforestation-free documentation requirements. Raw material flows draw from almond orchards in California's Central Valley, hazelnuts from Turkey's Black Sea region, and dried apricots from the Aegean coast. Single-source vulnerability concentrates in Turkish dried fruit channels exposed to geopolitical friction. Distribution runs through refrigerated consolidation hubs near Los Angeles and Rotterdam for transatlantic premium lines, with bulk shipments direct to North American roasting facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Almond water rights scarcity in California's Central Valley props organic input pricing, constraining capacity expansion and sustaining margin pools for qualified producers. This supply bottleneck justifies defensive consolidation among scaled players.
For Market Incumbents:Acquire roasting facilities with precision Maillard control systems and existing USDA organic certification to lock in technical talent scarce across food engineering labor markets. Consolidate shelf space agreements with convenience retailers expanding grab-and-go sections before emerging private-label entrants secure placement. Defend against PepsiCo's Gatorade-affiliated performance snack crossover through electrolyte-infused SKU development.
For New Entrants and Emerging Players:Launch via direct-to-consumer subscription models targeting Health-Conscious Shoppers in underpenetrated Pacific Northwest metropolitan markets with customizable clean-label blends. Exploit white space in airport terminal vending channels where premium single-serve packs remain scarce. Position around adaptogen and seed-based formulations bypassing FALCPA allergen disclosure requirements for school nutrition program access.
For Investors and Strategic Acquirers:Distressed-cycle entries favor vertically integrated nut processors with captive California almond acreage and existing EU organic certification. Long-term viability in this market rests on water rights security and deforestation-free supply chain documentation capabilities. Watch California State Water Resources Control Board allocation rulings as the primary inflection signal for input cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farm Partnership Expansion | Kellanov's Turkey-California sourcing model secures non-GMO almond supply continuity against drought volatility. |
| Nitrogen-Flush Packaging Upgrade | Modified atmosphere technology extends shelf stability to 12 months without synthetic antioxidant inclusion. |
| USDA Organic Certification Investment | Federal procurement preferences and school nutrition program expansions favor certified supplier eligibility. |
| Single-Serve Convenience Channel Entry | Airport terminals and urban transit hubs remain underpenetrated by premium trail mix brands. |
| Performance Snack Formulation Crossover | Electrolyte-infused variants target endurance athletes with pricing headroom from sports nutrition convergence. |
Methodological Framework
Document review covered FDA FALCPA guidance documents, USDA organic certification databases, and EU deforestation-free supply chain regulations, complemented by interviews with roasting facility operations managers, convenience retail category buyers, and organic certification auditors. Secondary validation drew from customs trade data on nut and dried fruit imports, Nielsen retail audit velocity figures, and SEC filings of diversified snack conglomerates. Bottom-up production capacity estimates triangulated against top-down consumption projections across the analysis window.
Historical shipment volumes from California almond processors and Turkish dried fruit exporters were cross-referenced against panel input from procurement leads at North American co-manufacturers. Segmentation modeling incorporated product type, packaging format, end-user archetype, and flavor profile dimensions across the projection horizon. CAGRs were derived from curve-fitting approaches applied to import volume trajectories and retail scanner data, with almond price volatility and currency exposure scenarios stress-testing base case assumptions.
California drought severity, Turkish geopolitical stability, and EU regulatory enforcement intensity are the dominant revision risks to modeled outcomes. Deviation in almond water allocation rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Nachos Market
Snacks
Grass-Fed Jerkies Market
Snacks
South America Energy Bar Market
Snacks
Forti Flakes Market
Snacks
Savory Snack Products Market
Snacks
Latin America Extruded Snack Food Market
Snacks
South Korea Snack Bar Market
Snacks
Crispy Fruit Chips Market
Snacks
Middle East Snack Bar Market
Snacks
Allergy-Free Snacks Market
Snacks
Dried Fruit Snacks Market
Snacks
Salty Puffed Snacks Market
Snacks
Energy Balls Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
US Potato Chips Market
Snacks
Seaweed Snacks Market