
 Macadamia Butter Market | 2026-2036
Macadamia Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Macadamia Butter Market Foresight
Subscription-based replenishment models for specialty nut butters is hardening into a core revenue layer for direct-to-consumer brands. MaraNatha leverages its established organic distribution network to sustain recurring purchases through auto-ship programs. Wilderness Poets anchors its premium positioning with small-batch sourcing transparency that commands loyalty in health-conscious segments. Big Spoon Roasters differentiates through chef-crafted flavor profiles that occupy a distinct niche between commodity spreads and luxury ingredients.
Macadamia butter is a smooth paste produced by grinding macadamia nuts, typically containing 70-80% fat with minimal carbohydrate content, created through either raw cold-processing or dry-roasting followed by mechanical milling. Its primary commercial purpose centers on delivering a dairy-free, keto-compatible fat source for baking, confectionery, and functional food formulations. Roasted butter captures the dominant margin pool due to broader palatability and extended shelf stability, while raw butter leads growth among cold-pressed and enzyme-retentive nutrition segments. Flavored butter variants concentrate value in specialty shops and online retail channels where experimentation commands price premiums.
FDA food labeling requirements and EFSA nutrition and health claims regulations shape permissible marketing language around macadamia butter's cardiovascular and metabolic properties, directly influencing product positioning and cross-border market access. Australia's FSANZ standards additionally govern maximum residue limits for aflatoxins in nut-based spreads, affecting import eligibility for processors in South Africa and Kenya. Stakeholders must monitor evolving clean-label enforcement intensity and origin-certification requirements as retail buyers sharpen traceability demands.
Market Dynamics
Clean-label mandates from FDA and EFSA are compressing formulation timelines for macadamia butter processors, forcing rapid substitution of emulsifiers and stabilizers with single-ingredient alternatives that satisfy retailer audit protocols.
Growth Catalysts
- Keto diet proliferation:North American bakery chains are reformulating pastry bases with macadamia butter to capture low-carbohydrate menu segments, displacing conventional shortening volumes in test kitchens.
- EFSA health claims pathway:Approved cardiovascular benefit language is enabling premium shelf positioning for monounsaturated fat content in EU retail channels, accelerating category migration from commodity nut spreads.
- Cold-press technology diffusion:Australian processors deploying enzyme-retentive milling systems are capturing raw-segment price premiums that roasted variants cannot command.
Market Restraints
- Input cost volatility:Macadamia kernel prices swing with Queensland harvest yields, compressing margin predictability for contract manufacturers dependent on Australian supply.
- Substitution elasticity:Almond butter and cashew paste maintain cost advantages in foodservice formulations, limiting macadamia penetration in price-sensitive bakery accounts.
- Aflatoxin regulatory friction:FSANZ maximum residue limits block Kenyan and South African processors from Australian distribution networks despite competitive raw material costs.
Strategic Opportunities
- Direct-to-consumer subscription channels:Auto-replenishment platforms bypass conventional retail slotting fees, capturing lifetime value from health-conscious households in California and New South Wales.
- Confectionery fat replacement:Belgian and Swiss chocolatiers are testing macadamia butter as cocoa butter extenders in praline fillings, opening industrial volume contracts.
- USDA Organic certification tailwind:Expanded acreage under organic macadamia cultivation in Hawaii is loosening supply constraints for certified-clean-label product lines.
Industry Challenges
- Specialized milling technician scarcity:Cold-press operation demands expertise in temperature-controlled lipid stabilization that conventional peanut butter facilities cannot repurpose without retraining.
- Legacy ERP integration friction:Lot-traceability requirements for FSANZ compliance force mid-tier processors to replace inventory systems before achieving export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macadamia Butter Market |
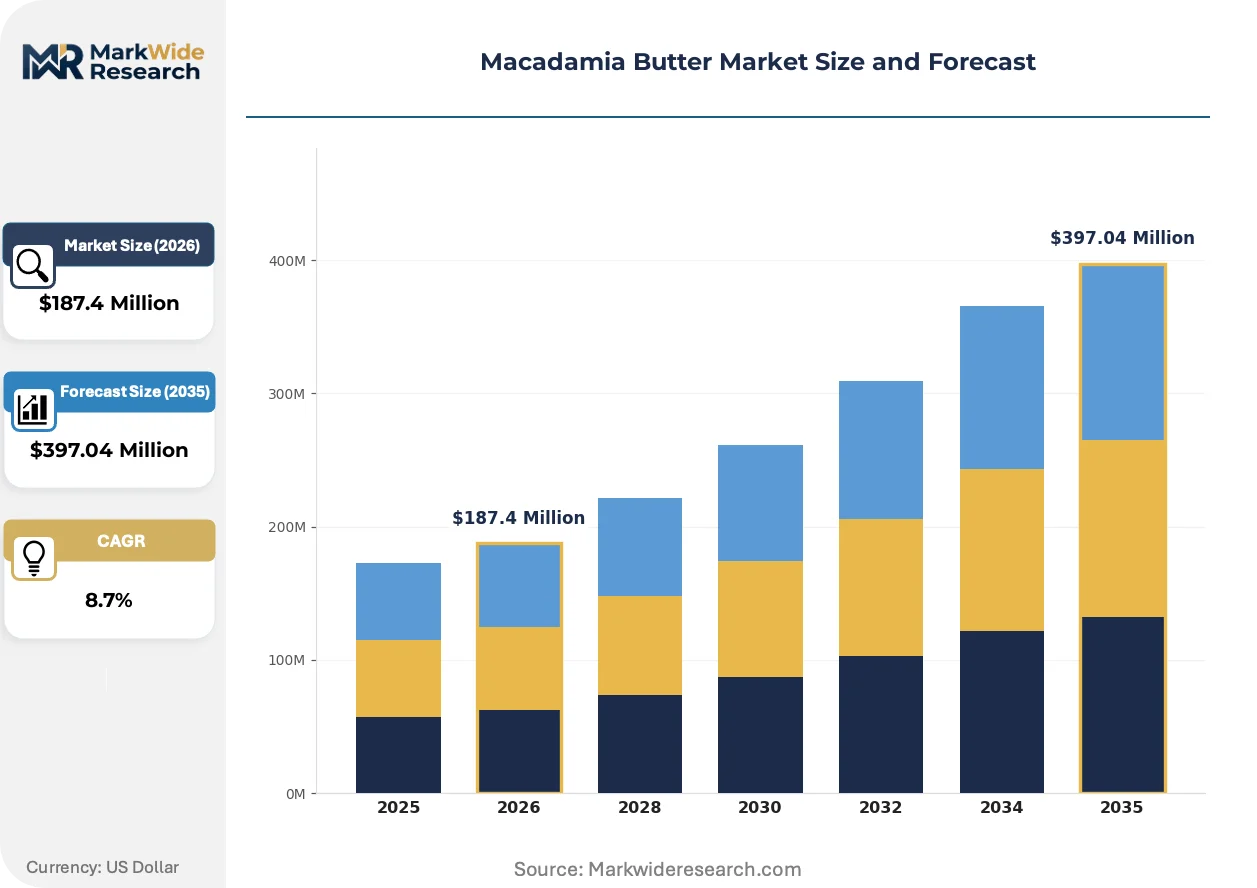
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Butter, Roasted Butter, Flavored Butter, Unsweetened Butter End User: Food Manufacturers, Bakeries, Restaurants, Health Food Stores Packing Type: Glass Jars, Plastic Containers, Tetra Paks, Pouches Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | MaraNatha, Futter’s Nut Butters, Wilderness Poets, Big Spoon Roasters, Woodstock Foods, Yumbutter, Carley’s of Cornwall Ltd, Tiny Isle, Torere Macadamias, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macadamia Butter Market Shifts & Advancements
Refrigerated supply chain infrastructure is expanding to accommodate enzyme-active raw macadamia butters, reshaping distributor relationships and retail placement strategies away from ambient shelf-stable norms.
High-pressure processing (HPP) is converging with raw macadamia butter production to extend refrigerated shelf life without thermal degradation of heat-sensitive bioactive compounds. Artisan producers in Byron Bay and Santa Barbara are adopting HPP lines to justify 40-60% price premiums over roasted alternatives. This convergence is compressing the traditional raw-roasted quality hierarchy by delivering safety parity with nutritional retention.
EFSA's updated nutrition and health claims regulation is tightening substantiation requirements for cardiovascular benefit marketing, forcing reformulators to commission clinical trials or withdraw specific monounsaturated fat language. The industrial consequence is a bifurcation between evidence-backed premium positioning and generic wellness claims. EU-facing brands are responding by funding intervention studies through pooled industry consortia to share substantiation costs.
Chef-driven procurement is displacing commodity purchasing in upscale foodservice accounts, with executive pastry chefs specifying single-origin macadamia butter by processor name in supply agreements. This specification behavior concentrates volume with traceable Australian and Hawaiian sources while marginalizing blended-origin alternatives. The shift is most visible in Michelin-tier restaurant groups across France and Japan where menu provenance disclosure is mandatory.
Macadamia Butter Market Segmentation
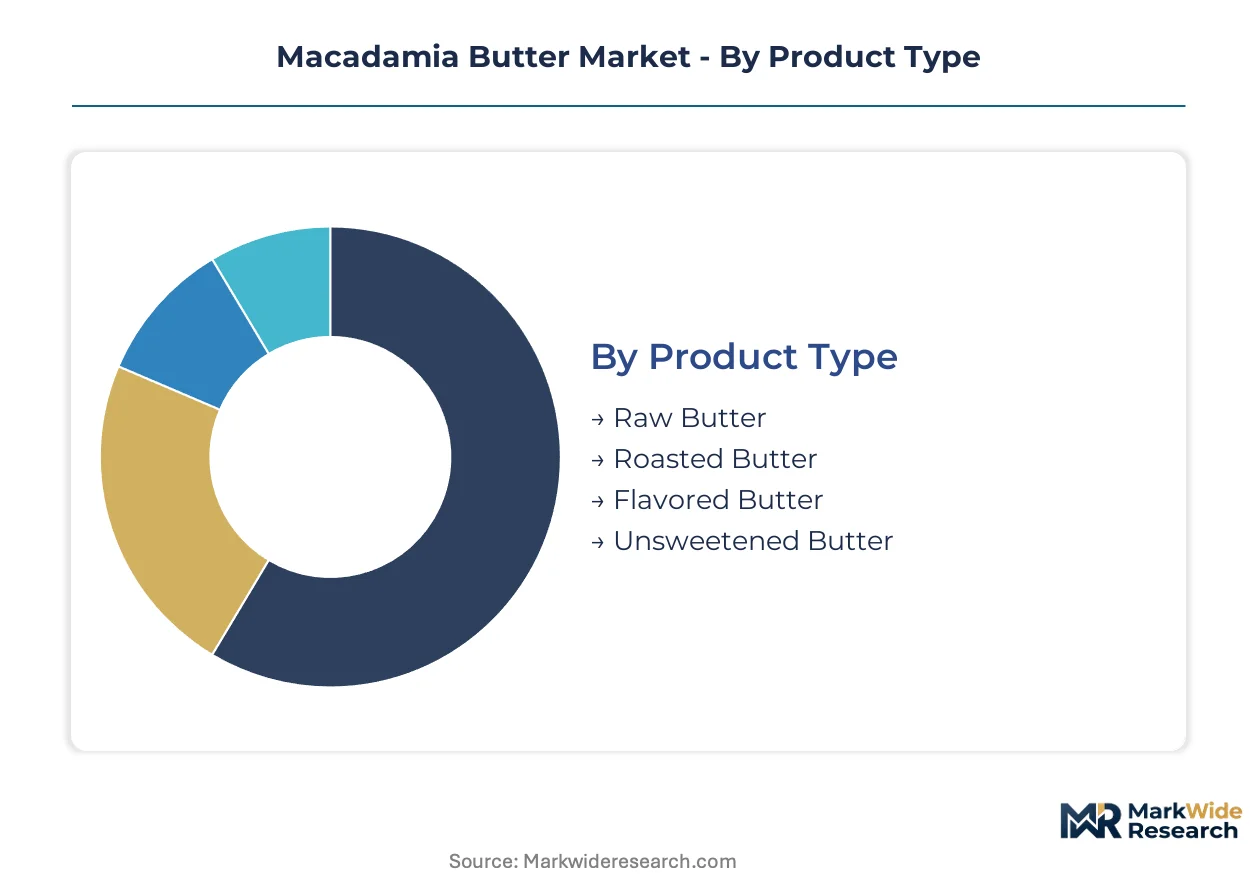
Macadamia butter's commercial structure fragments across production method, buyer sophistication, and channel access. Each segment carries distinct margin profiles and regulatory exposure that reshape procurement priorities for processors and distributors alike.
Product Type:
Supply concentration in Australian milling clusters favors processors with dedicated cold-press or roasting infrastructure over commodity nut butter facilities.
- Raw Butter:Produced through enzyme-retentive cold-milling below 40°C, preserving heat-sensitive bioactive lipids and phospholipids. Byron Bay and Santa Barbara producers command refrigerated distribution premiums in California and New South Wales health food channels where HPP-treated variants justify 40-60% price spreads over thermally processed alternatives.
- Roasted Butter:Dry-roasted kernels undergo mechanical milling to achieve broader palatability and 12-18 month ambient shelf stability. Australian processors in Queensland and Hawaiian cooperatives on the Big Island dominate contract manufacturing for North American bakery chains reformulating keto-compatible pastry bases.
- Flavored Butter:Infusions of vanilla, sea salt, or cacao powder target specialty shop and direct-to-consumer channels where experimentation commands price premiums.
- Unsweetened Butter:Single-ingredient formulations satisfy clean-label mandates from FDA and EFSA for cardiovascular health claim eligibility.
Roasted butter absorbs the bulk of installed capacity; raw butter is expanding most quickly.
End User:
Cost tier stratification separates industrial volume purchasers from premium-channel specialists with distinct specification behaviors.
- Food Manufacturers:Industrial buyers in Belgian and Swiss confectionery clusters test macadamia butter as cocoa butter extenders in praline fillings, sourcing through long-term contracts with traceable Australian and Hawaiian processors.
- Bakeries:Artisan and chain pastry operations in France and Japan specify single-origin butter by processor name, displacing commodity purchasing in Michelin-tier restaurant groups where menu provenance disclosure is mandatory.
- Restaurants:Chef-driven procurement concentrates volume with cold-press specialists offering lot-traceability for FSANZ compliance.
- Health Food Stores:Retail buyers sharpen origin-certification demands, prioritizing USDA Organic and small-batch sourcing transparency.
Food manufacturers absorb the bulk of installed capacity; bakeries are climbing the fastest.
Packing Type:
Volume concentration in ambient-stable formats competes with emerging refrigerated infrastructure for enzyme-active products.
- Glass Jars:Premium positioning in specialty shops and gift channels where visual clarity and reusability support sustainability narratives.
- Plastic Containers:Lightweight, shatter-resistant formats dominate supermarket and health store distribution with lower freight cost per unit.
- Tetra Paks:Aseptic filling extends shelf life for foodservice liquid formulations without refrigeration dependency.
- Pouches:Flexible packaging gains traction in online retail and subscription replenishment models for portion-controlled consumption.
Plastic containers absorb the bulk of installed capacity; pouches are gaining share fastest.
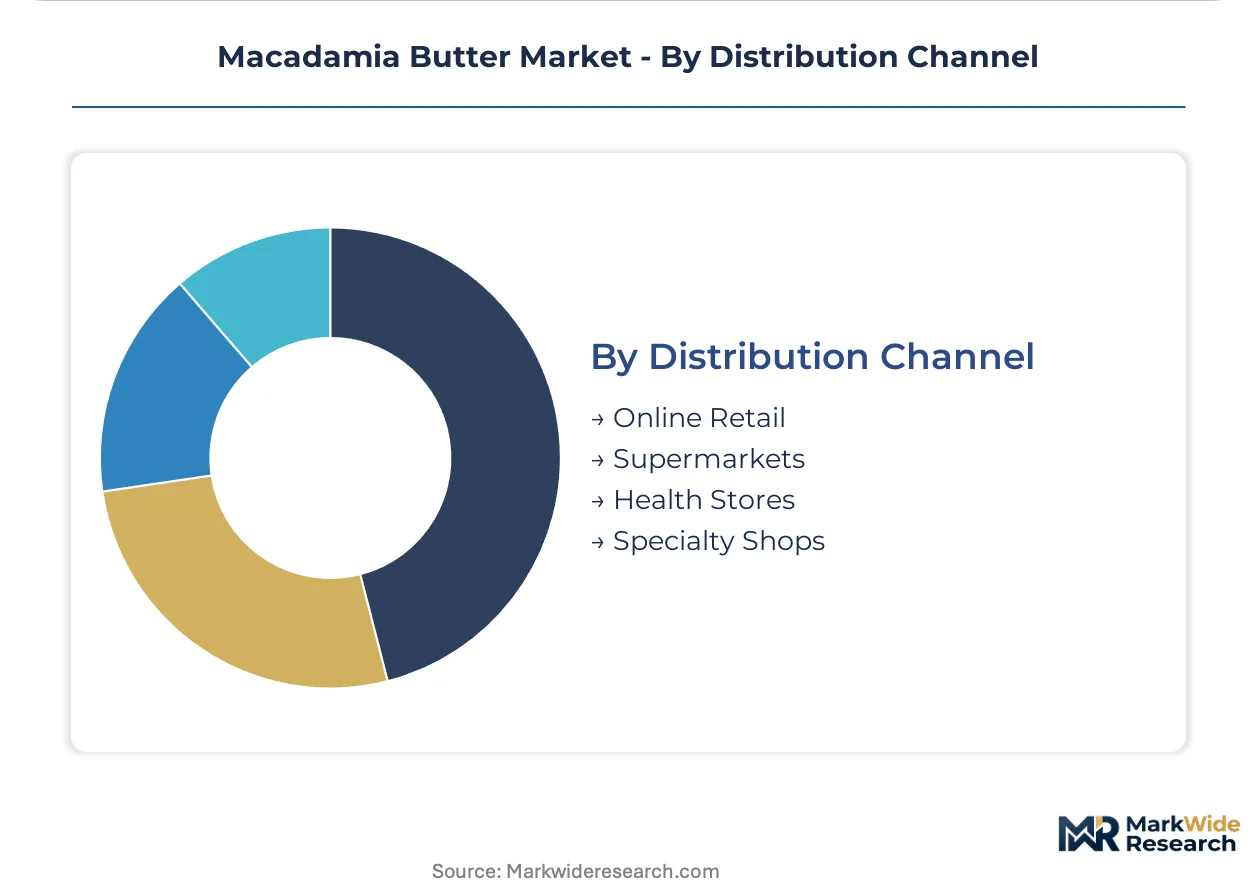
Distribution Channel:
Margin structure diverges sharply between slotting-fee-burdened retail and direct-to-consumer platforms capturing lifetime value.
- Online Retail:Auto-replenishment platforms bypass conventional retail slotting fees, with California and New South Wales households driving recurring subscription revenue for organic-certified lines.
- Supermarkets:Mass retail placement demands EFSA-compliant health claim substantiation or generic wellness positioning, bifurcating premium from commodity tiers.
- Health Stores:Staff-curated assortments favor raw and HPP-treated variants with transparent supply chain documentation.
- Specialty Shops:Limited SKU environments concentrate on flavored and single-origin products with experiential sampling programs.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia supplies the bulk of raw kernel while the United States absorbs the highest finished-product value. This production-consumption divide shapes trade flows and regulatory compliance burdens across origin and destination markets.
Australia
Queensland's Bundaberg and Gympie clusters host the world's deepest macadamia processing infrastructure, with cold-press capacity expanding to serve California and Japanese health food channels. FSANZ aflatoxin limits function as a non-tariff barrier that blocks Kenyan and South African competitors from Australian distribution networks. Byron Bay artisan producers deploy HPP-treated raw butter lines that command refrigerated logistics premiums in Sydney and Melbourne specialty retail.
United States
Hawaii's Big Island organic acreage expansion loosens supply constraints for USDA-certified clean-label product lines targeting keto bakery reformulations. FDA food labeling requirements compress formulation timelines, forcing rapid emulsifier substitution with single-ingredient alternatives. California's Santa Barbara cluster anchors direct-to-consumer subscription platforms that bypass conventional retail slotting fees through auto-replenishment models.
Belgium
Swiss and Belgian chocolatiers test macadamia butter as cocoa butter extenders in praline fillings, sourcing through long-term contracts with traceable Australian processors. EFSA cardiovascular health claim substantiation requirements bifurcate premium positioning from generic wellness claims in EU retail. Brussels-based industrial buyers concentrate volume with lot-traceable Queensland and Hawaiian origins for Michelin-tier restaurant group supply agreements.
Japan
Tokyo and Osaka pastry chefs specify single-origin macadamia butter by processor name, displacing commodity purchasing in high-end restaurant groups where menu provenance disclosure is mandatory. METI standards for food additive labeling intersect with EFSA-aligned health claim frameworks for imported specialty spreads. Kanto region distribution networks prioritize HPP-treated raw variants for refrigerated health store channels.
South Africa
KwaZulu-Natal and Mpumalanga growing regions face FSANZ exclusion from Australian markets despite competitive raw material costs due to aflatoxin maximum residue limits. Domestic processors redirect volumes toward EU confectionery and Middle East foodservice accounts with less stringent origin restrictions. Cape Town export infrastructure struggles with cold-chain integrity for enzyme-active raw butter shipments to European specialty buyers.
Macadamia Butter Market Competitive Landscape
Capital-heavy processors with dedicated cold-press and roasting infrastructure compete with asset-light brand builders that outsource milling to Australian or Hawaiian contract manufacturers. The market structure fragments across three tiers: integrated origin-producers controlling kernel supply, specialist millers with temperature-controlled lipid stabilization expertise, and direct-to-consumer brands capturing subscription lifetime value. Strategic archetypes include Queensland-based volume processors, California-centric organic certifiers, and European confectionery-focused ingredient suppliers. Competitive moves concentrate on backward integration into organic cultivation and HPP technology licensing for refrigerated shelf-life extension.
Among origin-integrated specialists, Torere Macadamias anchors the New Zealand-Australian nexus with captive kernel supply, while MaraNatha exemplifies the organic distribution network archetype through recurring auto-ship retention. Wilderness Poets occupies the premium transparency tier with small-batch sourcing documentation that commands loyalty in health-conscious segments. These three represent distinct competitive vectors: geographic integration, subscription infrastructure, and narrative-driven premium positioning.
| Leading Market Players |
|---|
| MaraNatha |
| Futter's Nut Butters |
| Wilderness Poets |
| Big Spoon Roasters |
| Woodstock Foods |
| Yumbutter |
| Carley's of Cornwall Ltd |
| Tiny Isle |
| Torere Macadamias |
| Others |
Supply & Pricing Matrix
Chef-driven procurement specifications in Michelin-tier restaurant groups are forcing processors to abandon blended-origin sourcing in favor of single-origin lot-traceability, concentrating supply with Australian and Hawaiian millers who command premium contract terms. This specification tightening compresses margin pools for commodity handlers while rewarding cold-press specialists with temperature-controlled lipid stabilization expertise.
Pricing Analysis
Margin tightening in raw butter tiers reflects HPP equipment amortization costs and refrigerated logistics premiums that roasted variants avoid. Three-tier pricing structure across premium single-origin, standard traceable, and economy blended levels separates contract manufacturers by certification grade and volume scale. Cost-down pressure on commodity roasted butter accelerates as almond and cashew pastes undercut macadamia in price-sensitive bakery accounts. Industrial food manufacturers exhibit highest price sensitivity; artisan chocolatiers and subscription direct-to-consumer channels show lowest.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-controlled returns of enzyme-active raw butter remains underdeveloped outside California and New South Wales, forcing write-offs when cold-chain integrity fails. Kernel supply concentrates in Australia's Queensland clusters and Hawaii's Big Island, with South African origins blocked from Australian distribution by FSANZ aflatoxin limits. Processing draws from specialized cold-press milling systems, dry-roasting infrastructure, and HPP treatment lines. Single-source vulnerability to Queensland harvest yield swings creates margin unpredictability for contract manufacturers. Distribution runs through direct-to-consumer subscription platforms, specialty retail, and industrial long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as processors pursue captive kernel supply to secure margin control against input cost volatility from Queensland harvest swings.
For Market Incumbents: Hedge against almond and cashew substitution in bakery accounts by locking long-term offtake with Hawaiian organic cooperatives. Deepen cold-press technician training pipelines to defend specialized milling capacity against competitor replication. FSANZ compliance investment functions as a moat against Kenyan and South African entrants. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms in California and New South Wales to bypass supermarket slotting fees and capture recurring revenue. Target Belgian and Swiss confectionery clusters testing macadamia butter as cocoa butter extenders, where specification behavior favors new traceable suppliers. White-space exists in USDA Organic-certified HPP-treated raw butter for refrigerated health store channels. For Investors and Strategic Acquirers: The window for entry favors origin-integrated processors with captive Queensland or Hawaiian kernel supply and installed HPP capacity. Long-term viability hinges on backward integration into organic cultivation and proprietary refrigerated distribution infrastructure. Watch FDA clean-label enforcement intensity and EFSA cardiovascular claim substantiation requirements as inflection indicators for premium positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Hawaiian acreage expansion loosens supply constraints for certified-clean-label product lines. |
| HPP Technology Licensing | Byron Bay and Santa Barbara producers justify refrigerated shelf-life premiums through safety-nutrition convergence. |
| Direct-to-Consumer Subscription Launch | California and New South Wales auto-replenishment platforms bypass retail slotting fees. |
| Single-Origin Specification Contracts | Michelin-tier restaurant groups in France and Japan mandate processor-name transparency. |
| EFSA Health Claim Substantiation Consortium | Pooled clinical trial funding shares cardiovascular benefit language compliance costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across macadamia processors, executive pastry chefs at Michelin-tier restaurant groups, health store category buyers, and cold-chain logistics operators. FDA food labeling guidance, EFSA nutrition and health claims regulations, FSANZ aflatoxin standards, and Australian Bureau of Agricultural and Resource Economics harvest reports supplied secondary validation. Bottom-up volume modeling triangulated against top-down value estimates.
Granularity-level modeling operated at product type, end user, and distribution channel dimensions, with additional segmentation by organic certification status and HPP treatment. CAGRs across the analysis window derived from trend extrapolation of kernel supply expansion, keto bakery reformulation penetration, and subscription platform adoption curves. Forecast inputs incorporated Queensland harvest yield volatility, Hawaiian organic acreage ramp rates, and EFSA substantiation timeline uncertainty.
The model assumes a particular technology adoption path; alternative pathways for high-pressure processing scale-up would alter the outlook for raw butter premium retention. Forecasts reflect assumptions around clean-label enforcement continuity, chef specification behavior persistence, and refrigerated infrastructure investment trajectories. Material deviation in Queensland climate patterns, FSANZ aflatoxin limit revisions, or FDA emulsifier ban timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Breadnut Market