
 Crispy Fruit Chips Market | 2026-2036
Crispy Fruit Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Crispy Fruit Chips Market Outlook
Specialty retail and direct-to-consumer channels is reshaping how crispy fruit chips reach buyers, bypassing traditional grocery gatekeepers. PepsiCo leverages its Frito-Lay distribution infrastructure to secure shelf dominance in conventional supermarkets. Crispy Green specializes in premium freeze-dried offerings, anchoring its brand in health food boutiques and airport kiosks. SunOpta extends its private-label manufacturing capabilities to serve emerging organic brands seeking co-packing partnerships.
Crispy fruit chips are thin, dehydrated or freeze-dried slices of whole fruit, typically processed at moisture levels below five percent to achieve shelf-stable crunch without frying oils or artificial preservatives. These products serve commercial purposes as clean-label alternatives to conventional potato and corn snacks in school lunch programs, corporate wellness vending, and airline catering portfolios. Apple chips lead volume in North American retail due to familiar flavor profiles and year-round raw material availability, while mango chips represent the fastest-growing product type driven by Southeast Asian supply chains and tropical positioning. Stand-up pouches with resealable closures capture the dominant packaging share, though resealable bags are gaining traction in club-store formats where bulk value messaging resonates with fitness enthusiasts.
FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions and supplier qualification timelines for domestic manufacturers. EFSA health claim regulations in Europe restrict how brands communicate glycemic benefits, forcing reformulation toward higher-fiber blends. Stakeholders must monitor evolving state-level extended producer responsibility laws for flexible packaging, as these will determine whether multi-layer pouch structures remain economically viable or trigger mandatory material redesigns.
Market Dynamics
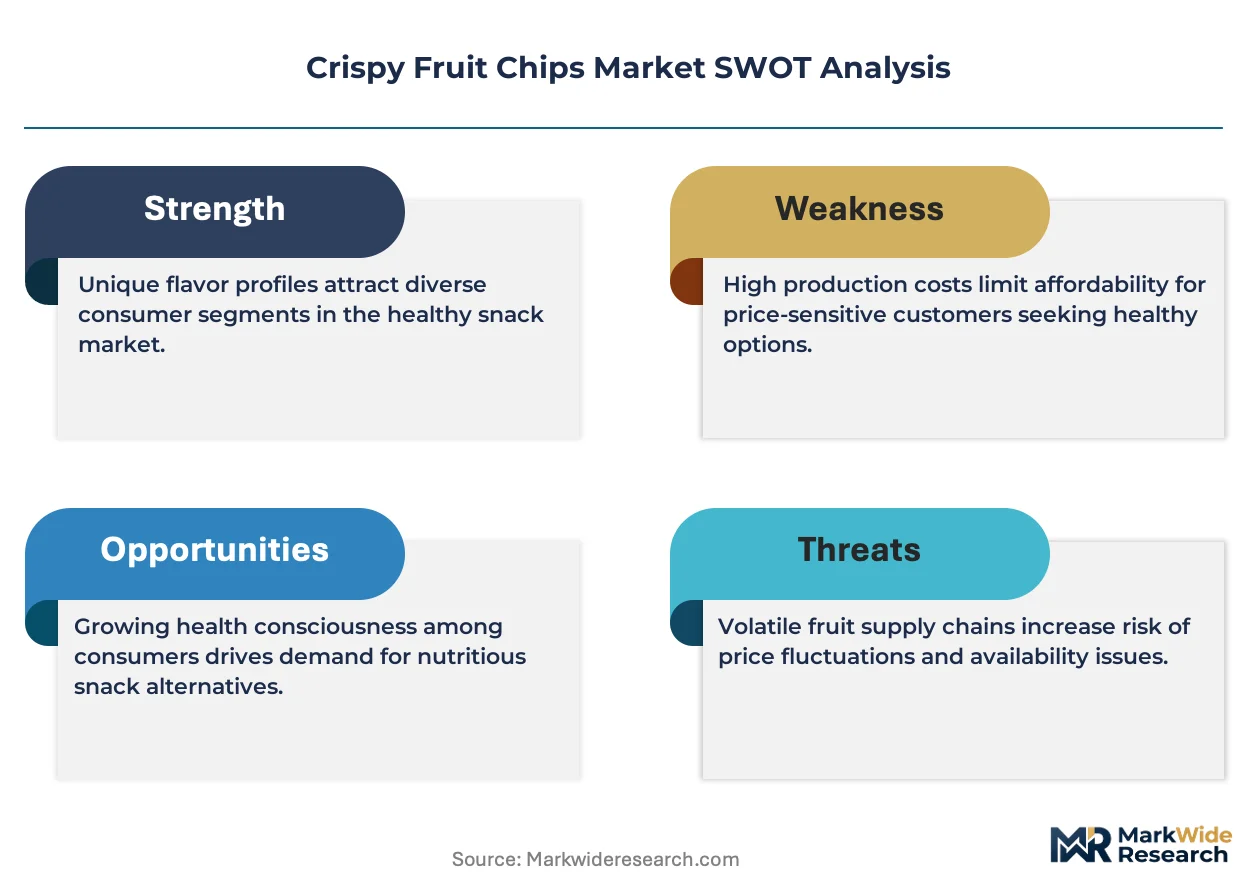
Freeze-drying technology diffusion is compressing production costs for shelf-stable fruit snacks, enabling mid-tier brands to match premium texture profiles that previously required capital-intensive equipment. This equipment democratization is redrawing competitive boundaries between private-label manufacturers and branded incumbents.
Growth Catalysts
- Clean-label mandates:FDA and EFSA guidelines on artificial additive disclosure are accelerating reformulation toward single-ingredient fruit profiles. School nutrition directors now specify zero-preservative snack options for federal meal programs.
- Airline catering recovery:Premium cabin service reinvestment is expanding procurement of lightweight, non-perishable fruit accompaniments. Singapore Airlines and Emirates have added freeze-dried mango to long-haul premium economy rotations.
- Subscription logistics infrastructure:Cold-chain-free fulfillment networks enable direct-to-consumer brands to bypass retail slotting fees. Shopify fulfillment centers in Texas and Ohio now stock ambient fruit chip SKUs for same-day delivery zones.
Market Restraints
- Apple concentrate price volatility:Washington State frost damage and Chinese import tariff schedules create 15-20% input cost swings for North American processors. Hedging instruments for agricultural commodities remain underdeveloped in this category.
- Single-origin supply concentration:Philippine dried mango processing clusters around Cebu and Davao, exposing buyers to typhoon disruption and port congestion. Alternative sourcing from Thailand or Vietnam requires 18-month grower qualification timelines.
- Moisture barrier technical limits:Current biodegradable film structures fail to maintain sub-5% moisture content beyond 90 days, forcing continued reliance on multi-layer petroleum-based laminates.
Strategic Opportunities
- Indian urban premium snacking:FSSAI clean-label recognition and Reliance Retail expansion create first-mover positioning in Mumbai and Bangalore airport lounges. Local guava and jackfruit varieties offer differentiation against imported apple SKUs.
- Corporate wellness vending:Fortune 500 campus refreshment contracts are unbundling traditional soda-and-chip portfolios. Cisco and Salesforce procurement teams now evaluate fruit chip suppliers against sodium and added-sugar thresholds.
- EU Green Deal packaging mandates:Extended producer responsibility fee structures favor mono-material pouch designs. Early compliance investments unlock preferred supplier status with Carrefour and Ahold Delhaize sustainability procurement gates.
Industry Challenges
- Freeze-dry operator skill scarcity:Equipment calibration for tropical fruit sugar content variations requires 18-month apprenticeship pipelines. Vocational programs in California's Central Valley and Spain's Valencia region cannot match hiring demand.
- Organic certification timeline compression:USDA National Organic Program inspector availability bottlenecks extend supplier onboarding from 90 to 240 days. Brands face raw material commitment without guaranteed certification completion.
- Legacy ERP integration friction:Batch-level traceability requirements for FDA Food Safety Modernization Act compliance clash with decades-old manufacturing execution systems at contract packers. Custom middleware development consumes 8-12% of IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crispy Fruit Chips Market |
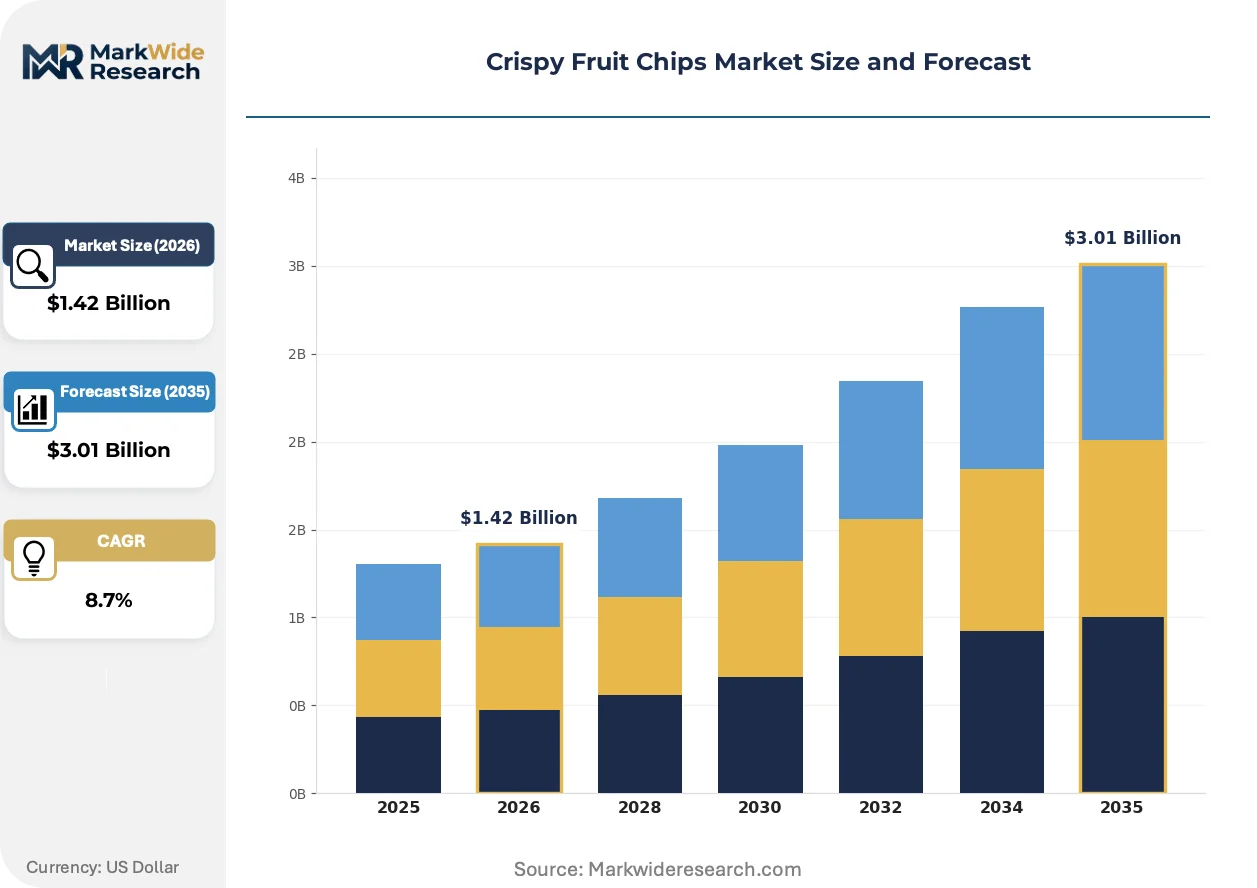
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple Chips, Mango Chips, Banana Chips, Pineapple Chips Packaging Type: Stand-Up Pouches, Resealable Bags, Cans, Boxes Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores End User: Children, Health-Conscious Adults, Fitness Enthusiasts, Snack Lovers |
| Companies Covered | PepsiCo, Inc., General Mills, Inc., Kellanov (formerly Kellogg Company), Crispy Green, Inc., The Kraft Heinz Company, Seneca Foods Corporation, Sunkist Growers, Inc., SunOpta Inc., Hain Celestial Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crispy Fruit Chips Market Strategic Shifts
Processing technology maturation and regulatory packaging mandates are converging to reshape product format possibilities and supply chain accountability requirements. These forces operate on different timelines but collectively determine which production configurations will remain viable.
Advanced microwave-assisted drying systems are rendering obsolete conventional hot-air dehydration for high-sugar fruits like pineapple and banana. Contract manufacturers in Mexico and Vietnam are adopting these units to reduce energy intensity by 40% while preserving volatile aromatic compounds. Premium private-label programs at Target and Whole Foods Market now specify microwave-dried origin claims as texture differentiators.
EFSA health claim regulations on glycemic index communications are forcing reformulation toward fiber-enriched blends. Brands can no longer reference blood sugar moderation without randomized clinical trial dossiers. German and Dutch retail buyers have responded by delisting single-fruit SKUs that cannot demonstrate 3g+ fiber per serving through apple peel inclusion or chia seed coating.
Direct-to-consumer subscription models are capturing health-conscious households before they enter conventional retail consideration sets. Brands like SnackNation and NatureBox curate quarterly fruit chip assortments that bypass supermarket shelf-space economics. This channel shift concentrates most visibly in coastal US metropolitan zones where fitness app user density correlates with snack box penetration rates.
Crispy Fruit Chips Market Segmentation
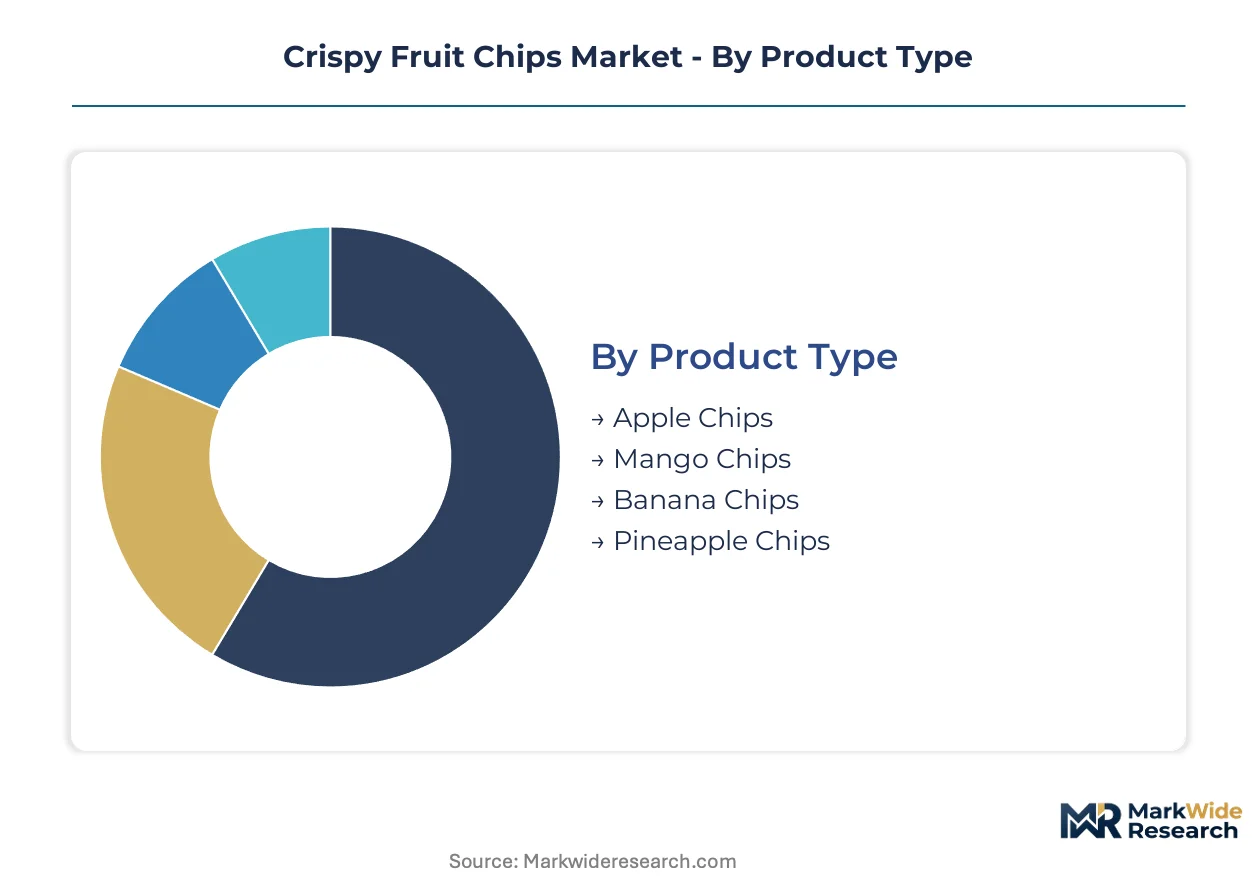
Segmentation in crispy fruit chips reveals how texture preferences, packaging convenience, and purchase occasion fragmentation create distinct profit pools. Manufacturers configure equipment and sourcing strategies differently for each slice, making segment selection a capacity commitment with multi-year payback horizons.
Product Type:
Cost tier positioning separates commodity dehydration from premium freeze-dried offerings, with equipment intensity and raw material sourcing geography determining margin architecture.
- Apple Chips:Sliced Washington or Chinese Fuji varieties dehydrated to sub-5% moisture content deliver familiar sweetness and year-round supply stability. North American school nutrition programs specify these for federal meal compliance due to established vendor relationships and predictable pricing.
- Mango Chips:Freeze-dried Philippine Carabao or Thai Nam Dok Mai varieties command premium shelf positioning through tropical flavor intensity and lower glycemic perception. Singapore Airlines and Emirates premium cabin procurement is rotating toward this SKU for lightweight service logistics.
- Banana Chips:Ecuadorian Cavendish slices processed through microwave-assisted drying systems reduce oil absorption versus traditional frying. Latin American contract manufacturers are expanding capacity for this segment.
- Pineapple Chips:Costa Rican MD-2 variety rings target smoothie bowl garnish and trail mix inclusion markets. Hawaiian origin claims support boutique health food store placement.
Apple Chips holds installed capacity. Mango Chips is rotating up the share rankings.
Packaging Type:
Application environment dictates barrier specifications, with shelf-life requirements and retail format constraints driving material selection tradeoffs.
- Stand-Up Pouches:Multi-layer PET-PE laminates with resealable zipper closures dominate conventional grocery and club store formats. The structure supports 12-month ambient stability for high-turnover SKUs while accommodating vibrant rotogravure printing for shelf differentiation.
- Resealable Bags:Lower gauge mono-material constructions serve fitness enthusiast bulk purchasing through warehouse clubs and direct-to-consumer subscription fulfillment. Shopify fulfillment centers in Texas and Ohio prioritize this format for dimensional weight efficiency.
- Cans:Composite paperboard cylinders with foil membranes target gift and seasonal premium positioning. Japanese department store food halls specify this format for omiyage culture compliance.
- Boxes:Recyclable paperboard with inner liner bags serves corporate wellness vending and airline catering portion control requirements. Cisco and Salesforce campus refreshment contracts evaluate this format for sustainability procurement scoring.
Stand-Up Pouches commands current volume leadership. Resealable Bags is gaining fastest in channel expansion.
Distribution Channel:
Customer type concentration varies sharply by channel, with purchase frequency and basket composition determining promotional investment economics.
- Supermarkets:Frito-Lay and PepsiCo infrastructure secures end-cap and checkout lane placement for mass-market apple chip SKUs. Slotting fee structures favor established brands with proven velocity metrics.
- Online Retailers:Amazon and Thrive Market algorithms prioritize subscription-enabled SKUs with repeat purchase velocity. Health-conscious household data from fitness app partnerships enables targeted acquisition.
- Health Food Stores:Crispy Green and specialty freeze-dried brands anchor premium positioning through non-GMO and organic certification visibility. Whole Foods Market regional buyers enforce clean-label compliance gates.
- Convenience Stores:Single-serve pouches at sub-dollar price points target impulse snacking occasions. 7-Eleven and Circle K distribution requires DSD logistics compatibility.
Supermarkets maintains infrastructure dominance. Online Retailers is climbing the fastest in customer acquisition efficiency.
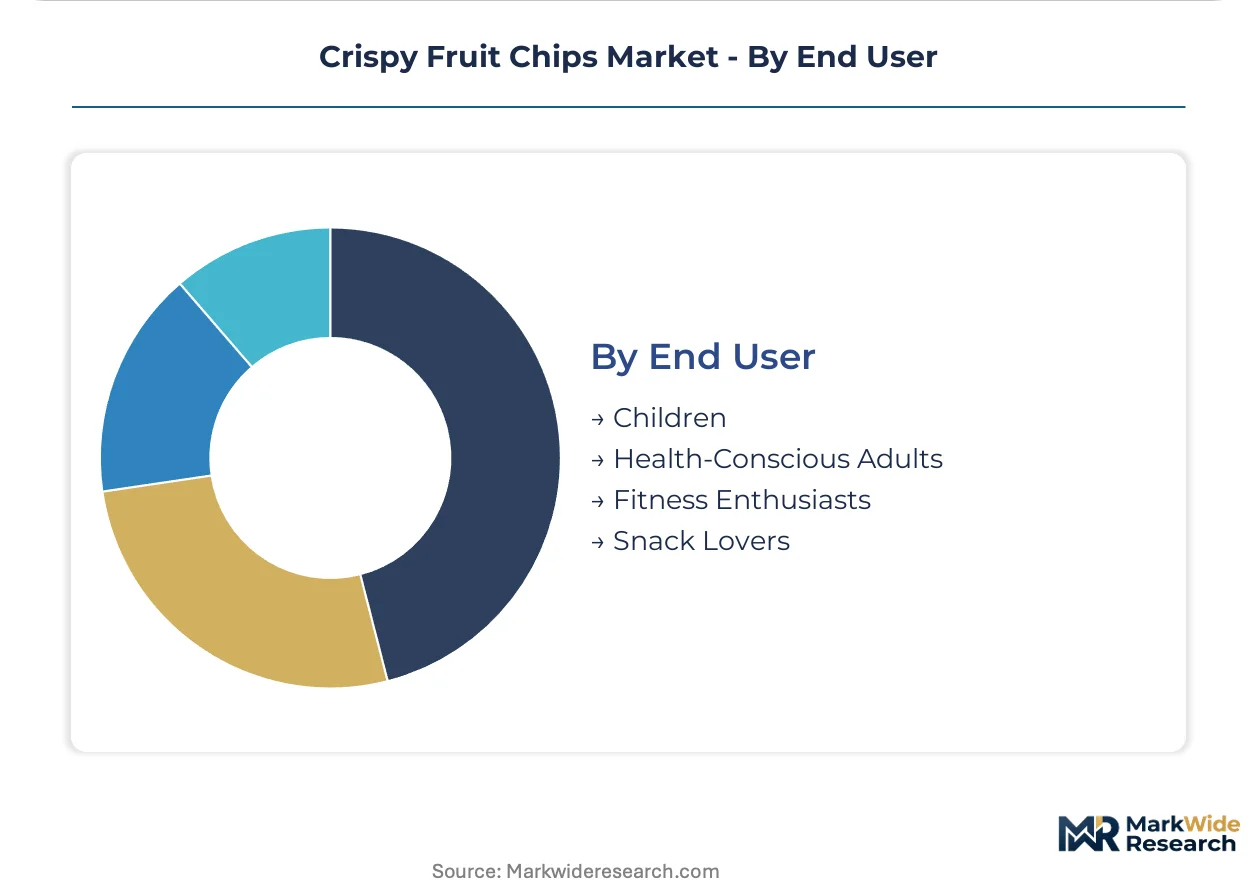
End User:
Volume consumption patterns and nutritional priority hierarchies segment the buyer base into distinct formulation and messaging targets.
- Health-Conscious Adults:Clean-label scrutiny drives single-ingredient preference and rejection of added sugars or sulfites. FDA nutrition labeling transparency supports purchase confidence for this cohort.
- Fitness Enthusiasts:Macro-tracking behavior favors portion-controlled packaging with precise carbohydrate and fiber disclosure. MyFitnessPal integration and protein pairing recommendations influence brand selection.
- Children:School lunch program eligibility requires USDA Smart Snacks compliance on sodium, fat, and sugar thresholds. Cartoon licensing and flavor novelty drive at-home purchase.
- Snack Lovers:Texture craving and flavor variety seeking support multi-pack assortments and limited-edition seasonal releases. Social media unboxing content amplifies trial generation.
Health-Conscious Adults anchors current revenue concentration. Fitness Enthusiasts is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling mandates and USDA organic certification standards in the United States are accelerating clean-label reformulation across export-oriented production clusters. EFSA health claim restrictions in Europe and FSSAI recognition frameworks in India are creating divergent compliance pathways that reshape supplier qualification timelines.
United States
Premium snacking culture and direct-to-consumer subscription channels drive demand concentration on the coasts. FDA Food Safety Modernization Act batch-level traceability requirements extend supplier onboarding timelines. Washington State apple processing clusters and California Central Valley freeze-dry operations anchor North American production capacity.
Germany
EFSA glycemic index communication restrictions force fiber-enriched reformulation toward apple peel inclusion. EU Green Deal extended producer responsibility fee structures favor mono-material pouch designs. Bavarian contract manufacturers invest in microwave-assisted drying systems to serve Carrefour and Ahold Delhaize sustainability procurement gates.
India
FSSAI clean-label recognition and Reliance Retail expansion create first-mover positioning in Mumbai and Bangalore airport lounges. Central government PLI scheme incentives for food processing equipment accelerate technology adoption. Guava and jackfruit processing clusters in Maharashtra and Karnataka offer differentiation against imported apple SKUs.
Philippines
Singapore Airlines and Emirates premium cabin procurement rotates toward freeze-dried Carabao mango for lightweight service logistics. Typhoon exposure in Cebu and Davao processing clusters drives alternative sourcing qualification timelines. Bureau of Food and Drug Administration export certification requirements shape supplier documentation standards.
Japan
Department store food hall omiyage culture specifies composite paperboard cylinder packaging for gift positioning. METI standards for reduced-sugar processed foods influence reformulation targets. Tokyo-Osaka metropolitan corridor retail buyers enforce clean-label compliance gates for non-GMO and organic certification visibility.
Crispy Fruit Chips Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: diversified snack conglomerates with frozen distribution infrastructure, specialized freeze-dried premium brands with health food channel anchoring, and private-label contract manufacturers with co-packing flexibility. Competitive moves concentrate on portfolio diversification into clean-label formats and geographic expansion through direct-to-consumer subscription logistics.
Within the diversified conglomerate tier, PepsiCo leverages Frito-Lay infrastructure for mass-market shelf dominance while General Mills occupies a position bridging conventional retail and emerging wellness channels. Crispy Green exemplifies the specialized premium archetype through health food boutique and airport kiosk anchoring. SunOpta represents the contract manufacturing vector with private-label capabilities serving emerging organic brands seeking co-packing partnerships.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| General Mills, Inc. |
| Kellanov (formerly Kellogg Company) |
| Crispy Green, Inc. |
| The Kraft Heinz Company |
| Seneca Foods Corporation |
| Sunkist Growers, Inc. |
| SunOpta Inc. |
| Hain Celestial Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Washington State apple concentrate processing clusters anchor North American input costs, concentrating margin capture downstream with freeze-dried mango specialists who command premium positioning through Philippine supply scarcity. Commodity dehydration operators face compressed spreads when apple concentrate swings disrupt hedging capacity.
Pricing Analysis
Volume-discount tiering structures separate subscription-direct brands from club-store bulk formats and conventional grocery single-serve placements. Price differentiation hinges on freeze-dry certification tier and organic USDA seal status, with premium tiers capturing health-food boutique positioning. Pricing pressure stems from apple concentrate volatility and Chinese tariff exposure, squeezing mid-tier dehydration operators. Corporate wellness vending buyers exhibit lowest price sensitivity, while convenience store impulse purchasers drive hard bargain thresholds.
Supply Chain Analysis
Export-control regime angles on freeze-dry technology transfer limit equipment flows to Southeast Asian contract manufacturers, constraining capacity expansion timelines. Geographic supply concentration centers on Washington State apple processing, Cebu and Davao mango drying clusters, and California Central Valley freeze-dry operations. Raw material dependencies include Fuji apple concentrate, Carabao mango pulp, and Cavendish banana feedstock. Single-origin typhoon exposure in Philippine processing clusters creates structural vulnerability. Distribution runs through Frito-Lay direct-store-delivery infrastructure for mass-market penetration and Shopify fulfillment networks for subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh fruit convenience packs and refrigerated snacking alternatives threaten crispy fruit chip shelf space as clean-label substitution accelerates. Incumbents must navigate this displacement pressure through format innovation and channel control reinforcement.
For Market Incumbents: Harden freeze-dry operator apprenticeship pipelines in California's Central Valley to offset skill scarcity bottlenecks. Deepen backward integration into Philippine mango grower networks to reduce typhoon exposure. Secure USDA organic certification pre-commitments before inspector availability constraints extend supplier onboarding timelines.
For New Entrants and Emerging Players: Pursue corporate wellness vending white space at Fortune 500 campuses where Cisco and Salesforce procurement teams unbundle traditional soda-and-chip portfolios. Target Indian airport lounge channels through FSSAI clean-label recognition and Reliance Retail expansion. Launch through fitness app partnership integrations to capture health-conscious households before retail consideration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing freeze-dry equipment and co-packing flexibility. Long-term viability hinges on mono-material packaging compliance investments ahead of EU Green Deal mandates. Watch extended producer responsibility fee structures as the inflection signal determining multi-layer pouch economic viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Dry Equipment Acquisition | Democratized texture capabilities compress mid-tier brand cost structures against premium incumbents. |
| Mono-Material Packaging Redesign | Early EU Green Deal compliance unlocks preferred supplier status with Carrefour and Ahold Delhaize. |
| Direct-to-Consumer Subscription Launch | Shopify fulfillment center stocking bypasses retail slotting fees and captures coastal fitness households. |
| Corporate Wellness Vending Contract | Cisco and Salesforce procurement gates evaluate suppliers against sodium and added-sugar thresholds. |
| Indian Airport Lounge Channel Entry | FSSAI clean-label recognition and Reliance Retail expansion create first-mover positioning in Mumbai. |
Study Parameters
Operator-level perspectives from freeze-dry equipment technicians, contract manufacturing plant managers, health food store category buyers, airline catering procurement officers, and school nutrition program directors anchored the qualitative base. Secondary validation drew from FDA nutrition labeling guidance documents, USDA National Organic Program certification records, EFSA health claim regulatory filings, Nielsen retail audit data, and customs trade records. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, packaging format, distribution channel, and end-user archetype. CAGRs derived from equipment adoption curves, channel shift velocities, and regulatory compliance timeline compressions. Forecast inputs incorporated freeze-dry technology diffusion rates and extended producer responsibility fee structure implementations.
Sensitivities concentrate around apple concentrate price volatility, Philippine typhoon disruption frequency, and biodegradable film moisture barrier technical limits. Forecasts reflect assumptions on equipment democratization pace and regulatory packaging mandate enforcement timelines. Material shifts in FDA Food Safety Modernization Act traceability requirements or EU Green Deal fee structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Extruded Snack Food Market
Snacks
South East Asia Snack Bar Market
Snacks
Vegan Snacks Market
Snacks
Refrigerated Snacks Market
Snacks
Dairy Protein Crisps Market
Snacks
Italy Energy Bar Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Low Fat Crackers Market
Snacks
Tortilla Mix Market
Snacks
North America Pretzel Market
Snacks
South Korea Snack Bar Market
Snacks
Thailand Snack Bar Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
Cereal Bars Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Healthy Snacks Market