
 Baking Mix, Base and Concentrate Market | 2026-2036
Baking Mix, Base and Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Baking Mix, Base and Concentrate Market Analytics
Alternative flours is decoupling from premium pricing tiers as scale economies in almond and tapioca processing compress unit costs across gluten-free lines. General Mills leverages its vertically milled grain network to captive-supply wheat flour bases for industrial bakeries. Puratos Group anchors European artisan channels through sourdough concentrate expertise. Cargill competes in clean-label sweetening systems that reduce added sugar declarations in cake mixes.
Baking mixes, bases, and concentrates comprise pre-formulated dry or semi-dry blends requiring only the addition of water, fat, or eggs to produce finished baked goods, with moisture content typically below 14 percent for powder forms to ensure shelf stability and prevent microbial proliferation. Their primary commercial purpose is to standardize output quality while reducing labor, equipment, and ingredient inventory burdens across bakery operations. Cake mix occupies the largest value pool due to celebration-driven purchasing frequency and seasonal demand spikes, yet gluten-free mix records the fastest expansion as celiac diagnoses and voluntary wheat avoidance broaden the addressable consumer base. Powder form dominates manufacturing economics and logistics efficiency, though liquid concentrates gain traction in food service for equipment-compatible dispensing and waste reduction.
FDA labeling rules and USDA organic certification requirements govern ingredient disclosure and marketing claims in the United States, while the EU Green Deal and EFSA health claim evaluations shape reformulation priorities across European formulations. These frameworks elevate compliance costs for cross-border suppliers but simultaneously reward early movers with approved health positioning and clean-label credentials. Stakeholders must monitor evolving threshold definitions for added sugar and whole grain content, as pending regulatory revisions will force portfolio restructuring across both retail and food service channels.
Market Dynamics
Clean-label reformulation mandates under EFSA and the EU Green Deal are forcing ingredient transparency upgrades across European supply chains, while US retail consolidation concentrates volume pull among fewer national distributors.
Growth Catalysts
- Post-pandemic home baking retention:Convenience-oriented cooking habits solidified during lockdowns continue driving repeat purchases of cake and bread mixes through grocery and direct-to-consumer channels.
- EFSA health claim evaluations:Approved positioning for reduced-sugar and whole-grain formulations enables premium shelf placement and marketing differentiation across EU member states.
- Celiac diagnosis expansion:Rising clinical identification of gluten intolerance broadens the addressable base for almond, tapioca, and rice flour-based alternatives beyond niche health segments.
Market Restraints
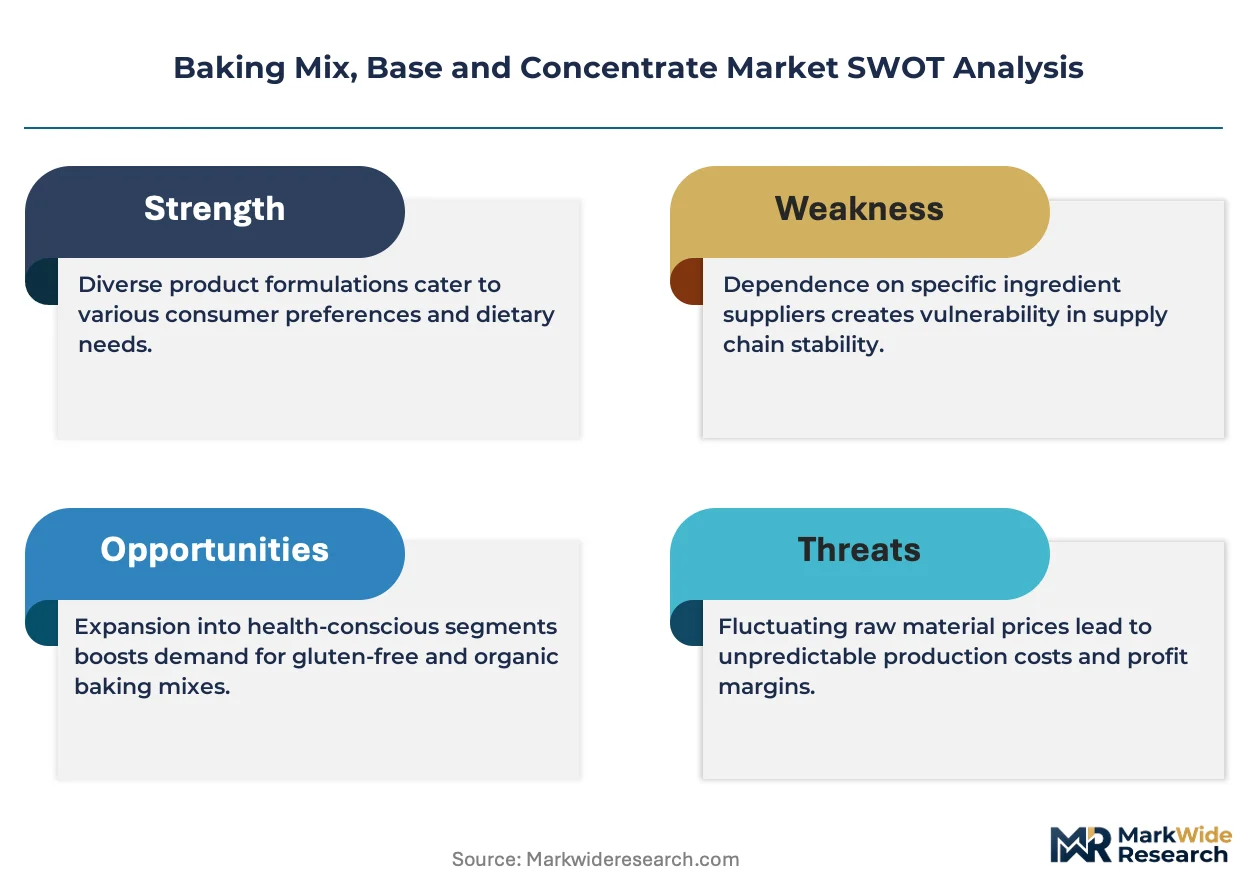
- Input cost volatility:Almond and specialty grain prices fluctuate with California water allocation cycles and Ukrainian sunflower oil disruptions, compressing margins on gluten-free lines.
- Supply concentration risk:Vertically milled wheat flour networks in the US Great Plains create captive dependencies for industrial bakeries seeking volume guarantees.
- Regulatory friction:Pending USDA organic certification threshold revisions for whole grain content force portfolio restructuring costs across dual-certified product lines.
Strategic Opportunities
- Food service liquid concentrate penetration:Equipment-compatible dispensing systems reduce waste and labor in commercial bakery operations, opening white space beyond powder-dominant retail.
- EU Green Deal ingredient transparency incentives:Early movers capturing clean-label credentials gain preferential listing terms with sustainability-focused retail banners in Germany and France.
- Sourdough concentrate expertise gaps:Artisan channel anchoring through fermented base technology remains underexploited outside established European specialists.
Industry Challenges
- Reformulation talent scarcity:Food scientists capable of balancing moisture content below 14 percent with clean-label ingredient performance command premium compensation.
- Cross-border compliance timelines:Dual FDA and EFSA approval pathways for novel sweetening systems extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baking Mix, Base and Concentrate Market |
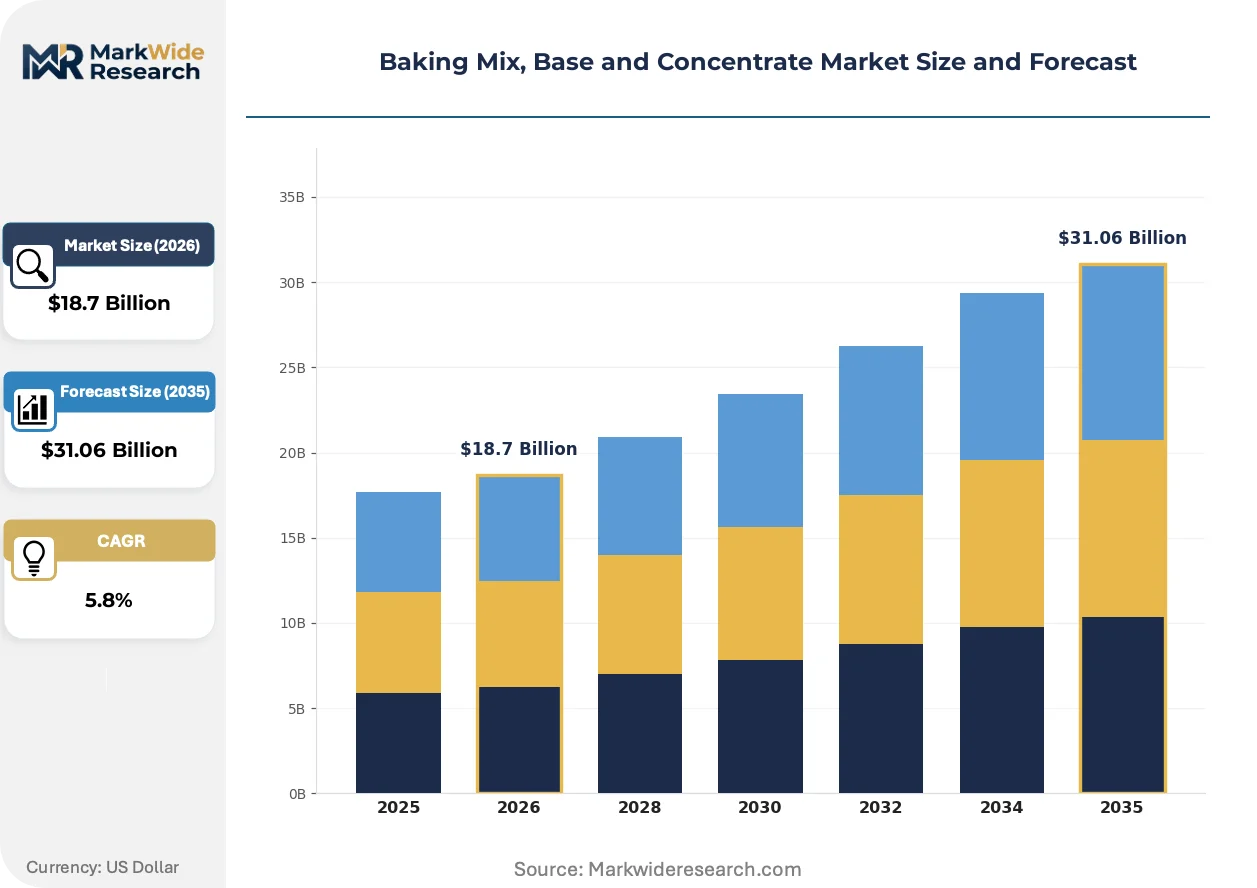
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cake Mix, Bread Mix, Gluten-Free Mix, Pancake Mix Ingredient Type: Wheat Flour, Almond Flour, Tapioca Starch, Sugar Form: Powder, Liquid, Ready-to-Use, Concentrate End User: Bakeries, Restaurants, Home Bakers, Food Manufacturers |
| Companies Covered | General Mills, ADM, Cargill, Puratos Group, Lesaffre Group, Associated British Foods, Dawn Foods, Bakels Group, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baking Mix, Base and Concentrate Market Evolving Landscape
Formulation science and distribution infrastructure are converging to reshape how baking inputs reach end-users, with regulatory pressure and channel fragmentation driving divergent innovation paths across geographies.
Encapsulated leavening systems stabilize reaction kinetics across extended shelf-life requirements. Industrial bakeries in the US Southeast are adopting these systems for just-in-time production scheduling. The technology is expanding into frozen dough applications where controlled release prevents premature expansion during cold chain transit.
EFSA added sugar threshold definitions are tightening ahead of pending EU Green Deal implementation timelines. Cake mix manufacturers must reformulate or face marketing claim restrictions in France, Germany, and Benelux markets. Mid-tier brands lacking R&D scale are exiting the celebratory baking segment rather than absorbing compliance costs.
Direct-to-consumer subscription models displace traditional grocery velocity metrics for specialty mix brands. Home bakers in coastal US metropolitan areas prioritize curated ingredient provenance over mass-market availability. This channel rotation concentrates marketing spend on digital acquisition rather than slotting fee negotiations.
Baking Mix, Base and Concentrate Market Segmentation
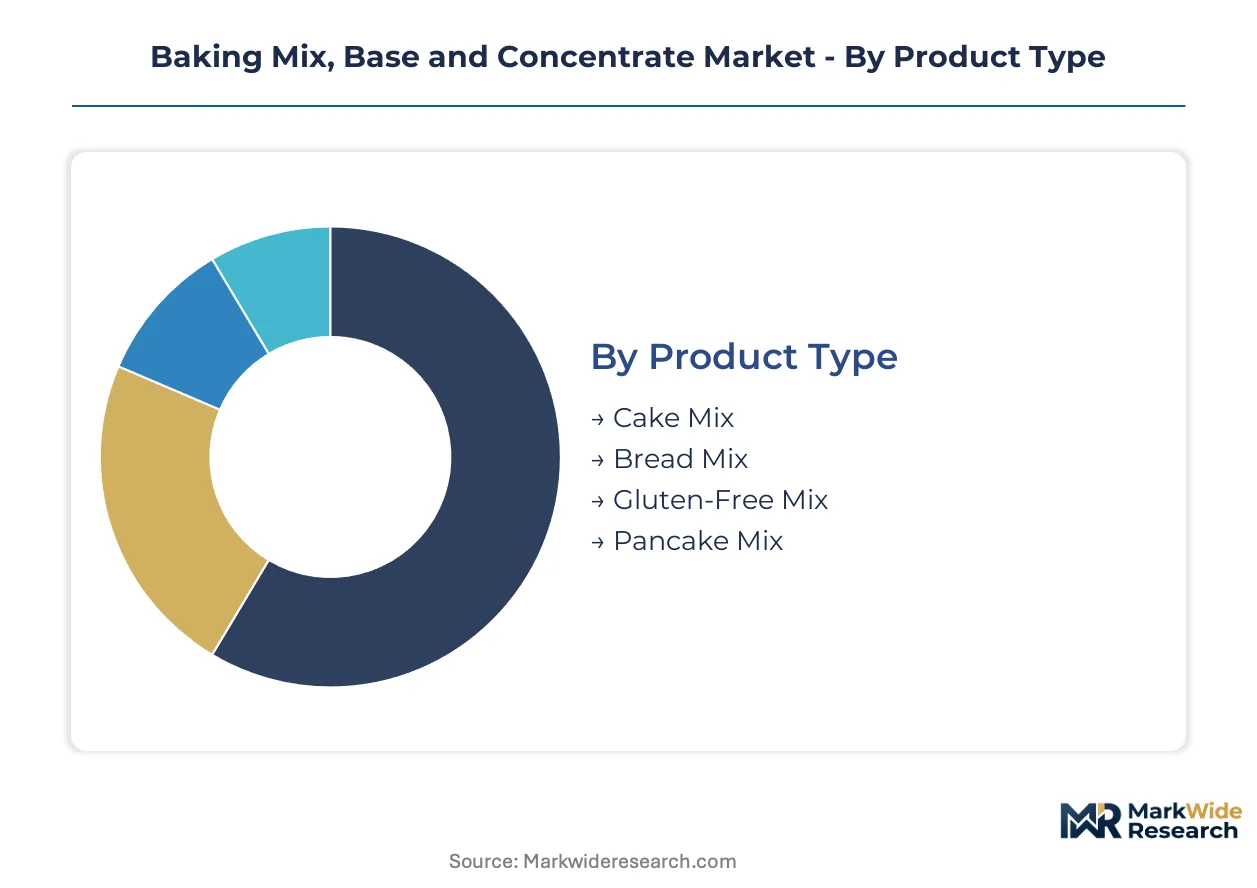
Segmentation in this market determines regulatory exposure and margin architecture. Powder forms face FDA moisture-content thresholds below 14 percent, while liquid concentrates navigate USDA pasteurization mandates. Ingredient sourcing choices—wheat versus almond versus tapioca—trigger divergent EFSA health claim eligibility and clean-label certification burdens.
Product Type:
FDA labeling rules govern celebratory baking claims, while EFSA added-sugar thresholds reshape formulation priorities across EU member states.
- Cake Mix:Pre-blended formulations requiring only fat and liquid addition, with moisture content engineered below 14 percent for shelf stability. Demand concentrates in United States retail channels driven by celebration-driven purchasing frequency and seasonal demand spikes.
- Bread Mix:Yeast-leavened or chemically-leavened bases standardized for consistent crumb structure and volume yield. Home bakers in coastal US metropolitan areas drive repeat purchases through direct-to-consumer subscription channels prioritizing provenance transparency.
- Gluten-Free Mix:Almond, tapioca, or rice flour-based alternatives formulated for celiac-safe production environments.
- Pancake Mix:Lower-complexity blends optimized for griddle-cooking applications with minimal equipment requirements.
Cake Mix sits at the top of the volume ranking, with Gluten-Free Mix climbing the fastest.
Ingredient Type:
Cost tiers separate commodity grain inputs from specialty flour alternatives, with water allocation cycles in California and Ukrainian supply disruptions driving margin volatility.
- Wheat Flour:Vertically milled grain networks in the US Great Plains deliver volume guarantees to industrial bakeries through captive supply arrangements. Food manufacturers anchor procurement around FDA-compliant identity standards for protein content and ash specifications.
- Almond Flour:Blanched and ground nut meal requiring allergen segregation protocols and California water-dependent sourcing. Premium pricing compression is accelerating as scale economies in almond processing expand gluten-free line accessibility.
- Tapioca Starch:Cassava-derived binding agent critical for texture restoration in gluten-free matrices.
- Sugar:Clean-label sweetening systems face pending USDA organic certification threshold revisions for added sugar declarations.
Wheat Flour dominates procurement volumes, though Almond Flour is gaining share fastest among reformulation-focused portfolios.
Form:
Customer type determines equipment compatibility requirements, with food service operators prioritizing waste-reduction features over retail shelf-stability engineering.
- Powder:Dry blends with sub-14 percent moisture content engineered for extended shelf life and microbial suppression. Manufacturing economics and logistics efficiency favor this format for grocery channel distribution and home baker pantry storage.
- Liquid:Pump-dispensed concentrates compatible with commercial bakery equipment and portion-control systems. Restaurants in the United States Southeast are adopting these formats for labor reduction and just-in-time production scheduling.
- Ready-to-Use:Fully hydrated doughs or batters requiring cold chain maintenance.
- Concentrate:High-solids semi-liquid bases dilutable at point of use for customized yield scaling.
Powder commands the highest shipment volumes, with Liquid expanding most quickly in food service penetration.
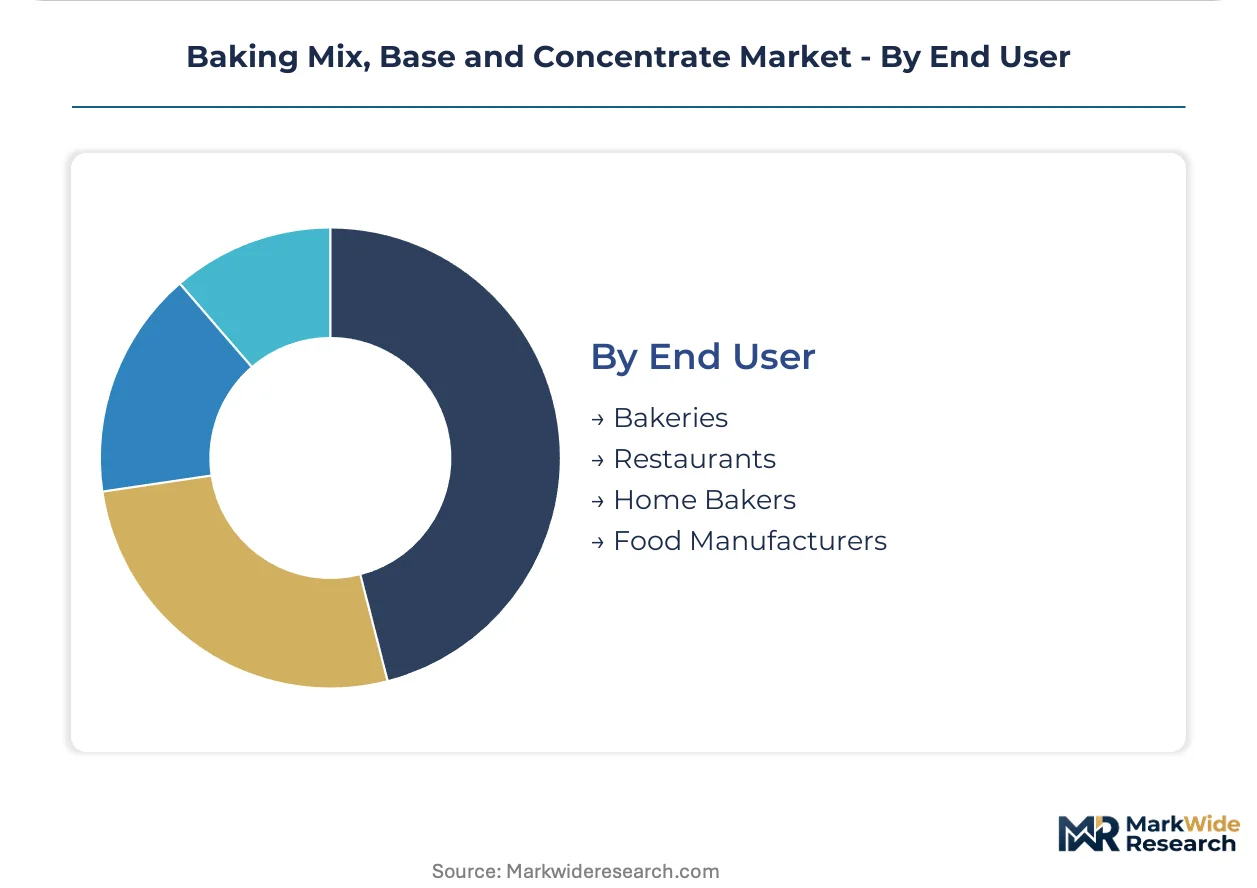
End User:
Supply concentration varies sharply across buyer categories, with industrial bakeries facing captive dependencies on vertically integrated flour networks while home bakers fragment across direct-to-consumer brands.
- Bakeries:Industrial and artisan operations requiring volume guarantees and consistent output quality through standardized base inputs. United States retail channel consolidation is concentrating volume pull among fewer national distributors serving this segment.
- Home Bakers:Convenience-oriented consumers solidifying post-pandemic cooking habits through repeat mix purchases. Coastal metropolitan areas in the United States prioritize curated ingredient provenance over mass-market grocery availability.
- Restaurants:Food service operations seeking equipment-compatible dispensing and waste reduction.
- Food Manufacturers:Co-packing and private-label producers requiring dual FDA-EFSA compliance for cross-border product lines.
Bakeries anchor procurement volumes, with Home Bakers following the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Great Plains vertically milled grain network anchors industrial bakery procurement volumes. FDA labeling rules and USDA organic certification requirements govern formulation transparency. EFSA health claim evaluations and EU Green Deal mandates reshape European reformulation priorities.
United States
Retail channel consolidation concentrates volume pull among fewer national distributors serving industrial bakeries. FDA moisture-content thresholds below 14 percent for powder forms enforce shelf-stability engineering standards. The Southeast region adopts liquid concentrate dispensing systems for commercial bakery waste reduction and labor efficiency.
Germany
Clean-label reformulation pressures under EFSA and EU Green Deal frameworks accelerate ingredient transparency requirements. The country's national food safety regulator enforces strict added-sugar threshold definitions ahead of implementation timelines. The Rhine-Ruhr industrial corridor hosts specialty milling operations supplying artisan bakery channels.
France
Celebration-driven cake mix purchasing frequency sustains premium positioning in retail channels. EFSA health claim evaluations enable marketing differentiation for reduced-sugar formulations. The Paris metropolitan area concentrates direct-to-consumer subscription brand activity targeting provenance-conscious home bakers.
United Kingdom
Post-pandemic home baking retention solidifies convenience-oriented cooking habits through repeat mix purchases. The country's national food standards agency aligns with evolving EU Green Deal ingredient transparency incentives. Greater London anchors direct-to-consumer brand marketing spend on digital acquisition rather than traditional grocery slotting.
China
Food service liquid concentrate penetration opens white space beyond powder-dominant retail formats. The country's national market regulator enforces dual carbon goals affecting packaging and logistics decisions. The Yangtze River Delta industrial cluster scales almond and tapioca processing for gluten-free line cost compression.
Baking Mix, Base and Concentrate Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers respond to post-pandemic home baking retention. The vendor base organizes around three tiers: multinational grain processors with captive supply networks, European artisan specialists with fermented base expertise, and direct-to-consumer brands bypassing traditional retail. Two strategic archetypes predominate: vertically integrated millers controlling wheat flour inputs, and clean-label formulators reducing added sugar declarations. M&A activity concentrates among regional bakery input suppliers, while strategic partnerships bridge food service equipment compatibility requirements.
Within the multinational processor tier, General Mills and Cargill exemplify scale-driven positioning through grain network control. Puratos Group occupies a position representing European artisan channel specialization. Associated British Foods anchors the diversified food conglomerate archetype with cross-category formulation capabilities. These three entities collectively illustrate the competitive spectrum from commodity grain supply through premium concentrate expertise.
| Leading Market Players |
|---|
| General Mills |
| ADM |
| Cargill |
| Puratos Group |
| Lesaffre Group |
| Associated British Foods |
| Dawn Foods |
| Bakels Group |
| Nestlé |
| Others |
Value Network & Pricing Analysis
Clean-label reformulation mandates under EFSA and the EU Green Deal are compressing formulation flexibility and forcing supply chains toward premium ingredient sourcing. Industrial bakeries seeking dual-certified organic and gluten-free inputs face tighter procurement constraints as California water cycles and Ukrainian sunflower oil disruptions amplify cost volatility.
Pricing Analysis
Input-cost pass-through from almond and specialty grain volatility is intensifying margin pressure across gluten-free tiers. Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified formulations from commodity wheat-based lines. Price differentiation rests on organic certification grade and volume scale commitments. Food service buyers exhibit highest price sensitivity due to thin operating margins, while direct-to-consumer home bakers tolerate premium positioning for provenance transparency.
Supply Chain Analysis
Single-source vulnerability sits with California almond processors and vertically integrated US Great Plains wheat milling networks. Raw material flows draw from United States grain belts, Brazilian tapioca cultivation zones, and Southeast Asian cassava processing hubs. Tariff exposure on sunflower-derived emulsifiers creates formulation substitution costs. Distribution runs through consolidated national grocery distributors and direct-to-consumer fulfillment centers serving coastal metropolitan demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA added-sugar threshold tightening ahead of EU Green Deal implementation timelines forces portfolio restructuring and creates compliance-driven demand for reformulation services.
For Market Incumbents: Anchor market position through backward integration into almond processing capacity and captive supply arrangements with California growers. Defend against specialty concentrate specialists by accelerating sourdough fermentation expertise acquisition. Prioritize dual FDA-EFSA approval pathway investment to compress cross-border launch cycles. For New Entrants and Emerging Players: Capture white space in food service liquid concentrate dispensing systems compatible with commercial bakery equipment. Target underpenetrated artisan channels in the United States Southeast where labor reduction demands outstrip supplier coverage. Deploy equipment partnership go-to-market models rather than slotting fee competition. For Investors and Strategic Acquirers: Asymmetric upside sits with clean-label formulators possessing approved EFSA health claim positioning and established European retail banner relationships. Five-to-ten year viability favors specialists with fermented base technology and regulatory approval velocity. Monitor USDA organic certification threshold revision timing as inflection indicator for portfolio restructuring volume.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA compliance enables premium shelf placement and marketing claim differentiation. |
| Food Service Liquid Concentrate Expansion | Equipment-compatible dispensing reduces waste and labor in commercial bakery operations. |
| Direct-to-Consumer Channel Development | Subscription models bypass consolidated grocery distributor gatekeeping in coastal metros. |
| Backward Integration into Almond Processing | California capacity captures scale economies compressing gluten-free line unit costs. |
| Sourdough Concentrate Expertise Acquisition | Fermented base technology anchors artisan channel positioning against commodity competitors. |
Research Methodology
Direct dialogue with baking mix procurement managers, food service operations directors, R&D formulation scientists, and retail category buyers grounds qualitative insights in operational reality. Secondary validation draws from FDA labeling guidance documents, EFSA health claim evaluation registers, USDA organic certification standards, and Nielsen retail audit data. Bottom-up demand modeling and top-down supply capacity assessments triangulate volume estimates.
Bottom-up segmentation across product type, ingredient sourcing, form factor, and end-user category generates granular demand decomposition. Top-down macro constraint analysis incorporates EFSA regulatory timelines, California water allocation projections, and food service equipment penetration curves. CAGRs derive from segment-level growth rate reconciliation against aggregate market boundary conditions. Forecast inputs include celiac diagnosis expansion trajectories and direct-to-consumer subscription velocity metrics.
Regulatory threshold revision timing, input cost volatility spikes, and channel consolidation acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about compliance cost absorption capacity and substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Biscuits Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Bread Premix Market
Bakery Products
Toasted Flour Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Global Bakery Product Market
Bakery Products
Pastry Premixes Market
Bakery Products
Pastry Margarine Market
Bakery Products
Cake Concentrate Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Qatar Bakery Product Market