
 Fresh Apricots Market | 2026-2036
Fresh Apricots Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Apricots Market Foresight
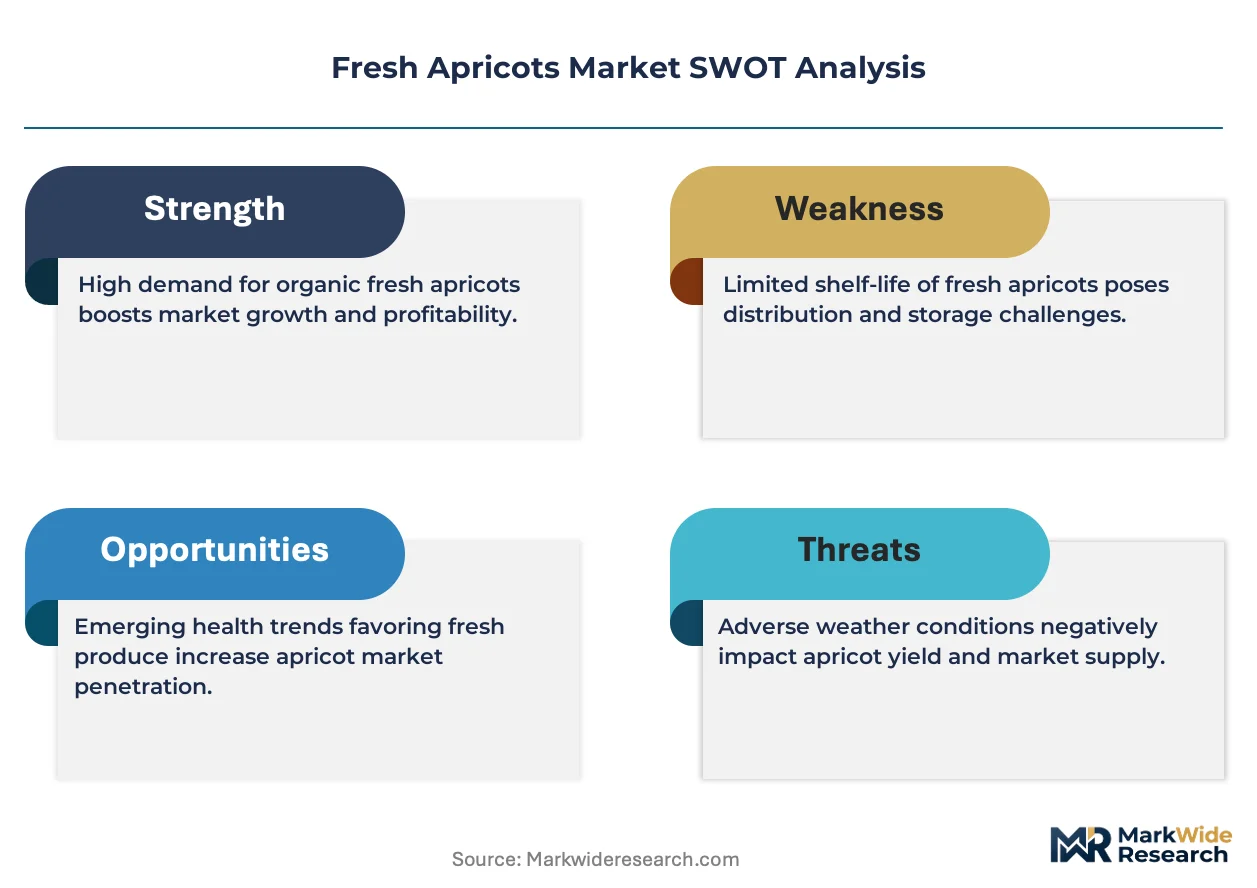
The capital-intensity divergence between integrated orchard operators and seasonal traders is unwinding competitive stability across the fresh apricots supply base. Dole Food Company leverages its refrigerated logistics network to sustain year-round availability across temperate retail markets. Kirlioglu Tarsal Urunler Gida Insaat Sanayi Ticaret anchors Turkish export volumes through controlled post-harvest handling infrastructure. Pagysa Pamuk Gida Sanayi ve Ticaret competes on varietal breadth, specializing in early-season Moorpark and Tilton cultivars for European wholesale markets.
Fresh apricots comprise the stone fruit Prunus armeniaca, harvested at soluble solids concentrations of 10–14°Brix and requiring hydrocooling to 0–2°C within four hours of picking to arrest respiration rates of 10–20 mg CO₂/kg/hr. The fruit serves fresh consumption, industrial processing into purees and concentrates, and extraction of kernel oil for cosmetic and nutraceutical applications. Moorpark and Goldcot varieties dominate premium retail positioning due to superior color stability and extended shelf life, while wholesale markets absorb volume-grade Tilton and Tilney lots with less stringent cosmetic grading. Online Retailers represent the fastest-expanding distribution channel as direct-to-consumer cold-chain investments reduce intermediation layers in perishable logistics.
EU REACH and EFSA maximum residue limits govern phytosanitary inputs for apricots entering European supermarkets, while FDA import alerts and USDA grading standards shape US market access thresholds for foreign suppliers. Turkey's BIS-aligned export certification and Uzbekistan's national phytosanitary regulator impose parallel conformity requirements that filter smallholder participation. Stakeholders must monitor evolving cold-chain efficiency benchmarks and varietal patent landscapes as climate adaptability becomes the decisive orchard investment criterion.
Market Dynamics
The EU's Farm to Fork Strategy is compressing permissible residue thresholds while Turkish and Uzbek orchard consolidation concentrates supply control among capitalized operators with captive cold-chain infrastructure.
Growth Catalysts
- EFSA Residue Limit Tightening:Supermarket chains in Germany and France now mandate sub-LOD phytosanitary certification, filtering out smallholder exporters and rewarding integrated operators with in-house laboratory testing.
- Online Retail Cold-Chain Investment:Direct-to-consumer platforms are building dedicated hydrocooling and refrigerated last-mile networks, collapsing traditional wholesale layers in perishable distribution.
- Nutraceutical Kernel Oil Demand:Cosmetic formulators in South Korea and Japan are contracting dedicated apricot kernel oil volumes, creating premium offtake for varieties with high amygdalin content.
Market Restraints
- Phytosanitary Input Cost Volatility:Sulfur and copper-based fungicide prices fluctuate with energy markets, compressing margins for operators in rain-fed Turkish growing regions.
- Supply Concentration in Central Asian Corridors:Uzbekistan's national phytosanitary regulator controls export licensing through a single-window system, creating bottleneck risk during peak harvest windows.
- Refrigerated Logistics Infrastructure Gaps:Last-mile cold-chain coverage remains sparse in secondary Indian and Indonesian cities, limiting shelf-life extension for imported fruit.
Strategic Opportunities
- Climate-Adaptive Varietal Development:Italian breeding programs are patenting heat-tolerant rootstocks, opening cultivation expansion into warming southern Spanish and Portuguese valleys.
- EU Green Deal Agricultural Transition Incentives:Carbon farming certification payments reward orchards adopting cover cropping and reduced tillage, offsetting compliance costs for integrated operators.
- Functional Food Ingredient Positioning:Beta-carotene and fiber content claims are penetrating Japanese and Australian health-conscious retail segments, commanding price premiums over commodity stone fruit.
Industry Challenges
- Post-Harvest Physiology Expertise Scarcity:Hydrocooling protocol optimization and controlled-atmosphere storage management require specialized technicians, with training pipelines lagging orchard expansion in Uzbekistan and Tajikistan.
- Variety-Specific Patent Licensing Complexity:Protected cultivar propagation rights held by French and Italian breeding consortia impose royalty structures and geographic restrictions on licensed planting.
- Multijurisdictional Certification Timeline Compression:Simultaneous BIS, EFSA, and FDA compliance audits for Turkish exporters strain documentation systems during narrow harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Apricots Market |
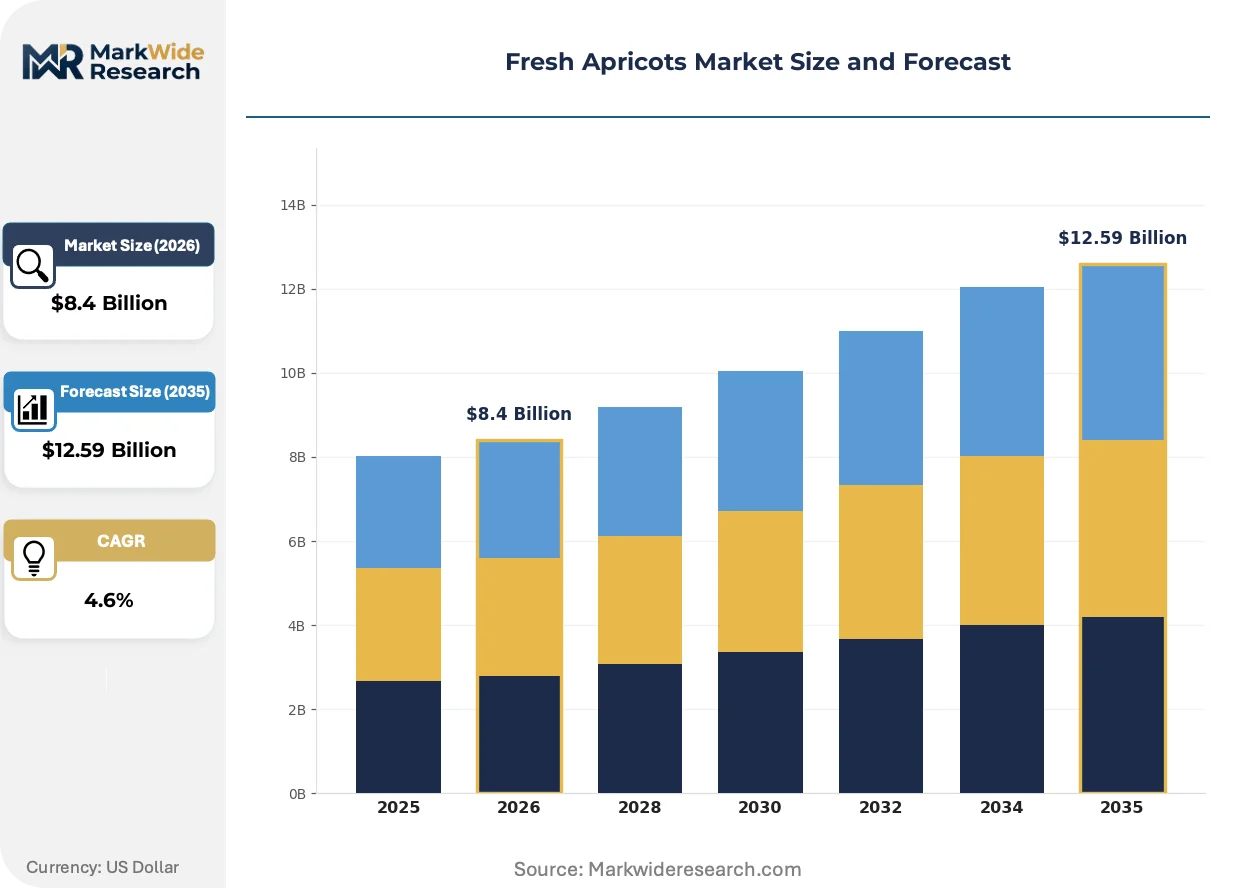
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Variety: Moorpark, Tilton, Tilney, Katy, Goldcot Distribution Channel: Supermarkets, Grocery Stores, Farmers Markets, Online Retailers, Wholesale Markets Application: Fresh Consumption, Food Processing, Culinary Ingredient, Nutraceuticals Packaging Type: Clamshells, Plastic Trays, Cardboard Boxes, Mesh Bags |
| Companies Covered | Kirlioglu Tarsal Urunler Gida Insaat Sanayi Ticaret, GRANDEZZA, Dole Food Company, Nazar Mosh Mas Uliyati Cheklangan Jamiyati, Công ty Cổ phần Chế biến Xuất nhập khẩu Thủy sản Anh Minh, Pagysa Pamuk Gida Sanayi ve Ticaret, Capespan, AO Grand Trade, Suer Gida Sanayi ve Ticaret, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Apricots Market Shifts & Advancements
Digital traceability platforms and precision-controlled atmosphere systems are restructuring quality assurance protocols, while regulatory convergence on residue standards is elevating compliance technology investment.
Spectral sorting technology using near-infrared hyperspectral imaging is bifurcating packhouse operations by automating bruise detection and soluble solids grading. Large retail chains in France and Germany are mandating its deployment for contracted volumes. The technology is bifurcating the supply base into capital-intensive certified suppliers and excluded small-scale operators lacking upgrade capital.
REACH and EFSA maximum residue limit harmonization is forcing reformulation of orchard spray programs across Mediterranean growing regions. Integrated pest management documentation requirements now span 180-day pre-harvest intervals. Italian and Spanish cooperative packhouses are consolidating testing laboratory investments to maintain supermarket access.
Subscription-based direct-to-consumer models are displacing traditional wholesale procurement for premium apricot varieties. Urban households in Tokyo, Seoul, and Sydney are accepting 48-hour delivery windows for tree-ripened fruit. Japanese online grocers are pioneering this channel with varietal-specific harvest-date labeling.
Fresh Apricots Market Segmentation
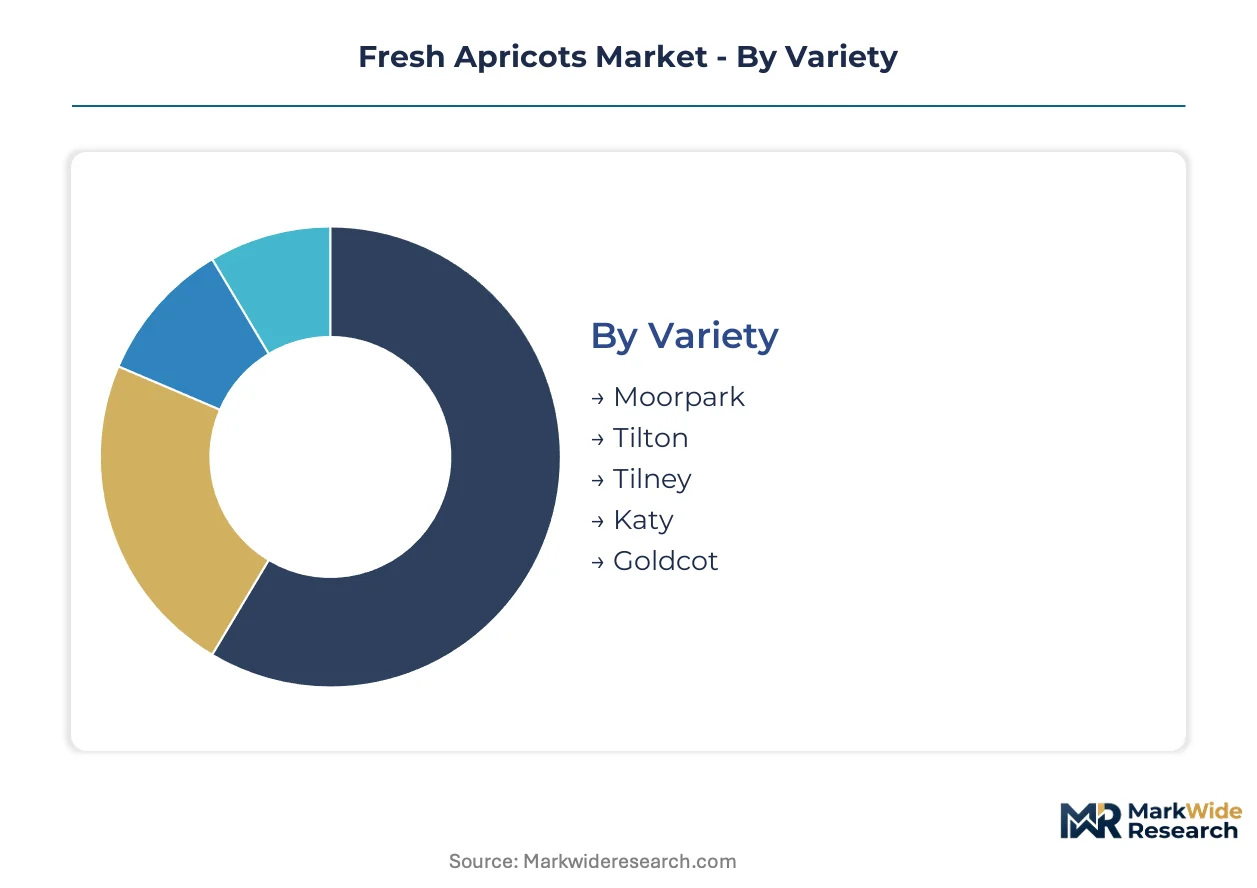
Fresh apricots flow through sharply divergent channel economics depending on varietal pedigree and post-harvest handling investment. Segmentation reveals where capitalized operators capture margin premiums versus where commodity handlers compete on throughput volume.
Variety:
Channel placement follows color stability and shelf-life performance, with premium retail commanding varieties that withstand hydrocooling and controlled-atmosphere storage.
- Moorpark:Deep orange flesh and superior color retention after cold-chain transit make this cultivar the standard for German and French supermarket premium tiers. EFSA sub-LOD certification requirements favor Moorpark plantings by integrated Turkish operators with captive laboratory testing.
- Goldcot:Extended post-harvest life of 14–21 days under controlled atmosphere enables year-round program supply through Dole's refrigerated logistics network. Japanese online grocers specify Goldcot for varietal-specific harvest-date subscription offerings.
- Tilton:Volume-grade fruit absorbed by wholesale markets with less stringent cosmetic grading tolerances.
- Tilney:Processing-dominant variety supplying industrial puree and concentrate contracts.
- Katy:Early-season cultivar capturing price premiums before main harvest windows.
Moorpark dominates installed base among export-oriented orchards. Goldcot is where expansion concentrates as climate adaptability becomes decisive.
Distribution Channel:
Margin structures invert with cold-chain depth, collapsing traditional wholesale layers where direct-to-consumer platforms invest in captive hydrocooling infrastructure.
- Online Retailers:Direct-to-consumer platforms in Tokyo, Seoul, and Sydney are building dedicated refrigerated last-mile networks. These operators collapse intermediation layers by accepting 48-hour delivery windows for tree-ripened fruit with varietal-specific harvest-date labeling.
- Supermarkets:German and French chains mandate spectral sorting technology deployment and sub-LOD phytosanitary certification, filtering supply to capitalized integrated operators. Kirlioglu and Pagysa anchor contracted volumes through controlled post-harvest handling infrastructure.
- Wholesale Markets:Volume-grade Tilton and Tilney lots flow through traditional intermediary layers with less stringent cosmetic grading.
- Farmers Markets:Localized procurement bypassing cold-chain investment for immediate consumption.
- Grocery Stores:Secondary retail tier absorbing regional supply with intermediate handling requirements.
Supermarkets dominate current procurement volume. Online Retailers are climbing the fastest as cold-chain infrastructure investments reduce perishability losses.
Application:
End-use specifications fragment by beta-carotene content thresholds and kernel oil extraction yields, with nutraceutical contracts commanding dedicated orchard blocks.
- Fresh Consumption:Soluble solids concentrations of 10–14°Brix and hydrocooling to 0–2°C within four hours define retail-grade specifications. Premium positioning in Japanese and Australian health-conscious segments leverages beta-carotene content claims.
- Nutraceuticals:Apricot kernel oil extraction for South Korean and Japanese cosmetic formulators creates premium offtake for varieties with high amygdalin content. Dedicated contracting bypasses fresh-market price volatility.
- Food Processing:Puree and concentrate production absorbing volume-grade fruit with lower cosmetic requirements.
- Culinary Ingredient:Restaurant and foodservice procurement prioritizing flavor intensity over shelf-life extension.
Fresh Consumption commands the largest revenue share. Nutraceuticals represent the steepest expansion trajectory as cosmetic formulators secure dedicated supply contracts.
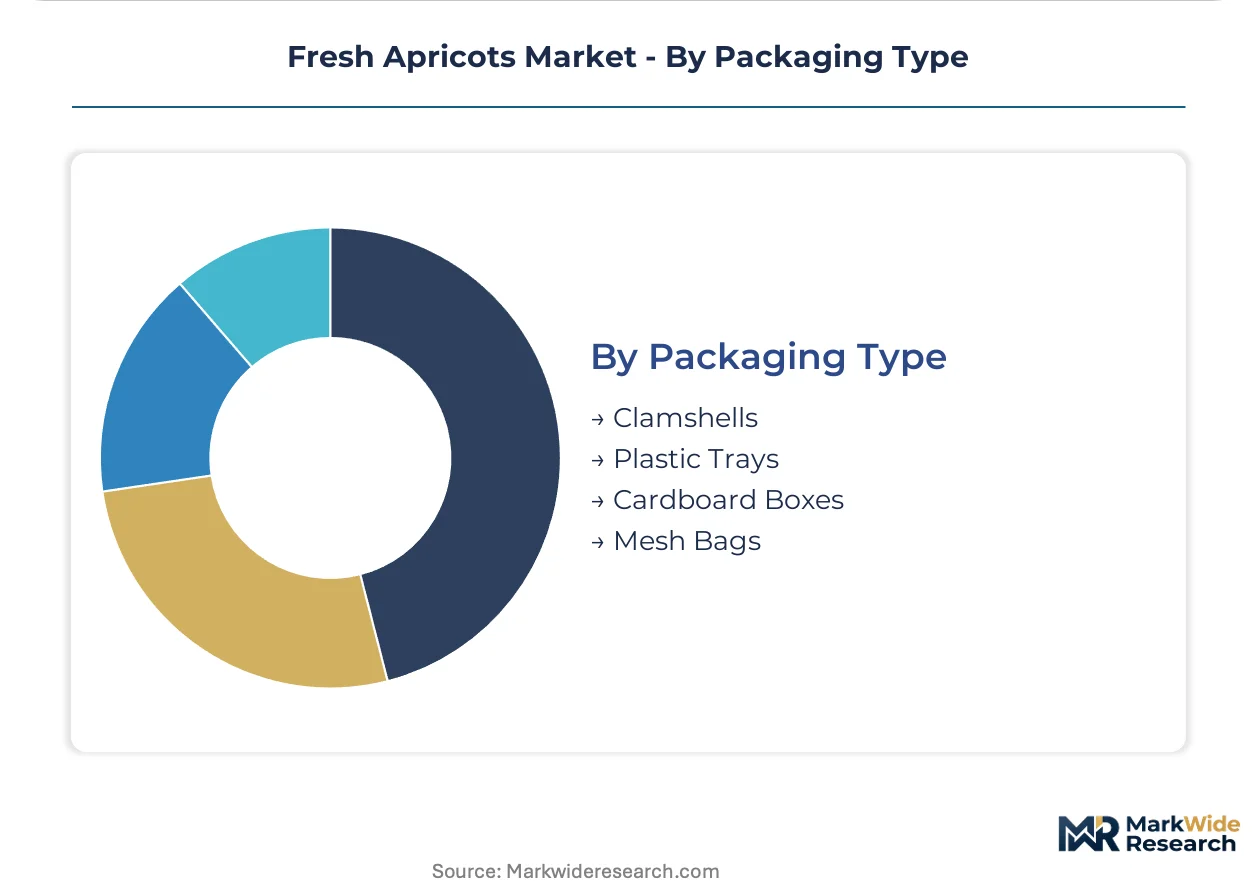
Packaging Type:
Material selection trades breathability against mechanical protection, with retail-facing formats requiring barcode compatibility and tamper-evident sealing.
- Clamshells:Premium retail standard in French and German supermarkets, offering mechanical protection and moisture regulation for varieties with extended shelf-life requirements. Spectral sorting compatibility mandates standardized dimensions.
- Cardboard Boxes:Wholesale and processing-channel standard for volume-grade fruit with shorter transit windows.
- Plastic Trays:Intermediate retail tier balancing cost and protection.
- Mesh Bags:Lowest-cost format for immediate-consumption channels with minimal handling stages.
Clamshells dominate premium retail placement. Cardboard Boxes concentrate volume throughput in processing and wholesale corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Turkish growing regions outstrips Central Asian corridors by double-digit margins, reflecting captive cold-chain infrastructure and EFSA-aligned certification capacity that Uzbekistan's national phytosanitary regulator has yet to replicate at scale.
Turkey
German and French supermarket chains source Moorpark and Goldcot varieties through Istanbul-based packhouses with spectral sorting deployment. BIS-aligned export certification and in-house laboratory testing filter smallholder participation. The Malatya and Elazıg orchard belts concentrate procurement activity among integrated operators with controlled post-harvest handling infrastructure.
Uzbekistan
Wholesale markets in Moscow and Almaty absorb volume-grade Tilton shipments through centralized export licensing. The national phytosanitary regulator's single-window system creates bottleneck risk during peak harvest windows. The Fergana Valley clustering dominates planted area as state-backed orchard consolidation accelerates.
Italy
Domestic consumption and re-export positioning into Swiss and Austrian retail channels sustain premium-tier pricing for early-season Katy cultivars. EU Green Deal agricultural transition incentives reward cover cropping adoption in Emilia-Romagna cooperative operations. The Po Valley breeding programs patent heat-tolerant rootstocks for southern Spanish and Portuguese valley expansion.
United States
California's Central Valley supplies domestic supermarket chains with hydrocooled fruit meeting USDA grading standards. FDA import alerts shape market access thresholds for Turkish and Uzbek suppliers. The Modesto-Fresno corridor anchors domestic production as water stress shifts acreage toward drip-irrigated blocks.
Japan
Tokyo and Osaka online grocers specify Goldcot for varietal-specific harvest-date subscription offerings with 48-hour delivery windows. Cosmetic formulators in Kobe and Yokohama contract dedicated apricot kernel oil volumes for high-amygdalin-content varieties. METI standards on cold-chain traceability elevate compliance technology investment for imported fruit.
Fresh Apricots Market Competitive Landscape
Concentration sits with integrated orchard operators possessing captive post-harvest infrastructure and multijurisdictional certification capacity. Seasonal traders lacking laboratory testing and hydrocooling assets face systematic exclusion from German and French supermarket supply programs. Three archetypes dominate: vertically integrated Turkish exporters with BIS-EFSA-FDA parallel compliance, Central Asian state-linked aggregators controlling export licensing, and diversified fresh fruit multinationals leveraging refrigerated logistics networks. Competitive moves center on varietal patent licensing for climate adaptability and direct-to-consumer cold-chain investments collapsing wholesale intermediation.
Within the integrated Turkish exporter tier, Kirlioglu Tarsal Urunler Gida Insaat Sanayi Ticaret and Pagysa Pamuk Gida Sanayi ve Ticaret exemplify operators with controlled post-harvest handling infrastructure and EFSA sub-LOD certification capacity. Dole Food Company represents the diversified multinational archetype, occupying a position sustained by refrigerated logistics networks enabling year-round program supply across temperate retail markets.
| Leading Market Players |
|---|
| Kirlioglu Tarsal Urunler Gida Insaat Sanayi Ticaret |
| GRANDEZZA |
| Dole Food Company |
| Nazar Mosh Mas Uliyati Cheklangan Jamiyati |
| Công ty Cổ phần Chế biến Xuất nhập khẩu Thủy sản Anh Minh |
| Pagysa Pamuk Gida Sanayi ve Ticaret |
| Capespan |
| AO Grand Trade |
| Suer Gida Sanayi ve Ticaret |
| Others |
Supply & Pricing Matrix
Four-hour hydrocooling windows from harvest to cold-chain entry compress margin capture for operators lacking captive infrastructure, concentrating pricing power among Turkish integrated exporters with Malatya-based packhouses while fragmenting returns for rain-fed smallholders dependent on spot-market intermediaries. EFSA-aligned certification capacity and spectral sorting deployment separate premium-tier Moorpark contract pricing from volume-grade Tilton spot trading.
Pricing Analysis
Contract-to-spot spreads of 35-50% separate EFSA sub-LOD certified Moorpark shipments for German supermarket programs from wholesale Tilton lots absorbed by Moscow traders. Premium-mid-economy pricing differentiation rests on hydrocooling protocol adherence and varietal patent licensing for climate-adaptive rootstocks. Pricing pressure stems from sulfur and copper-based fungicide cost volatility in Turkish growing regions. Supermarket procurement teams exhibit lowest price sensitivity due to shelf-life performance requirements, while wholesale intermediaries in Central Asian corridors face acute margin compression.
Supply Chain Analysis
Just-in-time hydrocooling protocols dominate premium retail channels, while strategic stockpiling through controlled-atmosphere storage enables year-round program supply for Japanese subscription platforms. Supply concentrates in Turkey, Uzbekistan, and Italy, with raw material dependencies spanning sulfur-based fungicides, hydrocooling energy inputs, and clamshell packaging resins. Single-source vulnerability runs through Uzbekistan's national phytosanitary regulator single-window licensing system. Distribution runs through Istanbul-based packhouses with BIS-EFSA-FDA parallel compliance capacity for EU and US market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer cold-chain investments are collapsing traditional wholesale layers into platform-mediated subscription economics, with Japanese online grocers pioneering harvest-date traceability as the interoperability standard reshaping buyer-seller relationships.
For Market Incumbents: Compound spectral sorting technology deployment with captive laboratory testing infrastructure to defend supermarket contract positioning against emerging Central Asian state-linked aggregators. Prioritize varietal patent licensing for heat-tolerant rootstocks as climate adaptability becomes the decisive orchard investment criterion. Expand controlled-atmosphere storage capacity in Malatya and Elazıg to capture subscription-platform volumes. For New Entrants and Emerging Players: Anchor in nutraceutical kernel oil contracting for South Korean and Japanese cosmetic formulators, where dedicated offtake agreements bypass fresh-market price volatility. Target early-season Katy cultivar positioning in Australian health-conscious retail segments leveraging beta-carotene content claims. Pursue carbon farming certification under EU Green Deal agricultural transition incentives to offset compliance cost burdens. For Investors and Strategic Acquirers: Long-term, this sits as a cold-chain infrastructure consolidation play because perishable logistics capabilities determine market access filtration across tightening EFSA residue thresholds. Acquisition targets center on Turkish integrated operators with BIS-EFSA-FDA parallel compliance and Malatya-based packhouse assets. The signal to watch is Uzbekistan's national phytosanitary regulator licensing queue compression during peak harvest windows.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Adaptive Varietal Patent Licensing | Italian breeding programs in Emilia-Romagna secure heat-tolerant rootstock propagation rights for southern Spanish valley expansion. |
| Direct-to-Consumer Cold-Chain Buildout | Tokyo and Seoul platforms reduce intermediation layers through dedicated hydrocooling and 48-hour last-mile networks. |
| EFSA Sub-LOD Certification Investment | In-house laboratory testing at Istanbul packhouses filters smallholder competition for German supermarket programs. |
| Nutraceutical Kernel Oil Contracting | South Korean cosmetic formulators secure dedicated offtake for high-amygdalin varieties bypassing fresh-market volatility. |
| Carbon Farming Certification Adoption | EU Green Deal incentives reward cover cropping and reduced tillage, offsetting compliance costs for integrated operators. |
Research Methodology
A standing panel of orchard operations managers, Turkish export packhouse directors, German supermarket category buyers, Japanese online grocer procurement leads, and South Korean cosmetic formulator supply chain managers provided ongoing calibration across primary fieldwork. Secondary validation drew from EFSA residue limit databases, BIS export certification records, Turkish Statistical Institute trade data, and EU Farm to Fork Strategy implementation reports. Bottom-up variety-level volume modeling triangulated against top-down country production estimates.
Consistency checks against external benchmarks validated projections across the analysis window through cross-reference with customs clearance volumes and cold-chain infrastructure investment disclosures. Segmentation dimensions spanned varietal pedigree, distribution channel cold-chain depth, end-use application specifications, and regional regulatory cluster alignment. CAGRs derived from trend extrapolation of orchard area expansion rates and per-capita consumption patterns in target markets, with climate adaptability indices and phytosanitary compliance cost trajectories as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA residue limit tightening and stable Turkish-Georgian transit corridor access; material deviation would warrant model refresh. Specific risks include Uzbekistan single-window licensing bottlenecks, sulfur fungicide price spikes tied to energy markets, and varietal patent litigation constraining rootstock adoption. Revision becomes warranted when hydrocooling infrastructure deployment in Central Asian corridors crosses operational scale thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
South Africa Fruits and Vegetables Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Grapes Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Fresh Peaches Market