
 Grass-Fed Jerkies Market | 2026-2036
Grass-Fed Jerkies Market Size, Share, and Industry Trends Forecast 2026-2036
Grass-Fed Jerkies Market Insights
Asset-light contract manufacturing and private-label financing is rewriting entry economics for emerging jerky brands. Chomps leverages direct-to-consumer subscription models to sustain premium pricing without captive production. Country Archer anchors its competitive position through in-house smokehouse operations in California. Jack Link's competes at scale through established cold-chain distribution networks that smaller grass-fed specialists cannot replicate.
Grass-fed jerkies are dried, cured meat products sourced from cattle raised on pasture-based diets without grain finishing, typically processed through low-temperature dehydration or traditional smoking to preserve amino acid profiles and minimize synthetic additive use. The beef segment dominates current volume as established ranching infrastructure supports consistent grass-fed supply, while bison offers higher per-unit margins due to constrained herd sizes and distinct nutritional positioning. Resealable bag packaging leads grocery channel penetration for portability and shelf-life extension, though bulk formats command loyalty within specialty shops and farmers markets where repeat purchasers prioritize cost efficiency.
USDA Agricultural Marketing Service standards for grass-fed claims and FDA food labeling requirements shape product positioning and substantiation burdens for domestic producers. State-level organic certification programs in California and Texas add compliance layers that favor vertically integrated ranch-to-package operators over outsourced processors. Stakeholders must monitor evolving pasture-raised definitions and carbon-accounting disclosures as retail buyers increasingly tie shelf access to verified sourcing documentation.
Market Dynamics
USDA Agricultural Marketing Service enforcement of grass-fed claim substantiation is compressing label integrity gaps and forcing ranch-to-package traceability investments across domestic supply chains.
Growth Catalysts
- Fitness-oriented consumer migration:Paleo and Whole30 diet adherents are expanding addressable demand through specialty retail channels and direct-to-consumer platforms, with protein-forward snacking displacing conventional processed alternatives.
- California organic certification layering:State-level programs beyond federal USDA organic standards are creating premium tier separation that rewards vertically integrated operators with price capture advantages.
- Low-temperature dehydration advancement:Modified atmosphere drying technologies are preserving amino acid profiles more effectively than conventional heat processing, enabling cleaner-label positioning without synthetic preservatives.
Market Restraints
- Grass-fed cattle supply concentration:Established ranching corridors in Colorado and Texas dominate pasture-raised livestock availability, constraining national scale-up for new market entrants lacking geographic proximity.
- Grain price volatility spillover:Feed cost fluctuations in conventional beef operations indirectly pressure grass-fed premiums as relative price differentials compress during commodity downturns.
- Cold-chain distribution replication barriers:Jack Link's and established protein snack incumbents control refrigerated logistics infrastructure that smaller specialists cannot economically duplicate.
Strategic Opportunities
- Bison protein expansion:Constrained North American herd sizes and distinct nutritional positioning enable margin premiums that beef-based products cannot match, with specialty retailers creating dedicated shelf space.
- Carbon-accounting disclosure integration:Pasture-based livestock operations qualify for emerging Scope 3 emissions reduction claims that retail buyers increasingly require for shelf access contracts.
- Farmers market bulk format penetration:Direct-to-consumer packaging at specialty shops bypasses grocery slotting fees while building repeat purchase loyalty through cost efficiency.
Industry Challenges
- Smokehouse operator skill scarcity:Traditional curing expertise required for consistent low-temperature processing is concentrated among aging craft practitioners, constraining in-house production scaling.
- Multi-jurisdiction certification timelines:Simultaneous USDA organic, state-level, and retailer-specific audit requirements extend product launch cycles and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass-Fed Jerkies Market |
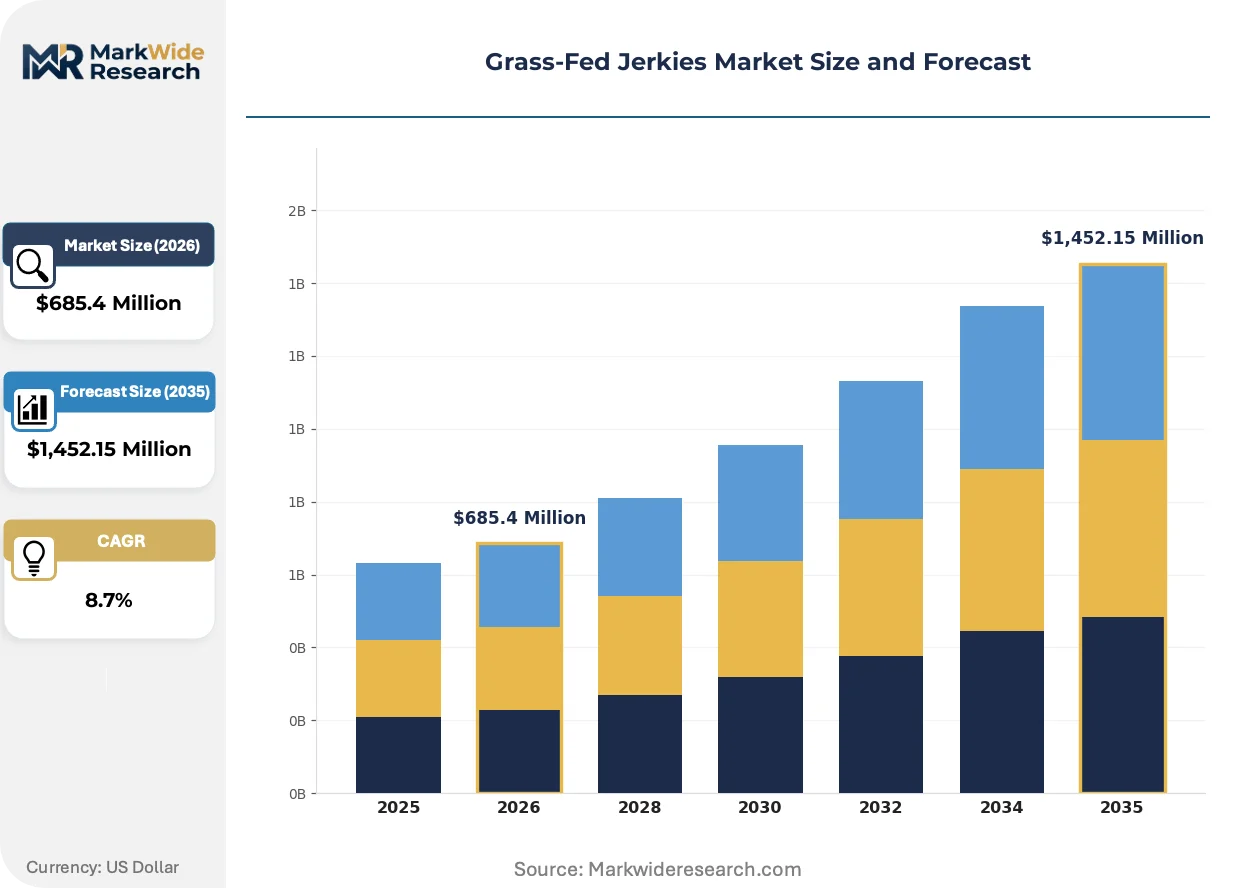
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Bison, Turkey, Lamb Flavor Profile: Spicy, Teriyaki, Original, Garlic Packaging Type: Resealable Bags, Pouches, Jars, Bulk Distribution Channel: Online Retail, Grocery Stores, Specialty Shops, Farmers Markets |
| Companies Covered | Chomps, Country Archer, Paleovalley, Jack Link's, Archer Provisions, No Man's Land Beef Jerky, Starwalker Organic Farms, White Oaks, Ripped Jerky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass-Fed Jerkies Market Trends and Innovations
Processing technology convergence and procurement transparency demands are reconfiguring how grass-fed jerky producers substantiate premium positioning and secure shelf access.
Modified atmosphere packaging with embedded oxygen scavengers is hybridizing traditional preservation methods with active shelf-life extension. Specialty retailers and subscription box curators are adopting these formats to reduce spoilage returns. This convergence is compressing the viability window for conventional vacuum-sealed alternatives that lack real-time freshness indicators.
USDA Agricultural Marketing Service standards for grass-fed claim verification are tightening substantiation burdens on domestic producers. The agency's 2023 enforcement memorandum requires documented pasture access records rather than self-attestation. Smaller ranch-to-package operators are responding faster than outsourced processors due to captive supply chain visibility.
Subscription-based replenishment models are displacing intermittent grocery purchase patterns among protein-forward snack consumers. Direct-to-consumer platforms capture recurring revenue while bypassing slotting fee structures that disadvantage emerging brands. Colorado and Texas ranching corridor proximity to fulfillment infrastructure accelerates delivery velocity for these channels.
Grass-Fed Jerkies Market Segmentation
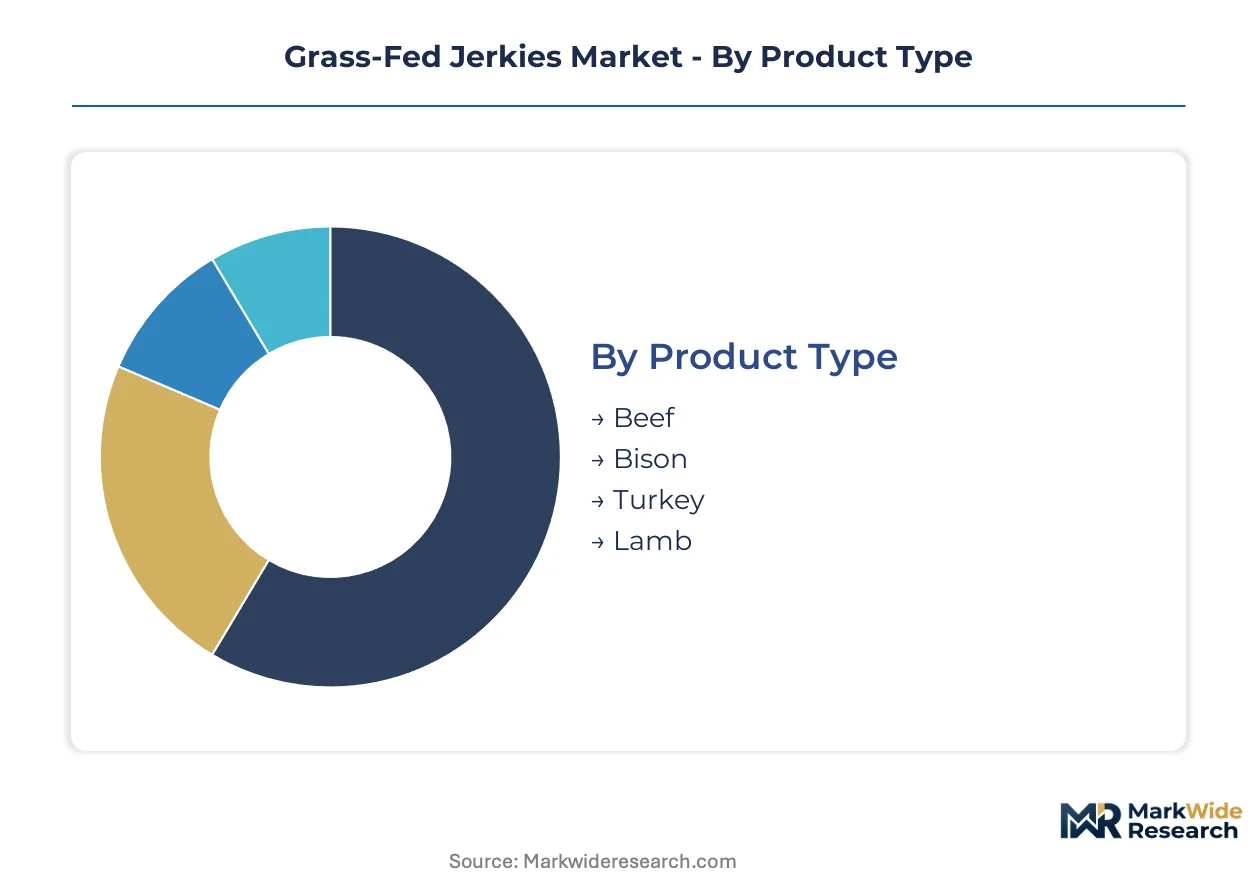
Grass-fed jerky producers navigate four distinct segmentation dimensions that determine pricing power, shelf placement, and customer acquisition costs. Product type and distribution channel stratification create the sharpest margin differentials, while packaging and flavor decisions shape repeat purchase velocity in a category where loyalty drives lifetime value.
Product Type:
Cost tier separation in protein sourcing determines which ranching corridors and processing investments each segment requires.
- Beef:Pasture-raised cattle from Colorado and Texas ranching corridors supply the volume base, with established cold-chain infrastructure supporting national grocery penetration. USDA grass-fed verification requirements favor vertically integrated operators who control ranch-to-package traceability.
- Bison:Constrained North American herd sizes create supply scarcity that enables 40-60% price premiums over beef equivalents, with specialty retailers carving dedicated shelf space for the distinct nutritional positioning. Demand concentrates among paleo diet adherents willing to pay for omega-3 fatty acid differentiation.
- Turkey:Lean protein profile attracts fitness-oriented consumers tracking macronutrient ratios, though pasture-raised turkey supply remains thinner than cattle alternatives.
- Lamb:Distinct flavor profile and Mediterranean diet alignment create niche positioning in coastal urban specialty shops with lower volume ceilings.
Beef commands the established base. The steepest expansion runs through Bison.
Flavor Profile:
Application context—snacking occasion, meal replacement, or social sharing—shapes which flavor investments deliver repeat purchase conversion.
- Original:Unseasoned cured meat preserves amino acid integrity through minimal processing, appealing to Whole30 adherents who reject added sugars and synthetic flavor enhancers. Colorado and Texas ranching corridor proximity to smokehouse operations ensures consistent low-temperature curing quality.
- Spicy:Capsaicin-forward formulations attract younger male demographics through convenience store and online subscription channels, with heat intensity becoming a brand differentiation vector that supports premium pricing without ingredient cost escalation.
- Teriyaki:Sweet-savory balance requires careful sugar source selection to maintain clean-label positioning, constraining formulation flexibility for USDA organic certification seekers.
- Garlic:Umami depth from natural curing agents appeals to Mediterranean diet crossover consumers, though volatile sulfur compounds complicate modified atmosphere packaging shelf-life extension.
Original flavor anchors the clean-label segment. Spicy variants are climbing the fastest in direct-to-consumer subscription velocity.
Packaging Type:
Volume throughput and margin structure diverge sharply between single-serve portability formats and cost-efficient bulk alternatives.
- Resealable Bags:Multi-layer barrier films with embedded oxygen scavengers extend shelf life without synthetic preservatives, commanding grocery channel slotting fees that favor scaled producers. Modified atmosphere technologies from California packaging suppliers enable 12-18 month freshness claims.
- Bulk:Minimal packaging overhead supports 25-35% per-ounce cost reductions that drive loyalty at farmers markets and specialty shops where repeat purchasers prioritize value over portability.
- Pouches:Flexible format suits subscription box curation and airline snack programs, though lower barrier properties constrain shelf life versus bag alternatives.
- Jars:Premium glass positioning supports gift market and specialty retail placement, with higher shipping costs limiting e-commerce scalability.
Resealable bags dominate grocery penetration. Bulk formats are gaining share fastest in direct-channel repeat purchase economics.
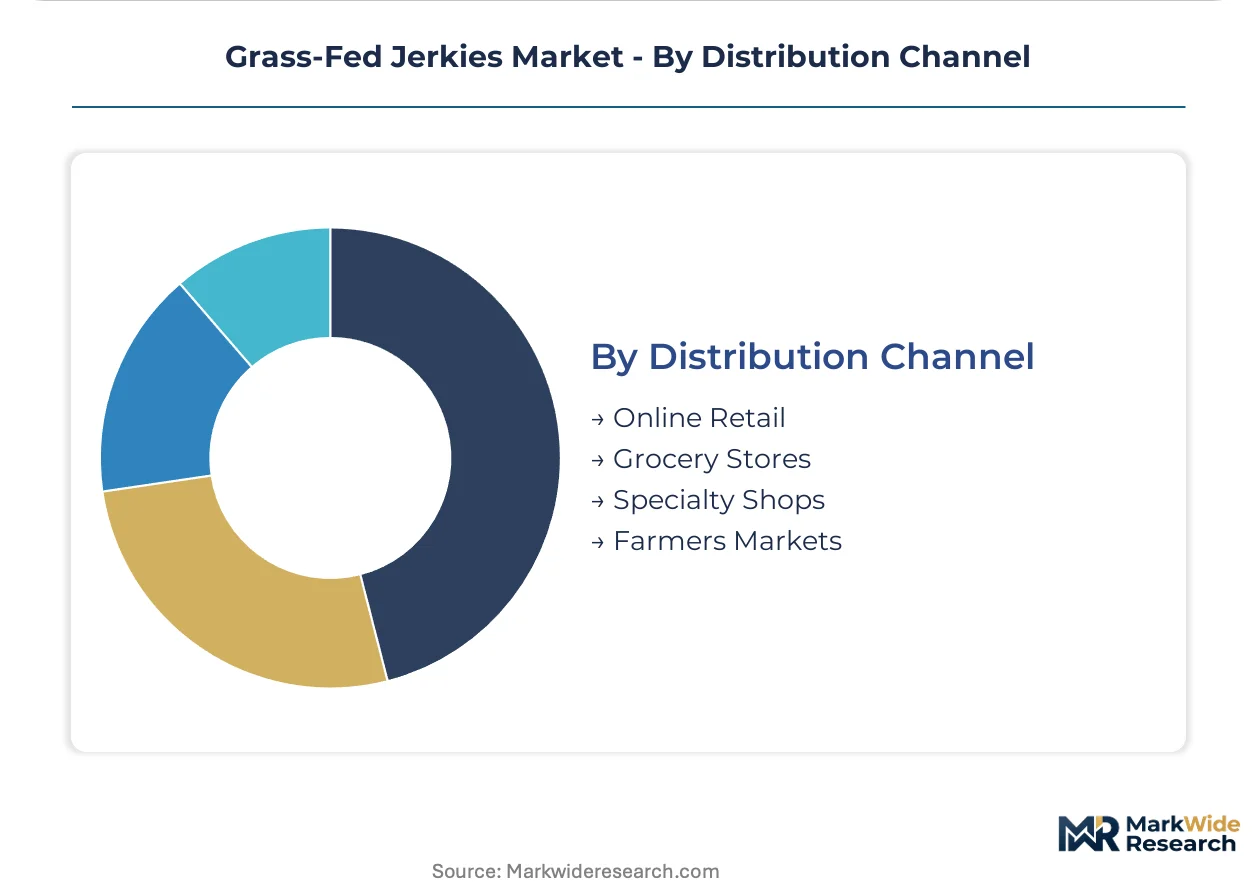
Distribution Channel:
Customer type and purchase context—impulse, planned replenishment, or discovery—determine which channel investments absorb working capital most efficiently.
- Specialty Shops:Curated shelf space and educated staff enable margin premiums that offset lower throughput, with Colorado and Texas corridor proximity reducing freight costs for regional ranch-to-package operators. Staff recommendation velocity drives trial conversion for emerging bison and lamb entrants.
- Online Retail:Subscription replenishment models capture recurring revenue while bypassing slotting fee structures, with Chomps demonstrating that direct-to-consumer platforms sustain premium pricing without captive production infrastructure.
- Grocery Stores:Mass channel penetration requires cold-chain logistics scale that Jack Link's and established incumbents control, compressing margin availability for grass-fed specialists.
- Farmers Markets:Direct producer-consumer relationships build brand equity and enable bulk format trial, though seasonality and geographic concentration constrain national scale.
Specialty shops anchor premium positioning. Online retail is expanding most quickly in subscription-based customer lifetime value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level certification incentives across multiple jurisdictions are concentrating grass-fed jerky production in established ranching corridors with verified pasture access documentation.
United States
Paleo and Whole30 diet adherence drives specialty retail demand, particularly in fitness-dense metropolitan areas. USDA Agricultural Marketing Service enforcement of documented pasture access records raises compliance barriers for new entrants. Colorado and Texas ranching corridors anchor domestic supply, with vertically integrated operators leveraging proximity to smokehouse infrastructure.
Canada
Health Canada and CFIA organic certification requirements create dual-layer substantiation for cross-border export eligibility. Provincial organic programs in British Columbia and Alberta add premium tier separation that rewards ranch-to-package traceability. Calgary and Edmonton processing clusters serve domestic prairie beef supply while accessing Pacific export logistics.
Australia
FSANZ food standards and grass-fed certification protocols align with export market access requirements for premium protein snacks. Queensland and New South Wales pastoral zones supply cattle under year-round grazing conditions. Sydney and Melbourne specialty retail channels import US positioning strategies for domestic paleo consumer segments.
Germany
EFSA clean-label preferences and Bundesamt für Verbraucherschutz enforcement drive synthetic additive rejection among protein snack purchasers. Bavarian and Lower Saxony organic livestock programs support limited domestic grass-fed beef supply. Berlin and Hamburg specialty retailers curate imported US and Australian jerky for fitness-oriented urban consumers.
United Kingdom
FSA and Defra pasture-raised claim standards tighten following post-Brexit regulatory divergence from EU frameworks. Scottish Highland and Welsh grassland cattle operations supply niche domestic raw material. London specialty food halls and direct-to-consumer subscription platforms concentrate demand for verified provenance jerky products.
Grass-Fed Jerkies Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Cold-chain logistics scale and grocery slotting fee absorption favor established protein snack incumbents, while direct-to-consumer subscription models enable emerging brands to bypass traditional retail gatekeeping. Three archetypes dominate: vertically integrated ranch-to-package operators, asset-light contract manufacturing brands, and diversified meat snack conglomerates. Competitive moves concentrate on geographic sourcing proximity and packaging technology differentiation.
Within the direct-to-consumer specialist tier, Chomps and Paleovalley exemplify asset-light brand building through subscription replenishment models that sustain premium pricing without captive production infrastructure. Country Archer anchors the vertically integrated archetype with in-house smokehouse operations. Jack Link's occupies the scale-driven position through established refrigerated distribution networks.
| Leading Market Players |
|---|
| Chomps |
| Country Archer |
| Paleovalley |
| Jack Link's |
| Archer Provisions |
| No Man's Land Beef Jerky |
| Starwalker Organic Farms |
| White Oaks |
| Ripped Jerky |
| Others |
Pricing and Supply Chain Analysis
Underutilized smokehouse capacity across Colorado and Texas ranching corridors is compressing processing margins while simultaneously elevating price premiums for verified pasture-raised supply. Capacity constraints force smaller operators toward contract manufacturing relationships that sacrifice margin capture to incumbents with captive infrastructure.
Pricing Analysis
Certification level creates the primary spread between commodity beef jerky and premium grass-fed alternatives, with USDA organic verification commanding the widest differential. Three-tier pricing structure separates unverified pasture-raised claims from AMS-documented grass-fed products and state-level organic certified tiers. Price erosion runs through conventional beef jerky as grain-fed commodity supply floods mass channels. Fitness-oriented subscription buyers demonstrate lowest price sensitivity, while grocery impulse purchasers show highest elasticity.
Supply Chain Analysis
Tariff exposure between United States and Canada complicates cross-border organic certification reciprocity for ranch-to-package operators seeking North American scale. Raw material supply draws from Colorado and Texas cattle corridors, with bison sourcing concentrated in Montana and South Dakota rangelands. Single-source vulnerability sits with aging smokehouse operator expertise concentrated among craft practitioners nearing retirement. Distribution runs through cold-chain logistics partnerships that Jack Link's and established protein snack networks dominate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
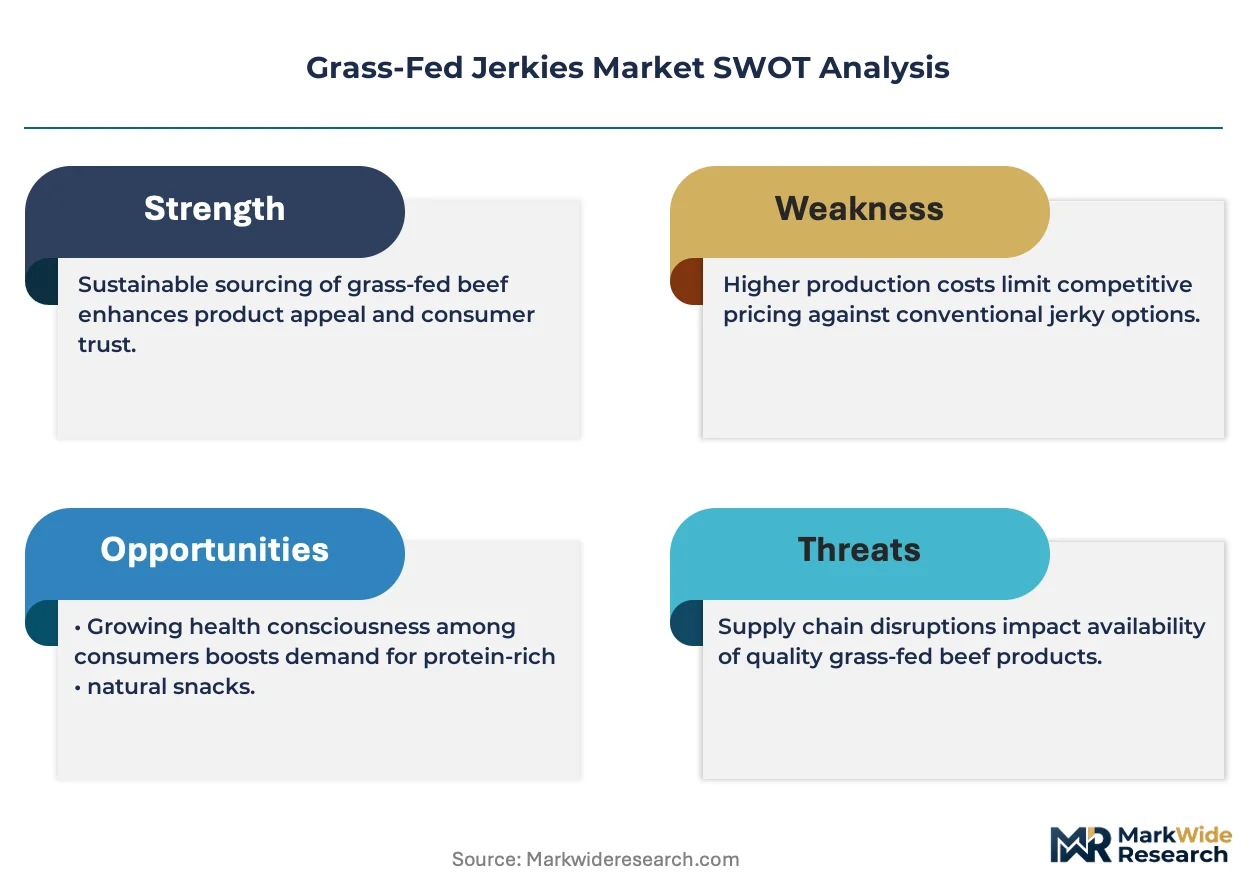
Fragmentation across certification tiers and distribution channels creates multiple niche entry points for specialists. Paleo and Whole30 diet adherence continues splintering demand into verified provenance segments that reward traceability investments.
For Market Incumbents: Pre-empt subscription model replication by Chomps and Paleovalley through captive direct-to-consumer platform development. Secure exclusive smokehouse operator relationships in Colorado and Texas corridors before craft expertise scarcity intensifies. Defend against asset-light brand erosion by anchoring shelf access through carbon-accounting disclosure integration that retail buyers increasingly mandate. For New Entrants and Emerging Players: Pursue bison protein white space where constrained North American herd sizes sustain margin premiums unavailable in beef commoditization. Target farmers market bulk format penetration in fitness-dense metropolitan areas where repeat purchase loyalty compounds cost efficiency advantages. Deploy ranch-to-package traceability storytelling as primary go-to-market angle to bypass grocery slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with captive Colorado or Texas ranching corridor access and AMS-compliant documentation systems. Long-term viability across the analysis window favors ranch-to-package archetypes over contract manufacturing dependent brands. Watch for FDA enforcement memorandum expansion on grass-fed claim substantiation as signal for accelerated consolidation toward compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Smokehouse Infrastructure Acquisition | Captures scarce curing expertise in Colorado and Texas corridors before operator retirement waves. |
| Carbon-Accounting Disclosure Program | Unlocks Scope 3 emissions reduction claims required by retail buyer shelf access contracts. |
| Direct-to-Consumer Platform Launch | Bypasses grocery slotting fees while capturing subscription recurring revenue Chomps has demonstrated. |
| Bison Supply Agreement | Secures constrained North American herd access for 40-60% price premium positioning. |
| State-Level Organic Certification | Creates California and Texas premium tier separation beyond federal USDA standards. |
Research Methodology
Desk research of USDA AMS enforcement memoranda, FDA food labeling guidance, and state-level organic program documentation preceded structured interviews with smokehouse operators, specialty retail category buyers, ranch-to-package brand founders, and cold-chain logistics coordinators. Primary fieldwork combined with secondary validation against Nielsen retail audit data, customs records for bison protein trade flows, and SEC filings from diversified protein snack conglomerates. Bottom-up volume modeling triangulated against top-down category spend estimates.
Assumptions held fixed include current USDA AMS pasture access documentation requirements and prevailing cold-chain logistics cost structures across the projection horizon. The analytical framework modeled product type, flavor profile, packaging format, and distribution channel segmentation dimensions. CAGRs derived from historical volume trajectories adjusted for fitness-oriented consumer migration patterns and paleo diet adherence trends. Forecast inputs incorporated modified atmosphere packaging adoption curves and subscription replenishment model penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by asset-light brands would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Crackers Market
Snacks
Low Calorie Dip Market
Snacks
South Korea Snack Bar Market
Snacks
Low-Fat Tortillas Market
Snacks
North America Fruit Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Spain Snack Bar Market
Snacks
Asia Pacific Tortilla Market
Snacks
Low Fat Granola Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Low Calorie Snack Foods Market
Snacks
Energy Balls Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Italy Snack Bar Market