
 Middle East Snack Bar Market | 2026-2036
Middle East Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Snack Bar Market Insights
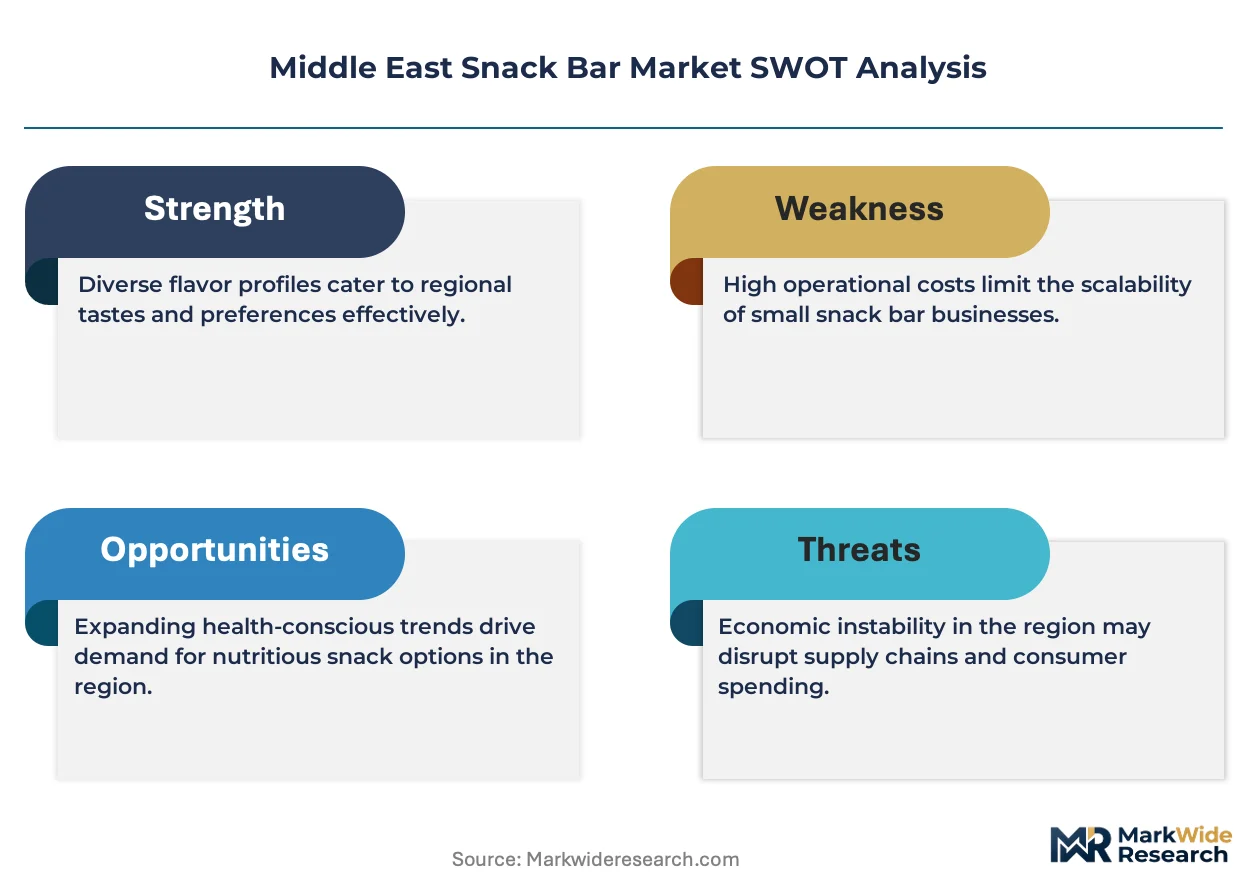
Private-label contract manufacturing is rewriting margin distribution across the Middle East Snack Bar Market, shifting value from brand ownership toward production flexibility and co-packing scale. PepsiCo leverages its beverage distribution infrastructure to secure shelf placement in Gulf retail chains. Almarai anchors its position through backward integration into dairy-based protein inputs and cold-chain logistics across Saudi Arabia.
A snack bar is a shelf-stable, extruded or cold-pressed food product typically comprising cereals, nuts, binders, and functional additives, formed into a handheld bar format with moisture content below 12% to ensure ambient stability without refrigeration. Protein Bars command premium shelf positioning as gym culture and corporate wellness programs expand across Gulf cities. Online Retail channels are capturing disproportionate growth velocity among teenagers and young adults, while Supermarkets retain volume leadership through promotional bundling and impulse-placement strategies.
Saudi Food and Drug Authority nutrition-labeling mandates and UAE Ministry of Industry and Advanced Technology halal-certification protocols shape formulation requirements and cross-border market access for international suppliers. Compliance with Gulf Standardization Organization packaging material regulations adds technical complexity for flexible-film suppliers entering the region. Stakeholders must monitor evolving sugar-tax discussions across Gulf Cooperation Council jurisdictions and calibrate product portfolios toward clean-label positioning ahead of anticipated regulatory tightening.
Market Dynamics
Private-label contract manufacturing is redistributing margin capture from brand equity toward production flexibility and co-packing scale across Gulf retail networks. This structural shift compels established players to defend shelf positioning through cold-chain infrastructure investments and backward integration into protein inputs.
Growth Catalysts
- SFDA Nutritional Labeling Mandates:Saudi Food and Drug Authority tightening of nutritional-claim standards is forcing reformulation toward clean-label positioning, creating first-mover advantage for compliant suppliers.
- Gym Culture Expansion:Protein-fortified formats gain traction as corporate wellness programs proliferate across Riyadh and Dubai commercial districts, pulling demand from conventional confectionery.
- Halal Certification Harmonization:UAE Ministry of Industry and Advanced Technology protocols are streamlining cross-border market access for international suppliers targeting Gulf Cooperation Council corridors.
Market Restraints
- Date Syrup Input Volatility:Local sweetener supply concentrates in Saudi Arabia's Al-Qassim region, exposing formulations to climatic yield fluctuations and procurement cost spikes.
- Flexible-Film Technical Barriers:Gulf Standardization Organization packaging material regulations impose barrier-property requirements that limit supplier qualification to specialized converters.
- Fresh Snack Substitution:Chilled dairy desserts and grab-and-go fruit cups compete for the same impulse-purchase occasions in climate-controlled retail environments.
Strategic Opportunities
- Kuwait and Bahrain Penetration:Underdeveloped modern-trade infrastructure in secondary Gulf cities offers whitespace for direct-store-distribution models ahead of hypermarket saturation.
- Sugar-Tax Anticipation:Preemptive portfolio pivot toward no-added-sugar and stevia-sweetened variants positions suppliers ahead of anticipated Gulf Cooperation Council fiscal policy alignment.
- Online-First Teen Segmentation:Social-commerce integration and influencer-curated subscription boxes capture disproportionate growth velocity among digital-native consumers.
Industry Challenges
- Food Technologist Scarcity:Formulation expertise in ambient-stable protein binding and shelf-life extension remains concentrated with multinational R&D hubs, constraining local product development velocity.
- Co-Packer Qualification Timelines:Halal audit and SFDA facility registration cycles extend new entrant time-to-market by 8-14 months versus established contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Snack Bar Market |
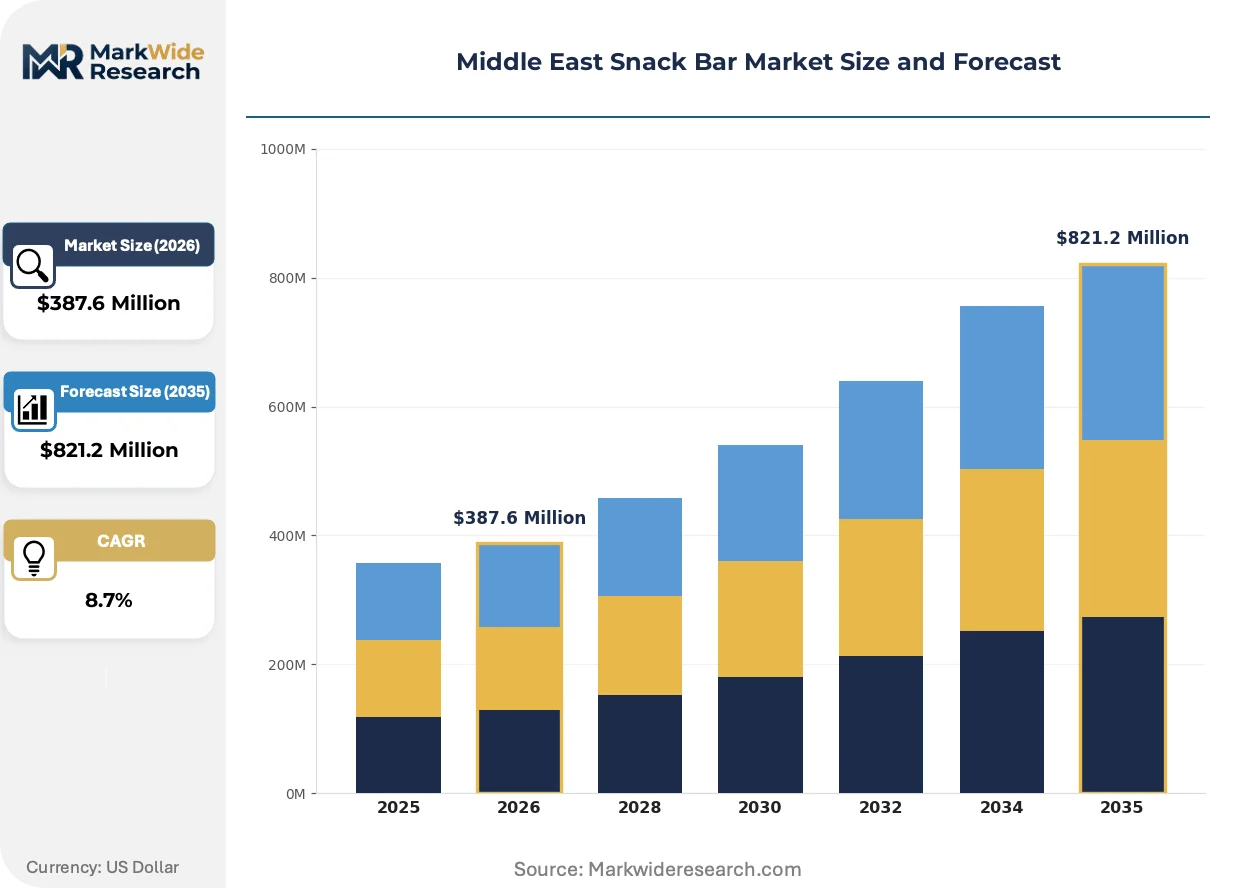
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Bars, Protein Bars, Granola Bars, Rice Snacks Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packing Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Individually Wrapped Consumer Age Group: Children, Teenagers, Adults, Seniors |
| Companies Covered | PepsiCo, Mondelēz, Nestlé, Ferrero International SA, Almarai, Mars, General Mills, Associated British Foods PLC, Kellogg, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Snack Bar Market Trends and Innovations
Cold-pressed processing and clean-label binding systems are displacing conventional extrusion methods across premium-tier launches. Three concurrent developments are compressing traditional competitive advantages while opening new positioning territory.
Cold-pressed bar technology preserves heat-sensitive micronutrients and enables raw-positioning claims without synthetic preservatives. Premium urban consumers in Jeddah and Dubai are adopting these formats at double the rate of conventional extruded alternatives. This processing shift is rendering obsolete legacy hot-extrusion lines that require capital-intensive retrofit for clean-label compliance.
SFDA front-of-pack nutritional warning label requirements are mandating reformulation across sugar-dense legacy SKUs. Industrial consequence includes accelerated R&D spend on natural sweetener systems and fiber-bulked matrices. Protein Bar sub-segments face the steepest compliance burden, with manufacturers racing to achieve sub-5% added-sugar thresholds ahead of enforcement windows.
Corporate procurement of snack bars for employee wellness programs is consolidating volume through direct B2B contracts, bypassing traditional retail markup structures. Foodservice distributors and office-catering platforms are capturing this volume at the expense of supermarket promotional bundles. Saudi Aramco and Emirates Group headquarters canteens exemplify this demand migration toward institutional channels.
Middle East Snack Bar Market Segmentation
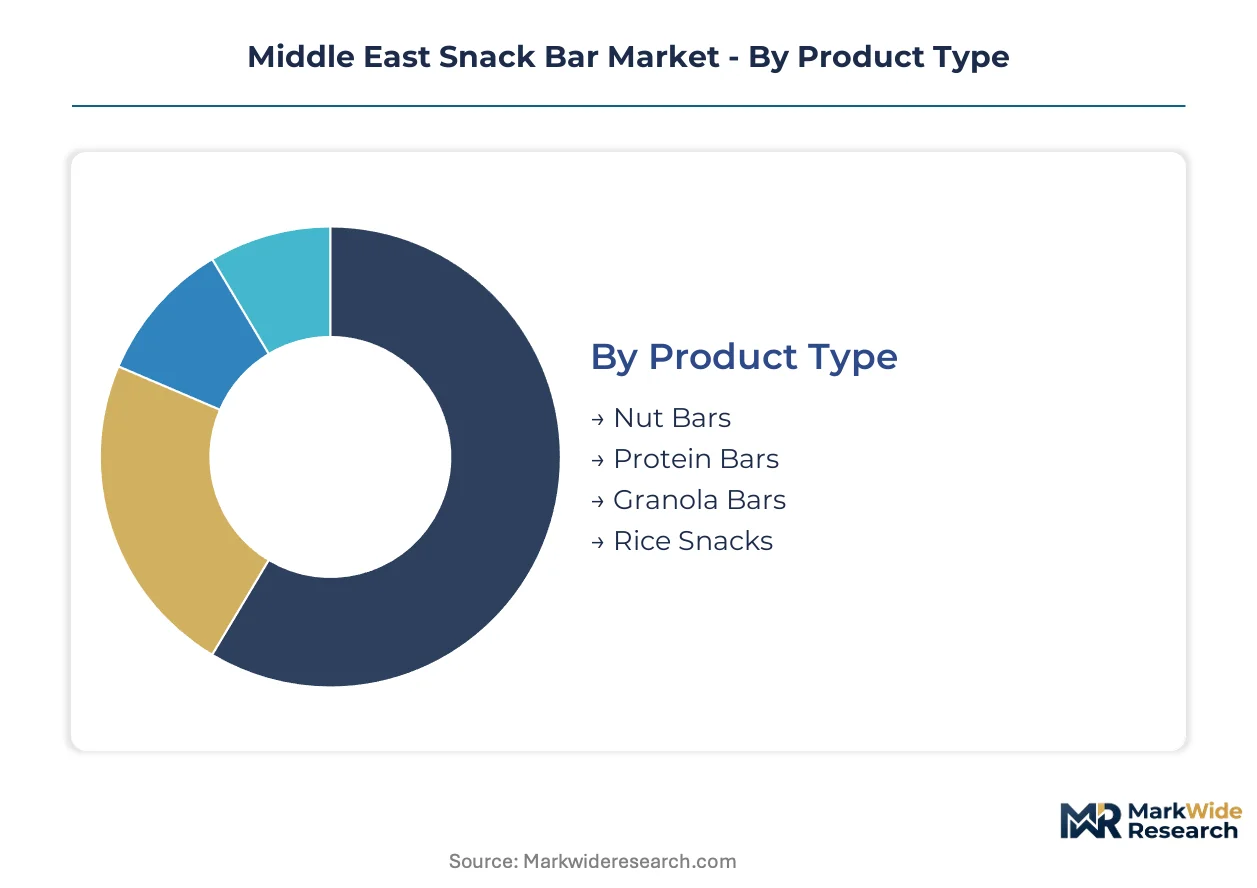
Segmentation in the Middle East Snack Bar Market reveals how consumption patterns split across functional needs, purchase occasions, and demographic life stages. Understanding these divides exposes where margin concentrates and which channels are capturing volume migration.
Product Type:
Inventory velocity varies dramatically across formats, with protein-fortified variants turning fastest in gym-adjacent retail while nut-based staples maintain steadier replenishment cycles in family-oriented channels.
- Protein Bars:Extruded or cold-pressed formats with protein content exceeding 15g per serving, typically employing whey or plant-based isolates. Demand clusters in Riyadh and Dubai corporate districts where gym culture and workplace wellness programs intersect, pulling volume from conventional confectionery aisles. Reformulation pressure from SFDA nutritional warning labels is accelerating R&D spend on sub-5% added-sugar variants.
- Nut Bars:Cold-pressed or baked formats combining almonds, dates, and pistachios with minimal binders. Jeddah and traditional retail corridors in Saudi Arabia's central region anchor volume, with date syrup supply volatility from Al-Qassim region exposing margins to climatic yield fluctuations.
- Granola Bars:Baked oat-based formats with honey or date binding systems. Breakfast substitution and school lunchbox occasions sustain baseline demand across GCC supermarket chains.
- Rice Snacks:Puffed or extruded rice matrices with savory or sweet coatings. Price-sensitive positioning captures impulse purchases in convenience channels throughout secondary Gulf cities.
Protein Bars anchor the volume base while Nut Bars gain share at the steepest rate as clean-label positioning displaces legacy extruded alternatives.
Distribution Channel:
Channel economics diverge sharply between high-touch retail requiring cold-chain integrity and digital-native routes capturing subscription velocity among younger cohorts.
- Supermarkets:Hypermarket and supermarket chains across Dubai, Riyadh, and Jeddah dominate volume through promotional bundling and strategic impulse placement at checkout zones. PepsiCo leverages beverage distribution infrastructure to secure shelf positioning in these formats.
- Online Retail:E-commerce platforms and direct-to-consumer subscription models. Teenagers and young adults in urban Saudi Arabia and the UAE drive disproportionate growth velocity through social-commerce integration and influencer-curated boxes.
- Convenience Stores:Petrol station forecourts and urban corner stores. Grab-and-go occasions in climate-controlled environments compete directly with chilled dairy desserts.
- Specialty Stores:Health food retailers and gym-adjacent nutrition shops. Premium positioning and personalized consultation support margin capture for protein-fortified formats.
Supermarkets retain volume leadership while Online Retail expands most quickly as digital-native consumers bypass traditional retail markup structures.
Packing Type:
Packaging investment priorities split between barrier-property compliance for ambient stability and sustainability positioning for premium tier differentiation.
- Flexible Packaging:Metallized films and multi-layer laminates ensuring moisture content below 12% for ambient shelf stability. Gulf Standardization Organization barrier-property requirements limit supplier qualification to specialized converters with halal-certified facilities.
- Individually Wrapped:Single-serve formats enabling portion control and on-the-go consumption. Corporate wellness programs and institutional procurement favor this format for canteen and office-catering distribution.
- Rigid Packaging:Carton or tray formats for multi-bar retail presentation. Premium tier launches in Dubai and Jeddah employ rigid secondary packaging for gift and subscription box applications.
- Bulk Packaging:Multi-unit bags for club retail and foodservice channels. Cost-per-unit optimization targets family households and institutional buyers with predictable consumption patterns.
Flexible Packaging anchors the volume base while Individually Wrapped formats climb the fastest as institutional channels bypass traditional retail structures.
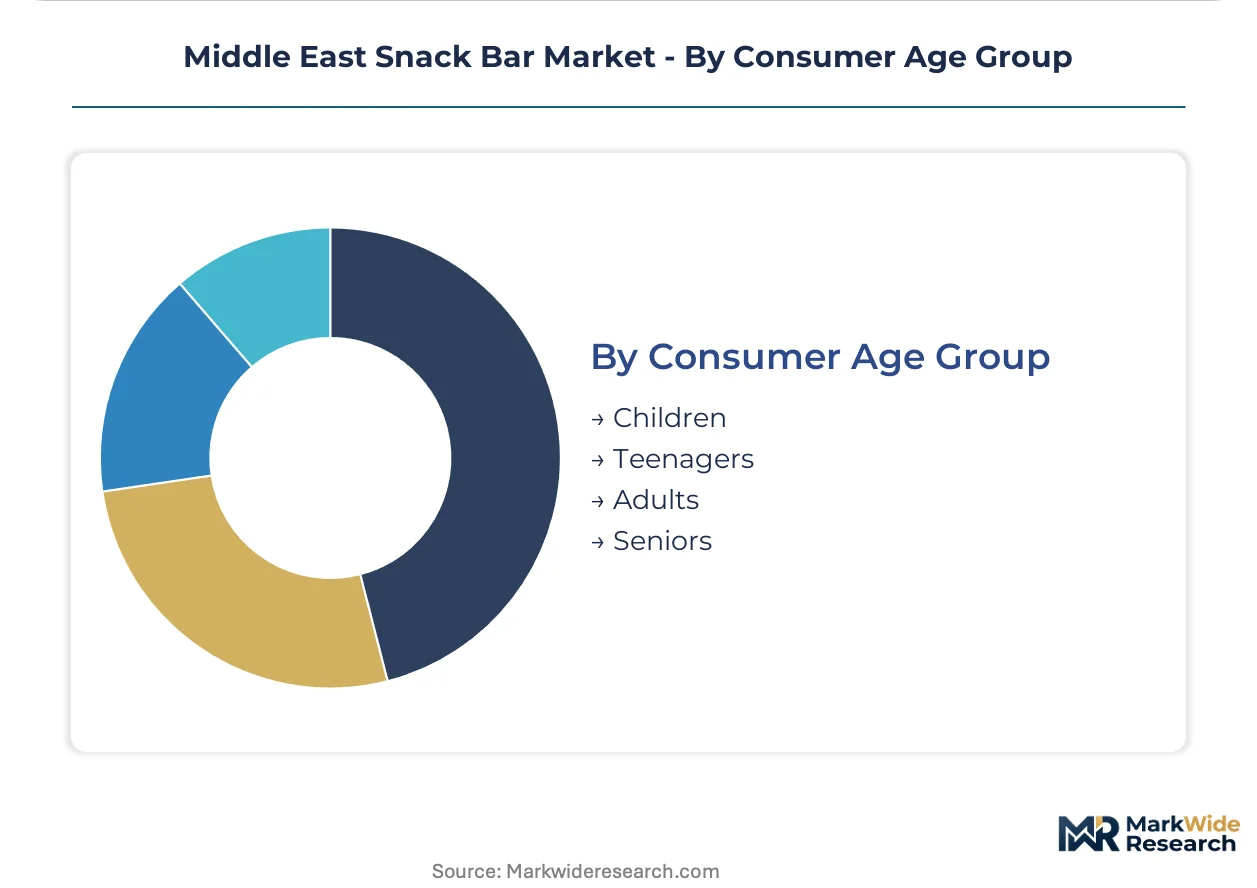
Consumer Age Group:
Life-stage segmentation exposes divergent price sensitivity, with younger cohorts accepting premium positioning for functional claims while family purchasers prioritize value engineering.
- Adults:Working-age professionals aged 25-45 in urban Saudi Arabia and the UAE. Corporate wellness program procurement and gym culture adoption concentrate demand for protein-fortified formats with clean-label positioning.
- Teenagers:Digital-native consumers aged 13-19. Social-commerce integration and influencer marketing drive trial velocity, with subscription box models capturing recurring revenue at the expense of supermarket promotional bundles.
- Children:School-age consumers with parent-mediated purchase decisions. Lunchbox-compatible formats and fortified positioning for growth support sustain demand in family-oriented retail channels.
- Seniors:Consumers aged 60+ with texture-modified and low-glycemic requirements. Underdeveloped product development velocity constrains penetration relative to other age cohorts.
Adults anchor the volume base while Teenagers gain share fastest as digital channels reshape purchase pathways away from traditional retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes snack bars primarily through institutional wellness channels, while UAE demand concentrates in premium retail and digital-native subscription models, creating a bifurcated consumption architecture across the Gulf.
Saudi Arabia
Riyadh and Jeddah anchor volume through corporate canteen procurement at Saudi Aramco and Emirates Group headquarters. SFDA nutritional labeling mandates are accelerating reformulation timelines for sugar-dense legacy SKUs. Al-Qassim region date syrup supply volatility exposes nut-bar margins to climatic yield fluctuations.
United Arab Emirates
Dubai's gym-adjacent retail and social-commerce integration drive protein-fortified and cold-pressed format adoption among young professionals. MOHAP halal-certification protocols streamline cross-border market access for international suppliers. Abu Dhabi institutional procurement is consolidating volume through direct B2B contracts bypassing traditional retail markup.
Kuwait
Underdeveloped modern-trade infrastructure in secondary Gulf cities creates whitespace for direct-store-distribution models. Family-oriented channels sustain granola bar demand for breakfast substitution and school lunchbox occasions. Urban corner stores compete directly with chilled dairy desserts for impulse-purchase occasions.
Qatar
Corporate wellness program proliferation across Doha commercial districts pulls demand from conventional confectionery aisles. Premium positioning in health food retailers supports margin capture for protein-fortified formats. Climate-controlled retail environments intensify competition with grab-and-go fresh snack alternatives.
Bahrain
Teenage digital-native consumers drive trial velocity through influencer-curated subscription boxes. Convenience store channels at petrol station forecourts capture grab-and-go occasions. Secondary city penetration offers expansion runway ahead of hypermarket saturation in larger Gulf markets.
Middle East Snack Bar Market Competitive Landscape
Capability concentration sits with multinational R&D hubs possessing formulation expertise in ambient-stable protein binding; scale advantage sits with Gulf-based dairy and beverage conglomerates leveraging backward integration into protein inputs and cold-chain infrastructure. The vendor base splits between global FMCG majors with beverage distribution synergies and regional dairy specialists with captive ingredient supply. Three archetypes dominate: multinational brand owners defending shelf position through infrastructure investment, regional dairy-integrated players controlling protein input costs, and private-label contract manufacturers capturing margin through co-packing flexibility. Competitive moves center on halal certification harmonization and preemptive sugar-tax portfolio pivoting.
Among multinational brand owners, PepsiCo and Nestlé occupy positions defined by beverage distribution infrastructure and global R&D scale respectively. PepsiCo leverages existing Gulf retail chain relationships to secure impulse-placement at checkout zones. Nestlé exemplifies the reformulation-responsive archetype as SFDA front-of-pack warning requirements force added-sugar threshold compliance. Almarai anchors the regional-integrated tier through captive dairy-based protein supply and Saudi cold-chain logistics dominance.
| Leading Market Players |
|---|
| PepsiCo |
| Mondelēz |
| Nestlé |
| Ferrero International SA |
| Almarai |
| Mars |
| General Mills |
| Associated British Foods PLC |
| Kellogg |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali Port freight corridors from Dubai anchor cost dynamics for date syrup and protein isolate shipments, concentrating procurement leverage among Saudi and UAE distributors while downstream pricing stratifies across premium clean-label and economy extruded tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between Almarai and Al-Qassim date syrup cooperatives, insulating nut-bar margins from spot volatility while protein-fortified variants command premium-mid-economy pricing differentiation based on halal certification tier and cold-chain delivery guarantees. SFDA nutritional warning label compliance is compressing sugar-dense legacy SKU margins, with institutional buyers at Saudi Aramco and Emirates Group headquarters showing lowest price sensitivity due to wellness program budgets, while family-oriented channels in Kuwait and Bahrain remain most cost-conscious.
Supply Chain Analysis
Upstream feedstock for whey protein isolates draws from New Zealand and EU dairy processors, while date syrup supply rests on Saudi Arabia's Al-Qassim region and UAE domestic cultivation. Flexible-film laminates hinge on specialized converters in Turkey and India qualified under Gulf Standardization Organization barrier-property protocols. Single-source vulnerability concentrates in halal-certified facility registration cycles that extend co-packer qualification timelines. Distribution runs through PepsiCo beverage infrastructure and Almarai cold-chain logistics across GCC metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment; SFDA facility registration and halal audit cycles create switching costs that protect incumbent positions against faster-moving international entrants lacking local certification velocity.
For Market Incumbents: Harden shelf positioning through backward integration into Al-Qassim date syrup procurement and captive cold-chain infrastructure investments across Riyadh and Jeddah distribution nodes. Accelerate reformulation R&D on sub-5% added-sugar variants ahead of anticipated Gulf Cooperation Council sugar-tax alignment, using PepsiCo-style beverage channel leverage to block private-label contract manufacturer encroachment at hypermarket checkout zones. For New Entrants and Emerging Players: Build out direct-store-distribution models in Kuwait and Bahrain secondary cities where modern-trade infrastructure remains underdeveloped ahead of hypermarket saturation. Target teenage digital-native segments through influencer-curated subscription boxes and social-commerce integration, bypassing established retail markup structures that favor incumbent scale advantages in supermarket promotional bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational FMCG parents seeking to divest non-core snack bar portfolios lacking Gulf-specific halal certification infrastructure. Mid-term viability through the projection horizon depends on acquiring facilities with existing SFDA registration and GSO-compliant flexible-film supply relationships. Monitor sugar-tax legislative momentum across Gulf Cooperation Council jurisdictions as the primary inflection signal for portfolio pivot timing.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Harmonization | UAE MOHAP protocols streamline cross-border market access for international suppliers targeting GCC corridors. |
| Cold-Chain Infrastructure Expansion | Almarai's dairy logistics network secures ambient-stable distribution for protein-fortified formats in Saudi Arabia. |
| Clean-Label Reformulation | SFDA front-of-pack warning requirements force added-sugar threshold compliance across legacy SKUs. |
| Direct-to-Consumer Subscription Launch | Social-commerce integration captures recurring revenue from teenage digital-native consumers bypassing retail markup. |
| Private-Label Contract Manufacturing Scale-Up | Co-packing flexibility redistributes margin capture from brand equity toward production scale across Gulf retail networks. |
Research Methodology
A standing panel of category buyers at Carrefour and Lulu hypermarkets, protein bar brand managers, SFDA regulatory affairs consultants, and cold-chain logistics operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against Nielsen retail audit data, Saudi Customs import records, Gulf Standardization Organization technical bulletins, and SEC 10-K filings from listed snack bar parents. Bottom-up volume modeling from SKU-level retail velocity and top-down macroeconomic triangulation anchored the analytical framework.
Scenario-bracketing around sugar-tax implementation timing and date syrup yield volatility shaped the projection horizon. Segmentation dimensions modeled include product type, distribution channel, packaging format, and consumer age cohort across the analysis window. CAGRs derived from historical velocity trends and forward-looking regulatory compliance cost curves, with protein-fortified format adoption rates and institutional channel migration serving as key forecast inputs.
Stress conditions across Al-Qassim climatic yield bands, SFDA enforcement window timing, and Gulf Cooperation Council fiscal policy coordination were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about halal certification harmonization progress and cold-chain infrastructure investment continuity. Cross-checking against IEA food price indices and regional retail sales benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Sugar Fruit Snacks Market
Snacks
Fiber Bars Market
Snacks
Vegan Protein Balls Market
Snacks
Low Fat Sweet Snacks Market
Snacks
Europe Snack Bar Market
Snacks
South Korea Snack Bar Market
Snacks
North America Frozen Snacks Market
Snacks
Brazil Snack Bar Market
Snacks
Extruded Snacks Market
Snacks
Super Low Calorie Snacks Market
Snacks
Baked Chips Market
Snacks
United States Children's Snack Bar Market
Snacks
Organic Chips Market
Snacks
United States Popcorn Market
Snacks
North America Energy Bar Market
Snacks
North America Potato Chips Market