
 Italy Automotive Composites Market | 2026-2036
Italy Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Composites Market Foresight
Subscription-based predictive maintenance software for composite component health monitoring is hardening into a standard offering alongside physical material supply. Solvay S.A. leverages its fluoropolymer heritage to dominate high-performance resin formulations for Italian OEM programs. Toray Industries, Inc. anchors carbon fiber prepreg supply to premium vehicle platforms assembled in the Piedmont region. Hexcel Corporation specializes in intermediate modulus fiber grades that sustain structural certification margins under tightening load-bearing specifications.
Automotive composites are fiber-reinforced polymer systems combining continuous or chopped reinforcement with thermoset or thermoplastic matrices, engineered to achieve specific strength-to-weight ratios exceeding 150 MPa per g/cm³ for primary structural duty. Their industrial purpose centers on mass reduction without sacrificing crashworthiness or stiffness targets set by vehicle platform architects. Glass fiber composites retain volume leadership across body panel and interior component applications where cost sensitivity limits carbon fiber penetration. Carbon fiber composites command premium positioning in chassis and structural parts where Italian OEMs pursue top-decile stiffness metrics. Hybrid composites occupy an emerging middle ground, blending fiber types to optimize performance-per-euro across Tier-1 supplier portfolios serving mixed-model assembly lines.
Italy's national automotive composites sector operates under the EU Green Deal framework, REACH chemical registration requirements, and Euro 7 emissions standards that collectively mandate lighter vehicle architectures to offset powertrain compliance costs. ECHA substance restrictions on certain epoxy curing agents are reshaping formulation choices among compounders supplying Italian Tier-1 networks. Stakeholders must monitor how delegated acts under the EU AI Act could impose conformity assessment burdens on predictive design software used for composite layup optimization.
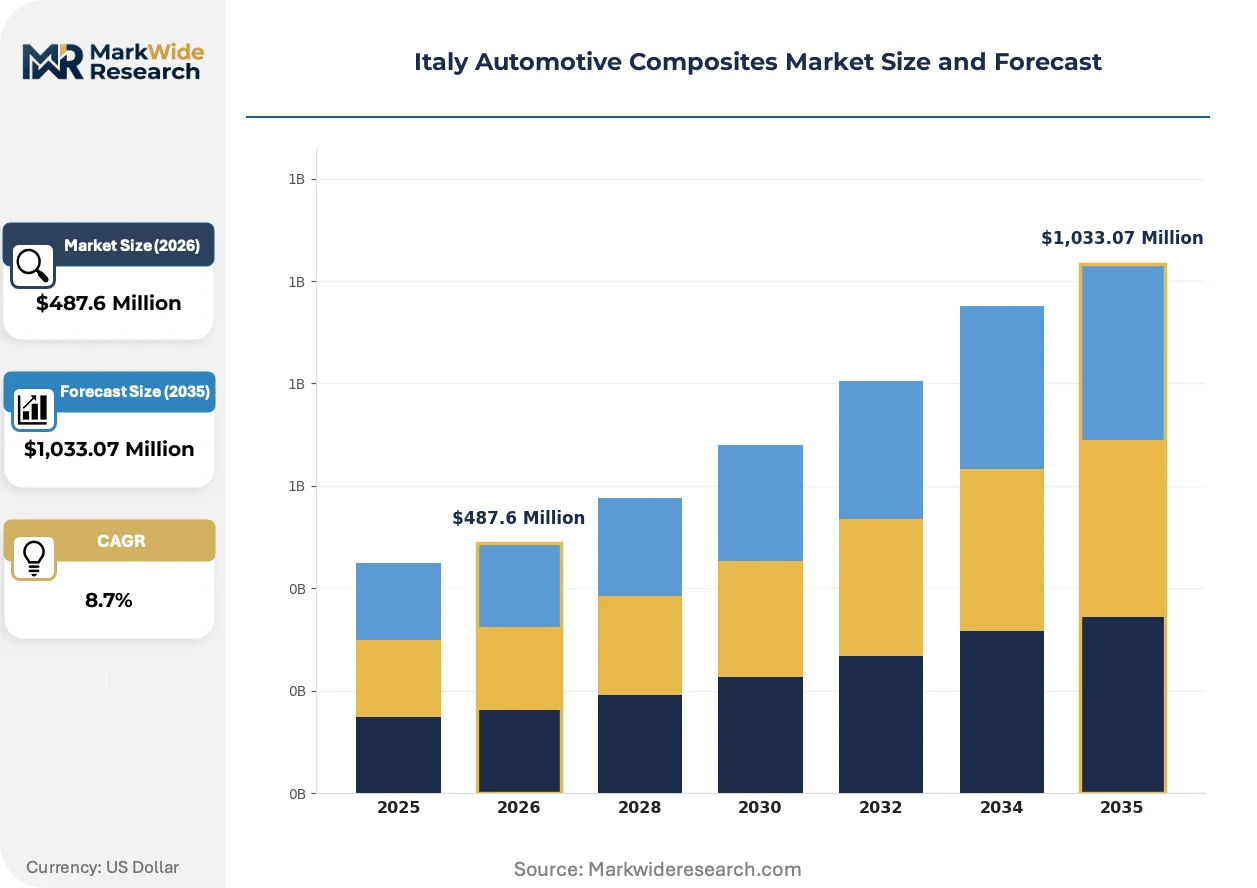
Market Dynamics
EU fleet emissions targets are forcing Italian OEMs to reweight vehicle architectures toward carbon fiber-intensive platforms, compressing substitution timelines for aluminum-intensive body-in-white structures. This regulatory pressure cascade is restructuring supplier qualification protocols across the Piedmont manufacturing corridor.
Growth Catalysts
- Euro 7 Standards:The forthcoming emissions framework mandates mass reduction pathways that elevate composite penetration in chassis and structural assemblies. Italian OEMs are accelerating platform redesigns to preempt compliance cost escalation.
- Turin-Milan Manufacturing Corridor:Concentrated Tier-1 supplier networks surrounding these cities enable just-in-time prepreg delivery to premium vehicle assembly plants. Proximity reduces logistics friction for time-sensitive autoclave processing.
- Thermoplastic Resin Systems:Out-of-autoclave processing technologies are compressing cycle times for high-volume structural components. Italian compounders are qualifying these systems for A-pillar and floor pan applications.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs swing with energy market fluctuations, destabilizing margin forecasts for Italian Tier-1 suppliers locked into annual OEM pricing agreements.
- Japanese Carbon Fiber Concentration:Toray Industries and Mitsubishi Chemical control upstream PAN-based fiber supply, exposing Italian converters to currency hedge complexity and allocation priority risks during demand surges.
- ECHA Curing Agent Restrictions:REACH substance evaluations are phasing out certain amine hardeners used in epoxy formulations, forcing reformulation investments without performance equivalence guarantees.
Strategic Opportunities
- Southern Italy Supplier Base:Underdeveloped composite conversion capacity in Campania and Sicily offers greenfield expansion potential for Tier-1 suppliers seeking labor cost arbitrage against northern wage structures.
- Battery Enclosure Applications:Electric vehicle platform proliferation is creating demand for flame-retardant composite housings that meet ECE R100 thermal propagation standards. Italian compounders are qualifying phenolic and PEEK-based systems for this specification.
- EU Green Deal Industrial Policy:Strategic autonomy funding streams are subsidizing domestic carbon fiber precursor production. Italian chemical producers are bidding for conversion grants to reduce import dependency.
Industry Challenges
- Autoclave Technician Scarcity:Specialized layup and cure monitoring expertise is concentrated among aging workforces in Turin province. Vocational training pipelines are insufficient to replace retirements at current qualification throughput rates.
- Multi-Material Joining Certification:OEM structural warranty requirements demand validated adhesive and mechanical fastening protocols for carbon fiber-to-aluminum interfaces. Italian engineering service providers are absorbing extended validation timelines that compress program margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Composites Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Plastics, Carbon Fiber Composites, Glass Fiber Composites, Hybrid Composites Application: Body Panels, Interior Components, Structural Parts, Chassis End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Specialty Vehicle Manufacturers Form: Sheet, Rod, Tube, Custom Shapes |
| Companies Covered | Solvay S.A., Gurit Holding AG, Toray Industries, Inc., BASF SE, Hexcel Corporation, SGL Carbon SE, Teijin Limited, 3B Fiberglass, Mitsubishi Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Composites Market Shifts & Advancements
Digital thread integration across design-to-manufacture workflows is compressing composite component development cycles. Italian OEMs are mandating predictive simulation fidelity that reduces physical prototype iterations.
Automated fiber placement systems are integrating robotic tow steering with in-situ consolidation for complex geometric preforms. Tier-1 suppliers serving Ferrari and Lamborghini programs are adopting these lines to achieve the surface quality tolerances required for Class-A body panels. The technology is integrating quality assurance directly into the layup process, eliminating downstream inspection bottlenecks.
REACH delegated acts on substance restrictions are forcing systematic substitution of bisphenol-A based epoxy formulations. Italian compounders are accelerating bio-based hardener qualification to maintain ECHA compliance without sacrificing Tg performance thresholds. High-voltage battery enclosure applications face the tightest reformulation timelines due to combined thermal and electrical safety certifications.
Subscription-based predictive maintenance software is displacing traditional warranty coverage for composite structural components. Italian fleet operators and premium vehicle owners are accepting per-kilometer monitoring fees that transfer degradation risk to material suppliers. This model concentrates in commercial vehicle segments where downtime costs exceed subscription premiums.
Italy Automotive Composites Market Segmentation
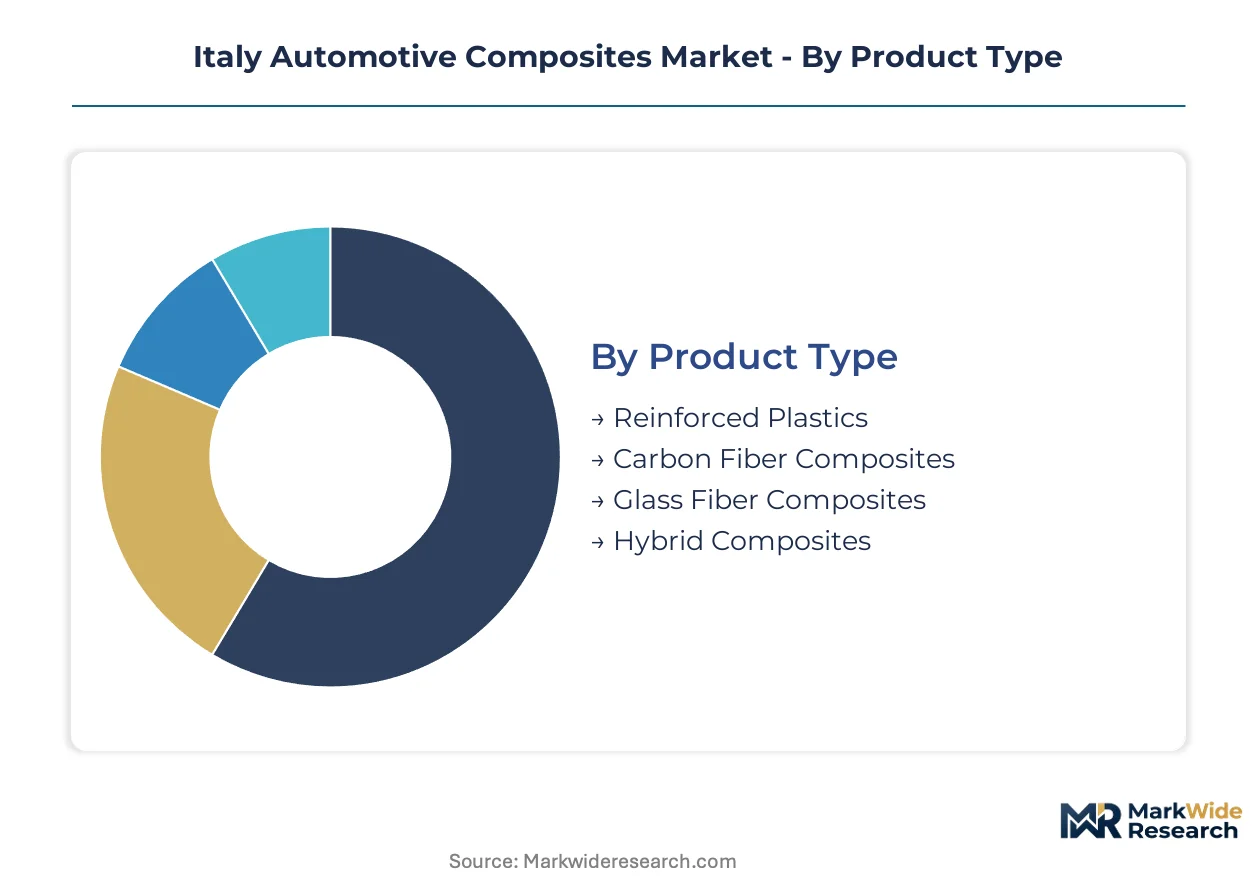
Segmentation in Italy's automotive composites market reveals how material selection, manufacturing form, and supply chain position determine procurement economics. Italian OEMs and Tier-1 suppliers navigate distinct technical and commercial trade-offs across each dimension, from fiber type to end-user category.
Product Type:
Customization intensity varies sharply across this category, with commodity-grade formulations at one pole and application-specific hybrids at the other.
- Reinforced Plastics:Thermoset and thermoplastic matrices loaded with short or long glass fiber deliver cost-efficient stiffness for non-structural applications. Demand clusters with Fiat Stellantis volume platforms manufactured in Pomigliano d'Arco, where per-part cost targets override performance margins.
- Carbon Fiber Composites:Continuous fiber prepregs and RTM systems achieve specific modulus values exceeding 130 GPa, enabling primary structural duty. Ferrari and Lamborghini programs in Modena and Sant'Agata Bolognese absorb premium-grade Toray T800S fiber allocations for monocoque chassis.
- Glass Fiber Composites:E-glass and S-glass formulations dominate bumper beams, underbody shields, and engine covers where corrosion resistance matters more than weight minimization.
- Hybrid Composites:Glass-carbon blends optimize performance-per-euro for mixed-material platforms transitioning from aluminum-intensive architectures.
Leading the category by volume: Glass Fiber Composites. Growing fastest: Carbon Fiber Composites.
Application:
Cost tier stratification separates visible Class-A surfaces from hidden structural elements, with certification burden rising toward safety-critical assemblies.
- Body Panels:Class-A surfaces demand in-mold coating compatibility and thermal expansion matching to metal adjacent components. Lamborghini Huracán replacement panels require 0.1mm dimensional tolerance achievable only with autoclave-cured carbon fiber prepreg.
- Interior Components:Dashboard carriers, door modules, and seat structures prioritize acoustic damping and low VOC emissions over structural load-bearing.
- Structural Parts:A-pillars, B-pillars, and floor pans absorb crash energy and maintain cabin integrity during offset collisions. Euro NCAP rating pressures are accelerating CFRP adoption here.
- Chassis:Suspension cradles and subframes face multi-axial fatigue loading that disqualifies most thermoplastic formulations from primary duty.
Volume concentration: Interior Components. Steepest expansion trajectory: Structural Parts.
End User:
Customer type determines specification authority, with OEMs retaining material selection power for visible components while delegating subsystem design to Tier-1 networks.
- OEMs:Stellantis, Ferrari, and Lamborghini maintain direct composite procurement for proprietary platforms, qualifying suppliers through extended development cycles exceeding 36 months.
- Tier-1 Suppliers:Magneti Marelli and Brembo absorb composite conversion for brake ducts, aerodynamic elements, and thermal management housings.
- Aftermarket Providers:Tuning specialists and collision repair networks source pre-impregnated repair kits and adhesive systems for cosmetic carbon fiber restoration.
- Specialty Vehicle Manufacturers:Dallara and other low-volume constructors purchase raw fiber and resin separately to protect formulation intellectual property.
Procurement volume leader: Tier-1 Suppliers. Fastest contract growth: OEMs.
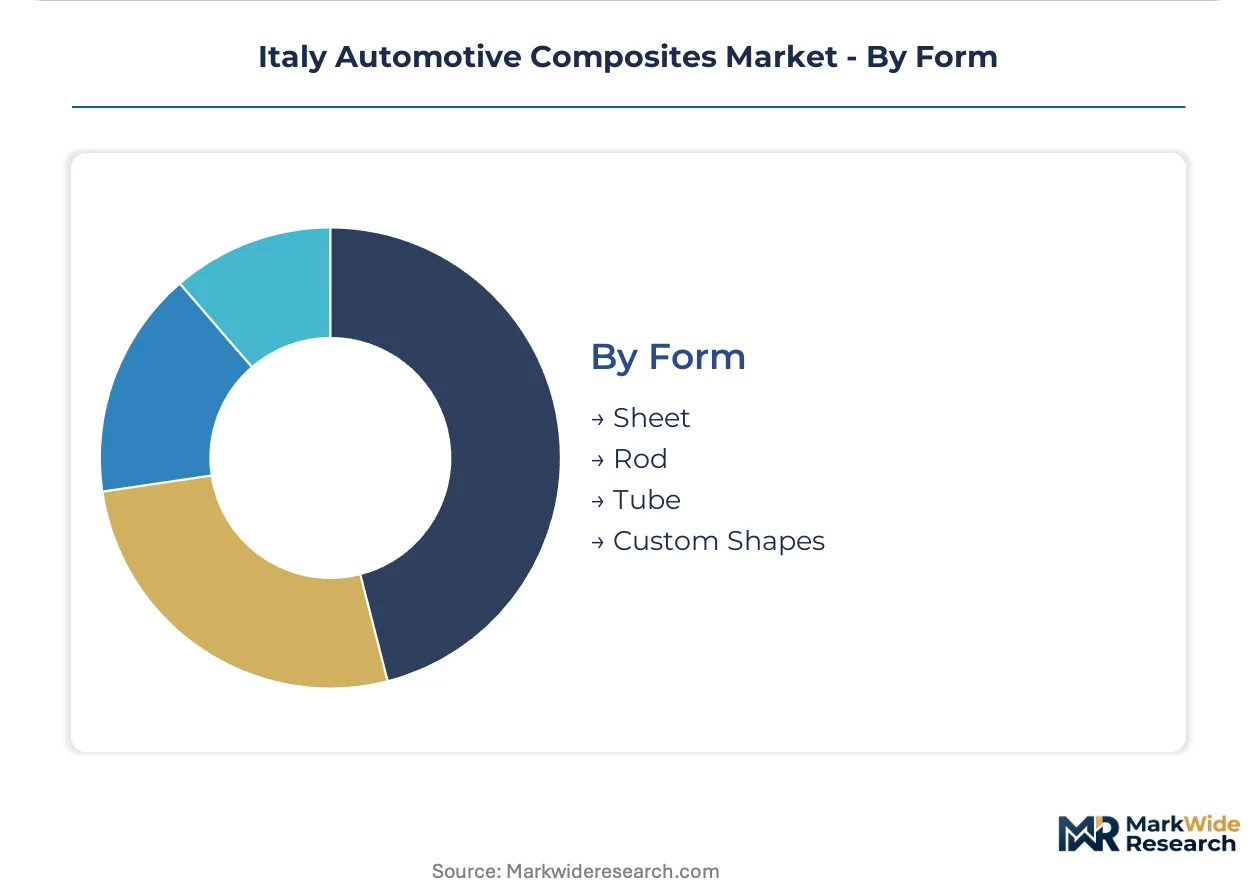
Form:
Supply concentration in the Turin-Milan corridor favors flat sheet and simple extrusions, with complex geometries requiring southern Italian or imported conversion capacity.
- Sheet:Compression-molded SMC and GMT panels serve hoods, trunk lids, and roof modules where planar geometry simplifies tooling investment.
- Rod:Pultruded profiles reinforce bumper beams and side-impact bars with unidirectional fiber alignment.
- Tube:Filament-wound and roll-wrapped hollow sections reduce mass in driveshafts and suspension links.
- Custom Shapes:Braided preforms and 3D-woven near-net shapes minimize scrap for complex nodes in spaceframe architectures.
Form distribution leader: Sheet. Fastest process adoption: Custom Shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turin anchors Italy's automotive composites demand through its concentration of Stellantis, Ferrari, and Lamborghini assembly operations. The Piedmont manufacturing corridor generates procurement pull for carbon fiber prepregs and structural thermoplastic systems. Northern Italy's Tier-1 supplier density enables just-in-time material flows that southern regions cannot yet replicate.
Piedmont
Ferrari's Maranello-adjacent operations and Stellantis Mirafiori complex drive carbon fiber chassis demand exceeding regional supply capacity. EU Green Deal industrial policy subsidies are attracting precursor conversion investments to reduce import dependency from Japanese suppliers. Turin province hosts specialized autoclave processing facilities serving Lamborghini's Sant'Agata Bolognese assembly plant.
Lombardy
Milan's engineering service providers absorb extended validation timelines for multi-material joining certification between carbon fiber and aluminum. REACH delegated acts on epoxy curing agents are forcing systematic reformulation investments among compounders headquartered in the region. The Monza-Brianza industrial zone concentrates thermoplastic resin system qualification for A-pillar applications.
Emilia-Romagna
Lamborghini's Sant'Agata Bolognese facility commands premium-grade fiber allocations for monocoque architectures. Motor Valley's motorsport heritage sustains specialized workforce pipelines for complex layup operations. Modena province hosts automated fiber placement system integrators serving Class-A body panel specifications.
Veneto
Glass fiber composite demand clusters with Fiat Stellantis volume platforms manufactured in Pomigliano d'Arco. ECHA substance restrictions on amine hardeners are reshaping formulation choices among regional compounders. Vicenza province's pultrusion specialists supply bumper beam profiles to Tier-1 networks across northern Italy.
Campania
Underdeveloped composite conversion capacity offers greenfield expansion potential for suppliers seeking labor cost arbitrage. Strategic autonomy funding streams are subsidizing domestic precursor production bids from chemical producers near Naples. The region lacks qualified autoclave technician pipelines that northern provinces maintain through vocational training networks.
Italy Automotive Composites Market Competitive Landscape
Capital-heavy resin formulators compete with asset-light fiber distributors across Italy's automotive composites procurement channels. The supplier base concentrates around three strategic tiers: integrated chemical conglomerates controlling upstream polymer supply, specialized carbon fiber converters serving premium OEM programs, and regional compounders qualifying thermoplastic systems for volume platforms. Dominant competitive moves include backward integration into precursor production and strategic partnerships for out-of-autoclave processing technology licensing.
Among Belgian chemical conglomerates, Solvay S.A. occupies a position exemplifying fluoropolymer heritage leveraged into high-performance resin formulations. Toray Industries, Inc. anchors the Japanese carbon fiber supply vector to Italian OEM programs. Gurit Holding AG represents the specialized converter archetype serving premium vehicle platforms. Hexcel Corporation exemplifies intermediate modulus fiber specialists sustaining structural certification margins. These three named entities—Solvay S.A., Toray Industries, Inc., and Hexcel Corporation—sit within distinct competitive tiers that Italian Tier-1 suppliers navigate during procurement qualification.
| Leading Market Players |
|---|
| Solvay S.A. |
| Gurit Holding AG |
| Toray Industries, Inc. |
| BASF SE |
| Hexcel Corporation |
| SGL Carbon SE |
| Teijin Limited |
| 3B Fiberglass |
| Mitsubishi Chemical Corporation |
| Others |
Supply & Pricing Matrix
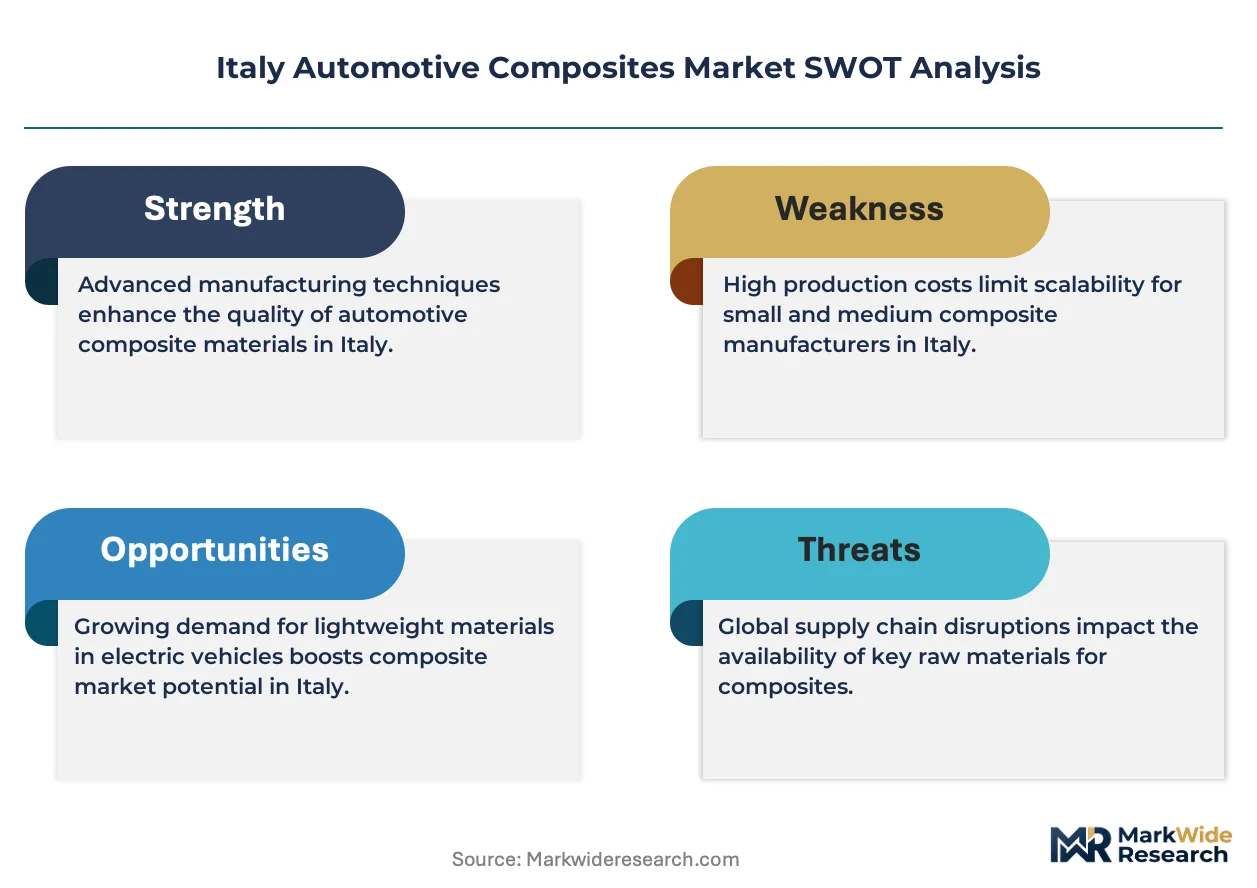
Out-of-autoclave thermoplastic processing is compressing cycle times for Italian Tier-1 suppliers while simultaneously redistributing cost economics away from energy-intensive autoclave curing toward capital-light press forming. This method shift concentrates pricing power among compounders mastering rapid-cure resin chemistry, squeezing converters locked into legacy epoxy autoclave infrastructure.
Pricing Analysis
Subscription-based per-kilometer monitoring fees for composite structural health now anchor value-based pricing for premium Italian fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates Ferrari-grade T800S carbon fiber prepreg from Fiat Stellantis volume SMC formulations and generic glass fiber bumper beam compounds. Pricing pressure stems from acrylonitrile feedstock volatility destabilizing margin forecasts for northern Italian converters. Volume platform procurement teams at Pomigliano d'Arco exhibit extreme price sensitivity, while Lamborghini and Ferrari chassis engineering tolerates premium markups for certified structural prepregs.
Supply Chain Analysis
Polyacrylonitrile precursor supply rests on Japanese specialty chemical producers Toray Industries and Mitsubishi Chemical, exposing Italian converters to yen-denominated hedge complexity and allocation priority risks during demand surges. Raw material dependencies center on acrylonitrile monomer, epoxy resin formulations, and fluoropolymer hardener systems. Single-source vulnerability concentrates in intermediate modulus carbon fiber grades where Hexcel and Toray dominate qualification protocols. Distribution runs through just-in-time prepreg delivery networks clustered in the Turin-Milan corridor, with southern Italian regions lacking comparable logistics density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian automotive composites is consolidating around compounders with captive precursor access and qualified out-of-autoclave capacity, as ECHA substance restrictions and Euro 7 compliance costs force subscale operators toward exit.
For Market Incumbents: Lock in backward integration into PAN precursor production through EU Green Deal strategic autonomy grants before Japanese suppliers impose allocation rationing. Defend qualification status with Ferrari and Lamborghini by accelerating bio-based hardener certification ahead of REACH delegated acts phasing legacy amine systems. Prioritize autoclave technician apprenticeship pipelines in Turin province to preempt workforce attrition from aging layup specialists. For New Entrants and Emerging Players: Tier-2 engineering service providers in southern Italy represent the most penetrable channel partner type for greenfield composite conversion capacity seeking labor cost arbitrage against northern wage structures. Target Campania and Sicily for filament winding and pultrusion facilities serving underdeveloped bumper beam and driveshaft supply to Fiat Stellantis volume platforms. Pursue phenolic-based battery enclosure qualification as the fastest path to OEM sourcing approval under ECE R100 thermal propagation standards. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Belgian and German chemical conglomerates seeking Italian OEM program access. Long-term viability favors compounders with dual thermoset-thermoplastic qualification and southern European geographic diversification. Watch for EU carbon border adjustment mechanism implementation as the inflection signal triggering distressed asset availability among import-dependent northern Italian converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | EU Green Deal grants enable Italian chemical producers to reduce dependency on Japanese PAN fiber suppliers. |
| Out-of-Autoclave Processing Qualification | Thermoplastic resin systems compress cycle times for A-pillar and floor pan applications at Stellantis. |
| Bio-Based Hardener Certification | ECHA REACH restrictions on amine curing agents force systematic reformulation investments among Lombardy compounders. |
| Southern Italy Greenfield Expansion | Campania and Sicily offer labor cost arbitrage for Tier-1 suppliers serving Fiat volume platforms. |
| Battery Enclosure Composite Qualification | Phenolic and PEEK-based systems meet ECE R100 standards for electric vehicle thermal propagation containment. |
Research Methodology
Multi-period observation of EU fleet emissions compliance trajectories, ECHA substance restriction timelines, and OEM platform redesign cycles anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, composite compounder technical leads, and autoclave processing facility managers. Secondary validation drew from EU Green Deal policy documents, REACH delegated act drafts, Euro 7 regulatory impact assessments, and Italian industrial production statistics. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
The input-output matrix framed composite demand through vehicle production forecasts, content-per-vehicle assumptions by propulsion architecture and vehicle class, and regional production cluster allocation. Segmentation dimensions modeled encompassed fiber type, matrix chemistry, manufacturing form, application criticality, and end-user procurement authority. CAGRs derived from regression analysis of historical substitution patterns against regulatory compliance cost curves, incorporating carbon fiber price elasticity and thermoplastic adoption S-curves as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential suspension of EU Green Deal industrial policy funding, accelerated Euro 7 implementation delays, and breakthroughs in aluminum-intensive body-in-white architectures reversing composite substitution. Forecasts reflect documented assumptions about Japanese precursor supply continuity and Italian vocational training pipeline throughput. A small set of named triggers warrants ongoing watch: ECHA bisphenol-A epoxy restrictions, EU carbon border adjustment mechanism rollout, and Stellantis platform standardization decisions affecting composite content per vehicle.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Navigation Light Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
HCV Axles Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market