
 Truck Suspension System Market | 2026-2036
Truck Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Suspension System Market Analysis
Asset-light leasing and pay-per-mile financing arrangements is reconfiguring how fleet operators procure suspension systems, shifting capital burdens from buyers to suppliers and opening doors for mid-tier component makers. Hendrickson USA, L.L.C. leverages its domestic manufacturing footprint to anchor just-in-time contracts with major fleet lessors. ZF Friedrichshafen AG competes through integrated axle-suspension modules that reduce installation complexity at assembly plants. Meritor Inc. specializes in lightweight air suspension architectures that address federal weight-compliance thresholds without sacrificing payload capacity.
A truck suspension system comprises spring mechanisms, damping elements, and linkage assemblies engineered to isolate vehicle chassis from road irregularities while maintaining tire contact and load distribution. Modern heavy-duty configurations integrate air bellows with electronically controlled dampers to achieve variable ride height across gross vehicle weight ranges from 10,000 to 80,000 pounds. Air suspension leads product-type value generation due to its prevalence in Class 8 tractors and refrigerated trailers where cargo protection commands premium positioning. Leaf spring retains volume dominance in vocational and medium-duty segments where cost sensitivity and repair simplicity sustain aftermarket demand. Application-level margin pools concentrate in heavy-duty trucks where integrated air-ride seats and cab suspensions multiply per-vehicle component counts.
The EPA governs commercial vehicle emissions and fuel efficiency through Phase 3 standards that indirectly mandate weight reduction technologies including lightweight suspension materials. NHTSA enforces Federal Motor Vehicle Safety Standard 121 governing air brake and suspension performance under emergency stopping conditions. California Air Resources Board operates Advanced Clean Trucks rules that accelerate fleet turnover in the largest state market, creating compliance-driven demand spikes for qualifying suspension configurations. Stakeholders must monitor how pending federal axle-weight harmonization proposals interact with state-level zero-emission vehicle mandates to anticipate specification shifts before procurement cycles lock.
Market Dynamics
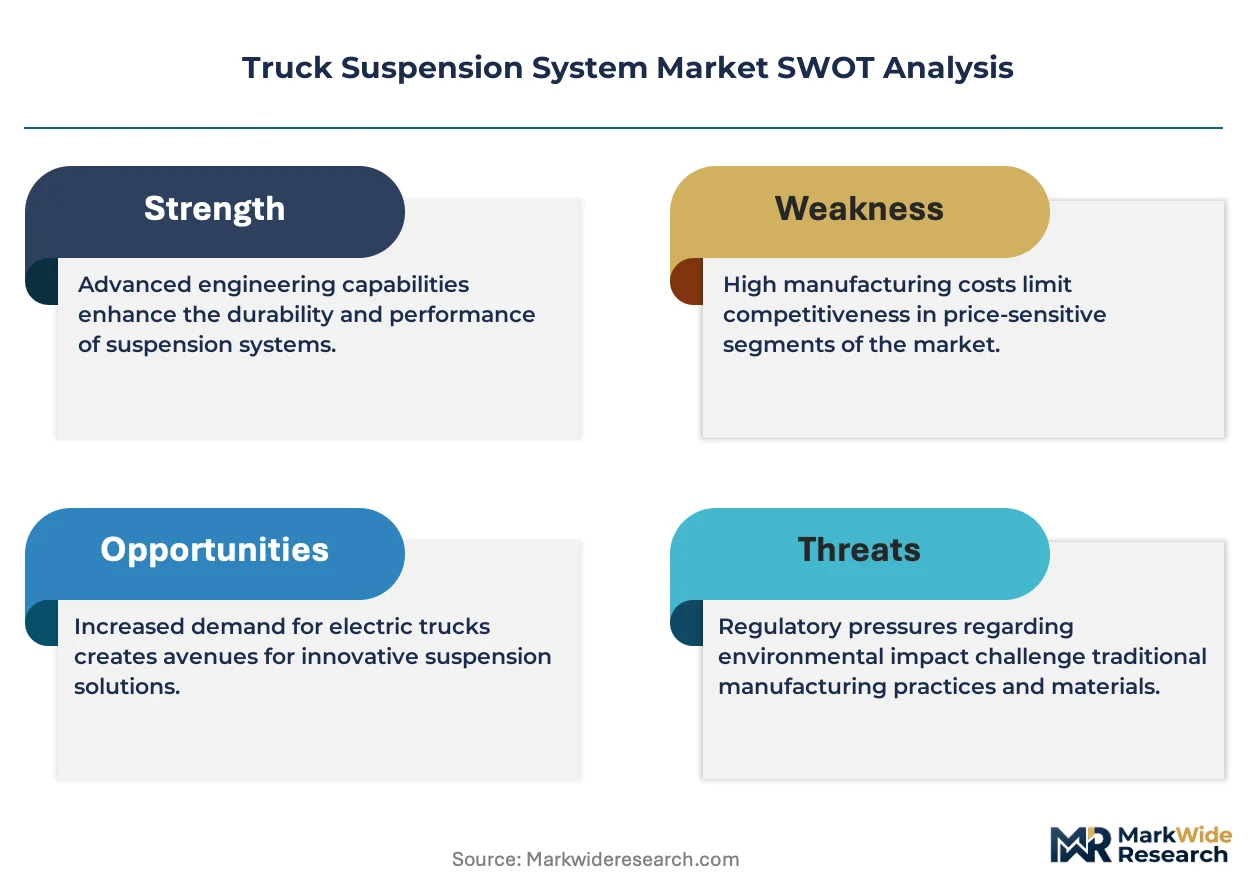
Fleet electrification timelines are compressing suspension development cycles, forcing suppliers to engineer lightweight air-ride architectures that preserve battery range while maintaining load-bearing capacity for heavy-duty configurations.
Growth Catalysts
- EPA Phase 3 Standards:Federal greenhouse gas regulations mandate axle-weight reductions that accelerate air suspension adoption in long-haul Class 8 tractors.
- California Advanced Clean Trucks:State-level zero-emission fleet mandates create compliance-driven replacement demand for qualifying suspension configurations.
- Refrigerated Trailer Cargo Protection:Temperature-sensitive freight operators prioritize air-ride systems to reduce vibration damage and insurance claims.
Market Restraints
- Steel and Aluminum Volatility:Leaf spring and air suspension manufacturers face margin compression from fluctuating commodity input costs.
- Supplier Concentration in Midwest Manufacturing:Domestic production clusters create geographic vulnerability to regional labor disruptions.
- Technical Limitation in Extreme Cold:Air bellows experience performance degradation below -20°F, limiting deployment in northern freight corridors.
Strategic Opportunities
- Texas and Florida Fleet Hubs:Sun Belt freight growth creates underpenetrated demand for corrosion-resistant coastal suspension specifications.
- Integrated Telematics Convergence:Combining air pressure sensors with fleet management platforms enables predictive maintenance revenue streams.
- IRA Commercial Vehicle Incentives:Federal tax credits for clean-fleet investments subsidize premium suspension upgrades during procurement cycles.
Industry Challenges
- Mechatronics Talent Scarcity:Shortage of engineers proficient in both mechanical suspension design and electronic control systems delays product launches.
- FMVSS 121 Recertification Burden:Modified air brake-suspension configurations require extensive NHTSA testing that extends time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Suspension System Market |
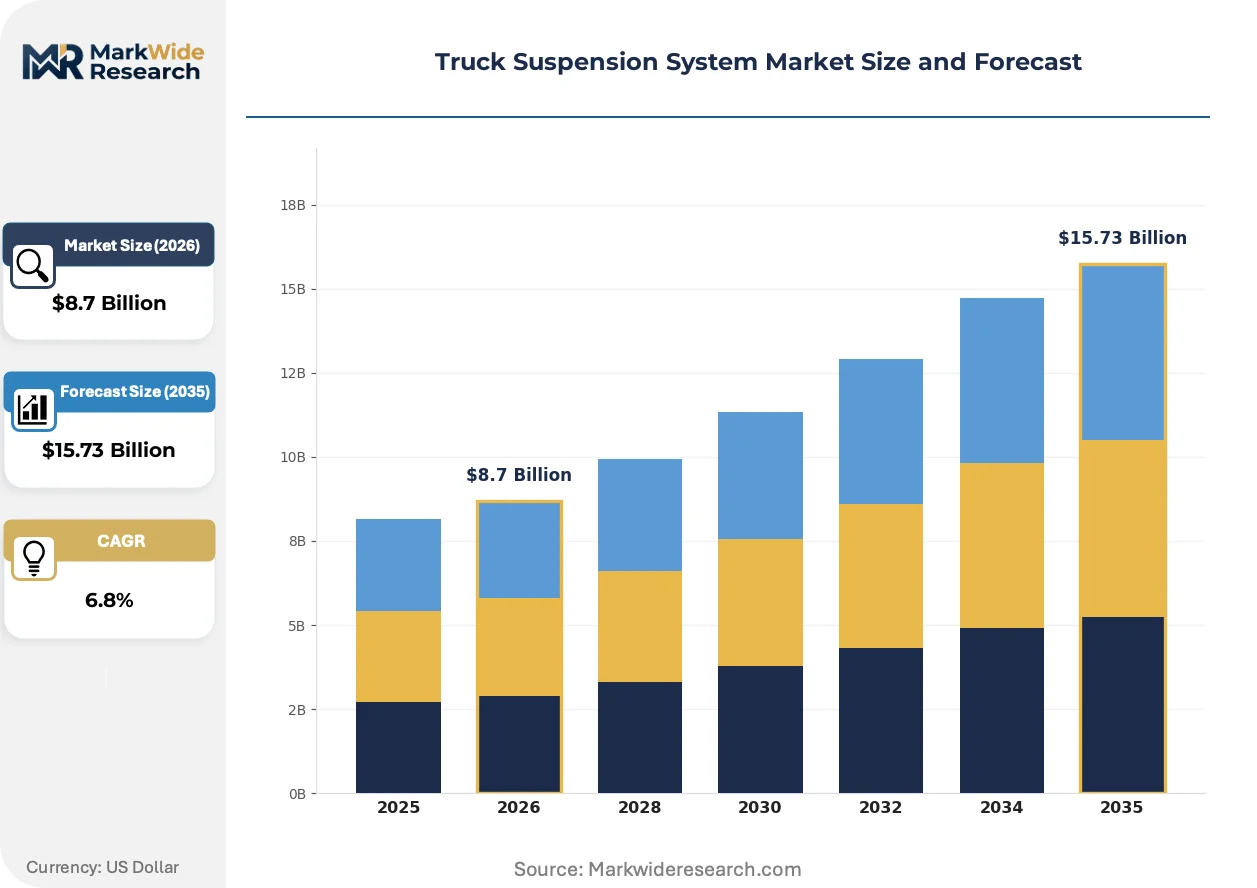
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
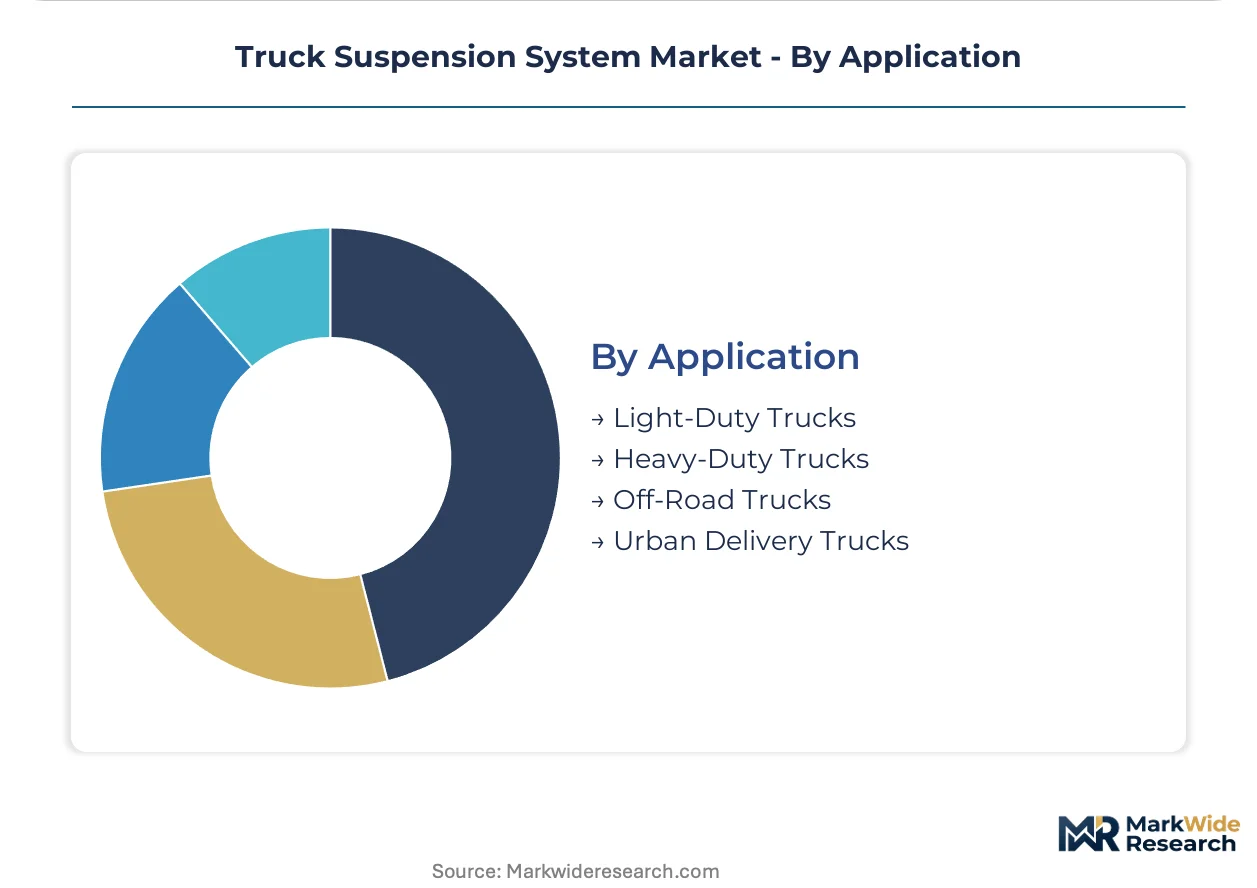
| Segmentation | Type: Leaf Spring, Air Suspension, Coil Spring, Torsion Bar Component: Shocks, Struts, Stabilizers, Control Arms End User: OEMs, Aftermarket Providers, Fleet Operators, Independent Repair Shops Application: Light-Duty Trucks, Heavy-Duty Trucks, Off-Road Trucks, Urban Delivery Trucks |
| Companies Covered | Meritor Inc., Hendrickson USA, L.L.C., ZF Friedrichshafen AG, Continental AG, SAF-HOLLAND GmbH, Dana Incorporated, JOST Werke AG, Ridewell Corporation, Bendix Commercial Vehicle Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Suspension System Market Emerging Trajectories
Sensor integration and real-time adjustability are transforming suspension from passive mechanical assemblies into active vehicle control systems that optimize for fuel efficiency, driver comfort, and cargo protection simultaneously.
Electronically controlled air suspension is digitizing load management by automatically adjusting ride height based on real-time weight distribution and road conditions. Regional lessors operating mixed freight fleets are retrofitting legacy tractors with these systems at accelerated rates. The technology is digitizing procurement specifications, compressing the traditional RFP cycle as fleet managers prioritize integrated smart-suspension packages over component-level sourcing.
EPA Phase 3 greenhouse gas standards are tightening concurrently with NHTSA fuel efficiency mandates, creating a regulatory stack that effectively requires weight reduction technologies. Heavy-duty tractor manufacturers must demonstrate compliance across combined emissions and safety frameworks. Long-haul fleet operators in the United States are responding by locking multi-year air suspension supply agreements before specification windows close.
Leasing companies are unbundling suspension maintenance from vehicle contracts, creating standalone service revenue streams that alter traditional ownership economics. Fleet operators now favor pay-per-mile arrangements that transfer capital risk to component suppliers and lessors. This restructuring is most visible in California and Texas, where asset-light logistics providers dominate refrigerated and dry-van freight segments.
Truck Suspension System Market Segmentation
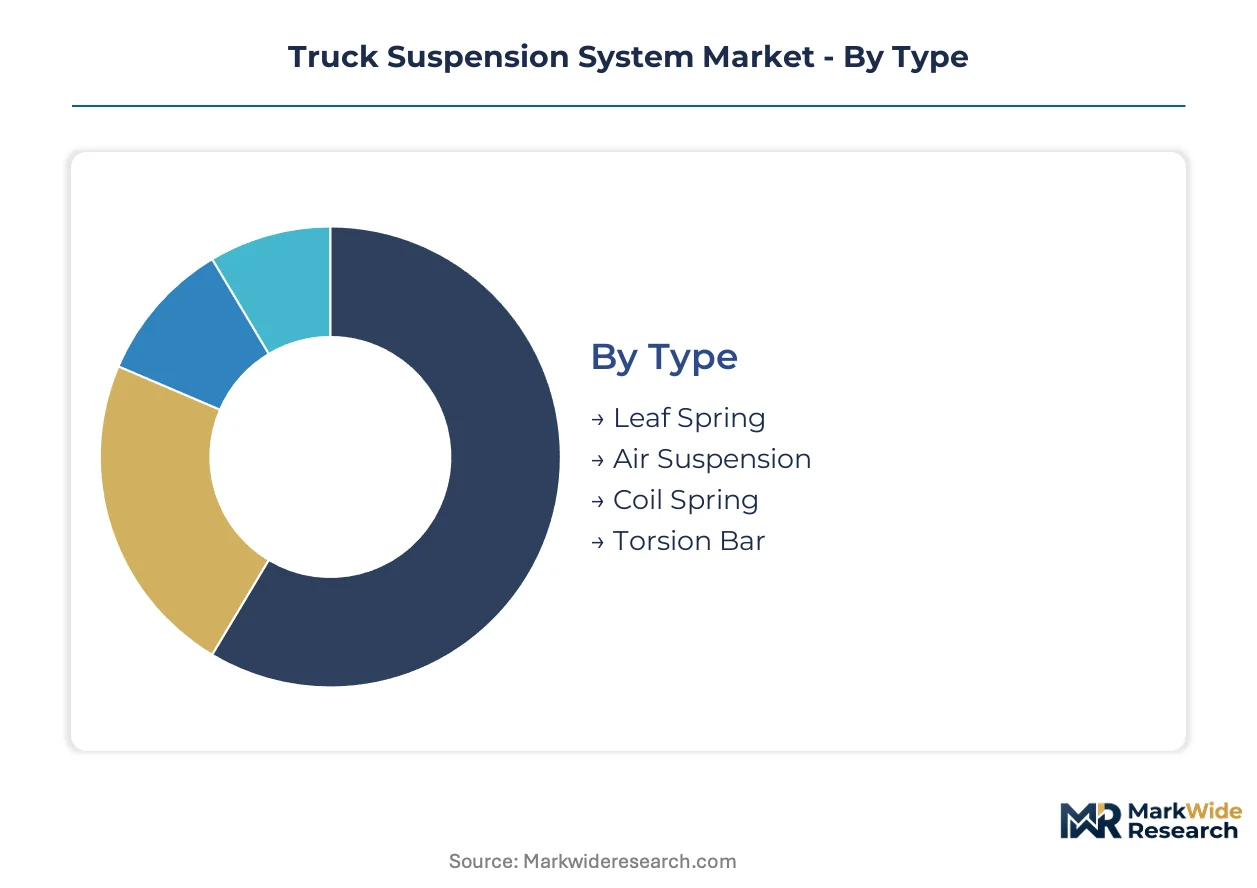
Truck suspension procurement patterns diverge sharply across duty cycles, maintenance models, and regulatory exposure. Fleet operators segment their specifications by payload demands, compliance timelines, and total cost of ownership horizons.
Type:
Use-case spectrum spans vocational durability requirements to long-haul cargo protection priorities.
- Air Suspension:Compressible air bellows paired with electronic height control modulate ride characteristics across variable loads. Demand concentrates in Class 8 tractors serving California's Advanced Clean Trucks corridors where weight compliance and driver retention drive premium specification. EPA Phase 3 axle-weight thresholds accelerate displacement of legacy alternatives in refrigerated and dry-van segments.
- Leaf Spring:Multi-layer steel strips deliver load-bearing capacity through mechanical deflection without auxiliary power. Vocational operators in Texas construction and Midwest agriculture sustain aftermarket volume due to repair simplicity and field-serviceability. Cost sensitivity in medium-duty distribution fleets preserves specification share where uptime requirements permit scheduled maintenance windows.
- Coil Spring:Helical steel wire configurations provide independent wheel movement in lighter GVWR applications.
- Torsion Bar:Longitudinal spring bars twist under load to deliver compact packaging in cab and chassis integrations.
Established volume favors Leaf Spring; emerging adoption favors Air Suspension.
Component:
Component sourcing patterns reflect maintenance interval differentiation and warranty exposure.
- Shocks:Hydraulic or gas-charged dampers dissipate kinetic energy from road inputs to preserve tire contact and chassis stability. Fleet operators in Florida's corrosion-exposed coastal corridors accelerate replacement cycles due to salt degradation, creating recurring aftermarket demand independent of vehicle age.
- Struts:Structural spring-damper assemblies integrate load-bearing and damping functions in cab suspension and steer axle configurations. OEM assembly plants in Michigan and Ohio specify modular strut modules to compress installation time and reduce line-side complexity.
- Stabilizers:Torsion bars or linkages reduce body roll during cornering and lane-change maneuvers.
- Control Arms:Linkage components maintain wheel geometry and suspension travel limits across axle articulation ranges.
Aftermarket replacement intensity runs highest for Shocks; OEM specification value concentrates in Struts.
End User:
Procurement authority fragmentation creates parallel channel strategies with divergent margin structures.
- Fleet Operators:Asset owners with direct specification authority negotiate multi-year supply agreements tied to vehicle replacement cycles. Long-haul operators in the United States leverage scale to mandate integrated air-ride packages with predictive maintenance telemetry, transferring component risk to suppliers through pay-per-mile arrangements.
- OEMs:Vehicle manufacturers integrate suspension modules at assembly plants with design-for-manufacturing constraints. Domestic production clusters in the Midwest favor suppliers with just-in-time logistics capabilities and FMVSS 121 pre-certification documentation.
- Aftermarket Providers:Distributors and jobbers serve independent repair channels with replacement inventory.
- Independent Repair Shops:Service facilities perform component-level replacement without vehicle manufacturer affiliation.
Contract value aggregates with Fleet Operators; volume throughput concentrates with Aftermarket Providers.
Application:
Duty-cycle severity and regulatory exposure stratify specification requirements across vehicle classes.
- Heavy-Duty Trucks:Class 8 configurations operating above 33,000 pounds GVWR demand integrated air suspension with electronic damping to satisfy federal weight compliance and driver comfort mandates. Long-haul freight corridors between California and Texas anchor specification value as fleet operators lock procurement ahead of Phase 3 implementation deadlines.
- Urban Delivery Trucks:Medium-duty configurations with frequent stop-start cycles prioritize low-speed ride quality and cab suspension isolation. Last-mile operators in dense metropolitan areas specify air-ride seats and secondary cab suspensions to reduce driver fatigue and workers compensation exposure.
- Light-Duty Trucks:Pickup and van configurations below Class 6 GVWR emphasize cost-optimized coil and leaf configurations.
- Off-Road Trucks:Mining and construction applications demand reinforced architectures with extended travel ranges and sealed components.
Margin concentration pools in Heavy-Duty Trucks; unit volume expansion tracks fastest in Urban Delivery Trucks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in heavy-duty suspension exports to Canada and Mexico under USMCA provisions, while importing specialized air-ride components from German and Japanese suppliers. Trade flows concentrate around Detroit-Windsor cross-border assembly corridors and Laredo-Nuevo Laredo freight corridors.
United States
Long-haul fleet operators in California and Texas are accelerating procurement of air suspension systems ahead of EPA Phase 3 implementation deadlines. The NHTSA enforces FMVSS 121 certification requirements that govern air brake-suspension integration for emergency stopping performance. Manufacturing clusters in Michigan and Ohio anchor just-in-time supply contracts with domestic OEM assembly plants.
Germany
Precision engineering capabilities in Baden-Württemberg and Bavaria sustain premium-tier exports of integrated axle-suspension modules to North American and Asian markets. The KBA enforces type-approval standards for commercial vehicle safety systems that exceed baseline EU requirements. Suppliers in Stuttgart and Munich metropolitan areas specialize in mechatronic control systems for electronically adjustable air suspension.
China
Domestic heavy-duty truck production in Shandong and Hubei provinces is absorbing locally manufactured leaf spring and air bellows capacity at scale. The MIIT implements GB standards for commercial vehicle suspension performance that align with fuel efficiency targets under dual carbon goals. Yangtze River Delta manufacturing bases are expanding output of lightweight aluminum suspension components for export markets.
Japan
Keiretsu-affiliated suppliers in Aichi and Kanagawa prefectures maintain captive supply relationships with domestic OEMs while exporting damping technologies. METI coordinates industrial standards through JIS certification frameworks that emphasize durability testing protocols. Nagoya-area production clusters focus on compact air suspension architectures for medium-duty urban delivery configurations.
India
Cost-optimized leaf spring production in Tamil Nadu and Maharashtra serves domestic commercial vehicle demand and African export markets. The BIS mandates automotive component testing under AIS standards that progressively incorporate global technical regulations. Pune and Chennai industrial corridors are attracting joint ventures for air suspension localization as fleet operators upgrade specifications.
Truck Suspension System Market Vendor Landscape
On the supply side, the industry is consolidating around integrated system providers capable of delivering pre-certified axle-suspension modules that compress OEM assembly timelines. Tiered competition separates full-line suppliers with FMVSS 121 pre-certification capabilities from component specialists serving aftermarket channels. Two dominant strategic archetypes have emerged: diversified automotive suppliers leveraging electronics integration expertise, and suspension-focused specialists defending positions through lightweight material architectures. Competitive dynamics center on backward integration into aluminum forging and strategic partnerships with fleet telematics platforms.
Within the diversified supplier tier, ZF Friedrichshafen AG and Continental AG exemplify scale-driven competitors with cross-divisional technology transfer capabilities. Among suspension specialists, Hendrickson USA, L.L.C. occupies a position anchored in domestic manufacturing proximity to Midwest OEM clusters. Meritor Inc. represents the lightweight architecture archetype, with company naming conventions indicating North American operational heritage. These three entities collectively illustrate the competitive segmentation between integrated module providers and component specialists.
| Leading Market Players |
|---|
| Meritor Inc. |
| Hendrickson USA, L.L.C. |
| ZF Friedrichshafen AG |
| Continental AG |
| SAF-HOLLAND GmbH |
| Dana Incorporated |
| JOST Werke AG |
| Ridewell Corporation |
| Bendix Commercial Vehicle Systems LLC |
| Others |
Supply Flow & Price Mechanics
Michigan and Ohio manufacturing clusters concentrate air suspension module capacity, granting Tier 1 suppliers leverage over long-haul fleet operators negotiating multi-year procurement contracts. This geographic concentration compresses margin buffers for buyers locked into EPA Phase 3 compliance timelines, while steel and aluminum input volatility transmits directly into component pricing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span vehicle platform lifecycles. Three-tier pricing structure across premium, standard, and economy levels separates FMVSS 121 pre-certified integrated modules from component-level sourcing. Cost compression in standard-tier leaf spring configurations is intensifying because Midwest foundries face electricity cost escalation. Vocational fleet operators in Texas construction segments exhibit highest price sensitivity, while California refrigerated carriers accept premium positioning for cargo protection compliance.
Supply Chain Analysis
Steel coil from Indiana mills, aluminum forgings from Ohio foundries, and synthetic rubber bellows from German chemical suppliers feed into domestic assembly plants. Supplier concentration in the Great Lakes region creates geographic vulnerability to regional labor disruptions and winter logistics interruptions. Distribution runs through captive OEM supply agreements and independent aftermarket distributors serving independent repair shops. Tariff exposure on Chinese aluminum components remains a structural risk for lightweight architecture producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance telemetry subscriptions are expanding faster than hardware sales as fleet operators unbundle suspension service from vehicle contracts. This service-attach dynamic restructures supplier economics toward recurring revenue models.
For Market Incumbents: Harden backward integration into aluminum forging capacity to insulate margin structures from commodity volatility. Secure FMVSS 121 pre-certification documentation for integrated axle-suspension modules before NHTSA specification windows tighten. Lock multi-year just-in-time contracts with Midwest OEM assembly plants to defend against emerging mechatronics specialists.
For New Entrants and Emerging Players: Pursue telematics-enabled aftermarket retrofit opportunities in Texas and Florida fleet hubs where corrosion-resistant coastal specifications remain underpenetrated. Target independent lessors operating mixed freight fleets with pay-per-mile financing arrangements that transfer capital risk from buyers. Lead with sensor integration capabilities rather than mechanical component manufacturing.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA Phase 3 and California Advanced Clean Trucks mandates lock in replacement demand regardless of freight volume cyclicality. Acquire specialists with lightweight air-ride architectures and pre-existing NHTSA certification dossiers. Monitor federal axle-weight harmonization proposals as the inflection signal for specification shift timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Forging | Captive supply of lightweight suspension components insulates margins from Midwest electricity cost volatility. |
| FMVSS 121 Pre-Certification Investment | Pre-certified axle-suspension modules compress OEM assembly timelines and accelerate procurement decisions. |
| Predictive Maintenance Platform Development | Air pressure sensor integration with fleet telematics enables recurring service revenue beyond hardware sales. |
| Corrosion-Resistant Coastal Specification Launch | Salt-degradation-resistant architectures address Florida and Texas fleet hub replacement cycles. |
| Pay-per-Mile Financing Arrangement | Asset-light structures transfer capital risk to suppliers while penetrating mid-tier fleet operator segments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, OEM platform engineers, aftermarket distribution managers, and suspension component R&D leads. Secondary validation drew from NHTSA FMVSS 121 certification databases, EPA Phase 3 regulatory filings, vehicle production registries, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Calibration against historical replacement cycles and regulatory implementation timelines anchored the projection framework. Segmentation dimensions modeled include suspension type, vehicle class, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from slope analysis of technology displacement curves and compliance-driven procurement acceleration. Forecast inputs incorporated steel and aluminum price elasticity coefficients alongside fleet electrification weight-reduction requirements.
Macroeconomic conditions sit as an overlay; deviation in freight volume indices, interest rate environments, or commodity price trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and technology adoption curves. Cross-checking against IHS Markit commercial vehicle registration data and ACT Research freight forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
China Forklift Battery Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market