
 Energy Efficient Elevators Market | 2026-2036
Energy Efficient Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Elevators Market Foresight
The EU Green Deal is restructuring demand specifications across European commercial construction, requiring regenerative drive systems and standby power reduction in all new vertical transport installations. Otis Elevator Company leverages its Gen3 platform with built-in energy recovery to secure specification-led projects. KONE Corporation anchors its market presence through machine-room-less elevator dominance in high-rise residential towers across Asia-Pacific. Schindler Group competes on smart elevator integration with building management systems, differentiating through predictive maintenance algorithms.
Energy efficient elevators employ regenerative drive technology, permanent magnet synchronous motors, and LED cabin lighting to reduce power consumption by returning braking energy to the building grid rather than dissipating it as heat. These systems typically operate at efficiency levels exceeding standard traction units and serve commercial, residential, and healthcare facilities seeking lower lifecycle operating costs. Machine-room-less elevators occupy the fastest-growing product category due to reduced shaft footprint and elimination of dedicated machine room construction costs. Smart elevator technology concentrates margin pools through software-enabled traffic optimization and predictive maintenance contracts. New installation work sustains volume leadership, though modernization and retrofitting segments accelerate as building codes tighten across mature building stock.
REACH and RoHS frameworks in Europe restrict hazardous substances in electrical components, while the EU F-Gas Regulation phases down fluorinated greenhouse gases used in some hydraulic systems, directly shaping product design requirements. EMA and national health regulators influence hospital elevator specifications through infection control and reliability standards. China's MIIT enforces GB standards for elevator energy consumption, and India's BIS certification mandates efficiency testing for imported units. Stakeholders must monitor evolving multi-jurisdiction efficiency benchmarks and decide whether to develop region-specific product variants or pursue unified global platforms.
Market Dynamics
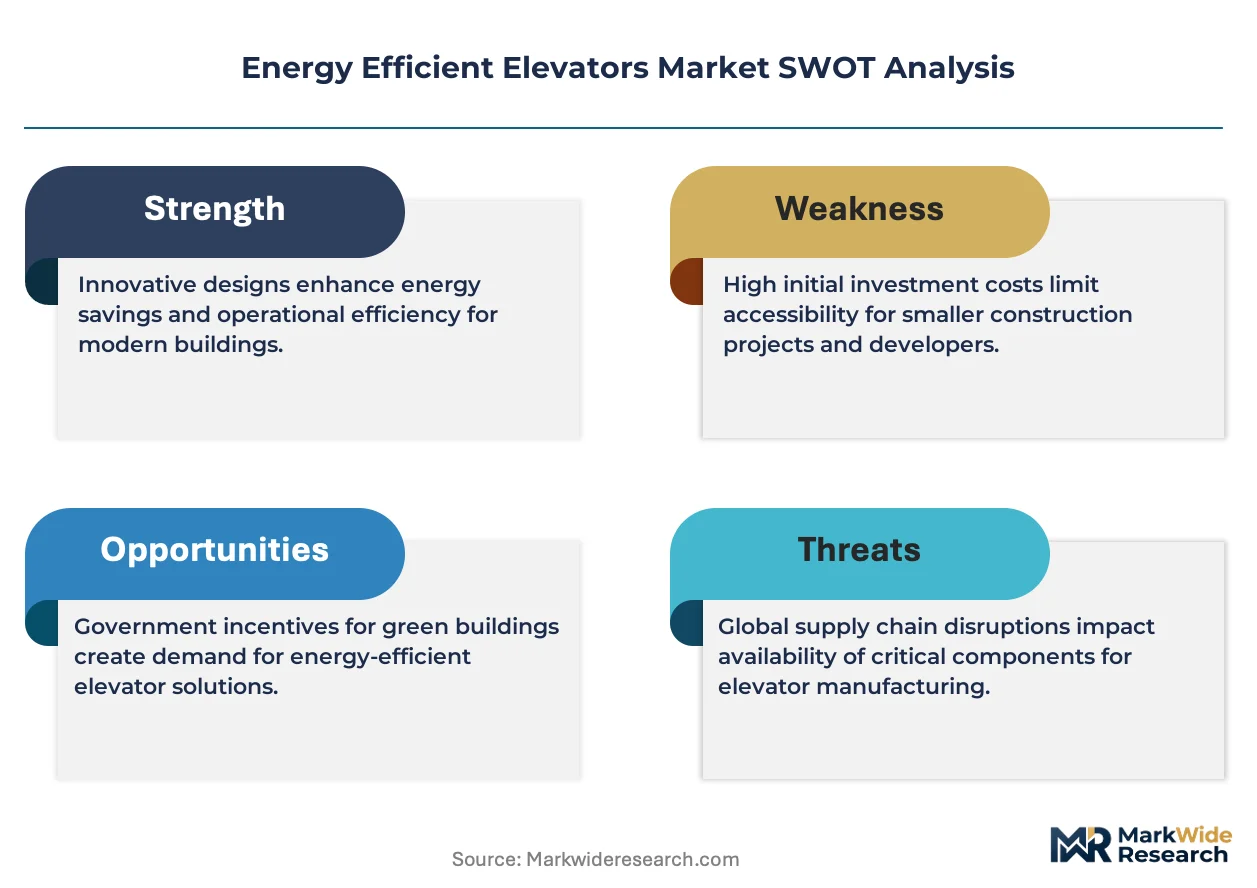
Regenerative drive technology is compressing lifecycle cost calculations and forcing specification changes across commercial real estate procurement, with green building certification now filtering elevator selection before price negotiation begins.
Growth Catalysts
- EU Green Deal mandates:The EU F-Gas Regulation phases down fluorinated greenhouse gases in hydraulic systems, forcing building developers toward permanent magnet synchronous motor alternatives.
- Machine-room-less construction economics:Elimination of dedicated machine room space reduces shaft footprint by approximately thirty percent in high-rise residential towers.
- China MIIT efficiency enforcement:GB standards for elevator energy consumption mandate testing protocols that advantage regenerative drive suppliers in new installation tenders.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet synchronous motors depend on neodymium processing concentrated in China, creating input cost volatility and geopolitical exposure.
- Legacy building structural constraints:Existing shaft dimensions and load-bearing specifications in buildings constructed before 2000 cannot accommodate machine-room-less retrofits without expensive civil works.
- REACH compliance friction:ECHA restrictions on hazardous substances in electrical components extend certification timelines and limit component sourcing flexibility for European projects.
Strategic Opportunities
- India BIS certification window:Mandatory efficiency testing for imported units creates first-mover advantage for suppliers establishing local assembly or testing partnerships.
- Predictive maintenance convergence:Integration of IoT sensors with building management systems enables subscription revenue models that decouple service income from equipment sales.
- Healthcare vertical specialization:Infection control and reliability standards from EMA and national health regulators create premium specification tiers for hospital elevator installations.
Industry Challenges
- Electromechanical systems integration:Smart elevator platforms must interface with legacy building automation protocols, requiring custom middleware development and extended commissioning periods.
- Certification timeline compression:Multi-jurisdiction efficiency benchmarks force simultaneous compliance with REACH, RoHS, GB standards, and BIS requirements, straining regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Elevators Market |
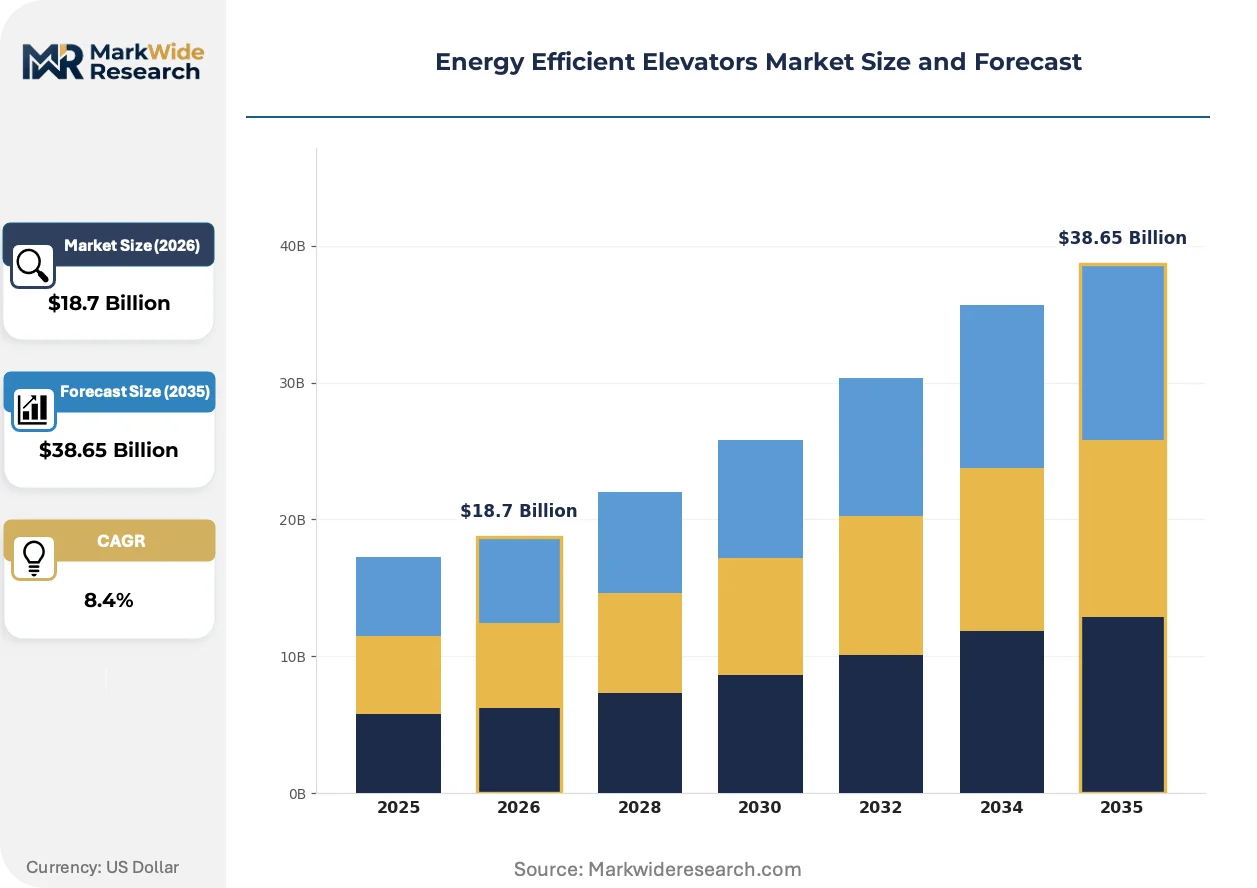
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traction Elevators, Hydraulic Elevators, Machine-Room-Less Elevators, Vacuum Elevators Installation: New Installation, Modernization, Retrofitting, Upgrading End User: Commercial Buildings, Residential Homes, Hospitals, Industrial Facilities Technology: Regenerative Drives, Smart Elevators, Green Technologies, Energy Recovery Systems |
| Companies Covered | Otis Elevator Company, KONE Corporation, Schindler Group, Mitsubishi Electric Corporation, Hitachi Ltd, Thyssenkrupp Elevator AG, Fujitec Co. Ltd, Hyundai Elevator Co. Ltd, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Elevators Market Shifts & Advancements
Software-defined functionality is displacing hardware differentiation in vertical transport, with energy recovery systems and traffic optimization algorithms now carrying more specification weight than mechanical performance metrics.
Regenerative drive technology captures braking energy and returns it to the building grid rather than dissipating it as heat. Commercial developers in Germany and France are specifying these systems in LEED-targeted projects to meet standby power reduction requirements. This capability is electrifying competitive bidding, compressing margins for suppliers offering standard traction units without energy recovery.
The EU F-Gas Regulation mandates phased reduction of fluorinated greenhouse gases in hydraulic elevator systems. Equipment manufacturers are redesigning product lines around permanent magnet synchronous motors and gearless traction alternatives. European commercial new-build segments are absorbing these design changes fastest, with specification consultants filtering non-compliant products from shortlists before price evaluation.
Building developers are unbundling after-sales service contracts from initial equipment procurement, selecting maintenance providers through separate competitive tender. This fragmentation is compressing OEM service margins and creating openings for independent service companies with predictive maintenance platforms. The pattern is most visible in Singapore and Dubai, where facility management outsourcing has matured fastest.
Energy Efficient Elevators Market Segmentation
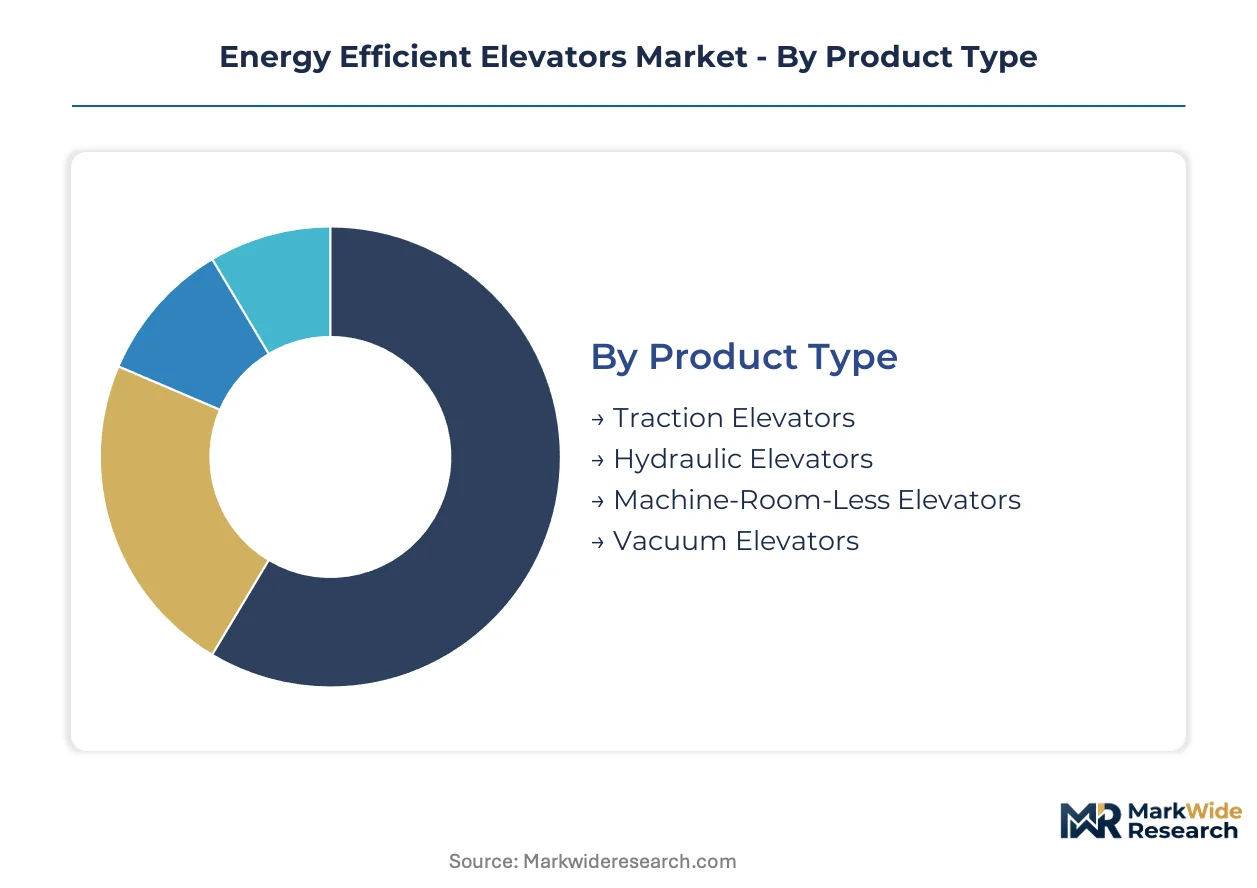
Segmentation in energy efficient elevators reveals how capital deployment, regulatory compliance, and lifecycle economics intersect across distinct procurement contexts. Each dimension—product architecture, installation mode, end-use environment, and technology platform—carries unique margin structures and specification requirements.
Product Type:
Capital intensity varies sharply across elevator architectures, with traction systems demanding the heaviest upfront mechanical investment while vacuum units minimize structural load requirements.
- Traction Elevators:Gearless traction systems with permanent magnet synchronous motors dominate high-rise commercial specifications. German and French developers specify these for LEED-targeted projects requiring regenerative energy recovery.
- Machine-Room-Less Elevators:Elimination of dedicated machine room space reduces shaft footprint by approximately thirty percent. High-rise residential towers across Singapore and Dubai absorb these systems fastest due to construction cost economics.
- Hydraulic Elevators:Fluid-powered systems face phase-down pressure from EU F-Gas Regulation restrictions on fluorinated greenhouse gases.
- Vacuum Elevators:Pneumatic tube systems serve low-rise residential retrofits where structural modifications are constrained.
Traction elevators absorb the bulk of installed capacity; machine-room-less elevators are expanding most quickly.
Installation:
Installation mode determines revenue recognition timing and customer relationship duration, with new construction offering single-point margins and modernization creating recurring service attachment.
- New Installation:Greenfield projects in China and India concentrate volume, with GB standards and BIS certification filtering supplier participation before tender evaluation.
- Modernization:Legacy building upgrades in Germany and Japan drive specification of regenerative drive retrofits to meet tightening efficiency codes.
- Retrofitting:Shaft modifications for machine-room-less conversion face structural constraints in buildings constructed before 2000.
- Upgrading:Component-level replacements target control systems and door operators in mature building stock.
New installation commands the largest revenue pool; modernization is climbing the fastest as building codes tighten across mature markets.
End User:
End-use environment shapes specification priorities, with healthcare and commercial segments demanding reliability certification while residential procurement emphasizes first-cost minimization.
- Commercial Buildings:Office and retail developers in Germany specify regenerative drives and standby power reduction to satisfy EU Green Deal procurement criteria.
- Hospitals:Infection control and reliability standards from EMA and national health regulators create premium specification tiers for vertical transport in healthcare facilities.
- Residential Homes:High-rise towers across Asia-Pacific prioritize machine-room-less systems to maximize sellable floor area.
- Industrial Facilities:Freight and heavy-duty applications favor traction systems with enhanced load-bearing capacity.
Commercial buildings account for the dominant share of specification-led procurement; hospitals are gaining share fastest through premium-tier requirements.
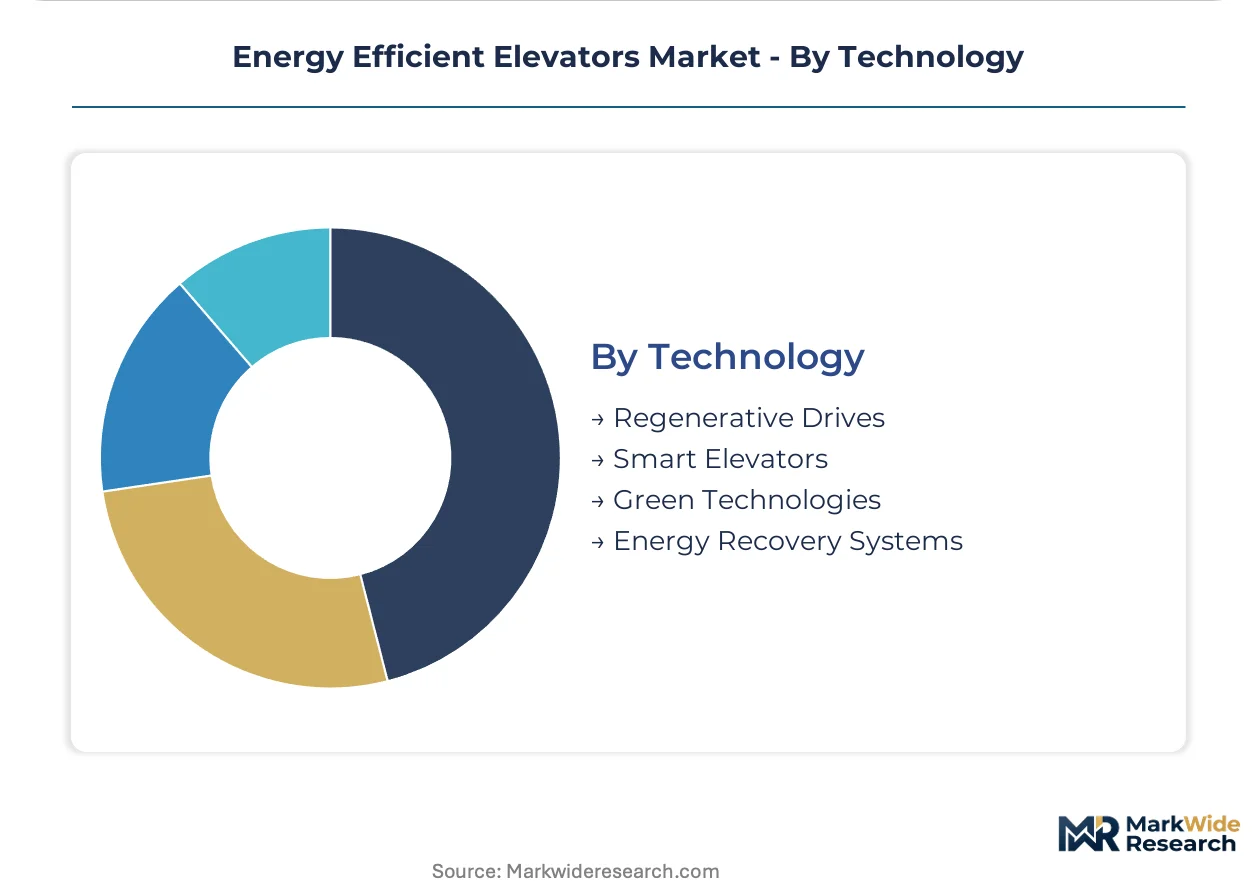
Technology:
Technology platform selection increasingly determines competitive positioning, with software-enabled functionality displacing mechanical performance as the primary specification filter.
- Regenerative Drives:Energy recovery systems capture braking power and return it to building grids rather than dissipating as heat. These systems electrify competitive bidding in France and Germany.
- Smart Elevators:IoT-enabled traffic optimization and predictive maintenance algorithms enable subscription revenue models that decouple service income from equipment sales.
- Green Technologies:LED cabin lighting and standby power reduction systems address EU Green Deal standby power mandates.
- Energy Recovery Systems:Building-integrated power return capabilities satisfy green building certification requirements.
Regenerative drives hold the largest installed base; smart elevators are expanding most quickly through predictive maintenance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of permanent magnet synchronous motors and regenerative drive systems concentrates in China and Germany, while installation demand spreads across high-rise construction corridors in Asia-Pacific and green building retrofit markets in Western Europe.
China
MIIT enforces GB standards for elevator energy consumption that filter supplier participation in new installation tenders across Shanghai and Shenzhen high-rise corridors. The Yangtze River Delta absorbs machine-room-less systems fastest as developers maximize sellable floor area in residential towers. Local rare earth processing around Baotou supplies neodymium for permanent magnet motors, though geopolitical exposure persists.
Germany
The EU Green Deal and F-Gas Regulation force specification of regenerative drives and standby power reduction in Frankfurt and Munich commercial developments. KBA building codes tighten efficiency requirements for modernization projects in legacy Berlin office stock. Baden-Württemberg industrial clusters supply precision mechanical components for gearless traction systems.
United States
LEED certification filters elevator selection in New York and Chicago commercial real estate procurement before price negotiation begins. ASHRAE standards and state-level building codes accelerate regenerative drive retrofits in pre-2000 structures across the Northeast corridor. Texas and Florida residential high-rises absorb machine-room-less construction for footprint reduction.
India
BIS certification mandates efficiency testing for imported units, creating first-mover advantage for suppliers establishing local assembly in Maharashtra and Gujarat. Mumbai and Delhi-NCR high-rise residential towers prioritize construction cost economics from eliminated machine rooms. The CEA pushes grid-interactive building standards that favor energy recovery capabilities.
Japan
METI efficiency guidelines and JIS standards shape procurement for Tokyo and Osaka skyscraper modernization programs. Aging building stock in Kansai drives specification of regenerative retrofits to meet tightening municipal codes. Nagoya industrial corridors manufacture compact control systems for space-constrained shaft conversions.
Energy Efficient Elevators Market Competitive Landscape
The competitive structure tilts toward integrated elevator OEMs with captive service networks rather than pure equipment vendors. Three tiers separate specification-led premium suppliers from cost-optimized volume players and regional specialists. Dominant competitive moves include predictive maintenance platform development and machine-room-less product line expansion across high-rise residential markets.
Among integrated global suppliers, Otis Elevator Company, KONE Corporation, and Schindler Group occupy positions defined by technology platform specialization. Otis exemplifies the regenerative drive specification tier through energy recovery system integration. KONE anchors the machine-room-less architecture segment with shaft footprint reduction capabilities. Schindler represents the smart elevator convergence archetype through building management system integration and predictive maintenance algorithm deployment.
| Leading Market Players |
|---|
| Otis Elevator Company |
| KONE Corporation |
| Schindler Group |
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Thyssenkrupp Elevator AG |
| Fujitec Co. Ltd |
| Hyundai Elevator Co. Ltd |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Certification-tier divergence between LEED-targeted regenerative drive specifications and commodity traction units splits both pricing power and sourcing geography across the energy efficient elevators landscape. Premium specification work commands project-based pricing with extended commissioning timelines, while volume residential procurement compresses margins through standardized machine-room-less platforms sourced from concentrated manufacturing clusters.
Pricing Analysis
Margin tightening in standard traction tiers reflects unbundling of after-sales service contracts from initial equipment procurement in Singapore and Dubai facility management markets. Project-based pricing dominates greenfield commercial developments, with price differentiation driven by GB certification grade for China-bound units and LEED tier for Western European specifications. Buyer price sensitivity concentrates in high-rise residential towers across Asia-Pacific, while hospital procurement committees prioritize reliability certification over first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing around Baotou for neodymium-dependent permanent magnet synchronous motors. Manufacturing draws from Germany for precision mechanical components, China for motor assemblies and control systems, and Japan for compact electronics. Tariff exposure on electrical components strains European project economics. Distribution runs through captive OEM service networks rather than independent channel partners, locking aftermarket revenue within integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy efficient elevators market is consolidating around specification-led players with predictive maintenance platforms, as software-enabled service revenue decouples viable competitors from pure equipment vendors facing compressed margins.
For Market Incumbents: Anticipate fragmentation pressure from independent service companies with IoT-enabled predictive maintenance platforms by deepening backward integration into permanent magnet motor production and securing exclusive channel control through multi-year building management system integration contracts. Prioritize certification investment for EU F-Gas Regulation compliance to filter non-compliant competitors from German and French commercial shortlists. For New Entrants and Emerging Players: Enter via India BIS certification partnerships in Maharashtra and Gujarat assembly operations, targeting the efficiency-testing window for imported units before established suppliers localize production. White-space opportunity concentrates in machine-room-less retrofits for pre-2000 building stock in Japan and Germany, where structural constraints exclude incumbent OEMs optimized for new installation workflows. For Investors and Strategic Acquirers: Re-rating potential sits with predictive maintenance platform specialists given convergence of IoT sensor deployment and subscription revenue models across commercial real estate portfolios. Long-term viability favors targets with captive neodymium supply arrangements or alternative motor architectures reducing rare earth dependency. Watch for GB standards enforcement acceleration in China as inflection indicator for regenerative drive supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | IoT sensor integration with building management systems enables recurring subscription revenue decoupled from equipment sales cycles. |
| Machine-Room-Less Product Line Expansion | Shaft footprint reduction captures high-rise residential specification work across Asia-Pacific construction corridors. |
| Regenerative Drive Certification Investment | EU Green Deal compliance filters non-compliant suppliers from German and French LEED-targeted project shortlists. |
| Local Assembly Partnership in India | BIS certification mandates for imported units create first-mover positioning in Maharashtra and Gujarat high-rise markets. |
| Alternative Motor Architecture R&D | Reduced rare earth dependency mitigates neodymium supply concentration risk from Chinese processing clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across elevator OEM procurement directors, facility management executives, commercial real estate developers, and building code consultants. Secondary validation drew from MIIT GB standard documentation, ECHA REACH restriction updates, BIS certification registries, and LEED project databases. Bottom-up unit deployment estimates triangulated against top-down construction spending allocation across commercial, residential, and healthcare verticals.
Data-stream reconciliation across product architecture, installation mode, end-use environment, and technology platform dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate convergence around efficiency mandate enforcement timelines and replacement cycle acceleration in mature building stock. Industry-specific inputs included rare earth price volatility assumptions and green building certification adoption curves across German, French, and Chinese urban construction clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt rare earth export restriction scenarios or accelerated EU F-Gas Regulation phase-down schedules. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and construction cycle duration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Signage Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Residential Electric Underfloor Heating Market