
 Lab Trays Market | 2026-2036
Lab Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Trays Market Foresight
Chinese polymer processors are expanding virgin polypropylene capacity for lab consumables, and this supply-side investment is shifting procurement patterns for Western tray converters. Thermo Fisher Scientific leverages its captive resin sourcing to sustain margin stability across disposable tray lines. Corning Inc. anchors North American supply through specialized borosilicate-adjacent plastic formulations for assay preparation workflows. Greiner Bio-One International GmbH dominates European distribution channels for clinical laboratory trays, competing on lot-to-lot consistency rather than price alone.
Lab trays are rigid or semi-rigid receptacles manufactured from polypropylene, polyethylene, aluminum, or stainless steel, designed to hold, transport, or temporarily store laboratory samples, reagents, or instruments with dimensional tolerances typically within 0.5 millimeters to ensure robotic handler compatibility. Their primary purpose spans sample collection, storage solutions, transportation, and assay preparation across research, clinical, and pharmaceutical environments. Plastic trays, particularly polypropylene variants, lead volume due to cost scalability and chemical resistance, while stainless steel trays command premium positioning in pharmaceutical companies where autoclave sterilization cycles exceed 500 uses. Disposable trays represent the fastest-expanding segment as clinical laboratories prioritize elimination of cross-contamination protocols and reduce washing infrastructure overhead.
FDA container closure guidance and ISO 15378 pharmaceutical packaging standards jointly determine material certification burdens for tray suppliers targeting US drug manufacturers. The EPA's emerging per- and polyfluoroalkyl substances reporting rules are pressuring converters to validate fluorine-free additive packages in polypropylene grades. ECHA REACH compliance for monomer residuals now extends to imported trays entering European Union clinical laboratories. Stakeholders must monitor regulatory divergence between US and European material disclosure thresholds, as divergent compliance investments will fragment supplier qualification pools and reshape sourcing geography decisions.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating tray specifications to reduce qualification overhead, compressing supplier margins while rewarding converters with captive resin supply chains and documented ISO 15378 compliance histories.
Growth Catalysts
- High-throughput screening expansion:Drug discovery pipelines at contract research organizations are standardizing 384-well and 1536-well tray formats to accelerate compound library processing.
- REACH monomer residual enforcement:ECHA's tightened import scrutiny is disqualifying non-compliant Asian converters, redirecting European clinical laboratory procurement toward certified EU suppliers.
- Fluorine-free additive validation:EPA reporting rules on per- and polyfluoroalkyl substances are forcing polypropylene grade reformulation, creating first-mover advantage for converters with validated alternative slip agents.
Market Restraints
- Virgin polypropylene supply concentration:Chinese polymer capacity expansion is capturing margin from Western tray converters dependent on spot resin markets.
- Autoclave cycle durability thresholds:Stainless steel trays face substitution pressure from advanced polymer formulations exceeding 200-cycle sterilization tolerance at one-fifth the unit cost.
- FDA container closure documentation burdens:Material traceability requirements for sterile drug contact applications are extending supplier qualification timelines beyond 18 months.
Strategic Opportunities
- Indian clinical laboratory buildout:CDSCO's streamlined medical device registration is opening procurement channels for tray converters with BIS-certified manufacturing partners.
- Cell therapy workflow integration:Cryopreservation-compatible tray formats are capturing demand from CAR-T manufacturing facilities requiring validated cold-chain handling.
- Direct-to-laboratory e-procurement platforms:Specialized distributors are disintermediating traditional medical supply houses for high-volume research tray categories.
Industry Challenges
- Robotic handler dimensional calibration:Tray converters must maintain 0.5-millimeter tolerances across temperature cycling while automated liquid handling platforms proliferate.
- Lot-to-lot consistency documentation:Pharmaceutical buyers are rejecting shipments lacking comprehensive extractables and leachables profiles for each resin batch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Trays Market |
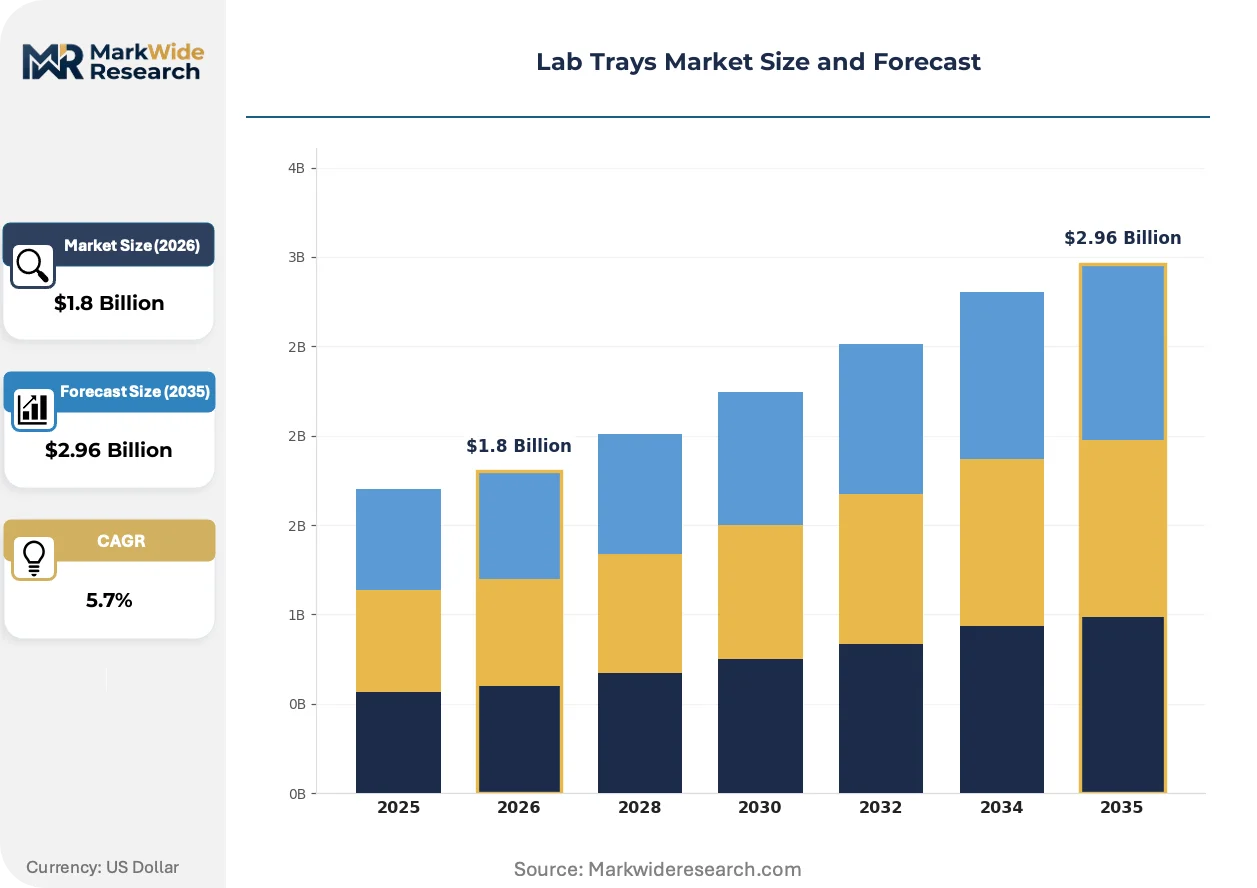
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Trays, Aluminum Trays, Stainless Steel Trays, Disposable Trays End User: Research Laboratories, Clinical Laboratories, Pharmaceutical Companies, Educational Institutions Application: Sample Collection, Storage Solutions, Transportation, Assay Preparation Material: Polypropylene, Polyethylene, Metal, Silicone |
| Companies Covered | Thermo Fisher Scientific Inc., Corning Inc., Eppendorf AG, Merck KGaA, Danaher Corporation, Agilent Technologies Inc., Greiner Bio-One International GmbH, Heathrow Scientific LLC, Simport Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Trays Market Shifts & Advancements
Automation compatibility requirements and material sustainability mandates are simultaneously elevating precision engineering standards and forcing resin formulation overhaul across the tray converter base.
Microplate tray architecture is modularizing around ANSI/SLAS dimensional standards, enabling interchangeability across Tecan, Hamilton, and Beckman Coulter liquid handling platforms. Academic core facilities and mid-sized biotechs are adopting these formats fastest, collapsing the historical fragmentation between instrument-specific consumable ecosystems.
EPA's emerging per- and polyfluoroalkyl substances reporting framework is compelling polypropylene processors to validate fluorine-free additive packages before 2025 enforcement windows. Tray converters with pre-qualified alternative slip agents are securing preferred supplier status with US drug manufacturers facing shareholder pressure on chemical disclosure.
Research procurement managers are consolidating vendor relationships to reduce qualification audit burden, favoring converters offering combined tray, seal, and barcode labeling solutions. This preference shift is most pronounced in Germany's contract research organization cluster, where Thermo Fisher Scientific and Greiner Bio-One are capturing expanded wallet share through integrated workflow offerings.
Lab Trays Market Segmentation
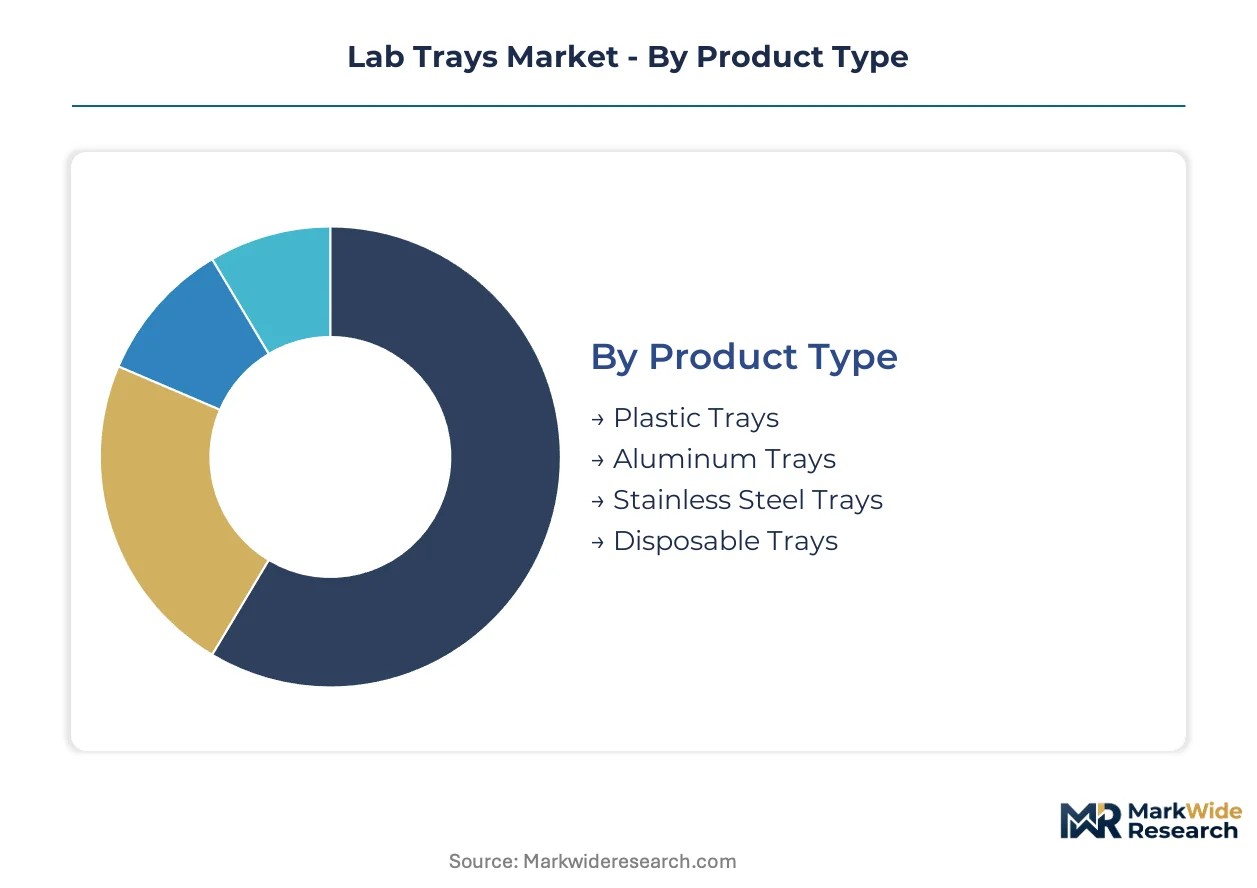
Tray specification divergence across pharmaceutical, clinical, and research environments creates distinct procurement pools with incompatible qualification requirements. Material certification burdens and automation compatibility standards fragment supplier addressable markets, forcing converters to prioritize segment-specific compliance investments over portfolio breadth.
Product Type:
Chinese virgin polypropylene capacity expansion is redrawing margin structures for Western converters, privileging those with captive resin supply or specialized formulation capabilities.
- Plastic Trays:Polypropylene and polyethylene variants dominate procurement volumes due to chemical resistance and cost scalability. Pharmaceutical companies in Germany are consolidating specifications around ISO 15378-certified grades to reduce supplier qualification overhead.
- Disposable Trays:Single-use formats eliminate cross-contamination protocols and washing infrastructure. Clinical laboratories in the United States are prioritizing these for high-throughput workflows under FDA container closure guidance tightening material traceability.
- Stainless Steel Trays:Autoclave-compatible formats exceeding 500 sterilization cycles command premium positioning in pharmaceutical manufacturing.
- Aluminum Trays:Lightweight thermal conductors serve cryopreservation and cold-chain applications in cell therapy facilities.
Plastic trays absorb the bulk of installed capacity; disposable trays are expanding most quickly.
End User:
Consolidation in contract research organizations is compressing supplier margins while rewarding converters with documented compliance histories.
- Pharmaceutical Companies:Sterile drug contact applications demand exhaustive extractables and leachables documentation per FDA guidance. Qualification timelines now stretch beyond 18 months, favoring incumbent suppliers with established regulatory files.
- Clinical Laboratories:High-throughput screening standardization around 384-well and 1536-well formats drives volume procurement. ECHA REACH enforcement on monomer residuals is redirecting European laboratory procurement toward certified EU converters.
- Research Laboratories:Academic core facilities adopt ANSI/SLAS dimensional standards for liquid handling platform interchangeability.
- Educational Institutions:Budget-constrained procurement favors basic polypropylene trays without specialized certification requirements.
Pharmaceutical companies command the steepest certification premiums; clinical laboratories represent the steepest expansion trajectory.
Application:
Robotic handler proliferation is elevating dimensional tolerance requirements across all functional categories, with 0.5-millimeter precision now mandatory for automated compatibility.
- Assay Preparation:Microplate tray architecture around ANSI/SLAS standards enables Tecan, Hamilton, and Beckman Coulter platform interchangeability. Mid-sized biotechs in Germany's CRO cluster are adopting these formats fastest.
- Sample Collection:Primary receptacles for diagnostic specimen handling require biocompatibility validation per ISO 10993.
- Storage Solutions:Cryopreservation-compatible formats capture demand from CAR-T manufacturing facilities requiring validated cold-chain integrity.
- Transportation:Transit-optimized designs with reinforced stacking features serve logistics-intensive pharmaceutical distribution networks.
Assay preparation dominates precision-engineering investments; storage solutions are climbing the fastest on cell therapy demand.
Material:
EPA per- and polyfluoroalkyl substances reporting rules are forcing polypropylene grade reformulation, creating first-mover advantage for converters with validated fluorine-free additive packages.
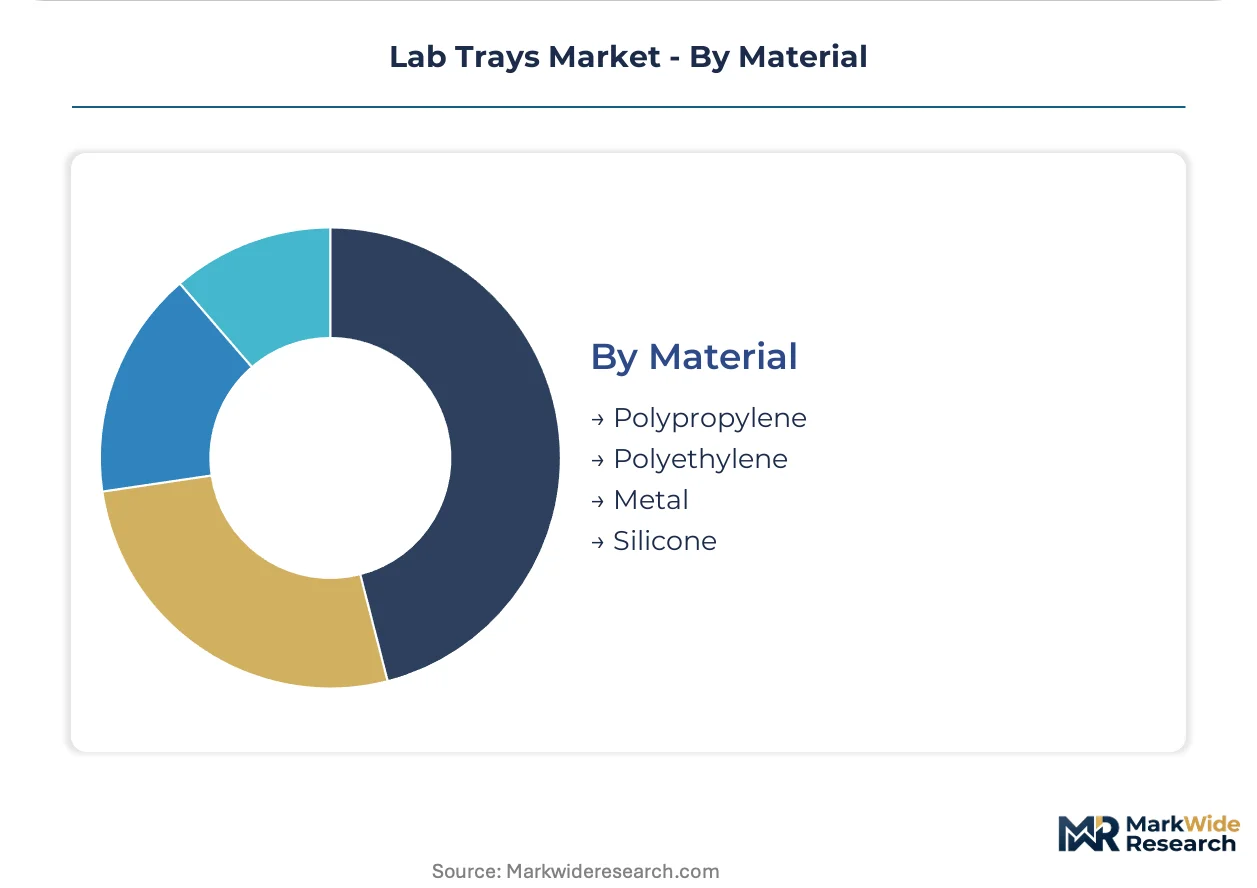
- Polypropylene:Dominant resin for disposable trays due to chemical resistance and thermoformability. Chinese polymer processors are expanding virgin capacity, shifting procurement patterns for Western converters dependent on spot resin markets.
- Polyethylene:Lower-cost alternative for non-sterile applications with reduced thermal tolerance requirements.
- Metal:Stainless steel and aluminum alloys serve reusable sterilization-intensive environments where polymer durability thresholds are insufficient.
- Silicone:Specialized formulations for extreme temperature cycling and flexible sealing applications in advanced assay workflows.
Polypropylene anchors volume production; silicone is gaining share fastest on specialized workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virgin polypropylene capacity expansion in Shandong and Zhejiang provinces is redirecting procurement flows for Western tray converters. German contract research organizations are consolidating supplier relationships around certified EU manufacturers.
United States
FDA container closure guidance for sterile products is extending supplier qualification timelines beyond 18 months for pharmaceutical tray applications. EPA per- and polyfluoroalkyl substances reporting rules are pressuring polypropylene grade reformulation before 2025 enforcement windows. Greater Boston's biotech cluster is standardizing ANSI/SLAS microplate formats for liquid handling platform interchangeability.
Germany
ECHA REACH enforcement on monomer residuals is disqualifying non-compliant Asian converters from European clinical laboratory procurement. ISO 15378 pharmaceutical packaging standards are determining material certification burdens for tray suppliers targeting drug manufacturers. The Rhine-Main CRO cluster is consolidating vendor relationships to reduce qualification audit overhead.
China
Polymer processors in Shandong and Zhejiang are expanding virgin polypropylene capacity for lab consumables export. NMPA medical device registration requirements are tightening for imported tray products. The Yangtze River Delta manufacturing belt is capturing margin from Western converters dependent on spot resin markets.
India
CDSCO streamlined medical device registration is opening procurement channels for tray converters with BIS-certified manufacturing partners. Central government production-linked incentive schemes for medical devices are attracting domestic tray fabrication investment. Maharashtra's clinical laboratory buildout is driving demand for disposable high-throughput screening formats.
Switzerland
Swissmedic pharmaceutical packaging standards are reinforcing material traceability requirements for sterile drug contact applications. The country's precision manufacturing heritage supports specialized borosilicate-adjacent plastic formulation capabilities. Basel's pharmaceutical manufacturing corridor is sourcing cryopreservation-compatible tray formats for cell therapy workflows.
Lab Trays Market Competitive Landscape
Global majors compete with regional champions across resin supply chain control and regulatory certification depth. The vendor base stratifies between captive resin converters, specialized precision fabricators, and broad-line distributors. Three archetypes dominate: integrated life science conglomerates with backward polymer control, mid-cap specialists with documented ISO compliance histories, and regional distributors with deep local laboratory relationships. Capacity expansion and qualification documentation investments are the dominant competitive moves.
Among integrated life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the archetype of converters leveraging captive resin sourcing to sustain margin stability. Greiner Bio-One International GmbH occupies a position within the European specialist tier, competing on lot-to-lot consistency rather than price alone. These three companies represent the competitive spectrum from global scale to regional certification depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Corning Inc. |
| Eppendorf AG |
| Merck KGaA |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Greiner Bio-One International GmbH |
| Heathrow Scientific LLC |
| Simport Scientific Inc. |
| Others |
Supply & Pricing Matrix
Captive resin sourcing by integrated life science conglomerates anchors both supply security and pricing power in the lab trays market, insulating converters from Chinese virgin polypropylene spot market volatility while compressing margins for competitors dependent on external procurement. This backward integration into polymer supply creates tiered cost structures that pharmaceutical buyers exploit through consolidated vendor relationships.
Pricing Analysis
Service-bundling differentiation separates tray converters who include extractables and leachables documentation, lot-to-lot consistency certification, and robotic handler calibration support from those offering bare product transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15378 certification grade and captive resin control, with pharmaceutical companies showing lowest price sensitivity due to 18-month qualification timelines, while educational institutions drive cost compression in uncertified polypropylene segments.
Supply Chain Analysis
ISO 15378 and FDA container closure qualification gating restricts viable supplier pools to converters with documented compliance histories, fragmenting procurement geography. Virgin polypropylene supply concentrates in China, Germany, and the United States, with tray fabrication drawing from specialized borosilicate-adjacent plastic formulations and fluorine-free additive packages. Single-source vulnerability runs through Chinese resin capacity expansion, while distribution feeds from direct-to-laboratory e-procurement platforms disintermediating traditional medical supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lab trays market functions as a cost-of-compliance story where FDA container closure guidance and ECHA REACH enforcement erect barrier-to-entry moats rewarding incumbents with pre-qualified regulatory files and documented lot-to-lot consistency.
For Market Incumbents: Deepen captive resin supply chain control through backward integration into virgin polypropylene sourcing or long-term offtake agreements with Shandong and Zhejiang processors, while consolidating assay preparation workflow offerings to capture expanded wallet share from Germany's CRO cluster facing qualification audit burden reduction priorities. For New Entrants and Emerging Players: Fluorine-free additive validation technology offers a wedge into EPA-compliant polypropylene grades for US pharmaceutical manufacturers, with India's CDSCO-streamlined medical device registration representing the most penetrable geography for BIS-certified manufacturing partnerships targeting Maharashtra's clinical laboratory buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with ISO 15378 certification depth and documented extractables profiles, with long-term viability hinging on 5-10 year regulatory divergence between US and European material disclosure thresholds; watch for ECHA enforcement intensity on monomer residuals as inflection indicator for European supplier qualification pool fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Polypropylene | Captive resin sourcing insulates margin stability from Chinese spot market volatility. |
| Fluorine-Free Additive Validation | EPA reporting rules reward first-movers with preferred supplier status at US drug manufacturers. |
| ANSI/SLAS Microplate Format Certification | Platform interchangeability captures demand from Tecan, Hamilton, and Beckman Coulter liquid handling ecosystems. |
| CDSCO Registration Partnership | BIS-certified manufacturing access opens procurement channels for India's clinical laboratory expansion. |
| Integrated Workflow Offering Development | Combined tray, seal, and barcode labeling solutions reduce qualification audit burden for Germany's CRO cluster. |
Research Methodology
Multi-period observation of resin pricing volatility, regulatory filing timelines, and CRO vendor consolidation patterns anchored the trend analysis, supplemented by interviews with laboratory procurement managers, polymer processing engineers, regulatory affairs specialists at tray converters, and pharmaceutical packaging qualification leads. Secondary validation drew from FDA container closure guidance documents, ECHA REACH enforcement notices, CDSCO medical device registration databases, and customs trade data for virgin polypropylene flows, with bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Input-output matrix framing connected raw material cost trajectories, certification burden intensity, and automation compatibility requirements to segment-specific demand projections across the analysis window. Segmentation dimensions modeled included product type, end user archetype, application function, material grade, and regional regulatory cluster, with CAGRs derived from elasticity-adjusted volume trends and value-per-unit certification premiums. Forecast inputs incorporated robotic handler installation rates and cell therapy facility buildout pipelines.
Several conditions sit outside the modeled scope, including unforeseen polymer formulation breakthroughs, abrupt tariff restructuring on Chinese resin imports, and pandemic-scale disruptions to laboratory capital expenditure cycles. A model refresh is warranted upon material change in FDA enforcement intensity on container closure documentation or ECHA monomer residual threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Anti Venom Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Filter Needles Market