
 North America Medical Clothing Market | 2026-2036
North America Medical Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Clothing Market Insights
Buyer concentration among hospital networks is broadening as integrated delivery systems across the United States and Canada consolidate supplier rosters under enterprise-wide contracts. Medline Industries sustains dominance through its direct-to-facility distribution infrastructure and private-label manufacturing scale. Cardinal Health leverages extensive GPO relationships to lock in multi-year scrub and gown commitments with top-ten health systems. Owens & Minor competes through logistics integration, positioning itself as the back-end supply chain operator for regional hospital alliances.
Medical clothing encompasses garments engineered for barrier protection, fluid resistance, and contamination control in clinical environments, typically constructed from woven or non-woven fabrics meeting AAMI PB70 liquid-borne pathogen standards. These textiles serve primarily to reduce cross-infection risk between healthcare workers and patients during procedures ranging from routine examinations to major surgery. Among product types, surgical gowns command premium positioning due to stringent barrier-classification requirements and shorter replacement cycles, while scrubs represent the highest-volume category driven by daily-change protocols in hospitals. Protective wear is gaining structural importance as outpatient surgical volumes rise and ambulatory centers adopt hospital-grade PPE standards previously limited to inpatient settings.
The FDA's AAMI PB70 classification system and OSHA's Bloodborne Pathogens Standard jointly dictate minimum barrier performance for surgical apparel sold in the United States, while Health Canada's Medical Devices Bureau enforces parallel requirements for Canadian market access. These frameworks elevate compliance costs for new entrants but create durable demand for certified, trackable product lines among risk-averse procurement officers. Stakeholders must monitor how impending updates to flame-resistance and sustainability standards reshape material specifications and sourcing obligations across the continent.
Market Dynamics
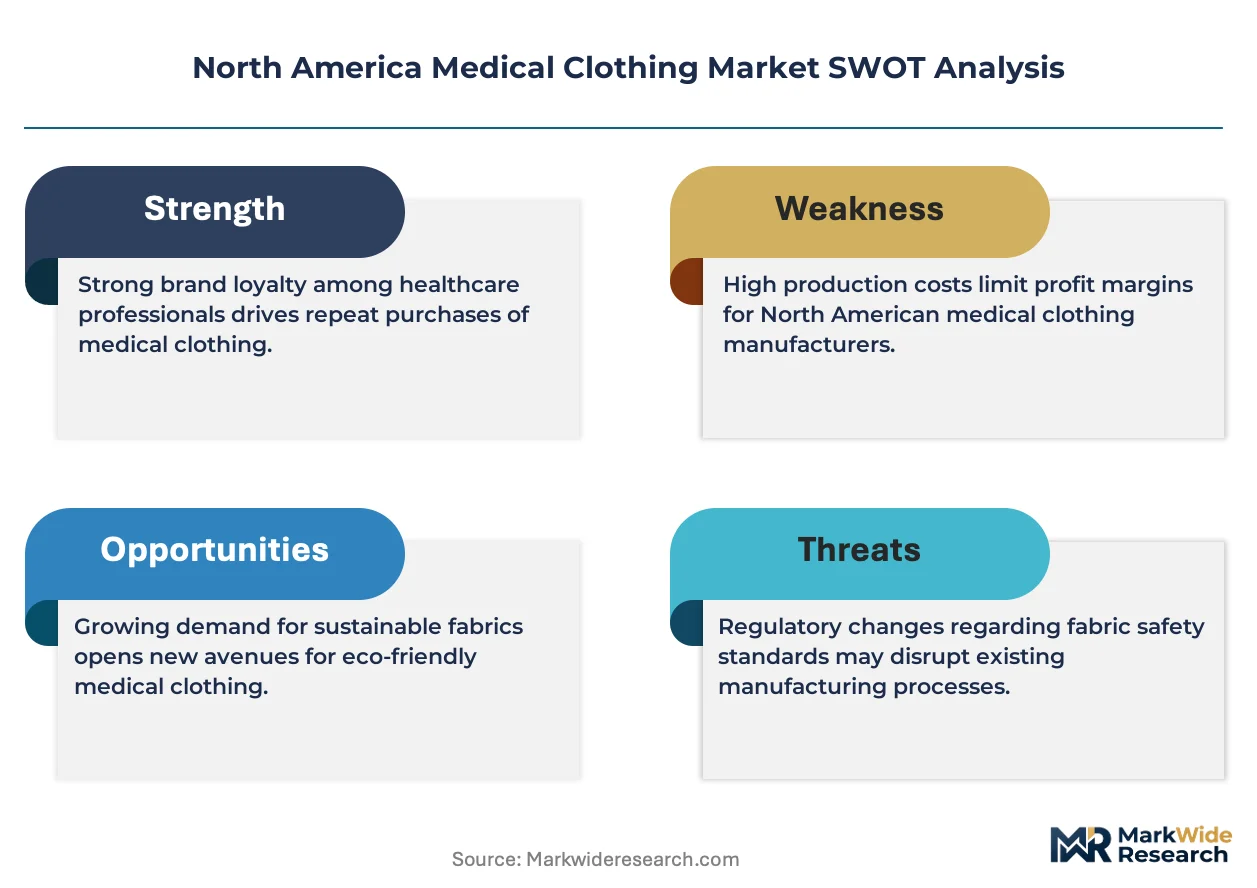
Hospital procurement consolidation across the United States and Canada is compressing vendor rosters and elevating compliance requirements for AAMI PB70 barrier certification as the dominant market-shaping force.
Growth Catalysts
- Integrated delivery system expansion:Multi-hospital networks in the southeastern United States are standardizing surgical gown specifications under enterprise contracts, driving volume commitments for certified suppliers.
- AAMI PB70 barrier upgrades:FDA guidance on liquid-borne pathogen resistance is pushing replacement of legacy woven textiles with synthetic non-woven materials in Level 3 and Level 4 surgical applications.
- Ambulatory surgical center proliferation:Outpatient facilities across Texas and Florida are adopting hospital-grade PPE standards previously limited to inpatient settings, expanding addressable demand for protective apparel.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyester fiber costs fluctuate with crude oil derivatives, compressing margins for non-woven surgical gown manufacturers dependent on synthetic feedstocks.
- Domestic supply concentration:Spunbond-meltblown-spunbond fabric production clusters in the southeastern United States create geographic vulnerability to hurricane disruption and regional logistics constraints.
- Reusable textile substitution:Industrial laundry services are advancing barrier-coated cotton alternatives for Level 1 and Level 2 applications, threatening disposables in low-acuity settings.
Strategic Opportunities
- Canadian market penetration:Health Canada's Medical Devices Bureau maintains less consolidated procurement than US integrated delivery networks, offering entry points for mid-scale certified manufacturers.
- Sustainability-linked procurement mandates:Emerging state-level hospital purchasing guidelines in California and New York favor recycled-content and biodegradable synthetic fibers, rewarding early compliance investment.
- Direct-to-facility distribution bypass:Regional hospital alliances in the Midwest are experimenting with vendor-managed inventory systems that displace traditional distributor markups.
Industry Challenges
- Barrier testing certification backlog:Third-party AAMI PB70 validation laboratories face capacity constraints, extending product launch timelines for new synthetic material formulations.
- Legacy linen service integration:Hospitals maintaining hybrid reusable-disposable programs require dual inventory management systems, complicating supply chain standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Clothing Market |
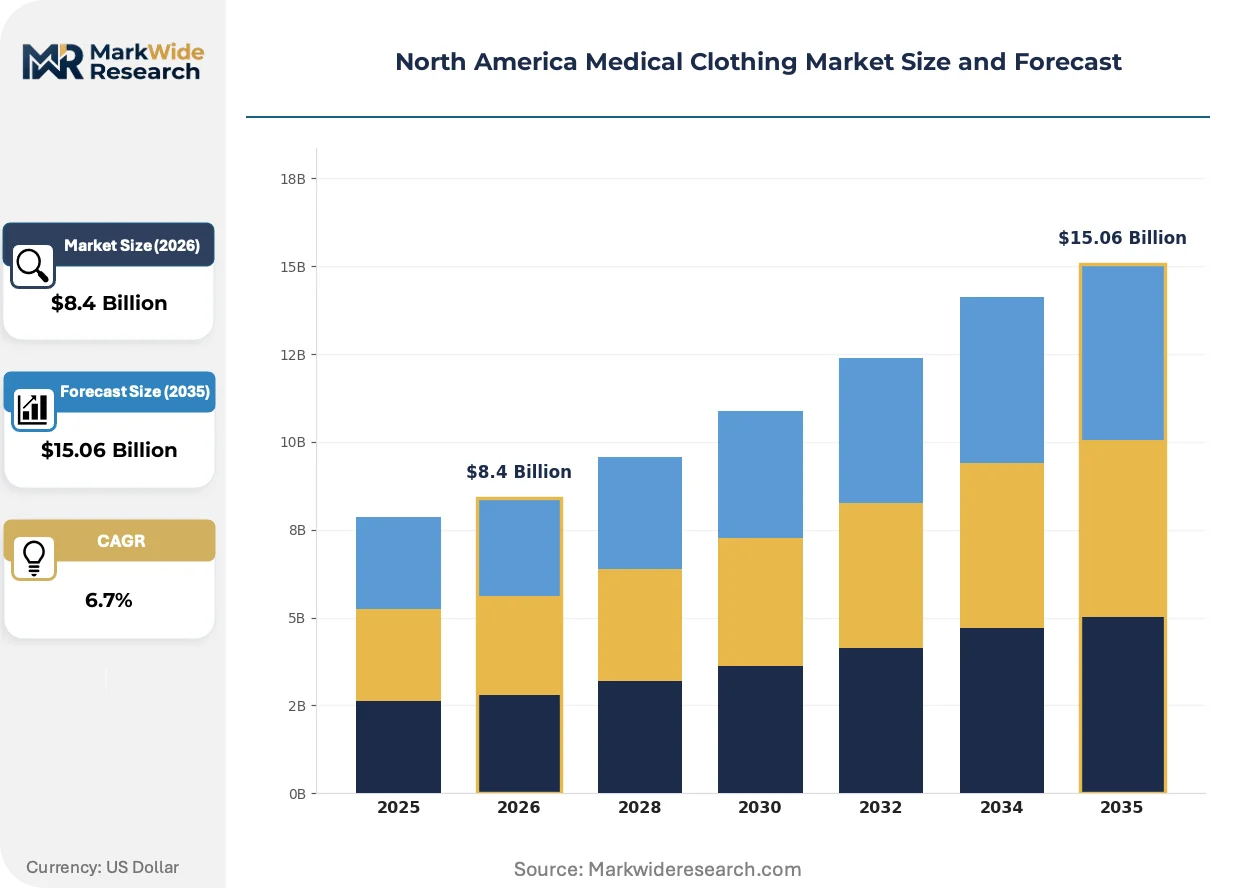
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrubs, Lab Coats, Surgical Gowns, Protective Wear End User: Clinics, Hospitals, Laboratories, Nursing Homes Material: Cotton, Polyester, Nylon, Blends Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Cardinal Health, Inc., Medline Industries, Inc., 3M Company, Superior Group of Companies, Smith & Nephew, Henry Schein, Inc., Ansell Ltd., Carhartt, Inc., Owens & Minor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Clothing Market Trends and Innovations
Material science advances and procurement centralization are restructuring how barrier protection is specified, sourced, and delivered across North American healthcare networks.
Spunbond-meltblown-spunbond composite fabrics with plasma-treated hydrophilic layers are modularizing surgical gown construction by enabling separate optimization of fluid strike-through resistance and wearer breathability. Major health systems in Georgia and North Carolina are piloting these configurable designs for orthopedic and cardiovascular procedures. This technology is modularizing supplier-customer relationships, allowing hospitals to specify barrier grade independently of base textile weight and cut.
OSHA's pending updates to the Bloodborne Pathogens Standard are tightening documentation requirements for employer-provided protective apparel selection rationale. Manufacturers must now maintain traceable lot-level test data for AAMI PB70 claims, elevating record-keeping costs but creating preference for vertically integrated producers with captive testing facilities. Surgical gown suppliers serving unionized hospitals in the Great Lakes region are investing most aggressively in compliance infrastructure.
Consolidated purchasing committees at multi-state health systems are displacing individual hospital materials management autonomy, compressing supplier negotiation cycles and standardizing product specifications across dozens of facilities simultaneously. This concentration is most visible in Texas, where three largest networks control scrub and gown procurement for over four hundred care sites.
North America Medical Clothing Market Segmentation
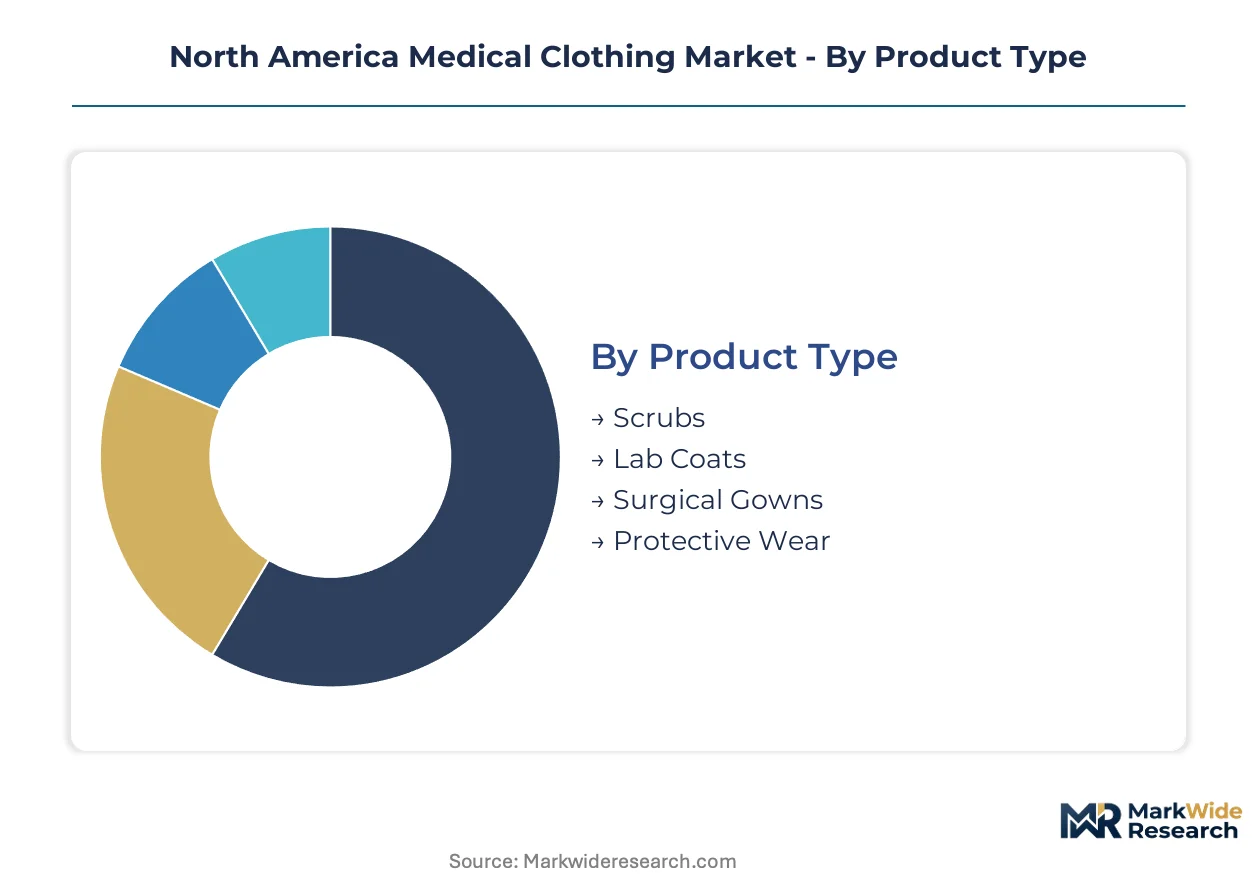
Hospital procurement committees across the United States and Canada segment medical clothing purchases by barrier performance, end-use acuity, and contract consolidation potential. Understanding these divisions reveals where synthetic material upgrades concentrate and which distribution channels capture enterprise contract value.
Product Type:
Replacement cycles and barrier-grade upgrades vary sharply across garment categories, with AAMI PB70 certification requirements driving divergence in procurement specifications.
- Surgical Gowns:Multi-layer synthetic non-woven constructions meeting Level 3 and Level 4 liquid-borne pathogen standards dominate hospital purchasing. Demand concentrates in southeastern United States surgical expansion projects where health systems replace legacy woven inventories with disposable barrier-grade alternatives.
- Scrubs:Daily-change protocols in hospital settings generate the highest unit volumes, typically constructed from polyester-cotton blends or pure synthetic fabrics for fluid resistance. Texas and Florida health networks are standardizing scrub specifications across hundreds of ambulatory sites simultaneously.
- Lab Coats:Mid-weight woven or knit fabrics with basic fluid-repellent finishes serve diagnostic and research environments. Procurement runs through institutional uniform programs rather than acute-care supply chains.
- Protective Wear:Isolation gowns, coveralls, and procedure-specific barriers address outpatient surgical center adoption of hospital-grade PPE standards. Growth accelerates in ambulatory settings across the Midwest where procedure volumes shift from inpatient facilities.
Scrubs sit at the top of the volume ranking, with protective wear climbing the fastest.
End User:
Facility acuity and reimbursement structure determine barrier-grade requirements, with cost tier separation between acute-care and outpatient settings.
- Hospitals:Enterprise contract consolidation across integrated delivery networks drives Level 3 and Level 4 surgical gown procurement. Specifications in Georgia and North Carolina health systems now mandate traceable lot-level AAMI PB70 documentation.
- Clinics:Outpatient diagnostic and minor procedure sites operate on lower barrier-grade standards with higher price sensitivity. California and New York clinic chains are piloting recycled-content fiber programs under emerging state sustainability mandates.
- Laboratories:Research and clinical testing facilities prioritize chemical resistance and static control over liquid-borne pathogen barriers. Demand clusters in Boston and San Diego biotech corridors.
- Nursing Homes:Long-term care facilities balance infection control with resident comfort, driving demand for reusable textile programs and lower-cost disposable alternatives. Midwest regional chains are testing vendor-managed inventory systems.
Hospitals command the steepest pricing tiers, while clinics gain share fastest as ambulatory volumes expand.
Material:
Raw material selection tracks barrier performance requirements and petrochemical input exposure, with synthetic fibers capturing share from natural alternatives.
- Polyester:Dominates scrub and protective wear construction through spunbond and meltblown non-woven technologies. Manufacturers in the southeastern United States face margin pressure from crude oil derivative volatility.
- Blends:Polyester-cotton combinations balance comfort and fluid resistance for mid-acuity applications. Industrial laundry services are advancing barrier-coated cotton-poly alternatives for Level 1 and Level 2 reusable programs.
- Cotton:Natural fiber retains presence in reusable textile programs and comfort-focused scrub lines. Pricing disadvantage against synthetics limits growth in barrier-critical applications.
- Nylon:High-tensile strength supports specialized surgical and chemical-resistant applications. Niche positioning limits volume scale relative to polyester alternatives.
Polyester leads material volume, with blends expanding most quickly as hybrid reusable-disposable programs proliferate.
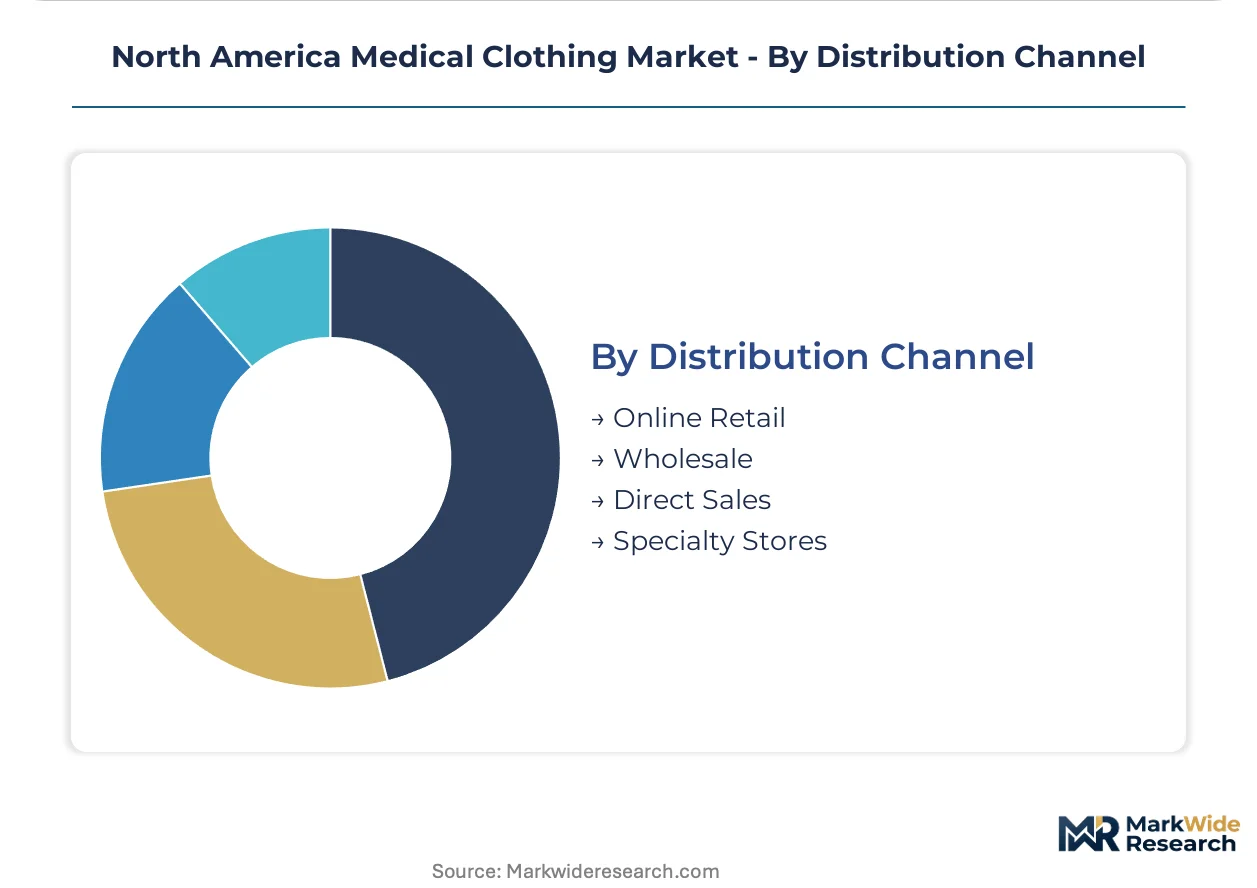
Distribution Channel:
Channel selection reflects procurement centralization and inventory management sophistication, with direct relationships displacing traditional intermediaries.
- Direct Sales:Manufacturer-to-facility relationships capture enterprise contract value at multi-hospital networks. Medline Industries and Cardinal Health leverage captive distribution infrastructure to bypass wholesale markups.
- Wholesale:Traditional medical supply distributors serve mid-scale facilities without consolidated purchasing power. Regional distributors in the Great Lakes region retain relevance for unionized hospitals with legacy supplier relationships.
- Online Retail:E-commerce platforms address small clinic and individual practitioner purchases outside enterprise contract coverage. Growth concentrates in independent ambulatory surgery centers.
- Specialty Stores:Uniform retailers and medical apparel boutiques serve nursing home and individual healthcare worker demand. Channel relevance declines as institutional procurement centralizes.
Direct sales holds the revenue concentration advantage, with online retail gaining traction fastest among independent outpatient facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater procurement volume than Canada, though both markets face parallel pressure from hospital network consolidation and evolving barrier-performance standards.
United States
Southeastern health systems in Georgia and North Carolina are replacing legacy woven inventories with Level 3 and Level 4 synthetic surgical gowns. The FDA's AAMI PB70 classification system mandates liquid-borne pathogen resistance documentation for all new product launches. Texas-based integrated delivery networks now standardize scrub specifications across hundreds of ambulatory sites simultaneously.
Canada
Health Canada's Medical Devices Bureau enforces barrier certification parallel to FDA requirements, though procurement remains less consolidated than US integrated delivery networks. Ontario and Quebec hospital alliances are piloting vendor-managed inventory systems for nursing home protective wear. Calgary and Edmonton surgical centers are adopting hospital-grade PPE standards previously limited to acute-care facilities.
Mexico
Northern border states supply contract manufacturing capacity for US-based medical apparel brands seeking tariff-advantaged production. Mexico's national health regulator, COFEPRIS, aligns medical device standards with FDA guidance to facilitate cross-border trade. Tijuana and Mexicali industrial parks host cut-and-sew operations for polyester scrub and surgical gown assembly.
North America Medical Clothing Market Competitive Landscape
United States producers anchor the premium tier through direct-to-facility distribution infrastructure; Canadian and Mexican specialists hold contract manufacturing and regional service positions. The vendor base concentrates around three strategic archetypes: integrated distributors with captive manufacturing, pure-play logistics operators, and diversified health conglomerates with medical apparel divisions. Capacity expansion and enterprise contract consolidation represent the dominant competitive moves.
Within the integrated distributor tier, Medline Industries, Inc. and Cardinal Health, Inc. exemplify the scale-driven model through private-label manufacturing and direct hospital network relationships. Owens & Minor, Inc. occupies a distinct logistics-centric position, serving as back-end supply chain operator for regional hospital alliances. 3M Company represents the diversified technology conglomerate archetype, leveraging material science capabilities across multiple healthcare segments.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Medline Industries, Inc. |
| 3M Company |
| Superior Group of Companies |
| Smith & Nephew |
| Henry Schein, Inc. |
| Ansell Ltd. |
| Carhartt, Inc. |
| Owens & Minor, Inc. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consolidation across southeastern United States health systems is compressing vendor rosters and mandating AAMI PB70 Level 3 and Level 4 certification, forcing manufacturers to absorb third-party validation costs and reposition pricing around barrier-grade tiers rather than commodity fabric weights.
Pricing Analysis
Capacity additions in Georgia and North Carolina are reshaping price floors for synthetic non-woven surgical gowns. Three-tier pricing structure across premium, standard, and economy levels separates Level 4 barrier documentation from Level 3 certification from unvalidated woven alternatives. Price differentiation tracks AAMI PB70 tier and volume commitment scale. Cost compression in the standard tier is intensifying because petrochemical feedstock volatility squeezes polypropylene margin. Independent ambulatory surgery centers in Texas and Florida show highest price sensitivity; integrated delivery networks in the Great Lakes region show lowest.
Supply Chain Analysis
AAMI PB70 certification gating through third-party validation laboratories creates supply chain bottlenecks, extending product launch timelines for new synthetic formulations. Manufacturing concentrates in the United States, Mexico, and Canada. Raw material supply draws from polypropylene resin, polyester fiber, and meltblown fabric production. Single-source vulnerability sits with spunbond-meltblown-spunbond fabric clusters in hurricane-exposed southeastern states. Distribution runs through direct-to-facility contracts at integrated delivery networks, displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America medical clothing market functions as a stable compounder, with hospital network consolidation and barrier-grade upgrade cycles generating predictable replacement demand across surgical gown and scrub categories.
For Market Incumbents: Hedge against reusable textile substitution by advancing barrier-coated synthetic blends for Level 1 and Level 2 applications. Deepen captive AAMI PB70 testing infrastructure to compress certification timelines and lock in enterprise contract renewals. Defensive consolidation through regional distributor acquisition protects channel position against vendor-managed inventory experiments in the Midwest. For New Entrants and Emerging Players: Canadian nursing home chains operating outside consolidated US procurement networks offer the most penetrable buyer archetype for mid-scale certified manufacturers. Health Canada's less concentrated purchasing environment enables direct relationship building without GPO exclusion. Vendor-managed inventory pilots in Ontario and Quebec provide a service-based go-to-market angle that differentiates against distributor-dependent incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated manufacturers possessing captive testing facilities and direct hospital network relationships. Long-term viability favors producers with backward integration into spunbond-meltblown-spunbond fabric production. Watch for OSHA Bloodborne Pathogens Standard updates as an inflection indicator that would accelerate compliance infrastructure investment and consolidate supplier rosters further.| Strategic Initiative | Industry Significance |
|---|---|
| AAMI PB70 Certification Investment | Captive testing facilities compress product launch timelines and secure enterprise contract renewals at southeastern health systems. |
| Direct-to-Facility Distribution Expansion | Bypassing traditional distributor markups captures value from vendor-managed inventory experiments in Midwest regional alliances. |
| Sustainability-Linked Product Development | Recycled-content and biodegradable synthetic fibers align with emerging California and New York state hospital purchasing mandates. |
| Canadian Market Penetration | Less consolidated procurement than US integrated delivery networks creates entry points for mid-scale certified manufacturers. |
| Reusable-Disposable Hybrid Program Integration | Dual inventory management capabilities address hospitals maintaining hybrid linen service and disposable surgical gown programs. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down synthetic fiber production tracking forms the analytical core. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and industrial laundry service operators combined with secondary validation from FDA 510(k) filings, Health Canada Medical Devices Bureau registrations, hospital procurement databases, and AAMI PB70 third-party laboratory records. Triangulation across supply-side capacity data and demand-side contract announcements ensures segment-level consistency.
Input-output matrix framing connects polypropylene resin pricing, meltblown fabric production capacity, and hospital capital expenditure announcements to surgical gown and scrub volume projections. Segmentation dimensions modeled include barrier performance tier, end-use facility acuity, material composition, and distribution channel structure. CAGRs derive from replacement cycle analysis and procurement standardization trends. Forecast inputs incorporate ambulatory surgical center expansion rates and OSHA regulatory update probability.
Inputs from hospital procurement databases and GPO contract registries were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around vendor-managed inventory adoption timing. Forecasts reflect assumptions regarding sustained hospital network consolidation and AAMI PB70 enforcement continuity. A model refresh is warranted upon material change in FDA surgical gown barrier guidance or petrochemical feedstock cost structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plasma Expanders Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Blood Bags Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Safety Pen Needles Market