
 Global Active Electronic Components Market | 2026-2036
Global Active Electronic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active Electronic Components Market Intelligence
System-level integration support for complex designs is reshaping the value proposition beyond discrete component sales. Texas Instruments leverages its extensive product catalog to provide comprehensive reference designs for customers. Infineon Technologies specializes in power systems, offering deep application support for automotive and industrial segments. NXP Semiconductors competes by providing secure, connected solutions for targeted end markets.
Active electronic components are semiconductor devices that require an external power source to operate, enabling them to amplify or switch electrical signals. Their function relies on materials like silicon, Gallium Nitride, or Silicon Carbide to control current flow. Integrated Circuits represent the largest segment by value, encompassing microprocessors and memory. While CMOS technology underpins the vast consumer electronics application, emerging Silicon Carbide and Gallium Nitride technologies are creating high-margin opportunities in industrial automation and telecommunications.
Material composition and product safety are governed by a complex web of international regulations. The EU’s RoHS and REACH directives heavily influence material selection, while China’s GB standards create specific market access requirements. These frameworks compel manufacturers to maintain transparent and adaptable supply chains. Consequently, balancing cost-efficiency with geopolitical diversification in sourcing and manufacturing will define competitive success.
Market Dynamics
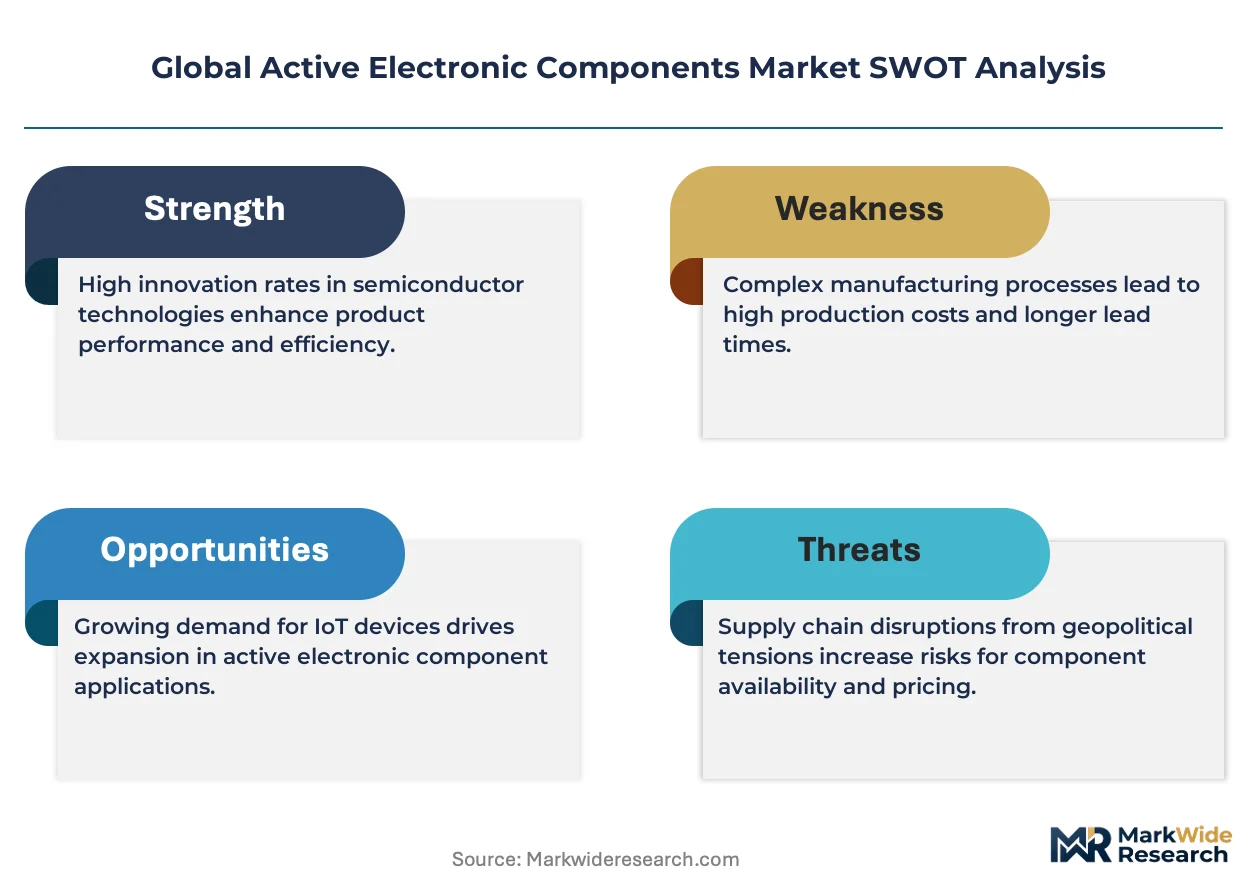
The central tension in the active electronics components market is the conflict between the need for resilient, geographically diverse supply chains and the intense concentration of advanced manufacturing and design expertise in a few key industrial clusters.
Growth Catalysts
- Wide-Bandgap Semiconductors:Adoption of Gallium Nitride and Silicon Carbide in electric vehicles and 5G base stations enhances energy efficiency and performance.
- Telecommunications Expansion:The global deployment of 5G networks necessitates a significant build-out of new infrastructure, demanding advanced active components.
- Onshoring Policies:Government incentives, such as the US CHIPS Act and similar European frameworks, encourage domestic semiconductor manufacturing investment.
Market Restraints
- High Capital Intensity:Constructing and equipping advanced semiconductor fabrication plants requires massive upfront investment, creating high barriers to entry for new players.
- Geopolitical Concentration:The heavy reliance on foundries in Taiwan for leading-edge chip production creates significant supply chain vulnerability to regional instability.
- Extended Qualification Cycles:Components for critical applications in the automotive, aerospace, and medical sectors require lengthy and rigorous testing and validation periods.
Strategic Opportunities
- Industrial IoT and Automation:The proliferation of connected devices in smart factories and logistics provides a vast new market for specialized sensors and microcontrollers.
- Advanced Packaging Technologies:System-in-Package (SiP) and other 3D integration techniques offer a path to increase functionality and performance without shrinking transistor nodes.
- Green Energy Transition:Policies like the EU Green Deal create demand for high-efficiency power semiconductors in solar inverters, wind turbines, and grid infrastructure.
Industry Challenges
- Talent Scarcity:A persistent shortage of skilled semiconductor engineers, IC designers, and fabrication technicians constrains industry growth and innovation capacity.
- Regulatory Fragmentation:Navigating the complex and divergent requirements of the EU's RoHS, China's GB standards, and other national rules increases compliance costs.
- Legacy System Integration:Integrating new components with legacy industrial or automotive systems presents significant validation and interoperability hurdles for engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active Electronic Components Market |
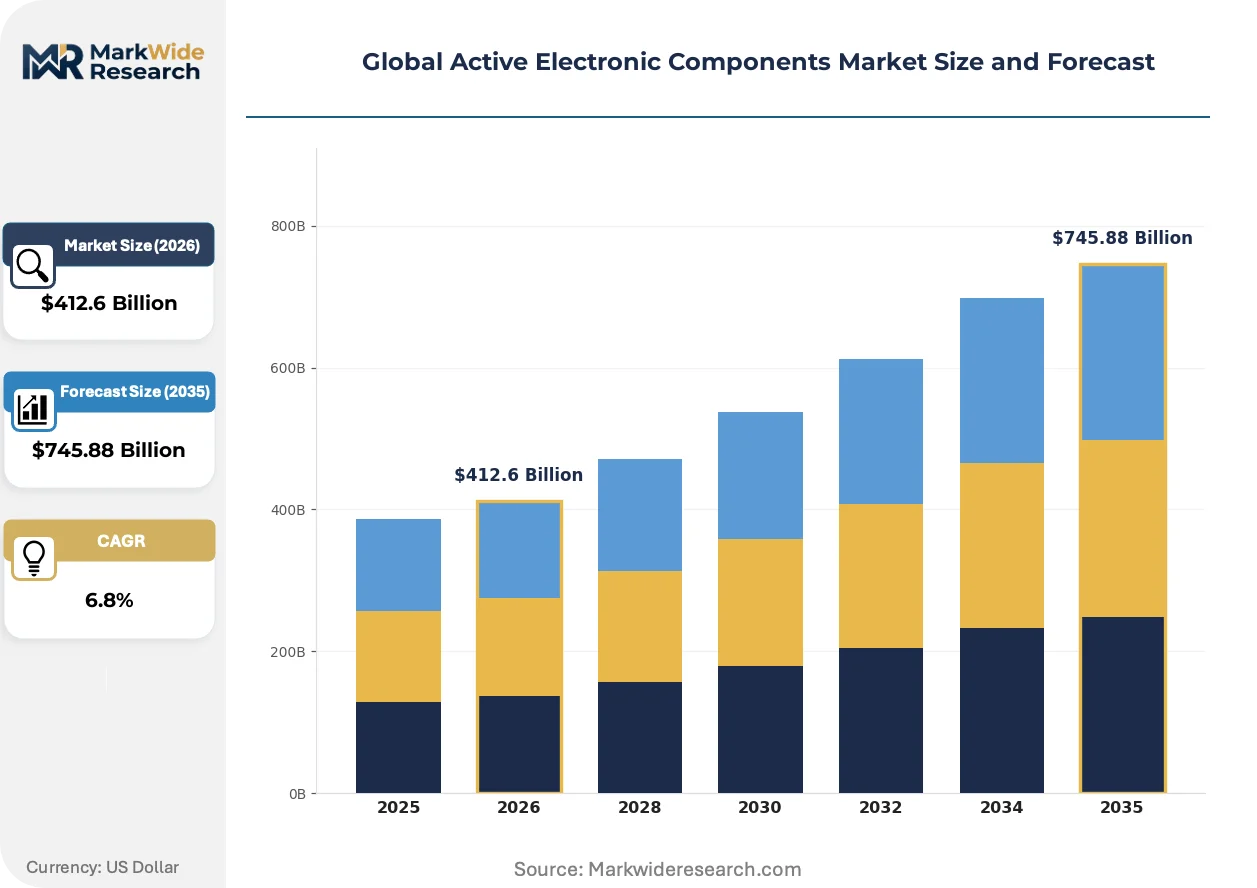
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $745.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Transistors, Diodes, Integrated Circuits, Optoelectronics, Sensors Technology: CMOS, Bipolar Junction, Gallium Nitride, Silicon Carbide, Microelectromechanical Systems Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Automation, Defense Devices End User: OEMs, System Integrators, Contract Manufacturers, Electronic Subassembly Producers, Measurement & Instrumentation |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies, NXP Semiconductors, STMicroelectronics, Broadcom, Microchip Technology, ON Semiconductor, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active Electronic Components Market Strategic Shifts & Innovations
The push for greater energy efficiency and data processing density alters component design and system architecture. Material science advancements enable performance gains previously unattainable with conventional silicon, creating new value pockets.
Wide-bandgap semiconductors like Gallium Nitride and Silicon Carbide deliver superior performance in high-power, high-frequency applications. The automotive sector for electric vehicle chargers and the telecommunications industry for 5G base stations are rapidly adopting these materials. This material shift is digitizing power management, enabling more efficient and compact power conversion systems.
European Union directives like RoHS and REACH impose strict controls on hazardous substances used in electronic components. This forces manufacturers to invest heavily in material compliance, supply chain tracking, and the requalification of alternative materials. The industrial and consumer electronics segments targeting the EU market are most impacted, requiring robust data management systems.
Customer procurement is evolving from buying discrete components to sourcing integrated reference designs and application-specific platforms. This behavior disrupts traditional distribution channels and favors suppliers offering deep system-level engineering support. The shift is most pronounced in complex markets like automotive ADAS and industrial robotics, where design-in cycle time is critical.
Global Active Electronic Components Market Segmentation
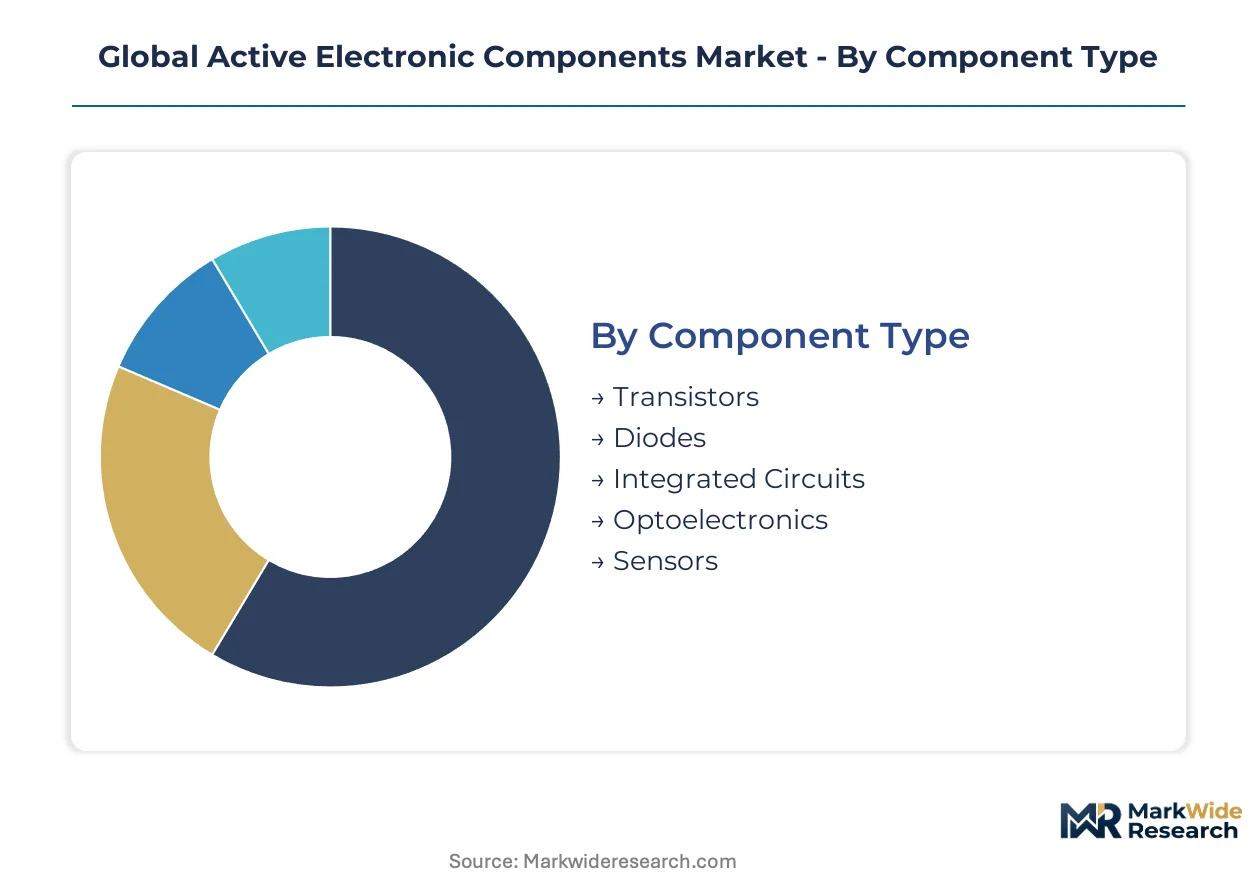
Understanding the segmentation of the global active electronic components market reveals the diverse technological requirements and end-user demands driving innovation. Each segment exhibits unique characteristics regarding component lifecycle, performance needs, and integration complexities.
Component Type:
The lifecycle of active electronic components varies significantly, with some segments experiencing rapid obsolescence while others maintain long product cycles.
- Integrated Circuits:Integrated circuits combine multiple electronic components onto a single semiconductor substrate, forming microprocessors, memory, and logic devices. Demand concentrates in consumer electronics and data centers, driven by continuous performance and miniaturization requirements.
- Transistors:Transistors are fundamental semiconductor devices used to amplify or switch electronic signals and electrical power, commonly found in power management and signal processing. Automotive and industrial applications drive demand for robust, high-power transistors, supporting electrification and automation trends.
- Diodes:Diodes are two-terminal electronic components that conduct current primarily in one direction, essential for rectification and voltage regulation.
- Optoelectronics:Optoelectronic devices convert electrical energy into light or vice versa, including LEDs, photodiodes, and optical sensors.
- Sensors:Sensors detect and respond to physical input from the environment, converting it into an electrical signal for processing.
Integrated Circuits dominate the installed base. Optoelectronics is where expansion concentrates.
Technology:
The supply concentration for active electronic component technologies varies, with some established processes widely available and others highly specialized.
- Gallium Nitride:Gallium Nitride (GaN) is a wide-bandgap semiconductor material offering superior efficiency and power density compared to silicon, ideal for high-frequency and high-power applications. Telecommunications equipment and electric vehicle chargers are rapidly adopting GaN, driven by energy efficiency mandates.
- Silicon Carbide:Silicon Carbide (SiC) is another wide-bandgap semiconductor material, providing high thermal conductivity and breakdown voltage for extreme power applications. Industrial motor drives and grid infrastructure projects in Europe demand SiC for enhanced reliability and efficiency.
- CMOS:Complementary Metal-Oxide-Semiconductor (CMOS) technology forms the basis for most modern integrated circuits, known for low power consumption.
- Bipolar Junction:Bipolar Junction Transistors (BJTs) are current-controlled current devices, offering high gain and used in amplification and switching circuits.
- Microelectromechanical Systems:Microelectromechanical Systems (MEMS) integrate mechanical elements, sensors, actuators, and electronics on a common silicon substrate.
CMOS technology forms the foundational volume. Gallium Nitride is climbing the fastest.
Application:
Active electronic component applications span diverse sectors, each with distinct performance and reliability requirements.
- Telecommunications Equipment:Telecommunications equipment utilizes active components for signal processing, amplification, and switching in network infrastructure, including base stations and data centers. Global 5G network rollouts drive immense demand for high-frequency and power-efficient components, particularly in Asia.
- Industrial Automation:Industrial automation systems rely on active components for precise control, sensing, and data processing in robotics, PLCs, and motor drives. The push for smart factories and Industry 4.0 initiatives in Germany and Japan fuels demand for rugged microcontrollers and sensors.
- Consumer Electronics:Consumer electronics, including smartphones, laptops, and home appliances, represent a high-volume application for various active components.
- Aerospace Systems:Aerospace systems demand highly reliable and robust active components for avionics, navigation, and communication in extreme environments.
- Defense Devices:Defense devices require specialized, high-performance active components for radar, electronic warfare, and secure communication systems.
Consumer Electronics drives significant volume. Industrial Automation exhibits the steepest expansion trajectory.
End User:
Active electronic component end-users exhibit varied procurement patterns and integration needs, influencing component design and support services.
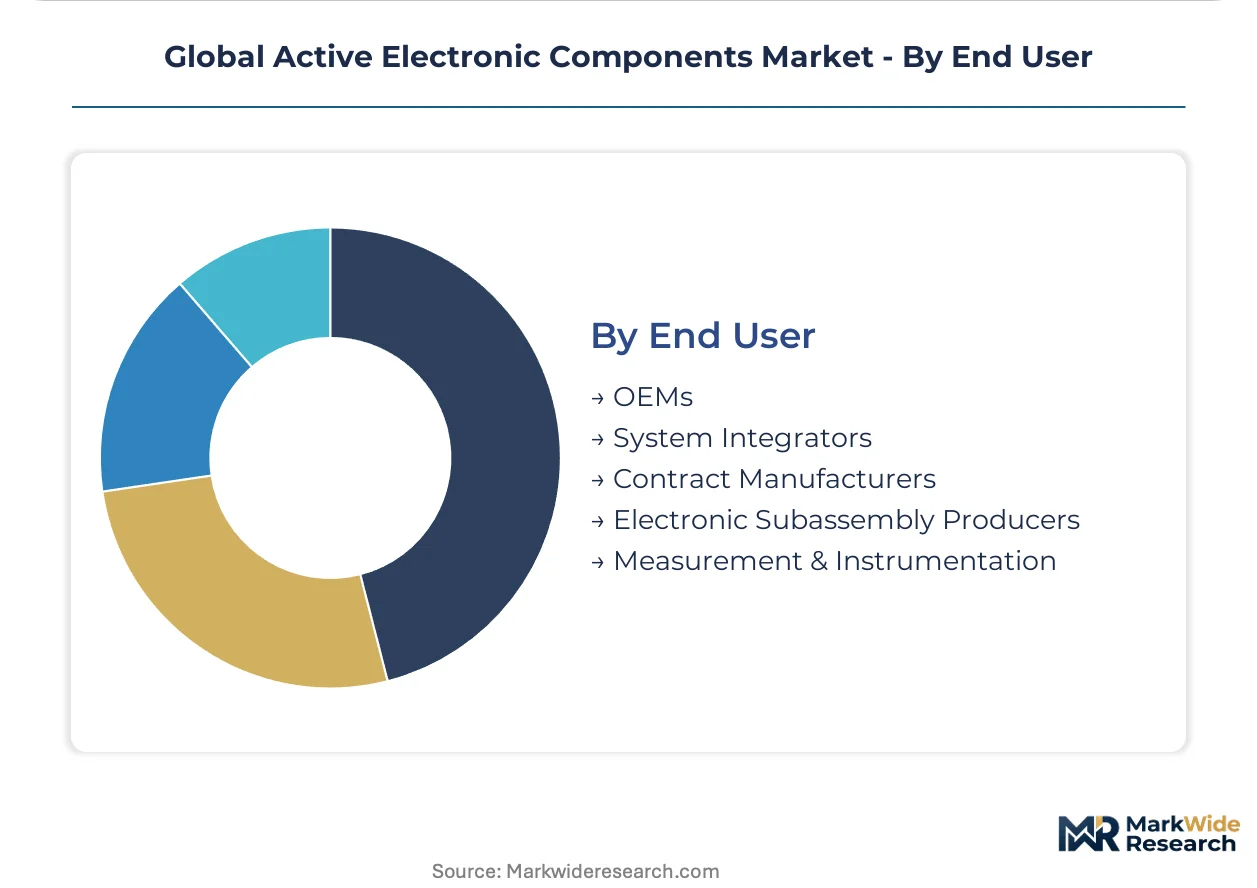
- OEMs:Original Equipment Manufacturers integrate active components directly into their final products, requiring extensive design-in support and long-term supply agreements. Automotive manufacturers and white goods producers represent significant OEM demand, driven by product innovation cycles.
- System Integrators:System integrators combine components from multiple suppliers to create complete solutions for specific customer projects, often requiring flexible supply and technical assistance. Industrial control system providers and defense contractors frequently engage system integrators for complex deployments.
- Contract Manufacturers:Contract manufacturers produce electronic assemblies and products for other companies, often procuring components based on customer specifications.
- Electronic Subassembly Producers:These entities specialize in creating modular electronic subassemblies that are then integrated into larger systems by other manufacturers.
- Measurement & Instrumentation:This sector uses active components in test equipment, analytical instruments, and precision measurement devices.
OEMs form the foundational demand. System Integrators demonstrate the most rapid shift in procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption patterns for active electronic components vary significantly across global geographies, reflecting distinct industrial priorities. Asia's telecommunications expansion drives demand for high-frequency components, while European markets prioritize high-efficiency power semiconductors for green energy initiatives. North America focuses on advanced packaging and secure solutions for diverse end markets.
United States
The United States market exhibits strong demand for advanced active components, fueled by investments in 5G networks and defense systems. The US CHIPS Act provides significant incentives for domestic semiconductor manufacturing investment. Silicon Valley and Arizona anchor substantial design and fabrication capabilities.
Germany
Germany drives demand for high-efficiency power semiconductors, particularly in industrial automation and electric vehicle applications. The EU Green Deal mandates stringent energy efficiency targets, propelling Silicon Carbide adoption. Bavaria and Baden-Württemberg host critical automotive and industrial electronics clusters.
Taiwan
Taiwan remains a central hub for leading-edge integrated circuit manufacturing and advanced packaging technologies. Its strategic importance creates supply chain vulnerabilities to regional instability. The Hsinchu Science Park concentrates a vast ecosystem of foundries and design houses.
South Korea
South Korea demonstrates robust demand for memory components and advanced logic devices, supporting its dominant consumer electronics industry. Government policies actively promote investment in next-generation semiconductor technologies. Gyeonggi Province houses major production facilities for integrated circuits and optoelectronics.
China
China's market expansion is propelled by its massive telecommunications equipment industry and burgeoning industrial IoT sector. China’s GB standards impose specific market access requirements on electronic components. The Yangtze River Delta region features extensive electronics manufacturing and assembly operations.
Global Active Electronic Components Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the active electronic components market. The industry exhibits a tiered structure, with a few large integrated device manufacturers alongside numerous specialized component providers. These strategic archetypes include broad-portfolio giants, niche technology specialists, and application-focused solution providers. Companies pursue strategic partnerships and targeted technology acquisitions to enhance their market positions.
Within the diverse landscape, companies like Texas Instruments exemplify broad-portfolio giants, leveraging extensive product catalogs to provide comprehensive reference designs and system-level integration support. Infineon Technologies occupies a distinct position as a specialist in power systems, offering deep application support for critical automotive and industrial segments. NXP Semiconductors further anchors the market by focusing on secure, connected solutions, targeting specific end markets with tailored offerings. These entities showcase varied approaches to value creation beyond discrete component sales.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Broadcom |
| Microchip Technology |
| ON Semiconductor |
| Renesas Electronics |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for delivering active electronic components, face cost volatility which directly influences supply chain resilience and downstream price differentiation. This dynamic highlights the intricate balance between globalized manufacturing and localized market demands.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for high-value active electronic components, providing stability for both suppliers and OEMs. Price differentiation arises from quality grade, particularly for automotive-certified parts, and the level of customization required for application-specific integrated circuits. Pricing softness currently affects commodity-grade components, stemming from intensified competition among new entrants in mature technology nodes. Consumer electronics manufacturers demonstrate the highest price sensitivity, while aerospace and defense sectors prioritize performance and reliability over cost.
Supply Chain Analysis
Export control regimes, such as those limiting advanced semiconductor technology transfers, directly impact the global supply chain for active electronic components. Supply concentration remains high in Taiwan, South Korea, and the United States for leading-edge manufacturing. The industry relies heavily on specialized silicon wafers and high-purity chemicals as key inputs. Single-source vulnerability, particularly for advanced foundry services, poses a significant structural risk. Downstream distribution primarily occurs through direct sales to large OEMs and specialized global distributors serving diverse end markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The active electronic components market navigates significant challenges posed by a critical scarcity of specialized engineering talent. This talent gap, especially in areas like advanced material science and complex IC design, constrains innovation velocity and manufacturing scalability.
For Market Incumbents: Entrench existing market leadership by investing heavily in next-generation wide-bandgap material research and expanding geographically diverse fabrication capacity. This strategy mitigates geopolitical concentration risks and counters emerging competition from specialized technology developers. Deepen vertical integration into critical raw material sourcing and secure long-term supply agreements for key inputs. Prioritize certification investments for high-reliability components targeting automotive and industrial applications.
For New Entrants and Emerging Players: Pursue niche market opportunities in rapidly expanding segments like industrial IoT sensors or high-efficiency power management solutions. The industrial automation sector, particularly in Germany and Japan, offers penetrable segments for specialized microcontrollers requiring deep application support. Differentiate offerings through superior system-level integration support and comprehensive reference designs, addressing specific customer pain points. Focus on areas where legacy silicon solutions are less efficient, leveraging new material advantages.
For Investors and Strategic Acquirers: Specialized technology developers focusing on wide-bandgap materials or advanced packaging techniques represent attractive acquisition targets. The market maintains strong long-term viability, driven by pervasive digitalization and electrification trends across industries. Strategic acquisitions should aim to consolidate intellectual property and secure critical talent pools. A key signal to watch is the volume of patent filings in novel semiconductor architectures or significant government funding allocations for domestic manufacturing initiatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ensures supply stability for critical components in high-demand sectors like automotive and telecommunications. |
| Advanced Packaging Investment | Enhances performance density and reduces form factor for next-generation devices. |
| Talent Development Programs | Addresses the persistent shortage of skilled engineers and fabrication technicians across the industry. |
| Geopolitical Diversification | Mitigates supply chain risks associated with concentrated manufacturing hubs in Asia. |
| Wide-Bandgap Material R&D | Captures high-margin opportunities in energy-efficient power electronics and 5G infrastructure. |
Research Approach
Desk research of industry association reports, government technology policies, and company annual reports preceded structured interviews with semiconductor engineers, procurement managers at OEMs, R&D directors, and supply chain strategists. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Both bottom-up and top-down triangulation methods were applied to refine market size estimations and forecast projections.
The forecast framework established a baseline by fixing assumptions around macroeconomic stability and current regulatory environments across the analysis window. Segmentation dimensions modeled included component type, technology, application, end-user, and geographic market maturity. Compound annual growth rates were derived through regression analysis and market share projections, incorporating industry-specific forecast inputs such as global 5G rollout schedules and electric vehicle production targets.
Sensitivities concentrate around geopolitical events, rapid technological obsolescence, and significant shifts in international trade policies. Forecasts inherently reflect assumptions about these factors. Material shifts in wide-bandgap semiconductor development or major disruptions to global shipping routes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Intel Motherboards Market
Electronic Components
Fixed Capacitor Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Digital Pulse Mixer Market
Electronic Components
Switch Diode Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Audio DSP Market
Electronic Components
US Supercapacitor Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
SAW Filters Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Capacitor Aluminum Polymer Market