
 Serial Device Servers Market | 2026-2036
Serial Device Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Serial Device Servers Market Analytics
Modular hardware configurations is decoupling legacy serial infrastructure from proprietary vendor ecosystems, forcing buyers to evaluate interoperability before total cost. Moxa leverages its embedded computing heritage to sustain design-win rates in transportation signaling. Digi International anchors its position through edge-software bundling that reduces field-deployment complexity. Advantech competes by extending its industrial motherboard supply chain into rack-mounted gateway assemblies.
Serial device servers translate RS-232, RS-422, and RS-485 electrical signals into TCP/IP or UDP packets, typically operating across -40°C to 75°C industrial temperature ranges with 10/100/1000 Mbps Ethernet uplinks. Ethernet device servers dominate volume shipments due to their compatibility with existing plant-floor cabling infrastructure. Edge Computing deployments within the technology segment represent the fastest-growing configuration as latency-sensitive manufacturing applications displace cloud-reliant architectures. Rack-mounted installations command premium positioning in energy substation and telecommunications central office environments where DIN-rail density drives enclosure standardization.
IEC 62443 industrial cybersecurity standards and FCC Part 15 emissions rules jointly determine product certification timelines and geographic market access eligibility for serial device server manufacturers. ETSI EN 301 489 radio compliance in Europe and China's GB/T 9254 electromagnetic compatibility requirements create divergent testing burdens that favor regionally established suppliers. Stakeholders must monitor how NIST SP 800-82 revision cycles reshape federal procurement specifications for critical infrastructure serial connectivity.
Market Dynamics
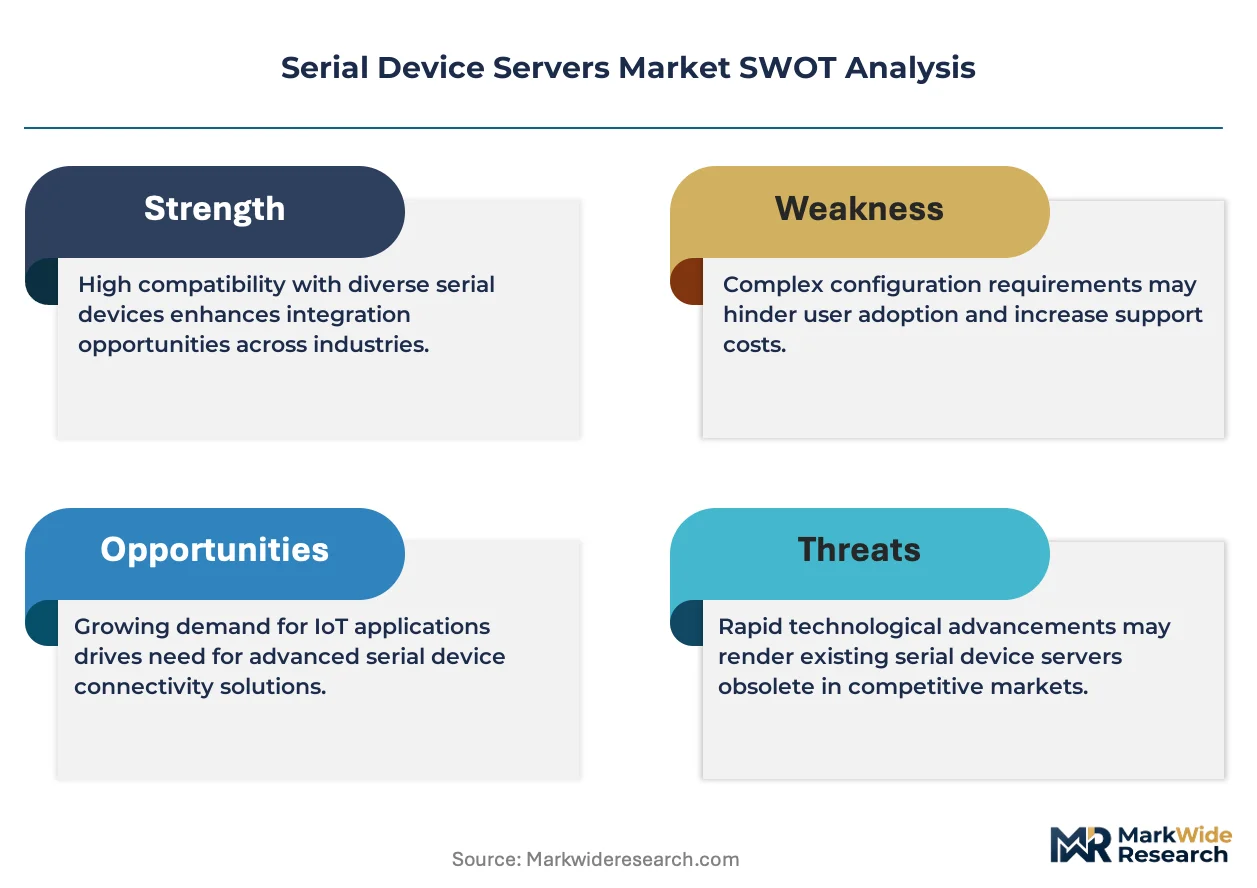
IEC 62443 cybersecurity compliance is restructuring procurement specifications across industrial automation, forcing serial device server vendors to embed security-by-design into hardware architectures rather than retrofitting software patches.
Growth Catalysts
- Edge Computing migration:Latency-sensitive manufacturing applications in automotive assembly lines are pulling compute closer to RS-485 field devices, expanding gateway deployment density.
- Transportation signaling modernization:Railway operators in Germany are replacing legacy copper-based control circuits with IP-enabled serial bridges to support predictive maintenance analytics.
- GB/T 9254 compliance:China's electromagnetic compatibility mandates for industrial equipment are accelerating domestic replacement cycles for non-compliant legacy serial infrastructure.
Market Restraints
- Copper and semiconductor input volatility:Ethernet PHY chips and industrial-grade magnetics face allocation constraints from automotive and telecom demand competition.
- ETSI EN 301 489 testing burden:European radio equipment compliance adds 4-6 month certification timelines that delay product launches for non-regional suppliers.
- Wireless IIoT substitution:Low-power Wi-SUN and LoRaWAN modules are bypassing wired serial connectivity in greenfield facility deployments.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for electronic manufacturing are attracting contract assembly investments for DIN-rail gateway production serving South Asian industrial corridors.
- NIST SP 800-82 revision cycles:Updated federal cybersecurity guidance for critical infrastructure is opening procurement pathways for security-certified serial connectivity in US energy substations.
- Time-Sensitive Networking convergence:IEEE 802.1AS time synchronization layered atop existing Ethernet device servers is creating upgrade revenue from installed base refresh.
Industry Challenges
- Embedded cybersecurity engineering scarcity:Firmware developers with IEC 62443-4-2 secure product development lifecycle expertise command premium compensation and extended hiring timelines.
- Multi-standard certification parallelism:Simultaneous FCC Part 15, CE marking, and GB/T 9254 testing creates resource conflicts in validation laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serial Device Servers Market |
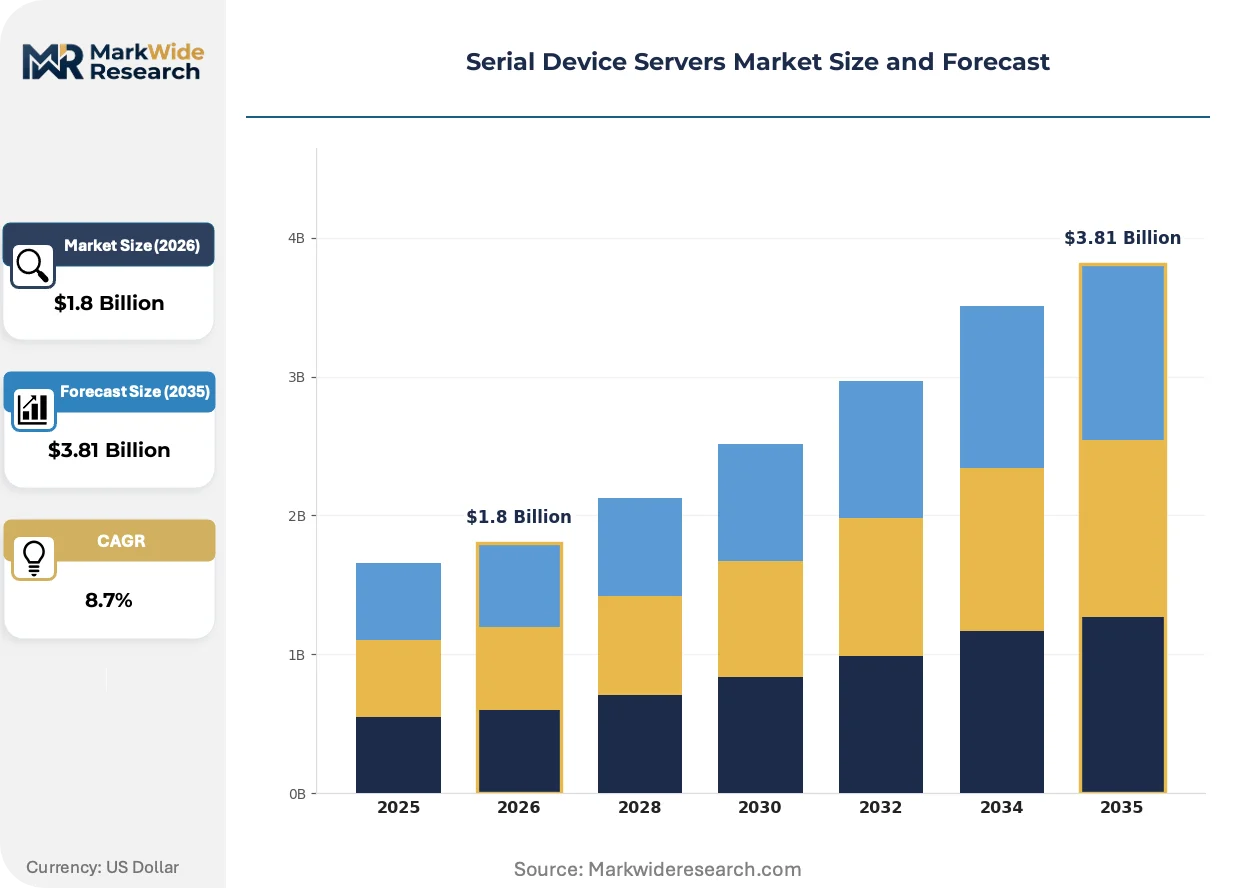
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Device Servers, Ethernet Device Servers, Wireless Device Servers, Serial to Ethernet Converters End User: Manufacturing, Transportation, Telecommunications, Energy Technology: Cloud-based, Edge Computing, IoT-enabled, Legacy Systems Installation: Rack-mounted, Wall-mounted, Portable, Embedded |
| Companies Covered | Moxa, Digi International, Advantech, Perle Systems, Lantronix, Siemens, Westermo, 3onedata, Sealevel Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serial Device Servers Market Evolving Landscape
Hardware abstraction is decoupling serial protocol translation from proprietary silicon, enabling software-defined configuration of physical layer interfaces that previously required dedicated ASICs.
Containerized edge runtime environments are rewriting how serial device servers integrate with higher-level manufacturing execution systems. Automotive OEMs in Stuttgart and Wolfsburg are deploying these microservice-capable gateways to collapse the traditional three-tier automation hierarchy. The compression of middleware layers is eliminating separate protocol converter hardware purchases.
FCC Part 15 Class A emissions rules are tightening enforcement for industrial digital equipment sold into US manufacturing facilities. The Federal Communications Commission's 2023 equipment authorization procedures now mandate third-party testing for all intentional radiators embedded in serial-to-wireless bridges. Energy sector buyers in Texas and California are prioritizing pre-certified modules to avoid site-level compliance failures.
Buyer preference is consolidating around vendors offering unified device management platforms spanning heterogeneous serial, Ethernet, and wireless endpoints. System integrators in Japan and South Korea are displacing single-protocol specialists with platform-agnostic suppliers. METI's Smart Manufacturing promotion subsidies are accelerating this vendor consolidation in Japanese automotive component plants.
Serial Device Servers Market Segmentation
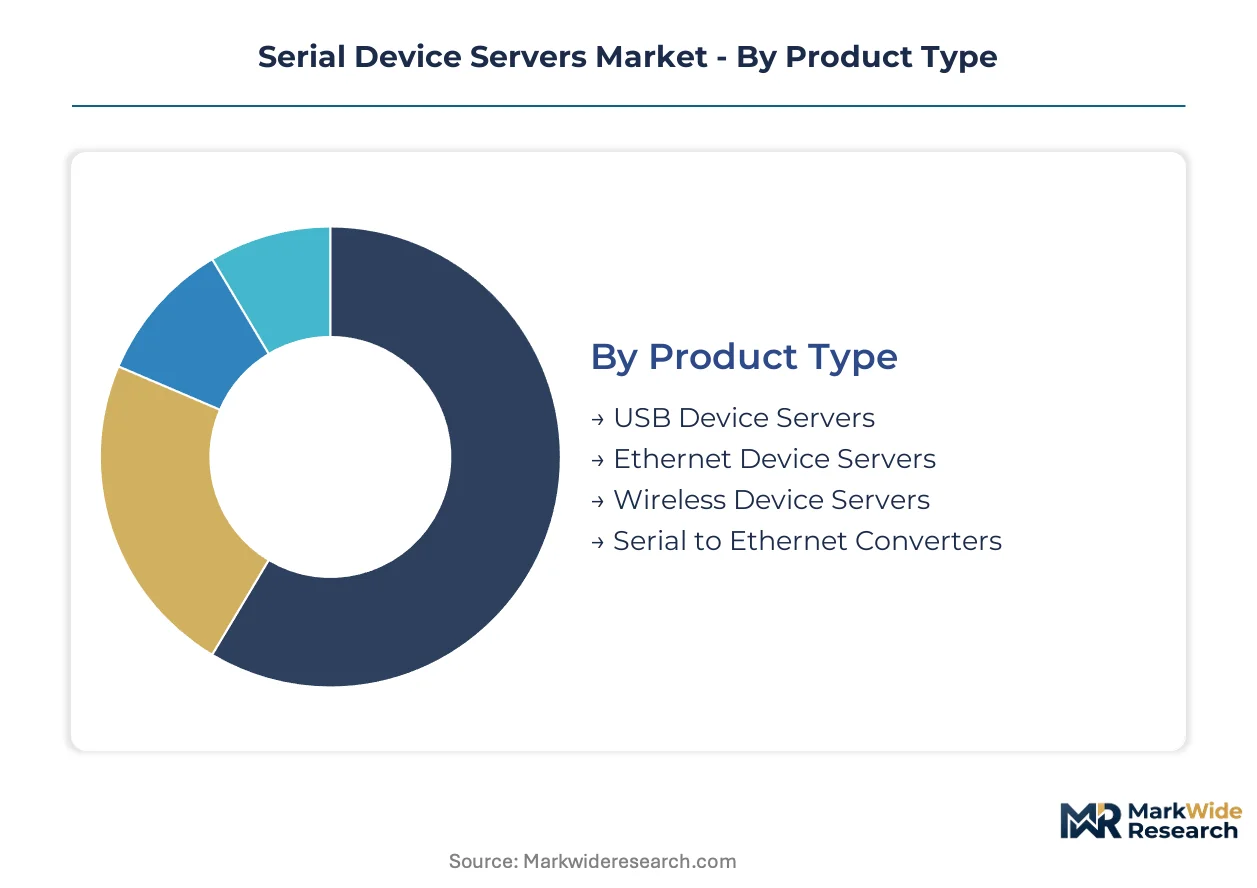
Segmentation in serial device servers reveals how integration depth determines hardware selection criteria. Buyers choosing standalone versus embedded configurations face fundamentally different procurement timelines and certification requirements.
Product Type:
Standalone device servers operate independently with dedicated power and enclosure systems, while embedded variants integrate directly into OEM equipment chassis requiring minimal external infrastructure.
- Ethernet Device Servers:These units translate RS-232/RS-422/RS-485 signals to 10/100/1000 Mbps Ethernet, typically housed in IP30 or IP67 rated enclosures. Demand clusters in Germany's automotive manufacturing corridor where plant-floor cabling infrastructure already supports copper Ethernet backbones. IEC 62443 compliance mandates are accelerating replacement of non-secure legacy units in these facilities.
- Wireless Device Servers:Wi-Fi, cellular, or proprietary radio bridges eliminate copper runs to remote field devices. Transportation signaling modernization across Deutsche Bahn networks is pulling these units into predictive maintenance architectures where trenching new cables proves cost-prohibitive.
- USB Device Servers:Peripheral sharing and remote USB access for industrial instruments. Compact footprint suits laboratory and medical equipment integration.
- Serial to Ethernet Converters:Single-purpose protocol translation without full server functionality. Lowest cost entry point for basic RS-485-to-TCP/IP requirements in building automation.
Volume placements concentrate in Ethernet Device Servers; the faster expansion belongs to Wireless Device Servers.
End User:
End-use segmentation tracks how operational technology maturity shapes connectivity requirements and cybersecurity investment thresholds.
- Manufacturing:Automotive assembly lines in Stuttgart and Wolfsburg deploy edge-capable gateways to collapse three-tier automation hierarchies. Containerized runtime environments here are eliminating separate protocol converter purchases.
- Energy:Substations and renewable generation sites demand rack-mounted units with -40°C to 75°C temperature tolerance. NIST SP 800-82 revision cycles are opening federal procurement pathways for security-certified connectivity in Texas and California grid infrastructure.
- Transportation:Railway and aviation maintenance systems. Copper replacement drives in European rail networks favor IP-enabled serial bridges.
- Telecommunications:Central office equipment monitoring and remote site management. DIN-rail density requirements drive enclosure standardization preferences.
Manufacturing commands the largest installed base; Energy shows the steepest expansion trajectory as critical infrastructure cybersecurity budgets inflate.
Technology:
Technology segmentation distinguishes architectures by where data processing occurs relative to the physical serial interface.
- Edge Computing:Local analytics execution without cloud round-trips. Latency-sensitive automotive assembly applications are pulling compute directly adjacent to RS-485 field devices.
- Cloud-based:Centralized data aggregation and fleet management. Smaller facilities without on-site IT expertise favor this operational simplicity despite bandwidth dependencies.
- IoT-enabled:MQTT and CoAP protocol support for direct platform integration. METI Smart Manufacturing subsidies in Japan are accelerating this configuration in automotive component plants.
- Legacy Systems:Basic TCP/UDP bridging without modern protocol stacks. Sustained demand from facilities with decade-old automation software commitments.
Edge Computing claims the highest unit growth rate; Legacy Systems retain the largest replacement-driven volume.
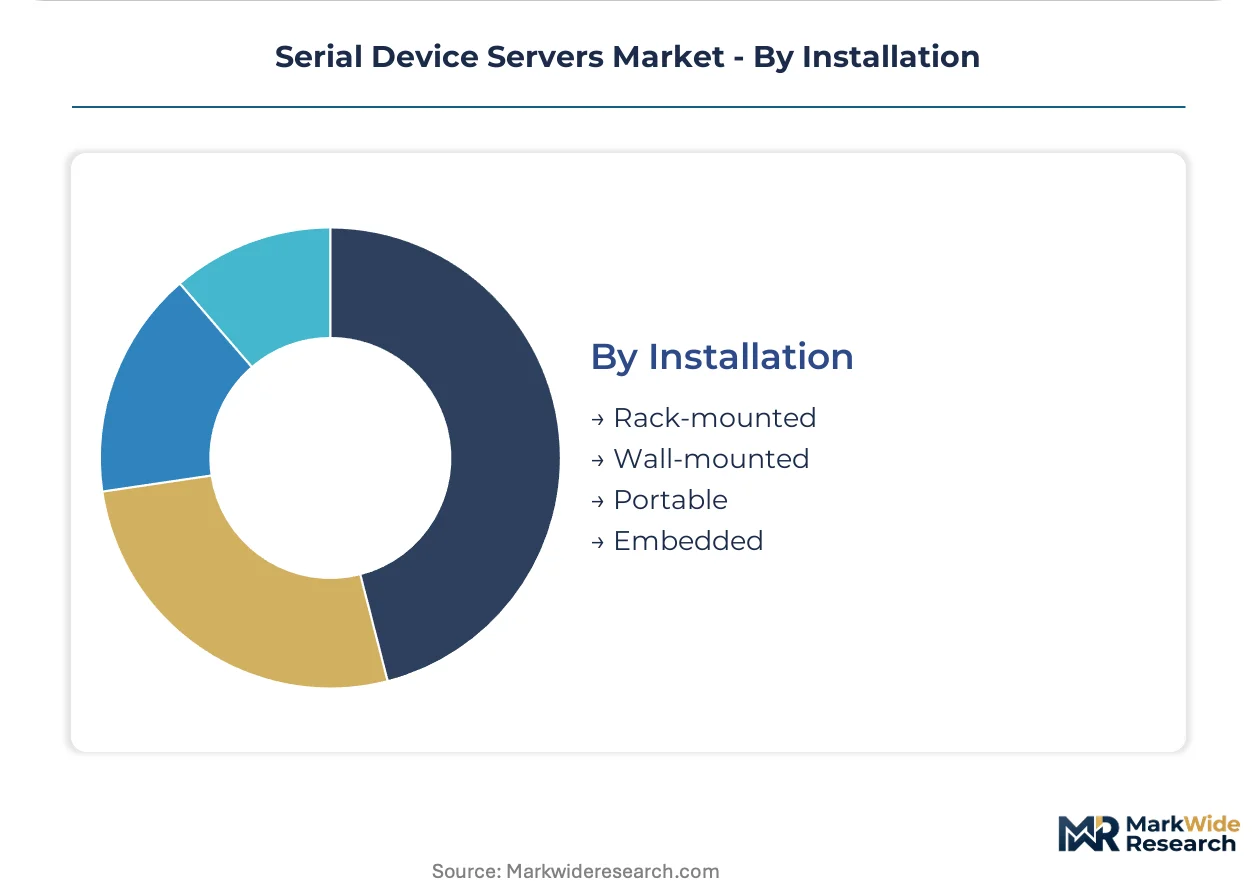
Installation:
Physical mounting configuration determines thermal management, accessibility for maintenance, and electromagnetic shielding specifications.
- Rack-mounted:19-inch standard enclosures for data centers and substation control houses. Premium positioning in energy and telecommunications central offices where equipment density drives standardization.
- Embedded:Board-level integration without separate enclosure. Advantech extends industrial motherboard supply chains into these assemblies for OEM equipment builders.
- DIN-rail:Industrial control panel mounting predominant in factory automation. India's PLI scheme for electronic manufacturing is attracting contract assembly investments for these units.
- Portable:Battery-powered or PoE-fed temporary deployments. Field service and commissioning applications where permanent installation is impractical.
Rack-mounted units dominate premium pricing tiers; Embedded configurations are gaining share fastest as OEMs internalize connectivity functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Germany and China drives production capacity, while consumption distributes across industrial automation corridors in the United States, Japan, and India where legacy serial infrastructure requires systematic replacement.
Germany
Automotive OEMs in Stuttgart and Wolfsburg anchor demand for IEC 62443-compliant Ethernet device servers. The KBA enforces cybersecurity certification timelines that favor pre-qualified suppliers. Siemens and Moxa maintain entrenched positions along the automotive manufacturing corridor where plant-floor cabling infrastructure supports copper Ethernet backbones.
United States
Energy substations in Texas and California require rack-mounted units with -40°C to 75°C temperature tolerance for grid hardening. NIST SP 800-82 revision cycles are opening federal procurement pathways for security-certified serial connectivity. FCC Part 15 Class A emissions enforcement is tightening for industrial digital equipment deployed in manufacturing facilities.
China
GB/T 9254 electromagnetic compatibility mandates are accelerating domestic replacement cycles for non-compliant legacy serial infrastructure. MIIT oversees industrial equipment certification that creates divergent testing burdens favoring regionally established suppliers. Production-linked incentive schemes are attracting contract assembly investments for DIN-rail gateway production serving South Asian industrial corridors.
Japan
METI's Smart Manufacturing promotion subsidies are accelerating vendor consolidation in automotive component plants. System integrators are displacing single-protocol specialists with platform-agnostic suppliers offering unified device management. Kanto and Kansai industrial belts concentrate demand for containerized edge runtime environments that collapse traditional three-tier automation hierarchies.
India
The PLI scheme for electronic manufacturing is attracting contract assembly investments for DIN-rail gateway production. Maharashtra and Gujarat industrial corridors are deploying edge-capable gateways to support latency-sensitive manufacturing applications. BIS certification requirements for industrial equipment are reshaping procurement specifications toward security-by-design hardware architectures.
Serial Device Servers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Industrial automation conglomerates leverage embedded computing heritage and supply chain scale, while communication technology specialists anchor positions through edge-software bundling. Three archetypes dominate: diversified industrial technology conglomerates with broad automation portfolios, communication infrastructure specialists with protocol translation expertise, and embedded computing vendors extending motherboard supply chains into connectivity assemblies. Strategic moves concentrate on cybersecurity certification pre-positioning and regional compliance laboratory partnerships.
Among diversified industrial technology conglomerates, Siemens occupies a position exemplifying the integrated automation platform approach. Moxa and Digi International represent the communication infrastructure specialist archetype, with Moxa leveraging embedded computing heritage and Digi International anchoring through edge-software bundling strategies. Advantech sits within the embedded computing extension archetype, competing by extending industrial motherboard supply chains into rack-mounted gateway assemblies.
| Leading Market Players |
|---|
| Moxa |
| Digi International |
| Advantech |
| Perle Systems |
| Lantronix |
| Siemens |
| Westermo |
| 3onedata |
| Sealevel Systems |
| Others |
Value Network & Pricing Analysis
Copper price volatility on the London Metal Exchange cascades through Ethernet PHY chip procurement into three-tier pricing stratification across IEC 62443-certified, CE-marked, and economy-grade serial device server tiers. Buyers in Germany's automotive corridor absorb premium positioning for pre-certified hardware while budget-constrained facilities in India's emerging industrial belts gravitate toward unbundled converter modules.
Pricing Analysis
Margin tightening in economy-tier units traces to semiconductor allocation competition from automotive and telecom sectors. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62443-4-2 certified hardware with embedded secure boot from basic TCP/UDP bridging modules. Price differentiation hinges on cybersecurity certification grade and after-sales firmware update subscriptions. System integrators in Japan show lowest price sensitivity; small facility operators in India's Gujarat corridor exhibit highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Siemens and Advantech's motherboard supply chain extensions, while distribution partners serve fragmented system integrator demand. Manufacturing concentrates in Taiwan for Ethernet PHY silicon, China for PCB assembly and enclosure fabrication, and Germany for precision magnetics feeding automotive-grade units. Raw material dependencies include industrial-grade copper magnetics, ARM-based embedded processors, and conformal coating chemistries. Single-source vulnerability in automotive-qualified Ethernet PHY chips creates allocation risk. Distribution runs through authorized industrial automation distributors with IEC 62443 technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IEC 62443 compliance costs erect a barrier-to-entry moat favoring incumbents with pre-positioned certification laboratories and embedded cybersecurity engineering teams. New entrants face 12-18 month certification timelines that compress available pricing headroom.
For Market Incumbents: Deepen vertical integration into automotive-qualified Ethernet PHY sourcing to defend against semiconductor allocation competition from telecom and automotive sectors. Fortify regional compliance laboratory partnerships in Germany, China, and the United States to compress multi-standard certification parallelism timelines. Pre-position NIST SP 800-82 revision cycle alignment for federal energy substation procurement pathways. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized DIN-rail gateway contract assembly serving Maharashtra and Gujarat industrial corridors. Target USB device server configurations for laboratory and medical equipment integration where certification burdens remain lighter. Lead with containerized edge runtime bundling to differentiate from legacy TCP/UDP bridging specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor communication infrastructure specialists with embedded computing heritage and pre-qualified IEC 62443-4-2 product lines in Germany and Japan. Long-term viability centers on firmware development teams with secure product development lifecycle expertise. Monitor NIST SP 800-82 procurement specification releases and FCC Part 15 Class A enforcement actions as inflection indicators for security-certified hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443-4-2 Certification Pre-Positioning | Accelerates procurement eligibility in Germany's KBA-regulated automotive corridor. |
| Regional Compliance Laboratory Partnerships | Compresses ETSI EN 301 489 and GB/T 9254 testing timelines for multi-market launches. |
| Containerized Edge Runtime Integration | Eliminates separate protocol converter purchases in Stuttgart and Wolfsburg assembly lines. |
| Automotive-Qualified PHY Chip Supply Agreements | Insulates against allocation constraints from telecom and automotive demand competition. |
| India PLI Scheme Contract Assembly Investment | Captures production-linked incentives for DIN-rail gateway manufacturing serving South Asian corridors. |
Research Methodology
SEC 10-K filings, IEC certification registries, and industrial automation trade customs data formed the secondary backbone for market sizing and competitive positioning validation. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and cybersecurity compliance officers at industrial facilities across Germany, the United States, Japan, China, and India supplied operational technology maturity assessments and procurement specification evolution. Bottom-up unit shipment estimates by product configuration triangulated against top-down automation capital expenditure forecasts.
Historical trendline analysis of Ethernet device server deployment density in automotive assembly lines established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-use vertical, technology architecture, and installation configuration dimensions. CAGRs derived from weighted average of equipment replacement cycle analysis and greenfield facility automation investment trajectories. Forecast inputs included NIST SP 800-82 revision timing, GB/T 9254 enforcement intensity, and METI Smart Manufacturing subsidy allocation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wireless IIoT substitution rates and copper price volatility. Practitioners should monitor FCC Part 15 Class A enforcement actions, ETSI EN 301 489 certification timeline extensions, and Wi-SUN module pricing trajectories for early signals of demand migration away from wired serial connectivity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Power Inductors Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Europe PCB Market
Electronic Components
Fuse Bases Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Electric Fuse Market
Electronic Components
North America Touch Screen Controllers Market