
 Screw Washer Market | 2026-2036
Screw Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Washer Market Analytics
Automotive electrification is decoupling from traditional internal-combustion fastener specifications as battery pack architectures demand lighter, corrosion-resistant hardware. Würth Group leverages its European distribution density to supply OEM assembly plants with just-in-time washer kits. Illinois Tool Works anchors North American demand through specialized coatings that meet salt-spray test protocols for underbody applications. Fastenal controls the maintenance-repair-operations channel with vendor-managed inventory systems at regional fleet service centers.
A screw washer is a thin disk with a central hole, typically manufactured through stamping, progressive die forming, or CNC machining from steel, stainless steel, or polymer substrates, designed to distribute clamping load and prevent fastener loosening under vibration or thermal cycling. Flat washers still occupy the largest volume share across construction and general industrial use, though sealing washers are registering the fastest expansion as fluid containment requirements intensify in automotive transmission and battery cooling modules. Steel dominates material tonnage due to cost efficiency, while stainless steel commands premium positioning in marine, chemical processing, and medical equipment applications where ISO 3506 corrosion standards apply.
The EPA enforces material content restrictions under TSCA for coated washers used in U.S. water infrastructure, while REACH in Europe mandates disclosure of hexavalent chromium and cadmium in surface treatments. China's GB standards through SAMR specify mechanical property classes for structural steel washers deployed in high-rise construction. Stakeholders must monitor evolving building codes in India and Brazil, where BIS and ANVISA respectively are tightening import certification for load-bearing fasteners in public infrastructure projects.
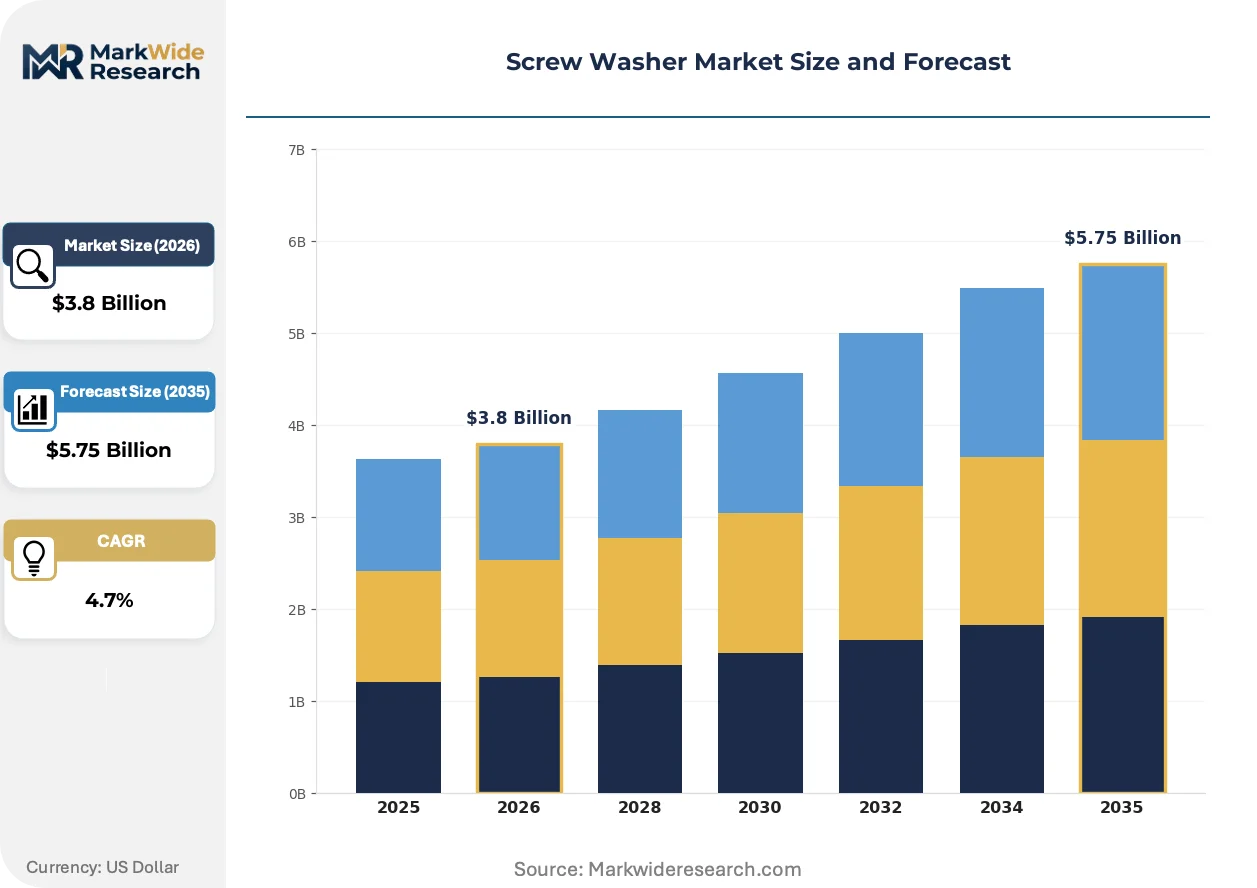
Market Dynamics
Automotive electrification is decoupling fastener specifications from legacy internal-combustion standards, forcing washer manufacturers to engineer lighter, corrosion-resistant hardware for battery pack architectures while aerospace assembly lines in Germany and the United States simultaneously expand fastener consumption per airframe.
Growth Catalysts
- REACH compliance tightening:ECHA mandates on hexavalent chromium and cadmium disclosure in surface treatments are accelerating demand for compliant coating alternatives across European industrial supply chains.
- East Asian manufacturing concentration:Production clusters around Shanghai and Guangzhou are consolidating procurement volumes, creating scale efficiencies for precision-stamped washer suppliers serving export-oriented assembly plants.
- Battery cooling module expansion:Sealing washer demand is intensifying as fluid containment requirements multiply across automotive transmission and EV thermal management systems.
Market Restraints
- Steel input cost volatility:Cold-rolled steel price fluctuations compress margin stability for high-volume stamped washer producers serving construction and general industrial segments.
- Supply concentration in East Asia:Progressive die forming capacity clusters heavily in Chinese manufacturing zones, exposing buyers to logistics disruption risks and trade policy friction.
- Polymer substitution ceiling:Load-bearing limitations of polymer substrates prevent full displacement of metal washers in structural applications despite weight advantages.
Strategic Opportunities
- Indian infrastructure buildout:BIS certification tightening for load-bearing fasteners in public projects creates first-mover advantage for compliant suppliers establishing local production or partnerships.
- Medical equipment corrosion standards:ISO 3506 compliance requirements in stainless steel washers open premium positioning for specialized coating and material qualification capabilities.
- Just-in-time kit consolidation:Vendor-managed inventory integration with OEM assembly plants allows washer suppliers to capture higher-margin kit assembly and logistics services.
Industry Challenges
- Coating qualification timelines:Salt-spray test protocol validation for underbody automotive applications extends product development cycles and delays revenue recognition.
- Multi-jurisdiction compliance stacking:Simultaneous EPA TSCA, REACH, and SAMR GB standard adherence strains quality assurance resources and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Washer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Washers, Lock Washers, Sealing Washers, Belleville Washers Material: Steel, Stainless Steel, Aluminum, Plastic Application: Construction, Automotive, Electronics, Aerospace Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Würth Group, Illinois Tool Works, Stanley Black & Decker, SFS Group, Fastenal, Precision Castparts Corp, Hilti, PennEngineering, Bossard Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Washer Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape washer manufacturing processes, with coating technologies and substrate alloys undergoing rapid specification evolution across automotive, aerospace, and medical end-uses.
Polymer-ceramic composite coatings are absorbing the functional requirements previously met by hexavalent chromium surface treatments, delivering comparable corrosion resistance without REACH-prohibited chemistry. Tier-1 automotive suppliers in Germany and the United States are qualifying these alternatives at accelerated pace for underbody and battery enclosure applications. The transition is compressing traditional electroplating equipment utilization rates while expanding capital deployment into spray deposition and PVD process lines.
EPA enforcement of TSCA material content restrictions for coated washers deployed in U.S. water infrastructure is tightening supply chain documentation requirements. Manufacturers must now maintain batch-level chemical disclosure records traceable through distribution channels. Municipal procurement specifications in California and Texas are increasingly referencing these EPA protocols, creating compliance-driven supplier selection criteria that favor domestic coating operations with established environmental management systems.
Fleet service centers are consolidating maintenance-repair-operations purchasing through integrated supply agreements that bundle fasteners with predictive inventory replenishment. This pattern displaces spot-buying from traditional distribution branches across North American commercial vehicle and agricultural equipment sectors. The shift is most visible in Midwestern U.S. states where regional fleet operators are centralizing procurement authority and demanding vendor-managed stock rotation at repair facilities.
Screw Washer Market Segmentation
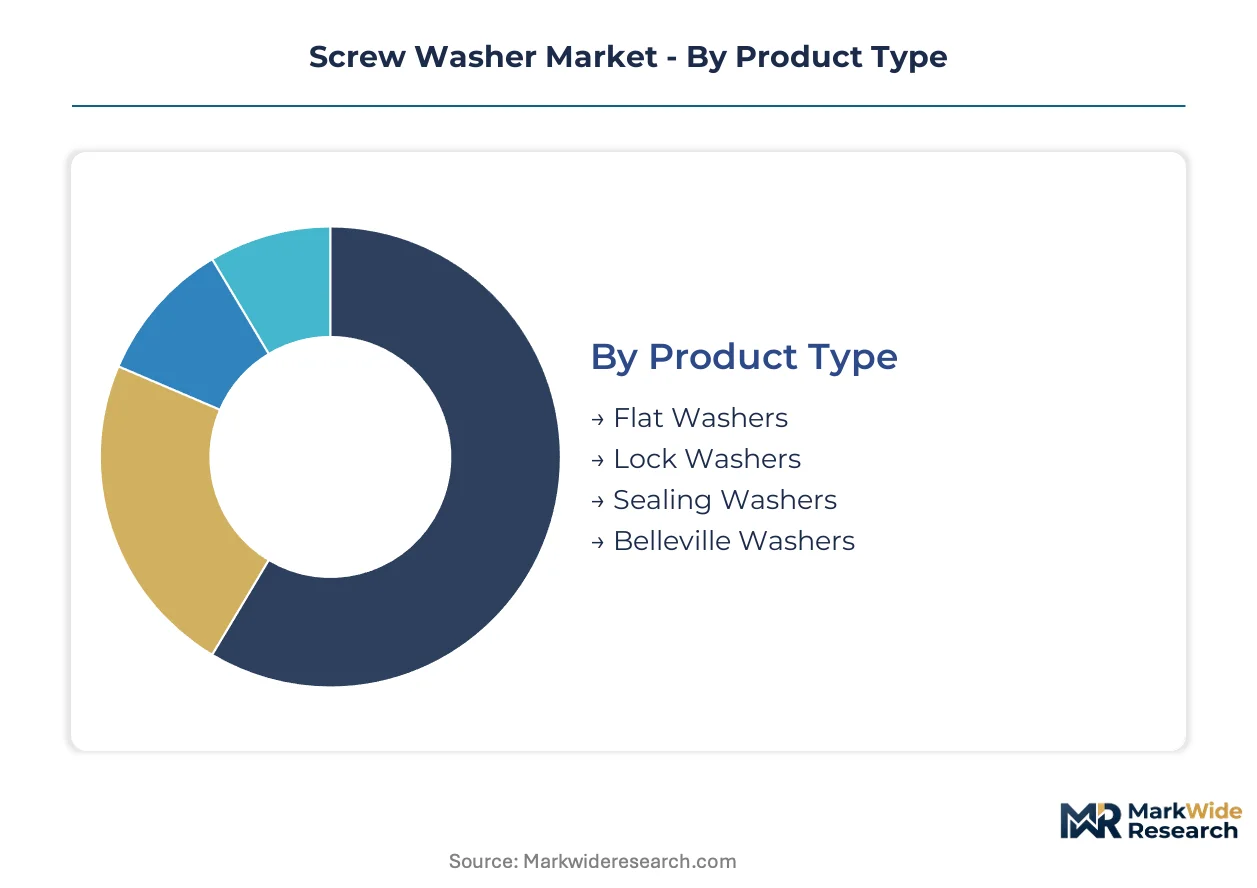
Washer specification varies sharply by integration depth: standalone fasteners in construction tolerate commodity grades, while embedded systems in aerospace and EV battery packs demand certified, traceable components with documented coating chemistry. Segmentation reveals where margin concentrates versus where volume commoditizes.
Product Type:
Integration depth separates commodity construction hardware from precision-embedded systems requiring traceable metallurgy and validated corrosion resistance.
- Flat Washers:Stamped carbon steel disks distribute clamping loads across general industrial and structural applications. Construction sites in India and Brazil absorb the highest volumes as infrastructure buildouts accelerate, though margin compression from steel price volatility limits supplier profitability in this tier.
- Sealing Washers:Elastomer-bonded or polymer-composite designs integrate fluid containment with mechanical fastening for thermal management systems. Battery cooling modules in German and U.S. automotive assembly plants are qualifying these at accelerated pace as electrification multiplies fluid sealing points per vehicle.
- Lock Washers:Split-ring or tooth-profile designs prevent fastener loosening under vibration through mechanical interference rather than friction alone.
- Belleville Washers:Conical spring washers maintain preload in bolted joints subject to thermal cycling, common in steam turbines and pressure vessel flanges.
Flat washers lead volumes today; sealing washers are gaining share fastest.
Material:
Cost tier stratification runs from commodity carbon grades through corrosion-resistant alloys to lightweight engineered substrates.
- Steel:Cold-rolled and hardened carbon grades dominate tonnage through cost efficiency in construction and general machinery. Shanghai and Guangzhou manufacturing clusters supply global demand from concentrated progressive die capacity, though REACH and EPA TSCA compliance costs are eroding margin advantage for coated variants.
- Stainless Steel:Austenitic and duplex grades command premium positioning where ISO 3506 corrosion standards apply. Medical equipment manufacturers in Germany and marine hardware fabricators in Japan specify these for salt-spray resistance and sterilization compatibility, with qualification timelines extending procurement cycles.
- Aluminum:Lightweight alloys serve aerospace weight-reduction targets and certain electronics thermal management applications.
- Plastic:Nylon and PEEK substrates eliminate galvanic corrosion in battery enclosures and reduce mass in consumer electronics assemblies.
Steel leads volumes today; stainless steel climbs the fastest on specification upgrading.
Application:
End-use maturity determines whether procurement prioritizes lowest unit cost or technical qualification depth.
- Automotive:Electrification is decoupling fastener specifications from legacy internal-combustion standards. Battery pack architectures demand lighter, corrosion-resistant hardware with documented coating chemistry for underbody and enclosure applications, extending development cycles but expanding per-vehicle washer counts.
- Construction:Structural steel assemblies in high-rise buildings and infrastructure projects specify load-bearing washers under China's GB standards and India's tightening BIS certification. Volume concentration here drives procurement scale but squeezes margin through competitive bidding.
- Aerospace:Airframe assembly lines in Germany and the United States expand fastener consumption per aircraft while tightening material traceability requirements.
- Electronics:Miniaturization and thermal management drive demand for precision-stamped micro-washers in server racks and telecommunications equipment.
Construction leads volumes today; automotive is expanding most quickly on electrification-driven specification change.
Distribution Channel:
Customer type and order pattern determine whether procurement flows through integrated supply agreements or fragmented spot purchasing.
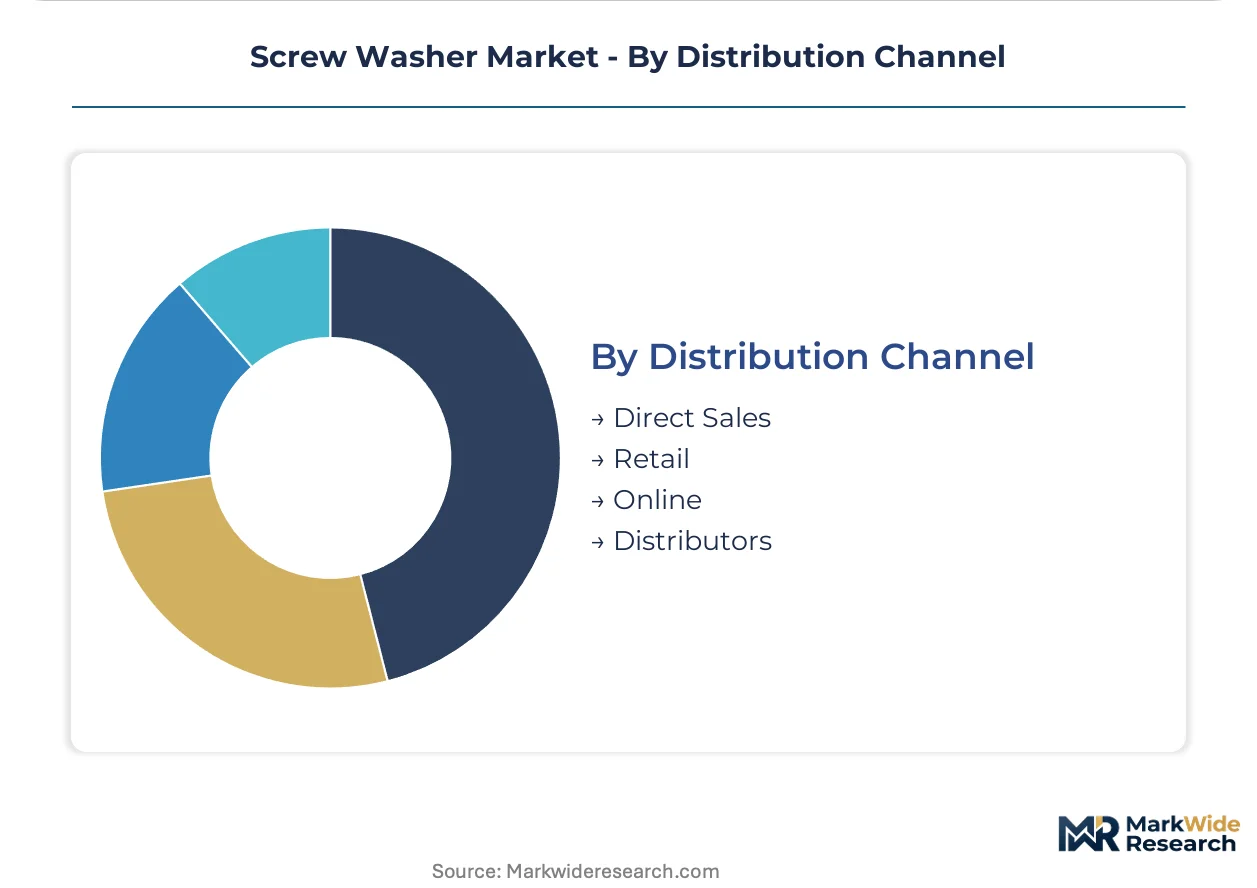
- Distributors:Industrial distributors with vendor-managed inventory systems capture maintenance-repair-operations demand from regional fleet service centers. Fastenal and Würth Group leverage density in North America and Europe respectively to supply OEM assembly plants with just-in-time washer kits, bundling fasteners with predictive replenishment.
- Direct Sales:Tier-1 automotive and aerospace suppliers negotiate multi-year supply agreements with qualified manufacturers, bypassing distribution markup for high-volume, specification-critical components.
- Retail:Hardware stores and trade counters serve small contractors and DIY consumers with pre-packaged assortments.
- Online:E-commerce platforms aggregate长尾 demand from remote maintenance facilities and small fabricators.
Distributors lead volumes today; direct sales is gaining share fastest on OEM consolidation of procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing washer production capacity toward jurisdictions with lower compliance burdens, even as end-use demand concentrates in developed markets with stringent coating chemistry mandates.
United States
Aerospace assembly lines in Washington State and South Carolina expand fastener consumption per airframe while battery pack architectures for EVs multiply washer counts per vehicle. EPA enforces TSCA material content restrictions for coated washers deployed in water infrastructure, tightening supply chain documentation requirements. Fleet service centers across the Midwest are consolidating maintenance-repair-operations purchasing through vendor-managed inventory systems.
Germany
Tier-1 automotive suppliers qualify polymer-ceramic composite coatings at accelerated pace for underbody and battery enclosure applications. ECHA mandates on hexavalent chromium and cadmium disclosure in surface treatments accelerate demand for compliant coating alternatives. Precision-stamped washer suppliers cluster around Stuttgart and Munich to serve export-oriented assembly plants with just-in-time logistics.
China
Progressive die forming capacity concentrates heavily in manufacturing zones around Shanghai and Guangzhou, creating scale efficiencies for precision-stamped washers. SAMR GB standards specify mechanical property classes for structural steel washers deployed in high-rise construction. Cold-rolled steel price fluctuations compress margin stability for high-volume stamped washer producers serving domestic and export markets.
India
Infrastructure buildouts accelerate structural steel assembly demand across high-rise buildings and public works projects. BIS certification tightening for load-bearing fasteners in public infrastructure creates first-mover advantage for compliant suppliers establishing local production. Construction sites in Maharashtra and Gujarat absorb the highest washer volumes as urbanization intensifies.
Japan
Marine hardware fabricators specify stainless steel grades for salt-spray resistance in coastal and shipbuilding applications. ISO 3506 corrosion standards extend procurement cycles for medical equipment manufacturers requiring sterilization compatibility. Industrial clusters in Osaka and Nagoya specialize in precision micro-washers for electronics thermal management and telecommunications equipment.
Screw Washer Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers deploy spray deposition and PVD process lines to replace traditional electroplating equipment. The vendor base stratifies across three tiers: integrated distribution conglomerates with logistics density, specialized coating houses with environmental management systems, and commodity stampers serving construction spot markets. Strategic archetypes include just-in-time kit consolidators, REACH-compliant surface treatment specialists, and scale-driven progressive die operators. Geographic expansion and portfolio diversification represent the dominant competitive moves as players establish local production in India and qualify alternative chemistries for European automotive supply chains.
Among European-integrated conglomerates, Würth Group leverages distribution density to supply OEM assembly plants with bundled fastener logistics. Illinois Tool Works anchors North American positioning through specialized coating capabilities. Fastenal occupies the maintenance-repair-operations channel with predictive inventory systems at regional fleet facilities. These three exemplify how scale, specialization, and service integration separate competitive tiers in a market where procurement authority is consolidating toward integrated supply agreements.
| Leading Market Players |
|---|
| Würth Group |
| Illinois Tool Works |
| Stanley Black & Decker |
| SFS Group |
| Fastenal |
| Precision Castparts Corp |
| Hilti |
| PennEngineering |
| Bossard Group |
| Others |
Value Network & Pricing Analysis
Automotive OEM consolidation of procurement authority toward direct supply agreements is compressing distributor margins while forcing washer manufacturers to absorb coating qualification costs. This demand-side restructuring fragments pricing power across channel tiers and accelerates margin divergence between specification-critical and commodity-grade suppliers.
Pricing Analysis
Distributor markups of 15-25 percent on standard-grade washers are eroding as fleet operators and OEMs consolidate purchasing through vendor-managed inventory contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant coated variants from commodity carbon steel and import-grade alternatives. Price compression runs through the construction segment due to competitive bidding on public infrastructure projects in India and Brazil. Tier-1 automotive buyers show lowest price sensitivity, prioritizing salt-spray validation and batch traceability over unit cost.
Supply Chain Analysis
Container freight rate volatility from Shanghai and Guangzhou to European and North American ports is destabilizing landed cost calculations for precision-stamped washers. Supply concentrates in China, Germany, and the United States, with progressive die forming capacity anchored in East Asian manufacturing zones. Cold-rolled steel, elastomer bonding compounds, and polymer-ceramic coating precursors constitute critical input dependencies. Single-source vulnerability persists around hexavalent chromium alternative chemistries qualified for REACH compliance. Distribution runs through integrated industrial distributors with logistics density in regional manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH disclosure mandates on coating chemistry and EPA TSCA enforcement for water infrastructure are structurally elevating compliance costs and reshaping supplier selection criteria.
For Market Incumbents: Hedge coating technology obsolescence by accelerating polymer-ceramic composite qualification and securing dual-source raw material agreements for chromium-free surface treatments. Backward integration into spray deposition equipment ownership defends margin position against electroplating capacity stranded by chemistry restrictions. For New Entrants and Emerging Players: Industrial distributors with vendor-managed inventory capabilities offer the most penetrable channel wedge for qualified washer kit suppliers seeking OEM assembly plant access. Target the Indian infrastructure buildout where BIS certification tightening creates compliance barriers for unqualified imports. Pursue qualification partnerships with German Tier-1 automotive suppliers seeking localized coating alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating houses possessing environmental management systems and REACH-compliant process lines. Long-term viability favors suppliers with demonstrated qualification timelines under ISO 3506 and salt-spray protocols. Watch for accelerated OEM consolidation of procurement authority as the inflection signal for channel margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Transition | Polymer-ceramic composite qualification displaces hexavalent chromium electroplating lines across German automotive supply chains. |
| Regional Manufacturing Footprint | Local production in Maharashtra and Gujarat captures Indian infrastructure procurement requiring BIS-certified load-bearing fasteners. |
| Vendor-Managed Inventory Integration | Predictive replenishment systems at Midwestern U.S. fleet service centers displace spot-buying from traditional distribution branches. |
| Certification Investment | ISO 3506 compliance for stainless steel washers opens premium positioning in Japanese marine and German medical equipment applications. |
| Raw Material Security | Dual-source agreements for cold-rolled steel and coating precursors mitigate margin volatility from input cost fluctuations. |
Research Methodology
Multiple input streams — procurement director interviews at Tier-1 automotive suppliers, regulatory compliance officer discussions, and distributor inventory system audits — were reconciled against customs trade data, SAMR GB standard filings, and SEC 10-K disclosures from industrial conglomerates. Primary fieldwork engaged fastener procurement leads at OEM assembly plants, coating technology R&D directors, and fleet maintenance operations managers. Secondary validation drew from ECHA REACH substance databases, EPA TSCA enforcement records, and BIS certification registries. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to constrain volume and value outputs.
Historical shipment patterns were cross-referenced against panel input from industry participants to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product type integration depth, material corrosion grade, end-use specification intensity, and channel procurement pattern. CAGRs were derived from slope analysis of normalized growth trajectories. Industry-specific forecast inputs incorporated battery cooling module washer counts per vehicle and airframe fastener consumption trends from German and U.S. aerospace assembly lines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility, trade policy friction affecting East Asian supply clusters, and regulatory acceleration of coating chemistry prohibitions. Forecasts reflect documented assumptions about OEM procurement consolidation velocity and qualification timeline compression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electric Capacitor Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Capacitor Kits Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Global Suction Tube Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Flexible Heater Market
Electronic Components
Serial Device Servers Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Automation Component Market
Electronic Components
RAID Controller Card Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Switch Diode Market