
 Total Artificial Heart Market | 2026-2036
Total Artificial Heart Market Size, Share, and Industry Trends Forecast 2026-2036
Total Artificial Heart Market Outlook
Remote patient monitoring subscriptions is realigning commercial models in the total artificial heart space. SynCardia Systems, LLC leverages its pneumatic driver platform to sustain long-term outpatient management programs. CARMAT differentiates through its bioprosthetic approach with embedded electronic control and sensor arrays. Abbott anchors North American market presence through established cardiac surgery channel relationships.
A total artificial heart replaces both native ventricles with a prosthetic pump system, typically employing biocompatible polymers, biological tissues, or electromechanical actuators to maintain systemic and pulmonary circulation without relying on the patient's own cardiac muscle. The device serves as a bridge to transplantation or destination therapy for end-stage biventricular failure. Mechanical heart configurations currently dominate installed base volumes due to longer commercial availability and established surgical protocols, while bioprosthetic heart designs represent the fastest-expanding segment as transcutaneous energy transfer and autoregulation algorithms mature. Electronic control technology commands premium positioning as software-defined perfusion management enables real-time cardiac output optimization.
FDA breakthrough device designation and EU MDR conformity assessment shape product development timelines and market access trajectories for manufacturers targeting the United States and European Union. ISO 14708 active implantable medical device standards establish baseline electrical safety and biocompatibility requirements that influence design architecture decisions. Stakeholders must monitor evolving reimbursement frameworks for destination therapy indications as health technology assessment bodies in France, Germany, and the United States evaluate cost-effectiveness thresholds for permanent implantation versus repeated hospitalization cycles.
Market Dynamics
Bioprosthetic materials science is rewriting competitive positioning in total artificial heart development, as transcutaneous energy transfer eliminates percutaneous driveline infection pathways that have constrained mechanical systems for decades.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress clinical validation timelines from typical PMA cycles, enabling earlier revenue recognition for novel bioprosthetic platforms.
- German Cardiac Surgery Clusters:Concentrated referral networks in Berlin, Munich, and Hamburg generate sufficient implant volumes to justify dedicated TAH surgical teams and specialized post-operative care infrastructure.
- Transcutaneous Power Transfer:Elimination of transcutaneous drivelines reduces sepsis rates and enables outpatient destination therapy programs previously limited to bridge-to-transplant indications.
Market Restraints
- Biocompatible Polymer Supply Concentration:Medical-grade polyurethane and silicone sourcing concentrates among three specialty chemical suppliers, exposing manufacturers to input cost volatility and qualification delays.
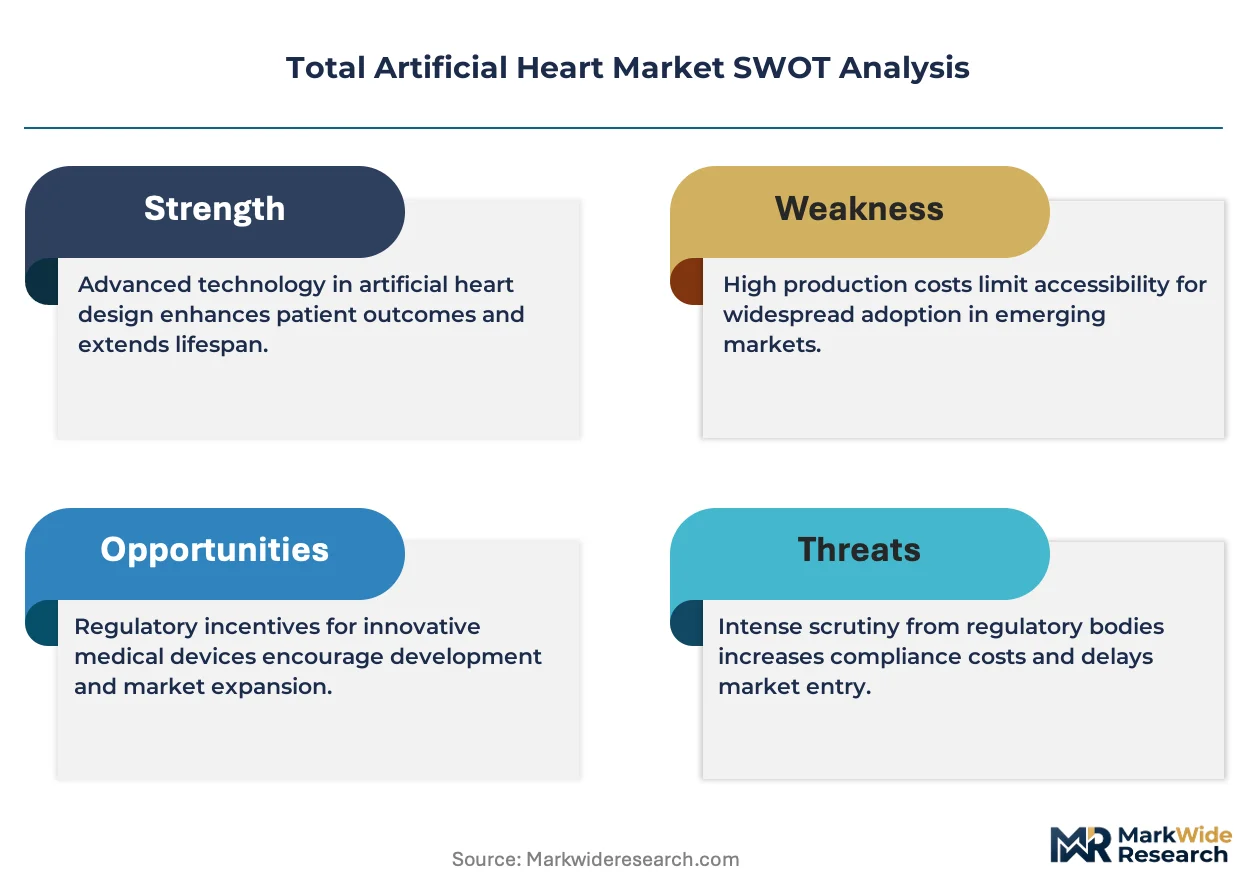
- EU MDR Conformity Assessment:Extended notified body capacity constraints and clinical evidence requirements for active implantable devices extend time-to-market by 18-36 months versus previous MDD pathways.
- Ventricular Assist Device Substitution:Established LVAD programs with shorter learning curves and lower per-procedure costs capture biventricular failure patients who might otherwise proceed to TAH implantation.
Strategic Opportunities
- Japan Destination Therapy Expansion:PMDA reimbursement framework evolution for permanent mechanical circulatory support creates first-mover advantage for bioprosthetic systems with demonstrated durability data.
- Remote Patient Monitoring Integration:Continuous hemodynamic telemetry and predictive algorithms enable proactive intervention, reducing emergency readmissions and supporting value-based contracting with US payers.
- Sensor-Embedded Bioprosthetic Convergence:Integration of MEMS pressure sensors with biological tissue engineering enables real-time autoregulation without external console dependency.
Industry Challenges
- Cardiac Surgeon Training Pipeline:Steep learning curves for biventricular excision and TAH implantation limit qualified surgical centers, constraining addressable patient volume regardless of device availability.
- ISO 14708-2 Active Implantable Compliance:Electromagnetic compatibility and electrical safety validation requirements demand specialized testing infrastructure that extends development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Artificial Heart Market |
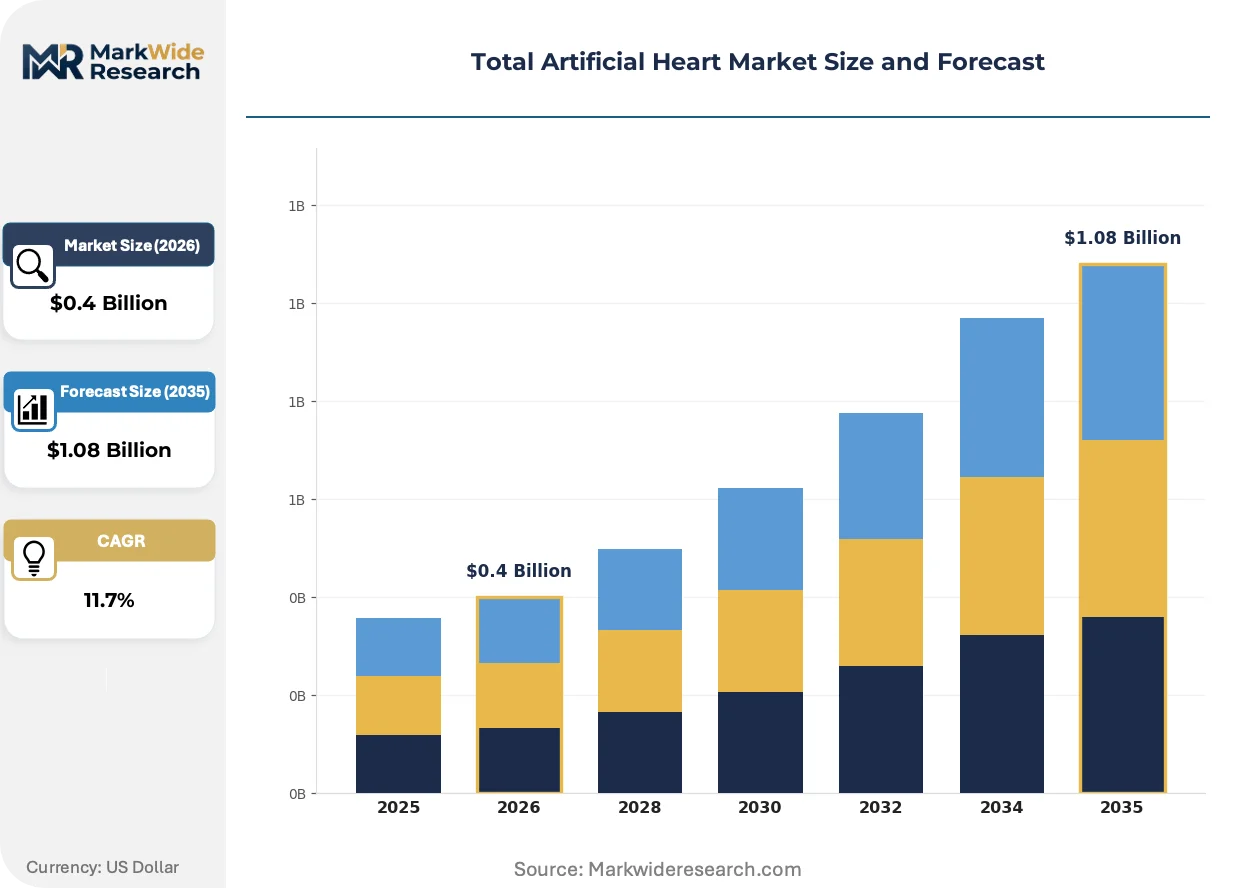
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Heart, Bioprosthetic Heart, Wearable Heart, Electrical Heart End User: Hospitals, Clinics, Surgical Centers, Specialty Care Facilities Application: Cardiac Surgery, Heart Transplant, Ventricular Assist, Emergency Cardiovascular Technology: Robotic Surgery, Hydraulic Systems, Pneumatic Systems, Electronic Control |
| Companies Covered | Jarvik Heart, Inc., Berlin Heart, SynCardia Systems, LLC, LivaNova PLC, Abbott, CARMAT, RealHeart, Getinge, BiVACOR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Artificial Heart Market Strategic Shifts
Software-defined perfusion management is displacing fixed-rate pneumatic driving systems, enabling real-time cardiac output optimization that adapts to patient activity levels and metabolic demand.
Bioprosthetic tissue engineering is rewriting long-term anticoagulation requirements for total artificial heart recipients. CARMAT's biological membrane approach reduces thromboembolic risk compared to polymer blood-contacting surfaces. Transplant centers in France and Germany are prioritizing these platforms for destination therapy candidates with contraindications to lifelong warfarin therapy.
FDA's breakthrough device designation pathway is compressing regulatory timelines for novel TAH platforms while maintaining safety standards. The program enables rolling review of modular clinical evidence packages. Bioprosthetic manufacturers with embedded sensor arrays are leveraging this pathway to reach US commercialization ahead of traditional PMA timelines.
Hospital procurement committees are consolidating mechanical circulatory support vendor relationships to capture volume discounts and streamline training protocols. Single-source contracting for TAH, ECMO, and temporary VAD platforms is displacing multi-vendor purchasing. Academic medical centers in the United States are leading this consolidation, negotiating multi-year agreements that bundle device supply with remote monitoring services.
Total Artificial Heart Market Segmentation
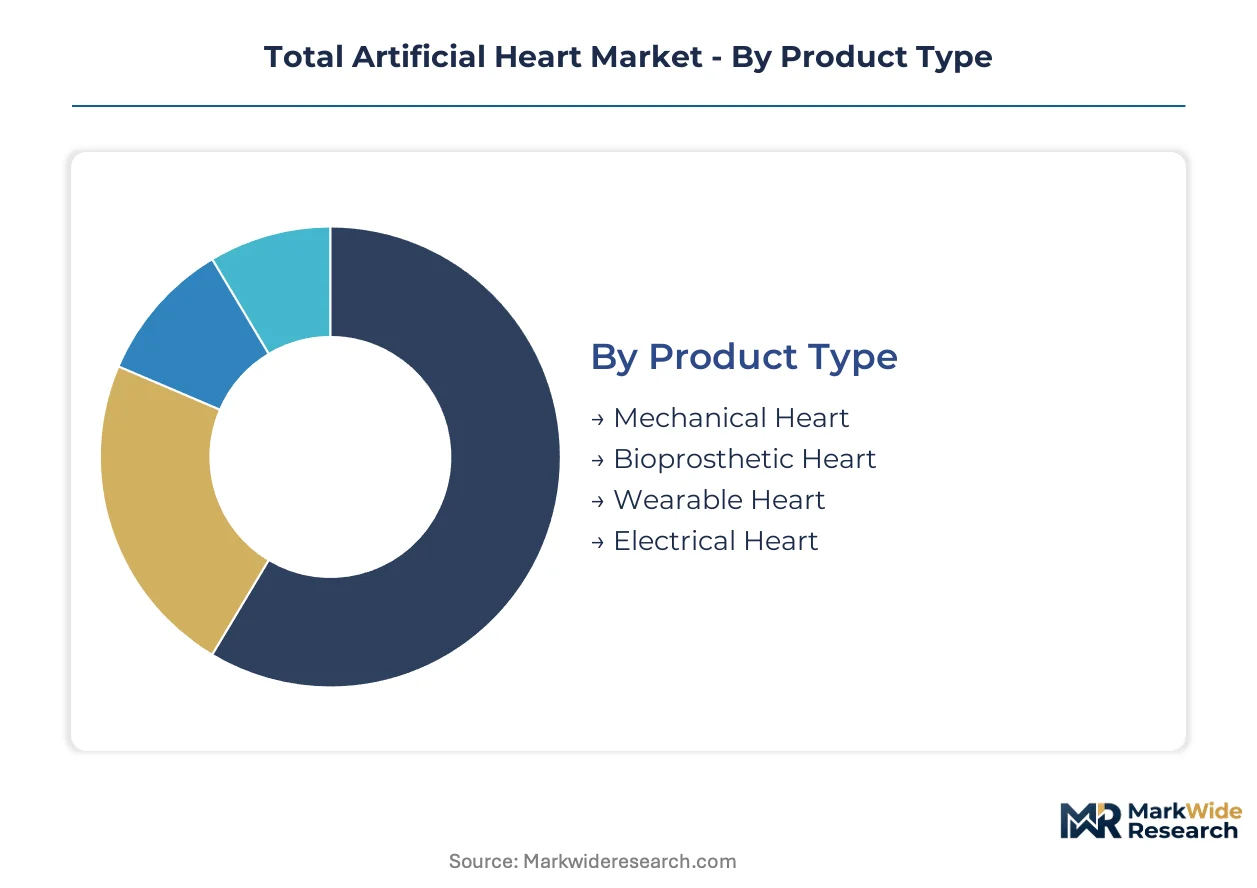
Segmentation in the total artificial heart market reveals distinct procurement patterns across product architectures and care settings. Hospital purchasing committees evaluate durability profiles against surgical complexity when selecting device categories. Technology choices determine reimbursement pathways and long-term patient management economics.
Product Type:
Standardization dominates mechanical configurations while bioprosthetic platforms demand customized surgical protocols and post-operative monitoring infrastructure.
- Mechanical Heart:Polymer and metallic blood-contacting surfaces deliver proven durability in bridge-to-transplant scenarios. German transplant centers in Berlin and Hamburg maintain the highest implant volumes for this category due to established surgical training pipelines and dedicated TAH teams. Fixed-rate pneumatic drivers limit outpatient mobility but reduce system complexity.
- Bioprosthetic Heart:Biological tissue membranes with embedded sensor arrays enable autoregulated blood flow without external console dependency. French and German cardiac surgery clusters prioritize these systems for destination therapy candidates with anticoagulation contraindications. Transcutaneous energy transfer eliminates percutaneous driveline infection pathways.
- Wearable Heart:Portable driver systems enable outpatient mobility for stable bridge-to-transplant patients.
- Electrical Heart:Fully implantable electromechanical actuators with transcutaneous power transfer represent emerging configurations.
Most installed capacity flows through Mechanical Heart configurations. Expansion is steepest in Bioprosthetic Heart platforms.
End User:
Cost tier stratification separates high-volume academic centers from specialized outpatient facilities with limited surgical capabilities.
- Hospitals:Academic medical centers with cardiac surgery residency programs generate sufficient implant volumes to justify dedicated TAH teams and specialized post-operative care infrastructure. These institutions negotiate multi-year procurement agreements bundling device supply with remote monitoring services. FDA breakthrough device designation pathways accelerate technology adoption at these sites.
- Surgical Centers:Focused cardiac surgery facilities concentrate expertise and achieve shorter learning curves for biventricular excision procedures. German clusters in Munich and Hamburg demonstrate how concentrated referral networks justify specialized infrastructure investment.
- Clinics:Outpatient management sites handle stable TAH patients with wearable driver systems.
- Specialty Care Facilities:Long-term rehabilitation centers manage destination therapy patients with remote monitoring support.
Revenue concentration sits with Hospitals. Patient volume growth is climbing fastest at Surgical Centers.
Application:
Application maturity spans decades-old bridge protocols to emerging destination therapy frameworks with evolving reimbursement structures.
- Heart Transplant:Bridge-to-transplant indications dominate current utilization with established reimbursement codes and surgical protocols. United States transplant centers expanding mechanical circulatory support programs drive referral volume concentration. Time-limited support until donor organ availability shapes device durability requirements.
- Cardiac Surgery:Intraoperative support and post-surgical recovery applications leverage TAH technology when ventricular assist devices prove insufficient for biventricular failure.
- Ventricular Assist:Temporary biventricular support scenarios where LVAD substitution is clinically inadequate.
- Emergency Cardiovascular:Acute resuscitation applications requiring rapid deployment capabilities.
Procedure volume centers on Heart Transplant applications. Regulatory momentum is building fastest for destination therapy expansion.
Technology:
Technology generations separate pneumatic legacy systems from software-defined platforms with embedded sensor arrays and predictive algorithms.
- Electronic Control:Software-defined perfusion management enables real-time cardiac output optimization adapting to patient activity levels and metabolic demand. Embedded sensor arrays with MEMS pressure transducers support autonomous regulation without external console dependency. ISO 14708 active implantable medical device standards establish electrical safety and electromagnetic compatibility requirements that shape design architecture decisions.
- Pneumatic Systems:Compressed air-driven diaphragm pumps deliver proven reliability with simpler maintenance protocols. SynCardia's driver platform sustains long-term outpatient management programs through established clinical validation.
- Robotic Surgery:Computer-assisted implantation systems reduce surgical variability in biventricular excision procedures.
- Hydraulic Systems:Fluid-driven actuation mechanisms offer alternative power transmission approaches.
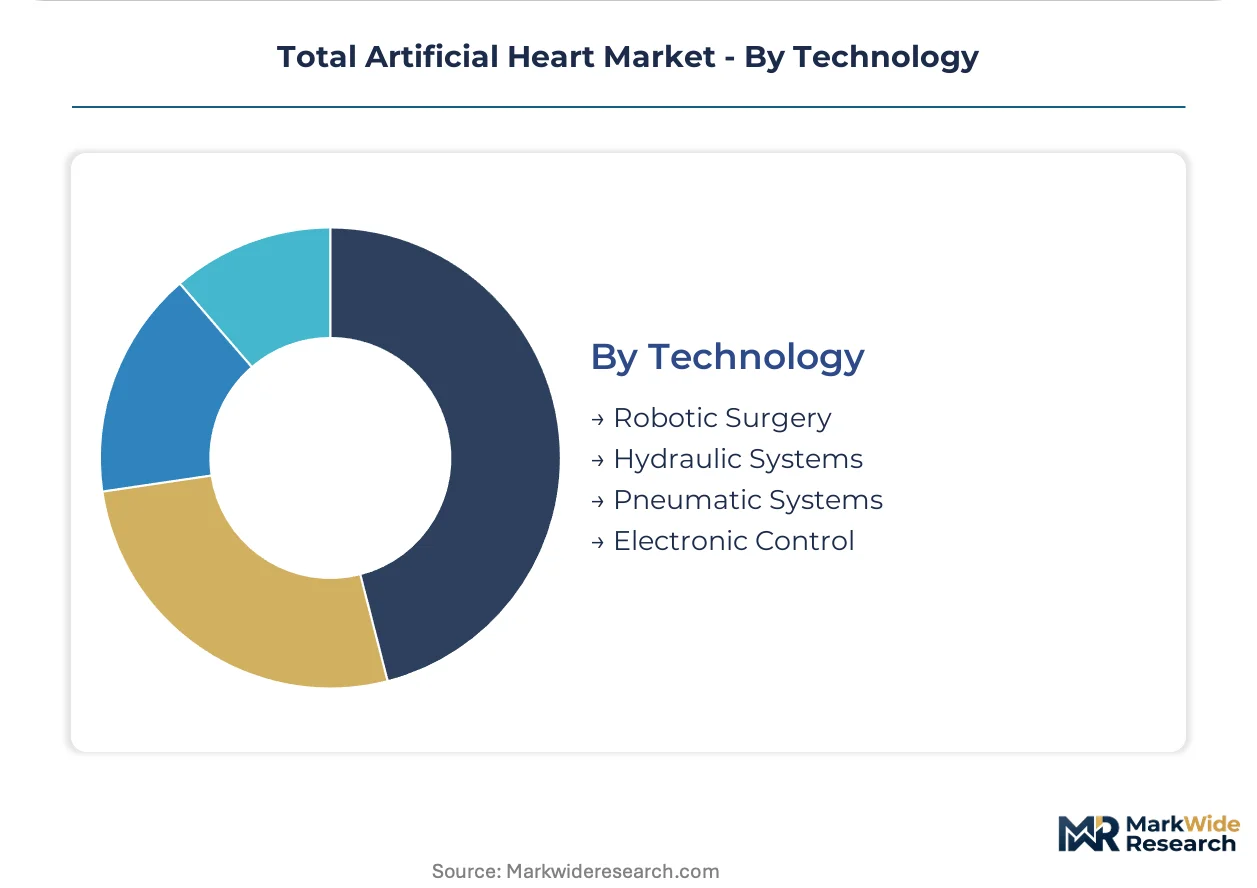
Installed base concentrates in Pneumatic Systems. Capability investment is accelerating most rapidly in Electronic Control platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains the highest implant volumes for total artificial heart procedures, while the United States drives regulatory pathway innovation through FDA breakthrough device designations. Japan's reimbursement evolution and France's bioprosthetic adoption create distinct competitive entry points across three continents.
United States
Academic medical centers in Texas and California generate concentrated referral volumes for bridge-to-transplant procedures. FDA breakthrough device designation pathways compress clinical validation timelines from traditional PMA cycles. Transplant centers in Houston and Los Angeles negotiate multi-year procurement agreements bundling device supply with remote monitoring services.
Germany
Specialized cardiac surgery clusters in Berlin, Munich, and Hamburg sustain sufficient implant volumes to justify dedicated TAH surgical teams. EU MDR conformity assessment requirements for active implantable devices extend time-to-market versus previous regulatory pathways. The Munich metropolitan area anchors the highest bioprosthetic heart adoption rates for destination therapy candidates.
France
Paris and Lyon transplant centers prioritize bioprosthetic platforms for patients with lifelong anticoagulation contraindications. ANSM oversees active implantable medical device standards that align with ISO 14708 electrical safety requirements. The Île-de-France region concentrates CARMAT's clinical validation infrastructure and specialized post-operative care networks.
Japan
PMDA reimbursement framework evolution for permanent mechanical circulatory support creates first-mover positioning for bioprosthetic systems. Tokyo and Osaka academic hospitals evaluate durability data for destination therapy expansion beyond bridge protocols. The Kanto region generates concentrated demand as aging demographics drive end-stage biventricular failure incidence.
United Kingdom
NHS specialized commissioning frameworks concentrate TAH procedures at designated cardiac surgery centers in London and Birmingham. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR standards while enabling UK-specific approval timelines. The Greater London region anchors clinical trial recruitment for novel bioprosthetic platforms.
Total Artificial Heart Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pneumatic legacy systems commanding established hospital procurement relationships while bioprosthetic entrants pursue regulatory fast-tracks. The market structure concentrates around three archetypes: mechanical heart incumbents with decades of surgical training infrastructure, bioprosthetic innovators leveraging sensor-embedded tissue engineering, and diversified cardiac device conglomerates with existing cath-lab channel access. Dominant competitive moves include strategic partnerships for remote patient monitoring integration and geographic licensing agreements to bypass EU MDR capacity constraints.
Within the mechanical heart tier, SynCardia Systems, LLC and Berlin Heart exemplify established players with proven pneumatic driver platforms and concentrated European surgical center relationships. CARMAT occupies a distinct position as a bioprosthetic specialist leveraging French clinical infrastructure for autoregulated blood flow systems. Abbott anchors the diversified conglomerate archetype through North American cardiac surgery channel relationships and bundled mechanical circulatory support contracting.
| Leading Market Players |
|---|
| Jarvik Heart, Inc. |
| Berlin Heart |
| SynCardia Systems, LLC |
| LivaNova PLC |
| Abbott |
| CARMAT |
| RealHeart |
| Getinge |
| BiVACOR Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty chemical suppliers anchor input cost structures for medical-grade polymers, compressing margin buffers for device manufacturers while concentrating pricing power among three polyurethane and silicone producers qualified to ISO 14708 active implantable standards.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for bioprosthetic membrane components as CARMAT scales French manufacturing. Three-tier pricing structure across premium sensor-embedded systems, standard pneumatic configurations, and economy bridge-to-transplant tiers reflects FDA breakthrough designation premiums versus legacy PMA pathways. Cost compression in mechanical heart segments runs through consolidated GPO contracting at US academic medical centers. Surgical centers with dedicated TAH teams demonstrate lowest price sensitivity; outpatient clinics managing wearable driver patients face highest budget constraints.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and France coordinate hub-and-spoke patterns for implantable device logistics. Manufacturing concentrates in the United States for pneumatic systems, France for bioprosthetic platforms, and Germany for precision polymer machining. Medical-grade polyurethane, biological tissue membranes, and MEMS pressure sensors feed from specialized suppliers with 18-36 month qualification cycles. Single-source vulnerability for ISO 14708-compliant polymer feedstock exposes manufacturers to notified body capacity constraints under EU MDR. Distribution runs through hospital procurement committees negotiating multi-year bundled agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA breakthrough pathway acceleration in the United States and EU MDR conformity delays extending German and French time-to-market by 18-36 months.
For Market Incumbents: To counter bioprosthetic substitution from CARMAT and emerging sensor-embedded platforms, SynCardia Systems and Berlin Heart should deepen backward integration into polymer supply through captive production of ISO 14708-qualified materials. Channel control via exclusive multi-year agreements with German cardiac surgery clusters in Berlin, Munich, and Hamburg preserves implant volume concentration against diversified conglomerate bundling. For New Entrants and Emerging Players: Begin with Japan destination therapy expansion as PMDA reimbursement framework evolution creates first-mover positioning ahead of US and EU regulatory saturation. BiVACOR and RealHeart should target Tokyo and Osaka academic hospitals with durability data packages for permanent mechanical circulatory support. Go-to-market leverage through remote patient monitoring integration supports value-based contracting with Japanese payers. For Investors and Strategic Acquirers: Diversified cardiac device conglomerates are the most active acquirer in this space, with Abbott's North American channel relationships demonstrating bundled mechanical circulatory support contracting economics. Five-to-ten year viability hinges on bioprosthetic durability data maturation and transcutaneous energy transfer standardization. Acquisition target archetype: sensor-embedded tissue engineering specialists with FDA breakthrough designation progress. Signal to watch: PMDA permanent implant reimbursement decisions triggering geographic demand rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Rolling review of modular clinical evidence compresses PMA timelines for bioprosthetic entrants. |
| EU MDR Conformity Assessment Navigation | Extended notified body capacity constraints demand early engagement with German and French regulators. |
| Remote Monitoring Platform Integration | SynCardia's pneumatic driver platform sustains outpatient subscription revenue and reduces emergency readmissions. |
| Hospital System Partnership Consolidation | Multi-year procurement agreements bundling device supply with telemetry services displace multi-vendor purchasing. |
| Bioprosthetic Tissue Engineering Scale-Up | CARMAT's autoregulated blood flow systems reduce anticoagulation burdens for destination therapy candidates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiac surgeons at Berlin, Munich, and Hamburg transplant centers, biomedical engineers at French ANSM-authorized facilities, US hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) and PMA filings, EU MDR notified body databases, CMS Medicare reimbursement codes, and hospital procurement contract disclosures. Bottom-up implant volume modeling triangulated against top-down market sizing across mechanical, bioprosthetic, and emerging electrical heart configurations.
Historical reference periods anchored the projection horizon through installed base analysis of pneumatic legacy systems and bioprosthetic adoption curves. Segmentation dimensions modeled include product architecture, application indication, technology generation, and end-user facility type. CAGRs derived from procedure volume trajectories at German cardiac surgery clusters, US academic medical center expansion rates, and Japanese PMDA reimbursement evolution timelines. Industry-specific inputs incorporated ISO 14708 compliance certification pipelines and transcutaneous power transfer durability datasets.
Several conditions sit outside the modeled scope, including regulatory approval delays beyond current EU MDR capacity constraints, novel anticoagulant therapy disruptions affecting bioprosthetic candidacy, and unforeseen material science breakthroughs in biological tissue engineering. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Chest Drainage System Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Hearing Loop Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
Medical Bionic Implant Market