
 Asia-Pacific Automotive Plastics Market | 2026-2036
Asia-Pacific Automotive Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Plastics Market Insights
The performance gap between premium engineering-grade resins and commodity polypropylene is broadening as OEMs face divergent cost and lightweighting targets. BASF SE leverages its specialty polyamide portfolio to anchor high-margin contracts with German-Japanese joint ventures operating in Thailand. SABIC competes aggressively on polycarbonate pricing for electric vehicle glazing applications across South Korea and China.
Asia-Pacific automotive plastics comprise thermoplastic and thermoset polymers formulated for structural, aesthetic, and functional vehicle components, typically requiring heat resistance above 120°C and impact strength measured by ISO 179 standards. These materials primarily serve to reduce curb weight and improve fuel efficiency or electric range. Polypropylene dominates volume across bumper and interior trim applications where cost sensitivity remains acute. Polycarbonate and ABS command premium positioning in instrument cluster housings and display bezels, where optical clarity and surface finish justify higher resin prices. Electric vehicle applications represent the fastest-expanding demand pool, driven by battery enclosure thermal management requirements and aerodynamic body panel needs.
China's MIIT enforces GB standards for passenger vehicle corporate average fuel consumption, directly incentivizing plastic substitution for metal body-in-white components. Japan's METI promotes next-generation vehicle material roadmaps that prioritize recycled polymer feedstocks, while South Korea's MFDS and KATS coordinate on automotive chemical safety standards affecting interior emissions. REACH-equivalent substance restrictions across multiple Asia-Pacific jurisdictions are tightening compliance costs for imported compound formulations. Stakeholders must evaluate captive compounding investments versus merchant supplier reliance as regulatory divergence between national standards intensifies.
Market Dynamics
China's dual carbon goals and MIIT-enforced GB standards for corporate average fuel consumption are forcing OEMs to substitute metal body-in-white components with engineered plastics at unprecedented scale across the Yangtze River Delta cluster.
Growth Catalysts
- MIIT Fuel Consumption Mandates:China's GB standards penalize metal-heavy vehicle designs, directly incentivizing polyamide and polycarbonate adoption in structural applications.
- Battery Thermal Management:Electric vehicle manufacturers require engineered plastics with heat resistance above 120°C for battery enclosures and cooling manifolds.
- Yangtze River Delta Concentration:Tier-1 suppliers operating at scale in this cluster achieve compounding efficiencies that accelerate OEM qualification timelines.
Market Restraints
- Crude-Derived Feedstock Volatility:Polypropylene and ABS pricing remains tethered to naphtha and propylene monomer cost swings that compress compounder margins.
- Specialty Resin Supply Concentration:High-performance polyamide and PPS capacity concentrates among three global suppliers, creating allocation risk during demand surges.
- Recycled Feedstock Quality Gaps:Japan's METI roadmap for next-generation recycled polymers outpaces available post-consumer automotive plastic streams with consistent ISO 179 impact performance.
Strategic Opportunities
- Southeast Asia EV Greenfield Plants:Thailand and Vietnam lack established automotive plastics compounding infrastructure, creating first-mover positioning for integrated resin-to-part suppliers.
- Closed-Loop Chemical Recycling:Pyrolysis-based feedstock recovery is converging with OEM sustainability commitments to unlock circular material contracts.
- India's PLI Scheme for Advanced Chemistry Cell Batteries:Domestic battery manufacturing incentives will cascade demand for flame-retardant polycarbonate and PBT compounds in enclosure applications.
Industry Challenges
- Multi-Jurisdiction REACH-Equivalent Compliance:Compounders must reformulate separately for China's MEE substance restrictions, South Korea's MFDS automotive chemical safety standards, and Japan's emerging recycled content verification protocols.
- Legacy Metal Stamping Workforce Transition:OEMs and tier-1s face retraining bottlenecks as injection molding and compression molding processes displace traditional body shop operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Plastics Market |
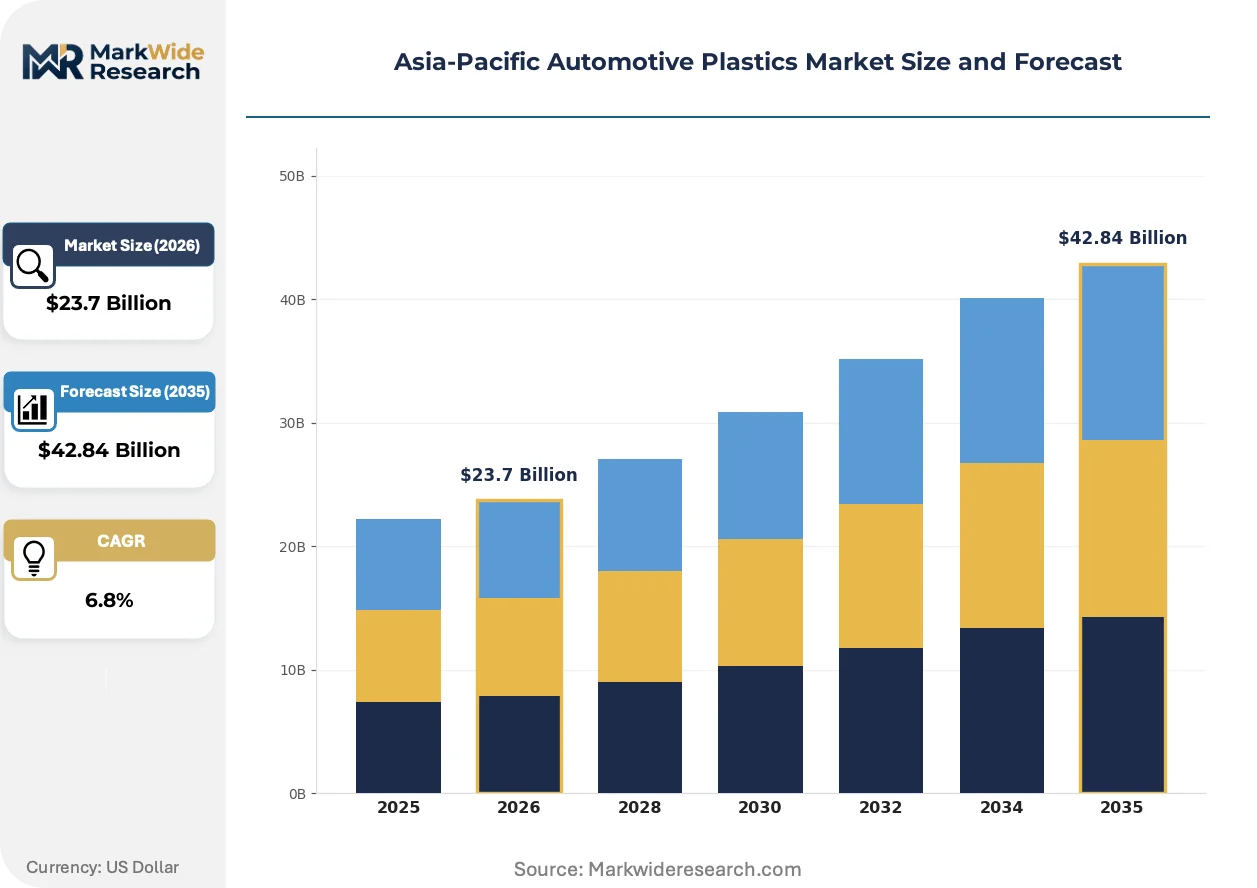
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Bumpers, Dashboards, Door Panels, Interior Trims Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Material Type: Polypropylene, Polyurethane, Polycarbonate, ABS Manufacturing Process: Injection Molding, Blow Molding, Extrusion, Thermoforming |
| Companies Covered | LG Chem, Borealis AG, BASF SE, DSM, Celanese Corporation, Covestro AG, LyondellBasell Industries Holdings B.V, Evonik Industries AG, SABIC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Plastics Market Trends and Innovations
Material science advances are compressing the performance gap between commodity and engineering-grade resins while regulatory pressure accelerates qualification cycles for sustainable alternatives.
Long-fiber thermoplastic (LFT) compounds are replacing short-fiber formulations in structural battery trays and load-bearing chassis components. Chinese EV manufacturers are qualifying these materials in 12-18 month windows versus traditional 36-month automotive timelines. LFT technology is converging with continuous fiber-reinforced tape layup processes to enable hybrid metal-plastic designs that satisfy crashworthiness requirements previously reserved for steel stampings.
South Korea's MFDS and KATS coordination on automotive interior emissions standards is tightening volatile organic compound limits for dashboard and seating applications. Compounders must reformulate stabilizer packages and eliminate legacy plasticizers to maintain qualification status. Interior trim suppliers serving Hyundai-Kia and domestic Chinese brands face the steepest retooling costs as dual certification for KATS and GB standards becomes mandatory.
Direct tier-1-to-OEM contracting is displacing traditional resin distributor networks for high-volume electric vehicle programs. BASF and SABIC field technical service teams inside battery and body engineering departments to co-develop part-specific formulations. This pattern is most visible in China's Yangtze River Delta and South Korea's Gyeonggi automotive corridor, where program volumes justify captive compounding investments over merchant supply.
Asia-Pacific Automotive Plastics Market Segmentation
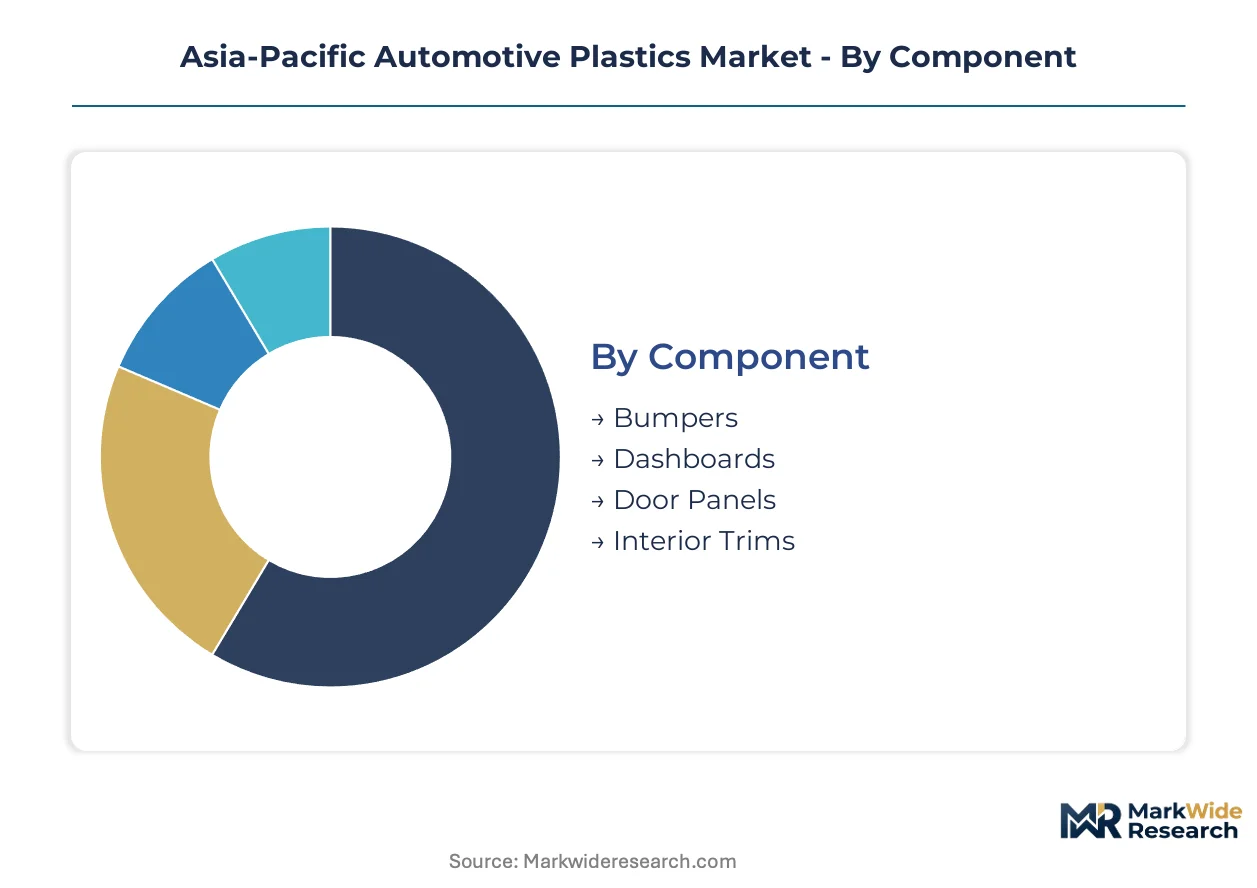
Automotive plastics procurement across the Asia-Pacific region fragments across four distinct axes, each carrying divergent certification burdens from MIIT, MFDS, and METI. Component-level specifications determine GB standard compliance pathways, while material selection locks in thermal performance thresholds for electric vehicle architectures.
Component:
MIIT structural integrity standards and MFDS interior emissions protocols impose tiered certification requirements that vary sharply by component function and occupant exposure risk.
- Bumpers:Polypropylene-based formulations dominate this segment, requiring ISO 179 impact strength validation and GB 8410 flammability certification for China's passenger vehicle fleet. Yangtze River Delta suppliers concentrate capacity here due to qualification efficiencies with SAIC and Geely programs.
- Dashboards:Polycarbonate-ABS blends command premium positioning, subject to South Korea's MFDS volatile organic compound limits and Japan's METI recycled content roadmaps. Dual certification for KATS and GB standards now represents a mandatory cost burden for Hyundai-Kia and domestic Chinese brand suppliers.
- Door Panels:Polypropylene composites with talc or glass fiber reinforcement satisfy cost-weight tradeoffs for mass-market vehicle lines.
- Interior Trims:Surface finish specifications and scratch resistance requirements differentiate commodity from engineering-grade resin selections.
Bumpers sit at the top of the volume ranking, with dashboards climbing the fastest.
Application:
End-use segmentation tracks powertrain electrification intensity, with thermal management requirements and curb weight targets diverging sharply across propulsion architectures.
- Passenger Vehicles:Corporate average fuel consumption mandates under China's GB standards pressure OEMs toward plastic-intensive body-in-white designs. MIIT penalties for metal-heavy architectures accelerate polyamide adoption in structural applications previously reserved for steel stampings.
- Electric Vehicles:Battery enclosure applications demand engineered plastics with heat resistance above 120°C, driving qualification timelines compressed to 12-18 months versus traditional 36-month automotive cycles. Chinese EV manufacturers anchor this segment's expansion.
- Commercial Vehicles:Durability specifications and load-bearing requirements sustain metal-plastic hybrid designs in chassis and cargo applications.
- Hybrid Vehicles:Dual thermal management needs for combustion and electric powertrains complicate material selection with competing temperature profiles.
Passenger vehicles maintain volume leadership, though electric vehicles gain share fastest on battery program ramp rates.
Material Type:
Resin selection stratifies by performance tier and feedstock cost exposure, with crude-derived commodities facing margin compression against specialty engineering grades.
- Polypropylene:Commodity-grade homopolymer and copolymer formulations serve cost-sensitive bumper and interior trim applications. Naphtha and propylene monomer price volatility compress compounder margins across Southeast Asian merchant supply chains.
- Polycarbonate:Optical clarity and flame-retardant specifications position this resin in instrument cluster housings, display bezels, and EV battery enclosures. SABIC competes aggressively on pricing for electric vehicle glazing applications across South Korea and China.
- Polyurethane:Foam and elastomer formulations address seating, insulation, and acoustic management requirements with tunable density characteristics.
- ABS:Surface finish quality and processability sustain demand in decorative trim and console applications despite acrylonitrile cost sensitivity.
Polypropylene dominates absolute volume, while polycarbonate expands most quickly on EV battery and glazing program wins.
Manufacturing Process:
Process technology selection determines part complexity limits, cycle economics, and workforce transition requirements as OEMs displace legacy metal stamping operations.
- Injection Molding:High-pressure precision molding enables complex geometries for dashboard assemblies and battery enclosure components. Tier-1 suppliers in China's Yangtze River Delta cluster achieve scale efficiencies that accelerate OEM qualification timelines.
- Blow Molding:Hollow part production serves fluid management applications including cooling manifolds and HVAC ducting for electric vehicle thermal systems.
- Extrusion:Continuous profile manufacturing addresses weatherstrip, sealing, and structural reinforcement applications with consistent cross-sectional tolerances.
- Thermoforming:Sheet-based forming processes serve large-area interior panels and exterior body applications with moderate structural demands.
Injection molding commands the highest process volume, with blow molding posting the steepest expansion trajectory on EV cooling system proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and process engineers concentrate in the Yangtze River Delta, anchoring the region's compounding expertise and accelerating OEM qualification timelines for lightweight vehicle architectures.
China
MIIT-enforced GB standards for corporate average fuel consumption penalize metal-intensive designs, forcing polyamide and polycarbonate adoption in structural body-in-white components. The dual carbon goals pressure OEMs toward plastic substitution at unprecedented scale. Tier-1 suppliers in Shanghai, Suzhou, and Ningbo achieve compounding efficiencies that compress traditional 36-month automotive qualification windows to 12-18 months for EV programs.
Japan
METI promotes next-generation vehicle material roadmaps prioritizing recycled polymer feedstocks, creating demand for post-consumer streams with consistent ISO 179 impact performance. Domestic OEMs source interior trim compounds meeting JIS standards for volatile organic compound emissions. Nagoya's automotive corridor hosts compounders developing closed-loop chemical recycling partnerships with tier-1 dashboard suppliers.
South Korea
MFDS and KATS coordination on automotive chemical safety standards tightens interior emissions limits for Hyundai-Kia supply chains. Polycarbonate demand surges for instrument cluster housings and battery enclosure applications requiring heat resistance above 120°C. The Gyeonggi automotive corridor anchors domestic compounding capacity serving both local OEMs and export-oriented joint ventures.
Thailand
German-Japanese joint ventures operating assembly plants drive specialty polyamide demand for lightweight chassis components. The Eastern Economic Corridor lacks established automotive plastics compounding infrastructure, creating first-mover opportunities for integrated resin-to-part suppliers. Bangkok-based technical service teams from global compounders co-develop formulations directly with OEM engineering departments.
India
The PLI scheme for Advanced Chemistry Cell batteries cascades demand for flame-retardant polycarbonate and PBT compounds in domestic battery enclosure manufacturing. Maharashtra and Tamil Nadu automotive clusters attract merchant compounders seeking proximity to emerging EV assembly operations. BIS certification requirements for automotive plastics lag China's GB standards, extending qualification timelines for imported formulations.
Asia-Pacific Automotive Plastics Market Competitive Landscape
Top-tier vendors anchor high-margin specialty resin contracts, while merchant compounders compete on polypropylene volume and regional logistics efficiency. The vendor base stratifies across three tiers: integrated petrochemical giants with captive feedstock, independent compounders with formulation expertise, and regional distributors serving cost-sensitive bumper and interior trim applications. Strategic archetypes include specialty polyamide specialists, polycarbonate glazing innovators, and polypropylene scale players. Capacity expansion in Southeast Asia and backward integration into pyrolysis-based feedstock recovery represent dominant competitive vectors.
Within the integrated petrochemical tier, BASF SE and SABIC exemplify divergent positioning strategies. BASF anchors high-margin contracts through technical service teams embedded in OEM engineering departments, while SABIC competes aggressively on polycarbonate pricing for electric vehicle glazing applications. LG Chem occupies a position bridging Korean domestic supply security with export-oriented EV battery material integration. These three represent distinct archetypes: European formulation-led premium positioning, Saudi-Arabian feedstock-integrated scale, and Korean battery-chemistry convergence.
| Leading Market Players |
|---|
| LG Chem |
| Borealis AG |
| BASF SE |
| DSM |
| Celanese Corporation |
| Covestro AG |
| LyondellBasell Industries Holdings B.V |
| Evonik Industries AG |
| SABIC |
| Others |
Pricing and Supply Chain Analysis
Captive compounding investments by tier-1 suppliers in China's Yangtze River Delta anchor both supply security and pricing leverage against merchant compounders serving cost-sensitive bumper applications. This integration choice compresses qualification timelines for polyamide and polycarbonate formulations while insulating premium resin contracts from naphtha price volatility.
Pricing Analysis
Bundled technical service contracts dominate premium polyamide and polycarbonate procurement, while unbundled commodity polypropylene moves through spot-market distributors. Price differentiation stems from MIIT GB standard certification tiers and volume scale commitments to Yangtze River Delta clusters. Cost compression in polypropylene homopolymer intensifies as naphtha-derived feedstock volatility squeezes merchant compounder margins. Mass-market bumper suppliers exhibit acute price sensitivity, whereas battery enclosure engineers prioritize thermal performance over resin cost.
Supply Chain Analysis
Specialty polyamide supply rests on concentrated capacity in Germany, Japan, and the United States, creating allocation vulnerability during EV platform ramp-ups. Feedstock dependencies span naphtha crackers for polypropylene, bisphenol-A for polycarbonate, and adipic acid for polyamide 66. Single-source vulnerability concentrates in high-performance PPS and long-fiber thermoplastic masterbatch supply. Distribution runs through direct tier-1-to-OEM contracting for electric vehicle programs, displacing traditional resin distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific automotive plastics market represents a late-cycle quality story as battery thermal management specifications displace commodity polypropylene with engineered grades requiring heat resistance above 120°C.
For Market Incumbents: Cement polyamide formulation leadership through backward integration into adipic acid supply and captive compounding capacity in Thailand's Eastern Economic Corridor. Defend margin position against SABIC's polycarbonate pricing aggression by embedding technical service teams inside OEM battery engineering departments. Prioritize MIIT GB standard pre-certification to lock out merchant compounders from structural body-in-white applications.
For New Entrants and Emerging Players: The premium-to-economy price gap in dashboard polycarbonate-ABS blends offers white-space entry for compounders mastering dual KATS and MFDS certification. Target Vietnam's nascent EV assembly corridor where established compounding infrastructure remains absent. Pursue pyrolysis-based chemical recycling partnerships to unlock circular material contracts with Japanese OEMs under METI recycled content roadmaps.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap independent compounders with formulation expertise because regulatory divergence between China's MEE substance restrictions, South Korea's MFDS standards, and Japan's recycled content protocols fragments compliance capabilities. Five-to-ten year viability favors specialists with demonstrated OEM qualification track records. Watch for inflection when India's PLI scheme for Advanced Chemistry Cell batteries triggers flame-retardant polycarbonate demand cascades in Maharashtra and Tamil Nadu clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Secures polyamide 66 feedstock against specialty resin supply concentration among three global suppliers. |
| Captive Compounding in Eastern Economic Corridor | Captures first-mover positioning in Thailand's German-Japanese joint venture chassis component demand. |
| Dual KATS-MFDS Certification Investment | Unlocks Hyundai-Kia and domestic Chinese brand dashboard supply contracts requiring volatile organic compound compliance. |
| Pyrolysis-Based Chemical Recycling Partnership | Aligns compounder offerings with METI recycled polymer roadmaps and OEM sustainability commitments. |
| Technical Service Team Embedding | Accelerates 12-18 month EV qualification timelines through direct OEM engineering department collaboration. |
Research Methodology
Coverage spans China, Japan, South Korea, Thailand, and India, with primary inputs from each market's automotive corridor. Primary interviews engaged tier-1 supplier procurement directors, OEM platform engineers, compounder technical service leads, and aftermarket distribution heads. Secondary validation drew from MIIT GB standard filings, MFDS automotive chemical safety registrations, customs trade data for resin imports, and vehicle production databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Granularity-level modeling addressed component function, propulsion architecture, resin performance tier, and manufacturing process technology across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by content-per-vehicle assumptions for battery enclosure applications. Forecast inputs incorporated OEM platform launch schedules, MIIT corporate average fuel consumption penalty structures, and thermal management specification evolution.
Caveats apply where crude-derived feedstock volatility, REACH-equivalent regulatory divergence, or recycled feedstock quality gaps could materially shift the outlook. Forecasts reflect assumptions about EV penetration rates, qualification timeline compression sustainability, and specialty resin capacity expansion timing. A small set of triggers—MIIT standard stringency revisions, PPS supply allocation disruptions, and closed-loop chemical recycling yield improvements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Chromium Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Mufflers Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Fender Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Differential Market