
 Topical Acne Medication Market | 2026-2036
Topical Acne Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Acne Medication Market Insights
The FDA's updated pregnancy labeling requirements for topical retinoids is pivoting the cost-of-entry calculus toward larger pharmaceutical portfolios. Galderma leverages its integrated dermatology platform to sustain leadership in prescription-grade retinoid formulations. Johnson & Johnson anchors its consumer division with mass-market benzoyl peroxide lines that dominate retail pharmacy shelves. Sun Pharmaceutical Industries competes through specialized generic topical antibiotics that occupy price-sensitive segments across emerging markets.
Topical acne medications comprise dermatological formulations containing active pharmaceutical ingredients such as benzoyl peroxide, retinoids, salicylic acid, or antibiotics, typically manufactured as semi-solid preparations with specific pH ranges between 3.0 and 7.0 to ensure skin tolerability and chemical stability. These products function primarily to reduce sebum production, accelerate epidermal turnover, inhibit Cutibacterium acnes colonization, or modulate inflammatory cascades in pilosebaceous units. Retinoid-based therapies lead prescription value pools due to their established efficacy in comedonal and inflammatory acne, while azelaic acid formulations represent the fastest-growing active ingredient segment driven by rosacea-acne overlap indications and favorable tolerability profiles. Cream and gel delivery modes capture divergent patient preferences, with gels penetrating the teenage segment through cosmetic elegance and creams retaining the adult dermatology channel through moisturizing co-benefits.
FDA pregnancy category labeling, EPA environmental release assessments for benzoyl peroxide manufacturing, and EMA's revised MDR requirements for CE-marked dermatological devices collectively elevate documentation burdens and extend development timelines for new topical entrants. Health Canada and Australia's TGA maintain aligned but distinct bioequivalence standards that fragment regulatory submission strategies for multinational portfolios. Stakeholders must monitor how FDA guidance on fixed-dose combination topicals evolves, as this will determine whether pipeline investments tilt toward single-entity reformulations or novel synergistic pairings.
Market Dynamics
FDA pregnancy labeling mandates for topical retinoids are compressing development timelines and forcing portfolio reallocation toward tolerability-first formulations. This regulatory pivot favors incumbents with established safety databases while raising capital requirements for novel active ingredient entrants.
Growth Catalysts
- Telehealth platform expansion:Direct-to-consumer dermatology channels in the United States are routing patients toward prescription-grade topical therapies, bypassing traditional primary care gatekeepers and accelerating treatment initiation.
- EMA MDR alignment:Streamlined CE-marking pathways for dermatological devices in Europe are reducing time-to-market for combination drug-device acne treatments, stimulating investment in microneedle and light-based delivery systems.
- Azelaic acid tolerability profile:Rosacea-acne overlap indications are expanding addressable patient populations beyond traditional teenage demographics, with adult dermatology clinics prioritizing this active ingredient for sensitive skin presentations.
Market Restraints
- Isotretinoin precursor supply concentration:Manufacturing of synthetic retinoid starting materials clusters in a limited number of Chinese chemical suppliers, exposing formulation pipelines to import tariff volatility and environmental compliance shutdowns.
- Benzoyl peroxide EPA assessment requirements:Environmental release documentation for peroxide manufacturing elevates facility capital costs and extends facility commissioning timelines by 18-24 months for new production entrants.
- Antibiotic resistance surveillance:Rising Cutibacterium acnes resistance to clindamycin and erythromycin is compressing the effective lifespan of topical antibiotic monotherapies, forcing earlier combination therapy adoption.
Strategic Opportunities
- India CDSCO fast-track pathways:Accelerated approval mechanisms for dermatological fixed-dose combinations are enabling earlier market entry for reformulated retinoid-antibiotic pairings targeting price-sensitive prescribing segments.
- Biome-targeted microbiome therapies:Convergence of metagenomic sequencing and topical formulation science is opening development corridors for bacterial lysate and postbiotic acne treatments that modulate skin commensal populations.
- Subscription pharmacy models:Automated refill platforms integrated with teledermatology consultations are capturing chronic acne patients through adherence-focused packaging and personalized regimen adjustment protocols.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in semi-solid stability engineering and transdermal penetration enhancement is concentrating among a narrow cohort of contract development organizations, extending recruitment timelines for in-house capability building.
- Legacy ERP integration with serialization:Track-and-trace compliance for topical pharmaceutical distribution requires substantial middleware investment to connect batch manufacturing records with downstream pharmacy verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Acne Medication Market |
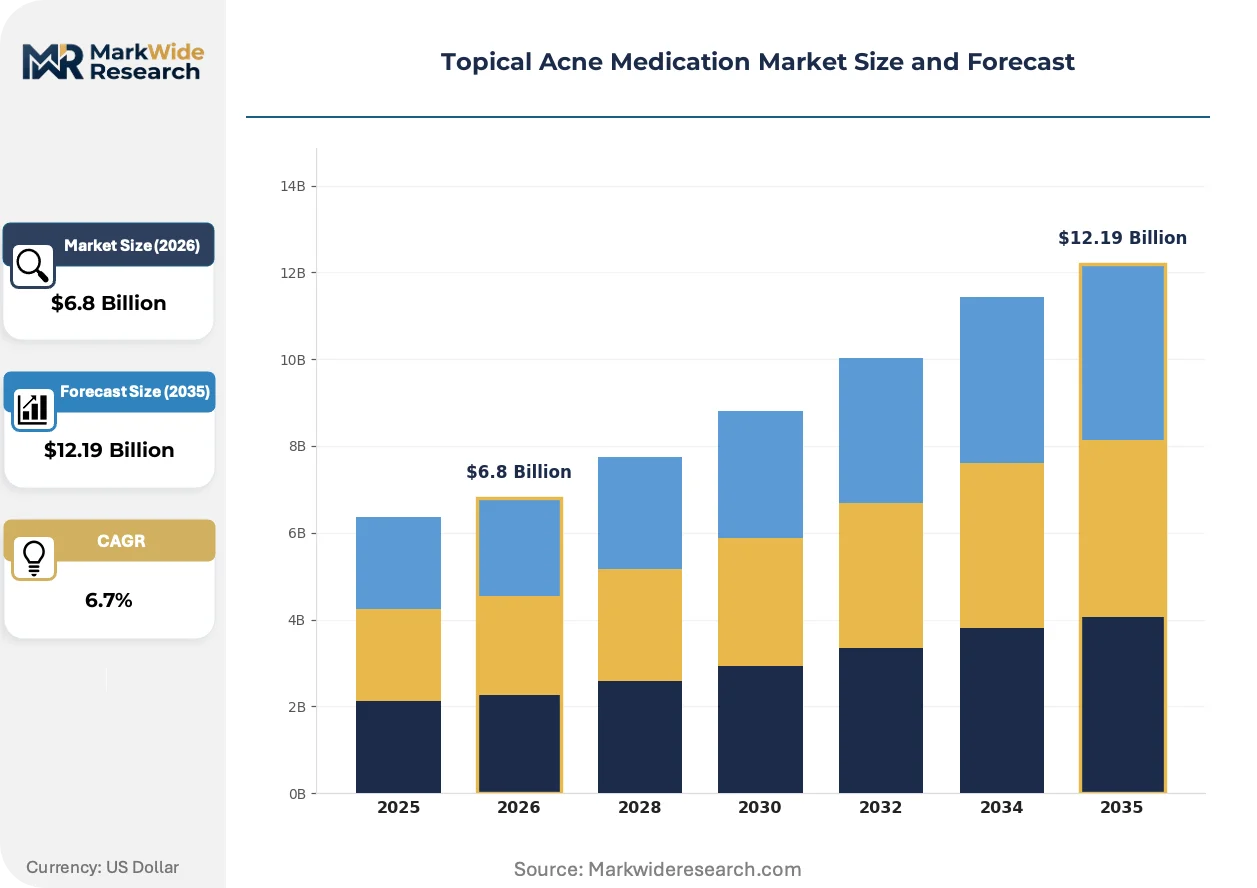
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzoyl Peroxide, Retinoids, Salicylic Acid, Antibiotics Delivery Mode: Creams, Gels, Lotions, Foams End User: Teenagers, Adults, Dermatologists, Clinics Active Ingredient: Azelaic Acid, Dapsone, Sulfur, Others |
| Companies Covered | Galderma, Johnson & Johnson, L'Oréal, Bausch Health Companies, Sun Pharmaceutical Industries, AbbVie, GlaxoSmithKline, Teva Pharmaceutical Industries, Almirall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Acne Medication Market Trends and Innovations
Formulation science and patient acquisition channels are undergoing simultaneous transformation, with delivery technology advances intersecting regulatory stringency and direct-to-consumer distribution expansion.
Encapsulated retinoid delivery systems using porous polymer microspheres are enabling controlled release of tretinoin and adapalene across extended wear periods. Teenage patient segments in the United States are adopting gel-based microsphere formulations at accelerating rates due to reduced irritation profiles and cosmetic elegance. This technology is electrifying the prescription compliance landscape by reducing early-therapy dropout rates that previously undermined long-term therapeutic outcomes.
REACH authorization requirements for benzoyl peroxide intermediates in the European Union are forcing reformulation of manufacturing processes to eliminate solvent-based purification steps. Industrial consequence includes accelerated migration toward continuous flow chemistry platforms that minimize environmental release volumes. Contract manufacturers serving European markets are responding by consolidating production at upgraded facilities in Germany and the Netherlands with integrated waste treatment capabilities.
Patient acquisition through social media dermatology content is displacing traditional physician referral pathways for initial acne treatment selection. United States-based telehealth platforms are capturing this demand shift through algorithmic skin assessment tools that route users toward branded topical prescriptions without in-person consultation. This behavioral pivot is most visible among millennial and Gen Z demographics in metropolitan markets where appointment access friction previously delayed treatment initiation.
Topical Acne Medication Market Segmentation
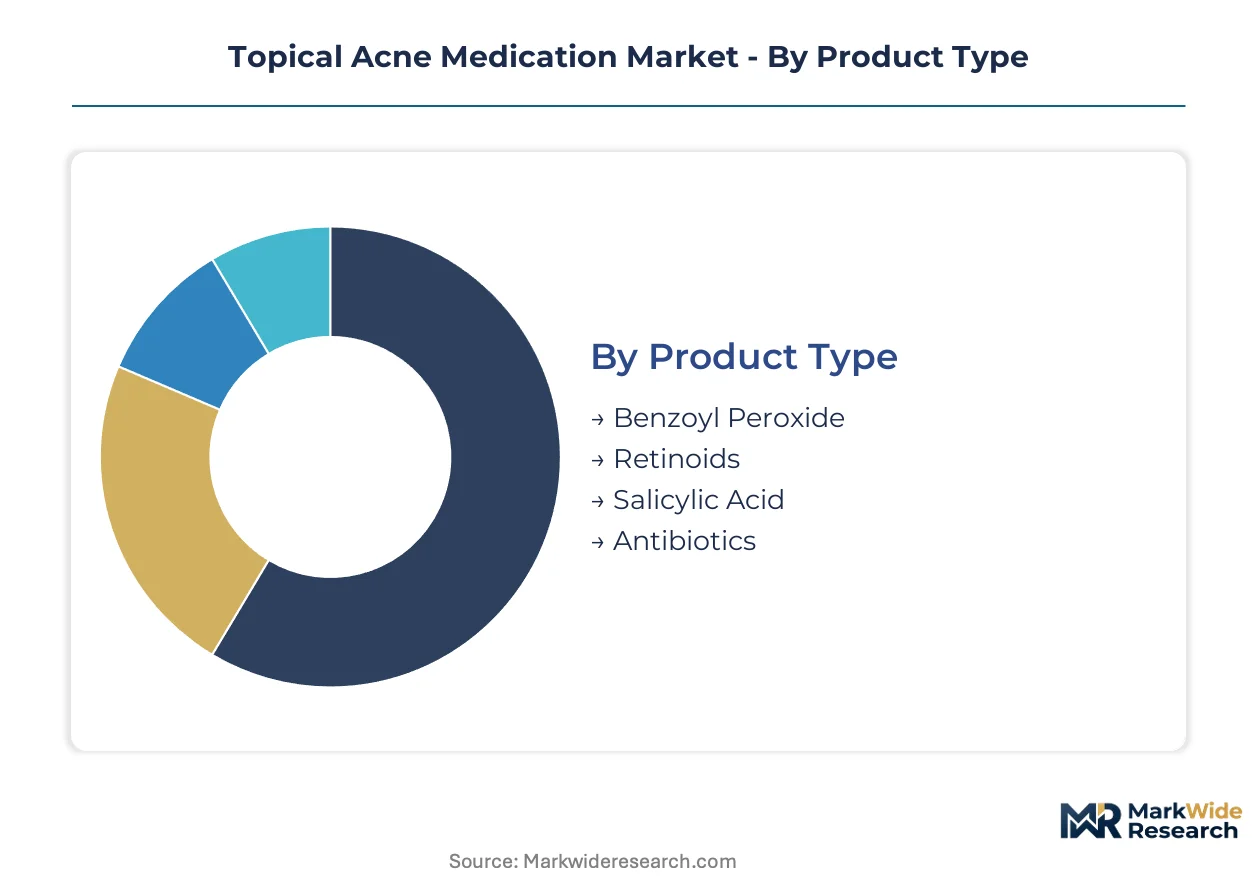
Topical acne medication segmentation reveals how formulation chemistry, patient demographics, and clinical settings create distinct commercial battlegrounds. Each dimension carries unique regulatory burdens and margin structures that determine portfolio prioritization for manufacturers.
Product Type:
Supply concentration for active pharmaceutical ingredients varies sharply across chemical classes, with synthetic retinoid precursors clustering among limited specialty chemical suppliers while benzoyl peroxide maintains more distributed production.
- Retinoids:Vitamin A derivatives including tretinoin, adapalene, and tazarotene formulated for comedonal acne disruption. Demand concentrates in United States dermatology clinics where FDA pregnancy labeling mandates elevate compliance costs but preserve premium pricing power for established safety databases.
- Benzoyl Peroxide:Organic peroxide compounds releasing oxygen to reduce Cutibacterium acnes colonization. United States retail pharmacy channels dominate volume through mass-market accessibility, though EPA environmental release assessments are extending facility commissioning timelines for new manufacturing entrants.
- Salicylic Acid:Beta-hydroxy acid exfoliants operating at 0.5-2.0% concentrations for keratolytic action in over-the-counter segments.
- Antibiotics:Topical clindamycin and erythromycin formulations facing compressed lifespans from rising bacterial resistance surveillance requirements.
Today's leader: Retinoids. Tomorrow's challenger: Benzoyl Peroxide.
Delivery Mode:
Cost tier differentiation separates premium-positioned gel technologies from economy lotion formulations, with manufacturing complexity and packaging sophistication determining margin capture.
- Gels:Aqueous-based semi-solids with rapid drying properties and cosmetic elegance. United States teenage segments are adopting microsphere-encapsulated gel formulations fastest due to reduced irritation profiles and extended wear compatibility.
- Creams:Oil-in-water emulsions delivering moisturizing co-benefits alongside active ingredient penetration. Adult dermatology channels in metropolitan United States markets retain cream preference for sensitive skin presentations and rosacea-acne overlap conditions.
- Lotions:Lower viscosity fluid preparations enabling large-area application with reduced residue.
- Foams:Propellant-driven delivery systems offering rapid absorption and minimal tactile residue for hair-bearing application sites.
Volume concentration favors gels. Margin expansion concentrates in creams.
End User:
Customer type segmentation maps directly to prescription authority and reimbursement pathway complexity, with direct-to-consumer channels disrupting traditional gatekeeper models.
- Adults:Patients over 25 seeking treatment for persistent or late-onset acne, often with concomitant skin sensitivity concerns. United States telehealth platforms are routing this demographic toward prescription-grade therapies through algorithmic skin assessment tools that bypass traditional primary care access friction.
- Dermatologists:Specialist physicians prescribing combination therapies and monitoring treatment-resistant cases. Academic medical centers in Boston and San Francisco are expanding adult acne prescription portfolios fastest as patient awareness of persistent post-adolescent conditions rises.
- Teenagers:Adolescent patients initiating first-line treatment, typically through pediatrician or family practice channels.
- Clinics:Institutional settings including community health centers and retail-based medical clinics managing high-volume acne caseloads.
Prescription value pools center on dermatologists. Patient acquisition velocity concentrates in adult direct-to-consumer channels.
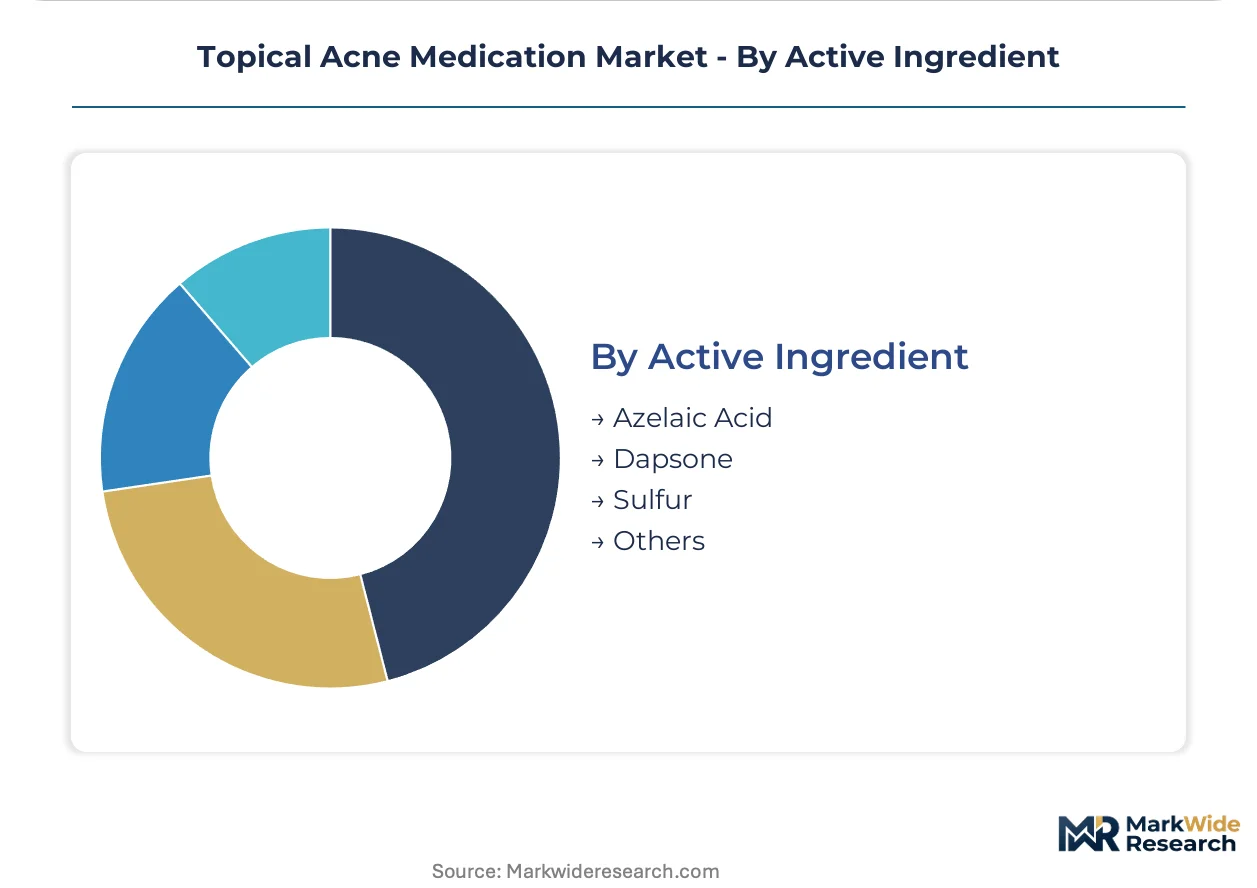
Active Ingredient:
Maturity stage differentiation separates established azelaic acid formulations from emerging microbiome-targeted alternatives, with regulatory approval pathways determining commercialization speed.
- Azelaic Acid:Dicarboxylic acid compounds at 15-20% concentrations with dual anti-inflammatory and antimicrobial mechanisms. Rosacea-acne overlap indications in United States adult dermatology practices are expanding addressable populations fastest due to favorable tolerability profiles against retinoid irritation.
- Dapsone:Sulfone-based anti-inflammatory agents formulated at 5% and 7.5% concentrations for inflammatory acne variants.
- Sulfur:Elemental preparations with keratolytic and mild antibacterial properties occupying niche over-the-counter positioning.
- Others:Emerging active categories including niacinamide, tea tree oil derivatives, and postbiotic bacterial lysates in pre-commercial development.
Established efficacy anchors azelaic acid. Steepest expansion trajectory belongs to others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in pharmaceutical hubs across the United States, Germany, and India, anchoring regional development capacity for semi-solid dermatological preparations.
United States
Telehealth dermatology platforms in metropolitan markets route adult patients toward prescription-grade retinoid therapies through algorithmic skin assessment tools. FDA pregnancy labeling mandates for topical retinoids compress development timelines while elevating compliance costs for new market entrants. Boston and San Francisco academic medical centers expand adult acne prescription portfolios fastest as post-adolescent condition awareness rises.
Germany
Contract manufacturers serving European markets consolidate production at upgraded facilities with integrated waste treatment capabilities for benzoyl peroxide intermediates. REACH authorization requirements force reformulation away from solvent-based purification steps toward continuous flow chemistry platforms. The Eindhoven-to-Düsseldorf corridor houses specialized semi-solid stability engineering expertise concentrated among narrow cohorts of contract development organizations.
India
CDSCO fast-track pathways for dermatological fixed-dose combinations enable earlier market entry for reformulated retinoid-antibiotic pairings targeting price-sensitive prescribing segments. Mumbai and Hyderabad formulation clusters specialize in generic topical antibiotics occupying emerging market segments. Domestic API manufacturing for synthetic retinoid precursors remains concentrated among limited specialty chemical suppliers in Gujarat and Maharashtra.
China
Isotretinoin precursor supply concentration among limited chemical suppliers exposes formulation pipelines to environmental compliance shutdowns and import tariff volatility. NMPA bioequivalence standards for topical generics fragment regulatory submission strategies for multinational portfolios seeking parallel approvals. Shanghai and Jiangsu province house the majority of domestic benzoyl peroxide manufacturing capacity subject to evolving environmental release assessments.
Australia
TGA maintains aligned but distinct bioequivalence standards from FDA and EMA that extend documentation burdens for topical generic entrants. Direct-to-consumer pharmacy platforms capture chronic acne patients through adherence-focused packaging and personalized regimen adjustment protocols. Sydney and Melbourne dermatology clinics prioritize azelaic acid formulations for rosacea-acne overlap indications in sensitive skin presentations.
Topical Acne Medication Market Competitive Landscape
The competitive structure tilts toward integrated dermatology platforms with established safety databases. Prescription-grade retinoid formulations concentrate among incumbents with decades of post-market surveillance data, while mass-market benzoyl peroxide lines fragment across consumer health divisions. Two strategic archetypes dominate: vertically integrated pharmaceutical portfolios spanning discovery-to-distribution, and specialized generic manufacturers exploiting price-sensitive segments. Competitive moves center on portfolio reallocation toward tolerability-first formulations and geographic expansion through accelerated regulatory pathways in emerging markets.
Among Swiss-anchored dermatology specialists, Galderma occupies a position exemplifying integrated platform advantages in prescription-grade retinoid development. Johnson & Johnson represents the consumer health archetype through mass-market accessibility strategies dominating retail pharmacy channels. Sun Pharmaceutical Industries anchors the emerging market generic tier, with Mumbai-based manufacturing capacity targeting price-sensitive antibiotic segments across Asia-Pacific and Latin American markets.
| Leading Market Players |
|---|
| Galderma |
| Johnson & Johnson |
| L'Oréal |
| Bausch Health Companies |
| Sun Pharmaceutical Industries |
| AbbVie |
| GlaxoSmithKline |
| Teva Pharmaceutical Industries |
| Almirall |
| Others |
Pricing and Supply Chain Analysis
Telehealth platform procurement preferences for prescription-grade retinoid therapies are compressing margins on unbundled product sales while rewarding integrated adherence packaging, forcing manufacturers to absorb formulation costs or consolidate service offerings. This demand shift elevates pricing power for vertically integrated dermatology platforms that bundle consultation, prescription fulfillment, and regimen monitoring into single-subscription structures.
Pricing Analysis
Bundled subscription services versus unbundled transactional product sales define the pricing architecture. Three-tier pricing structure across premium microsphere formulations, standard cream emulsions, and economy generic antibiotics separates patient segments by tolerability requirements and insurance coverage depth. Cost compression in economy antibiotic tiers is intensifying because Indian CDSCO fast-track approvals flood price-sensitive markets with generic clindamycin alternatives. Teenage direct-to-consumer buyers exhibit highest price sensitivity, while adult dermatology clinic procurement through GPO contracts shows lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese specialty chemical manufacturers controlling isotretinoin precursor synthesis. Active pharmaceutical ingredient production draws from China, India, and Germany for synthetic retinoids, benzoyl peroxide intermediates, and semi-solid formulation expertise respectively. Manufacturing of tretinoin starting materials, porous polymer microspheres, and propellant-driven foam systems feeds from concentrated chemical clusters in Jiangsu province, Gujarat state, and the Eindhoven-to-Düsseldorf corridor. Tariff exposure on Chinese retinoid precursors threatens margin stability for formulation-dependent portfolios. Distribution runs through direct-to-consumer pharmacy platforms, hospital GPO contracts, and retail pharmacy chains in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA pregnancy labeling mandates for topical retinoids continuously elevate compliance barriers that concentrate value among incumbents with established safety databases.
For Market Incumbents: Hedge against biosimilar retinoid erosion by deepening microbiome therapy R&D pipelines and securing captive supply of encapsulated delivery polymers. Threat vectors include Indian generic manufacturers exploiting CDSCO accelerated pathways and emerging postbiotic formulations displacing traditional antibiotic pairings. Priority levers center on backward integration into microsphere manufacturing and exclusive teledermatology platform partnerships that lock patient adherence data. For New Entrants and Emerging Players: Launch via subscription pharmacy models targeting adult acne patients in United States metropolitan markets with algorithmic skin assessment integration. Most penetrable white-space sits in rosacea-acne overlap indications where azelaic acid tolerability advantages remain underexploited in direct-to-consumer channels. Specific go-to-market angle emphasizes personalized regimen adjustment protocols that incumbent mass-market brands cannot replicate without infrastructure overhaul. For Investors and Strategic Acquirers: Asymmetric upside sits with contract development organizations specializing in semi-solid stability engineering and transdermal penetration enhancement. Long-term viability across the analysis window favors acquisition targets possessing integrated manufacturing footprints spanning API synthesis through finished dosage form, with particular strength in German or Dutch regulatory-compliant facilities. Signal to watch is FDA guidance evolution on fixed-dose combination topicals, which would trigger portfolio reallocation toward synergistic active ingredient pairings.| Strategic Initiative | Industry Significance |
|---|---|
| Microsphere Encapsulation Scale-Up | Controlled-release tretinoin formulations reduce irritation dropout rates in teenage prescription compliance. |
| CDSCO Fast-Track Exploitation | Accelerated Indian approvals enable earlier entry for retinoid-antibiotic fixed-dose combinations in price-sensitive segments. |
| Telehealth Platform Integration | Algorithmic skin assessment tools bypass primary care gatekeepers and capture adult patient acquisition velocity. |
| Continuous Flow Chemistry Transition | REACH-compliant benzoyl peroxide manufacturing eliminates solvent-based purification steps at upgraded German facilities. |
| Microbiome Therapy Pipeline Buildout | Bacterial lysate and postbiotic formulations open development corridors beyond established antibiotic resistance constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic procurement managers, formulation R&D directors at contract development organizations, regulatory affairs leads navigating FDA pregnancy labeling requirements, and telehealth platform pharmacy directors with secondary validation against FDA filings, EMA MDR submission databases, ClinicalTrials.gov protocol registries, and Indian CDSCO approval records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical reference periods spanning pre-pandemic baseline through telehealth expansion phases anchored the forecast window across the projection horizon. Segmentation dimensions modeled include active ingredient class, delivery mode formulation, end-user channel archetype, and regional regulatory cluster complexity. CAGRs were derived from growth driver elasticity analysis and constraint-bound ceiling estimation, with specific inputs capturing telehealth platform patient routing rates and benzoyl peroxide EPA facility commissioning timeline extensions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under import tariff volatility scenarios affecting Chinese retinoid precursor supply. Forecasts reflect documented assumptions on telehealth platform regulatory durability and antibiotic resistance surveillance intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market