
 US Acne Treatment Market | 2026-2036
US Acne Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
US Acne Treatment Market Intelligence
Dermatologist workforce shortages in rural counties is unwinding access patterns across the US acne treatment landscape. Galderma leverages its prescription-grade retinoid portfolio to dominate specialist channels. Johnson & Johnson sustains broad retail penetration through Neutrogena's mass-market benzoyl peroxide lines. La Roche-Posay differentiates via dermatologist-recommended formulations positioned above commodity skincare tiers.
Acne treatment encompasses topical, oral, and procedural interventions targeting pilosebaceous unit disorders through antimicrobial, anti-inflammatory, or keratolytic mechanisms, with benzoyl peroxide concentrations typically ranging from 2.5% to 10% and retinoid formulations requiring photostabilized delivery systems to maintain therapeutic efficacy. The category serves both medical clearance of active lesions and cosmetic management of post-inflammatory sequelae. Topical creams and retinoids capture the largest volume pools, while telehealth platforms represent the fastest-growing end-user channel as asynchronous prescribing models expand beyond traditional office visits. Prescription sales retain premium margin concentration, though e-commerce continues to erode pharmacy foot traffic for maintenance-grade regimens.
FDA oversight of over-the-counter monograph reform and EPA registration requirements for benzoyl peroxide manufacturing facilities shape product compliance costs and labeling standards across the US market. State-level scope-of-practice regulations governing nurse practitioners and physician assistants influence telehealth platform expansion into prescription acne management. Stakeholders must monitor how evolving DEA scheduling discussions around certain oral antibiotics intersect with dermatology's shift toward combination topical therapies.
Market Dynamics
Telehealth platforms are compressing traditional dermatology visit patterns while FDA scrutiny of benzoyl peroxide stability forces reformulation investments across topical manufacturing lines.
Growth Catalysts
- Asynchronous Prescribing Models:Telehealth platforms expand prescription acne management beyond metropolitan corridors into rural counties lacking dermatologist density.
- Humid Climate Sustained Demand:Texas and Florida maintain elevated treatment rates through large youth populations and climate-driven sebaceous activity.
- Photostabilized Retinoid Delivery:Advanced encapsulation technologies extend shelf stability and reduce irritation profiles for topical vitamin A derivatives.
Market Restraints
- Benzoyl Peroxide Input Volatility:EPA registration requirements for manufacturing facilities constrain domestic production capacity and elevate compliance overhead.
- Specialist Channel Concentration:Dermatologist workforce shortages in rural counties limit prescription-grade retinoid access outside urban academic medical centers.
- Antibiotic Stewardship Pressures:DEA scheduling discussions around oral antibiotics accelerate restrictions on combination oral therapies.
Strategic Opportunities
- Nurse Practitioner Scope Expansion:State-level regulations governing physician assistants and nurse practitioners unlock telehealth platform growth into prescription management.
- Post-Inflammatory Sequelae Segment:Cosmetic management of hyperpigmentation and scarring attracts premium positioning above commodity skincare tiers.
- E-Commerce Maintenance Regimens:Direct-to-consumer channels capture pharmacy foot traffic erosion for non-prescription benzoyl peroxide lines.
Industry Challenges
- Formulation Stability Expertise:Photostabilized delivery systems require specialized chemistry capabilities scarce among contract manufacturers.
- Monograph Reform Navigation:FDA OTC monograph reform creates labeling uncertainty and timeline risk for established topical portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Acne Treatment Market |
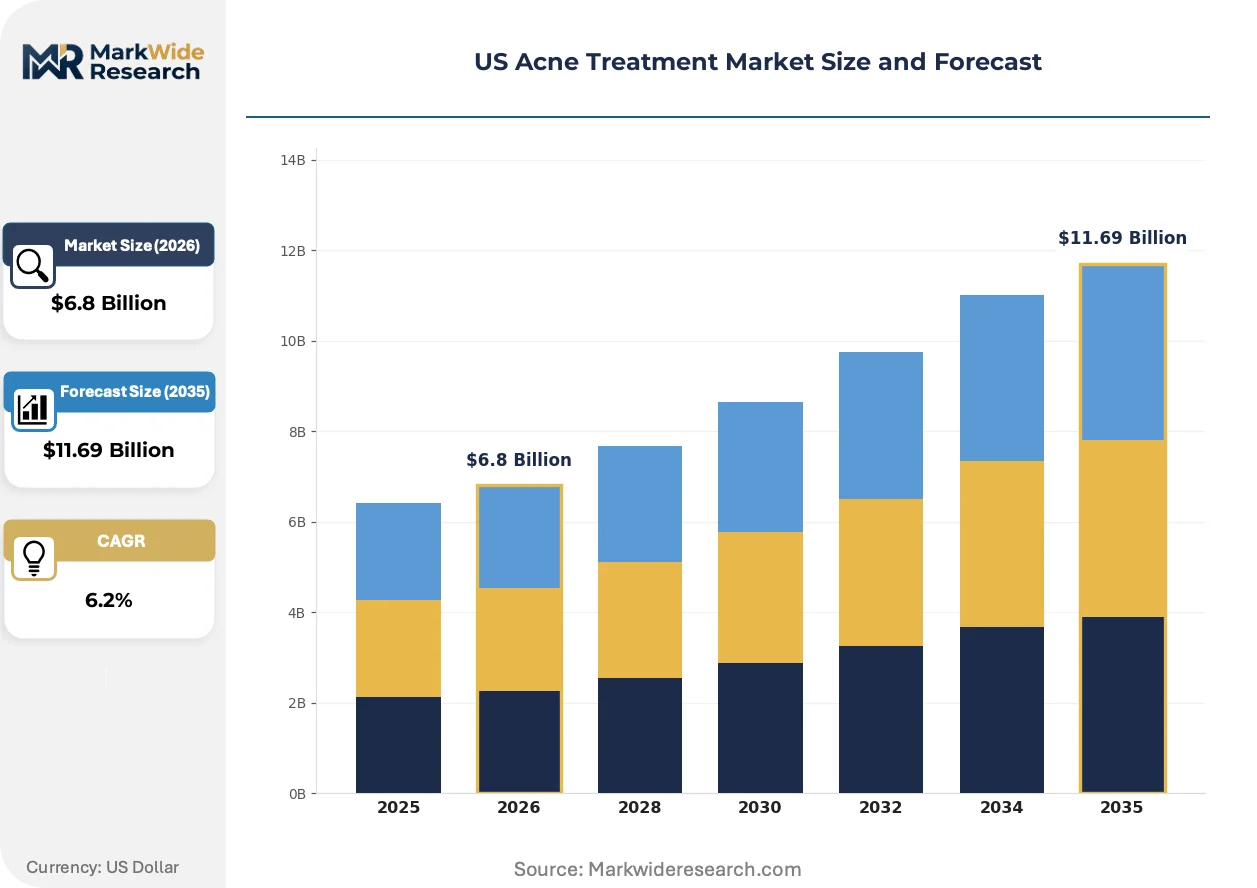
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Antibiotics, Retinoids, Salicylic Acid, Benzoyl Peroxide Application: Mild Acne, Moderate Acne, Severe Acne, Scarring Prevention, Hyperpigmentation Control End User: Dermatology Clinics, Pharmacies, Beauty Salons, Online Retailers, Telehealth Platforms Distribution Channel: Prescription Sales, Over-the-Counter, E-commerce, Specialty Stores, Mail Order |
| Companies Covered | CeraVe, Differin, Neutrogena, Galderma, Johnson & Johnson, Hero Cosmetics, La Roche-Posay, Proactiv, Panoxyl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Acne Treatment Market Strategic Shifts & Innovations
Formulation science and distribution architecture are diverging from legacy dermatology practice patterns. Three developments are restructuring competitive positioning.
Microencapsulated benzoyl peroxide enables controlled release and reduced irritation while maintaining antimicrobial efficacy. Mass-market skincare buyers adopt these advanced formulations at accelerating velocity. The technology is bifurcating the retail segment between stabilized premium offerings and commodity peroxide creams.
FDA's ongoing review of topical retinoid safety profiles is elevating documentation requirements for teratogenicity warnings and phototoxicity studies. Manufacturers face extended approval timelines and reformulation costs. Prescription-grade channels absorb the compliance burden while OTC retinoid alternatives face labeling restrictions.
Subscription-based regimen delivery displaces episodic pharmacy purchasing for maintenance-phase patients. Direct-to-consumer platforms capture recurring revenue from adolescents and young adults. This shift concentrates in suburban markets where dermatologist access friction sustains asynchronous care adoption.
US Acne Treatment Market Segmentation
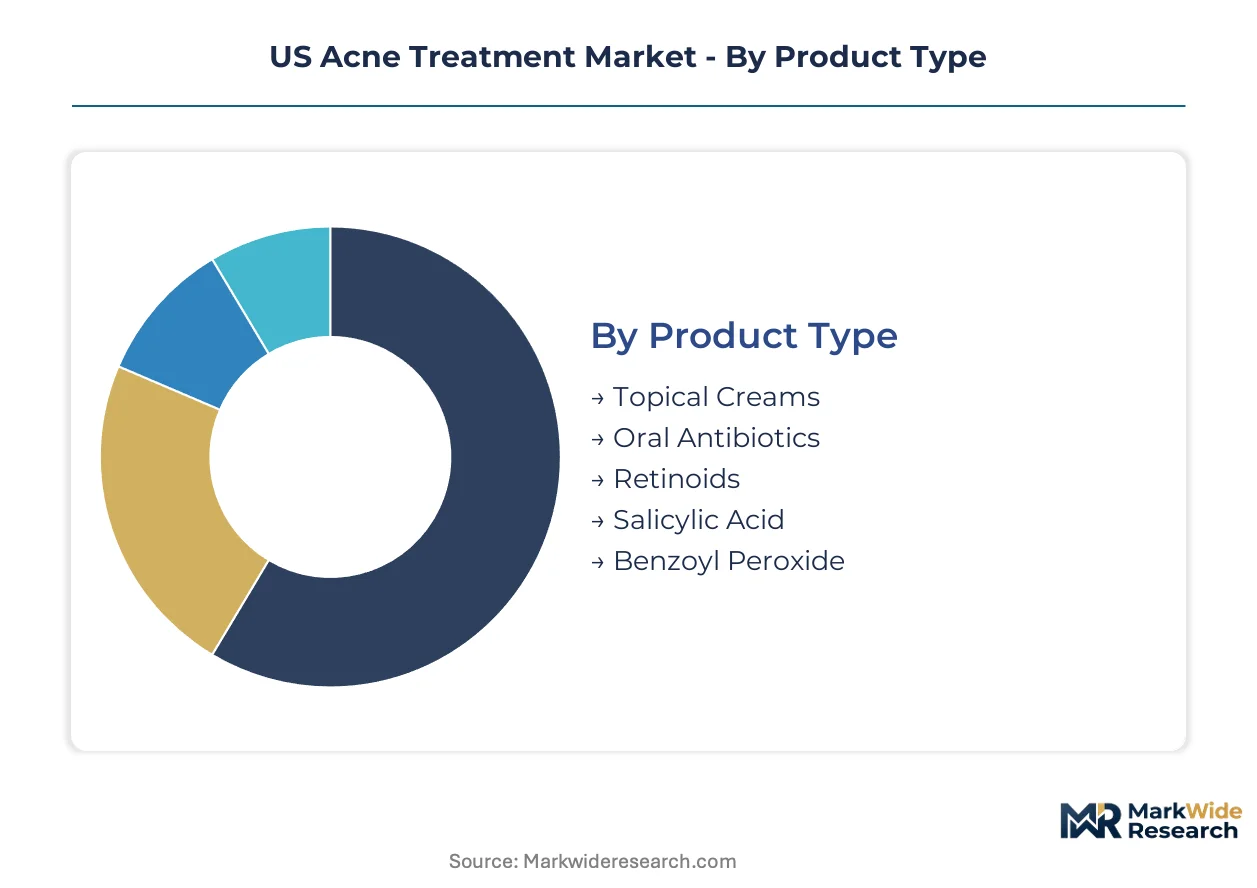
Segmentation reveals how margin pools concentrate across intervention modalities and access channels. Treatment intensity, reimbursement pathways, and patient acquisition costs diverge sharply across these dimensions.
Product Type:
Prescription retinoids command premium pricing through dermatologist gatekeeping, while benzoyl peroxide volumes flow through mass retail.
- Topical Creams:Water-based and emulsion formulations deliver antimicrobial and anti-inflammatory actives directly to pilosebaceous units. Demand clusters in suburban Texas and Florida pharmacy chains where humid climate sustains high turnover for maintenance regimens.
- Retinoids:Vitamin A derivatives require photostabilized delivery systems and teratogenicity warnings under FDA oversight. Specialist channels in urban academic medical centers absorb the compliance burden while capturing premium margins from severe acne cases.
- Oral Antibiotics:Systemic tetracycline-class therapies face DEA scheduling pressure and stewardship restrictions.
- Salicylic Acid:Beta-hydroxy acid keratolytics dominate OTC shelves through comedolytic action.
- Benzoyl Peroxide:EPA-registered manufacturing requirements constrain domestic capacity for this antimicrobial staple.
Topical creams hold installed capacity. Retinoids are rotating up the share rankings.
Application:
Clinical severity stratification determines intervention intensity and reimbursement eligibility.
- Severe Acne:Nodulocystic presentations require isotretinoin or combination oral therapies with mandatory risk management protocols. Texas dermatology clinics report patient volumes exceeding specialist capacity, driving telehealth platform expansion for prescription management.
- Hyperpigmentation Control:Post-inflammatory melanin deposition drives cosmetic-tier pricing above medical clearance indications. Florida's diverse patient demographics sustain disproportionate demand for tyrosinase-inhibiting adjunct therapies.
- Mild Acne:Comedonal presentations respond to OTC monograph formulations.
- Moderate Acne:Inflammatory papules and pustules bridge prescription and retail channels.
- Scarring Prevention:Early intervention protocols target at-risk populations before collagen remodeling defects manifest.
Severe acne anchors specialist revenue. Hyperpigmentation control is expanding most quickly as cosmetic positioning unlocks direct-to-consumer channels.
End User:
Channel selection determines patient acquisition economics and regulatory exposure.
- Telehealth Platforms:Asynchronous prescribing models compress dermatology visit patterns through nurse practitioner scope expansion in permissive states. Rural counties lacking specialist density drive fastest adoption where state regulations accommodate remote prescription authority.
- Dermatology Clinics:Brick-and-mortar specialists retain procedural revenue from chemical peels and laser interventions while ceding maintenance-phase prescriptions to digital competitors.
- Pharmacies:Traditional dispensing faces foot traffic erosion from subscription-based regimen delivery.
- Online Retailers:Direct-to-consumer platforms capture recurring revenue through automated refill algorithms.
- Beauty Salons:Aesthetic practitioners operate below medical scope for superficial extraction services.
Telehealth platforms are gaining share fastest. Dermatology clinics defend position through procedural differentiation.
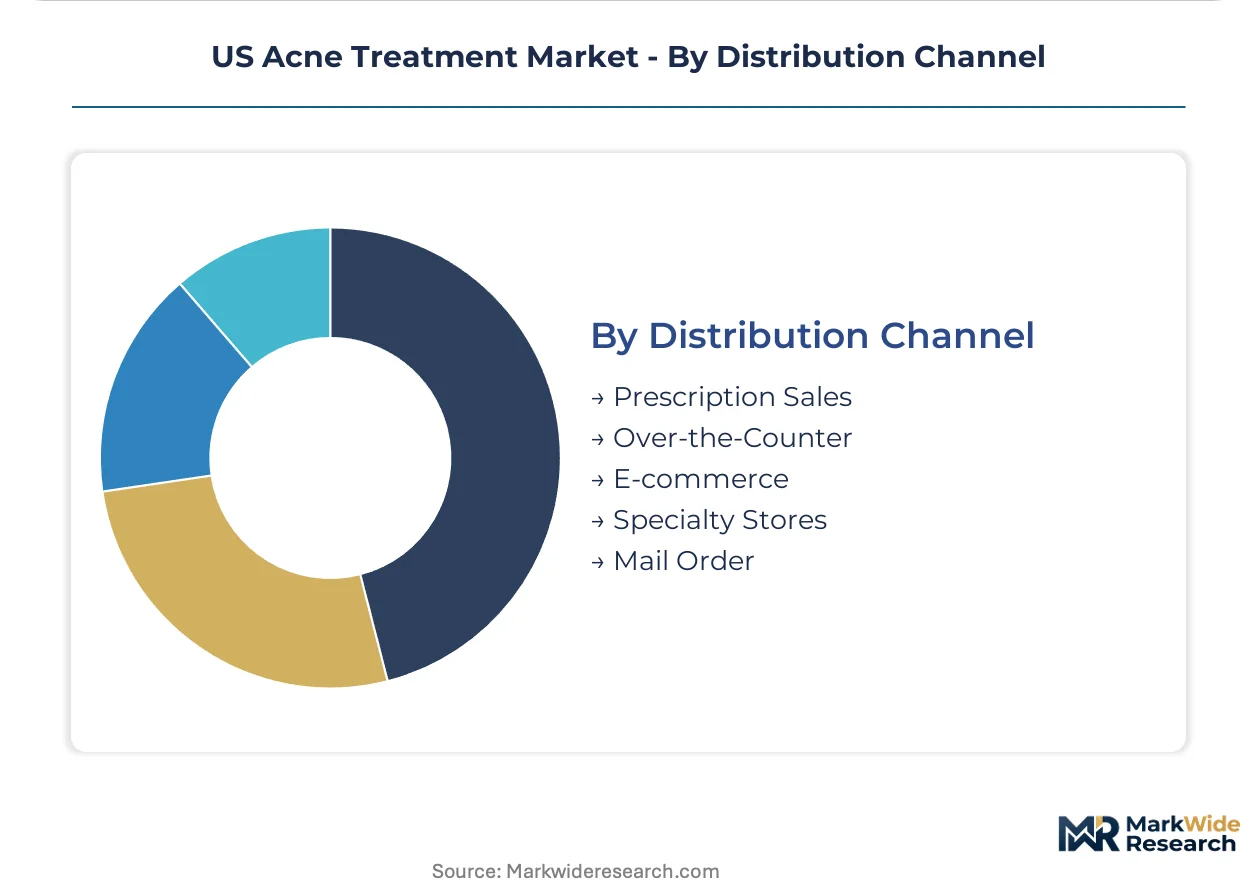
Distribution Channel:
Channel mix determines pricing power and patient adherence monitoring capabilities.
- E-commerce:Subscription-based regimen delivery displaces episodic pharmacy purchasing through automated replenishment algorithms. Suburban markets with dermatologist access friction sustain highest adoption velocity for adolescent and young adult cohorts.
- Prescription Sales:Physician-dispensed and pharmacy-fulfilled channels retain premium margin concentration through insurance adjudication and prior authorization workflows.
- Over-the-Counter:Mass retail shelves face bifurcation between stabilized premium formulations and commodity peroxide creams.
- Specialty Stores:Prestige skincare boutiques capture cosmetic-tier positioning above drugstore tiers.
- Mail Order:90-day supply fulfillment reduces per-unit dispensing costs for maintenance regimens.
Prescription sales hold installed capacity. E-commerce is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of topical retinoid safety profiles and benzoyl peroxide manufacturing standards anchors treatment access patterns across US sub-regions. State-level scope-of-practice regulations for nurse practitioners create divergent telehealth penetration rates. Humid climate zones sustain elevated sebaceous activity and corresponding demand intensity.
Texas
Large youth populations in Houston and Dallas-Fort Worth sustain high treatment volumes through humid climate-driven sebaceous activity. Texas Medical Board regulations governing telehealth prescribing authority expand asynchronous care models into rural counties lacking dermatologist density. The Austin-San Antonio corridor concentrates specialty clinic expansion as patient volumes exceed metropolitan specialist capacity.
Florida
Diverse patient demographics across Miami, Tampa, and Orlando drive disproportionate demand for post-inflammatory hyperpigmentation therapies. State-level Medicaid reimbursement policies influence prescription retinoid access patterns in lower-income counties. The Southeast Florida dermatology cluster absorbs procedural revenue from chemical peels and laser interventions while ceding maintenance prescriptions to digital competitors.
California
Silicon Valley and Los Angeles Basin telehealth platforms leverage permissive scope-of-practice regulations to compress traditional dermatology visit patterns. California Air Resources Board oversight intersects with EPA registration requirements for benzoyl peroxide manufacturing facilities operating within state boundaries. The San Diego biotech corridor concentrates photostabilized retinoid formulation development through specialized chemistry capabilities.
New York Metro
High-density urban patient populations sustain prescription-grade retinoid demand through academic medical center channels. New York State Department of Health regulations on physician assistant independent prescribing create friction for asynchronous platform expansion. The Manhattan-Brooklyn dermatology corridor retains procedural differentiation against subscription-based regimen delivery competitors.
Pacific Northwest
Seattle and Portland telehealth adoption rates exceed national averages due to dermatologist workforce shortages across Washington and Oregon rural counties. State pharmacy board regulations on mail-order 90-day supply fulfillment reduce per-unit dispensing costs for maintenance regimens. The Puget Sound region concentrates e-commerce platform headquarters capturing subscription revenue from adolescent and young adult cohorts.
US Acne Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the US acne treatment market structure. Prescription-grade retinoid manufacturers command premium margins through dermatologist gatekeeping relationships. Mass-market benzoyl peroxide suppliers compete on retail shelf presence and price positioning. Three archetypes dominate: integrated pharmaceutical-skincare conglomerates, dermatologist-recommended prestige brands, and direct-to-consumer subscription platforms. Competitive moves concentrate on portfolio diversification into post-inflammatory sequelae management and geographic expansion through telehealth platform partnerships.
Among integrated pharmaceutical-skincare conglomerates, Galderma and Johnson & Johnson occupy positions spanning prescription and retail channels. Galderma represents the prescription-grade retinoid specialist archetype with dermatologist-centric distribution. Johnson & Johnson exemplifies mass-market penetration through broad retail pharmacy relationships. La Roche-Posay sits within the dermatologist-recommended prestige tier, positioned above commodity skincare price points.
| Leading Market Players |
|---|
| CeraVe |
| Differin |
| Neutrogena |
| Galderma |
| Johnson & Johnson |
| Hero Cosmetics |
| La Roche-Posay |
| Proactiv |
| Panoxyl |
| Others |
Cost & Logistics Intelligence
Photostabilized retinoid delivery systems replacing conventional benzoyl peroxide formulations are redrawing manufacturing footprints toward specialized chemistry hubs while compressing margins on commodity peroxide lines. This substitution dynamic concentrates premium pricing power in encapsulation-capable facilities while forcing cost absorption among EPA-registered domestic manufacturers.
Pricing Analysis
Texas and Florida pharmacy chains command 15-20% premiums over Pacific Northwest equivalents for identical retinoid SKUs due to humid-climate demand intensity and dermatologist access friction. Three-tier pricing structure across prescription-grade, dermatologist-recommended prestige, and mass-market economy tiers stratifies the landscape. Cost compression in benzoyl peroxide manufacturing is intensifying because EPA registration requirements constrain domestic capacity expansion. Adolescent and young adult maintenance-phase patients exhibit highest price sensitivity, while severe acne cases seeking isotretinoin demonstrate lowest elasticity.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for tetracycline-class oral antibiotics and salicylic acid precursors, while Switzerland and France concentrate photostabilized retinoid formulation chemistry. Domestic U.S. manufacturing draws from imported API streams for benzoyl peroxide synthesis, with EPA-registered facilities in Texas and New Jersey serving as final formulation points. Single-source vulnerability in encapsulation-grade polymer supply creates chokepoint exposure for premium retinoid delivery systems. Distribution runs through three-tier architecture: direct-to-consumer subscription platforms, dermatologist-dispensed channels, and mass retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth platform interoperability with electronic health record systems is creating network-effect moats that reshape patient acquisition economics and subscription retention curves.
For Market Incumbents: Shield prescription-grade retinoid margins by deepening dermatologist gatekeeping relationships through proprietary photostabilization IP. Acquire or partner with telehealth platforms in Texas and Florida to capture asynchronous prescribing volume before nurse practitioner scope expansion fully commoditizes remote diagnosis. Vertical integration into encapsulation chemistry capabilities protects against contract manufacturer scarcity. For New Entrants and Emerging Players: FDA OTC monograph fast-track pathways for microencapsulated benzoyl peroxide formulations offer expedited market entry below prescription-grade compliance burdens. Target hyperpigmentation control segments in Florida's diverse demographic corridors where cosmetic-tier pricing exceeds medical clearance margins. Deploy direct-to-consumer subscription models with automated refill algorithms to capture adolescent maintenance-phase loyalty. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors telehealth-enabled prescription management over brick-and-mortar procedural differentiation. Long-term viability hinges on asynchronous care adoption curves and EPA manufacturing capacity constraints. Acquisition target archetype: regional telehealth platforms with nurse practitioner prescribing authority in permissive states. Monitor DEA scheduling discussions around oral antibiotics as inflection signal for combination topical therapy acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photostabilized Retinoid Formulation Partnership | Encapsulation chemistry alliances with Swiss and French specialty manufacturers secure premium-tier supply. |
| Nurse Practitioner Scope Expansion Lobbying | State-level regulatory engagement in Texas and Florida unlocks telehealth prescribing authority for asynchronous platforms. |
| Post-Inflammatory Sequelae Product Line Extension | Tyrosinase-inhibiting adjunct therapies capture cosmetic-tier pricing above medical clearance indications. |
| EPA Manufacturing Facility Certification | Domestic benzoyl peroxide production capacity shields against import dependency and registration delays. |
| Subscription-Based Regimen Delivery Platform | Automated replenishment algorithms capture recurring revenue from maintenance-phase patient cohorts. |
Research Approach
Desk research of FDA OTC monograph filings, EPA registration databases, and state medical board telehealth regulations preceded structured interviews with dermatology practice administrators, telehealth platform executives, formulary directors at pharmacy benefit managers, and procurement leads at mass retail chains. Secondary validation drew from CMS Medicare Part D utilization data, state-level scope-of-practice legislation trackers, and clinical trial registries for photostabilized retinoid formulations. Bottom-up patient volume modeling and top-down pharmaceutical shipment analysis were triangulated against channel-specific pricing surveys.
Variance decomposition across product type, application severity, end-user channel, and distribution modality shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include intervention modality, reimbursement pathway, patient acquisition channel, and regional regulatory cluster. CAGRs were derived from patient volume trajectories, pricing elasticity coefficients, and channel mix shift assumptions. Forecast inputs incorporated humid-climate demand intensity indices and nurse practitioner prescribing authority expansion timelines.
Underlying assumptions cover EPA manufacturing capacity stability, telehealth regulatory permissiveness continuity, and retinoid safety profile review outcomes, with deviation risk concentrated in DEA scheduling decisions for oral antibiotics and state-level scope-of-practice reversals. Recalibration cycles align with material shifts in FDA monograph reform timelines and asynchronous prescribing volume thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Scar Removal Treatment Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Personalized Skin Care Products Market
Skincare
Skin Resurfacing Market
Skincare
Sun-Care Wipes Market
Skincare
Facial Mask Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Retinol Skincare Product Market
Skincare
Professional Skin Care Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Natural Skin Care Products Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Skin Bioactive Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Facial Erythema Treatment Market