
 Methylphenidate Hydrochloride Market | 2026-2036
Methylphenidate Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Methylphenidate Hydrochloride Market Insights
Specialist psychiatrist availability is rotating unevenly across regions, constraining market penetration in underserved areas while concentrating prescription authority in urban medical corridors. Novartis Pharmaceuticals leverages its extended-release formulation heritage to sustain brand loyalty among pediatric prescribers. Teva Pharmaceutical Industries competes through generic breadth across multiple dosage forms, while Sun Pharmaceutical Industries anchors its position through cost-efficient manufacturing serving price-sensitive markets.
Methylphenidate hydrochloride is a central nervous system stimulant with the chemical formula C14H19NO2·HCl, functioning primarily as a dopamine and norepinephrine reuptake inhibitor formulated into tablets, extended-release capsules, oral solutions, and transdermal patches for controlled delivery. Its primary commercial purpose lies in managing attention deficit hyperactivity disorder and narcolepsy through regulated symptomatic treatment protocols. Extended-release capsules command premium positioning due to compliance advantages and reduced dosing frequency, while the therapy area segmentation reveals ADHD as the mature revenue core with cognitive disorders representing an emerging frontier. Distribution through hospital pharmacies dominates institutional prescribing, though online pharmacies are gaining structural share as digital health infrastructure matures.
The FDA's REMS framework for stimulant medications shapes dispensing logistics and patient access protocols, while the DEA's production quota system directly constrains active pharmaceutical ingredient allocation across manufacturers. China's NMPA maintains distinct approval pathways for psychotropic substances that limit import velocity. Stakeholders must monitor evolving controlled-substance scheduling debates and digital therapeutics integration as alternative interventions gain regulatory traction.
Market Dynamics
The DEA's annual production quota system for Schedule II controlled substances functions as the dominant structural force, directly constraining API allocation across manufacturers and creating artificial scarcity that shapes competitive positioning and pricing power throughout the value chain.
Growth Catalysts
- Extended-Release Formulation Demand:Pediatric psychiatrists increasingly prescribe once-daily dosing regimens to improve compliance and reduce school-day administration burden, driving volume toward higher-margin delivery technologies.
- Digital Health Infrastructure Maturity:Telehealth prescribing protocols established during the pandemic persist in expanding prescriber reach into rural and underserved counties where specialist availability previously limited diagnosis.
- FDA REMS Framework Evolution:Streamlined patient monitoring requirements for established stimulant therapies reduce administrative friction for certified prescribers, accelerating refill authorization workflows.
Market Restraints
- API Supply Concentration:Bulk methylphenidate production concentrates among a limited set of specialized chemical manufacturers, creating vulnerability to single-source disruption or quota reallocation decisions.
- Controlled Substance Scheduling Friction:International harmonization gaps between DEA Schedule II classification and varying national psychotropic schedules complicate cross-border formulation licensing and commercialization timelines.
- Non-Stimulant Substitution Threat:Atomoxetine and guanfacine extended-release alternatives gain traction among parents and adult patients seeking non-controlled options, particularly in markets with strict dispensing logistics.
Strategic Opportunities
- Transdermal Patch Penetration:The patch delivery segment remains underdeveloped relative to oral formulations, presenting white space for differentiated abuse-deterrent positioning in adolescent populations.
- Cognitive Disorder Label Expansion:Emerging clinical protocols for residual cognitive impairment in traumatic brain injury and stroke recovery populations represent adjacent therapeutic applications beyond established ADHD and narcolepsy indications.
- Specialty Pharmacy Channel Development:Direct-to-patient distribution through accredited specialty pharmacies bypasses traditional retail constraints and enables enhanced adherence monitoring programs.
Industry Challenges
- Pediatric Psychiatrist Workforce Scarcity:Fellowship-trained child and adolescent psychiatry specialists remain concentrated in urban academic medical centers, limiting prescriptive authority diffusion into community practice settings.
- REMS Compliance Infrastructure Burden:Mandatory prescriber certification, patient registry maintenance, and periodic retraining requirements impose ongoing operational costs that scale inefficiently for smaller practice groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methylphenidate Hydrochloride Market |
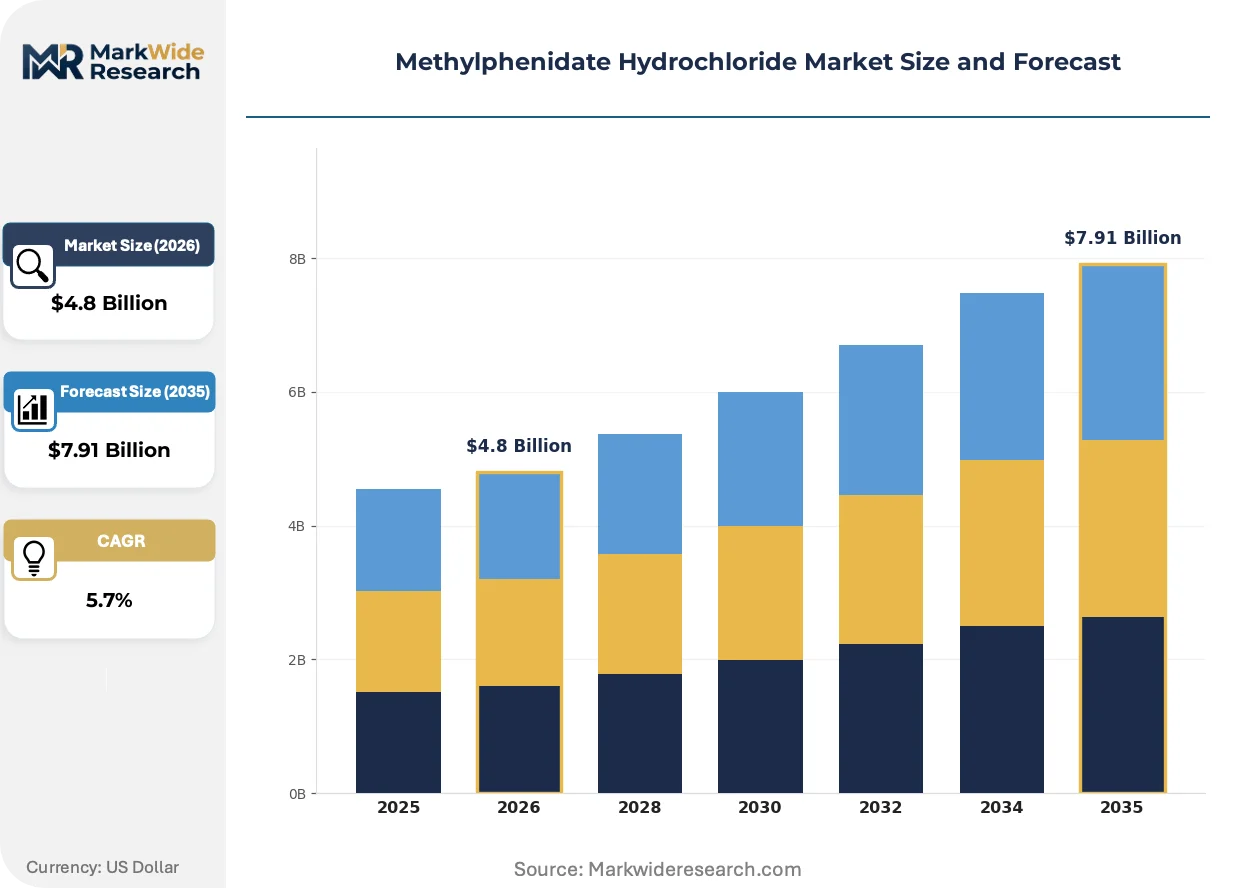
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Extended-Release Capsules, Oral Solution, Transdermal Patch Therapy Area: Attention Deficit Hyperactivity Disorder, Narcolepsy, Depression, Cognitive Disorders End User: Pediatric Patients, Adult Patients, Caregivers, Healthcare Providers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Clinics |
| Companies Covered | Novartis Pharmaceuticals, Takeda Pharmaceutical, Teva Pharmaceutical Industries, Mallinckrodt Pharmaceuticals, Sun Pharmaceutical Industries, Tonghua Renmin Pharmaceutical, China Resources Shuanghe Pharmaceutical, Janssen Pharmaceuticals, Noramco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methylphenidate Hydrochloride Market Trends and Innovations
Formulation science and digital therapeutics convergence are actively restructuring how methylphenidate therapies reach patients, with delivery mechanism innovation outpacing molecular modification as the primary vector of competitive differentiation.
Osmotic-controlled release oral system technology is displacing conventional matrix-based extended-release formulations in premium prescribing segments. Academic medical centers and large pediatric group practices have accelerated adoption of OROS-enabled products over the past five years. This shift is compressing margins on commodity extended-release capsules while rewarding manufacturers with proprietary osmotic platform expertise.
The FDA's Risk Evaluation and Mitigation Strategy for extended-release and long-acting opioid and stimulant formulations continues tightening patient access documentation requirements. Industrial consequence includes mandatory pharmacy-level verification systems and locked dispensing cabinets that increase per-prescription fulfillment costs. Pediatric-focused practices in high-diagnosis states have responded by consolidating prescribing authority within certified nurse practitioners to maintain patient throughput.
Direct-to-consumer telehealth platforms now facilitate initial ADHD screening and stimulant prescribing without traditional in-person psychiatric evaluation. This channel disruption replaces primary care physician gatekeeping with asynchronous clinician-patient matching algorithms. The shift is most visible in states with full practice authority for nurse practitioners and relaxed controlled substance telehealth prescribing waivers.
Methylphenidate Hydrochloride Market Segmentation
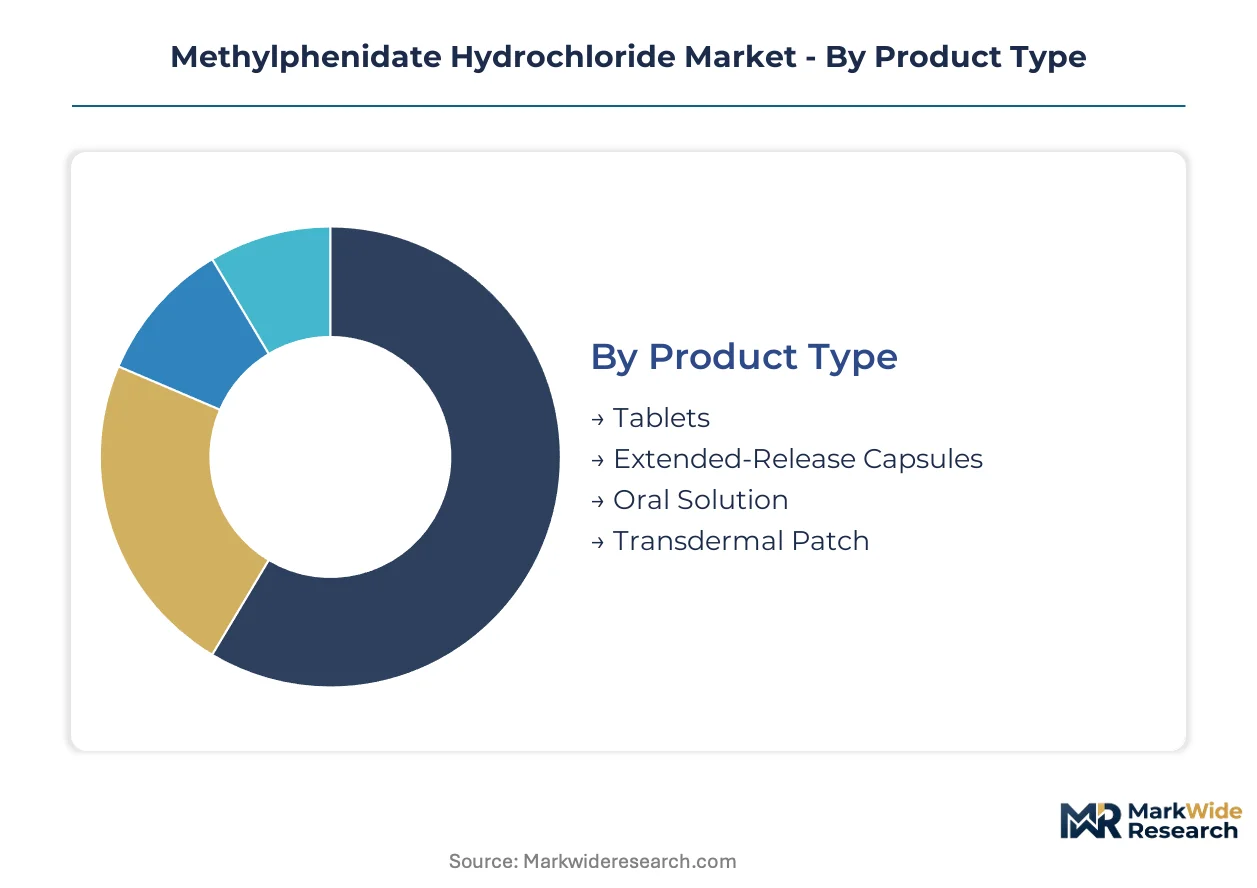
Methylphenidate hydrochloride's controlled-substance scheduling creates distinct margin architectures across delivery mechanisms, with formulation technology serving as the primary value differentiator rather than molecular innovation. Segmentation reveals how DEA quota constraints and prescriber certification requirements concentrate profitability in specific patient populations and channel configurations.
Product Type:
Margin pools concentrate in extended-release technologies where osmotic-controlled release systems command pricing premiums over conventional matrix formulations, while transdermal delivery remains underpenetrated relative to its abuse-deterrent potential.
- Extended-Release Capsules:OROS-enabled formulations utilize osmotic pressure differentials for zero-order drug release over 8-12 hours, eliminating midday school administration. Pediatric psychiatrists in high-diagnosis states prefer these for compliance advantages, though DEA quota allocation limits manufacturer expansion.
- Tablets:Immediate-release tablets deliver rapid onset with 3-4 hour duration requiring multiple daily doses. Demand concentrates in price-sensitive Medicaid populations and adult patients with flexible dosing requirements where cost constraints override convenience preferences.
- Oral Solution:Liquid formulations enable precise titration for patients with swallowing difficulties or those requiring dose flexibility during initial therapeutic optimization.
- Transdermal Patch:Daytrana and generic equivalents provide 9-hour wear time with peel-off abuse deterrence, finding niche adoption among parents concerned about diversion in adolescent populations.
Extended-release capsules hold installed capacity. Transdermal patch is rotating up the share rankings.
Therapy Area:
Volume concentration diverges sharply from value concentration, with ADHD representing mature prescription density while cognitive disorder applications command exploratory investment despite smaller current revenue bases.
- Attention Deficit Hyperactivity Disorder:The established indication accounts for the majority of commercial volume, with diagnostic expansion in adult populations extending the addressable patient base beyond the traditional pediatric focus. FDA REMS compliance infrastructure scales efficiently across this large prescriber base.
- Cognitive Disorders:Emerging protocols for post-stroke cognitive rehabilitation and traumatic brain injury residual impairment represent the steepest expansion trajectory, though reimbursement pathways remain unsettled and clinical evidence requirements are substantial.
- Narcolepsy:Modafinil and sodium oxybate competition limits methylphenidate penetration in this indication, with prescribing concentrated among sleep medicine specialists rather than general psychiatrists.
- Depression:Off-label augmentation therapy for treatment-resistant depression occupies a narrow niche, constrained by stimulant mood-destabilization concerns and non-stimulant antidepressant pipeline expansion.
ADHD maintains the volume foundation. Cognitive disorders are climbing the fastest among emerging applications.
End User:
Prescriptive authority distribution shapes demand concentration, with pediatric patient segments driving refill frequency while adult diagnosis expansion broadens the prescriber base beyond child and adolescent psychiatry specialists.
- Pediatric Patients:Children aged 6-17 represent the core demographic with highest diagnosis rates and strongest caregiver-driven compliance incentives. School-based behavioral assessment protocols in the United States accelerate identification and treatment initiation.
- Adult Patients:Retrospective diagnosis in adults aged 18-45 is expanding most quickly as workplace productivity framing reduces stigma, with telehealth platforms enabling access without traditional psychiatric referral barriers.
- Caregivers:Parental and spousal medication management influences formulation selection, with once-daily dosing preferred by working caregivers managing complex morning routines.
- Healthcare Providers:Prescriber segmentation between pediatric psychiatrists, general psychiatrists, and certified nurse practitioners determines dosing patterns and brand-generic substitution rates.
Pediatric patients anchor prescription volume. Adult patients are gaining share fastest among user categories.
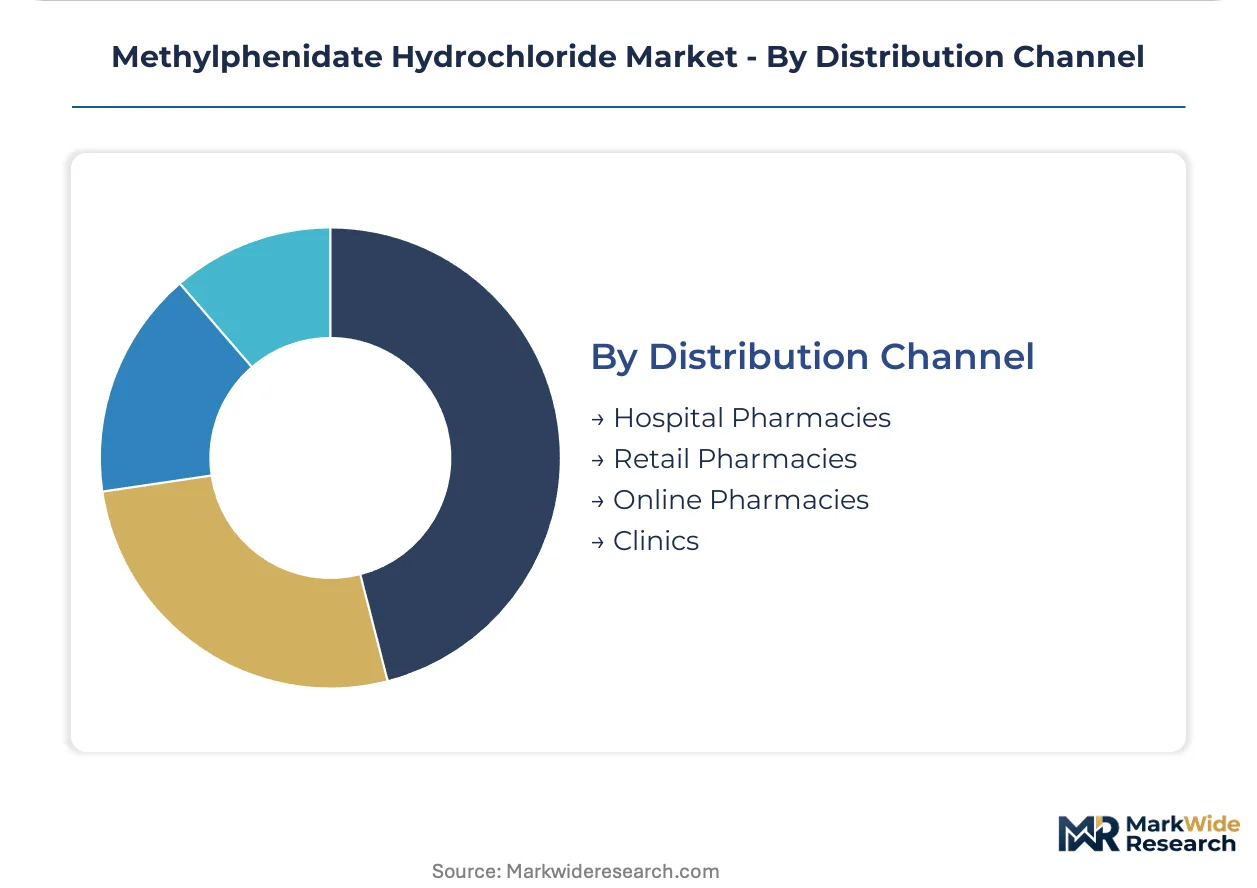
Distribution Channel:
Channel economics reflect controlled-substance handling requirements, with hospital pharmacies capturing institutional volume while online pharmacies reshape geographic access patterns.
- Hospital Pharmacies:Academic medical centers and children's hospitals with embedded ADHD clinics capture high-volume institutional prescribing, with locked dispensing infrastructure satisfying DEA security requirements.
- Online Pharmacies:Telehealth-integrated digital pharmacies bypass traditional retail constraints, expanding fastest in states with full nurse practitioner prescribing authority and relaxed controlled substance telehealth waivers.
- Retail Pharmacies:CVS, Walgreens, and independent chains handle the majority of refill volume, with mandatory pharmacy-level verification systems increasing per-prescription fulfillment costs.
- Clinics:On-site dispensing at high-volume ADHD specialty practices enables same-day initiation and adherence monitoring, though regulatory complexity limits this model's geographic spread.
Hospital pharmacies dominate institutional volume. Online pharmacies are expanding most quickly among channel alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's REMS framework and DEA production quotas anchor the United States as the dominant geography, with diagnosis rates and prescriptive authority concentrating demand in specific metropolitan corridors while regulatory fragmentation shapes access patterns elsewhere.
United States
Pediatric diagnosis expansion and adult retrospective identification drive prescription volume, particularly in high-income suburbs with embedded ADHD specialty practices. FDA REMS compliance infrastructure and DEA Schedule II quotas constrain API allocation and create artificial scarcity. Prescribing concentrates in Boston-Cambridge, New York Metro, and Los Angeles medical corridors where child and adolescent psychiatry specialists cluster.
Germany
Adult ADHD recognition and workplace productivity framing accelerate diagnosis among professionals aged 25-45. EMA centralized procedures and BfArM federal oversight maintain strict psychotropic dispensing protocols. Manufacturing and distribution cluster in Baden-Württemberg and North Rhine-Westphalia, with Stuttgart and Cologne serving as logistics hubs for continental European supply.
China
Urban pediatric behavioral health awareness and rising middle-class diagnostic demand expand the addressable patient base in tier-1 cities. NMPA maintains distinct approval pathways for psychotropic substances that limit import velocity and favor domestic manufacturers. Production concentrates in Jilin Province and Jiangsu Province, with Changchun and Suzhou housing active pharmaceutical ingredient facilities serving regional formulation demand.
India
Cost-efficient generic manufacturing and export-oriented API production position the country as a supply-side anchor for price-sensitive markets. CDSCO scheduling aligns with international controlled substance frameworks while permitting domestic formulation flexibility. Pharmaceutical manufacturing clusters in Gujarat and Maharashtra, with Ahmedabad and Mumbai serving as export gateways for methylphenidate hydrochloride intermediates.
Canada
Adult diagnosis expansion and telehealth prescribing integration reshape access patterns beyond traditional psychiatric referral pathways. Health Canada and PMRA maintain harmonized scheduling with DEA classifications while permitting province-level dispensing variation. Prescriptive authority concentrates in Ontario and British Columbia, with Toronto and Vancouver medical centers driving specialist referral networks.
Methylphenidate Hydrochloride Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary extended-release formulation expertise commanding premium positioning while generic breadth captures volume in price-sensitive segments. The market exhibits tiered consolidation around osmotic delivery platforms, with mid-scale manufacturers competing on API efficiency and regional licensing agility. Three archetypes dominate: originators with platform patents, integrated generic houses with vertical API control, and regional specialists with localized regulatory navigation. Competitive moves concentrate on formulation licensing partnerships and quota allocation lobbying rather than direct price confrontation.
Among Swiss-origin pharmaceutical conglomerates, Novartis Pharmaceuticals occupies a position exemplifying proprietary osmotic-controlled release heritage and pediatric prescriber loyalty. Israeli-headquartered Teva Pharmaceutical Industries represents the generic breadth archetype, spanning multiple dosage forms and leveraging manufacturing scale across controlled substance categories. Sun Pharmaceutical Industries anchors the cost-efficient manufacturing tier, serving price-sensitive markets through API-to-formulation integration and emerging market regulatory expertise.
| Leading Market Players |
|---|
| Novartis Pharmaceuticals |
| Takeda Pharmaceutical |
| Teva Pharmaceutical Industries |
| Mallinckrodt Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Tonghua Renmin Pharmaceutical |
| China Resources Shuanghe Pharmaceutical |
| Janssen Pharmaceuticals |
| Noramco |
| Others |
Pricing and Supply Chain Analysis
OROS-enabled formulation displacement of conventional matrix-based extended-release capsules is redrawing supply geography toward osmotic platform specialists in the United States and Switzerland while compressing margins on commodity extended-release products. This substitution dynamic concentrates pricing power with manufacturers possessing proprietary osmotic technology, leaving matrix-formulation producers exposed to DEA quota volatility and generic price erosion.
Pricing Analysis
Geographic price spreads widen between DEA-constrained United States markets and price-sensitive Indian and Chinese domestic markets, with OROS-enabled formulations commanding substantial premiums over matrix-based alternatives. Three-tier pricing structure across proprietary osmotic, licensed extended-release, and immediate-release generic levels reflects formulation complexity and prescriber certification requirements. Pricing pressure stems from DEA production quota reallocation decisions that artificially constrain API supply. Medicaid populations and adult patients with flexible dosing requirements exhibit highest price sensitivity, while pediatric psychiatrists in high-diagnosis states show lowest sensitivity due to compliance-driven formulation preferences.
Supply Chain Analysis
Inbound logistics costs for methylphenidate API shipments from Indian and Chinese chemical manufacturers to United States formulation facilities fluctuate with container availability on Asia-Pacific trade lanes and port congestion at Los Angeles-Long Beach. Bulk API production concentrates in India, China, and the United States, with Jilin Province and Gujarat housing specialized controlled-substance chemical manufacturers. The supply chain rests on piperidine derivative precursors and specialized osmotic membrane components subject to international precursor control regimes. Single-source vulnerability characterizes OROS platform technology licensing. Distribution runs through hospital pharmacies, accredited specialty pharmacies, and telehealth-integrated digital pharmacies with DEA-compliant locked dispensing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pediatric group practices and telehealth platforms that aggregate patient volume, fragmenting traditional prescriber authority and compressing manufacturer negotiating leverage.
For Market Incumbents: Fortify proprietary osmotic platform positions through backward integration into specialized membrane component production and expansion of DEA quota allocation lobbying capacity. Non-stimulant substitution threats from atomoxetine and guanfacine alternatives demand enhanced prescriber education investments. Priority lever centers on certification infrastructure scaling to maintain patient throughput under evolving FDA REMS frameworks. For New Entrants and Emerging Players: Differentiate on transdermal patch abuse-deterrent positioning in adolescent populations where parental diversion concerns create willingness to pay premiums. The most penetrable white space sits in cognitive disorder label expansion for post-stroke and traumatic brain injury applications with unsettled reimbursement pathways. Go-to-market angle should leverage specialty pharmacy direct-to-patient distribution to bypass retail pharmacy verification bottlenecks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated API-to-formulation operators with DEA quota access and pediatric prescriber loyalty. Long-term viability hinges on regulatory navigation capabilities across FDA REMS and international psychotropic scheduling harmonization. Acquisition target archetype includes mid-scale manufacturers with osmotic platform licensing potential. Signal to watch is digital therapeutics integration traction as alternative intervention modality.| Strategic Initiative | Industry Significance |
|---|---|
| OROS Platform Licensing Agreement | Proprietary osmotic technology access secures premium positioning with pediatric psychiatrists in high-diagnosis states. |
| DEA Quota Allocation Expansion | Increased API authorization directly enables volume growth in supply-constrained Schedule II controlled substance markets. |
| Specialty Pharmacy Partnership | Direct-to-patient distribution bypasses retail verification costs and enables adherence monitoring program deployment. |
| Cognitive Disorder Clinical Trial Advancement | Post-stroke and TBI label expansion opens adjacent therapeutic applications beyond mature ADHD revenue core. |
| Transdermal Patch Manufacturing Scale-Up | Abuse-deterrent delivery format addresses parental diversion concerns in adolescent patient populations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric psychiatrists, formulary directors at children's hospitals, DEA-registered API manufacturers, and specialty pharmacy operations executives. Secondary validation drew from FDA REMS documentation, DEA production quota publications, ClinicalTrials.gov protocol registries, and CMS Medicaid prescription data. Bottom-up prescription volume modeling triangulated against top-down manufacturer capacity assessments.
Across the analysis window, forecasts integrated patient population epidemiology, prescriber density by metropolitan corridor, and DEA quota trajectory assumptions. Segmentation dimensions modeled encompassed formulation technology, therapy area indication, patient age demographic, and distribution channel regulatory cluster. CAGRs derived from prescription volume trend extrapolation adjusted for diagnosis rate elasticity and non-stimulant substitution coefficients. Forecast inputs included FDA REMS compliance cost inflation and telehealth prescribing waiver persistence.
Decision-makers should treat outputs as directional under stable DEA scheduling and REMS framework assumptions; material deviation in controlled substance policy or digital therapeutics reimbursement would warrant model refresh. Forecasts reflect documented base-case assumptions regarding pediatric diagnosis expansion and adult retrospective identification rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market