
 Global Acne Medication Market | 2026-2036
Global Acne Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acne Medication Market Foresight
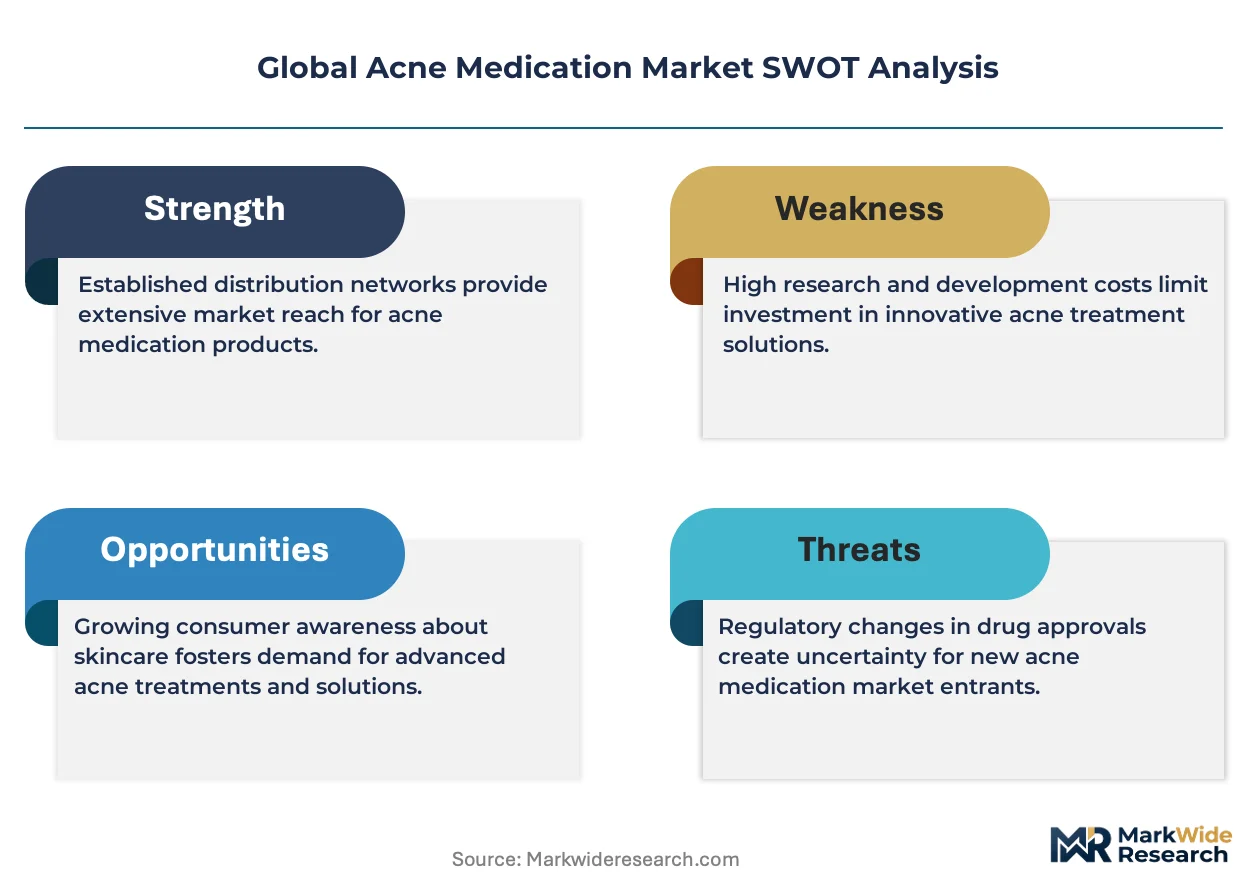
Online pharmacies is rewriting how acne medications reach patients, bypassing traditional retail gatekeepers with direct-to-consumer fulfillment and telehealth integrations. Galderma S.A. leverages its dermatology-focused portfolio to sustain premium positioning across prescription topical agents. Johnson & Johnson Services, Inc. anchors mass-market access through retail pharmacy shelf dominance and consumer brand recognition. Sun Pharmaceutical Industries Ltd. competes aggressively on cost-engineered generics, particularly in oral antibiotic categories.
Acne medication encompasses pharmaceutical and device-based interventions formulated to reduce sebum production, normalize follicular keratinization, and control Cutibacterium acnes colonization, typically delivered via topical gels, oral tablets, or narrow-band light systems. The primary commercial purpose centers on treating inflammatory and non-inflammatory acne vulgaris across adolescent and adult populations, with prescription-grade formulations targeting moderate-to-severe disease and over-the-counter options addressing mild presentations. Topical agents occupy the largest revenue pool due to established tolerability profiles and first-line prescribing habits, while combination therapies represent the fastest-expanding segment as clinicians seek to mitigate antibiotic resistance through multitarget mechanisms. Oral medication retains stable demand for severe nodulocystic cases, though safety monitoring requirements limit broader expansion.
FDA oversight of retinoid teratogenicity labeling and EPA manufacturing discharge standards for benzoyl peroxide production shape formulation decisions and facility siting across the United States. EMA's MDR classification for light therapy devices and REACH chemical restrictions on certain excipients create parallel compliance burdens for European market entry. India's CDSCO and BIS standards govern import quality for active pharmaceutical ingredients, particularly salicylic acid sourced from Chinese manufacturers. Stakeholders must monitor evolving antibiotic stewardship protocols and photobiomodulation device reclassifications to anticipate shifts in reimbursable treatment pathways.
Market Dynamics
Combination therapy adoption is restructuring prescribing patterns as dermatology clinics seek to circumvent antibiotic resistance through multitarget mechanisms, while FDA retinoid safety reviews compress development timelines for new topical entrants.
Growth Catalysts
- Antibiotic Stewardship Protocols:Clinical guidelines across the United States and European Union now mandate combination regimens over monotherapy, expanding formulary slots for fixed-dose retinoid-antibiotic formulations.
- India:CDSCO streamlining of active pharmaceutical ingredient import pathways accelerates generic production scale-up for oral antibiotics serving domestic and export demand.
- Telehealth Integration:Online pharmacy platforms with embedded dermatology consultations bypass traditional retail distribution, capturing patient cohorts in Brazil and the United States previously lost to prescription abandonment.
Market Restraints
- Retinoid Teratogenicity Monitoring:FDA Risk Evaluation and Mitigation Strategy requirements impose costly post-market surveillance burdens that limit patient pool expansion for isotretinoin prescribers.
- Benzoyl Peroxide Feedstock Concentration:Chinese manufacturers control over 70% of global salicylic acid precursor supply, exposing formulators to tariff and logistics volatility.
- Light Therapy Device Reimbursement Gaps:EMA MDR classification shifts photobiomodulation systems to higher-risk categories, triggering extended clinical trial obligations that deter mid-cap device entrants.
Strategic Opportunities
- Brazil:ANVISA harmonization with FDA bioequivalence standards opens pathways for US- and EU-approved generics to enter Latin America's largest dermatology market with abbreviated review timelines.
- Microbiome-Targeted Topicals:Phage therapy and postbiotic formulations addressing Cutibacterium acnes strain specificity represent unoccupied therapeutic territory beyond conventional antibacterial mechanisms.
- Subscription Direct-to-Patient Models:Telehealth-integrated auto-refill programs for chronic mild-to-moderate acne capture lifetime value through adherence monitoring and personalized regimen adjustment.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in topical vehicle design for retinoid stability and benzoyl peroxide release kinetics concentrates among legacy dermatology-focused contract manufacturers, constraining in-house pipeline expansion.
- Cross-Border Data Fragmentation:Disconnected adverse event reporting systems between FDA FAERS, EMA EudraVigilance, and India's Pharmacovigilance Programme complicate signal detection for rare teratogenic outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acne Medication Market |
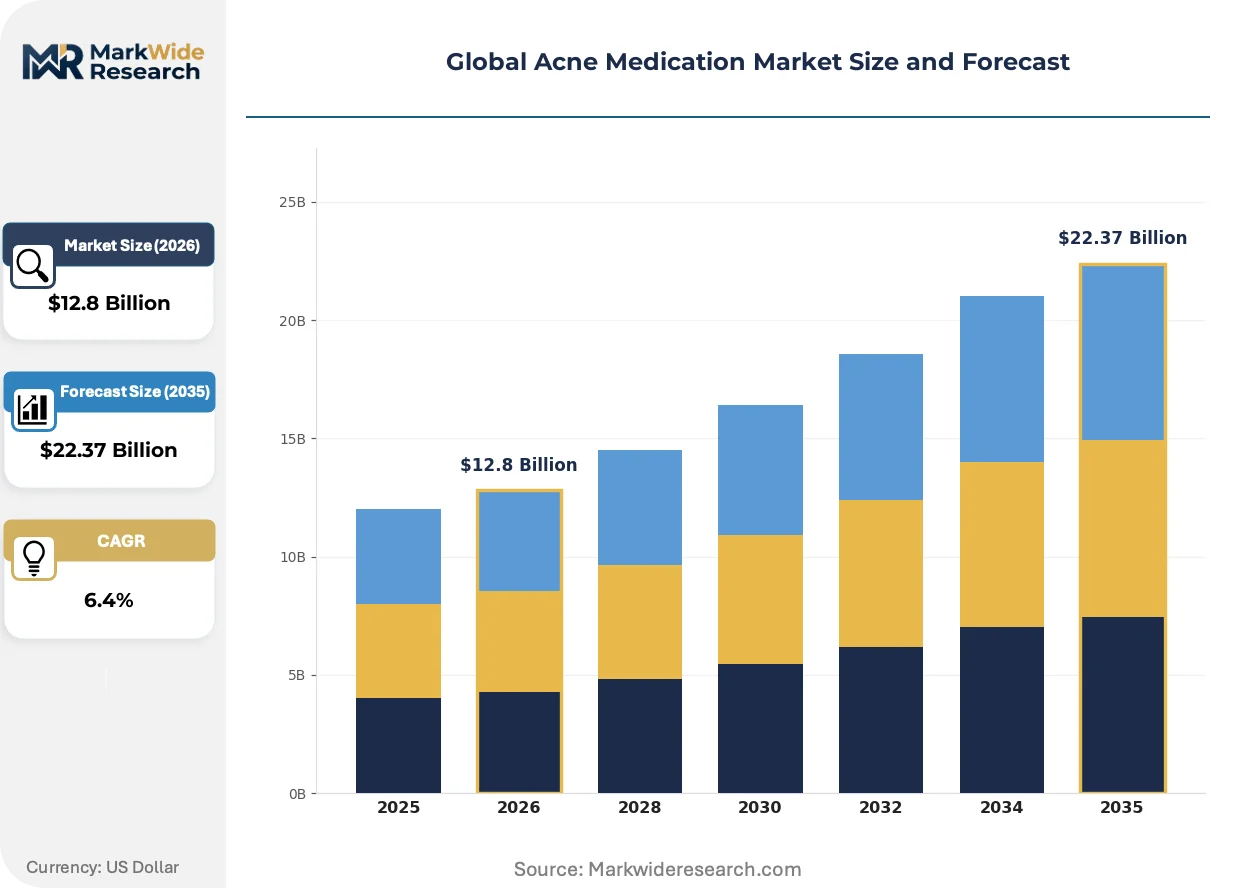
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Oral Medication, Combination Therapies, Light Therapy Active Ingredient: Benzoyl Peroxide, Retinoids, Antibiotics, Salicylic Acid Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Dermatology Clinics End User: Adults, Adolescents, Children, Dermatology Patients |
| Companies Covered | Galderma S.A., Bausch Health Companies Inc., Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Sun Pharmaceutical Industries Ltd., AbbVie Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Mayne Pharma Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acne Medication Market Shifts & Advancements
Topical delivery systems are converging with digital adherence tools, while regulatory pressure on antibiotic monotherapy accelerates investment in non-antibacterial mechanisms. Prescription pathways are fragmenting across direct-to-consumer and clinic-based channels.
Fixed-dose combination gels pairing adapalene with benzoyl peroxide are hybridizing first-line treatment algorithms by consolidating multiple mechanisms into single-application regimens. Dermatology clinics in the United States and Brazil are adopting these formulations as default mild-to-moderate acne protocols, displacing sequential monotherapy prescribing. This convergence compresses patient visit frequency while expanding pharmacy reimbursement codes for combination products.
EMA's Medical Device Regulation reclassification of narrow-band blue-light systems as Class IIa devices imposes clinical evidence requirements previously reserved for implantable technologies. European manufacturers must now submit prospective efficacy data against placebo controls, extending time-to-market by 18-24 months. German and French dermatology device distributors are responding by pivoting procurement toward US FDA-cleared systems with existing MDR technical file precedents.
Patient acquisition through social media dermatology influencers is displacing traditional physician referral pathways for mild acne cases. Instagram and TikTok content creators with medical credentials drive branded topical searches that convert directly to telehealth prescriptions, bypassing primary care gatekeepers. This channel shift concentrates marketing spend in the United States and United Kingdom, where platform advertising regulations permit before-and-after imagery with appropriate disclaimers.
Global Acne Medication Market Segmentation
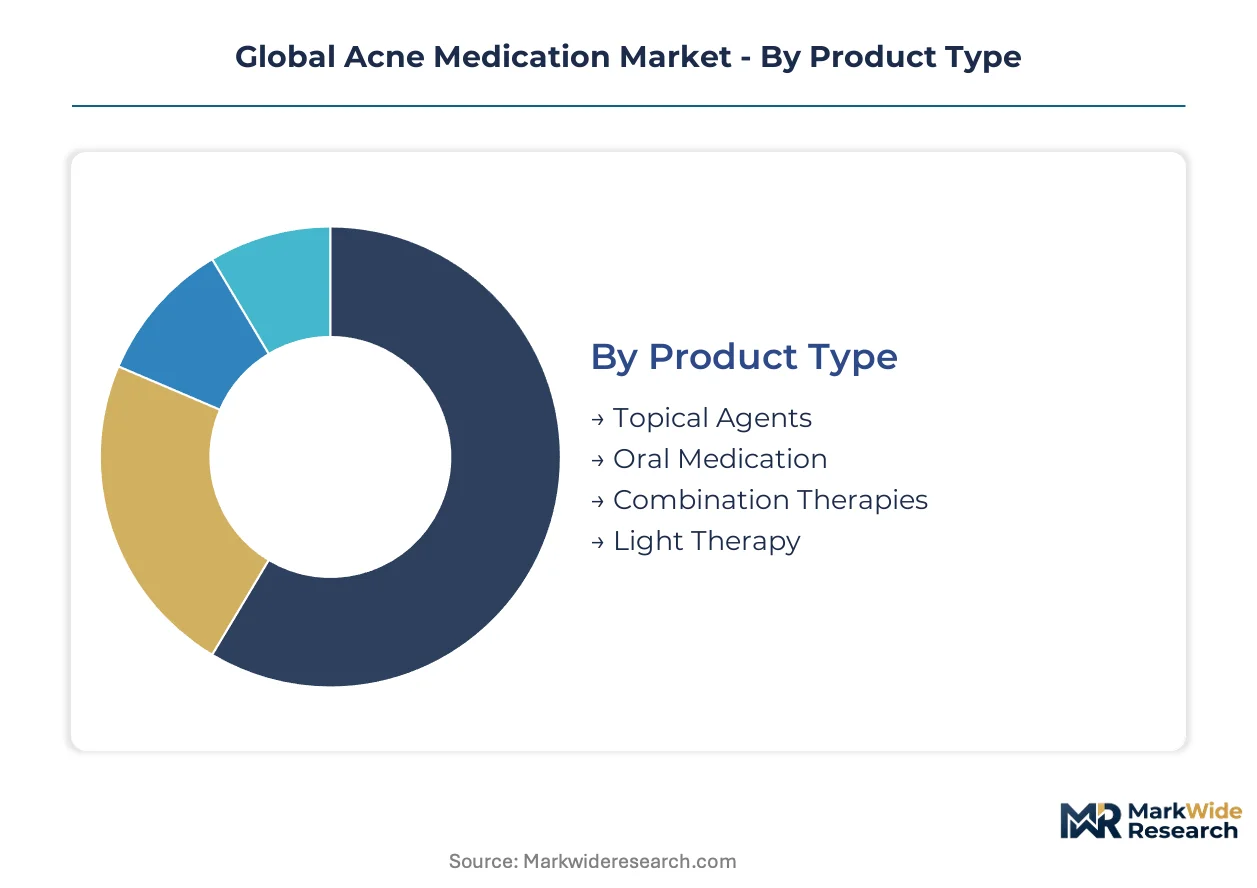
Acne medication segmentation reveals divergent commercial rhythms across product categories. Prescription renewal cycles, regulatory review timelines, and patient adherence patterns create distinct velocity profiles that reshape portfolio allocation decisions for manufacturers and distributors.
Product Type:
Cycle times vary dramatically — topical agents turn over in weeks while oral medications lock patients into multi-month monitoring protocols.
- Topical Agents:Gels, creams, and lotions delivering benzoyl peroxide or retinoids directly to affected skin. Demand concentrates in the United States and Brazil where first-line prescribing habits favor localized treatment with minimal systemic exposure.
- Oral Medication:Systemic antibiotics and isotretinoin formulations reserved for moderate-to-severe or treatment-resistant cases. Isotretinoin prescribers in the United States face FDA Risk Evaluation and Mitigation Strategy obligations that stretch treatment initiation timelines.
- Combination Therapies:Fixed-dose formulations merging multiple mechanisms into single-application regimens. Dermatology clinics across India and the United States are adopting these as default protocols to circumvent antibiotic resistance.
- Light Therapy:Narrow-band blue-light and photobiomodulation devices targeting Cutibacterium acnes through bacterial photodestruction. EMA MDR reclassification in Europe has extended device approval timelines.
Topical agents dominate installed base. Combination therapies are where expansion concentrates.
Active Ingredient:
Cost tiers separate commodity precursors from specialized synthesis pathways, with regulatory scrutiny intensity determining margin architecture.
- Benzoyl Peroxide:Oxidizing agent that reduces Cutibacterium acnes colonization through oxygen radical release. Formulators face EPA manufacturing discharge standards in the United States and feedstock concentration risk from Chinese salicylic acid suppliers.
- Retinoids:Vitamin A derivatives normalizing follicular keratinization and reducing sebum production. Adapalene and tretinoin formulations command premium positioning in prescription channels due to teratogenicity labeling requirements that limit OTC access.
- Antibiotics:Oral and topical antibacterial agents including clindamycin and doxycycline. Stewardship protocols in the United States and European Union are compressing monotherapy utilization.
- Salicylic Acid:Beta-hydroxy acid exfoliant penetrating oil-filled pores to dissolve comedonal plugs. Mass-market OTC positioning in India and Brazil sustains volume throughput despite lower per-unit economics.
Retinoids anchor premium-tier margins. Benzoyl peroxide generates volume throughput.
Distribution Channel:
Customer acquisition costs diverge sharply between physical and digital pathways, with telehealth integration rewriting patient journey economics.
- Online Pharmacies:Digital platforms with embedded dermatology consultations and direct-to-patient fulfillment. Brazil and the United States exhibit the fastest patient migration toward these channels.
- Retail Pharmacies:Mass-market shelf presence for OTC benzoyl peroxide and salicylic acid formulations. Johnson & Johnson Services, Inc. maintains dominant positioning through brand recognition and distribution scale.
- Hospital Pharmacies:Institutional procurement for severe nodulocystic acne requiring isotretinoin initiation. India's hospital network expansion is elevating this channel's share in oral medication dispensing.
- Dermatology Clinics:Prescription authority for combination therapies and device-based treatments. United States clinic consolidation is concentrating formulary decision-making among fewer purchasing entities.
Retail pharmacies maintain volume leadership. Online pharmacies are climbing the fastest.
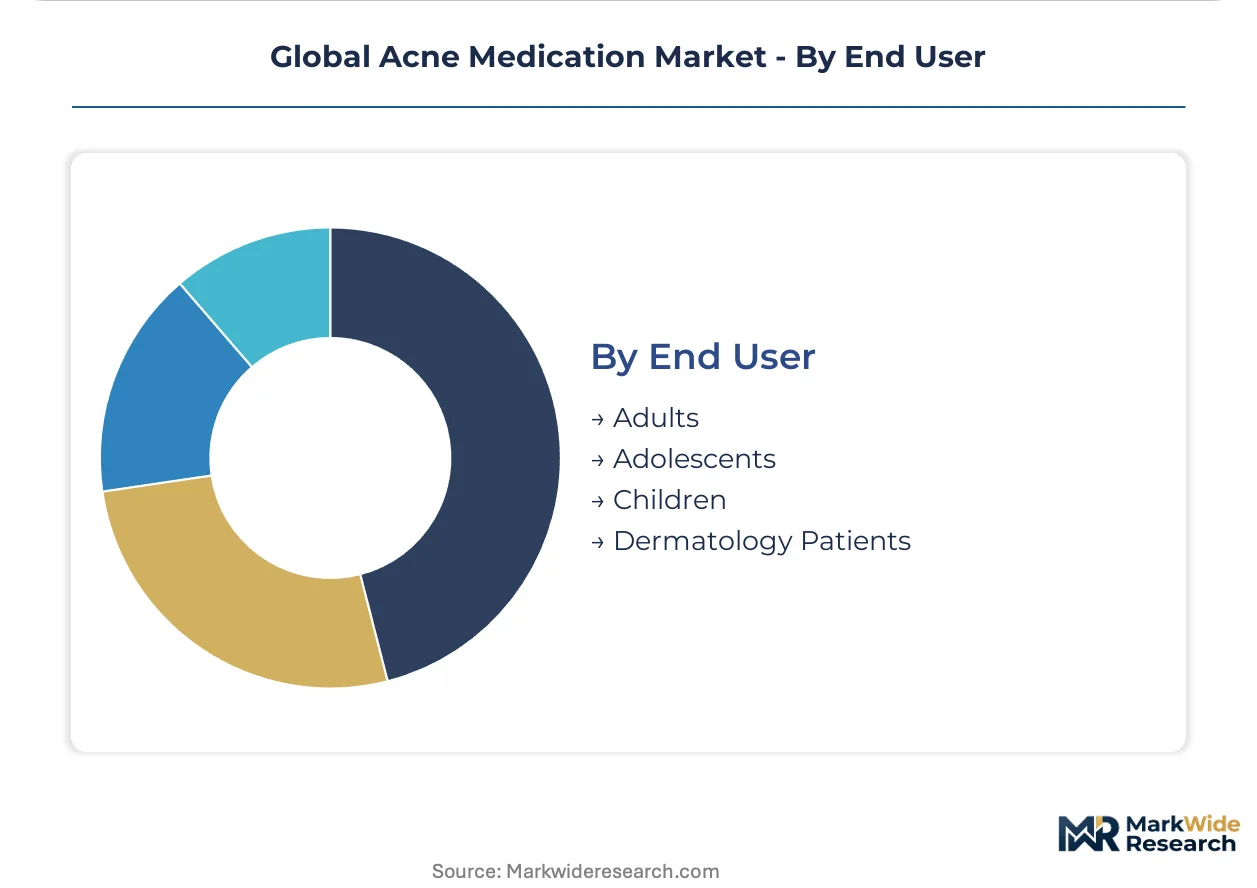
End User:
Maturity gradients separate established adult treatment markets from adolescent entry points where lifetime value calculations reshape marketing investment.
- Adults:Persistent or late-onset acne patients with higher treatment adherence and willingness to pay for prescription-grade formulations. Social media dermatology influencers in the United Kingdom and United States drive branded topical searches among this cohort.
- Adolescents:Peak acne incidence population with price-sensitive purchasing patterns and parental involvement in treatment decisions. Generic oral antibiotics from Sun Pharmaceutical Industries Ltd. compete aggressively on cost in this segment.
- Children:Pre-adolescent cases requiring specialized pediatric formulation tolerability profiles. Regulatory caution limits active ingredient concentration in products targeting this group.
- Dermatology Patients:Severe or treatment-resistant cases under specialist supervision. Galderma S.A. sustains premium positioning through dermatology-focused portfolio concentration.
Adolescents represent the largest addressable population. Adults command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States and Switzerland, where patent-protected retinoid formulations command margins that generic-dominated Indian and Brazilian markets cannot replicate. This asymmetry reshapes where multinationals allocate R&D investment versus manufacturing scale.
United States
Dermatology clinic consolidation in Texas and Florida drives formulary standardization around fixed-dose combination therapies. FDA Risk Evaluation and Mitigation Strategy protocols for isotretinoin impose surveillance infrastructure costs that filter out smaller prescribers. The Boston-Cambridge corridor anchors photobiomodulation device innovation, with MDR technical file precedents from US clearances easing European export pathways.
India
Domestic demand for oral antibiotics surges as adolescent acne prevalence climbs in Maharashtra and Karnataka urban corridors. CDSCO streamlining of active pharmaceutical ingredient import registrations accelerates generic production scale-up for benzoyl peroxide and clindamycin formulations. Hyderabad's bulk drug manufacturing cluster captures contract manufacturing overflow from Chinese salicylic acid supply constraints.
Brazil
Telehealth-integrated pharmacy platforms in São Paulo and Rio de Janeiro bypass traditional retail distribution, capturing prescription abandonment cohorts through embedded dermatology consultations. ANVISA harmonization with FDA bioequivalence standards opens abbreviated review pathways for US-approved generics. The Southeast region's pharmacy chain consolidation concentrates procurement decision-making among fewer purchasing entities.
Germany
EMA Medical Device Regulation reclassification of blue-light systems triggers extended clinical trial obligations that deter mid-cap device entrants. REACH chemical restrictions on certain excipients force reformulation of benzoyl peroxide vehicles for European market entry. The Rhine-Ruhr industrial corridor hosts contract manufacturers specializing in topical vehicle stability engineering for retinoid formulations.
Japan
PMDA's stringent tolerability requirements for pediatric formulations limit active ingredient concentrations in products targeting pre-adolescent cases. METI subsidies for domestic pharmaceutical manufacturing incentivize reshoring of oral antibiotic finishing operations. The Kansai region's Osaka-Kobe pharmaceutical cluster specializes in novel delivery system development for transdermal retinoid absorption enhancement.
Global Acne Medication Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The acne medication market structures around three distinct competitive layers: multinational dermatology platforms with end-to-end prescription-to-consumer pipelines, regional generic manufacturers competing on cost-engineered oral antibiotics, and device specialists navigating divergent FDA-EMA classification regimes. Consolidation pressures concentrate among mid-cap topical formulators lacking captive API supply. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and telehealth platform acquisitions to secure direct patient access channels.
Within the dermatology-focused platform tier, Galderma S.A. and Johnson & Johnson Services, Inc. exemplify divergent scale strategies. Galderma's Swiss S.A. structure positions it within prescription-grade topical specialization, while Johnson & Johnson's US-incorporated services division anchors mass-market retail pharmacy penetration. Sun Pharmaceutical Industries Ltd. represents the India-based generic archetype, occupying cost-competitive oral antibiotic manufacturing. Bausch Health Companies Inc. and Teva Pharmaceutical Industries Ltd. sit within the diversified pharmaceutical portfolio segment, with Israeli-incorporated Teva and Canadian-structured Bausch each leveraging geographic regulatory arbitrage across FDA, EMA, and Health Canada jurisdictions.
| Leading Market Players |
|---|
| Galderma S.A. |
| Bausch Health Companies Inc. |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| Sun Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Mayne Pharma Group Limited |
| Others |
Supply & Pricing Matrix
Chinese manufacturers control over 70% of global salicylic acid precursor supply, anchoring cost structures for benzoyl peroxide formulators while concentrating margin capture among US and Swiss prescription-grade retinoid specialists who command premium positioning through FDA Risk Evaluation and Mitigation Strategy compliance infrastructure.
Pricing Analysis
The customization-premium spread separates mass-market OTC benzoyl peroxide and salicylic acid formulations from prescription-grade retinoid therapies. Three-tier pricing structure across premium, standard, and economy levels stratifies by regulatory certification tier and brand heritage, with FDA REMS-compliant isotretinoin commanding the widest spreads. Cost compression in oral antibiotic categories is intensifying because Sun Pharmaceutical Industries Ltd. and Indian generic manufacturers compete aggressively on volume scale. Adolescent patients and parental purchasers exhibit the highest price sensitivity, while adult persistent-acne cohorts demonstrate willingness to pay for dermatologist-prescribed combination therapies.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical-grade chemical precursors limits flows of specialized retinoid synthesis intermediates from certain jurisdictions, though salicylic acid remains commercially accessible. Active pharmaceutical ingredient production concentrates in India and China, with formulation finishing operations distributed across the United States, Germany, and Brazil. Supply chains rest on Chinese salicylic acid feedstock, Indian clindamycin bulk drug output, and Swiss-German retinoid specialist manufacturing. Single-source vulnerability concentrates in benzoyl peroxide precursor supply, with tariff exposure escalating logistics volatility. Distribution runs through telehealth-integrated online pharmacy platforms, retail pharmacy shelf networks, and hospital pharmacy procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as telehealth integration and microbiome-targeted mechanism classes create niche entry points unoccupied by legacy dermatology platforms. Direct-to-patient subscription models and phage therapy development represent demand-side shifts that reward specialized entrants over diversified incumbents.
For Market Incumbents: Harden formulary positioning through captive API supply of benzoyl peroxide precursors and backward integration into Indian bulk drug manufacturing. Consolidate dermatology clinic procurement relationships before mid-cap formulators secure MDR technical file precedents for European light therapy device export. Channel control via telehealth platform acquisition defends against prescription abandonment to online pharmacy competitors.
For New Entrants and Emerging Players: Build out microbiome-targeted topical capabilities addressing Cutibacterium acnes strain specificity, the most penetrable therapeutic white space beyond conventional antibacterial mechanisms. Target Brazil's telehealth-integrated pharmacy platforms where ANVISA harmonization with FDA bioequivalence standards enables abbreviated generic entry. Subscription direct-to-patient models with embedded adherence monitoring offer the clearest go-to-market angle for chronic mild-to-moderate acne capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermatology device specialists navigating EMA MDR reclassification obligations. Long-term viability across the analysis window favors platforms with integrated prescription-to-consumer pipelines over component manufacturers exposed to API feedstock volatility. Acquisition targets should demonstrate telehealth integration or microbiome R&D positioning. The signal to watch is FDA antibiotic stewardship protocol expansion forcing combination therapy formulary adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Acquisition | Captures prescription abandonment cohorts through embedded dermatology consultations in Brazil and the United States. |
| Microbiome R&D Partnership | Positions entrants beyond antibiotic resistance constraints via phage therapy and postbiotic formulation development. |
| API Backward Integration | Insulates formulators from Chinese salicylic acid supply volatility and tariff exposure. |
| MDR Technical File Precedent | Accelerates European market entry for photobiomodulation devices through existing FDA clearance pathways. |
| Subscription Adherence Program | Locks in lifetime value via auto-refill models with personalized regimen adjustment for chronic acne patients. |
Research Methodology
A spread of perspectives from dermatology clinic formulary directors, pharmaceutical regulatory affairs leads, online pharmacy platform operators, and active pharmaceutical ingredient procurement managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA REMS documentation, EMA MDR classification records, CDSCO import registration filings, and ANVISA bioequivalence harmonization protocols. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing.
Demand-supply-balance framing structured the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, active ingredient class, distribution channel, and patient population age cohort. CAGRs derived from prescription volume trajectories, formulary adoption curves for combination therapies, and telehealth platform patient acquisition rates. Forecast inputs incorporated FDA antibiotic stewardship protocol evolution and EMA device reclassification implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by microbiome-focused biotech entrants or telehealth platform consolidators would shift outcomes. Material shifts in Chinese salicylic acid export restrictions, FDA retinoid teratogenicity labeling revisions, or EMA photobiomodulation device reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Inhalable Drug Market