
 Tool Holder Collets Market | 2026-2036
Tool Holder Collets Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Holder Collets Market Analytics
The gap between premium precision collets and commodity standard collets is realigning procurement patterns across machine shops. Kennametal Inc. leverages its carbide metallurgy expertise to dominate high-speed machining segments. Forkardt Hardinge anchors its position through backward integration into hardened steel supply chains. GDP Industrial Tooling competes on geographic proximity to Indian automotive OEM clusters.
Tool holder collets are precision clamping devices, typically manufactured from spring steel or carbide-composite alloys through CNC grinding and heat treatment, designed to secure cutting tools within a spindle taper with runout tolerances below 0.005 mm. Their primary purpose is maintaining concentricity and gripping force during high-speed rotational operations. Precision collets command the strongest margin pools in aerospace and medical device applications where DIN 6499B conformance is mandatory. Standard collets occupy the highest volume tier across general CNC machining job shops. Hydraulic collets represent the fastest-growing product category as manufacturers seek vibration damping for extended tool life in titanium milling.
ISO 9001 quality management systems, DIN 6499 dimensional standards, and OSHA machine guarding regulations collectively dictate collet certification requirements and market access thresholds. The EPA's metalworking fluid emissions guidelines indirectly shape demand for sealed hydraulic collet systems that reduce coolant exposure. Stakeholders must monitor evolving DIN standards for micro-machining collet geometries and assess captive versus outsourced heat-treatment capacity decisions.
Market Dynamics
Aerospace manufacturers in Germany and the United States are tightening DIN 6499B conformance requirements for turbine blade machining, forcing collet suppliers to upgrade heat-treatment capacity and traceability systems or exit high-margin precision segments entirely.
Growth Catalysts
- Titanium milling expansion:Aerospace OEMs in Stuttgart and Seattle are specifying vibration-damping hydraulic collets for extended tool life in superalloy machining, pulling demand away from standard spring-steel designs.
- ISO 9001 quality mandates:Medical device manufacturers now require certified collet suppliers with documented runout testing below 0.003 mm, creating procurement preference for qualified vendors.
- Carbide-composite metallurgy:Kennametal's proprietary alloy formulations enable spindle speeds above 40,000 RPM without thermal deformation, opening high-speed machining segments previously served by ceramic alternatives.
Market Restraints
- Spring steel supply concentration:Hardened steel feedstock for standard collets concentrates in Austrian and Swedish specialty mills, exposing mid-tier manufacturers to alloy price volatility and extended lead times.
- REACH substance restrictions:ECHA regulations on chromium VI in surface treatments complicate corrosion-resistant coating processes for European-distributed collets, adding compliance cost layers.
- Shrink-fit tool holders:Heat-expansion clamping systems from Haimer and others are displacing collets in heavy roughing applications above 50 mm diameter, capping collet addressable market in large-tool segments.
Strategic Opportunities
- Indian automotive clusters:Pune and Chennai machine tool densities remain underpenetrated by DIN-certified precision collet suppliers, offering first-mover positioning as domestic OEMs adopt ISO quality systems.
- Sealed hydraulic systems:EPA metalworking fluid emissions guidelines are accelerating demand for coolant-isolated collet designs that reduce operator exposure and extend bearing life in continuous-operation environments.
- Additive manufacturing post-processing:Metal 3D-printed aerospace components require micro-machining collets with sub-0.002 mm runout for support-structure removal, creating a specification tier above current DIN 6499B standards.
Industry Challenges
- Grinding technician scarcity:CNC collet manufacturing requires skilled operators for taper geometry control, with German and Japanese machine shops reporting 18-month backlogs for qualified grinding specialists.
- DIN 6499 revision uncertainty:Pending standards updates for micro-machining collet geometries are freezing R&D investment decisions, as suppliers delay tooling investments until taper specifications stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Holder Collets Market |
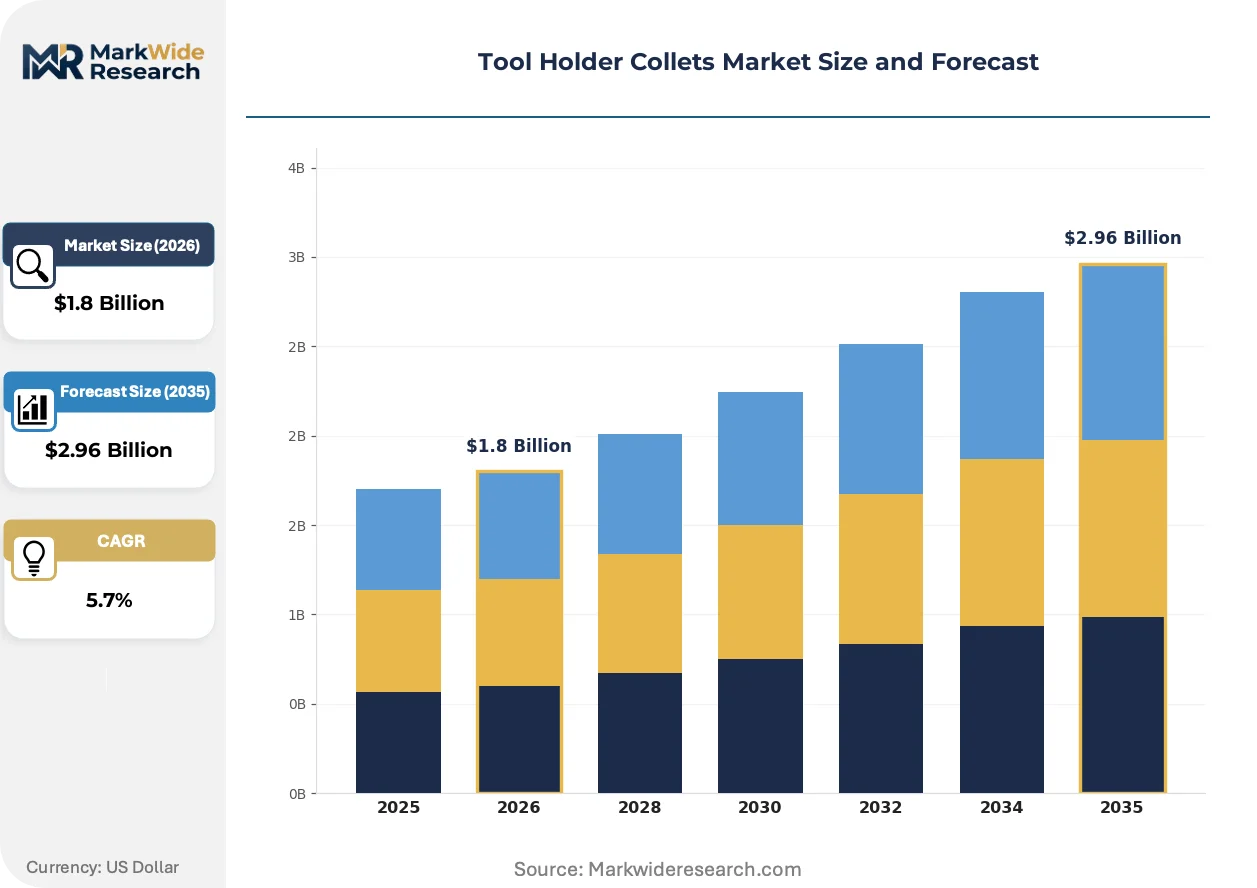
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Collets, Precision Collets, Hydraulic Collets, Pneumatic Collets Application: CNC Machining, Manual Machining, Tool Room Operations, Assembly Lines Material: Steel, Carbide, Aluminum, Polymer End User: Manufacturing, Aerospace, Automotive, Electronics |
| Companies Covered | GDP Industrial Tooling, Sikka Collets & Accessories, Toolsengg.com, Ann Way Machine Tools Co. Ltd., Forkardt Hardinge, T.M. Smith Tool International Corp., Kennametal Inc., Yukiwa Seiko, Techniks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Holder Collets Market Evolving Landscape
Smart manufacturing integration and predictive maintenance systems are rewriting collet specification criteria, with spindle-mounted sensors now enabling real-time clamping force monitoring that was technically impossible five years ago.
Carbide-composite collet construction is converging with sensor-embedded spindle architectures to enable real-time runout detection during titanium milling operations. Aerospace tier-1 suppliers in Toulouse and Hamburg are piloting these integrated systems for turbine disk finishing. The technology is converging with Industry 4.0 data platforms to compress quality assurance cycles from offline inspection to in-process verification.
EPA metalworking fluid emissions guidelines are mandating sealed collet systems that eliminate coolant exposure at the clamping interface. Machine shops in Michigan and Ohio are retrofitting hydraulic collet architectures to meet OSHA ventilation requirements simultaneously. Medical device manufacturers in Massachusetts face the strictest dual-compliance burden, driving specification premiums for certified sealed-system suppliers.
Aftermarket service unbundling is separating collet replacement from spindle maintenance contracts, with German machine tool OEMs now selling collet-only service agreements independent of full spindle rebuilds. Independent distributors in Bavaria and Baden-Württemberg are capturing this disintermediated volume through same-day logistics networks. The pattern is most advanced in automotive supplier parks where downtime costs exceed 2,000 euros per hour.
Tool Holder Collets Market Segmentation
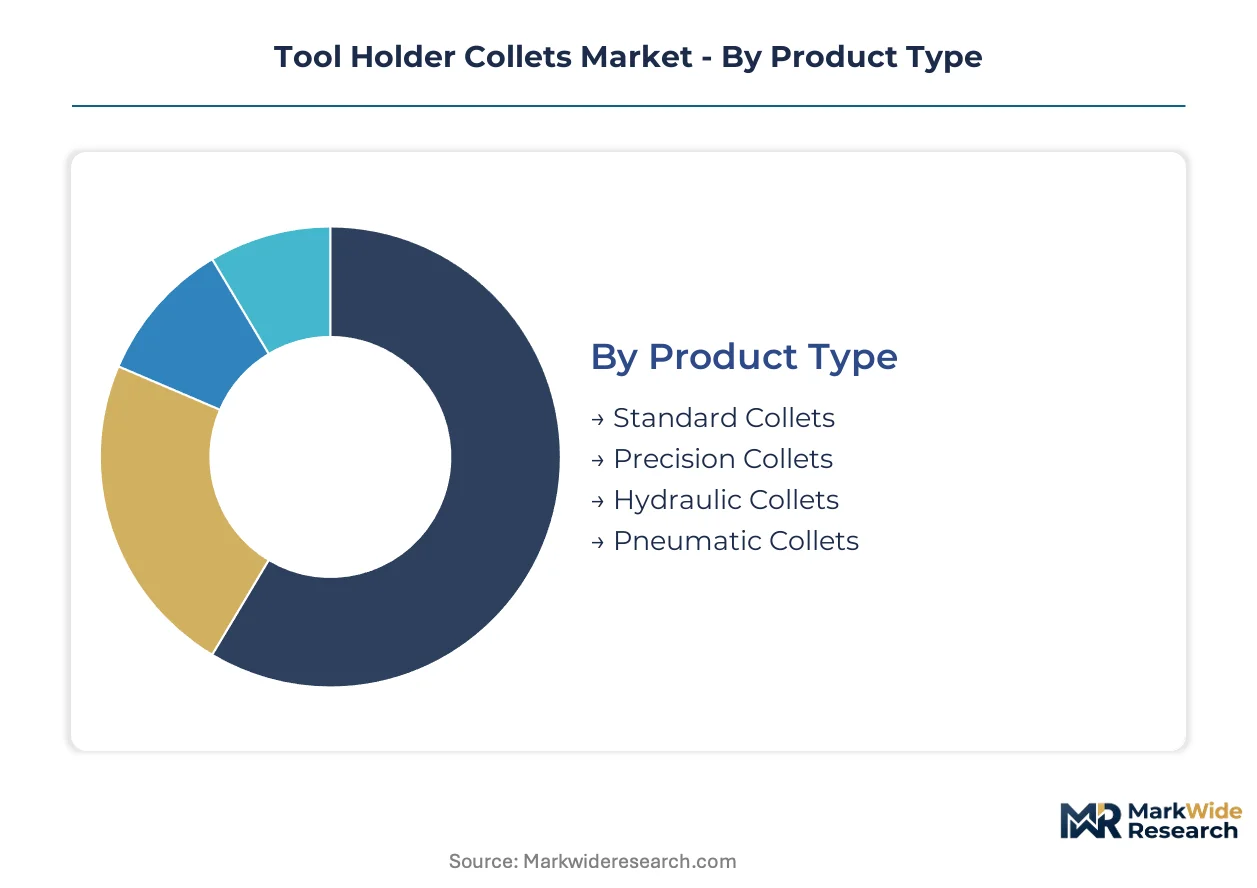
Tool holder collets serve radically different performance tiers across manufacturing verticals. Segmentation reveals how DIN 6499B-certified precision products command margin premiums while standard steel variants absorb volume concentration in general machining.
Product Type:
Supply concentration in spring steel feedstock from Austrian and Swedish specialty mills shapes cost structures across this category.
- Standard Collets:Manufactured from hardened spring steel through CNC grinding and heat treatment, these devices achieve runout tolerances of 0.005-0.010 mm. General CNC machining job shops in Germany's Stuttgart automotive cluster consume the highest replacement volumes as machine tool OEMs drive aftermarket cycles.
- Precision Collets:DIN 6499B-conforming designs utilizing carbide-composite alloys maintain sub-0.003 mm runout for turbine blade machining. Aerospace manufacturers in Hamburg and Toulouse mandate certified suppliers with documented traceability systems, forcing heat-treatment upgrades or market exit.
- Hydraulic Collets:Sealed vibration-damping architectures are expanding most quickly as titanium milling operations in Seattle and Stuttgart specify extended tool life for superalloy machining.
- Pneumatic Collets:Compressed-air clamping mechanisms serve specialized automation cells in electronics assembly where rapid tool changeover outweighs absolute precision requirements.
Today's leader: Precision Collets. Tomorrow's challenger: Hydraulic Collets.
Application:
Cost tier separation between automated production and manual intervention defines procurement patterns here.
- CNC Machining:Computer-numerical control operations demand collets with verified runout certification and spindle integration compatibility. Medical device manufacturers in Massachusetts now require ISO 9001 documentation below 0.003 mm, creating qualified-vendor procurement preferences.
- Manual Machining:Operator-controlled equipment tolerates wider specification ranges. Job shops in India's Pune automotive cluster prioritize geographic proximity and same-day availability over absolute precision certification.
- Tool Room Operations:Maintenance and prototyping environments favor quick-change collet systems with modular taper adapters for multi-machine flexibility.
- Assembly Lines:High-volume automated production integrates collets into fixed spindles with predictive maintenance monitoring via Industry 4.0 sensor platforms.
CNC Machination anchors current revenue. Hydraulic integration for titanium milling represents the steepest expansion trajectory.
Material:
Margin stratification follows metallurgical performance tiers from commodity steel to engineered composites.
- Steel:Spring steel and hardened alloy formulations dominate volume production. REACH substance restrictions on chromium VI surface treatments complicate European-distributed corrosion-resistant coatings, adding compliance cost layers.
- Carbide:Tungsten-carbide composites enable spindle speeds above 40,000 RPM without thermal deformation, opening high-speed machining segments previously served by ceramic alternatives.
- Aluminum:Lightweight alloys serve specialized applications in electronics manufacturing where spindle inertia reduction outweighs wear resistance requirements.
- Polymer:Engineering plastic collets address non-magnetic and chemically inert requirements in semiconductor processing equipment.
Steel commands volume. Carbide captures margin expansion.
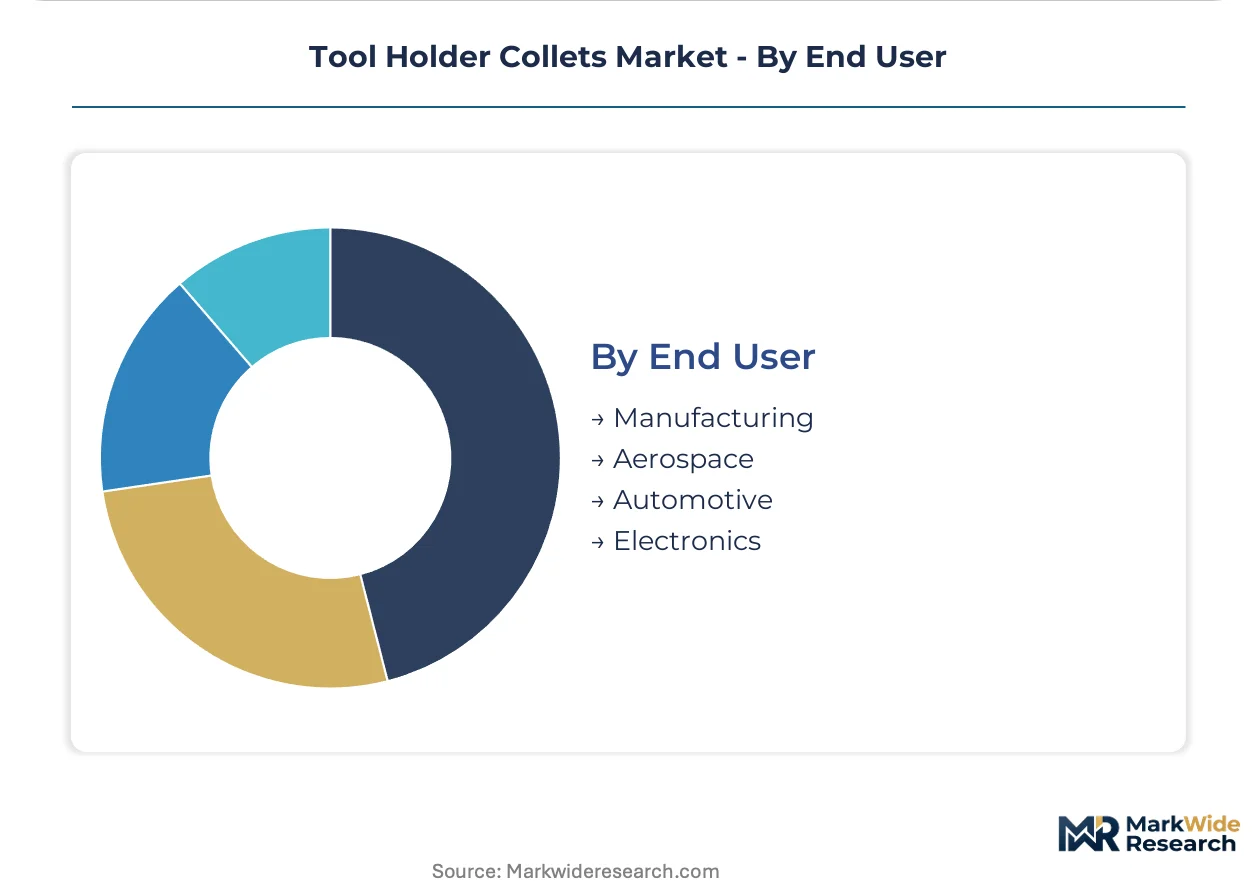
End User:
Customer type concentration in automotive and aerospace clusters dictates regional distribution strategies.
- Manufacturing:General industrial machining spans the full specification range from economy-grade standard collets to precision-certified systems for contract manufacturers serving multiple verticals.
- Aerospace:Turbine component machining in Germany and the United States tightens DIN 6499B conformance requirements, forcing supplier upgrades to heat-treatment capacity and traceability systems.
- Automotive:Powertrain and chassis machining in supplier parks drives aftermarket service unbundling, with independent distributors capturing disintermediated volume through same-day logistics networks.
- Electronics:Miniaturization trends require micro-machining collets with sub-0.002 mm runout for printed circuit board and connector fabrication.
Aerospace leads premium positioning. Electronics micro-machining climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's machine tool density outpaces the United States in precision collet consumption per capita, while India's automotive clusters are accelerating DIN certification adoption faster than any other emerging manufacturing base.
Germany
Stuttgart and Dresden automotive supplier parks drive replacement cycles for DIN 6499B-certified precision collets, with machine tool OEMs unbundling aftermarket service contracts. REACH substance restrictions on chromium VI surface treatments from ECHA add compliance cost layers for corrosion-resistant coating processes. Bavarian independent distributors capture disintermediated volume through same-day logistics networks serving automotive tier-1 suppliers.
United States
Seattle aerospace manufacturers specify vibration-damping hydraulic collets for titanium milling operations, pulling demand away from standard spring-steel designs. EPA metalworking fluid emissions guidelines mandate sealed collet systems that reduce operator exposure in Michigan and Ohio machine shops. Massachusetts medical device manufacturers face the strictest dual-compliance burden for ISO 9001 documentation below 0.003 mm runout.
Japan
Chubu/Nagoya precision machinery clusters maintain sub-0.002 mm runout requirements for micro-machining collets in electronics component fabrication. METI industrial standards shape procurement criteria for spindle-integrated sensor systems enabling real-time clamping force monitoring. Osaka-based tier-1 suppliers pilot carbide-composite collet construction converging with Industry 4.0 data platforms.
India
Pune and Chennai automotive OEM clusters remain underpenetrated by DIN-certified precision collet suppliers as domestic manufacturers adopt ISO quality systems. BIS standards are converging with international certification requirements for imported machine tool accessories. Maharashtra-based fabricators compete on geographic proximity to reduce downtime costs exceeding 2,000 euros per hour in supplier parks.
China
Yangtze River Delta machine tool builders are retrofitting hydraulic collet architectures to meet dual carbon goals and emissions reduction targets. GB standards for collet taper specifications are tightening alignment with DIN 6499 dimensional requirements. Shenzhen electronics manufacturers drive demand for micro-machining collets with sub-0.002 mm runout for printed circuit board fabrication.
Tool Holder Collets Market Competitive Landscape
Top-tier vendors anchor precision-certified segments, while mid-tier fabricators compete on geographic proximity and replacement cycle timing. The vendor base clusters around three strategic archetypes: metallurgy specialists leveraging carbide-composite formulations, backward-integrated manufacturers controlling hardened steel supply chains, and regional distributors capturing unbundled aftermarket service contracts. Dominant competitive moves include capacity expansion in heat-treatment traceability systems and strategic partnerships with machine tool OEMs for spindle integration compatibility.
Among the named participants, Kennametal Inc. and Forkardt Hardinge occupy positions exemplifying divergent strategic approaches to premium-tier positioning, while GDP Industrial Tooling represents the geographic-proximity archetype serving clustered manufacturing bases. Yukiwa Seiko and Techniks Inc. sit within the precision-specialist tier, with Ann Way Machine Tools Co. Ltd. and T.M. Smith Tool International Corp. representing regional-scale fabricators. Sikka Collets & Accessories and Toolsengg.com exemplify the distributor-captured aftermarket model.
| Leading Market Players |
|---|
| GDP Industrial Tooling |
| Sikka Collets & Accessories |
| Toolsengg.com |
| Ann Way Machine Tools Co. Ltd. |
| Forkardt Hardinge |
| T.M. Smith Tool International Corp. |
| Kennametal Inc. |
| Yukiwa Seiko |
| Techniks Inc. |
| Others |
Value Network & Pricing Analysis
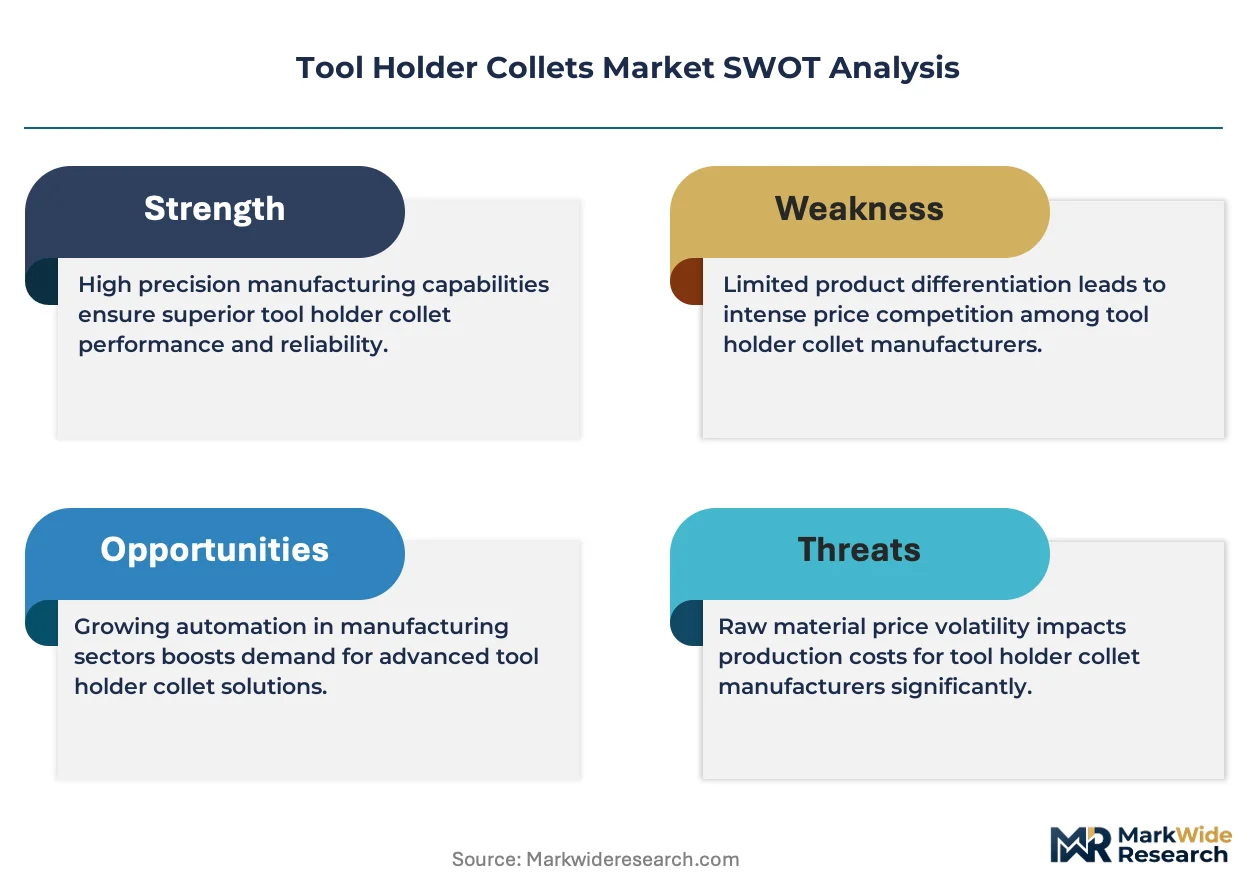
Backward integration into hardened steel supply chains anchors Forkardt Hardinge's cost position while enabling pricing power in DIN 6499B-certified precision tiers. This upstream control insulates margin pools against Austrian and Swedish specialty mill volatility that compresses mid-tier competitors serving standard collet demand.
Pricing Analysis
Capacity additions in India's Pune and Chennai automotive clusters are reshaping price floors for standard steel collets as domestic fabricators compete on geographic proximity. Three-tier pricing structure across precision-certified, standard-grade, and economy-level collets separates aerospace procurement at sub-0.003 mm runout from general machining tolerance bands. Cost compression in standard spring-steel tiers intensifies because REACH substance restrictions on chromium VI coatings add compliance layers without commensurate value capture. Job shops in India's automotive supplier parks exhibit highest price sensitivity, while aerospace tier-1 suppliers in Hamburg and Toulouse prioritize certified traceability over unit cost.
Supply Chain Analysis
Refurbishment flows for precision collets in Germany's Bavarian distributor networks extend asset life and compress replacement cycle revenue for OEM service contracts. Spring steel feedstock concentrates in Austria, Sweden, and Japan's specialty metallurgy clusters, while carbide-composite powders draw from Chinese and Russian tungsten sources. Single-source vulnerability in heat-treatment capacity for DIN 6499B conformance exposes aerospace suppliers to grinding technician scarcity. Distribution runs through machine tool OEM captive channels in Stuttgart and Dresden, with independent distributors capturing unbundled aftermarket volume via same-day logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tool Holder Collets Market functions as a stable compounder anchored by aerospace OEM specification tightening that mandates recurring precision collet replacement cycles.
For Market Incumbents: Lock in heat-treatment traceability investments before DIN 6499 revision finalization freezes competitive positioning. Kennametal's carbide-composite metallurgy expertise and Forkardt Hardinge's backward integration into hardened steel supply chains demonstrate defensible moats against hydraulic collet substitution in titanium milling. Capacity addition in Indian automotive clusters represents the priority lever for volume defense against geographic-proximity competitors. For New Entrants and Emerging Players: The price-point gap between DIN 6499B-certified precision collets and uncertified standard variants creates entry space for mid-tier positioning. Pune and Chennai automotive supplier parks offer the most penetrable geography as domestic OEMs adopt ISO quality systems. A go-to-market angle anchored to same-day logistics partnerships with Bavarian-style distributor networks addresses downtime cost sensitivity exceeding 2,000 euros per hour. For Investors and Strategic Acquirers: Roll-up economics work for precision-certified collet specialists because grinding technician scarcity and heat-treatment capacity constraints prevent rapid organic scaling. Long-term viability favors targets with documented DIN 6499B conformance and aerospace customer lock-in. Monitor ECHA REACH substance restriction enforcement as inflection indicator for sealed hydraulic system specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Traceability Investment | DIN 6499B conformance mandates documented runout testing below 0.003 mm for aerospace tier-1 suppliers. |
| Carbide-Composite Metallurgy Expansion | Kennametal's proprietary alloys enable spindle speeds above 40,000 RPM without thermal deformation. |
| Sealed Hydraulic System Development | EPA metalworking fluid emissions guidelines accelerate coolant-isolated collet demand in Michigan and Ohio. |
| Geographic Proximity Distribution | Maharashtra-based fabricators reduce downtime costs in Pune automotive supplier parks through same-day logistics. |
| Aftermarket Service Unbundling | German machine tool OEMs now sell collet-only service agreements independent of full spindle rebuilds. |
Research Methodology
Bottom-up CNC machining and aerospace end-use modeling reconciled against top-down spring steel and carbide-composite supply tracking forms the analytical core. Primary interviews with grinding technicians, heat-treatment facility managers, aerospace procurement leads, and machine tool OEM aftermarket directors combined with secondary validation from DIN standards documentation, ECHA REACH substance restriction filings, EPA metalworking fluid emissions guidelines, and customs trade data for specialty steel imports. Triangulation between stakeholder demand signals and supply-side capacity announcements ensures cross-verified volume and value estimates.
Historical replacement cycle analysis across Stuttgart, Dresden, Seattle, and Hamburg manufacturing clusters established baseline demand patterns. Segmentation dimensions modeled include product type precision tier, material metallurgy grade, end-use industry vertical, and regional machine tool density cluster. CAGRs derived from fitted trendlines across the projection horizon incorporate aerospace OEM specification tightening velocity and hydraulic collet substitution rates in titanium milling applications.
Caveats apply where DIN 6499 revision timing or ECHA substance restriction expansion could materially shift the outlook for precision-certified supplier viability. Practitioners should monitor grinding technician training pipeline output and heat-treatment capacity utilization in German and Japanese machine shops for early signals of supply constraint acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Height Gauge Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Tool Holder Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Deburring Machine Market
Industrial Tools
India Power Tool Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Handheld DC Torque Tools Market