
 Drill Drivers Market | 2026-2036
Drill Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
Drill Drivers Market Foresight
Tool-as-a-service subscription models for fleet management and predictive maintenance is consolidating how commercial contractors procure drill driver systems. Stanley Black & Decker leverages its service network to anchor recurring revenue streams across North American job sites. Robert Bosch GmbH competes through brushless motor specialization and battery platform interoperability. Makita Corporation sustains manufacturing scale advantages in lithium-ion power packs across Asian and European distribution channels.
Drill drivers are rotary power tools designed to bore holes and drive fasteners, typically rated by torque output in newton-meters and rotational speed in revolutions per minute, with cordless variants relying on rechargeable battery chemistries for field portability. Cordless configurations now dominate volume shipments as lithium-ion energy density improvements extend runtime per charge cycle. Brushless motor technology captures expanding margin pools through reduced friction wear and higher efficiency coefficients, while brushed designs occupy price-sensitive DIY segments. Construction application demand leads absolute unit consumption, though woodworking specialty configurations grow fastest among premium contractor tiers seeking precision control.
OSHA workplace safety standards in the United States mandate ergonomic design and vibration exposure limits, while EU REACH regulations restrict hazardous substances in battery assemblies and housings. China's GB standards enforce electromagnetic compatibility and insulation ratings for domestically manufactured and imported units. Stakeholders must monitor battery chemistry transition timelines and regional certification harmonization to align product roadmaps with shifting compliance thresholds.
Market Dynamics
Brushless motor architecture is compressing supplier margins while elevating performance benchmarks across cordless drill driver portfolios, forcing incumbents to reconfigure R&D roadmaps around magnetic efficiency gains and thermal management systems.
Growth Catalysts
- EU Ecodesign Efficiency Mandates:Tightened energy performance requirements under the EU Green Deal are accelerating factory retooling toward brushless motor platforms. OEMs serving European distribution channels must certify compliance to maintain shelf access.
- Residential Renovation Surge:North American home improvement retail channels are reporting elevated cordless drill turnover as homeowners undertake deferred maintenance projects. Big-box inventory positioning reflects this demand concentration.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements from cylindrical to pouch configurations are extending runtime per charge cycle. Field contractors now complete full workdays without battery swaps.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium refining capacity clusters in China's Inner Mongolia and Jiangxi provinces. Western OEMs face input cost volatility and geopolitical exposure.
- REACH Substance Restrictions:EU regulations on hazardous substances in battery assemblies are complicating housing material selection. Compliance testing extends product development timelines.
- Pneumatic Tool Substitution:Compressed-air drill systems retain cost advantages in fixed industrial installations. Automotive assembly plants continue specifying pneumatic for high-torque applications.
Strategic Opportunities
- Tool-as-a-Service Models:Predictive maintenance subscriptions are penetrating commercial contractor fleets. Stanley Black & Decker's service network anchors recurring revenue streams across job sites.
- Woodworking Specialty Configurations:Precision control features are capturing premium contractor tiers. Brushless variable-speed triggers enable furniture-grade finish work previously requiring manual tools.
- India PLI Scheme:Production-linked incentives for advanced manufacturing are attracting lithium-ion pack assembly investments. Domestic OEMs target both construction and export tool markets.
Industry Challenges
- Battery Chemistry Transition Timelines:Solid-state cell development requires capital-intensive pilot lines. Manufacturers must balance R&D allocation against current lithium-ion platform optimization.
- OSHA Vibration Exposure Certification:Workplace safety standards mandate ergonomic design validation. Testing protocols for hand-arm vibration syndrome compliance add certification overhead.
- Platform Interoperability Standards:Proprietary battery interfaces fragment contractor tool ecosystems. Cross-brand compatibility remains technically constrained by voltage management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drill Drivers Market |
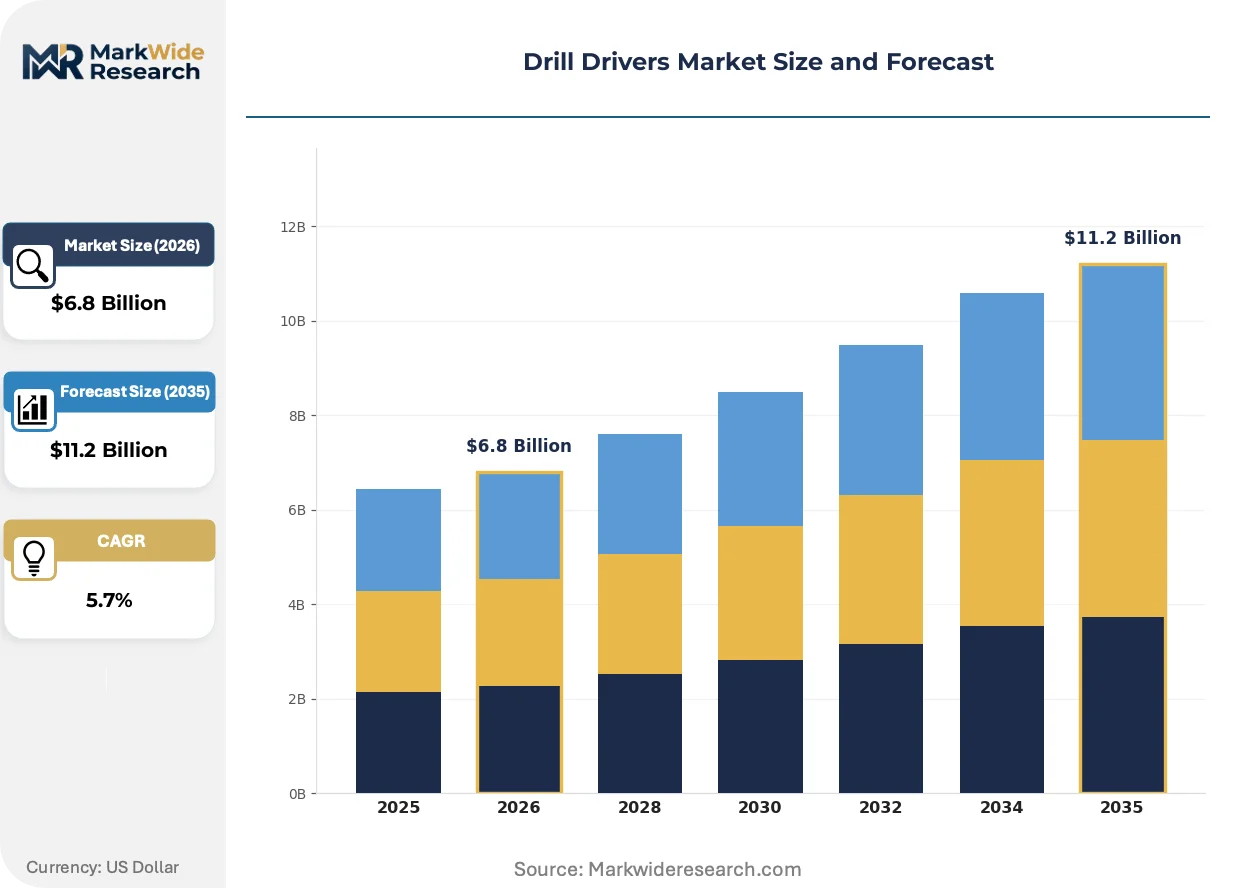
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Hammer, Impact Technology: Brushless, Brushed, Lithium-Ion, Ni-Cd End User: DIY Enthusiasts, Contractors, Industrial, Commercial Application: Construction, Renovation, Woodworking, Metalworking |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Makita Corporation, Hilti Group, Techtronic Industries, Hitachi Koki, Panasonic Corporation, Chervon Holdings Limited, Festool GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drill Drivers Market Shifts & Advancements
Intelligent power management systems are embedding sensor arrays into drill driver housings, enabling real-time torque modulation and usage analytics that reshape how contractors interact with handheld tools.
Brushless DC motor technology is consolidating market positioning around magnetic rotor designs that eliminate carbon brush friction. Commercial contractors in Germany and Japan are specifying brushless platforms for high-duty-cycle applications. The technology is consolidating supplier tiers by compressing margins on brushed motor legacy inventories while rewarding specialized magnetic component manufacturers.
EU REACH regulations are restricting cadmium and lead content in battery electrode formulations. Battery assemblers serving European markets are reformulating cathode chemistries to maintain CE marking eligibility. Professional-grade cordless lines face the steepest compliance costs due to higher cell counts per pack.
Subscription-based fleet management is displacing outright equipment ownership among North American commercial contractors. Rental channels and distributor financing programs are capturing maintenance and replacement revenue streams. This procurement evolution is most visible in metropolitan construction corridors where tool utilization tracking justifies per-use pricing models.
Drill Drivers Market Segmentation
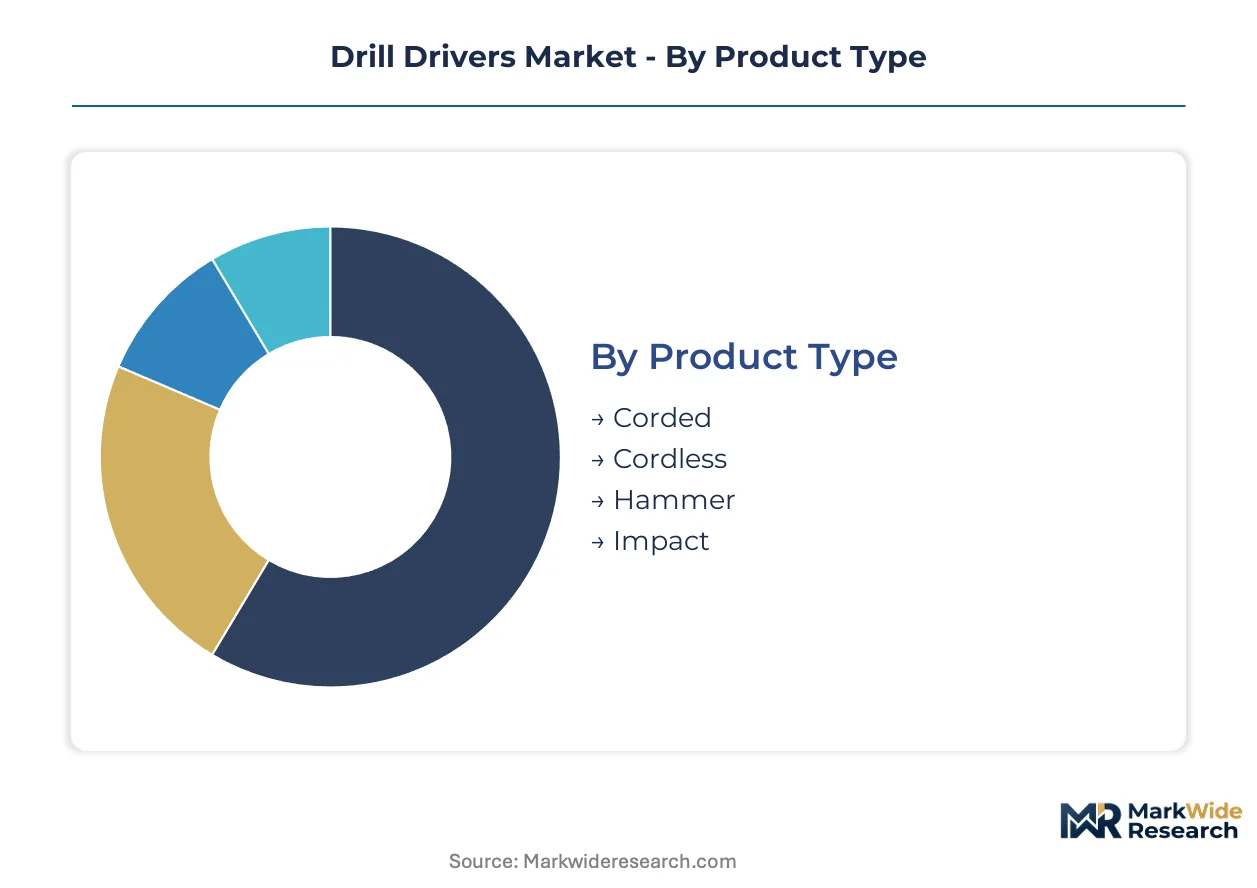
Segmentation in drill drivers reveals how power source architecture and motor technology map to distinct procurement channels and job site requirements. Each dimension carries implications for margin structure, certification burden, and aftermarket service attach rates.
Product Type:
Corded configurations serve fixed-installation environments where continuous runtime outweighs mobility needs, while cordless variants embed rechargeable battery systems for field portability across residential and commercial job sites.
- Corded:Sustained torque delivery from wall current supports metalworking and concrete drilling in workshop settings. Demand clusters in Germany's industrial fabrication corridors where pneumatic alternatives face voltage standardization constraints.
- Cordless:Lithium-ion energy density improvements now enable full-shift operation without battery swaps. North American home improvement retail channels report elevated turnover as residential renovation activity accelerates.
- Hammer:Pneumatic percussion mechanisms penetrate masonry and concrete substrates. Construction contractors in China's manufacturing belt specify these for structural anchoring applications.
- Impact:High-torque pulse mechanisms drive large fasteners in automotive assembly and heavy equipment maintenance. Industrial procurement favors these for repetitive fastening tasks.
Volume placements concentrate in Cordless; the faster expansion belongs to Impact.
Technology:
Motor architecture and battery chemistry together determine thermal efficiency, runtime economics, and regulatory compliance pathways across regional certification regimes.
- Brushless:Electronic commutation eliminates carbon brush friction, extending motor lifespan and reducing maintenance intervals. EU Ecodesign mandates are compressing supplier margins while elevating performance benchmarks.
- Brushed:Mechanical commutation via carbon brushes occupies price-sensitive DIY segments. Cost advantages persist in emerging market distribution channels where upfront acquisition cost dominates purchase decisions.
- Lithium-Ion:Cylindrical and pouch cell configurations deliver energy density gains for extended runtime. REACH substance restrictions complicate cathode formulation for European market eligibility.
- Ni-Cd:Nickel-cadmium chemistry retains niche positioning in cold-weather applications and legacy tool compatibility. Regulatory pressure from cadmium content limits is constraining new product development.
Brushless platforms command premium positioning; Lithium-Ion gains share fastest as cell costs decline.
End User:
Procurement sophistication varies sharply across user tiers, from price-driven retail purchases to enterprise fleet management contracts with predictive maintenance provisions.
- DIY Enthusiasts:Home improvement retail channels serve occasional users prioritizing upfront affordability over durability ratings. Big-box inventory positioning reflects this price sensitivity.
- Contractors:Commercial job sites demand tool-as-a-service subscriptions with utilization tracking and maintenance scheduling. Stanley Black & Decker's service network anchors recurring revenue in this tier.
- Industrial:Fixed manufacturing installations specify pneumatic or corded systems for high-duty-cycle applications. Automotive assembly plants retain compressed-air infrastructure for torque-critical fastening.
- Commercial:Facility maintenance departments balance acquisition cost against total cost of ownership. Procurement patterns favor interchangeable battery platforms across multiple tool categories.
Contractor segment drives absolute unit volume; Commercial tier climbs fastest on fleet modernization cycles.
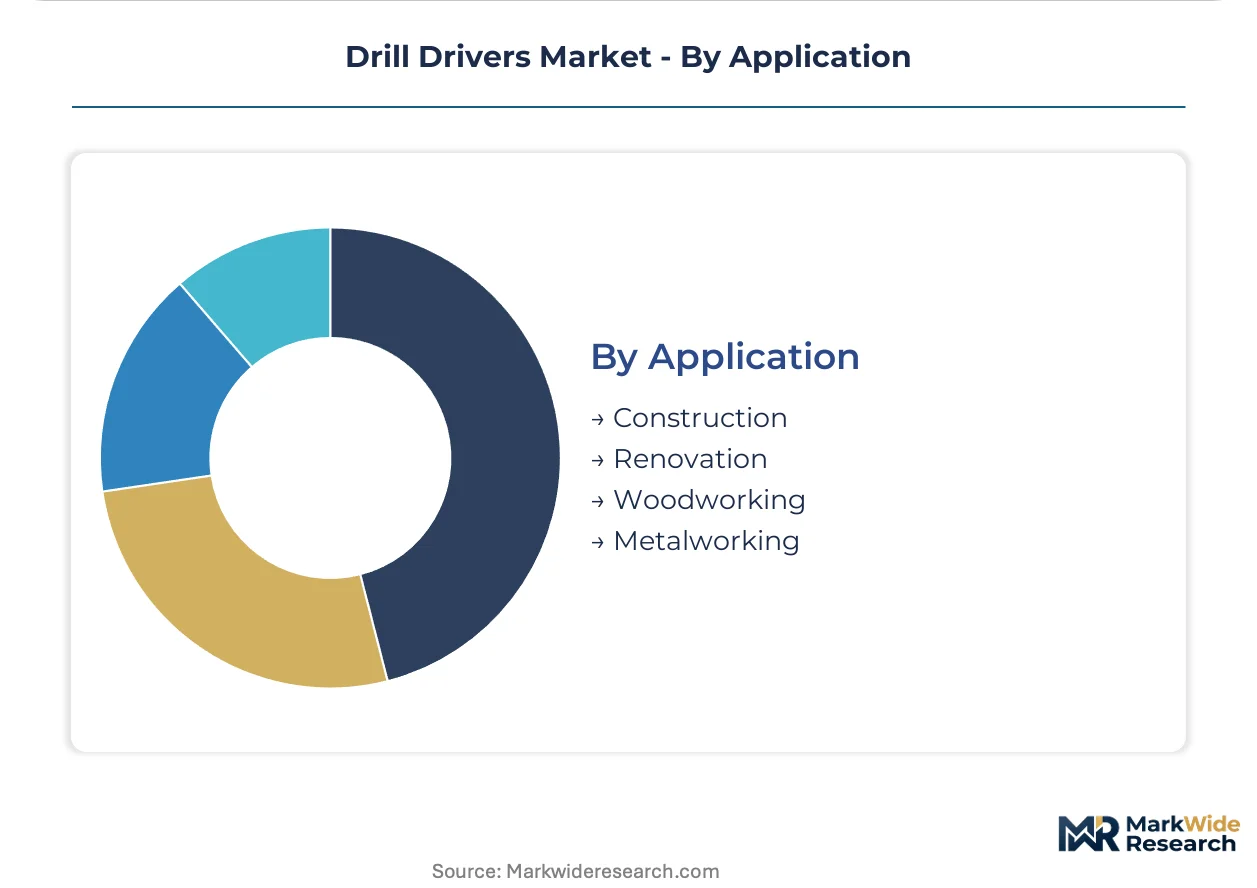
Application:
Task-specific torque and speed requirements shape product specification, with precision control features commanding premium positioning in finish-oriented trades.
- Construction:Structural drilling and fastening in concrete, steel, and timber framing consumes the largest absolute unit volumes. OSHA vibration exposure standards mandate ergonomic design validation for sustained use.
- Renovation:Residential retrofit activity combines demolition and finish work in variable substrate conditions. North American deferred maintenance backlogs are elevating cordless drill turnover.
- Woodworking:Precision variable-speed triggers enable furniture-grade finish work. Brushless motor control is capturing premium contractor tiers seeking manual-tool alternatives.
- Metalworking:High-torque, low-speed operation for drilling hardened steels and alloys. Workshop environments favor corded configurations for thermal stability under sustained load.
Construction absorbs the largest shipment volumes; Woodworking posts the steepest expansion trajectory on precision feature adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of drill driver units for export markets, while the United States and Germany absorb the highest value consumption per capita. This production-consumption asymmetry shapes regional competitive dynamics and certification requirements.
United States
Residential renovation backlogs drive cordless drill turnover through home improvement retail channels. OSHA mandates ergonomic design and hand-arm vibration exposure limits for commercial job site equipment. Tool-as-a-service subscription models concentrate in metropolitan construction corridors across Texas and California.
Germany
Industrial fabrication demand sustains corded configuration preference in workshop settings. EU Ecodesign mandates under the Green Deal accelerate brushless motor platform certification. Stuttgart and Munich anchor precision tool manufacturing clusters serving automotive assembly tool specifications.
China
Domestic construction activity and export tool manufacturing concentrate demand in the Yangtze and Pearl River Delta manufacturing belts. GB standards enforce electromagnetic compatibility and insulation ratings for domestically produced units. Shenzhen and Suzhou house lithium-ion pack assembly operations supplying global OEMs.
Japan
High-duty-cycle commercial applications favor brushless motor durability ratings. METI efficiency guidelines shape domestic procurement specifications for professional-grade equipment. Nagoya and Osaka manufacturing corridors specialize in magnetic component production for motor assemblies.
India
Construction sector expansion drives absolute unit consumption growth in tier-one cities. PLI scheme incentives attract lithium-ion pack assembly investments from domestic and foreign OEMs. Maharashtra and Gujarat industrial zones target export tool market penetration alongside domestic infrastructure buildout.
Drill Drivers Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through battery platform interoperability and service network density, while mid-tier specialists compete on brushless motor specialization and regional manufacturing scale. The vendor base organizes around three strategic archetypes: diversified power tool conglomerates with multi-brand portfolios, specialized motor technology houses, and battery-centric platform operators. Consolidation pressures favor M&A activity targeting battery chemistry capabilities and predictive maintenance software assets.
Within the diversified conglomerate tier, Stanley Black & Decker and Robert Bosch GmbH exemplify integrated service-network positioning, while Makita Corporation represents scale-driven lithium-ion manufacturing advantages. These three entities anchor distinct competitive vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Makita Corporation |
| Hilti Group |
| Techtronic Industries |
| Hitachi Koki |
| Panasonic Corporation |
| Chervon Holdings Limited |
| Festool GmbH |
| Others |
Supply & Pricing Matrix
Captive integration into rare earth magnet refining anchors supplier positioning and pricing power for brushless motor platforms. OEMs securing neodymium supply from China's Inner Mongolia belt insulate margins against spot volatility while REACH compliance costs in battery assemblies compress returns on European-bound shipments.
Pricing Analysis
Margin tightening in the contractor tier reflects brushless motor R&D amortization and lithium-ion cell chemistry transitions. Three-tier pricing structure across premium brushless, standard brushed, and economy DIY levels segments buyer archetypes. Certification grade for OSHA vibration exposure and EU Ecodesign efficiency mandates drives price differentiation. DIY enthusiasts exhibit highest price sensitivity; commercial contractors prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
CE marking and OSHA certification gating filter supplier access to premium distribution channels. Manufacturing concentrates in China, Japan, and Germany for motor assemblies, battery packs, and precision components respectively. Neodymium magnets, lithium carbonate, and copper windings constitute critical input dependencies. Single-source vulnerability in rare earth refining exposes Western OEMs to geopolitical disruption. Distribution runs through home improvement retail, industrial distributors, and emerging tool-as-a-service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drill driver market functions as a vertical-integration race where battery platform control and motor manufacturing depth determine sustainable margin capture. Players securing upstream magnet supply and downstream service networks will consolidate positioning.
For Market Incumbents: Extend battery platform interoperability to lock in contractor fleet renewals and capture aftermarket service revenue. Defend against pneumatic tool substitution in automotive assembly by emphasizing cordless runtime gains. Deepen backward integration into lithium-ion cell assembly to offset cathode material cost volatility. For New Entrants and Emerging Players: Specialty woodworking contractors represent an underserved buyer archetype seeking precision brushless control for furniture-grade applications. India's PLI scheme incentives offer manufacturing scale entry with export market access. Target tier-one Indian construction corridors with localized battery pack assembly and distributor financing partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in battery chemistry capabilities and predictive maintenance software assets. Long-term viability hinges on solid-state cell development timelines and fleet management platform adoption. Monitor brushless motor patent filings as inflection indicator for technology leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium sourcing from China's Jiangxi province insulates margin from spot price volatility. |
| Tool-as-a-Service Platform Launch | Subscription models anchored by Stanley Black & Decker's service network capture recurring contractor revenue. |
| Brushless Motor Specialization | Robert Bosch GmbH's magnetic efficiency focus elevates performance benchmarks under EU Ecodesign mandates. |
| Battery Platform Standardization | Interoperability across drill categories reduces contractor fleet complexity and raises switching costs. |
| India Manufacturing Scale-Up | PLI scheme incentives in Maharashtra attract lithium-ion pack assembly for domestic and export tool markets. |
Research Methodology
Independent corroboration across OEM product managers, battery chemistry specialists, and commercial contractor procurement heads underwrites the qualitative findings. Primary interviews with maintenance directors at automotive assembly plants, aftermarket service heads at industrial distributors, and regulatory affairs leads at power tool manufacturers combined with secondary validation from OSHA enforcement databases, EU Ecodesign certification registries, and customs trade flow records. Bottom-up shipment analysis and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical brushless adoption curves and lithium-ion energy density improvement trajectories structured the forecast window across the projection horizon. Segmentation dimensions modeled include power source architecture, motor technology tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating construction activity indices, residential renovation spending patterns, and manufacturing capacity expansion announcements.
Revisions become necessary when solid-state battery commercialization timelines accelerate or rare earth export restrictions materialize. Forecasts reflect documented assumptions on technology transition pacing and regulatory harmonization progress. A model refresh is warranted upon material change in EU REACH substance restriction scope or OSHA vibration exposure standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Die Grinders Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Micro Welders Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
India Power Tool Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Height Gauge Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Coordinate Measuring Machine Market