
 Micro Welders Market | 2026-2036
Micro Welders Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Welders Market Insights
The gap between premium fiber laser micro welders and commodity TIG resistance units is expanding. Amada Weld Tech leverages its Japanese manufacturing base to dominate precision electronics assembly with sub-50-micron spot control. Lincoln Electric anchors North American distribution through captive service networks for aerospace component suppliers. ESAB competes on hybrid laser welding configurations that bridge speed and heat-affected zone constraints.
Micro welders are precision joining systems that deliver controlled energy input to fuse thin-gauge metals, typically operating at power densities exceeding 10⁶ W/cm² with spot diameters below 0.5 mm for applications in electronics, medical implants, and turbine blade repair. Laser micro welders command the widest margin pools due to fiber laser source costs and optical train complexity, while resistance micro welders retain volume leadership in battery tab bonding and sensor lead termination. Ultrasonic micro welders capture growing share in dissimilar metal joints for medical device fabrication where thermal distortion must stay below 2 μm.
FDA 21 CFR Part 820 quality system regulations and EU MDR Class III device requirements compel medical micro welder vendors to validate process repeatability through automated data logging. ISO 17657-1 resistance welding standards and AWS D17.1 aerospace specifications further fragment certification burdens across end user industries. Stakeholders must weigh captive versus outsourced welding cell deployment as semiconductor manufacturers and dental laboratories diverge on capital intensity tolerance.
Market Dynamics
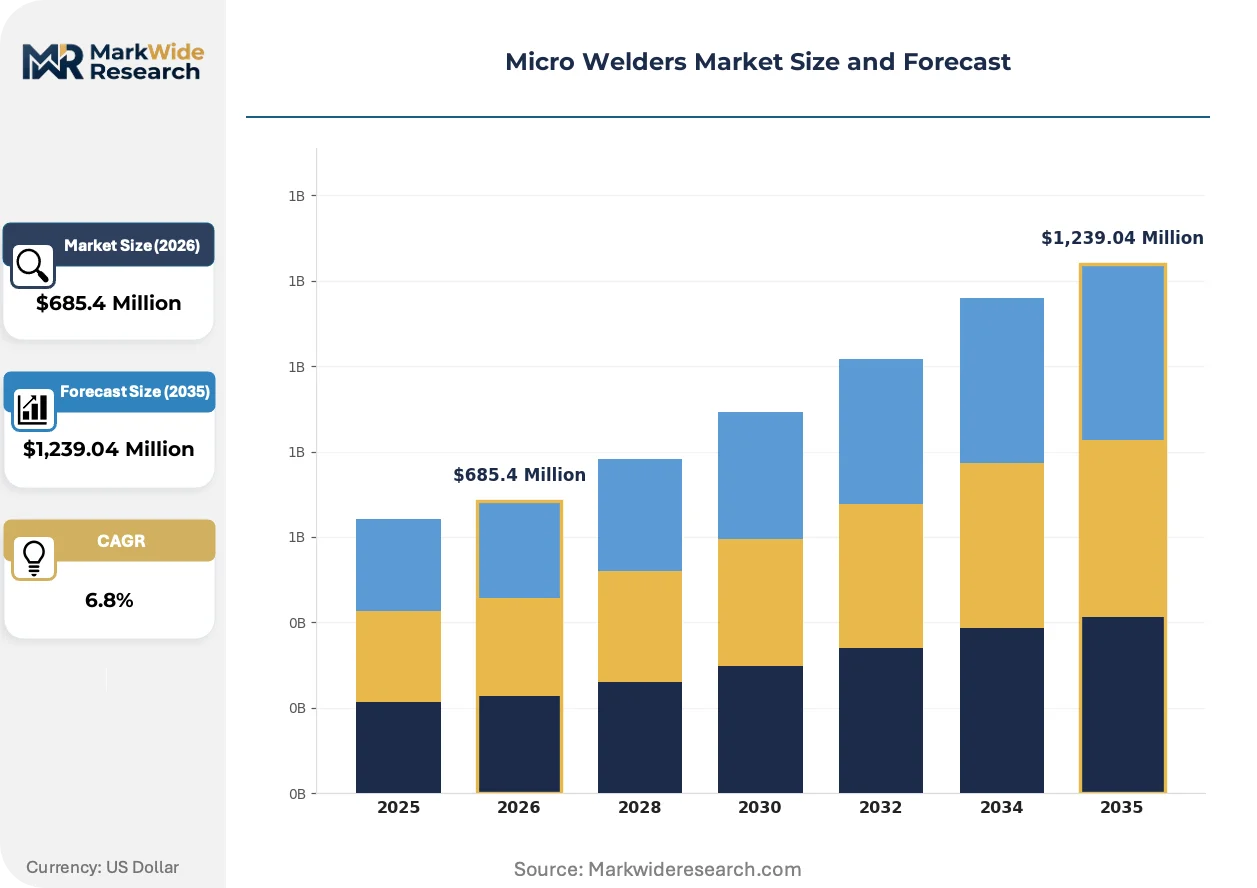
Fiber laser source costs are compressing at 8-12% annually while spot control precision demands tighten, creating a bifurcation between premium optical train configurations and commodity resistance welding systems serving battery tab bonding.
Growth Catalysts
- EU MDR traceability mandates:Medical device fabricators in Germany and Switzerland now require automated data logging capabilities that only fiber laser micro welders with closed-loop power monitoring can deliver.
- Semiconductor packaging density escalation:South Korea's Gyeonggi-do cluster absorbs resistance and ultrasonic micro welding capacity as advanced packaging nodes shrink interconnect pitches below 100 microns.
- FDA 21 CFR Part 820 validation requirements:Dental laboratories and orthopedic implant manufacturers must demonstrate process repeatability through continuous weld parameter recording, favoring capital-intensive laser systems over manual TIG units.
Market Restraints
- Fiber laser source concentration:IPG Photonics and nLIGHT control 70% of ytterbium-doped fiber supply, exposing micro welder OEMs to input cost volatility and extended lead times for high-brightness modules.
- AWS D17.1 aerospace certification timelines:Turbine blade repair applications require 18-24 month qualification cycles that freeze equipment selection decisions and delay revenue recognition for vendors.
- Ultrasonic welding substitution:Dissimilar metal joints in pacemaker housings increasingly favor ultrasonic micro welders where thermal distortion must stay below 2 μm, constraining laser system addressable market.
Strategic Opportunities
- India PLI scheme for medical devices:Domestic manufacturing incentives are drawing contract manufacturers to Hyderabad and Ahmedabad, creating fresh demand for ISO 13485-compliant micro welding cells.
- Laser-ultrasonic hybrid convergence:Systems combining fiber laser pre-heating with ultrasonic consolidation are opening dissimilar metal joints in neurostimulator leads previously unreachable by single-mode processes.
- Outcome-based service contracts:Semiconductor packaging houses in Taiwan are unbundling equipment ownership from weld joint guarantees, shifting vendor revenue toward per-bond pricing models.
Industry Challenges
- Optical train alignment expertise:Field service engineers capable of sub-50-micron beam delivery calibration command 40% wage premiums, constraining vendor scale-up in emerging geographies.
- ISO 17657-1 resistance welding standard fragmentation:Divergent national implementations of electrode force and current measurement protocols force redundant certification testing for multi-country deployments.
- Legacy TIG cell integration:Battery manufacturers face production line reconfiguration costs when retrofitting fiber laser micro welders into existing resistance welding footprints designed for 1990s tab bonding geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Welders Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Micro Welders, Resistance Micro Welders, Ultrasonic Micro Welders, Electron Beam Micro Welders Technology: Fiber Laser, Diode Laser, TIG, Hybrid Laser Welding, Cold Welding, Plasma Welding Application: Electronics Assembly, Jewelry Manufacturing, Medical Device Fabrication, Aerospace Components, Watchmaking End User Industry: Semiconductor Manufacturers, Optical Equipment Makers, Dental Laboratories, Aerospace Component Suppliers, Textile Tooling |
| Companies Covered | Amada Weld Tech, Lincoln Electric, Alpha Laser, Miller Electric, ESAB, LaserStar, IPG Photonics, Control Laser Corp., TRUMPF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Welders Market Trends and Innovations
Beam delivery architectures are fragmenting as end-users demand application-specific optical trains rather than universal platforms, while regulatory data logging requirements harden into competitive differentiators.
Single-mode fiber laser micro welders are modularizing into swappable galvo-scanning and fixed-optic configurations that battery manufacturers reconfigure between cylindrical cell tab welding and prismatic busbar joining within single shift cycles. Medical device subcontractors in Switzerland now specify field-replaceable beam expanders to accommodate both stent cutting and implant hermetic sealing without equipment redundancy. This modularity is compressing capital deployment timelines from 14-week installation cycles to 72-hour changeover protocols.
EU MDR Class III device requirements now mandate 15-year weld traceability records with cryptographic integrity verification, forcing micro welder vendors to embed blockchain-anchored data logging directly into power supply firmware. German orthopedic implant manufacturers have suspended purchases from suppliers lacking EU 2017/745-compliant audit trails. FDA 21 CFR Part 820 quality system regulations are converging toward similar immutable record standards, with Boston-area cardiovascular device firms already rejecting equipment lacking native SQL database export capabilities.
Semiconductor packaging houses are unbundling capital equipment ownership from process guarantee contracts, with Gyeonggi-do foundries now paying per-successful-bond rather than per-machine-hour. This consumption-pattern shift transfers yield risk to micro welder vendors while compressing upfront procurement cycles from 9-month capital approval to 30-day operational expenditure sign-offs. Taiwan-based advanced packaging specialists have pioneered this model, with Malaysian OSATs now replicating the structure for memory module assembly lines.
Micro Welders Market Segmentation
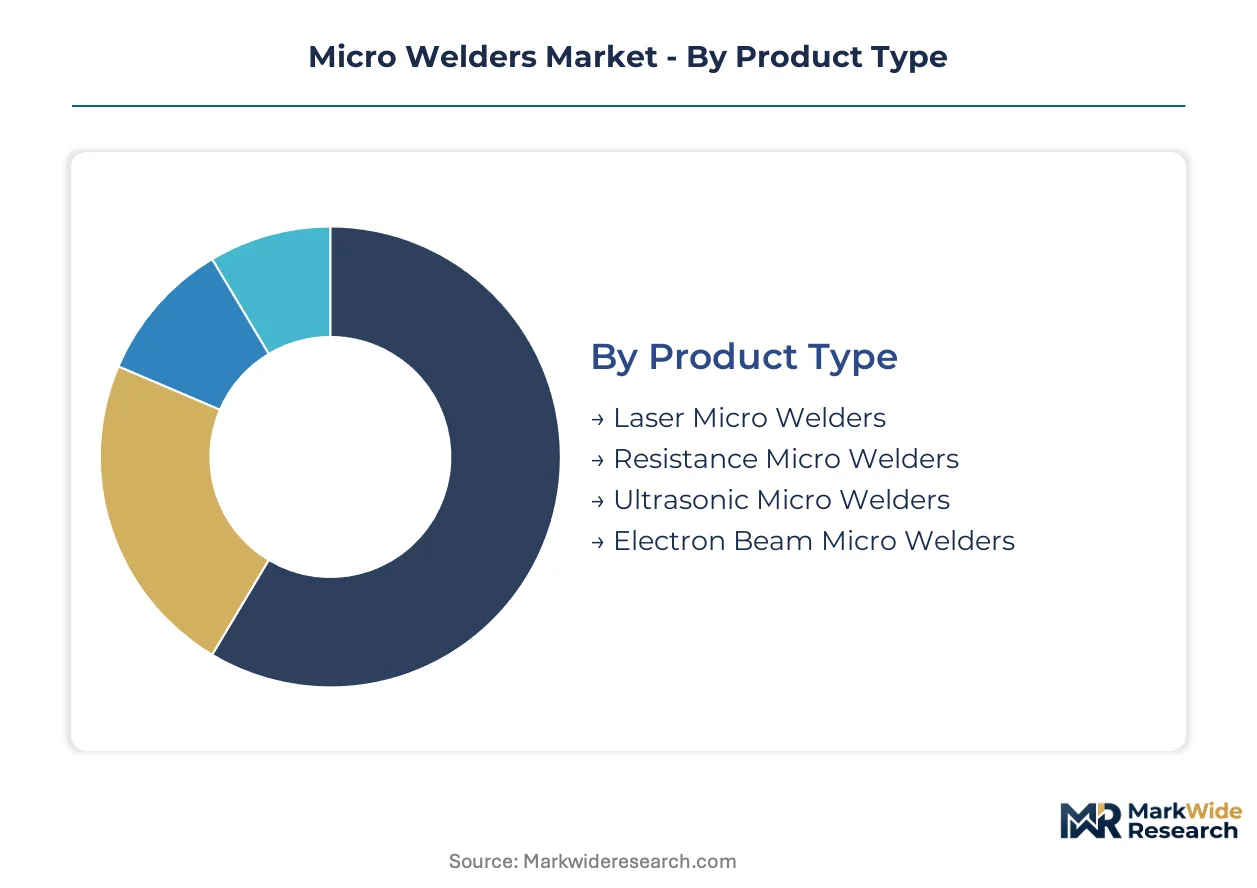
Micro welder procurement splits sharply between high-margin precision systems and volume-oriented commodity units. Technology choice, application requirements, and regulatory compliance burdens each reshape vendor targeting and pricing architecture across end-use verticals.
Product Type:
Laser systems command premium positioning while resistance welders anchor volume deployment across battery and sensor manufacturing.
- Laser Micro Welders:Fiber laser sources deliver power densities exceeding 10⁶ W/cm² with sub-50-micron spot control for hermetic sealing of cardiac implants. Swiss orthopedic manufacturers and South Korean semiconductor packaging houses absorb capacity as traceability mandates tighten.
- Resistance Micro Welders:Electrode-based systems dominate battery tab bonding and sensor lead termination through controlled current-time profiles. German automotive suppliers and Chinese cylindrical cell producers deploy these units at scale where thermal precision requirements stay below laser thresholds.
- Ultrasonic Micro Welders:Solid-state bonding without bulk heating captures dissimilar metal joints in pacemaker housings where distortion must stay below 2 μm.
- Electron Beam Micro Welders:Vacuum-chamber systems serve specialized aerospace turbine blade repair with minimal heat-affected zones.
Today's leader: Laser Micro Welders. Tomorrow's challenger: Ultrasonic Micro Welders.
Technology:
Source cost compression and optical train complexity fragment competitive positioning across six distinct energy delivery architectures.
- Fiber Laser:Ytterbium-doped fiber modules from IPG Photonics and nLIGHT enable sub-50-micron spot control with closed-loop power monitoring for EU MDR-compliant medical fabrication.
- Diode Laser:Direct-emitting bars serve lower-precision jewelry and watchmaking applications where capital constraints outweigh beam quality requirements.
- TIG:Manual tungsten inert gas systems retain share in dental laboratory repair work and legacy aerospace maintenance where requalification costs deter equipment replacement.
- Hybrid Laser Welding:Combined heat source configurations bridge speed and heat-affected zone constraints for thick-section aerospace component joining.
- Cold Welding:Pressure-based solid-state bonding serves specialized electrical contact applications without thermal distortion.
- Plasma Welding:Constricted arc systems occupy niche positions in precision tube welding for medical instrumentation.
Fiber laser sources are expanding most quickly. Diode laser and TIG technologies face substitution pressure from upstream and downstream respectively.
Application:
Regulatory intensity and precision requirements stratify demand across five end-use domains with diverging capital intensity tolerance.
- Electronics Assembly:Advanced packaging nodes below 100-micron interconnect pitches in South Korea's Gyeonggi-do cluster absorb resistance and ultrasonic micro welding capacity as semiconductor densities escalate.
- Medical Device Fabrication:FDA 21 CFR Part 820 and EU MDR Class III mandates compel automated data logging and 15-year traceability records with cryptographic integrity verification for implantable devices.
- Jewelry Manufacturing:Pulsed laser systems serve precious metal joining where aesthetic quality and minimal material loss override throughput metrics.
- Aerospace Components:AWS D17.1 certification timelines extending 18-24 months freeze equipment selection for turbine blade repair applications.
- Watchmaking:Swiss manufacturers deploy micro TIG and laser systems for heritage movement restoration and contemporary production alike.
Electronics Assembly and Medical Device Fabrication together concentrate premium system demand. Jewelry Manufacturing and Watchmaking sustain specialized vendor margins.
End User Industry:
Capital deployment cycles and compliance burdens diverge sharply between semiconductor foundries, regulated medical fabricators, and tooling specialists.
- Semiconductor Manufacturers:Taiwan and South Korean advanced packaging houses are unbundling equipment ownership from process guarantees, shifting toward per-successful-bond pricing models that transfer yield risk to vendors.
- Optical Equipment Makers:Precision alignment subassemblies for telecommunications and sensing equipment require sub-micron positioning repeatability in welded joints.
- Dental Laboratories:FDA 21 CFR Part 820 validation requirements for orthodontic and prosthetic devices favor automated laser systems over manual TIG units despite higher upfront capital.
- Aerospace Component Suppliers:Turbine blade repair and airframe subassembly applications face extended qualification cycles that delay revenue recognition for equipment vendors.
- Textile Tooling:Precision welding of cutting and forming tools for technical fabric production occupies a specialized niche with limited vendor competition.
Semiconductor Manufacturers are driving the steepest pricing model innovation. Dental Laboratories represent the fastest-regulatory-compliance-driven upgrade cycle among traditional end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium fiber laser micro welder deployments for EU MDR-compliant medical fabrication, while South Korea's semiconductor packaging sector absorbs resistance and ultrasonic capacity at scale.
Germany
Orthopedic implant manufacturers in Baden-Württemberg and Bavaria scale automated fiber laser systems to satisfy EU MDR Class III traceability mandates with cryptographic data logging. The national medical device regulator enforces 15-year weld record retention through delegated authority under EU 2017/745. Stuttgart's precision engineering cluster concentrates battery tab bonding equipment for automotive suppliers serving BMW and Mercedes-Benz electrification programs.
Switzerland
Watchmaking heritage brands in the Jura Arc and medical subcontractors near Zurich deploy hybrid micro welding configurations for stent cutting and implant hermetic sealing. Swissmedic aligns device manufacturing standards with EU MDR through bilateral recognition agreements. The Lake Geneva corridor hosts specialized service engineers capable of sub-50-micron optical train calibration commanding wage premiums.
South Korea
Advanced packaging foundries in Gyeonggi-do Province consume resistance and ultrasonic micro welding capacity as interconnect pitches shrink below 100 microns. MFDS pharmaceutical and medical device regulations drive validation protocols for implantable neurostimulator production. Seoul Capital Area semiconductor houses pioneer per-successful-bond pricing models that transfer yield risk to equipment vendors.
United States
FDA 21 CFR Part 820 quality system regulations compel Boston-area cardiovascular device firms and dental laboratories to reject equipment lacking native SQL database export capabilities. The FDA mandates automated weld parameter recording for Class II and III device manufacturing. Greater Boston's medical technology corridor concentrates orthopedic and dental implant fabrication requiring closed-loop power monitoring systems.
India
Contract manufacturers in Hyderabad and Ahmedabad establish ISO 13485-compliant micro welding cells under the PLI scheme for medical devices. CDSCO harmonizes quality management expectations with FDA and EMA precedents for export-oriented production. Gujarat's industrial belt attracts precision electronics assembly operations serving domestic automotive sensor markets.
Micro Welders Market Competitive Landscape
Top-tier vendors anchor premium fiber laser configurations with closed-loop traceability systems, while mid-tier specialists compete on resistance welding volume for battery applications. Japanese and German manufacturers dominate precision electronics and medical device segments through captive optical train expertise. Competitive positioning hardens around three archetypes: integrated laser source suppliers, precision system integrators, and regional resistance welding specialists. Market consolidation proceeds through strategic partnerships for ytterbium-doped fiber supply security and geographic expansion into India PLI beneficiary zones.
Within the precision system integrator tier, Amada Weld Tech and TRUMPF exemplify manufacturers leveraging domestic optical engineering ecosystems for sub-50-micron spot control. Lincoln Electric occupies a position among North American fabricators anchoring distribution through captive service networks. IPG Photonics represents the integrated source supplier archetype, controlling critical ytterbium-doped fiber capacity that constrains competitor scaling.
| Leading Market Players |
|---|
| Amada Weld Tech |
| Lincoln Electric |
| Alpha Laser |
| Miller Electric |
| ESAB |
| LaserStar |
| IPG Photonics |
| Control Laser Corp. |
| TRUMPF |
| Others |
Pricing and Supply Chain Analysis
Optical train calibration specialists in the Lake Geneva corridor command wage premiums that compress margin spreads between premium fiber laser configurations and standard resistance welding systems. Labor-cost differentials between Swiss precision engineers and Chinese battery equipment technicians widen pricing-tier spreads across EU MDR-compliant medical fabrication and commodity battery tab bonding segments.
Pricing Analysis
Bundled equipment-ownership models now compete with unbundled per-successful-bond service contracts across Taiwan and South Korean semiconductor packaging houses. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated fiber laser systems with cryptographic data logging from ISO 17657-1 resistance welders and manual TIG units for dental laboratories. Pricing pressure stems from fiber laser source cost compression as IPG Photonics and nLIGHT expand ytterbium-doped fiber supply. Battery manufacturers exhibit highest price sensitivity due to cylindrical cell volume procurement, while Swiss orthopedic implant fabricators prioritize traceability compliance over capital expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale semiconductor foundry demand in South Korea and Taiwan, while regional distributors serve mid-tier battery manufacturers in India and Germany. Ytterbium-doped fiber laser sources concentrate in the United States and Germany, with precision optical train components sourcing from Switzerland and Japan. Raw material dependencies span rare-earth fiber dopants, high-purity copper electrodes, and piezoelectric transducers for ultrasonic systems. Single-source vulnerability around IPG Photonics and nLIGHT fiber supply exposes micro welder OEMs to input cost volatility. Distribution runs through captive service networks for aerospace component suppliers and independent integrators for medical device subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR Class III traceability mandates and FDA 21 CFR Part 820 validation requirements continuously upgrade equipment specifications and extend replacement cycles.
For Market Incumbents: Deploy backward integration into ytterbium-doped fiber supply to secure input cost stability against IPG Photonics and nLIGHT concentration. Expand captive service engineer training programs in India and Southeast Asia to reduce optical train calibration wage premiums. Certification investment in ISO 13485-compliant data logging firmware defends position against emerging ultrasonic welding substitution in pacemaker fabrication. For New Entrants and Emerging Players: India's PLI scheme for medical devices attracts contract manufacturers to Hyderabad and Ahmedabad seeking ISO 13485-compliant micro welding cells without legacy equipment baggage. Laser-ultrasonic hybrid system development targets neurostimulator lead applications previously unreachable by single-mode processes. Go-to-market angle emphasizes 72-hour modular reconfiguration protocols against incumbent 14-week installation cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional resistance welding specialists lacking EU MDR compliance roadmaps. Long-term viability centers on vendors controlling optical train alignment expertise as semiconductor packaging densities escalate. Signal to watch is per-successful-bond pricing model adoption rates across Taiwan OSATs as indicator of yield risk transfer inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Certification | Swissmedic-aligned cryptographic data logging unlocks German orthopedic implant procurement pipelines. |
| Fiber Laser Source Backward Integration | In-house ytterbium-doped fiber production reduces exposure to IPG Photonics and nLIGHT supply constraints. |
| Modular Optical Train Development | Field-replaceable beam expanders compress capital deployment timelines from 14 weeks to 72-hour changeover protocols. |
| Per-Successful-Bond Service Contracts | Taiwan semiconductor packaging houses transfer yield risk to vendors while accelerating procurement cycles. |
| India PLI Zone Manufacturing Scale-Up | Hyderabad and Ahmedabad ISO 13485-compliant cells capture domestic medical device production incentives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both equipment shipment patterns and procurement decision dynamics. Primary discussions with micro welder OEM product managers, semiconductor packaging procurement directors, orthopedic implant manufacturing engineers, and medical device regulatory affairs specialists informed demand segmentation. Secondary validation drew from FDA 510(k) filings for laser welding systems, EU MDR technical documentation databases, SEC filings of listed fiber laser source suppliers, and semiconductor capital expenditure disclosures. Bottom-up unit economics and top-down industry spend estimates were triangulated to anchor volume projections.
Comparable-period anchoring linked forward projections to historical equipment replacement cycles and regulatory compliance upgrade waves across the analysis window. Segmentation modeling spanned technology type, application vertical, end-user industry scale, and geographic regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting against validated baseline data points. Industry-specific forecast inputs included semiconductor packaging node shrinkage rates and EU MDR audit trail enforcement intensity indices.
Inputs from FDA and EMA regulatory filing databases were available through the study window; gaps in real-time OEM order backlog disclosures introduce uncertainty bands around quarterly shipment estimates. Forecasts reflect documented assumptions regarding fiber laser source cost compression continuity and ultrasonic welding substitution velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Height Gauge Market
Industrial Tools
Electric Tools Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
India Power Tool Market
Industrial Tools
Die Grinders Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Jigs and Other Tools Market