
 Flat-Rolled Stainless Steel Market | 2026-2036
Flat-Rolled Stainless Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Flat-Rolled Stainless Steel Market Analysis
Indonesia's nickel-processing corridor is reconfiguring raw material flows for austenitic grades. China Baowu Steel Group leverages captive nickel supplies to control feedstock costs across its integrated mills. Outokumpu anchors European specialty production with emphasis on low-carbon ferrochrome sourcing. POSCO sustains technical leadership in ultra-thin precision strips for electronics applications.
Flat-rolled stainless steel denotes continuously cast and hot- or cold-rolled chromium-alloyed steel products supplied in widths typically exceeding 600 mm, with austenitic grades 304 and 316 containing 18-20% chromium and 8-14% nickel to achieve oxidation resistance and formability for demanding fabrication environments. Coils dominate volume throughput due to compatibility with automated stamping and continuous processing lines, while sheets command premium positioning in architectural and appliance segments where surface finish specifications drive selection. Grade 316 variants capture margin concentration in marine and chemical processing applications where molybdenum-enhanced pitting resistance justifies material cost premiums over standard 304 formulations.
EPA emissions standards and OSHA workplace exposure limits constrain melt shop operations and finishing line configurations in the United States, while REACH compliance and the EU Green Deal carbon border adjustments reshape import competitiveness for Asian producers serving European end users. China's MEE enforces dual carbon targets that penalize conventional blast furnace routes, redirecting investment toward scrap-intensive electric arc melting. Stakeholders must monitor regulatory divergence between carbon accounting methodologies as this determines relative cost positioning across supply corridors.
Market Dynamics
Automotive electrification is redrawing grade specifications across the flat-rolled stainless steel value chain, with battery enclosure demand forcing mills to certify new thickness tolerances and surface finish protocols for electric vehicle platforms.
Growth Catalysts
- EU Green Deal carbon border adjustments:Import parity rules under CBAM are accelerating low-carbon ferrochrome procurement among European distributors, creating certified-grade premiums for mills with verified Scope 3 reductions.
- Fuel cell bipolar plate demand:Hydrogen transportation infrastructure in Japan and South Korea is specifying ultra-thin precision strips with specialized coating compatibility for proton exchange membrane stacks.
- Indonesia's nickel-processing corridor:NPI-to-matte conversion capacity expansion is shortening feedstock transit times for austenitic grade producers serving East Asian automotive supply chains.
Market Restraints
- Nickel price volatility:LME nickel contract discontinuities and Indonesian export duty regimes are compressing margin predictability for mills without captive laterite supply.
- Blast furnace route carbon intensity:China's MEE dual carbon enforcement is idling conventional capacity faster than electric arc furnace conversions can replace volume, tightening prompt delivery availability.
- Aluminum substitution in battery enclosures:Extruded aluminum tray designs are capturing share in entry-segment electric vehicles where crash performance specifications permit lower stiffness materials.
Strategic Opportunities
- India's automotive component localization:PLI scheme incentives for advanced chemistry cell manufacturing are creating stainless steel demand for module housings and thermal management plates.
- Scrap-intensive EAF certification:MEE carbon accounting protocols favor mills with verified scrap ratios, enabling cost-competitive positioning against conventional integrated producers.
- Digital twin process optimization:Rolling mill sensor integration with predictive maintenance algorithms is collapsing unplanned downtime for precision strip lines serving electronics applications.
Industry Challenges
- Skilled metallurgist shortage:Electric arc furnace process control and secondary refining expertise is concentrating at established producers, constraining greenfield project staffing.
- Surface finish certification timelines:Automotive OEM qualification protocols for 2B and BA finishes require 18-24 month validation cycles that delay new mill market entry.
- Legacy ERP integration with carbon tracking:Mill information systems require substantial reconfiguration to capture real-time emissions data for customer Scope 3 reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat-Rolled Stainless Steel Market |
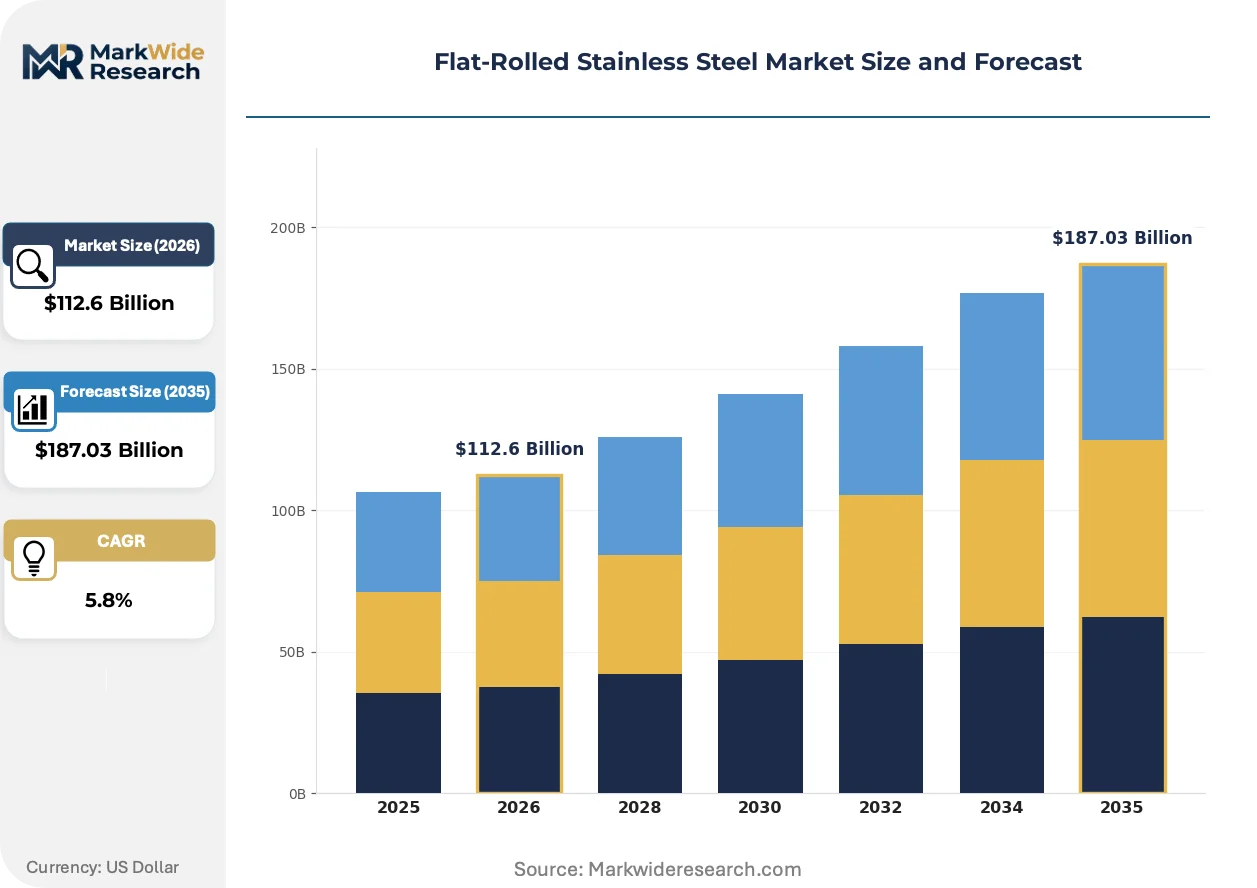
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Strips, Coils, Plates End Use Industry: Aerospace, Automotive, Construction, Food Processing Grade: 304, 316, 430, 445 Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin |
| Companies Covered | Nippon Steel Corporation, Acerinox, ArcelorMittal, Aperam, Jindal Stainless, China Baowu Steel Group, Outokumpu, North American Stainless, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat-Rolled Stainless Steel Market Emerging Trajectories
Process intensification and regulatory carbon accounting are converging to redefine competitive advantage in flat-rolled stainless steel, with digitalization and scrap optimization emerging as the primary vectors of technical differentiation.
Advanced laser welding of coil edges is collapsing downstream slitting requirements for precision strip applications. Electronics component manufacturers in South Korea and Japan are adopting continuously welded master coils to eliminate edge trim waste and improve yield rates. This technology is collapsing the traditional boundary between hot mill and cold mill process steps, compressing lead times for ultra-thin gauge deliveries.
REACH compliance extensions under SCIP database requirements are forcing European distributors to document alloy composition traceability across every coil transaction. Stainless steel service centers must now maintain digital material passports from melt shop through finishing line to satisfy downstream construction and appliance OEM due diligence obligations. German automotive supply chains are most affected, with tier-one stampers rejecting uncertified coil shipments regardless of price positioning.
Consolidated procurement through mill-direct contracts is displacing traditional distributor stocking models among large appliance manufacturers. Buyers in China's Yangtze River Delta manufacturing cluster are negotiating annual volume agreements with Baowu and Tsingshan that bypass regional steel traders entirely. This pattern is most visible in washing machine and refrigerator panel applications where specification standardization permits long-run production commitments.
Flat-Rolled Stainless Steel Market Segmentation
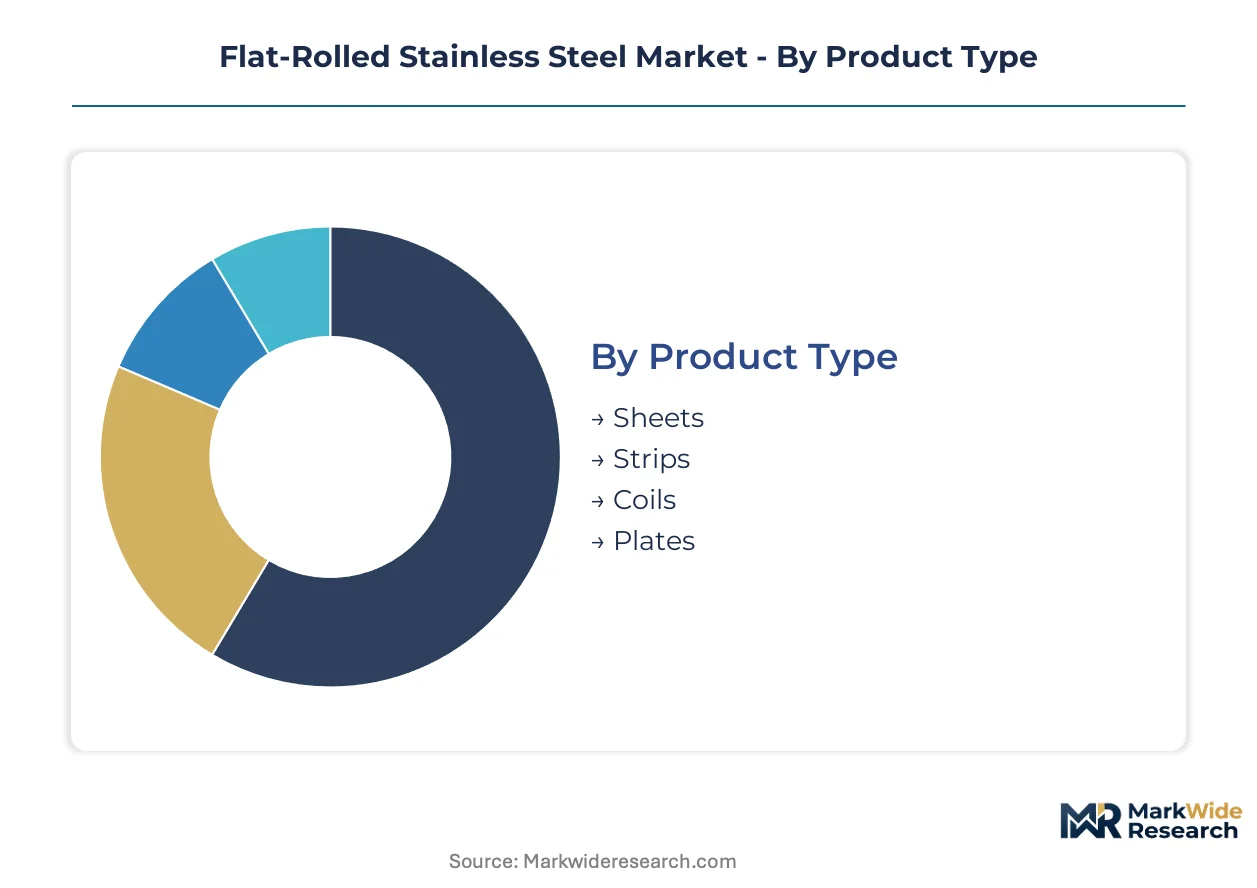
Segmentation in flat-rolled stainless steel reveals how material specifications, processing formats, and end-use requirements create distinct competitive arenas. Mills optimize melt chemistry and rolling parameters differently for precision electronics strips versus heavy-gauge pressure vessel plates. Understanding these divisions exposes where technical differentiation commands margin premiums versus where scale economies dominate.
Product Type:
Volume concentration and processing intensity separate formats that exit the same hot mill but diverge sharply in downstream value capture.
- Sheets:Cut-to-length flat products deliver standardized dimensions for architectural facades and appliance panels. Surface finish specifications from 2B to BA drive selection in German automotive supply chains where REACH SCIP database compliance now mandates full alloy traceability.
- Strips:Narrow-width precision products enable continuous feeding into high-speed stamping lines. Japanese and South Korean electronics manufacturers specify ultra-thin strips with specialized coating compatibility for fuel cell bipolar plate applications.
- Coils:Master coil formats dominate volume throughput through automated slitting and blanking operations.
- Plates:Heavy-gauge products serve pressure vessel and structural applications requiring certified mechanical properties.
Coils command the established base. The steepest expansion runs through strips.
End Use Industry:
Application-driven certification requirements and performance specifications fragment demand across sectors with divergent qualification timelines.
- Automotive:Battery enclosure specifications for electric vehicle platforms are forcing mills to certify new thickness tolerances and surface finish protocols. China's Yangtze River Delta manufacturing cluster is negotiating mill-direct contracts that bypass traditional distributors for specification-standardized appliance panel applications.
- Construction:Architectural facades and structural applications emphasize corrosion resistance and aesthetic surface finishes. German tier-one stampers now reject uncertified coil shipments regardless of price positioning under extended REACH compliance requirements.
- Aerospace:Stringent material certification and traceability requirements constrain supplier qualification to established specialty producers.
- Food Processing:Hygienic surface specifications and cleanability standards drive grade selection for equipment and containment systems.
Construction holds the largest installed demand. Automotive is climbing the fastest.
Grade:
Alloy chemistry differentiates performance characteristics and cost positioning across the chromium-nickel-molybdenum spectrum.
- 304:The workhorse austenitic formulation with 18-20% chromium and 8-10.5% nickel balances oxidation resistance, formability, and cost. Indonesian nickel-processing corridor expansion is shortening feedstock transit times for producers serving East Asian automotive supply chains.
- 316:Molybdenum-enhanced variants deliver superior pitting resistance for marine and chemical processing environments. Molybdenum content justifies material cost premiums where chloride exposure threatens standard 304 performance.
- 430:Ferritic grades eliminate nickel content for cost-sensitive applications accepting reduced corrosion resistance and formability.
- 445:High-chromium ferritic formulations offer specialized corrosion performance for niche architectural and appliance applications.
304 anchors the volume base. The steepest expansion trajectory belongs to 316.
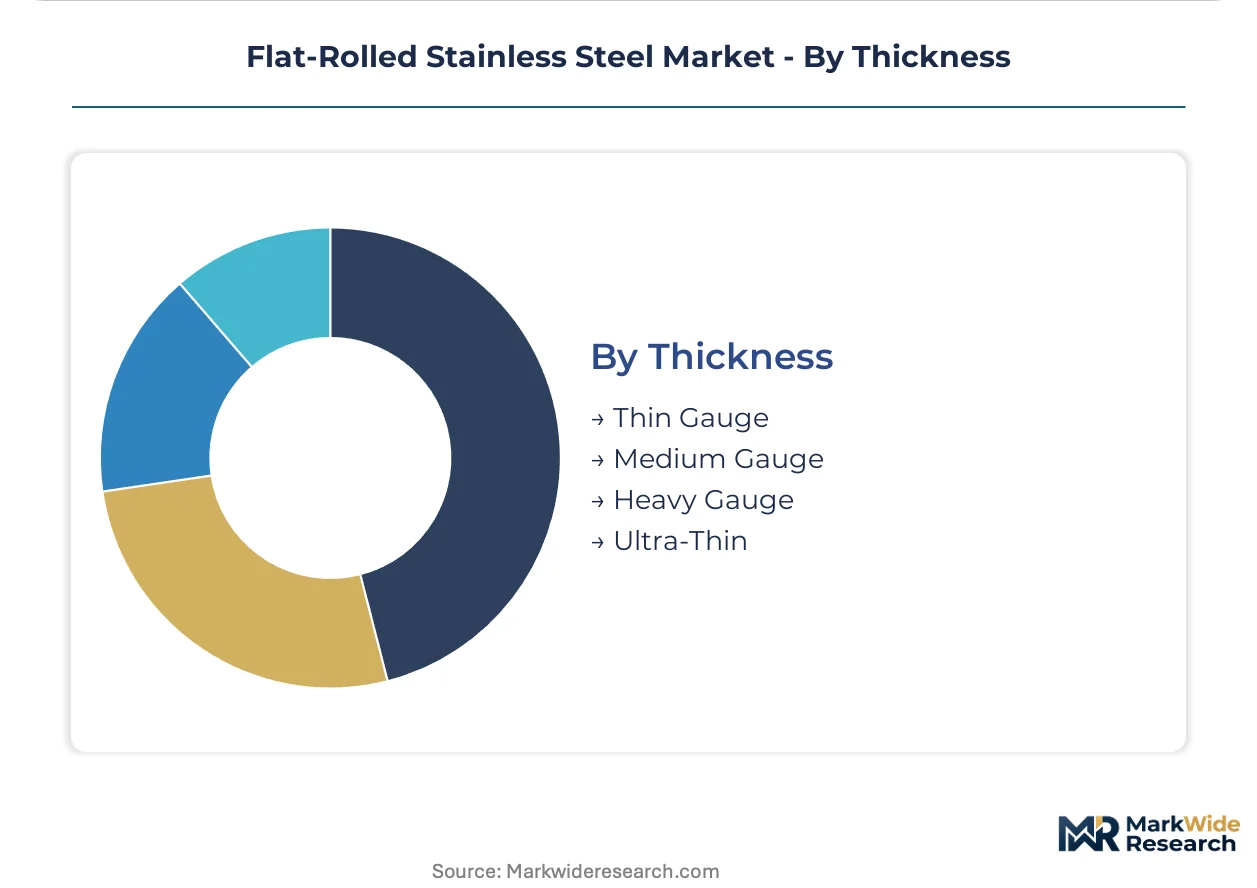
Thickness:
Gauge selection determines rolling mill configuration requirements and end-use performance envelopes.
- Ultra-Thin:Sub-millimeter precision products demand specialized cold rolling and annealing sequences. Advanced laser welding of coil edges is collapsing downstream slitting requirements for South Korean and Japanese electronics component manufacturers adopting continuously welded master coils.
- Thin Gauge:Standard light-gauge products serve broad appliance, automotive trim, and general fabrication applications.
- Medium Gauge:Intermediate thicknesses bridge structural and decorative applications with balanced strength and formability.
- Heavy Gauge:Thick plate and coil products meet pressure vessel, structural, and heavy equipment requirements where load-bearing capacity dominates.
Medium gauge captures the established base. Ultra-thin is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE dual carbon enforcement is redirecting investment toward scrap-intensive electric arc melting across China's integrated steel corridor. This regulatory pivot is compressing conventional blast furnace availability while accelerating low-carbon capacity buildouts.
China
Baowu and Tsingshan negotiate mill-direct contracts with Yangtze River Delta appliance manufacturers for specification-standardized panel applications. MEE carbon accounting protocols favor mills with verified scrap ratios, enabling cost-competitive positioning against conventional integrated producers. The Shanghai-Ningbo corridor concentrates precision strip capacity for electronics and automotive stampers.
Japan
Fuel cell bipolar plate demand from hydrogen transportation infrastructure specifies ultra-thin precision strips with specialized coating compatibility. METI clean hydrogen roadmaps are channeling procurement toward domestic mills with certified low-carbon ferrochrome sourcing. The Nagoya-Osaka manufacturing belt anchors specialty production for automotive and electronics supply chains.
South Korea
Automotive electrification is forcing mills to certify new thickness tolerances and surface finish protocols for battery enclosure applications. MFDS workplace exposure frameworks constrain melt shop configurations while supporting precision strip qualification for proton exchange membrane stacks. The Busan-Ulsan industrial complex concentrates ultra-thin gauge capacity serving Japanese and domestic electronics manufacturers.
Germany
REACH SCIP database requirements now mandate full alloy traceability from melt shop through finishing line for construction and appliance OEM due diligence. EU Green Deal carbon border adjustments are accelerating low-carbon ferrochrome procurement among European distributors. The Ruhr industrial region maintains heavy-gauge pressure vessel capacity while specialty producers in Bavaria serve automotive tier-one stampers.
United States
EPA emissions standards and OSHA workplace exposure limits constrain melt shop operations and finishing line configurations across integrated producers. NHTSA vehicle safety protocols are incorporating stainless steel battery enclosure specifications for electric vehicle platforms. The Ohio River Valley and Gulf Coast corridors concentrate flat-rolled capacity serving appliance and automotive manufacturers.
Flat-Rolled Stainless Steel Market Vendor Landscape
Integrated mega-mills and specialty precision producers split the market into distinct competitive arenas. Consolidation around captive nickel supply and scrap-optimized electric arc routes is compressing margins for conventional blast furnace operators. Three archetypes dominate: Chinese state-backed integrated groups with upstream resource control, European specialty mills with low-carbon certification advantages, and East Asian precision strip specialists with electronics qualification heritage. Competitive moves center on backward integration into nickel processing and strategic partnerships for fuel cell bipolar plate qualification.
Among East Asian integrated producers, POSCO and Nippon Steel Corporation exemplify the precision-specialist archetype with established electronics and automotive qualification protocols. China Baowu Steel Group occupies a position representing state-backed scale advantage with captive feedstock control across austenitic grade production. European specialty capacity anchors around Outokumpu, which sits within the low-carbon certification tier emphasizing verified Scope 3 reductions for EU Green Deal compliance.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Acerinox |
| ArcelorMittal |
| Aperam |
| Jindal Stainless |
| China Baowu Steel Group |
| Outokumpu |
| North American Stainless |
| POSCO |
| Others |
Supply Flow & Price Mechanics
Indonesia's Morowali Industrial Park concentrates nickel-to-matte conversion capacity that feeds austenitic grade producers across East Asia, translating captive feedstock control into pricing power for integrated mills serving automotive and electronics supply chains.
Pricing Analysis
Price spreads between Indonesian captive-nickel mills and European scrap-dependent producers have widened as MEE carbon accounting protocols favor verified scrap ratios. Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon grades from conventional production and commodity spot material. Pricing pressure stems from aluminum substitution in entry-segment electric vehicle battery enclosures. Tier-one automotive stampers show least price sensitivity under REACH SCIP compliance mandates, while appliance manufacturers in China's Yangtze River Delta cluster negotiate aggressively on volume.
Supply Chain Analysis
Extended payment terms from 90 to 120 days have become standard for service centers serving German construction and appliance OEMs under REACH documentation requirements. Raw material flows draw from Indonesia's nickel-processing corridor, China's ferrochrome production belt, and South African chromite mines. Single-source vulnerability concentrates in Indonesian laterite supply for austenitic grades. Distribution runs through mill-direct contracts displacing traditional distributor stocking among large appliance manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification fragments demand across battery enclosure specifications, fuel cell bipolar plate applications, and precision electronics strips—creating specialist niches alongside commodity volume.
For Market Incumbents: Entrench low-carbon certification advantages by securing verified Scope 3 ferrochrome sourcing for EU Green Deal compliance. Deepen backward integration into Indonesian nickel matte production to defend margin position against Tsingshan and Baowu captive supply economics. Accelerate digital twin deployment across precision strip lines to collapse automotive OEM qualification timelines from 24 months. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cell manufacturing represents the most penetrable entry point for stainless steel module housing and thermal management plate supply. Scrap-intensive electric arc furnace capacity in China's Shandong province offers white-space positioning under MEE dual carbon enforcement. Target mill-direct qualification with Yangtze River Delta appliance manufacturers bypassing established distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting arbitrage play because regulatory divergence between EU CBAM and Chinese MEE protocols will persist through the decade. Acquisition targets center on European specialty mills with verified low-carbon ferrochrome sourcing and East Asian precision strip producers with fuel cell bipolar plate qualification heritage. Monitor Indonesian export duty regime adjustments as the critical inflection signal for integrated producer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Processing | Captive laterite supply insulates margin predictability against LME discontinuities and Indonesian export duties. |
| Scrap-Intensive EAF Certification | Verified scrap ratios unlock cost-competitive positioning under MEE carbon accounting protocols. |
| Digital Twin Process Optimization | Predictive maintenance algorithms collapse unplanned downtime for precision strip lines serving South Korean electronics. |
| Fuel Cell Bipolar Plate Qualification | Ultra-thin precision strip certification for proton exchange membrane stacks opens hydrogen infrastructure procurement. |
| REACH SCIP Database Compliance | Full alloy traceability from melt shop through finishing line satisfies German automotive tier-one due diligence. |
Methodological Framework
Initial hypotheses were tested against primary input from melt shop operations directors, automotive tier-one procurement managers, stainless steel service center executives, and EAF process metallurgists and refined through secondary validation against customs trade data, SEC filings from listed producers, MEPS stainless steel price indices, and EU ETS carbon market disclosures. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic projections.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by grade tier, end-use industry, thickness gauge, and regional production hub. CAGRs derived from volume trajectory analysis incorporating automotive electrification content per vehicle, fuel cell deployment roadmaps, and appliance manufacturing cluster output. Scrap availability curves and nickel laterite supply elasticity fed industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction activity, European automotive production, or Indonesian mining policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
India Metal Fabrication Market
Metals
US Copper Scrap Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Aluminum Welding Wires Market
Metals
Stainless Steel Panels Market
Metals
Global Tantalum Market
Metals
Titanium Market
Metals
Aluminum Slugs Market
Metals
Titanium Sponge Market
Metals
Gold Smelting Market
Metals
Lithium Tungstate Market
Metals
Europe Aluminum Extrusion Market
Metals
High Purity Tungsten Market
Metals
Beryllium Copper Plate Market
Metals
Heat-Treated Steel Plates Market