
 Tire Reinforcement Materials Market | 2026-2036
Tire Reinforcement Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Reinforcement Materials Market Intelligence
China is narrowing its steel cord capacity gap with established European producers through large-scale domestic expansion projects. Bekaert NV leverages its integrated steel wire operations across Belgium and China to sustain cost leadership in high-tensile cord products. Hyosung Corporation anchors its position in nylon and polyester tire cord through captive polymer supply and dedicated weaving facilities in South Korea. Toray Industries, Inc. differentiates via carbon fiber reinforcement technologies for next-generation tire architectures.
Tire reinforcement materials comprise engineered fibers and metallic cords embedded within rubber compounds to provide structural integrity, dimensional stability, and load-bearing capacity under cyclic stress and elevated temperatures. Steel cord typically contains brass-coated high-carbon steel filaments twisted into multi-layer constructions, while aramid and polyester variants offer weight reduction for performance applications. Steel reinforcement occupies the dominant share in commercial vehicle and heavy-duty segments where fatigue resistance and cut-through strength command premium positioning. Aramid reinforcement represents the fastest-expanding material category as manufacturers seek weight reduction for electric vehicle range optimization. The passenger car application segment generates the deepest margin pools due to specification diversity across OEM platforms and replacement cycles.
The EPA regulates particulate emissions from tire manufacturing facilities in the United States, directly affecting reinforcement material processing standards and facility permitting requirements. REACH compliance in Europe mandates disclosure of Substances of Very High Concern in chemical treatments applied to tire cords, reshaping supplier qualification protocols for access to EU tire OEMs. China's GB standards and MEE environmental enforcement are tightening wastewater and emission controls at steel cord and fabric treatment plants. Stakeholders must monitor evolving chemical compliance thresholds and carbon intensity benchmarks as these become embedded in OEM procurement criteria and trade access conditions.
Market Dynamics
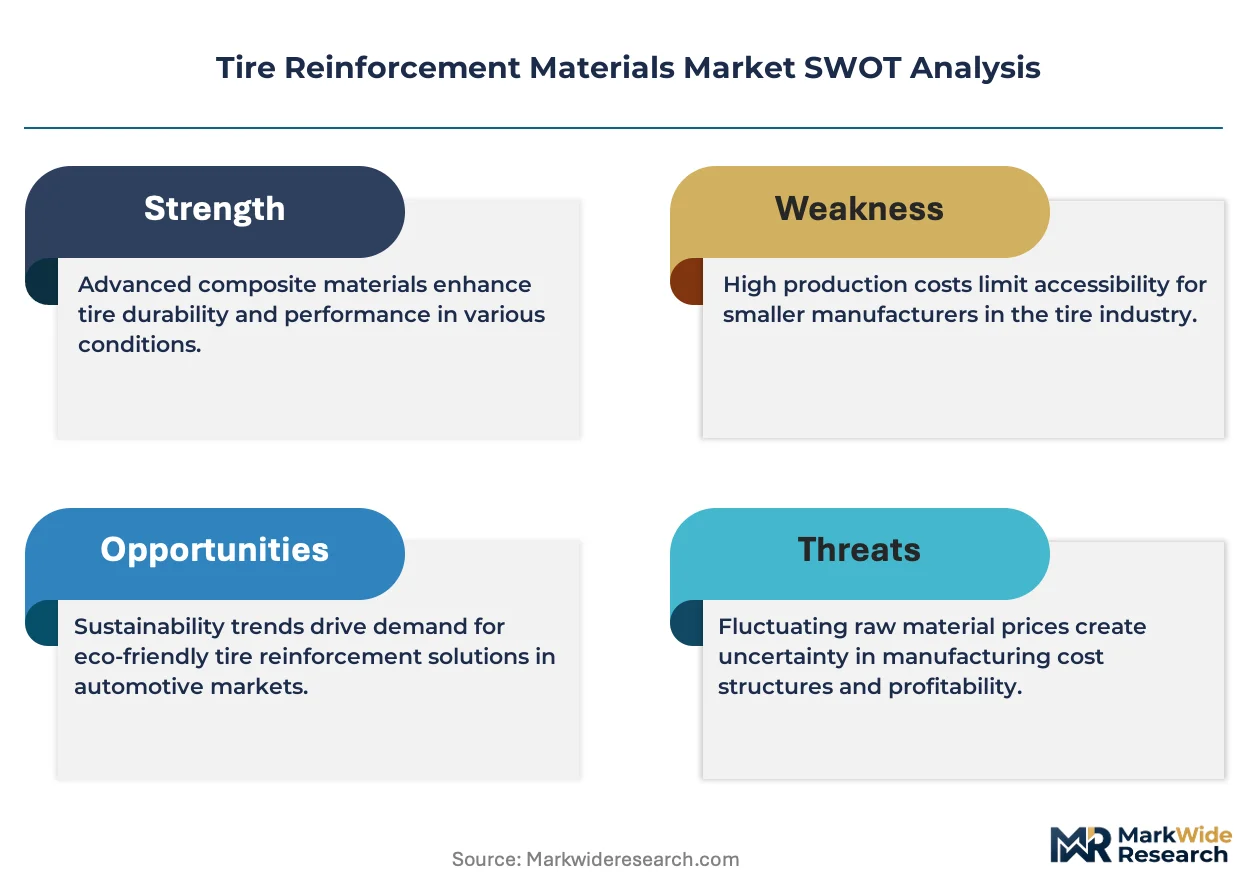
Electric vehicle battery weight loads are forcing tire reinforcement specifications upward, while EU REACH chemical disclosure mandates are rewriting supplier qualification protocols across the value chain.
Growth Catalysts
- REACH SVHC disclosure mandates:European OEMs now require full chemical treatment transparency in tire cord supply chains, accelerating qualification of compliant reinforcement material producers.
- High-tensile steel cord adoption:Commercial vehicle fleets operating in China and India are specifying advanced steel constructions to manage heavier axle loads on expanded highway networks.
- Aramid fiber penetration:Performance tire manufacturers targeting electric vehicle range optimization are embedding aramid reinforcements to reduce unsprung mass without sacrificing durability.
Market Restraints
- Brass coating input volatility:Copper and zinc price swings directly compress margins on high-carbon steel cord production, particularly for non-integrated manufacturers lacking captive metal supply.
- Steel cord supply concentration:Belgian and Chinese producers control the majority of high-tensile capacity, creating bottleneck risk for tire makers in South Asia and Latin America.
- Polymer substitution ceiling:Aramid and carbon fiber reinforcements face technical barriers in heavy-duty mining and agricultural tire segments where cut-through resistance demands steel.
Strategic Opportunities
- India tire export expansion:Domestic tire makers in Gujarat and Tamil Nadu are scaling radial capacity for Middle Eastern and African replacement markets, opening reinforcement material procurement windows.
- Carbon fiber-rubber bonding advances:Emerging surface treatment chemistries are enabling hybrid reinforcement architectures that combine carbon fiber stiffness with steel fatigue resistance.
- China MEE environmental enforcement:Tightened wastewater standards at steel cord plants are accelerating consolidation, creating acquisition targets for compliance-capable multinationals.
Industry Challenges
- Polymer-weaving technician scarcity:Nylon and polyester tire cord production requires specialized loom operators whose training pipelines have narrowed in Western Europe and Japan.
- REACH compliance timeline compression:Substance of Very High Concern candidate list expansion is forcing reformulation cycles faster than traditional automotive qualification windows permit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Reinforcement Materials Market |
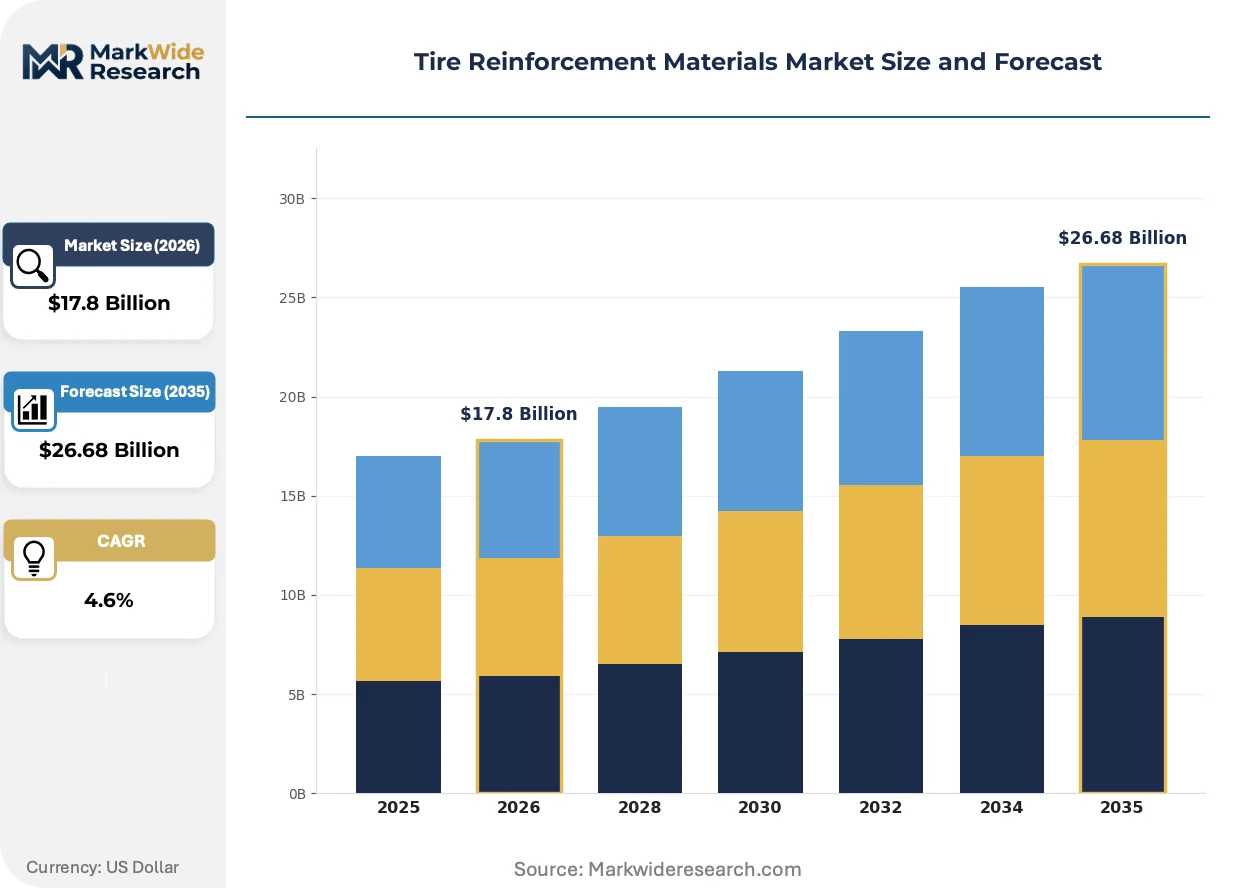
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Polyester, Nylon, Aramid Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles Manufacturing Process: Extrusion, Weaving, Bonding, Molding End User: Tire Manufacturers, OEMs, Aftermarket Providers, Distributors |
| Companies Covered | Continental AG, Hyosung Corporation, Bekaert NV, Toray Industries, Inc., Sumitomo Rubber Industries, Ltd., Bridgestone Corporation, Kordsa Global, Teijin Limited, Michelin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Reinforcement Materials Market Strategic Shifts & Innovations
Material science breakthroughs and chemical regulatory stringency are converging to reshape reinforcement specifications, with sustainability metrics now embedded in OEM procurement scorecards alongside performance benchmarks.
Hybrid aramid-steel cord constructions are rendering obsolete single-material reinforcement designs in premium passenger tires. Tier 1 suppliers to German and Korean electric vehicle platforms are qualifying these hybrids for original fitment, enabling 12-15% weight reduction in tire belt packages without the fatigue trade-offs of pure aramid solutions.
EU REACH Substances of Very High Concern disclosure requirements are forcing chemical treatment reformulations across the tire cord supply chain. Brass coating chemistries and adhesion promoters face intensified scrutiny, compelling reinforcement producers to establish analytical laboratories capable of certifying SVHC-free status to retain access to European OEM qualification programs.
Fleet procurement departments are consolidating tire supplier relationships and demanding lifecycle cost documentation that incorporates reinforcement durability data. Large logistics operators in North America and Western Europe are shifting from spot purchasing to multi-year framework agreements with embedded performance guarantees, compressing the viable supplier base to those with verified testing infrastructure and actuarial wear modeling capabilities.
Tire Reinforcement Materials Market Segmentation
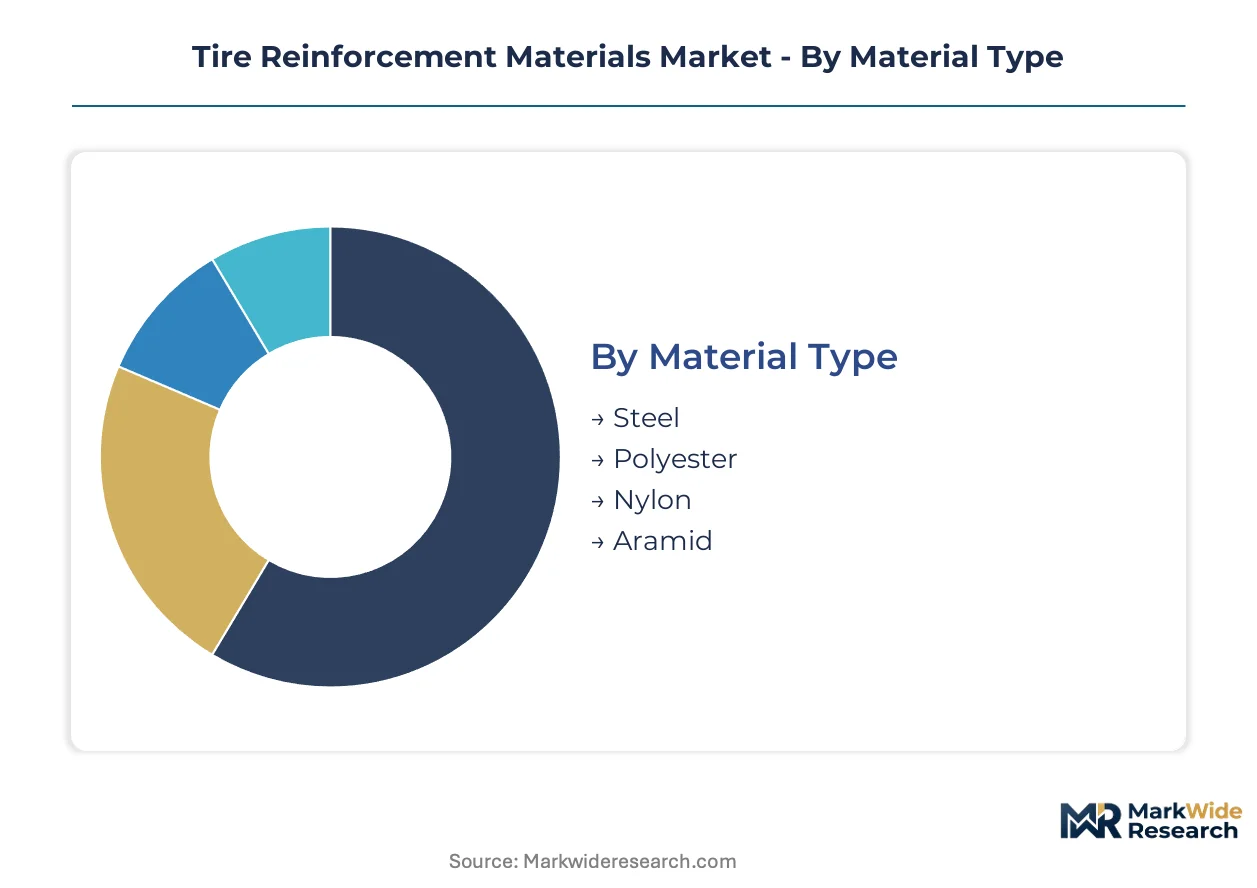
Tire reinforcement materials segment along material chemistry, vehicle application, and manufacturing methodology. Each dimension carries distinct margin profiles and qualification barriers that shape supplier positioning across OEM and replacement channels.
Material Type:
The maturity spectrum spans from century-old steel constructions to emerging aramid architectures, with polyester and nylon occupying intermediate technology positions.
- Steel:Brass-coated high-carbon steel filaments twisted into multi-layer cord constructions deliver fatigue resistance and cut-through strength. Commercial vehicle fleets operating in China and India specify advanced steel constructions to manage heavier axle loads on expanded highway networks, though copper and zinc price volatility compresses margins for non-integrated producers.
- Aramid:Aromatic polyamide fibers provide exceptional strength-to-weight ratios for performance applications. Electric vehicle manufacturers targeting range optimization embed aramid reinforcements to reduce unsprung mass without sacrificing durability, making this the fastest-expanding material category.
- Polyester:PET-based tire cord offers dimensional stability and heat resistance for passenger car radial tires at moderate cost points.
- Nylon:Polyamide 6 and 6,6 variants excel in impact absorption and flex fatigue resistance for heavy-duty and off-road tire constructions.
Steel handles the majority of throughput; aramid is the fastest mover on share.
Application:
Volume concentration follows vehicle parc distribution, with passenger cars generating the deepest specification diversity across platform replacement cycles.
- Passenger Cars:Radial tire constructions demand hybrid reinforcement packages combining steel belt plies with textile body plies. German and Korean electric vehicle platforms are qualifying aramid-steel hybrids for original fitment, enabling weight reduction in tire belt packages without fatigue trade-offs.
- Commercial Vehicles:Heavy-duty truck and bus tires require high-tensile steel cord constructions to manage sustained highway loads and retread cycles. Fleet procurement departments are consolidating supplier relationships and demanding lifecycle cost documentation incorporating reinforcement durability data.
- Two-Wheelers:Motorcycle and scooter tires utilize nylon-based bias constructions for maneuverability and cost efficiency in high-volume Asian markets.
- Off-Road Vehicles:Mining and agricultural tires face technical barriers to polymer substitution where cut-through resistance demands steel reinforcement.
Passenger cars dominate volume throughput; commercial vehicles command premium positioning on unit economics.
Manufacturing Process:
Process selection tracks material form factor and final tire architecture requirements, with weaving and bonding commanding specialized equipment investments.
- Extrusion:Continuous steel cord and monofilament production through die-forming operations.
- Weaving:Textile tire cord fabric formation requiring specialized loom operators whose training pipelines have narrowed in Western Europe and Japan.
- Bonding:Adhesion promoter application and rubber-coating operations face intensified REACH scrutiny on chemical treatments.
- Molding:Final tire curing processes integrating reinforcement packages into tread and sidewall compounds.
Weaving handles textile throughput; bonding faces the steepest regulatory transformation.
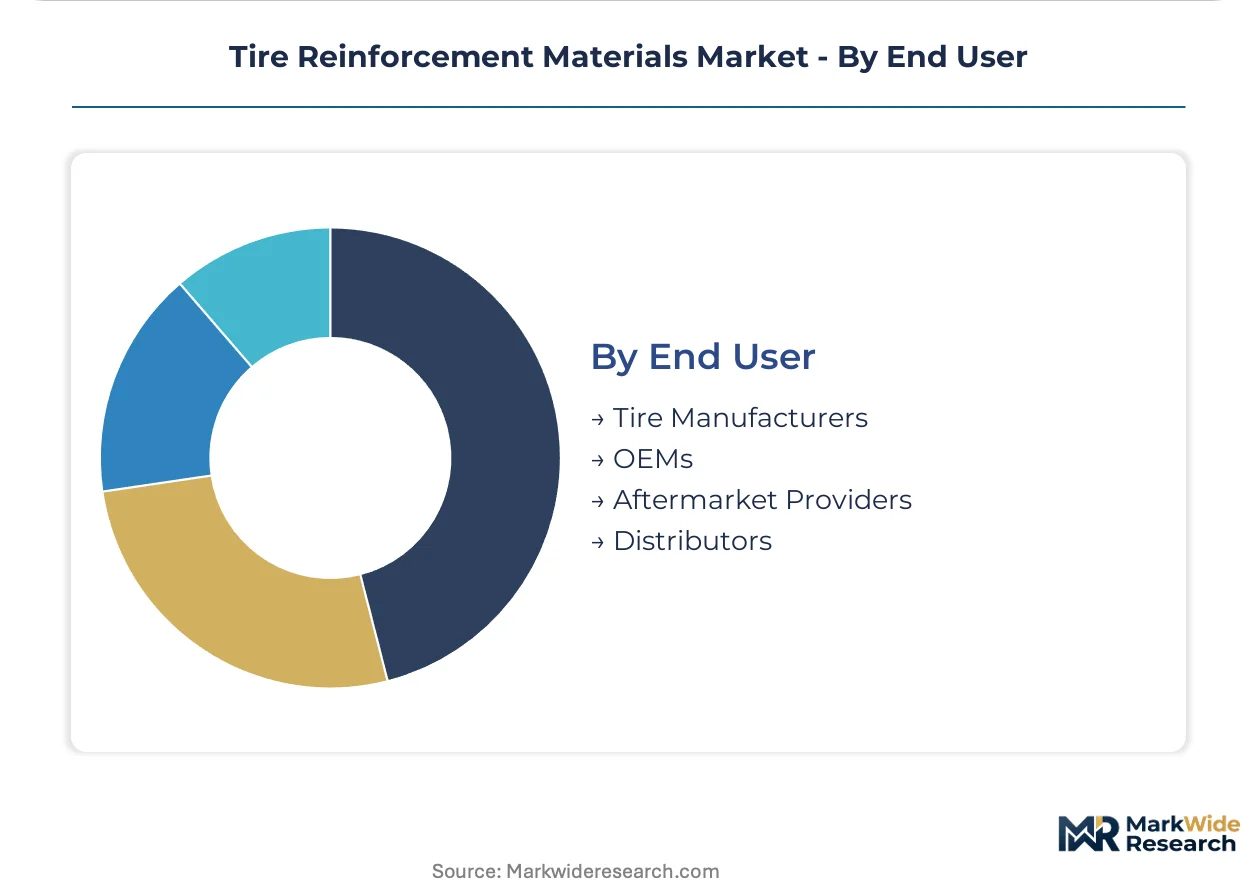
End User:
Customer type determines qualification protocols and contract structures, with OEMs imposing the most stringent performance documentation requirements.
- Tire Manufacturers:Integrated producers and standalone tire makers source reinforcement materials based on platform specifications and regional cost structures.
- OEMs:Vehicle assemblers specify reinforcement grades through approved supplier lists with embedded performance guarantees, compressing the viable supplier base to those with verified testing infrastructure.
- Aftermarket Providers:Replacement tire distributors and retailers procure based on price-performance positioning across premium, standard, and economy tiers.
- Distributors:Wholesalers and logistics operators manage inventory positioning across regional demand clusters.
OEMs drive specification innovation; aftermarket providers concentrate volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE environmental enforcement in China anchors the dominant geography, where tightened wastewater standards at steel cord plants are accelerating consolidation and reshaping procurement patterns for tire manufacturers worldwide.
China
Domestic tire makers in Shandong and Jiangsu provinces are scaling radial capacity for export markets to the Middle East and Africa. GB standards and MEE environmental enforcement are tightening wastewater controls at steel cord and fabric treatment plants. Qingdao and Dongying industrial clusters host expanding high-tensile steel cord operations serving both domestic OEMs and international replacement channels.
United States
Commercial vehicle fleets operating on expanded interstate highway networks are specifying advanced steel constructions to manage heavier axle loads. EPA particulate emission regulations directly affect reinforcement material processing standards and facility permitting requirements. Southeast manufacturing corridors in Georgia and South Carolina concentrate tire production capacity with integrated reinforcement supply chains.
Germany
Electric vehicle OEMs in Stuttgart and Munich are qualifying hybrid aramid-steel reinforcement packages for original fitment on premium passenger platforms. REACH Substances of Very High Concern disclosure mandates are rewriting supplier qualification protocols across the value chain. Ruhr Valley industrial zones maintain specialized steel wire operations serving continental tire manufacturers.
India
Domestic tire makers in Gujarat and Tamil Nadu are scaling radial capacity for Middle Eastern and African replacement markets. Central Electricity Authority and Bureau of Indian Standards frameworks govern industrial energy use and material specifications at manufacturing facilities. Chennai and Ahmedabad production hubs are opening reinforcement material procurement windows as export-oriented capacity expands.
Japan
Performance tire manufacturers are embedding aramid reinforcements to reduce unsprung mass for electric vehicle range optimization. METI industrial standards and JIS certification requirements shape material qualification pathways for domestic OEM supply chains. Nagoya and Osaka metropolitan industrial zones concentrate carbon fiber reinforcement technology development for next-generation tire architectures.
Tire Reinforcement Materials Market Key Industry Players
Integrated steel wire operators and specialized polymer fabricators split the market along material chemistry lines. The structure concentrates high-tensile steel capacity among Belgian and Chinese producers while aramid and polyester supply fragments across Asian and European specialists. Three archetypes dominate: captive steel wire integrators, polymer-to-fabric vertical specialists, and carbon fiber technology developers. Capacity expansion and REACH compliance certification represent the dominant competitive moves as OEM procurement scorecards embed chemical transparency requirements.
Among Belgian-based steel wire operators, Bekaert NV exemplifies the integrated archetype with operations spanning European and Chinese production bases. Hyosung Corporation anchors the polymer-to-fabric specialist tier through South Korean weaving and polymer supply integration. Toray Industries, Inc. occupies a position within the advanced materials tier, representing carbon fiber reinforcement technology development for emerging tire architectures. These three entities collectively illustrate the geographic and technological segmentation that defines supplier positioning across OEM and replacement channels.
| Leading Market Players |
|---|
| Continental AG |
| Hyosung Corporation |
| Bekaert NV |
| Toray Industries, Inc. |
| Sumitomo Rubber Industries, Ltd. |
| Bridgestone Corporation |
| Kordsa Global |
| Teijin Limited |
| Michelin Group |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese steel cord facilities is compressing supplier margins and forcing pricing concessions to European tire makers seeking dual-source security. This utilization squeeze simultaneously accelerates consolidation among domestic producers and shifts bargaining power toward multinational buyers with REACH-compliant qualification status.
Pricing Analysis
Belgian and Chinese steel cord producers command a 15-20% premium over Indian and Southeast Asian competitors on high-tensile specifications. Price differentiation rests on brass coating quality grades and EU REACH SVHC certification tiers, with OEM-approved suppliers capturing margin pools unavailable to uncertified rivals. Pricing pressure stems from copper and zinc input volatility eroding brass coating economics. Fleet procurement departments exhibit the highest price sensitivity through consolidated multi-year framework agreements, while premium passenger OEMs prioritize qualification stability over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for European tire OEMs sourcing Chinese steel cord, straining working capital at non-integrated producers. Supply concentrates in Belgium, China, and South Korea, with high-tensile capacity anchored in Ruhr Valley and Qingdao industrial clusters. The chain draws from high-carbon steel wire rod, copper and zinc for brass coating, and aramid polymer feedstock. Single-source vulnerability runs through Belgian high-tensile specialists serving German OEM platforms. Distribution runs through tire manufacturer integrated procurement divisions and approved supplier list frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as European tire OEMs consolidate supplier relationships around REACH-compliant producers with verified testing infrastructure. This consolidation compresses the viable supply base to integrated operators with analytical laboratory capabilities.
For Market Incumbents: Entrench qualification status by accelerating SVHC-free certification investments and expanding captive brass coating capacity to buffer metal price volatility. Bekaert NV's integrated steel wire model across Belgium and China illustrates the defensive architecture required. Threat of polymer substitution in passenger electric vehicle tires demands parallel aramid-steel hybrid R&D pipelines. For New Entrants and Emerging Players: Establish a beachhead in India's radial tire export supply chain serving Middle Eastern and African replacement markets. Gujarat and Tamil Nadu production hubs offer procurement windows as domestic capacity scales. Target carbon fiber-rubber bonding technology licensing to Japanese performance tire manufacturers seeking next-generation architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across REACH-compliant steel cord production as analytical laboratory investments become mandatory for European OEM access. Long-term viability favors integrated operators with captive polymer or metal supply. Acquisition targets include Chinese steel cord facilities facing MEE environmental enforcement consolidation. Watch for brass coating input price spikes as early indicators of margin compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| REACH SVHC Certification Investment | Analytical laboratory capabilities unlock European OEM qualification programs for reinforcement producers. |
| Backward Integration into Brass Coating | Captive copper and zinc processing buffers margin volatility from London Metal Exchange price swings. |
| Aramid-Steel Hybrid R&D Program | German and Korean electric vehicle platforms are qualifying these constructions for original fitment. |
| India Manufacturing Footprint Expansion | Gujarat and Tamil Nadu hubs access Middle Eastern and African replacement market procurement windows. |
| Carbon Fiber Surface Treatment Licensing | Japanese performance tire manufacturers seek bonding chemistry advances for next-generation belt packages. |
Research Approach
Desk research of customs trade databases, SEC 10-K filings, and ECHA SVHC candidate list updates preceded structured interviews with tire manufacturer procurement directors, steel cord plant managers, polymer R&D leads, and REACH compliance officers. Primary fieldwork combined with secondary validation through BIS material specifications, MEE environmental enforcement records, and IHS Markit vehicle production data. Bottom-up capacity modeling and top-down OEM demand triangulation anchored volume estimates.
Assumptions held fixed include current EU REACH disclosure thresholds, Chinese GB standard wastewater limits, and brass coating chemistry compositions. Variable assumptions encompass electric vehicle penetration rates, commercial vehicle axle load regulations, and aramid fiber cost curves. The analytical framework modeled material chemistry, vehicle application, and manufacturing process segments across the projection horizon. CAGRs derived from installed tire capacity expansion, replacement cycle frequencies, and content-per-vehicle reinforcement specifications.
Sensitivities concentrate around REACH SVHC candidate list expansion timelines, Chinese MEE enforcement intensity, and copper-zinc price correlation breakdowns. Forecasts reflect these documented assumptions. Macroeconomic deviation in commercial vehicle fleet investment, regulatory acceleration in chemical disclosure mandates, or breakthroughs in carbon fiber-rubber bonding would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Global Tire Material Market
Rubber
Performance Elastomers Market
Rubber
Hospital Rubber Sheet Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Silica for S-SBR Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Wear Liners Market
Rubber
Polyisoprene Market
Rubber
Rubber Accelerators Market
Rubber
Liquid Silicone Rubber Market
Rubber
Europe Neoprene Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Plastomers Market
Rubber
Rubber Color Masterbatch Market
Rubber
Rubber Sand Market