
 Plastomers Market | 2026-2036
Plastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Plastomers Market Analysis
Buyer concentration in automotive tier-one supply chains is shifting as OEMs consolidate qualified polymer vendors across multiple component categories. SABIC leverages its vertical integration from feedstock to compounded resin to secure long-term supply agreements with European and Asian automakers. Dow differentiates through catalyst technology leadership in metallocene-based polyolefin elastomers, while ExxonMobil Chemical dominates capacity positions in North American ethylene-alpha olefin copolymer production.
Plastomers are polymeric materials exhibiting properties intermediate between thermoplastics and elastomers, typically produced via metallocene or single-site catalyst polymerization of ethylene with alpha-olefins such as 1-butene, 1-hexene, or 1-octene, yielding precise control over molecular weight distribution and crystallinity for applications requiring flexibility, toughness, and processability. Thermoplastic polyolefins anchor the largest volume position due to their cost-performance balance in automotive bumper fascia and interior skins, while thermoplastic elastomers capture expanding margin pools in medical device tubing and soft-touch consumer electronics housings where overmolding compatibility commands specification premiums. Thermoplastic polyurethanes occupy a specialized niche in high-performance films and textile coatings where abrasion resistance and optical clarity outweigh raw material cost premiums.
REACH registration requirements and EU F-Gas Regulation phase-down schedules are tightening compliance burdens for fluorinated processing aids used in plastomer extrusion, redirecting R&D spending toward PFAS-free additive packages. FDA biocompatibility standards and ISO 10993 testing protocols govern medical-grade plastomer qualification timelines in the United States and European healthcare sectors, creating multi-year barriers to entry for unvalidated suppliers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in Germany and France, where packaging recycling targets will increasingly dictate plastomer grade selection and design-for-recyclability investments.
Market Dynamics
Automotive lightweighting mandates are compressing material substitution cycles as OEMs replace conventional rubber with plastomers in seal systems and interior components. REACH registration deadlines and EU F-Gas phase-down schedules are simultaneously forcing reformulation investments across European compounders.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards in the United States and EU CO2 fleet targets are accelerating plastomer substitution for metal and rubber in bumper fascia and weatherstrip profiles.
- REACH-driven bio-based grade development:ECHA registration requirements for new polymer substances are redirecting R&D budgets toward renewable feedstock routes and chemically recyclable architectures.
- Medical device tubing demand:ISO 10993 biocompatibility protocols are creating specification premiums for thermoplastic elastomers in catheters and fluid management systems.
Market Restraints
- Alpha-olefin feedstock volatility:1-octene and 1-hexene supply tightness from steam cracker co-product streams generates margin compression for ethylene-alpha olefin copolymer producers.
- Metallocene catalyst concentration:Single-site catalyst intellectual property and manufacturing know-how concentrate among a handful of technology licensors, limiting new entrant capacity additions.
- Fluorinated processing aid regulatory friction:EU F-Gas Regulation phase-down schedules and emerging PFAS restrictions in Germany and France are eliminating incumbent extrusion additives faster than replacements qualify.
Strategic Opportunities
- India automotive compounding expansion:PLI scheme incentives for advanced chemistry cell and component manufacturing are attracting polymer compounders to Gujarat and Tamil Nadu industrial corridors.
- Design-for-recyclability mandates:Extended Producer Responsibility frameworks in Germany and France will reward mono-material plastomer architectures in packaging films and consumer goods.
- Metallocene-PP hybrid technology convergence:Reactor-grade thermoplastic polyolefin elastomers with tunable crystallinity blocks are opening soft-touch electronics housing applications previously served by thermoplastic vulcanizates.
Industry Challenges
- Multi-year medical certification timelines:FDA 510(k) and EMA MDR conformity assessment procedures for implantable-grade plastomers extend qualification cycles beyond typical capital planning horizons.
- PFAS-free additive package integration:Reformulating extrusion and molding compounds without fluorinated process aids requires concurrent validation of surface finish, cycle time, and scrap rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastomers Market |
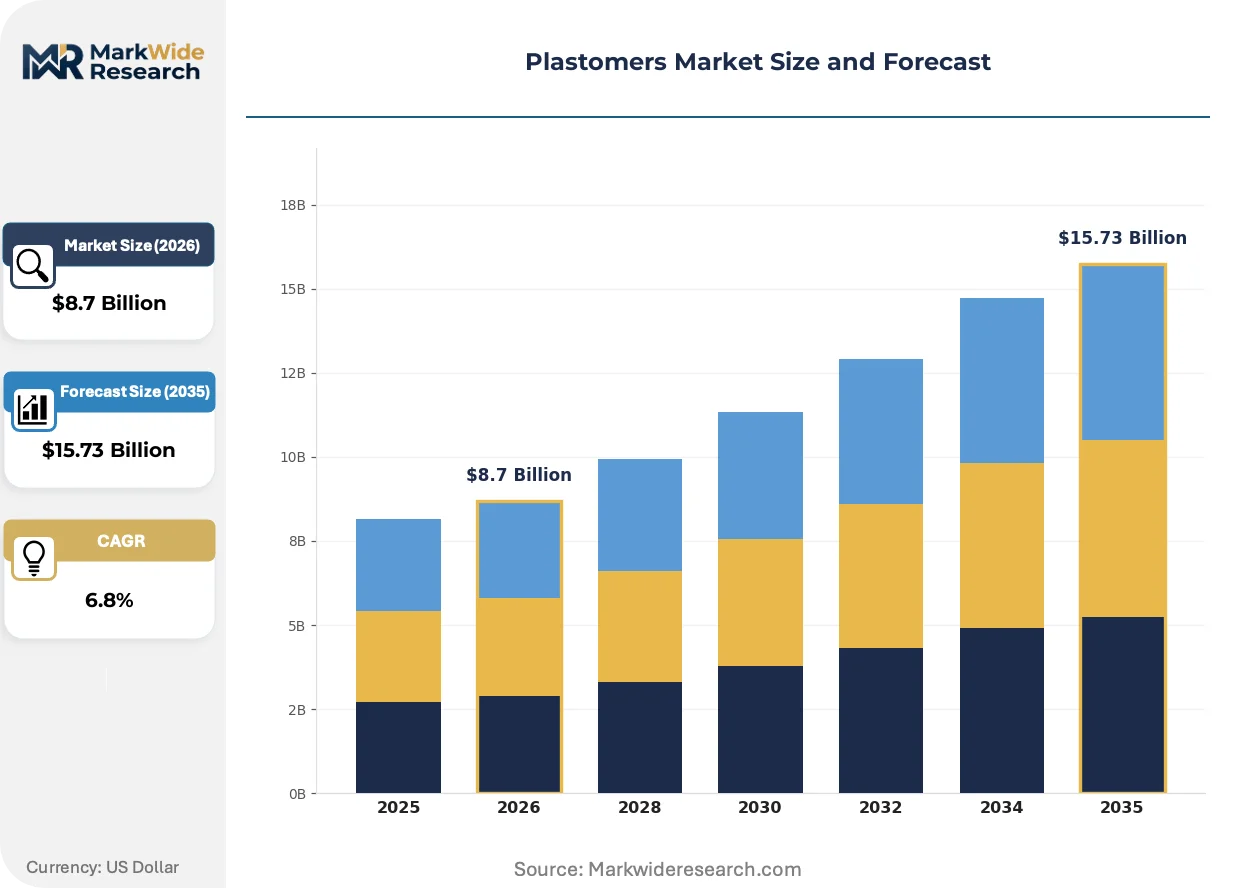
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Copolymers, Thermoplastic Elastomers, Thermoplastic Polyolefins, Thermoplastic Polyurethanes Application: Automotive Components, Consumer Goods, Medical Devices, Packaging Solutions End User: Automotive Industry, Healthcare Sector, Electronics Manufacturers, Packaging Industry Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | SABIC, LG Chem, Dow, Sumitomo Chemical, LyondellBasell Industries, ExxonMobil Chemical, Mitsui Chemicals, Westlake Chemical Corporation, Borealis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastomers Market Emerging Trajectories
Single-site catalyst platforms and advanced process control systems are fragmenting the traditional trade-off between elastomeric performance and thermoplastic processability. These capabilities are enabling grade proliferation that targets narrower application specifications.
Reactor-grade thermoplastic polyolefin elastomers with in-situ rubber phase morphology control are decentralizing the historical dominance of mechanically blended compounds. Tier-one automotive suppliers in Stuttgart and Shanghai are qualifying these materials for instrument panel skins and door seals. The technology is decentralizing compounding value capture from independent compounders back to integrated resin producers.
ECHA PFAS restriction proposals under REACH are forcing additive package redesigns across European extrusion operations. Compounders are trialing polymer processing aids based on polyethylene wax and modified polyolefin architectures to maintain surface quality. Medical tubing and food contact film segments face the steepest requalification burdens as they cannot tolerate process variability during transition.
Automotive OEMs are consolidating qualified polymer vendors across interior, exterior, and underhood categories to reduce qualification overhead. Procurement teams in Detroit, Wolfsburg, and Toyota City are awarding multi-year resin supply agreements with embedded volume commitments and technical service provisions. This concentration is most advanced in electric vehicle platforms where thermal management and crash performance requirements have tightened material specifications.
Plastomers Market Segmentation
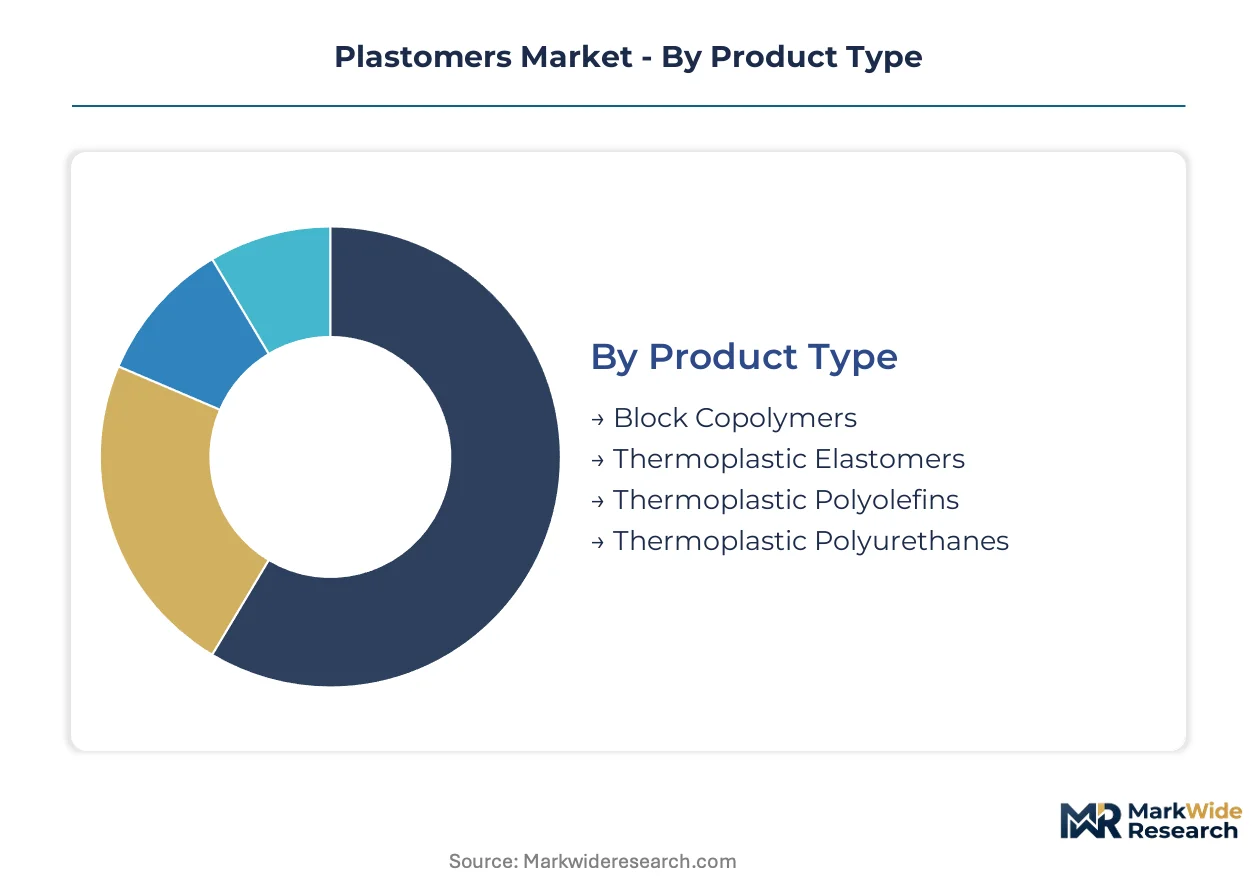
Plastomer grade selection hinges on crystallinity control and catalyst architecture, with specification boundaries blurring as reactor-grade materials displace mechanically blended compounds. Automotive procurement teams now specify by performance tier rather than traditional polymer taxonomy, compressing the relevance of historical product-type distinctions.
Product Type:
Metallocene catalyst platforms enable precise control over molecular weight distribution and rubber-phase morphology, differentiating performance across the crystallinity spectrum.
- Thermoplastic Polyolefins:Reactor-grade TPOs with in-situ rubber phase morphology anchor volume positions in bumper fascia and instrument panel skins. Demand concentrates in Stuttgart and Toyota City as electric vehicle platforms tighten thermal management specifications.
- Thermoplastic Elastomers:Styrenic block copolymers and copolyester elastomers deliver overmolding compatibility for soft-touch electronics housings. Medical device tubing in ISO 10993-governed segments commands specification premiums due to multi-year qualification barriers.
- Thermoplastic Polyurethanes:Abrasion-resistant grades with optical clarity serve high-performance films and textile coatings where raw material cost premiums are offset by durability requirements.
- Block Copolymers:Hydrogenated styrenic mid-block architectures provide compression set resistance in automotive weatherstrip and seal applications.
Mature deployment sits with Thermoplastic Polyolefins in automotive exterior panels. Newer deployment is concentrated in Thermoplastic Elastomers for medical-grade tubing and soft-touch consumer electronics.
Application:
End-use requirements dictate molecular architecture selection, with regulatory compliance timelines creating divergent margin structures across segments.
- Automotive Components:Lightweighting mandates from NHTSA and EU CO2 fleet targets accelerate substitution for metal and rubber in bumper fascia, door seals, and underhood components. REACH-driven bio-based grade development redirects formulation investments for seal systems.
- Medical Devices:Catheters, fluid management systems, and implantable components require FDA 510(k) or EMA MDR conformity assessment. Extended qualification cycles beyond typical capital planning horizons protect incumbent suppliers.
- Packaging Solutions:Extended Producer Responsibility frameworks in Germany and France reward mono-material architectures in films and flexible packaging. PFAS-free additive package integration remains unresolved for surface quality-critical applications.
- Consumer Goods:Soft-touch housings and overmolded grips leverage thermoplastic elastomer processability in electronics and personal care products.
Specification premiums peak in Medical Devices due to biocompatibility certification burdens. Volume expansion is climbing the fastest in Automotive Components as electric vehicle platforms consolidate material specifications.
End User:
Procurement consolidation across tier-one supply chains is compressing vendor qualification overhead and embedding technical service provisions in multi-year agreements.
- Automotive Industry:OEMs in Detroit, Wolfsburg, and Toyota City consolidate qualified polymer vendors across interior, exterior, and underhood categories. Long-term supply agreements now include embedded volume commitments and collaborative R&D provisions.
- Healthcare Sector:Hospital systems and device manufacturers in the United States and European Union face ISO 10993 and FDA biocompatibility standards that govern qualification timelines. The steepest requalification burdens fall on tubing and fluid management applications.
- Electronics Manufacturers:Soft-touch housing demand from consumer electronics OEMs drives overmolding compatibility specifications for thermoplastic elastomers.
- Packaging Industry:Film converters and flexible packaging producers navigate ECHA PFAS restriction proposals and national Extended Producer Responsibility targets.
Contract security is strongest with Automotive Industry procurement teams. Technical validation intensity is highest in Healthcare Sector engagements.
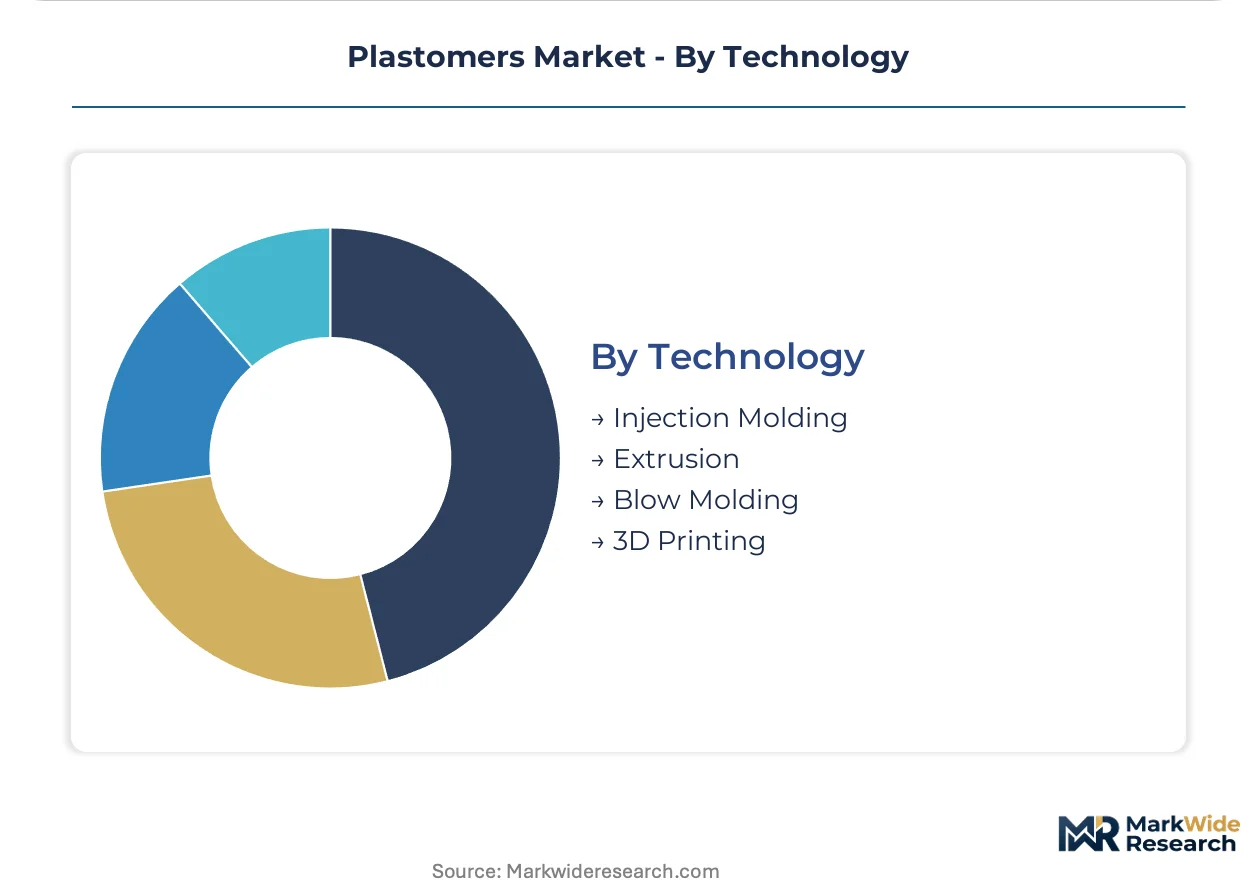
Technology:
Processing method selection interacts with additive package architecture, particularly as fluorinated processing aids face regulatory phase-down schedules.
- Injection Molding:High-volume automotive interior and consumer electronics components rely on cycle time optimization and surface finish consistency. PFAS-free processing aid trials are most advanced in this segment.
- Extrusion:Weatherstrip profiles, medical tubing, and packaging films depend on melt strength and dimensional stability. EU F-Gas Regulation compliance is eliminating incumbent additives faster than polyethylene wax replacements qualify.
- Blow Molding:Hollow automotive components and industrial containers leverage plastomer toughness and processability.
- 3D Printing:Emerging filament and powder bed applications for prototyping and low-volume production are gaining specification traction in medical device development workflows.
Process maturity concentrates in Injection Molding for automotive and electronics volume. Regulatory disruption is most acute in Extrusion operations serving European medical and food contact segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene-alpha olefin feedstock availability from Gulf Coast steam crackers anchors United States capacity positions, while metallocene catalyst manufacturing clusters concentrate in Germany and Japan.
United States
NHTSA fuel economy standards accelerate plastomer substitution in automotive bumper fascia and weatherstrip profiles. EPA oversight of chemical manufacturing interacts with state-level environmental regulations in Texas and Louisiana. Houston-Galveston petrochemical corridors host integrated ethylene-alpha olefin copolymer production serving Detroit and Toyota City automakers.
Germany
EU CO2 fleet targets compress material substitution cycles for OEMs replacing conventional rubber in seal systems. REACH registration deadlines and ECHA PFAS restriction proposals force reformulation investments across compounders in Baden-Württemberg. Stuttgart automotive clusters qualify reactor-grade thermoplastic polyolefins for electric vehicle instrument panel skins.
China
Dual carbon goals and MIIT industrial policy redirect polymer investments toward lightweighting-compatible grades. GB standards and SAMR market supervision govern food contact film and medical tubing specifications. Yangtze River Delta compounding infrastructure in Jiangsu and Zhejiang provinces serves Shanghai-based electric vehicle platforms.
Japan
METI technology roadmaps prioritize advanced catalyst platforms for molecular architecture control. JIS standards and PMDA medical device regulations extend qualification timelines for implantable-grade materials. Nagoya-Toyota City automotive supply chains integrate thermoplastic elastomers for soft-touch interior components.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract polymer compounders to industrial corridors. BIS standards and CDSCO medical device regulations create multi-year validation requirements for tubing applications. Gujarat and Tamil Nadu chemical parks develop compounding capacity for domestic automotive tier-one suppliers.
Plastomers Market Vendor Landscape
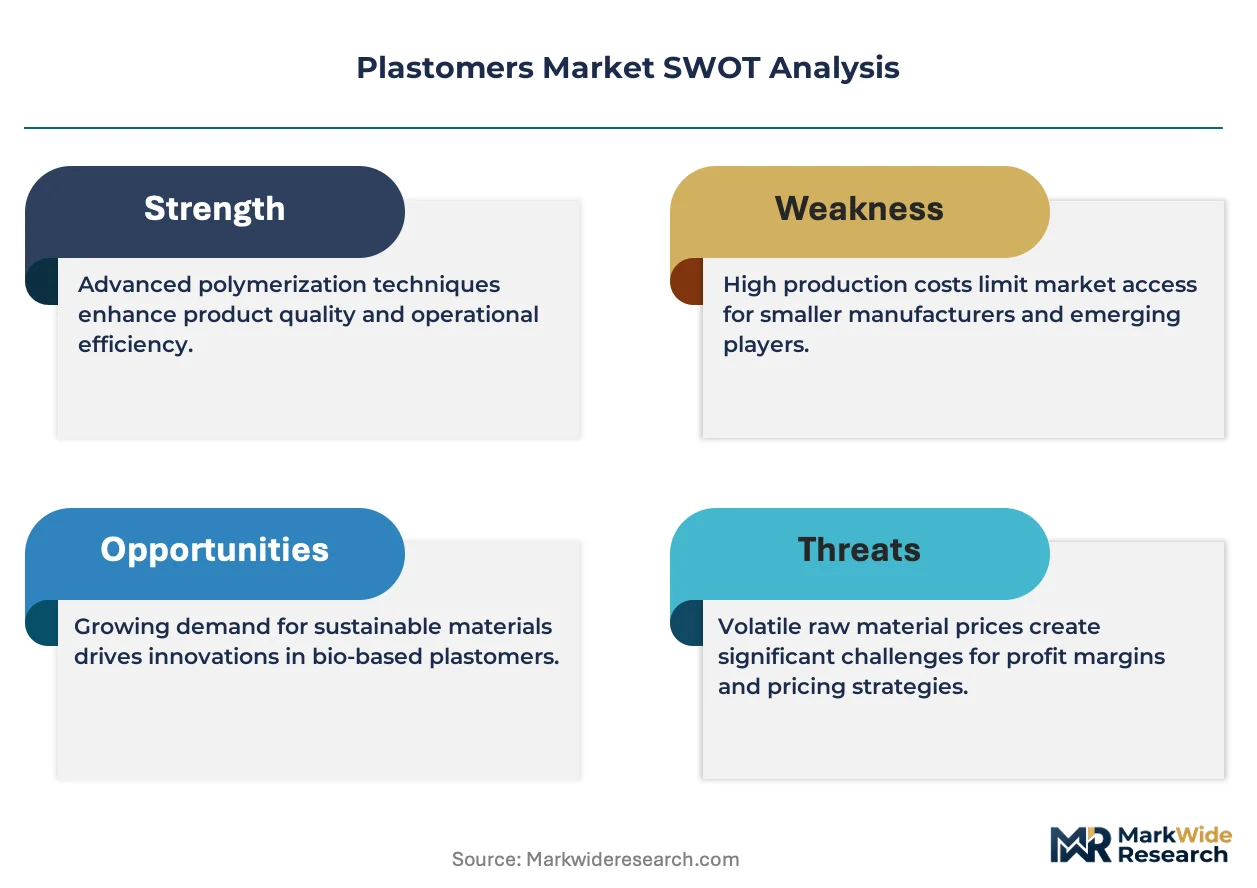
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock routes and specialty medical grades. The vendor base concentrates among integrated petrochemical conglomerates with captive ethylene supply, regional chemical majors with catalyst technology licensing, and specialized compounders serving ISO 10993-governed healthcare segments. Dominant competitive moves include capacity expansion in low-cost feedstock regions and strategic partnerships with automotive OEMs for multi-year supply agreements.
Within the integrated petrochemical tier, SABIC, Dow, and ExxonMobil Chemical exemplify archetypes defined by feedstock access and catalyst control. SABIC represents Middle Eastern producers leveraging ethane cost positions; Dow anchors North American metallocene technology leadership; ExxonMobil Chemical occupies the scale-driven end of ethylene-alpha olefin copolymer manufacturing. These entities sit within a competitive structure where backward integration into feedstock and forward integration into compounded resin capture value across specification tiers.
| Leading Market Players |
|---|
| SABIC |
| LG Chem |
| Dow |
| Sumitomo Chemical |
| LyondellBasell Industries |
| ExxonMobil Chemical |
| Mitsui Chemicals |
| Westlake Chemical Corporation |
| Borealis AG |
| Others |
Supply Flow & Price Mechanics
Metallocene catalyst specialists concentrated in Germany and Japan drive labor-cost differentials that widen spreads between premium reactor-grade and standard mechanically blended plastomer tiers. REACH registration burdens and EU F-Gas compliance investments compound these gaps as European compounders pass reformulation costs downstream.
Pricing Analysis
Volume concentration in commodity thermoplastic polyolefins compresses margins, while specification premiums widen for medical-grade thermoplastic elastomers facing ISO 10993 certification barriers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical grades from automotive specification tiers and bulk packaging compounds. Pricing pressure stems from alpha-olefin feedstock tightness as steam cracker co-product availability constrains 1-octene supply. Packaging converters exhibit highest price sensitivity due to thin margins and substitutability with conventional polyolefins, whereas medical device OEMs absorb premiums to secure multi-year qualification security.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are redirecting compounding investments toward Gujarat and Tamil Nadu corridors, reshaping regional sourcing patterns for automotive tier-one suppliers. Feedstock concentration centers on the United States Gulf Coast, Germany's Rhine-Ruhr chemical cluster, and Saudi Arabia's ethane-advantaged complexes. Supply chains draw from alpha-olefin co-product streams, metallocene catalyst manufacturing nodes in Germany and Japan, and fluorinated processing aid stocks facing ECHA phase-down deadlines. Single-source vulnerability concentrates in metallocene catalyst intellectual property held by technology licensors. Distribution runs through integrated resin producers with captive compounding, independent compounders serving medical specialty grades, and direct automotive OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration requirements and ECHA PFAS restrictions erect barrier-to-entry moats favoring incumbents with validated additive packages and established regulatory dossiers.
For Market Incumbents: Deploy catalyst technology licensing as a defensive lever to capture value from reactor-grade TPO proliferation while consolidating qualified vendor positions across automotive interior, exterior, and underhood categories. Secure long-term alpha-olefin supply agreements to hedge feedstock volatility from steam cracker co-product tightness. Deepen backward integration into bio-based feedstock routes to preempt EU Green Deal mandates reshaping specification premiums. For New Entrants and Emerging Players: Specialty medical device tubing manufacturers underserved by incumbent compounders present the most penetrable entry point given multi-year FDA 510(k) and EMA MDR timelines protecting validated suppliers. Target India's PLI-subsidized automotive compounding corridors where domestic capacity lags demand from Gujarat and Tamil Nadu industrial clusters. Pursue partnership-based go-to-market models with European compounders seeking PFAS-free additive package co-development. For Investors and Strategic Acquirers: Re-rating potential sits with metallocene-PP hybrid technology specialists given reactor-grade material displacement of mechanically blended compounds across soft-touch electronics applications. Long-term viability favors integrated producers with captive ethylene supply and catalyst control spanning the analysis window. Monitor ECHA PFAS restriction implementation timelines as inflection indicators for additive package reformulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Supply | Captive 1-octene and 1-hexene production hedges margin compression from steam cracker co-product tightness. |
| PFAS-Free Additive Package Development | Polyethylene wax and modified polyolefin architectures secure ECHA compliance ahead of restriction deadlines. |
| Reactor-Grade TPO Capacity Expansion | In-situ rubber phase morphology control captures value migration from independent compounders to resin producers. |
| Medical-Grade Certification Investment | FDA 510(k) and ISO 10993 validation creates multi-year barriers protecting specification premiums in tubing. |
| Long-Term Automotive Supply Agreement | Embedded volume commitments with Stuttgart and Toyota City OEMs reduce procurement consolidation risk. |
Methodological Framework
Trade databases, ECHA registration filings, and SEC chemical company disclosures formed the secondary backbone, cross-referenced with primary interviews involving polymer plant managers, automotive Tier 1 procurement leads, medical device regulatory affairs directors, and distribution channel partners. Bottom-up and top-down triangulation validated volume estimates against customs data and OEM material specification disclosures.
Bottom-up modeling anchored forecasts, with top-down macro checks against automotive production and medical device registration trends. Segmentation dimensions spanned crystallinity grade, catalyst architecture, end-use industry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution dynamics for rubber and rigid plastics. Industry-specific inputs included NHTSA fuel economy trajectory, EU CO2 fleet target stringency, and MIIT dual carbon policy implementation pace.
Revisions become necessary when ECHA PFAS restriction timelines accelerate, alpha-olefin supply disruptions exceed historical volatility bands, or automotive OEM vendor consolidation reverses toward multi-source strategies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
EPDM Rubber Market
Rubber
Acrylic Rubber Market
Rubber
FKM Elastomers Market
Rubber
Rubber Gloves Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Rubber Splicing Tape Market
Rubber
Global Crumb Rubber Market
Rubber
Rubber Bulbs Market
Rubber
Rubber Roller Cleaner Market
Rubber
Rubber Ropes Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Acrylic Based Elastomers Market
Rubber
Rubber Carbon Black Market
Rubber
Tire Chemicals Market
Rubber
Abrasion-Resistant Rubber Pipe Market