
 Rubber Sand Market | 2026-2036
Rubber Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Sand Market Analytics
Modular bulk packaging for rubber sand is consolidating buyer choice around standardized container loads rather than custom bag sizes. Sibelco leverages its European logistics network to anchor supply contracts with construction distributors. Vulcan Materials Company sustains geographic dominance across North American infrastructure projects through captive quarry access. Pattison Sand differentiates via specialized sizing capabilities for sports infill specifications.
Rubber sand consists of granulated rubber particles, typically derived from recycled tire crumb or virgin synthetic compounds, sized between 0.5 and 2.0 millimeters for industrial blending applications. The material functions primarily as a flexible aggregate additive that imparts shock absorption, drainage, and elasticity to surface systems in sports fields, playground bases, and architectural coatings. Natural rubber commands premium positioning in sports infill where elasticity performance justifies higher material cost, while reclaimed rubber occupies the fastest-expanding volume tier as circular economy mandates intensify tire recycling obligations. The coatings application segment carries concentrated margin pools due to specialized dispersion chemistry requirements and technical service bundling.
EPA guidelines on crumb rubber leachate testing shape product liability exposure for domestic suppliers, while REACH substance restrictions in Europe constrain aromatic oil content in recycled feedstock. OSHA silica exposure standards intersect with rubber sand handling protocols at blending facilities, forcing capital investment in dust suppression systems. Stakeholders must monitor evolving state-level procurement specifications for recycled content quotas in public works contracts.
Market Dynamics
REACH substance restrictions on aromatic oil content in recycled feedstock are forcing European suppliers to requalify entire supply chains, while municipal procurement mandates for recycled content quotas in Germany and France reshape volume allocation across the value chain.
Growth Catalysts
- EU circular economy mandates:Tire recycling obligations under extended producer responsibility frameworks are expanding reclaimed rubber feedstock availability for sand production.
- Sports field infrastructure:Municipal stadium upgrades across Germany are concentrating volume procurement of infill-grade rubber sand.
- Coatings chemistry bundling:Technical service partnerships with dispersion specialists are opening margin pools in architectural surface applications.
Market Restraints
- Feedstock certification costs:ECHA documentation requirements for SVHC screening in crumb rubber are elevating qualification expenses for smaller recyclers.
- Natural rubber price volatility:Plantation supply disruptions in Southeast Asia are compressing margins on premium sports infill grades.
- Substitute aggregate competition:Cork and coconut husk infill materials are capturing specification share in elite sports facility tenders.
Strategic Opportunities
- Modular bulk packaging:Standardized container loads are displacing custom bag sizes, enabling logistics network consolidation among European distributors.
- Playground safety surfacing:Fall-height certification requirements in France are creating specification pull for shock-absorbing rubber sand bases.
- EPR scheme alignment:Germany's tire stewardship program is generating captive feedstock access for integrated recyclers.
Industry Challenges
- OSHA silica exposure protocols:Dust suppression capital requirements at blending facilities are elevating operational fixed costs.
- Leachate testing variability:EPA guideline inconsistencies across state environmental agencies are fragmentating product liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Sand Market |
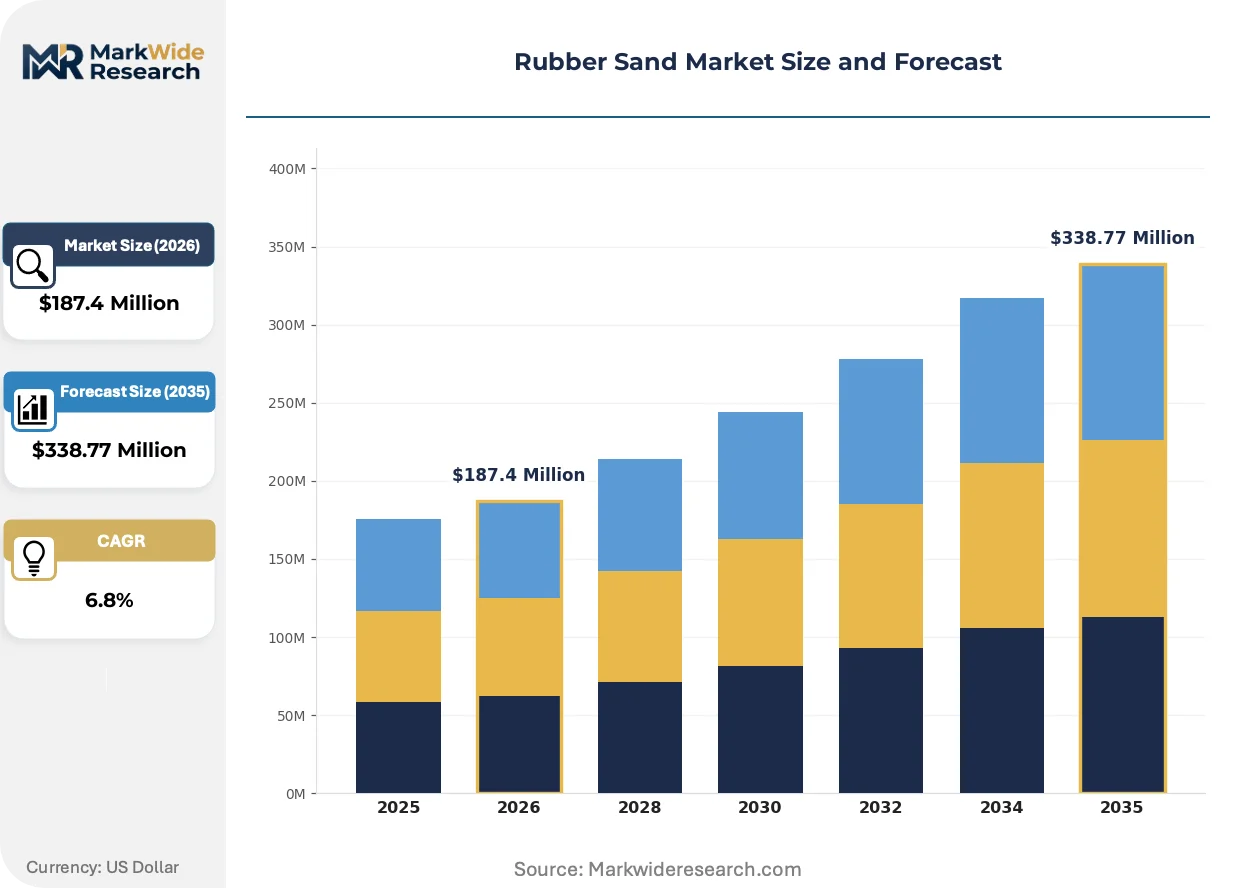
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Reclaimed Rubber, Blended Rubber End Use Industry: Construction, Automotive, Sports, Landscaping Application: Fillers, Coatings, Adhesives, Insulation Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Saint-Gobain, Nugent Sand, Pattison Sand, Sibelco, Vulcan Materials Company, Tochu Corporation, Quarzwerke, Asahi Yukizai Corp, Mangalore Minerals Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Sand Market Evolving Landscape
Material science advances and regulatory chemistry requirements are compressing traditional supply arrangements while opening new specification tiers for qualified producers.
Precision cryogenic grinding systems are rewriting particle size distribution control for sports infill applications. German turf installers are specifying sub-millimeter tolerances for shock absorption consistency. This capability compression is marginalizing ambient grinding operations unable to meet certification thresholds.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in extender oils are tightening feedstock acceptance criteria across European compounding operations. Suppliers must now document oil source provenance through polymerization stage. Coatings segment formulators in the Netherlands are accelerating solvent-free dispersion chemistry adoption to preempt substance restriction expansion.
Performance-based material certification is displacing commodity purchasing in municipal procurement. French playground safety auditors now require fall-impact test documentation tied to specific rubber sand batches. This documentation burden concentrates contract awards among suppliers with in-house testing laboratories.
Rubber Sand Market Segmentation
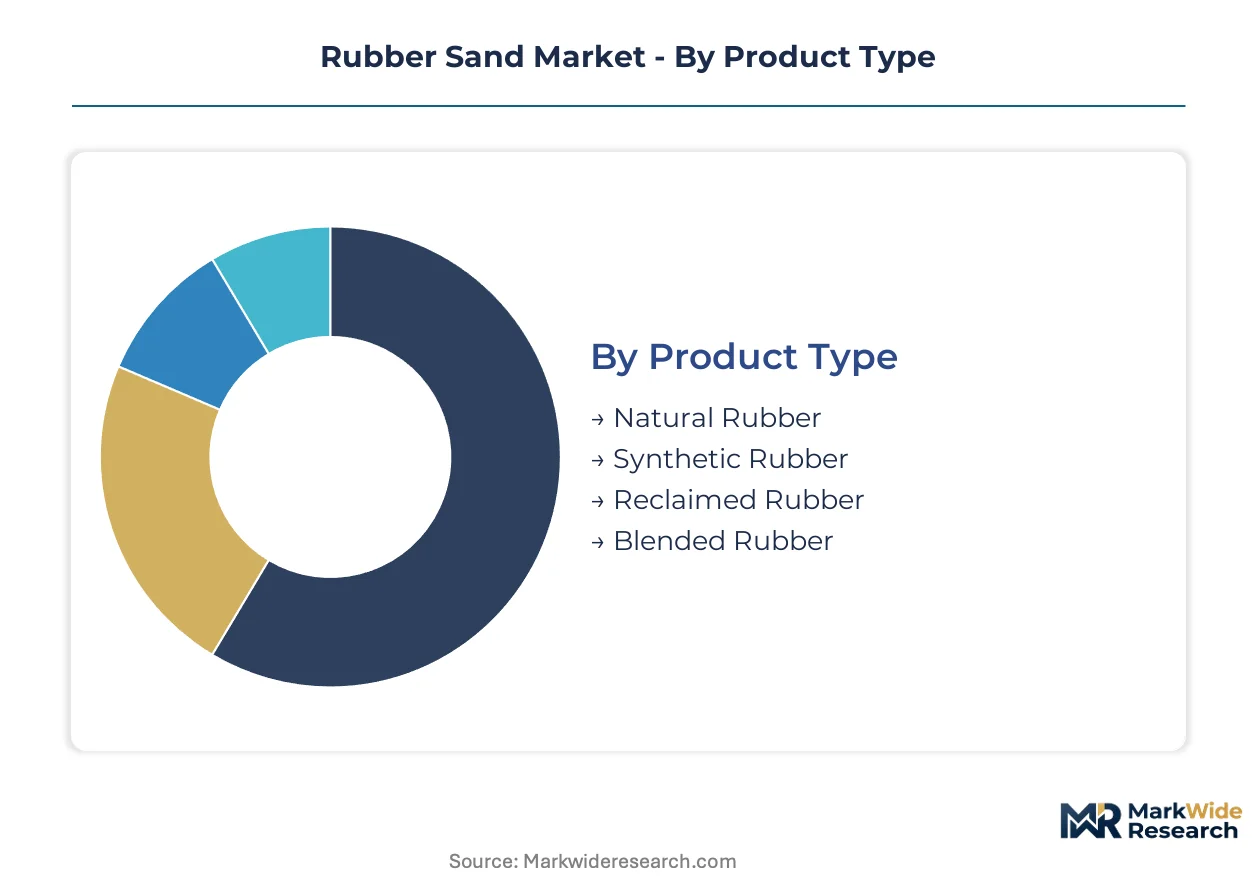
Rubber sand segmentation reveals how specification tiers align with distinct upgrade cycles across end-use industries. Sports field refurbishments and municipal infrastructure programs are compressing procurement timelines for premium grades. Construction sector buyers are extending replacement intervals for standard formulations through performance bundling with coatings suppliers.
Product Type:
Stadium resurfacing programs in Germany are accelerating specification shifts toward certified infill grades, forcing compounders to requalify feedstock streams ahead of REACH substance reviews.
- Natural Rubber:Plantation-derived latex compounds sized 0.5–1.2 millimeters deliver superior elasticity modulus for elite sports turf specifications. German municipal stadium upgrades are concentrating procurement of this grade despite Southeast Asian supply disruptions elevating landed costs.
- Reclaimed Rubber:Cryogenically ground tire crumb with documented SVHC screening meets circular economy mandates under extended producer responsibility frameworks. France and Germany are tightening aromatic oil content thresholds, expanding qualification requirements for integrated recyclers with captive shredding operations.
- Synthetic Rubber:Virgin polymer compounds from styrene-butadiene or ethylene-propylene feedstock offer batch consistency for coatings chemistry applications.
- Blended Rubber:Engineered mixtures combining reclaimed crumb with virgin synthetic binders balance cost and performance for playground safety surfacing.
Reclaimed rubber sits at the top of the volume ranking, with natural rubber climbing the fastest on sports infrastructure premiumization.
End Use Industry:
Margin pools concentrate where fall-height certification and leachate testing documentation create procurement barriers for undifferentiated suppliers.
- Sports:Synthetic turf infill and track surfacing demand sub-millimeter particle tolerances with shock absorption certification. German KBA-equivalent municipal auditors now require batch-specific test documentation, concentrating contract awards among compounders with in-house laboratories.
- Construction:Architectural coatings and waterproofing membranes utilize rubber sand as flexible aggregate for crack resistance. Dutch formulators are accelerating solvent-free dispersion chemistry adoption to preempt REACH Annex XVII expansion.
- Automotive:Underbody sealants and vibration damping compounds consume consistent-grade crumb for NVH applications.
- Landscaping:Decorative mulch and pathway surfacing represent price-sensitive volume with lower specification barriers.
Sports commands the steepest expansion trajectory on safety certification mandates, while construction maintains the deepest margin pools through technical service bundling.
Application:
Functional differentiation across application tiers determines whether buyers treat rubber sand as commodity input or performance-critical formulation component.
- Coatings:Specialized dispersion chemistry for architectural and industrial surface systems requires controlled particle size distribution and surface treatment compatibility. Technical service partnerships with formulators are opening margin pools through application engineering support.
- Fillers:Bulk volume consumption in sports infill and construction aggregate depends on standardized container logistics rather than custom bag sizing.
- Adhesives:Modified bitumen and construction bonding agents utilize fine-grade crumb for flexibility enhancement.
- Insulation:Acoustic and thermal barrier applications specify low-density granules for cavity fill systems.
Fillers dominate absolute volume throughput, with coatings gaining share fastest on formulation complexity premiums.
Distribution Channel:
Procurement channel selection tracks buyer scale and specification burden, with certified grades consolidating through distributor networks capable of documentation custody.
- Distributors:Construction and sports surfacing specialists with REACH documentation capabilities are anchoring supply contracts for certified grades. Sibelco leverages its European logistics network to consolidate container-load procurement around standardized specifications.
- Direct Sales:Volume compounders and coatings formulators with technical service requirements bypass intermediaries for specification development support.
- Online:Standard-grade landscaping and small-volume construction applications migrate to digital procurement platforms.
- Retail:Consumer-scale playground and garden products reach end-users through building material merchants.
Distributors anchor the volume ranking, with direct sales expanding most quickly on technical service bundling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic turf infill chemistry originated in post-war European rubber recycling operations, with German industrial clusters pioneering cryogenic grinding for sports surface applications. Regional demand patterns now track municipal stadium refurbishment cycles and circular economy enforcement intensity.
Germany
Municipal stadium upgrades in North Rhine-Westphalia and Bavaria concentrate procurement of REACH-certified infill grades. KBA-equivalent auditors enforce batch-specific shock absorption documentation, disqualifying ambient grinding operations. Cologne and Düsseldorf logistics hubs anchor container-load distribution networks serving Benelux markets.
United States
EPA guideline variations across state environmental agencies fragment product liability exposure for crumb rubber suppliers. California and Texas municipal procurement programs specify recycled content quotas for public works contracts. Vulcan Materials Company leverages captive quarry access across Sun Belt infrastructure corridors.
France
Fall-height certification requirements for playground safety surfacing create specification pull in Île-de-France and Auvergne-Rhône-Alpes. ANSM oversight intersects with REACH Annex XVII aromatic oil thresholds, forcing feedstock requalification. Lyon-based formulators accelerate solvent-free dispersion chemistry adoption.
Netherlands
Architectural coatings demand concentrates around Rotterdam chemical cluster technical service partnerships. ECHA documentation requirements for SVHC screening elevate qualification barriers for imported crumb rubber. Dutch distributors consolidate standardized container logistics displacing custom bag sizing.
Japan
METI circular economy guidelines expand tire recycling obligations for reclaimed rubber feedstock. Kansai region synthetic turf installers specify sub-millimeter particle tolerances for shock absorption consistency. Osaka-based compounders invest in precision cryogenic grinding systems to meet certification thresholds.
Rubber Sand Market Competitive Landscape
The competitive structure tilts toward integrated materials conglomerates with captive mineral and recycled feedstock access. Tier-one positions concentrate among quarry operators and industrial minerals specialists with logistics network density. Three archetypes dominate: construction materials conglomerates with backward integration into aggregate supply, specialized industrial minerals distributors with REACH documentation capabilities, and regional sand fabricators with sports infill sizing expertise. Capacity consolidation and certification-driven supply chain requalification represent the dominant competitive moves reshaping vendor selection criteria.
Among European industrial minerals specialists, Sibelco and Quarzwerke occupy positions defined by logistics network consolidation and standardized container-load procurement systems. Vulcan Materials Company exemplifies the construction materials conglomerate archetype with quarry-based geographic anchoring. Pattison Sand represents specialized sizing capability differentiation for sports infill specifications. Saint-Gobain sits within diversified materials science positioning with technical service bundling potential.
| Leading Market Players |
|---|
| Saint-Gobain |
| Nugent Sand |
| Pattison Sand |
| Sibelco |
| Vulcan Materials Company |
| Tochu Corporation |
| Quarzwerke |
| Asahi Yukizai Corp |
| Mangalore Minerals Pvt Ltd |
| Others |
Value Network & Pricing Analysis
Precision cryogenic grinding specialists in Germany command wage premiums that widen spreads between REACH-certified premium grades and ambient-ground standard tiers. Labor-cost differentials between certified European compounders and undifferentiated recyclers feed directly into three-tier pricing stratification across infill, coatings, and landscaping applications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract negotiations, with certification grade and volume scale as primary price differentiation drivers. Price erosion runs through standard-grade landscaping supply as Asian tire recyclers expand export volumes. Municipal sports procurement teams in Germany exhibit lowest price sensitivity due to batch-specific documentation mandates, while French playground contractors face acute cost pressure from fall-height certification expenses.
Supply Chain Analysis
REACH SVHC screening and ECHA documentation requirements are gating supply chain participation, concentrating qualified feedstock access among integrated European recyclers with captive shredding operations. Germany, France, and the Netherlands anchor supply concentration for certified grades, while Southeast Asian plantation rubber feeds premium natural rubber tiers. Raw material dependencies rest on scrap tire collection networks, cryogenic grinding equipment, and aromatic oil-free extender compounds. Single-source vulnerability around German precision grinding capacity threatens supply security. Distribution runs through construction and sports surfacing specialists with documentation custody capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where municipal procurement shifts toward certified infill specifications reward compounders with in-house testing infrastructure.
For Market Incumbents: Hedge against cork and coconut husk substitution in elite sports tenders by deepening technical service partnerships with dispersion formulators. Anchor capacity additions in North Rhine-Westphalia logistics corridors to defend container-load consolidation advantages against distributor network challengers. For New Entrants and Emerging Players: REACH Annex XVII aromatic oil restrictions in France open a window for integrated recyclers with documented oil-source provenance. Target playground safety surfacing in Île-de-France where fall-height certification requirements concentrate specification pull among qualified suppliers lacking local production presence. For Investors and Strategic Acquirers: Construction materials conglomerates are the most active acquirer in this space, seeking backward integration into certified rubber sand supply. Five-to-ten-year viability hinges on EPR scheme alignment generating captive feedstock access. Monitor German KBA-equivalent auditor enforcement intensity as inflection signal for certification-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tire Recycling | EPR scheme alignment in Germany secures captive feedstock access against REACH requalification waves. |
| Cryogenic Grinding Capacity Expansion | Sub-millimeter tolerance capability captures municipal stadium upgrade specifications in Bavaria. |
| Technical Service Partnership | Dutch coatings formulators bundle application engineering support to preempt solvent-free chemistry mandates. |
| Documentation Custody Investment | In-house SVHC screening laboratories concentrate French playground safety contract awards. |
| Logistics Network Consolidation | Standardized container-load systems displace custom bag sizing across Benelux distribution corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports surfacing installers, coatings formulators, tire recycling plant managers, and municipal procurement officers with secondary validation against ECHA substance databases, EU customs trade records, and SEC filings from construction materials conglomerates. Bottom-up volume builds across product grades and end-use segments triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed value and volume across natural, reclaimed, synthetic, and blended rubber tiers, with further disaggregation by sports, construction, automotive, and landscaping end-use industries. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of circular economy mandate enforcement intensity. Cryogenic grinding capacity utilization rates and REACH certification timelines served as industry-specific forecast inputs across the analysis window.
Revisions become necessary when ECHA expands SVHC screening lists or when EPA guideline harmonization fragments state-level procurement specifications. A model refresh is warranted upon material change in German municipal stadium refurbishment program funding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Coatings Market
Rubber
Rubber Splicing Tape Market
Rubber
Global Tire Material Market
Rubber
Nitrile Elastomers Market
Rubber
Isoprene Rubber Market
Rubber
Snap on Rubber Stopper Market
Rubber
Tire Chemicals Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Polyisoprene Rubber Market
Rubber
Rubber Conveyor Belt Market
Rubber
Rubber Bulbs Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Rubber Ropes Market
Rubber
Liquid Silicone Rubber Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market