
 Rubber Accelerators Market | 2026-2036
Rubber Accelerators Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Accelerators Market Analytics
REACH is hardening the cost-of-entry calculus for rubber accelerator producers serving European tire and industrial rubber clients. Lanxess AG leverages its integrated antidegradant and accelerator portfolio to sustain supply security across German and Belgian production nodes. Sunsine anchors its position through captive thiuram and sulfenamide capacity at Shandong facilities. Eastman Chemical Company competes on specialty sulfenamide grades for high-performance tire formulations.
Rubber accelerators are sulfur-donating or sulfur-activating organic compounds that reduce vulcanization time from hours to minutes at 140-180°C, enabling cross-link density control in diene rubbers. Sulfenamides dominate value capture due to their delayed-action scorch safety and broad compatibility with NR, SBR, and BR tire compounds. Thiurams retain structural importance in industrial rubber products and cable sheathing where ultra-fast cure cycles offset higher raw material costs. Powder and granular forms command logistics advantages in high-volume tire manufacturing, while liquid dispersions penetrate specialty automotive parts requiring precise dosing automation.
EPA oversight of nitrosamine precursors and OSHA permissible exposure limits for thiuram dust reshape formulation choices and plant engineering investments in United States facilities. ECHA substance evaluation under REACH Annex XV restricts certain dithiocarbamate salts, forcing reformulation toward guanidine and sulfenamide alternatives in EU-bound production. China's MEE enforcement of volatile organic compound emission standards at rubber chemical parks accelerates consolidation toward compliant integrated producers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capacity commitments.
Market Dynamics
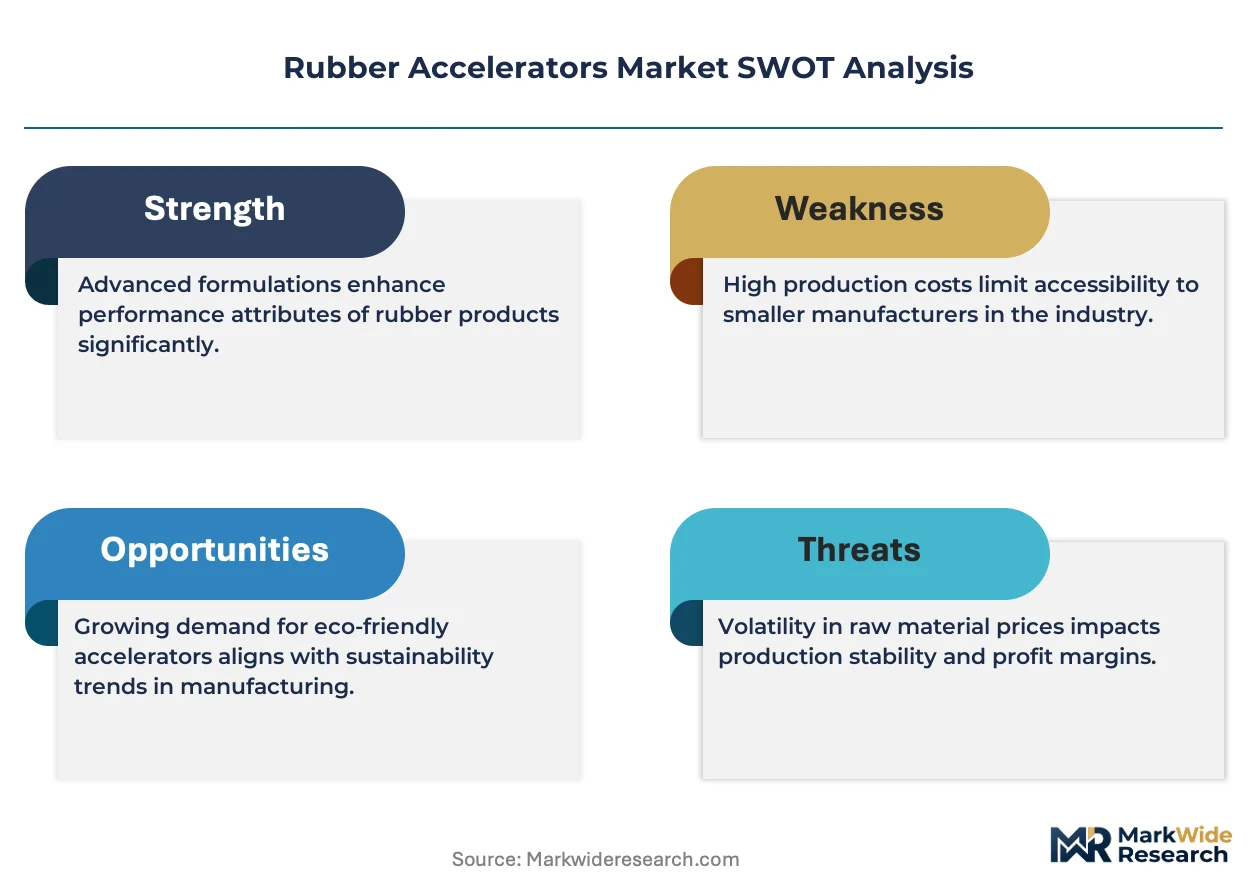
REACH Annex XV restrictions on dithiocarbamate salts are forcing tire compounders across Europe toward guanidine and sulfenamide alternatives, compressing formulation windows while tightening supply security requirements for compliant accelerator portfolios.
Growth Catalysts
- Asia-Pacific tire manufacturing expansion:China, India, and Thailand concentrate new radial tire capacity, pulling sulfenamide and thiuram volumes toward integrated rubber chemical parks with captive sulfur-donation capabilities.
- REACH compliance thresholds:ECHA substance evaluation protocols harden entry barriers for non-compliant producers, rewarding integrated European manufacturers with certified antidegradant-accelerator portfolios.
- Ultra-fast cure automation:Liquid dispersion dosing systems in automotive sealing and hose applications enable precise cross-link density control at 140-180°C vulcanization temperatures.
Market Restraints
- Aniline feedstock volatility:Sulfenamide production depends on aniline derivatives subject to benzene-cracker output fluctuations and Asian petrochemical pricing cycles.
- Shandong supply concentration:Captive thiuram and sulfenamide capacity clusters in China's eastern chemical corridor, creating single-geography exposure for global tire formulators.
- Thiuram substitution pressure:Guanidine accelerators displace dithiocarbamate salts in EU-bound industrial rubber where nitrosamine precursor restrictions apply.
Strategic Opportunities
- Indian tire manufacturing scale-up:Domestic radial capacity expansion under PLI scheme incentives creates demand for delayed-action sulfenamide grades with scorch safety profiles.
- EPA nitrosamine precursor oversight:United States facilities face reformulation mandates that favor suppliers with pre-validated alternative accelerator portfolios and compliant plant engineering.
- MEE VOC enforcement:China's volatile organic compound emission standards at rubber chemical parks accelerate consolidation toward integrated producers with captive environmental compliance systems.
Industry Challenges
- Cross-jurisdiction formulation alignment:Tire compounders serving EU, US, and Asian markets simultaneously must maintain parallel accelerator inventories as EPA, ECHA, and MEE requirements diverge on nitrosamine thresholds and dust exposure limits.
- Legacy equipment retrofit costs:Powder-to-liquid dispersion switching requires dosing automation investments that strain mid-volume automotive parts manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Accelerators Market |
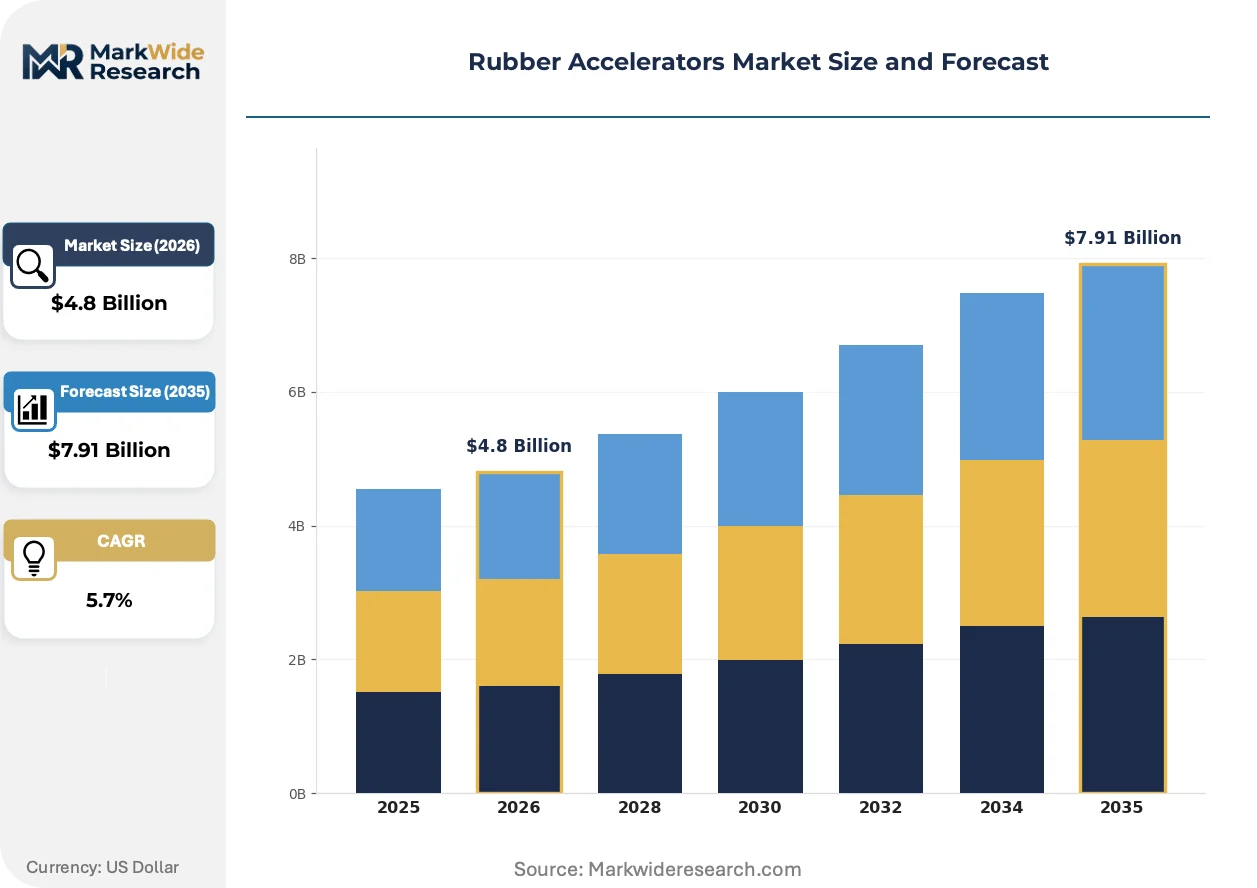
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sulfenamides, Thiurams, Guanidines, Dithiocarbamates Application: Tires, Industrial Rubber Products, Footwear, Automotive Parts End User: Manufacturers, Distributors, Retailers, Exporters Form: Liquid, Granular, Powder, Paste |
| Companies Covered | Lanxess AG, Sunsine, Eastman Chemical Company, BASF SE, Sennics, Kemai Chemical, AkzoNobel, Arkema SA, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Accelerators Market Evolving Landscape
Accelerator technology is converging around precision dosing automation and regulatory pre-certification, compressing the gap between raw chemical production and compound-ready delivery formats.
Pre-dispersed masterbatch technology is unifying accelerator delivery with polymer-bound carrier systems that eliminate dust exposure and dosing variability. Tier-one tire manufacturers in Germany and Japan adopt these systems for high-performance tread compounds where batch-to-batch consistency determines warranty exposure. The technology is unifying quality assurance protocols across multiple production nodes, reducing inbound QC overhead for multi-site compounders.
ECHA REACH Annex XV restrictions on zinc dithiocarbamate salts are compelling reformulation toward thiuram-free industrial rubber compounds for cable sheathing and conveyor belting. German and Belgian producers face substance evaluation timelines that compress product development cycles to 18-month validation windows. EU-bound automotive sealing applications are responding with guanidine-sulfenamide hybrid systems that trade cure speed for compliance security.
Compounders are consolidating supplier relationships around integrated accelerator-antidegradant portfolios that reduce qualification overhead. Automotive parts manufacturers in the US Midwest and Southeast favor single-source contracts covering CBS, TBBS, and TMTD grades with unified specification documentation. This concentration is most visible in heavy-duty truck tire and off-road equipment segments where formulation stability outweighs marginal price differentiation.
Rubber Accelerators Market Segmentation
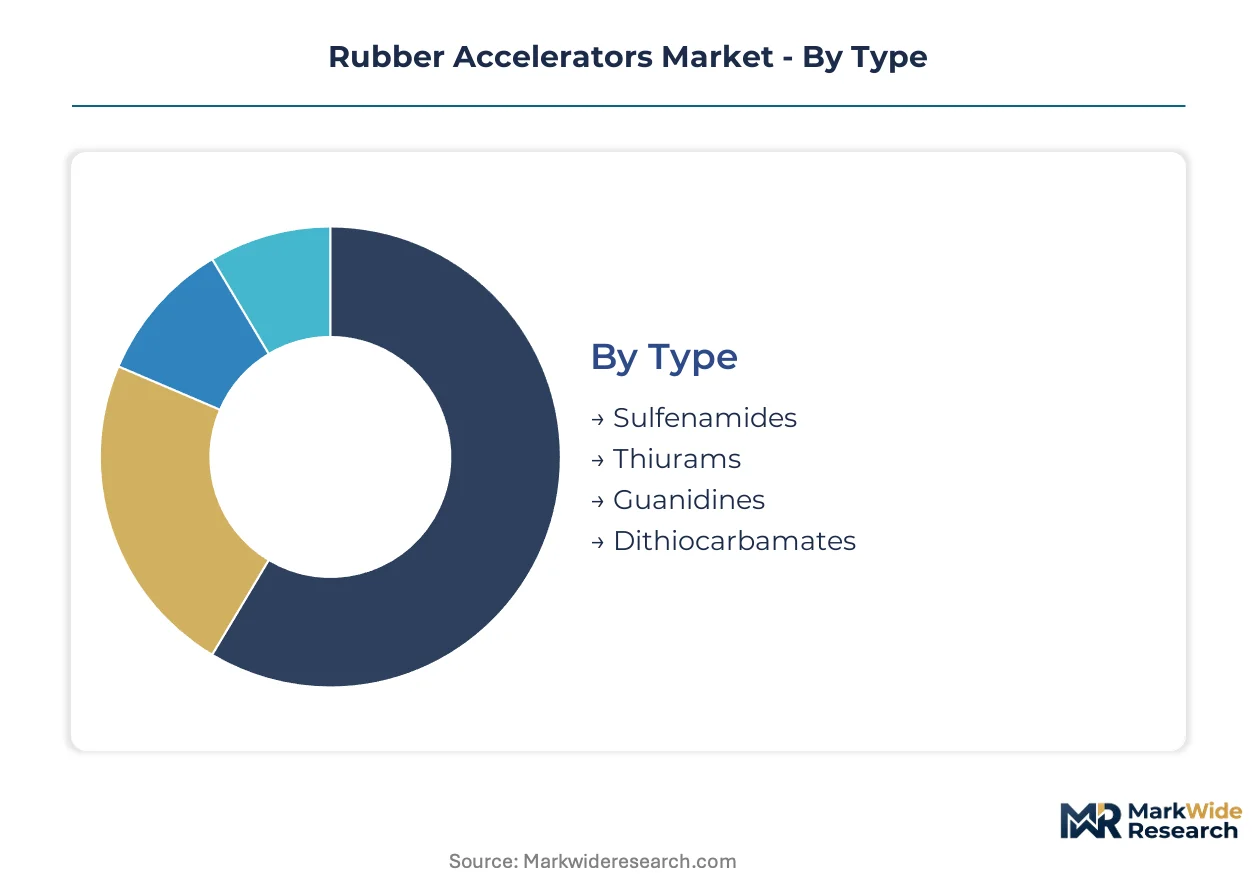
Rubber accelerator segmentation reveals how formulation chemistry, delivery format, and end-use specifications fragment supply relationships. Tire manufacturers demand different technical specifications than industrial rubber compounders, forcing suppliers to maintain parallel product architectures.
Type:
Supply concentration for each accelerator chemistry varies dramatically across production geographies, with integrated producers capturing margin through captive intermediate synthesis.
- Sulfenamides:Delayed-action scorch safety makes these the dominant chemistry for high-performance tire treads. Demand concentrates at radial tire plants in China, Thailand, and Germany where CBS and TBBS grades enable precise vulcanization control at 140-180°C. REACH-compliant European producers leverage integrated aniline derivative supply to defend position against Asian imports.
- Thiurams:Ultra-fast cure kinetics serve industrial rubber applications and cable sheathing where cycle speed offsets higher raw material costs. TMTD and TETD grades face substitution pressure from guanidine alternatives in EU-bound production due to ECHA Annex XV restrictions on nitrosamine precursors. Shandong chemical parks concentrate global thiuram capacity.
- Guanidines:DPG and DOTG grades function as primary accelerators for thick-section industrial rubber and as secondary boosters in tire compounds. Lower cost structure and regulatory compliance security drives displacement of dithiocarbamate salts in European cable and conveyor belt applications.
- Dithiocarbamates:Zinc and sodium salts deliver ultra-fast cure in latex dipping and adhesive applications. EPA and ECHA regulatory scrutiny on nitrosamine formation compresses addressable market to non-tire industrial segments with validated extraction protocols.
Today's leader: Sulfenamides. Tomorrow's challenger: Guanidines.
Application:
Application-driven demand splits between high-volume tire manufacturing and specification-intensive industrial segments with divergent qualification timelines.
- Tires:Radial passenger and truck tire production consumes the majority of sulfenamide volumes, with delayed-action scorch safety enabling automated calendering and extrusion at Asian tire plants. OEM qualification protocols require 18-24 month validation cycles that lock in supplier relationships.
- Industrial Rubber Products:Conveyor belting, hoses, and seals demand thiuram and guanidine grades with balanced cure speed and compression set resistance. ECHA REACH restrictions on dithiocarbamate salts accelerate reformulation toward thiuram-free compounds in German and Belgian production.
- Footwear:Soling and upper applications use pre-dispersed masterbatch formats to eliminate dust exposure in Vietnamese and Indonesian manufacturing. Liquid dispersion dosing enables precise cross-link density control for microcellular EVA and rubber blends.
- Automotive Parts:Engine mounts, seals, and hoses require specialty sulfenamide grades with low volatile content for US and German OEM supply chains. Tier-one suppliers consolidate around single-source contracts with unified specification documentation covering CBS, TBBS, and antidegradant portfolios.
Tire applications anchor volume scale. Industrial rubber products offer the steepest expansion trajectory as regulatory compliance reshapes formulation choices.
End User:
End-user channel structure determines pricing power and technical service intensity, with direct manufacturer relationships commanding premium positioning.
- Manufacturers:Tire and rubber goods producers purchase bulk sulfenamide and thiuram grades through annual contracts with indexed aniline pricing. Integrated producers with captive antidegradant supply capture multi-year supply security agreements from German and Japanese tire manufacturers.
- Distributors:Regional chemical distributors serve mid-volume compounders with blended accelerator packages and technical formulation support. Inventory consolidation and just-in-time delivery capabilities differentiate positioning in the US Midwest and Southeast automotive parts clusters.
- Retailers:Small-lot sales of pre-weighed accelerator blends penetrate specialty rubber repair and custom compounding shops. E-commerce channels gain share for standardized powder and granular formats with published safety data sheets.
- Exporters:Trading companies arbitrage price differentials between Chinese chemical park production and import-dependent markets in Southeast Asia and Latin America. REACH and EPA pre-certification requirements filter non-compliant traders from EU and US-bound shipments.
Manufacturers control value capture. Distributors face margin compression from direct procurement trends among scaled compounders.
Form:
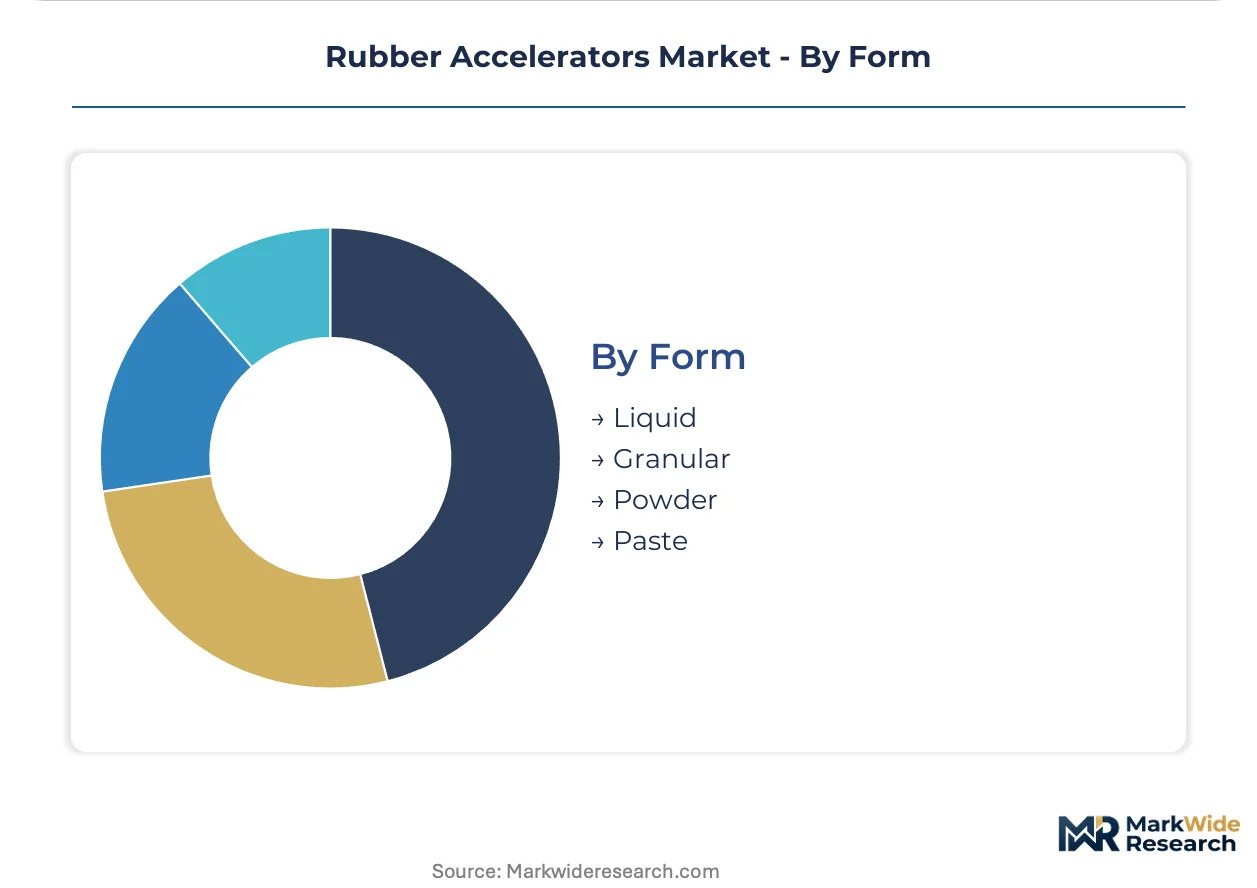
Physical delivery format selection reflects automation level, dust exposure regulations, and dosing precision requirements across end-use facilities.
- Liquid:Aqueous and oil-based dispersions enable automated pumping and metering in automotive sealing and hose manufacturing. German and Japanese tier-one suppliers specify liquid CBS and TBBS for batch-to-batch consistency in warranty-critical tread compounds.
- Granular:Dust-suppressed granules balance flowability with reduced respirable exposure, dominating high-volume tire manufacturing in China and Thailand. Granular sulfenamides command logistics advantages in automated weighing systems at integrated rubber chemical parks.
- Powder:Standard milled powders retain cost advantage for manual batching operations in emerging market tire plants. OSHA permissible exposure limits and MEE VOC enforcement accelerate displacement toward granular and pre-dispersed alternatives.
- Paste:Polymer-bound masterbatches eliminate dust entirely and enable direct mill addition without pre-weighing. Pre-dispersed technology unifies quality assurance protocols across multi-site compounders, reducing inbound QC overhead for German tire manufacturers.
Granular formats dominate today's volume. Liquid and paste formats gain share fastest as automation and regulatory compliance reshape plant engineering investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering pioneered modern rubber accelerator synthesis in the early twentieth century. Industrial scaling migrated toward Asian petrochemical corridors during the 1990s. Regulatory divergence now fragments formulation standards across production zones.
China
Shandong Province concentrates captive thiuram and sulfenamide capacity serving radial tire plants in Qingdao and Weifang. MEE enforcement of volatile organic compound standards at designated rubber chemical parks accelerates consolidation toward integrated producers with in-house environmental compliance. Yangtze River Delta specialty chemical clusters supply liquid dispersion formats for automotive sealing applications.
Germany
Leverkusen and Cologne chemical complexes anchor European sulfenamide production for premium tire tread compounds. ECHA REACH Annex XV substance evaluation protocols restrict dithiocarbamate salt formulations, compelling reformulation toward guanidine alternatives in industrial rubber segments. Bavarian automotive parts manufacturers specify pre-dispersed masterbatch grades with unified antidegradant documentation.
United States
Gulf Coast petrochemical corridors supply aniline feedstock for sulfenamide production at Texas and Louisiana facilities. EPA oversight of nitrosamine precursors and OSHA permissible exposure limits for thiuram dust reshape plant engineering investments and formulation choices. Midwest automotive parts clusters in Ohio and Michigan consolidate procurement around single-source accelerator-antidegradant contracts.
India
Maharashtra and Gujarat tire plants expand radial capacity under PLI scheme incentives, creating demand for delayed-action sulfenamide grades with scorch safety profiles. BIS certification requirements and state-level pollution control board enforcement filter non-compliant imports from Southeast Asian traders. Chennai automotive belt manufacturers adopt granular dosing formats for automated weighing systems.
Thailand
Rayong and Chonburi rubber processing zones serve Japanese and Korean tire manufacturers with integrated accelerator supply from Eastern Seaboard chemical parks. Board of Investment incentives for green chemistry investments attract reformulation capacity for REACH-compliant guanidine and sulfenamide alternatives. Bangkok-based distributors arbitrage price differentials between Chinese chemical park production and domestic compounders.
Rubber Accelerators Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive intermediate synthesis. Three to five diversified multinationals control premium-tier supply relationships through certified antidegradant-accelerator portfolios. Mid-scale Asian producers compete on volume sulfenamide and thiuram grades with indexed aniline pricing. Dominant competitive moves include backward integration into aniline derivatives and geographic expansion toward Indian tire manufacturing corridors.
Among European-based diversified chemical groups, Lanxess AG exemplifies the integrated portfolio archetype with supply security across German and Belgian production nodes. Eastman Chemical Company occupies a position within the specialty-grade tier, serving high-performance tire formulation requirements. Sunsine represents the captive-capacity model with concentrated thiuram and sulfenamide production at Shandong facilities. These three anchors illustrate how geographic regulatory exposure and production integration determine competitive positioning.
| Leading Market Players |
|---|
| Lanxess AG |
| Sunsine |
| Eastman Chemical Company |
| BASF SE |
| Sennics |
| Kemai Chemical |
| AkzoNobel |
| Arkema SA |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Pre-dispersed masterbatch adoption simultaneously compresses per-unit production economics and concentrates supply relationships around integrated producers with captive polymer-binding capabilities. This technology shift rewards compounders willing to absorb higher upfront formulation costs while squeezing standalone powder manufacturers out of premium-tier supply chains.
Pricing Analysis
Bundled accelerator-antidegradant packages command premium positioning against unbundled commodity grades. Pricing stratifies across REACH-certified, OSHA-compliant, and standard industrial tiers, with certification-grade sulfenamides capturing margin premiums from German and Japanese tire manufacturers. Cost compression in standard powder grades is intensifying because Shandong chemical parks flood spot markets with indexed aniline-linked supply. Small-lot distributors exhibit highest price sensitivity, while tier-one automotive OEMs prioritize specification security over marginal cost differentials.
Supply Chain Analysis
REACH and OSHA certification gating filters non-compliant traders from EU and US-bound shipments, compressing qualified supplier pools. Manufacturing concentrates in China, Germany, and India, with Shandong Province anchoring global thiuram capacity and Leverkusen-Cologne complexes defending European sulfenamide supply. Feedstock dependencies draw from benzene-cracker aniline derivatives, sulfur donation intermediates, and polymer carrier systems. Single-geography concentration in China's eastern chemical corridor creates vulnerability to MEE environmental enforcement actions. Distribution runs through direct manufacturer contracts for scaled compounders and regional distributors for mid-volume automotive parts clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH Annex XV substance evaluations on dithiocarbamate salts are forcing wholesale reformulation toward compliant accelerator alternatives.
For Market Incumbents: Lock in multi-year supply security agreements with German and Japanese tire manufacturers before 18-24 month OEM qualification windows close to new entrants. Deepen backward integration into aniline derivative production to buffer benzene-cracker volatility and defend margin structure against Shandong-based spot competitors. Prioritize pre-dispersed masterbatch capacity additions in Belgian and US Gulf Coast facilities to capture automotive sealing automation demand. For New Entrants and Emerging Players: The premium-to-economy pricing gap in Indian radial tire manufacturing creates immediate white-space opportunity for delayed-action sulfenamide grades with scorch safety profiles. Target Maharashtra and Gujarat compounders operating under PLI scheme capacity expansion with technical service-intensive go-to-market models that legacy traders cannot replicate. Penetrate Vietnamese and Indonesian footwear soling segments through liquid dispersion formats where dust exposure regulations are tightening fastest. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Asian producers lacking REACH pre-certification but possessing captive thiuram synthesis infrastructure acquirable for compliance retrofit. Long-term viability favors integrated accelerator-antidegradant portfolios with demonstrated ECHA dossier submission capabilities. Watch ECHA substance evaluation timelines for zinc dithiocarbamate salts as the inflection signal determining which industrial rubber compounders face forced supplier switches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Derivatives | Captive benzene-cracker supply buffers Lanxess and Eastman against Asian petrochemical pricing cycles. |
| REACH-Compliant Guanidine Capacity Expansion | Belgian and German producers capture industrial rubber reformulation demand as ECHA restricts dithiocarbamate salts. |
| Pre-Dispersed Masterbatch Manufacturing Scale-Up | Polymer-bound formats eliminate dust exposure liability for US Midwest automotive parts manufacturers facing OSHA scrutiny. |
| Long-Term Supply Agreements with Indian Tire OEMs | Maharashtra radial capacity expansion under PLI incentives locks in sulfenamide volume commitments before qualification windows close. |
| Joint Venture for Liquid Dispersion Technology | German-Japanese tier-one supplier partnerships enable precision dosing automation in warranty-critical tread compounds. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tire compound procurement directors, rubber chemical plant managers, ECHA regulatory affairs specialists, and automotive tier-one supplier quality engineers with secondary validation against customs trade data, Cefic sector reports, SEC 10-K chemical segment disclosures, and BIS certification registries. Bottom-up volume builds from individual accelerator chemistry grades triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Segment-weighting approaches distributed value and volume across sulfenamide, thiuram, guanidine, and dithiocarbamate chemistries, further disaggregated by tire versus industrial rubber end-use, granular versus liquid versus paste form factors, and REACH-compliant versus standard-grade certification tiers. CAGRs were derived from elasticity-adjusted demand projections tied to radial tire capacity expansion announcements and regulatory substitution mandates. Forecast inputs incorporated aniline pricing volatility indices and MEE environmental enforcement intensity scores at designated rubber chemical parks.
Caveats apply where ECHA substance evaluation timelines, MEE VOC enforcement actions, or EPA nitrosamine precursor rulemakings could materially shift the outlook for specific accelerator chemistries. Forecasts reflect assumptions about continued radial tire demand growth and regulatory divergence persistence without harmonization. A model refresh is warranted upon material change in REACH Annex XV restriction scope or Shandong supply consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Isoprene Rubber Market
Rubber
Sterile Rubber Stopper Market
Rubber
Global Cast Elastomers Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Polybutadiene Elastomers Market
Rubber
Rubber Coatings Market
Rubber
Global Rubber Additives Market
Rubber
Rubber Roller Cleaner Market
Rubber
Industrial Rubber Products Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Performance Elastomers Market
Rubber
Rubber Sheets Market
Rubber
Isobutylene Market
Rubber
Global Elastomers Market
Rubber
Chloroprene Rubber Tape Market