
 Performance Elastomers Market | 2026-2036
Performance Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Elastomers Market Analysis
Specialty chemical distribution is narrowing as producers bypass traditional distributors to serve automotive OEMs and Tier-1 suppliers directly. Dow Inc. leverages its integrated silicone elastomer supply chain to secure long-term contracts with electric vehicle manufacturers. Lanxess AG anchors its competitive position through backward integration into ethylene-propylene rubber feedstocks and compounding assets.
Performance elastomers are high-polymer materials engineered to sustain elastic recovery under cyclic deformation across temperature extremes from minus sixty to plus three hundred degrees Celsius, serving critical sealing, damping, and insulation functions in machinery and transportation equipment. EPDM dominates volume in automotive cooling and weatherstrip systems due to its ozone resistance and cost position, while NBR specializes in oil-contact applications for industrial hydraulics where acrylonitrile content determines fluid compatibility. Sheet and extruded forms capture the majority of industrial fabrication demand, whereas molded components command premium positioning in healthcare device sealing.
REACH registration requirements and the EU F-Gas Regulation constrain fluorocarbon-based elastomer formulations, redirecting formulation investment toward peroxide-curable hydrocarbon alternatives. FDA biocompatibility standards and ISO 10993 testing protocols govern healthcare elastomer qualification timelines, creating extended certification barriers for new material entrants. Stakeholders must monitor regulatory divergence between European chemical hazard classifications and emerging Chinese GB standards for silicone materials used in electric vehicle battery enclosures.
Market Dynamics
Automotive electrification is compressing thermal management tolerances, forcing elastomer suppliers to reformulate for battery enclosure sealing and coolant loop integrity under sustained high-voltage loads.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH substance evaluations are accelerating substitution timelines toward bio-based feedstocks, opening contract windows for sustainable EPDM suppliers in German automotive corridors.
- Heat-resistant sealing demand:Electric vehicle power electronics generate localized temperatures exceeding 150°C, pulling silicone and fluorocarbon grades into inverter housing and charging port applications.
- Battery enclosure standards:China's GB/T protocols for thermal runaway containment are mandating compression-set-resistant gaskets, directing procurement toward peroxide-curable hydrocarbon formulations.
Market Restraints
- Feedstock cost volatility:Propylene and ethylene derivatives expose EPDM compounders to naphtha-cracker margin swings, compressing working capital cycles for mid-tier producers.
- Fluorocarbon supply concentration:FKM polymerization capacity clusters in Japan and select US Gulf Coast sites, creating geographic single-source risk for aerospace and semiconductor sealing buyers.
- REACH registration burdens:ECHA data requirements for novel curatives extend qualification timelines, freezing formulation pipelines for two to four years.
Strategic Opportunities
- Healthcare device sealing:FDA 21 CFR 177.2600 compliance gaps among Asian compounders create entry points for US and European suppliers with validated ISO 13485 quality systems.
- India PLI scheme:Production-linked incentives for domestic automotive manufacturing are pulling compounding capacity toward Chennai and Pune industrial zones.
- Digital twin integration:Finite-element modeling of elastomer creep and stress relaxation is compressing prototype cycles, enabling virtual qualification for Tier-1 supplier contracts.
Industry Challenges
- Compounding technician scarcity:Expertise in peroxide versus sulfur cure systems is retiring from European and North American workforces faster than apprenticeship pipelines replenish.
- Multi-standard certification complexity:Simultaneous UL 94 flammability, ISO 10993 biocompatibility, and OEM-specific material data sheet requirements extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Elastomers Market |
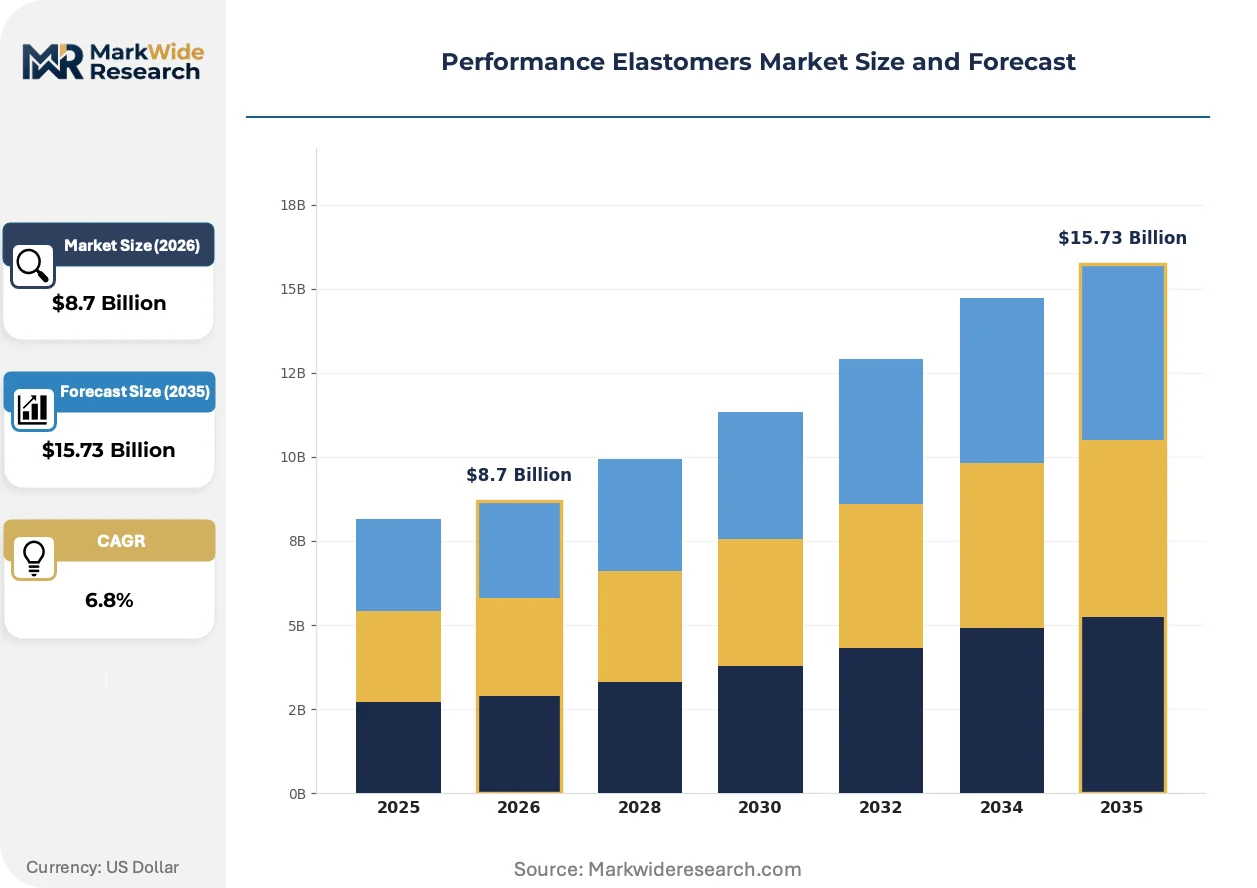
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBR, EPDM, NBR, NR Application: Automotive, Industrial, Construction, Healthcare End User: OEMs, Tier-1 Suppliers, Manufacturers, Distributors Form: Sheet, Tube, Molded, Extruded |
| Companies Covered | Wacker Chemie AG, Arkema S.A., Dow Inc., Shin-Etsu Chemical Co., Ltd., Lanxess AG, DuPont de Nemours, Inc., Solvay S.A., Mitsui Chemicals, Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Elastomers Market Emerging Trajectories
Computational materials science and in-situ process monitoring are collapsing the traditional empiricism of rubber compounding, enabling predictive formulation rather than iterative batch testing.
Dynamic mechanical analysis coupled with machine learning is digitizing viscoelastic property prediction across temperature and frequency domains. Automotive sealing engineers at German OEMs are adopting these platforms to compress material qualification from eighteen months to under six. The technology is digitizing supplier-customer technical exchanges, replacing physical sample shipments with encrypted simulation data transfers.
REACH authorization procedures for medium-chain chlorinated paraffins are forcing compounders to abandon established plasticizer systems in NBR and CR formulations. Industrial hose manufacturers face reformulation costs exceeding prior raw material budgets by substantial margins. EPDM weatherstrip producers have responded fastest, already certifying bio-based process oil alternatives for European passenger vehicle programs.
Direct procurement contracts between polymer producers and automotive OEMs are disintermediating traditional chemical distributors. Tier-1 sealing system suppliers in Stuttgart and Wolfsburg now negotiate compound specifications and pricing through bilateral technical partnerships. This channel compression is most advanced in Germany, where integrated silicone producers have captured long-term supply agreements for electric vehicle battery sealing platforms.
Performance Elastomers Market Segmentation
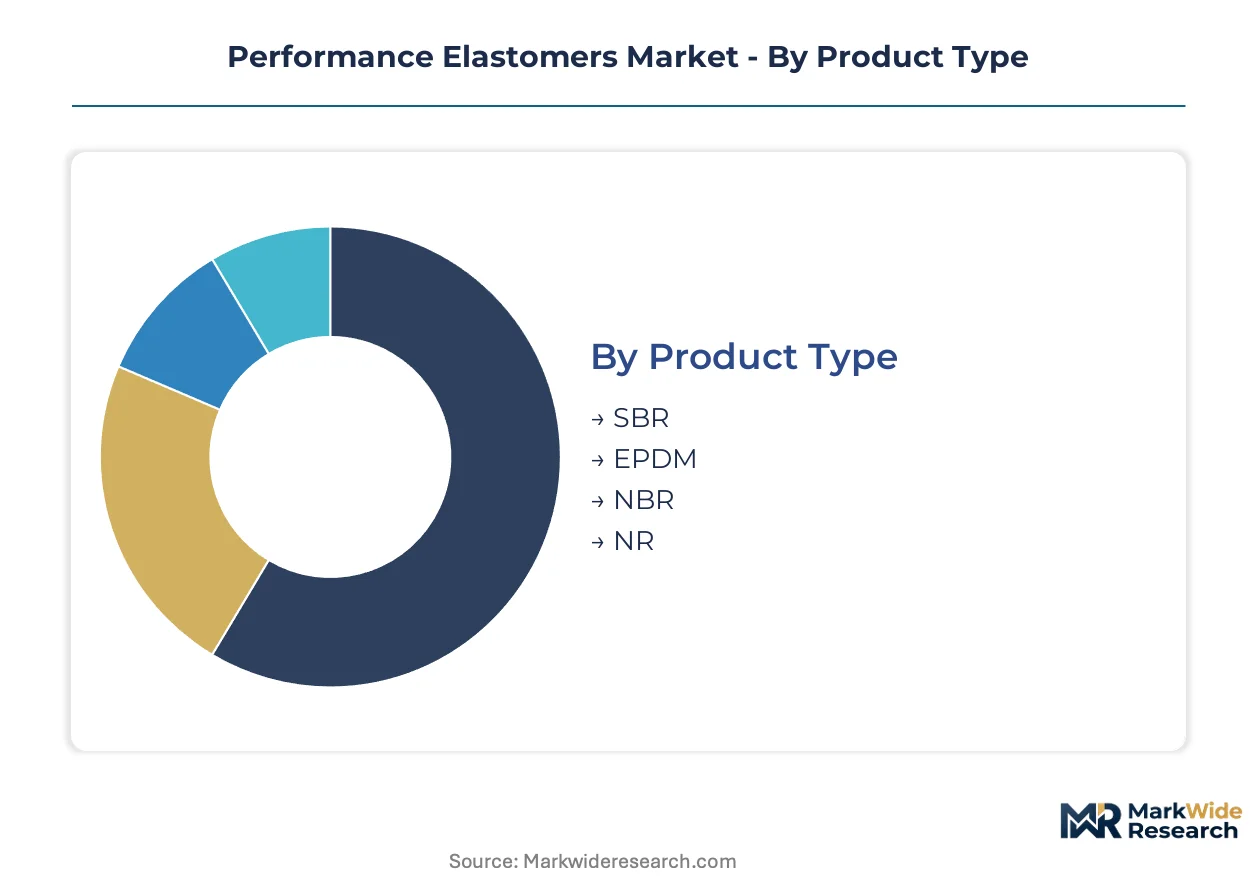
Performance elastomers serve distinct functional requirements across temperature extremes, chemical exposure profiles, and deformation cycles. Segmentation reveals how material specifications align with end-use criticality, from commodity weatherstripping to life-sustaining medical seals. Procurement patterns diver sharply between direct OEM contracting and distributor-mediated industrial supply.
Product Type:
Each polymer chemistry trades off fluid resistance, thermal ceiling, and elastic recovery to match specific environmental stressors.
- EPDM:Ethylene-propylene-diene terpolymer delivers superior ozone and weathering resistance with saturated backbone stability. Automotive cooling systems and door seals in Germany's Stuttgart corridor specify peroxide-cured grades for 150°C continuous service under ECHA REACH substance restrictions.
- NBR:Acrylonitrile-butadiene rubber varies acrylonitrile content from 18% to 50% to modulate oil swell resistance. Industrial hydraulic hose producers in Japan's Kansai manufacturing belt specify high-ACN grades for phosphate ester fluid compatibility amid feedstock cost volatility.
- SBR:Styrene-butadiene copolymer dominates tire sidewall and industrial belting applications through cost-optimized emulsion polymerization.
- NR:Natural rubber from Hevea brasiliensis latex supplies high-tensile dynamic applications including anti-vibration mounts and conveyor systems.
The dominant share belongs to EPDM, while NBR is closing the gap fastest on electrification-driven thermal management demand.
Application:
End-use sectors impose divergent certification burdens and volume scale requirements.
- Automotive:Battery enclosure sealing, inverter housing gaskets, and cooling loop integrity under sustained high-voltage loads. China's GB/T thermal runaway containment protocols mandate compression-set-resistant grades for electric vehicle platforms.
- Industrial:Hydraulic seals, conveyor belting, and vibration isolation systems serving process equipment. ISO 10993 biocompatibility standards govern healthcare device sealing, creating extended qualification barriers.
- Construction:Roofing membranes, window gaskets, and expansion joint systems exposed to UV and ozone degradation.
- Healthcare:FDA 21 CFR 177.2600 compliant seals for drug delivery devices and surgical instruments requiring validated ISO 13485 quality systems.
Automotive commands the largest volume position, though healthcare generates the steepest expansion trajectory on aging demographics and device complexity.
End User:
Channel structure determines technical engagement depth and contract duration.
- OEMs:Direct material specification authority with multi-year platform agreements. German automotive producers in Wolfsburg negotiate compound formulations bilaterally with integrated silicone suppliers.
- Tier-1 Suppliers:Sealing system integrators responsible for subsystem validation and warranty exposure.
- Manufacturers:Industrial fabricators purchasing standard grades through distribution for MRO and capital equipment.
- Distributors:Traditional chemical intermediaries facing disintermediation as producers bypass to serve automotive accounts directly.
OEMs retain specification control, while Tier-1 Suppliers are consolidating procurement leverage through platform standardization.
Form:
Processing method dictates dimensional precision, surface finish, and unit economics.
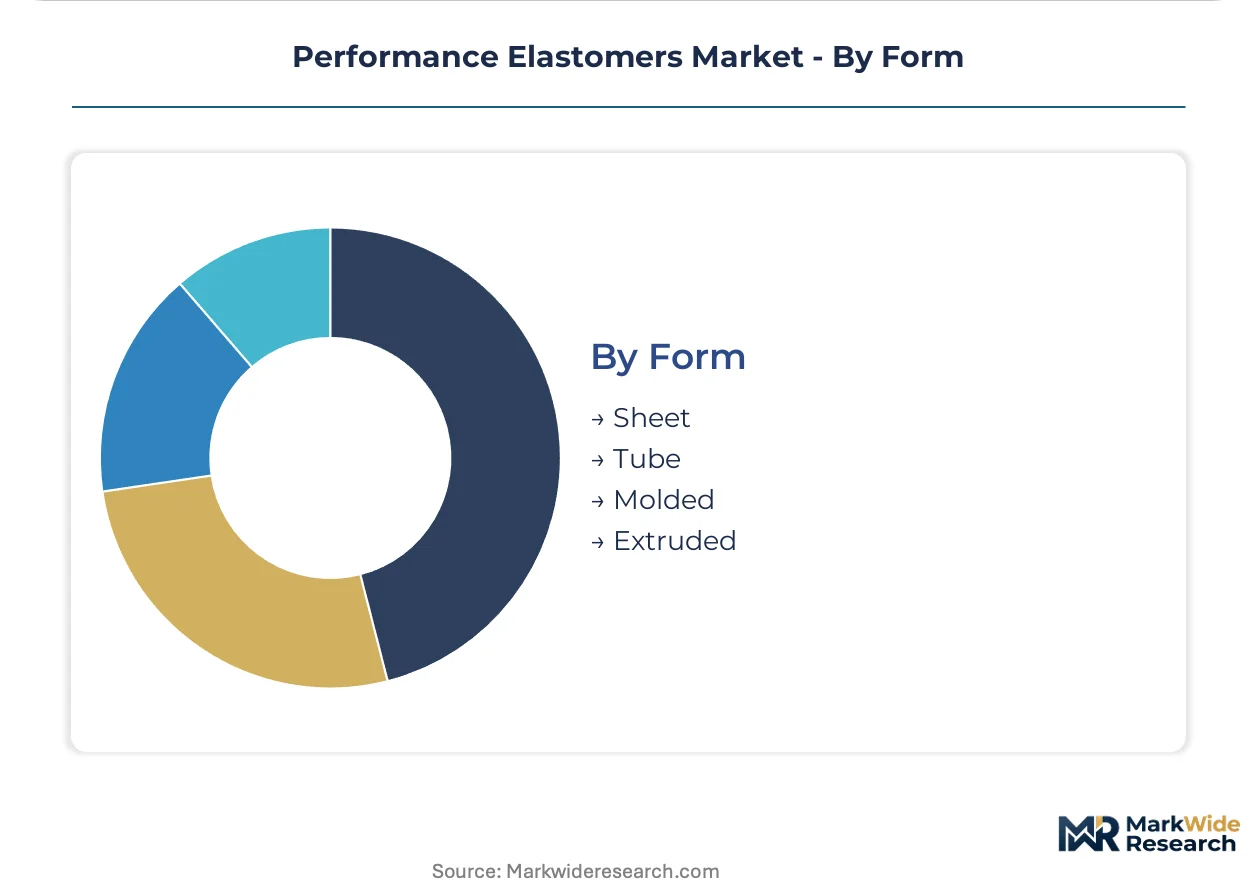
- Molded:Compression and injection molding achieve complex geometries with tight tolerances for healthcare device sealing and automotive gaskets.
- Extruded:Continuous profiles serve door seals, tubing, and weatherstripping with high throughput and minimal waste.
- Sheet:Calendered goods supply industrial fabrication with die-cut flexibility for gaskets and pads.
- Tube:Extruded hollow sections serve fluid transfer and protective sleeving applications.
Sheet and extruded forms capture majority industrial volume, while molded components command premium positioning on precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway and Rotterdam-Antwerp pipeline corridor underwrite Europe's chemical logistics supremacy for elastomer feedstock distribution. Automotive electrification is redrawing procurement maps as battery sealing specifications diverge across regulatory jurisdictions.
United States
EPA enforcement of TSCA Section 5 premanufacture notices is slowing novel curative introductions for silicone formulations. The Houston Ship Channel petrochemical complex anchors EPDM rubber production with integrated propylene supply from Gulf Coast crackers. Electric vehicle battery plants in Michigan and Tennessee are pulling compounded gasket materials away from traditional distributor channels.
Germany
ECHA REACH substance evaluations are accelerating substitution timelines for plasticizers in NBR and chloroprene compounds. The Stuttgart-Wolfsburg automotive supplier corridor concentrates specification authority for peroxide-cured EPDM grades in electric vehicle cooling systems. Lanxess AG's backward integration into ethylene-propylene rubber feedstocks exemplifies producer-Tier-1 direct contracting.
China
GB/T thermal runaway containment protocols for electric vehicle battery enclosures mandate compression-set-resistant gasket specifications. The Yangtze River Delta petrochemical cluster around Shanghai supplies silicone monomer for domestic elastomer compounding. MIIT industrial policy is pulling fluorocarbon polymerization capacity toward domestic semiconductor sealing applications.
Japan
METI carbon neutrality roadmaps are redirecting synthetic rubber investment toward bio-based feedstock pilot plants. The Kansai manufacturing belt around Osaka retains specialized fluorocarbon elastomer polymerization for aerospace and semiconductor sealing. Shin-Etsu Chemical Co., Ltd.'s integrated silicone supply chain anchors premium-grade production for electric vehicle inverter housings.
India
PLI scheme production-linked incentives for domestic automotive manufacturing are pulling compounding capacity toward Chennai and Pune industrial zones. BIS certification requirements for automotive sealing components are extending qualification timelines for imported formulations. The Maharashtra-Gujarat chemical corridor is attracting EPDM masterbatch investments to serve domestic electric vehicle battery enclosure demand.
Performance Elastomers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and compounding. The vendor base separates into integrated polymer producers with captive monomer supply, independent compounders serving industrial distribution, and specialized fabricators for healthcare and aerospace qualification tiers. Three archetypes dominate: backward-integrated chemical majors, regional compounding specialists, and application-specific qualification holders. Competitive moves concentrate on direct OEM contracting to bypass distribution, and digital twin integration to compress material qualification cycles.
Among integrated chemical majors, Dow Inc. and Wacker Chemie AG occupy positions exemplifying captive silicone value chain control. DuPont de Nemours, Inc. and Solvay S.A. represent the fluorocarbon-specialist archetype with concentration in high-temperature sealing applications. Arkema S.A. and Mitsui Chemicals, Inc. sit within the diversified polymer portfolio tier serving multiple industrial end-uses through regional compounding partnerships.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Arkema S.A. |
| Dow Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Lanxess AG |
| DuPont de Nemours, Inc. |
| Solvay S.A. |
| Mitsui Chemicals, Inc. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
The Rhine-Main-Danube waterway and Rotterdam-Antwerp pipeline corridor transmit feedstock cost volatility directly into EPDM compounder margins, compressing working capital for mid-tier producers while enabling integrated majors to enforce three-tier pricing stratification across automotive OEM direct contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates peroxide-cured silicone grades for electric vehicle battery sealing from sulfur-cured EPDM weatherstrip compounds and commodity industrial sheet goods. Price differentiation rests on REACH compliance certification and volume scale, with automotive OEM direct contracts commanding substantial premia over distributor-mediated industrial supply. Cost compression in standard-tier NBR hydraulic hose formulations is intensifying because propylene derivative feedstock volatility has compressed compounder margins by double-digit percentages. Tier-1 automotive suppliers exhibit lowest price sensitivity due to warranty exposure and platform standardization, while industrial fabricators purchasing through distribution demonstrate highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Contract manufacturing concentration for fluorocarbon elastomer polymerization sits with Shin-Etsu Chemical and select US Gulf Coast integrated producers, creating geographic single-source exposure for aerospace and semiconductor sealing buyers. Geographic supply concentration clusters in Germany, China, and Japan, with the Stuttgart-Wolfsburg corridor anchoring European EPDM compounding and the Yangtze River Delta dominating silicone monomer production. Raw material dependencies draw from naphtha-cracker propylene and ethylene derivatives, bio-based process oil alternatives, and specialty peroxide curatives facing ECHA registration delays. Single-source vulnerability in FKM polymerization capacity presents acute structural risk. Distribution runs through direct producer-OEM bilateral partnerships that are disintermediating traditional chemical distributors, particularly in German automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification compressing thermal management tolerances represents a high-growth disruption, as battery enclosure sealing specifications diverge across China's GB/T protocols and EU REACH substance restrictions, creating contract windows for compliant compounders.
For Market Incumbents: Harden backward integration into ethylene-propylene rubber feedstocks to defend against naphtha-cracker margin volatility and propylene derivative cost swings. Anchor competitive position through captive compounding assets in the Stuttgart-Wolfsburg corridor, securing multi-year platform agreements with electric vehicle manufacturers before REACH authorization procedures freeze formulation pipelines.
For New Entrants and Emerging Players: India's underpenetrated automotive compounding landscape offers white-space expansion, with PLI scheme production-linked incentives pulling capacity toward Chennai and Pune industrial zones. Target healthcare device sealing applications where FDA 21 CFR 177.2600 compliance gaps among Asian compounders create entry points for suppliers with validated ISO 13485 quality systems. Pursue digital twin integration partnerships with German Tier-1 suppliers to compress material qualification cycles.
For Investors and Strategic Acquirers: Regional compounding specialists with peroxide cure system expertise and established automotive OEM relationships represent priority acquisition targets, as retiring European and North American technician knowledge creates capability scarcity. Long-term viability favors suppliers with demonstrated REACH substitution timelines and bio-based feedstock certification. Monitor ECHA substance evaluation announcements for early signals of formulation pipeline freezes that would reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Lanxess AG's captive ethylene-propylene rubber production secures margin control against naphtha-cracker volatility. |
| Direct OEM Contracting | Dow Inc.'s bilateral technical partnerships with electric vehicle manufacturers disintermediate traditional chemical distributors. |
| Digital Twin Integration | Finite-element modeling platforms compress material qualification from eighteen months to under six for Tier-1 suppliers. |
| Healthcare Certification Investment | ISO 13485 quality systems create entry barriers against Asian compounders lacking FDA 21 CFR 177.2600 compliance. |
| Bio-based Feedstock Transition | EPDM weatherstrip producers certifying sustainable process oils capture contract windows under EU Green Deal restrictions. |
Methodological Framework
Cross-validation between primary interviews with elastomer plant managers, automotive Tier-1 procurement leads, and technical R&D directors and secondary validation through ECHA REACH substance databases, SEC 10-K filings of integrated chemical majors, and Cefic industry reports anchors the qualitative findings. Bottom-up triangulation of compounding capacity utilization and top-down reconciliation against automotive production forecasts establish volume integrity across the analysis window.
Calibration against historical substitution timelines for REACH-authorized substances and electric vehicle platform deployment trajectories shapes the analytical framework. Segmentation dimensions modeled include polymer chemistry tier, end-use industry criticality, cure system type, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections for battery enclosure sealing and cooling loop applications, incorporating GB/T thermal runaway containment protocol adoption curves and peroxide curative supply constraints.
Practitioners should monitor ECHA authorization procedure announcements, propylene derivative margin spreads, and electric vehicle platform standardization decisions for early signals of forecast revision. Quarterly review of REACH substance evaluation timelines, automotive OEM direct contracting announcements, and bio-based feedstock certification progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Global Latex Allergy Market
Rubber
Industrial Rubber Market
Rubber
Polyisoprene Rubber Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Rubber Color Masterbatch Market
Rubber
Isoprene Rubber Market
Rubber
Liquid Silicone Rubber Market
Rubber
Global Crumb Rubber Market
Rubber
Tire Reinforcement Materials Market
Rubber
Europe Neoprene Market
Rubber
Silicone Rubber Market
Rubber
Rubber Splicing Tape Market
Rubber
Cellular Rubber Market
Rubber
Rubber Tapes Market
Rubber
Rubber Sand Market