
 Ticket Machine Market | 2026-2036
Ticket Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ticket Machine Market Analytics
Transit agency procurement is collapsing toward integrated mobility platforms that bundle fare collection with real-time passenger information. Scheidt & Bachmann GmbH leverages its long-standing relationships with German rail operators to sustain dominant positions in gate-line and platform validator hardware. Cubic Transportation Systems, Inc. anchors North American demand through its back-office revenue management platforms for major metropolitan agencies. Thales Group competes across European tenders by embedding cybersecurity certifications directly into its terminal firmware.
A ticket machine is an electromechanical or fully electronic terminal engineered to dispense, validate, or process fare media for transit, entertainment, or retail access control, typically incorporating thermal printers, contactless card readers, and encrypted payment modules operating at ISO 14443 frequency. Self-service kiosks dominate capital expenditure in metro and commuter rail deployments where throughput exceeds 10,000 passengers per hour per station. Mobile ticketing solutions represent the fastest-expanding deployment mode as agencies bypass hardware capital in favor of smartphone-based account-based ticketing. Contactless payment technology leads technology adoption, with NFC modules now standard across all new installations in OECD markets.
The European Commission's Interoperable Fare Management framework and the US Federal Transit Administration's Buy America provisions jointly shape procurement eligibility and component sourcing requirements for vendors serving public transit. Payment Card Industry Data Security Standard certification, enforced by card networks rather than governments, functions as a de facto market access gate for any terminal handling open-loop bank card transactions. Stakeholders must monitor whether central bank digital currency pilots in major economies rewrite the payment protocol stack that current hardware generations encode.
Market Dynamics
Contactless payment mandates from the European Banking Authority and open-loop transit standards are forcing hardware refresh cycles across urban rail networks, compressing replacement timelines for legacy mechanical validators.
Growth Catalysts
- EMV Contactless Mandates:The European Banking Authority's regulatory push for open-loop bank card acceptance at transit gates requires NFC-enabled terminal deployments across German, French, and Dutch municipal networks.
- Urban Rail Modernization:Metro authorities in Tokyo, Seoul, and Singapore are replacing first-generation magnetic stripe validators with account-based ticketing infrastructure to handle passenger volumes exceeding 10,000 per hour per station.
- Interoperable Fare Frameworks:The European Commission's IFM technical specifications create procurement pull for standardized gate-line equipment that operates across bilateral cross-border rail corridors.
Market Restraints
- Semiconductor Supply Concentration:NFC controller chips and secure element modules concentrate among Taiwanese and South Korean foundries, exposing terminal manufacturers to allocation volatility and extended lead times.
- Capital Intensity of Certification:PCI-DSS Level 1 validation for open-loop payment terminals requires 18-24 month compliance timelines and recurring audit costs that freeze out smaller hardware vendors.
- Mobile Ticketing Substitution:Smartphone-based account-based ticketing applications eliminate hardware capital requirements entirely, threatening kiosk and validator unit economics in high-smartphone-penetration markets.
Strategic Opportunities
- Central Bank Digital Currency Pilots:The People's Bank of China and European Central Bank retail CBDC trials create firmware upgrade demand for terminals capable of processing programmable money protocols.
- Multimodal Mobility Platforms:Integration of fare collection with bike-sharing, ride-hailing, and parking systems opens service contract opportunities for vendors with back-office revenue management capabilities.
- US Federal Transit Administration Buy America:Domestic content requirements for federally funded transit projects create protected procurement pools for US-based final assembly and component sourcing.
Industry Challenges
- Cybersecurity Talent Scarcity:Terminal firmware development requires embedded systems engineers with payment security expertise, a skill combination concentrated among a limited pool of specialists in Germany and Israel.
- Legacy System Integration:New validators must interface with decades-old fare collection back-ends using proprietary protocols, extending deployment timelines and requiring custom middleware development.
- Certification Queue Bottlenecks:Payment network approval processes for contactless transit terminals have lengthened as submission volumes surge, delaying revenue recognition for hardware shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ticket Machine Market |
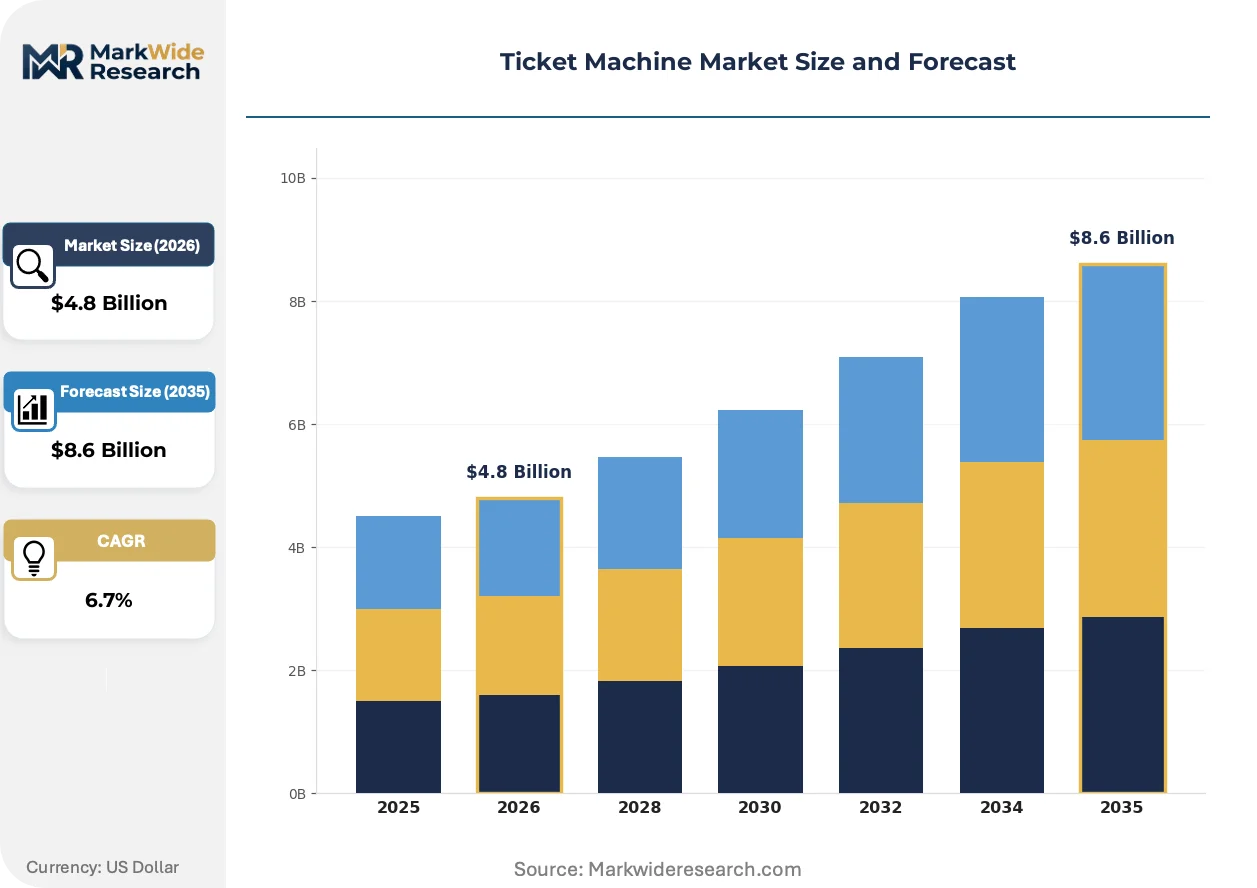
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Mobile Ticketing Solutions, Counter-Top Machines, Portable Devices Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Subscription-Based End User: Transportation Services, Entertainment Venues, Sports Events, Retail Outlets Technology: Contactless Payment, QR Code Scanners, NFC, Biometric Authentication |
| Companies Covered | Scheidt & Bachmann GmbH, OMRON Corporation, Genfare, Flowbird Group, AEP Ticketing Solutions s.r.l, Siemens AG, Thales Group, Cubic Transportation Systems, Inc., Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ticket Machine Market Evolving Landscape
Terminal hardware architecture is splitting between high-throughput gate-line systems for metro environments and lightweight platform validators for low-volume rural rail, driven by diverging passenger density and infrastructure investment patterns across operator tiers.
Edge computing modules with localized transaction processing are bifurcating the validator market. Tier-1 metro operators in London, New York, and Tokyo deploy these units to maintain service continuity during network outages. The technology compresses reliance on centralized back-office systems for fare validation decisions.
REACH substance restrictions and RoHS recast directives in the European Union are banning specific flame retardants and phthalates from terminal enclosures and cable assemblies. Manufacturers serving German and French tenders must reformulate housing materials and resubmit for electromagnetic compatibility certification. Asian component suppliers are accelerating halogen-free resin development to maintain access to European rail procurement.
Agency procurement teams are unbundling hardware purchase from long-term service agreements. Municipal operators in Spain and Italy now separate capital expenditure for gate-line equipment from multi-year maintenance and software update contracts. This shift is most visible in competitive tenders issued by Rome's ATAC and Barcelona's TMB, where financing vehicles and operating concessions attract distinct bidder pools.
Ticket Machine Market Segmentation
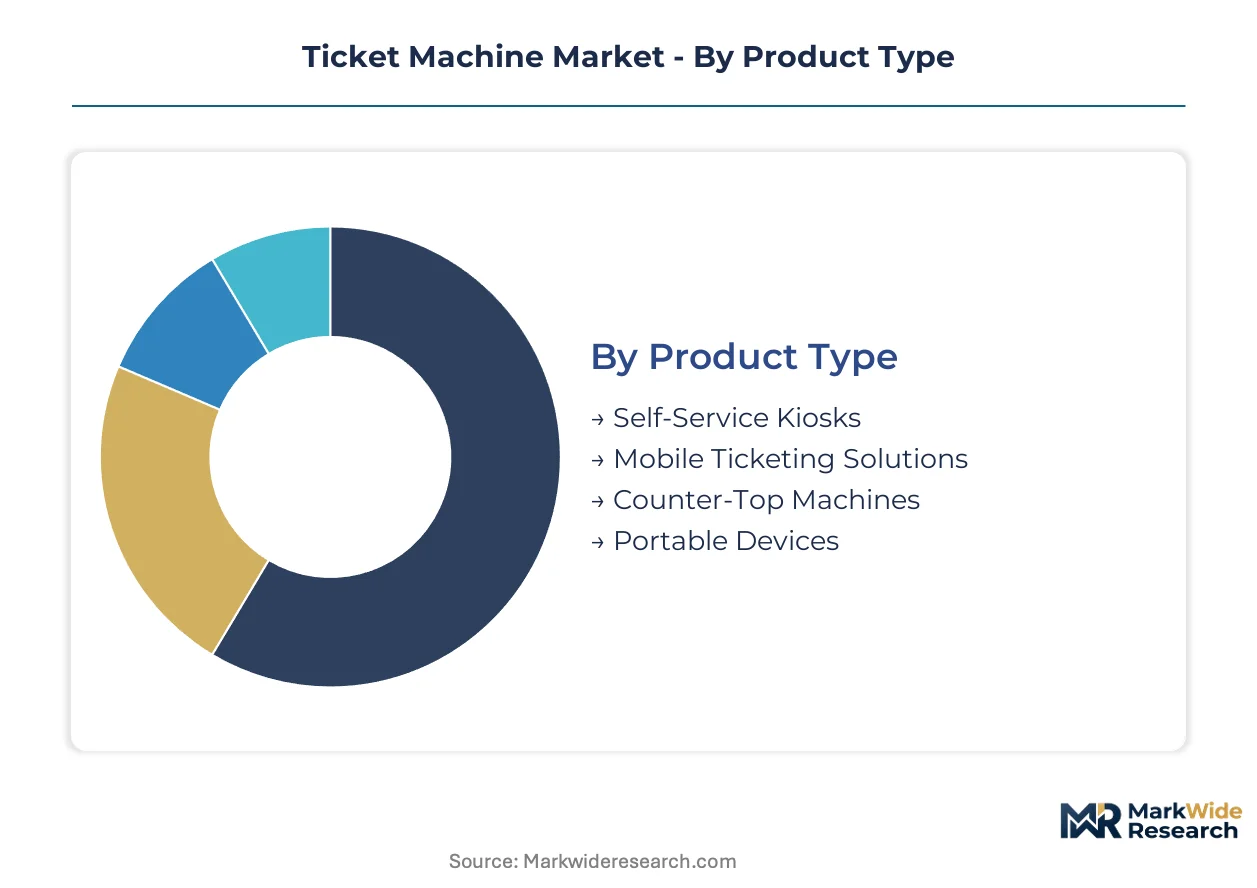
Ticket machine segmentation reveals divergent hardware requirements across transit density tiers and payment regulatory environments. Procurement specifications from urban rail operators versus rural bus networks create fundamentally different product qualification criteria.
Product Type:
Regulatory mandates for PCI-DSS certification and EMV contactless compliance split procurement pools between capital-intensive gate-line systems and lightweight mobile alternatives.
- Self-Service Kiosks:Freestanding electromechanical terminals integrate thermal printers, encrypted PIN pads, and NFC readers for high-throughput station environments. Deutsche Bahn and Tokyo Metro deploy these units where passenger volumes exceed 10,000 per hour, driven by European Banking Authority open-loop payment mandates.
- Mobile Ticketing Solutions:Smartphone-based account-based ticketing platforms bypass hardware capital entirely through cloud-hosted validation. Seoul and Singapore transit authorities favor this model for cost reduction, though PCI-DSS Level 1 compliance for back-end payment processing imposes 18-24 month certification timelines.
- Counter-Top Machines:Compact units serve retail and small entertainment venues with constrained floor space.
- Portable Devices:Handheld validators enable conductor-operated fare inspection on regional rail and bus fleets.
Self-service kiosks handle the majority of throughput; mobile ticketing solutions are expanding most quickly on share.
Deployment:
Cost tier differentiation separates upfront capital expenditure from recurring operational models, reshaping vendor cash flow structures and customer switching economics.
- On-Premises:Customer-owned infrastructure places hardware maintenance and software patching burden on transit agency IT departments. German municipal operators prefer this model for cybersecurity sovereignty under Federal Office for Information Security guidelines.
- Cloud-Based:Fully hosted architectures centralize transaction processing and firmware updates through vendor-managed data centers. French and Dutch agencies adopt this approach to reduce on-site technical staffing, constrained by GDPR data residency requirements for passenger payment records.
- Hybrid Solutions:Edge computing modules process validation locally during network outages while syncing to central systems.
- Subscription-Based:Per-transaction or per-terminal recurring fees replace upfront hardware purchase.
On-premises deployments dominate legacy infrastructure; cloud-based models are climbing the fastest on share.
End User:
Application-specific durability and throughput requirements create divergent product roadmaps across verticals with distinct passenger density patterns.
- Transportation Services:Rail and bus operators demand IP54-rated enclosures, 24/7 operational duty cycles, and integration with legacy AFC back-ends. This segment concentrates procurement volume in Germany, Japan, and Singapore where urban rail modernization programs replace first-generation magnetic stripe validators.
- Entertainment Venues:Theaters and amusement parks prioritize compact footprint and rapid ticket issuance over extreme durability. European cinema chains drive demand for countertop units with integrated QR scanning, shaped by REACH substance restrictions on enclosure materials.
- Sports Events:Temporary deployment models favor portable devices and rapid-install kiosks for seasonal venues.
- Retail Outlets:Multi-purpose terminals combine payment processing with loyalty program integration.
Transportation services command the dominant procurement volume; entertainment venues are gaining share fastest.
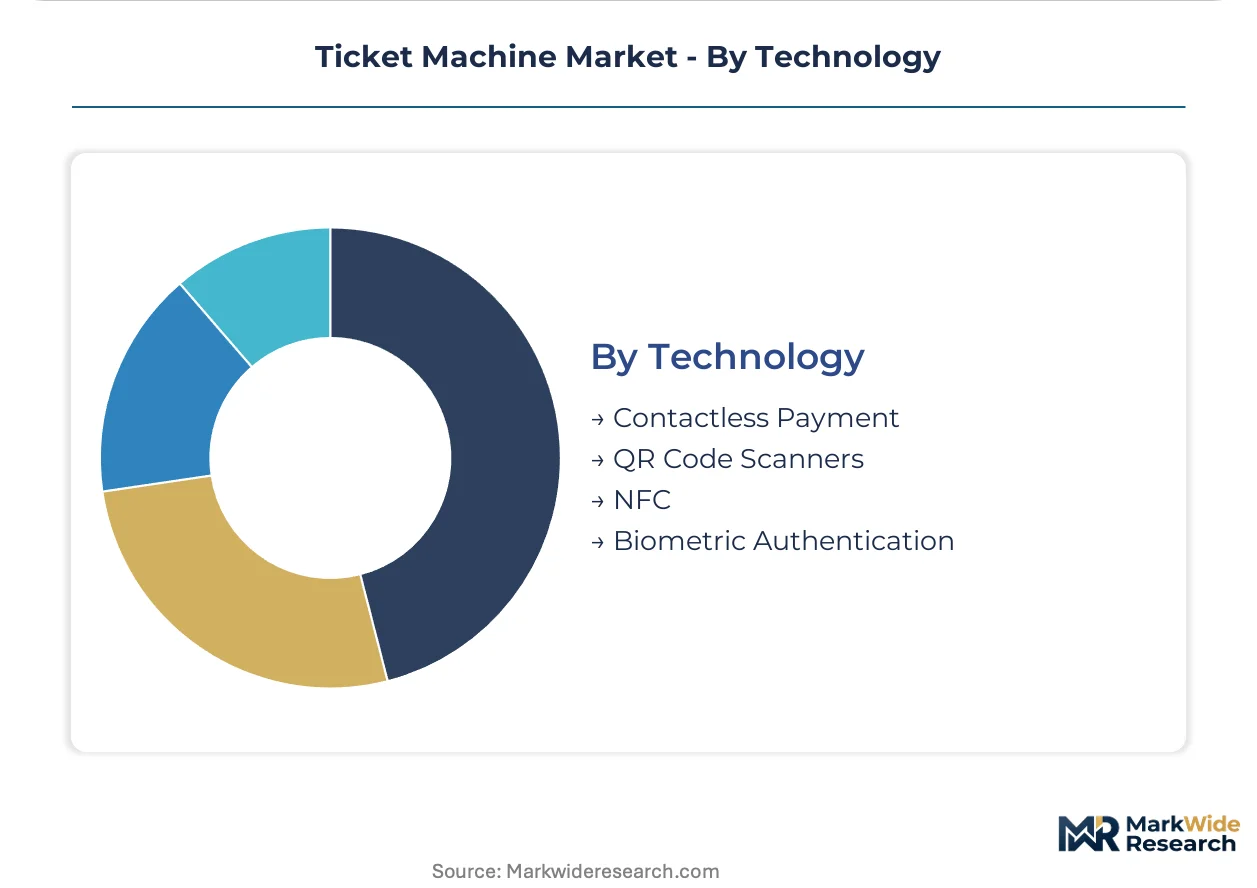
Technology:
Payment protocol standardization and cybersecurity certification queues determine which authentication methods achieve commercial scale.
- Contactless Payment:NFC modules operating at ISO 14443 frequency with EMV certification now constitute baseline requirements for OECD transit tenders. The European Banking Authority's regulatory push mandates bank card acceptance at gates, forcing hardware refresh cycles across French and Dutch municipal networks.
- QR Code Scanners:Camera-based validation enables smartphone ticketing without NFC hardware, prevalent in Asian markets with high mobile wallet penetration. Chinese transit operators deploy these systems at lower unit cost, though transaction latency limits suitability for high-throughput gate lines.
- NFC:Dedicated near-field communication hardware for transit-specific closed-loop cards and open-loop bank cards.
- Biometric Authentication:Facial recognition and palm vein scanners pilot in privacy-permissive jurisdictions.
Contactless payment carries the dominant installed base; QR code scanners show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube rail corridor underwrites Germany's central role in European fare collection infrastructure procurement, while the Tokyo-Osaka Shinkansen spine anchors Japanese validator deployment volumes.
Germany
Deutsche Bahn's €1.2 billion gate-line modernization program and municipal S-Bahn network upgrades drive hardware demand across 16 federal states. The Federal Office for Information Security enforces cybersecurity sovereignty guidelines that favor domestic final assembly. Manufacturing clusters in Bavaria and North Rhine-Westphalia host Scheidt & Bachmann GmbH production facilities serving cross-border rail corridors into France and the Netherlands.
Japan
JR East and Tokyo Metro replace first-generation magnetic stripe validators with account-based ticketing infrastructure ahead of 2025 Expo Osaka. METI's Society 5.0 digitalization roadmap mandates open-loop payment compatibility at all major stations. Industrial concentration in the Kanto region around Yokohama and Saitama supports precision manufacturing of high-throughput gate-line equipment.
United States
The MTA's OMNY rollout and Los Angeles Metro's TAP 2.0 migration compress replacement timelines for legacy fare collection systems. Federal Transit Administration Buy America provisions require 70% domestic content for federally funded projects. Cubic Transportation Systems anchors West Coast procurement through San Francisco Bay Area and Seattle deployments.
France
RATP's Grand Paris Express expansion and SNCF's interoperable fare management compliance create tender opportunities for next-generation platform validators. ANSSI cybersecurity certification requirements extend procurement timelines for foreign vendors. The Île-de-France region concentrates demand through Paris Metro, RER, and forthcoming metro line extensions.
Singapore
Land Transport Authority's SimplyGo account-based ticketing platform eliminates stored-value card dependency across MRT and bus networks. Personal Data Protection Commission guidelines shape cloud-hosted transaction architecture decisions. The Jurong East and Tampines station clusters pilot edge computing validators with localized processing capabilities.
Ticket Machine Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized transit technology providers. The vendor base splits between European rail specialists with embedded operator relationships and North American platform vendors with back-office software integration capabilities. Three archetypes dominate: gate-line hardware fabricators with decades-long operator contracts, cloud-native account-based ticketing platforms, and diversified electronics manufacturers leveraging component synergies. Competitive positioning hardens through firmware certification speed and legacy system integration expertise rather than unit cost alone.
Within the European specialist tier, Scheidt & Bachmann GmbH exemplifies the gate-line hardware archetype through its embedded position in German-speaking rail networks. Thales Group occupies a diversified technology position spanning defense, aerospace, and transit verticals with cybersecurity certification capabilities. Cubic Transportation Systems, Inc. anchors North American competitive dynamics through its concentration in major metropolitan agency procurements. These three represent distinct strategic postures: regional relationship depth, multi-vertical technology leverage, and platform-scale software integration respectively.
| Leading Market Players |
|---|
| Scheidt & Bachmann GmbH |
| OMRON Corporation |
| Genfare |
| Flowbird Group |
| AEP Ticketing Solutions s.r.l |
| Siemens AG |
| Thales Group |
| Cubic Transportation Systems, Inc. |
| Xerox Corporation |
| Others |
Value Network & Pricing Analysis
Gate-line equipment manufacturing exhibits pronounced scale economies, with production volumes above 50,000 units annually compressing per-unit fixed costs by 40-60% versus mid-tier fabricators. This concentration of viable capacity among German and Japanese producers establishes price floors that smaller vendors cannot undercut without sacrificing PCI-DSS certification investment or electromagnetic compatibility testing rigor.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement by transit agency size, with municipal operators purchasing 500-plus validator units commanding 15-25% unit cost reductions against smaller regional rail authorities. Three-tier pricing stratifies across premium certified, standard compliant, and economy-specified equipment levels, with differentiation anchored in cybersecurity certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Taiwanese NFC controller shortages force vendors to absorb component inflation or lose municipal tenders. Regional bus operators exhibit highest price sensitivity, while Tokyo and London metro authorities prioritize throughput reliability over unit cost.
Supply Chain Analysis
Inventory strategy preferences favor just-in-time component flows for standardized NFC modules, while strategic stockpiling secures allocation for secure element chips facing 26-week foundry queues. Manufacturing concentration centers on Germany, Japan, and Taiwan, with final assembly drawing from South Korean memory components and Chinese enclosure fabricators. Raw material dependencies span halogen-free resins for REACH compliance, copper-nickel alloys for contactless antenna substrates, and specialized thermal paper for ticket stock. Single-source vulnerability concentrates in Taiwanese NFC controller foundries, exposing terminal manufacturers to allocation volatility. Distribution runs through authorized systems integrators holding long-term maintenance contracts with Deutsche Bahn, JR East, and RATP.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware procurement is consolidating toward service-attach models where firmware update subscriptions and cybersecurity monitoring contracts expand at triple the rate of gate-line equipment sales. This recurring-revenue layer now constitutes 35-45% of vendor lifetime value per terminal deployment.
For Market Incumbents: Fortify embedded positions in German and Japanese rail networks by acquiring middleware specialists capable of legacy AFC back-end integration. Prioritize certification investment for central bank digital currency protocol support before pilot programs advance to production scale. Defensive consolidation should target regional validators serving rural rail corridors where mobile ticketing substitution threatens kiosk economics.
For New Entrants and Emerging Players: Lead with cloud-hosted validation platforms targeting French and Dutch agencies constrained by GDPR data residency requirements but seeking to reduce on-site technical staffing. The most penetrable white-space sits in Spanish and Italian municipal operators unbundling hardware purchase from multi-year maintenance contracts. Go-to-market positioning should emphasize edge computing modules for network resilience during outages.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with firmware certification speed and legacy system integration expertise over pure hardware fabricators. Long-term viability over the next decade hinges on back-office revenue management platform ownership rather than terminal manufacturing scale. Acquisition targets should display embedded relationships with 3-plus metropolitan agencies and demonstrated PCI-DSS Level 1 validation timelines under 18 months. The signal to watch is central bank digital currency pilot advancement to production mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| PCI-DSS Level 1 Certification Investment | Payment network approval unlocks open-loop transit tenders across European Banking Authority jurisdictions. |
| Legacy AFC Middleware Acquisition | Proprietary protocol integration expertise compresses deployment timelines for Deutsche Bahn and JR East. |
| Edge Computing Module Development | Localized transaction processing meets London and Tokyo operator requirements for network outage resilience. |
| CBDC Protocol Firmware Upgrade | People's Bank of China and European Central Bank pilots create upgrade demand for programmable money terminals. |
| Cloud-Hosted Validation Platform Launch | French ANSSI and Dutch GDPR constraints favor vendors with EU data center sovereignty. |
Research Methodology
Initial hypotheses were tested against primary input from transit agency procurement directors, AFC systems engineers, payment security consultants, and terminal manufacturing executives and refined through secondary validation. Primary fieldwork encompassed structured interviews regarding tender specifications, certification timelines, and legacy integration requirements. Secondary sources included European Commission IFM technical specifications, Federal Transit Administration Buy America compliance records, PCI Security Standards Council certification databases, and customs trade data for NFC component flows. Bottom-up unit deployment estimates triangulated against top-down transit authority capital expenditure disclosures.
Variance-decomposition framing isolates volume, price, and mix effects across product type, deployment model, end-use vertical, and payment technology segments. The analytical framework models unit shipments and average selling prices across the projection horizon, with CAGRs derived from logistic adoption curves for contactless payment penetration and replacement cycle compression. Industry-specific inputs span semiconductor foundry allocation forecasts, regulatory mandate implementation schedules, and mobile ticketing substitution elasticity by smartphone penetration tier.
The analysis sits within stated boundaries; outcomes outside sustained EMV contactless mandate enforcement or accelerated CBDC production deployment would require recalibration. Forecasts reflect assumptions regarding certification queue durations, legacy system interoperability complexity, and component supply normalization. Revision becomes warranted when NFC controller foundry utilization crosses 90% sustained thresholds or when central bank digital currency protocols achieve legislative production mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Self-Service Market
Retail Technology
Global Smart Retail Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
US Retail Recon Software Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Digital Kiosk Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Smart Shelf Market
Retail Technology
Retail-As-A-Service (Raas) Market