
 VR Amusement Equipment Market | 2026-2036
VR Amusement Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
VR Amusement Equipment Market Insights
6-DOF motion tracking specifications is redrawing competitive benchmarks across the VR amusement equipment landscape. Meta Platforms Inc. leverages its Quest hardware ecosystem to anchor large-scale location-based deployments in North American entertainment venues. HTC Corporation specializes in enterprise-grade arcade systems with sub-millimeter tracking precision, while Zero Latency Pty. Ltd. operates wireless free-roam arenas that dominate the premium out-of-home segment.
VR amusement equipment encompasses electromechanical systems combining head-mounted displays, motion platforms, and spatial computing interfaces engineered to deliver immersive entertainment experiences in commercial venues. These installations typically integrate refresh rates exceeding 90 Hz, positional tracking accuracy below 20 milliseconds latency, and haptic feedback arrays to synchronize physical stimuli with visual output. Motion simulators command the highest capital allocation per unit across product categories, whereas VR experiences built on gesture recognition technology represent the fastest-expanding technology segment. Family entertainment centers absorb the majority of end-user procurement volume, with shopping mall installations emerging as a concentrated margin pool due to foot traffic density and shorter payback periods.
FCC equipment authorization requirements in the United States, CE marking obligations under European machinery directives, and China's GB standards for electronic amusement devices collectively shape product compliance costs and market entry timelines. Japan's METI safety guidelines for immersive entertainment systems further constrain hardware design parameters for vendors targeting East Asian deployment. Stakeholders must weigh regulatory certification lead times against the acceleration of location-based entertainment rollouts in tier-one metropolitan markets.
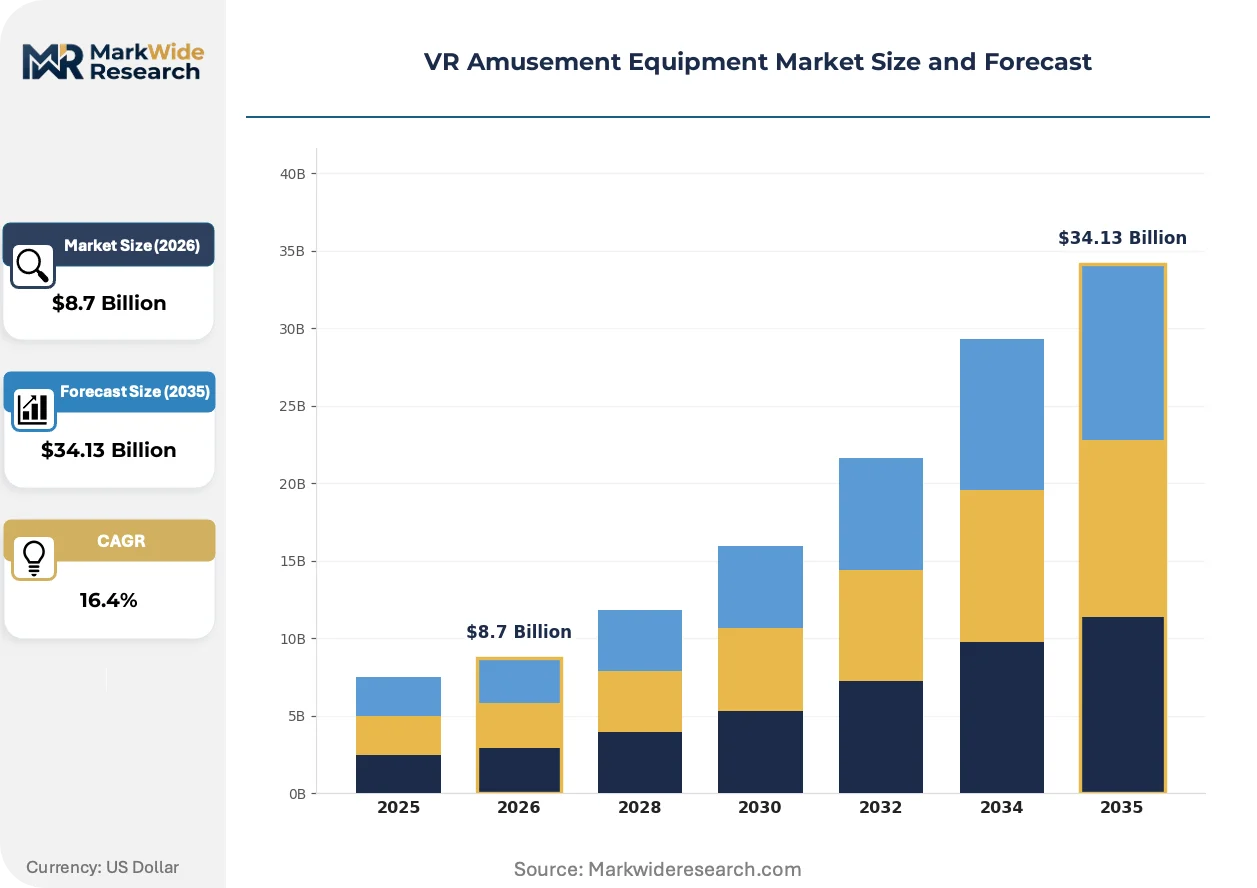
Market Dynamics
6-DOF motion tracking specifications are compressing refresh rate and latency thresholds across commercial VR deployments, forcing hardware vendors to recalibrate electromechanical integration strategies for location-based entertainment venues.
Growth Catalysts
- MIIT immersive device standards:China's tightening certification requirements for safety and content ratings are accelerating product differentiation among compliant manufacturers seeking venue deployment contracts.
- Metropolitan entertainment clusters:Concentrated demand in United States, China, and Japan urban centers is generating network effects that reduce customer acquisition costs for repeat-installation vendors.
- Free-roam wireless architectures:Elimination of tethered constraints in premium out-of-home venues is expanding throughput capacity per square meter and compressing payback periods.
Market Restraints
- Motion platform capital intensity:Electromechanical base systems with sub-20ms latency specifications require specialized servo motor arrays and precision fabrication that concentrate supply among Japanese and German component specialists.
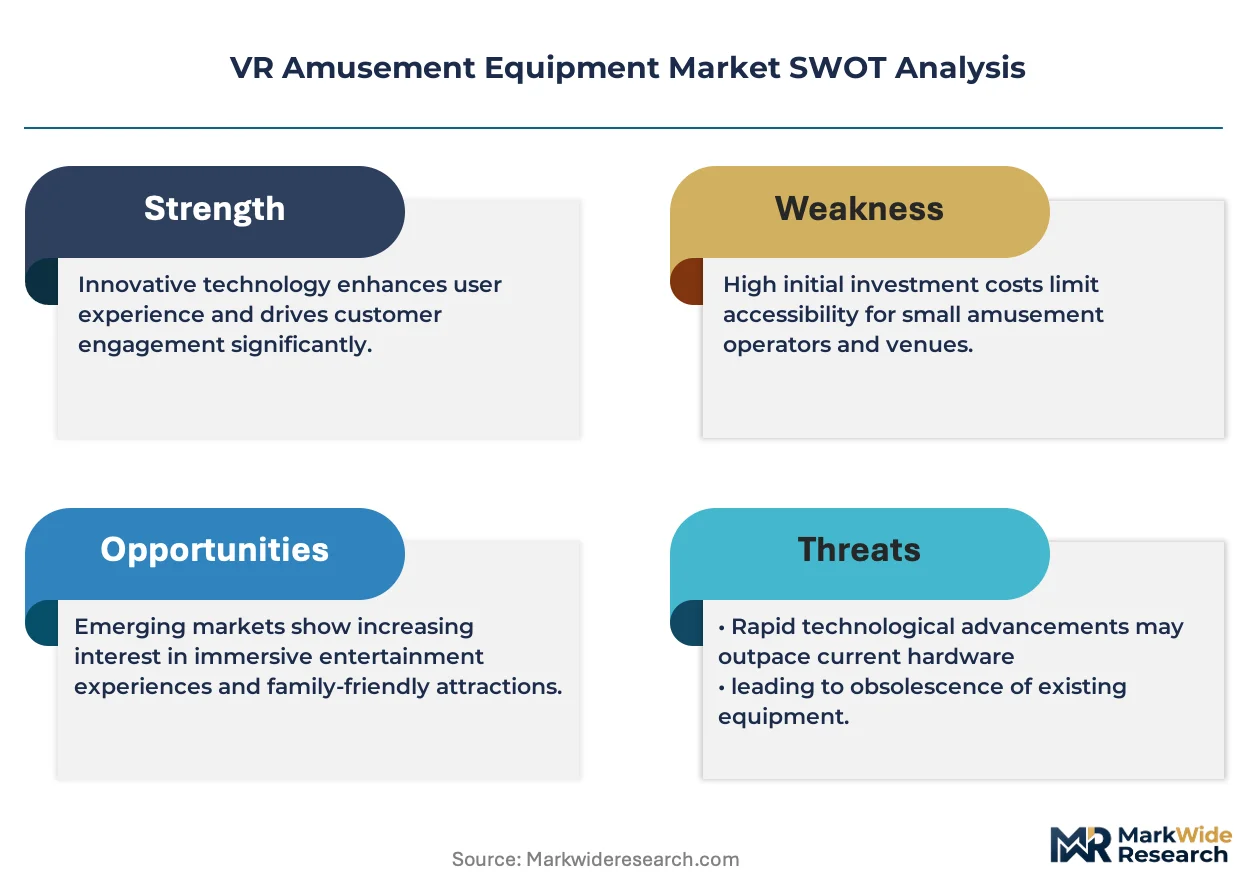
- FCC equipment authorization timelines:United States radio frequency certification for wireless tracking systems extends market entry lead times by 4-8 months for non-domestic manufacturers.
- Gesture recognition substitution pressure:Camera-based hand tracking without controller hardware is eroding attach rates for haptic peripheral bundles in mid-tier family entertainment center configurations.
Strategic Opportunities
- Shopping mall channel expansion:Foot traffic density in United States and United Arab Emirates retail complexes is creating concentrated margin pools with shorter depreciation cycles than standalone arcade venues.
- Japan METI safety guideline alignment:Proactive compliance with East Asian immersive entertainment standards opens procurement pipelines in Japanese family entertainment centers and export-adjacent markets.
- Haptic-audio convergence:Integration of spatial audio arrays with force-feedback seating systems is enabling premium pricing tiers for narrative-driven location-based experiences.
Industry Challenges
- Spatial computing talent scarcity:Shortage of engineers with simultaneous expertise in electromechanical systems, real-time rendering pipelines, and venue operations is constraining R&D velocity for mid-scale manufacturers.
- CE marking machinery directive complexity:European conformity assessment for motion platforms with passenger-carrying functions requires third-party notified body involvement that extends certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Amusement Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VR Arcade Machines, VR Headsets, Motion Simulators, VR Experiences Technology: Head-Mounted Displays, Haptic Feedback, Gesture Recognition, VR Software End User: Entertainment Parks, Shopping Malls, Events, Family Entertainment Centers Customer Type: Casual Gamers, Adventure Seekers, Families, Corporate Clients |
| Companies Covered | Meta Platforms Inc., Sony Group Corporation, HTC Corporation, Samsung Electronics Co., Ltd., Hologate, Zero Latency Pty. Ltd., Sandbox VR, The Void LLC, Survios Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Amusement Equipment Market Trends and Innovations
Wireless free-roam architectures and AI-driven content personalization are restructuring capital deployment patterns across location-based entertainment, compressing the technical specifications gap between premium and standard-tier installations.
Inside-out tracking systems leveraging onboard cameras and IMU fusion are supplanting external lighthouse configurations in commercial deployments. Family entertainment centers across the United States and United Arab Emirates are adopting these self-contained architectures to reduce installation complexity and venue retrofit costs. The shift is enabling faster equipment rotation cycles and reducing dependency on specialized technical staff for calibration maintenance.
China's MIIT standards for immersive device safety and content ratings are tightening hardware design parameters and certification documentation requirements. Domestic manufacturers are accelerating in-house testing laboratory investments to compress approval timelines. The regulatory pressure is most acute for motion simulator categories with passenger restraint systems, where GB standard compliance documentation now requires extended durability testing protocols.
Venue procurement patterns are fragmenting toward shorter-term equipment leasing arrangements with integrated content refresh obligations. Shopping mall operators in Japan and the United Arab Emirates are displacing outright purchase models with revenue-share structures that transfer obsolescence risk to equipment vendors. This behavioral shift is most visible in metropolitan entertainment clusters where tenant turnover rates exceed 24-month equipment depreciation schedules.
VR Amusement Equipment Market Segmentation
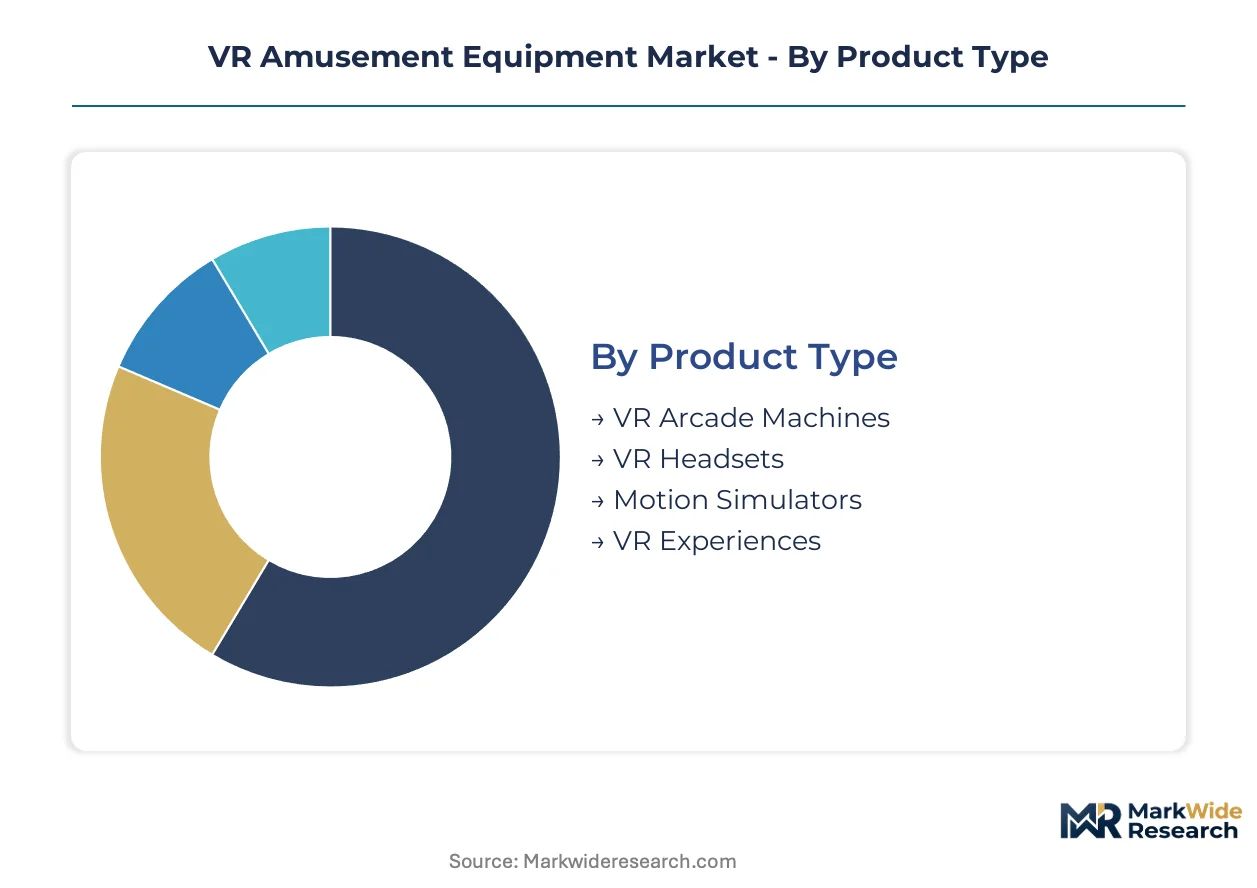
Segmentation in the VR amusement equipment market reveals divergent margin pools across hardware categories, with capital intensity and venue throughput capacity determining vendor profitability. Procurement patterns vary sharply between electromechanical systems requiring specialized installation and self-contained units suited for rapid retail deployment.
Product Type:
Margin concentration follows capital intensity gradients, with high-ticket electromechanical systems commanding premium pricing and extended depreciation schedules.
- Motion Simulators:Electromechanical base systems integrate servo motor arrays, six-axis motion platforms, and passenger restraint mechanisms engineered for sub-20ms latency synchronization. Demand clusters in Japanese and United States family entertainment centers where throughput capacity justifies six-figure unit investments and 36-month payback thresholds.
- VR Experiences:Software-driven installations leveraging wireless free-roam architectures eliminate tethered constraints and reduce venue retrofit costs. Shopping mall operators in the United Arab Emirates and United States metropolitan clusters are accelerating procurement of these systems due to faster installation cycles and revenue-share leasing compatibility.
- VR Arcade Machines:Cabinet-based systems with integrated displays and controller peripherals occupy mid-tier positioning between premium simulators and entry-level headsets.
- VR Headsets:Standalone HMD units for tethered or wireless deployment represent the lowest capital entry point with highest equipment rotation frequency.
The dominant share belongs to Motion Simulators, while VR Experiences is closing the gap fastest.
Technology:
Technology segmentation tracks hardware-software integration depth, with systems combining multiple sensory modalities capturing disproportionate venue procurement budgets.
- Haptic Feedback:Force-feedback arrays and vibrotactile interfaces synchronize physical stimuli with visual output, enabling premium pricing for narrative-driven location-based entertainment. Family entertainment centers in Japan and the United States are prioritizing these systems for differentiated guest experiences.
- Gesture Recognition:Camera-based hand tracking without controller hardware is eroding attach rates for peripheral bundles while expanding addressable venue segments. China's MIIT certification requirements for optical tracking systems are compressing approval timelines for domestic manufacturers.
- Head-Mounted Displays:Display modules with refresh rates exceeding 90 Hz form the visual foundation across all installation tiers.
- VR Software:Content platforms and experience management systems determine equipment utilization rates and repeat visitation metrics.
Haptic Feedback retains the revenue concentration lead, though Gesture Recognition is expanding most quickly among mid-tier configurations.
End User:
End-user segmentation maps directly to foot traffic density and capital deployment flexibility, with multi-use venues outperforming single-purpose installations on utilization metrics.
- Family Entertainment Centers:Integrated venues combining dining, arcade, and attraction functions absorb the majority of procurement volume across the United States, Japan, and China. These operators prioritize equipment with 24-month depreciation compatibility and content refresh obligations.
- Shopping Malls:Retail complex installations in the United Arab Emirates and United States benefit from ambient foot traffic and shorter payback periods than standalone venues. Revenue-share leasing structures are displacing outright purchase models as tenant turnover accelerates.
- Entertainment Parks:Large-scale theme park deployments require extended durability testing and regulatory documentation for passenger-carrying systems.
- Events:Temporary installations for corporate activations and touring exhibitions favor rapid-deployment equipment with minimal venue retrofit requirements.
Family Entertainment Centers hold the installed base majority, while Shopping Malls is gaining share fastest on leasing model adoption.
Customer Type:
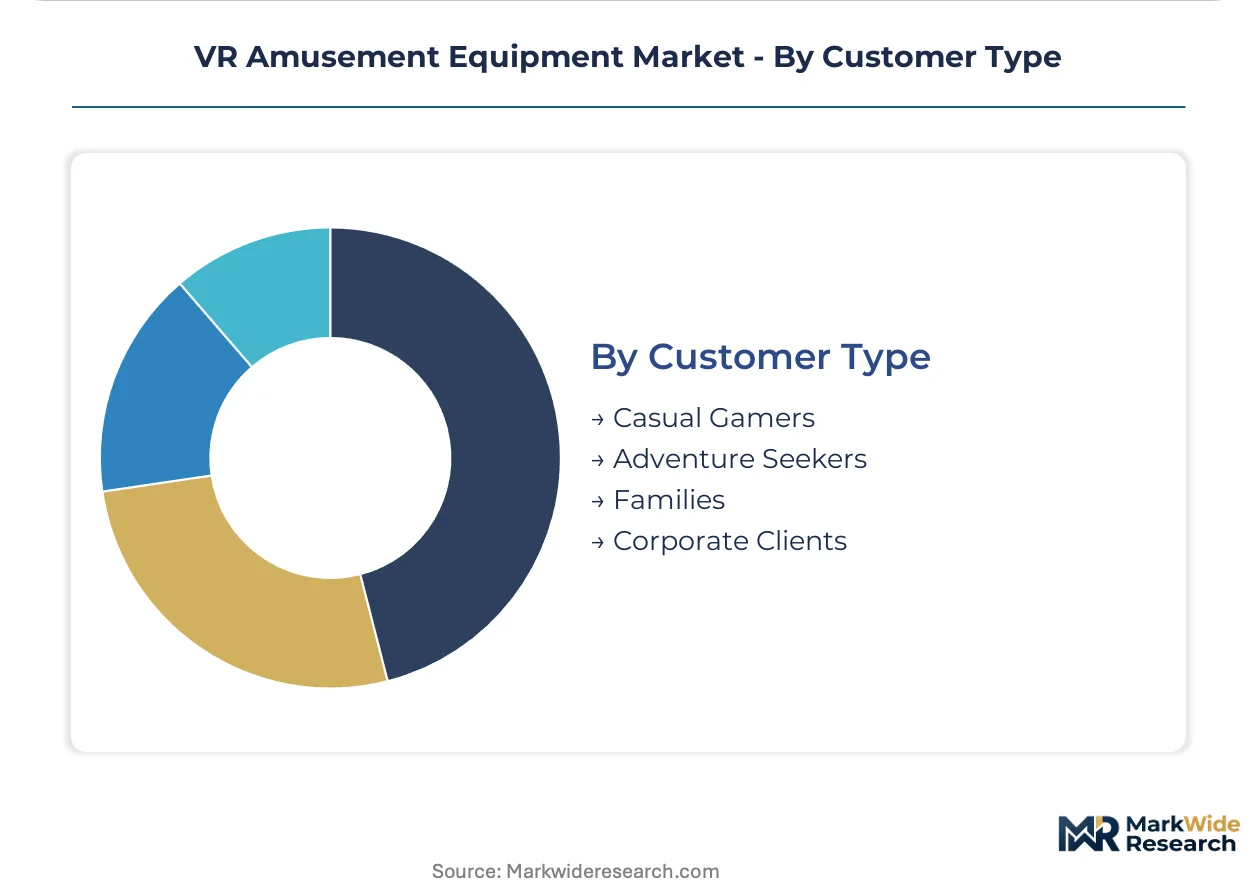
Customer segmentation reflects experience duration and group size preferences, with corporate and family segments driving divergent equipment specifications.
- Families:Multi-generational groups prioritize accessible content with moderate motion intensity and 15-20 minute experience durations. Venues in Japan and the United States are configuring equipment zones specifically for family unit throughput.
- Corporate Clients:Team-building and event rental demand concentrates in metropolitan United States and United Arab Emirates markets, favoring wireless free-roam systems supporting 4-8 simultaneous participants.
- Adventure Seekers:Individual enthusiasts and enthusiast groups drive premium tier demand for high-fidelity motion simulation and competitive multiplayer configurations.
- Casual Gamers:Spontaneous participation without pre-booking requirements favors low-friction access points with minimal orientation overhead.
Families constitute the volume base, while Corporate Clients is climbing the fastest on event rental expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export VR motion platforms to family entertainment centers across the United States and Japan, establishing the dominant trade corridor in location-based immersive hardware.
United States
FCC equipment authorization requirements govern wireless tracking system deployments in metropolitan entertainment clusters. Shopping mall operators in Los Angeles and Dallas-Fort Worth are accelerating revenue-share leasing arrangements with shorter depreciation cycles than standalone arcades.
China
MIIT immersive device standards are compressing certification timelines for domestic manufacturers with in-house testing laboratories. The Yangtze River Delta concentration around Shanghai and Hangzhou hosts the majority of motion platform fabricators serving export markets.
Japan
METI safety guidelines for passenger-carrying immersive systems constrain hardware design parameters for family entertainment center procurement. Tokyo and Osaka metropolitan clusters absorb premium-tier motion simulator installations with extended durability requirements.
United Arab Emirates
Shopping mall foot traffic density in Dubai and Abu Dhabi is creating concentrated margin pools for rapid-deployment VR experiences. MOHAP regulatory alignment with international safety standards facilitates faster equipment import clearance than neighboring Gulf markets.
Germany
CE marking machinery directives for electromechanical systems extend certification cycles through third-party notified body involvement. Bavarian industrial clusters supply precision servo motor arrays to Japanese and Chinese motion platform integrators.
VR Amusement Equipment Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded technology conglomerates anchoring premium hardware segments while venture-backed operators dominate wireless free-roam venue deployments. The structure concentrates high-volume manufacturing among Asian electronics conglomerates and specialized motion engineering firms, with North American entities controlling content platform and venue operation layers. Three archetypes define competitive positioning: integrated technology conglomerates with captive hardware ecosystems, dedicated immersive venue operators with proprietary wireless architectures, and component specialists supplying precision electromechanical subsystems. Geographic expansion through franchised venue licensing and backward integration into motion platform manufacturing represent the dominant competitive moves.
Within the technology conglomerate tier, Meta Platforms Inc. and Sony Group Corporation exemplify integrated hardware-software positioning, while HTC Corporation occupies a specialist role in enterprise-grade tracking systems. Zero Latency Pty. Ltd. and Sandbox VR represent the venture-backed venue operator archetype with wireless free-roam deployment models. Hologate sits within the European specialist fabricator category.
| Leading Market Players |
|---|
| Meta Platforms Inc. |
| Sony Group Corporation |
| HTC Corporation |
| Samsung Electronics Co., Ltd. |
| Hologate |
| Zero Latency Pty. Ltd. |
| Sandbox VR |
| The Void LLC |
| Survios Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day component lead times for precision servo motor arrays concentrate pricing power with Japanese and German electromechanical specialists, compressing margin flexibility for mid-tier VR motion platform integrators dependent on external sourcing. Family entertainment center procurement teams face extended depreciation schedules when electromechanical base systems exceed six-figure unit investments, shifting volume toward self-contained wireless architectures with faster installation cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command six-figure positioning through sub-20ms latency specifications and MIIT certification documentation, while standard configurations compete on 24-month depreciation compatibility. Cost compression in mid-tier haptic peripheral bundles intensifies because gesture recognition substitution erodes attach rates. Shopping mall operators exhibit highest price sensitivity due to revenue-share leasing structures, whereas Japanese family entertainment centers demonstrate lowest sensitivity given extended durability requirements.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes amplify inbound logistics costs for Chinese motion platform fabricators serving United States and Japanese export markets. Supply concentrates in China's Yangtze River Delta, Bavarian industrial clusters, and Japanese precision component corridors. Electromechanical systems draw from specialized servo motor arrays, six-axis motion platforms, and passenger restraint mechanisms. Single-source vulnerability concentrates in German precision fabrication for sub-millimeter tracking components. Distribution runs through franchised venue licensing networks and direct procurement contracts with family entertainment center chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR amusement equipment market sits in early-cycle expansion, with metropolitan entertainment cluster network effects accelerating repeat-installation vendor penetration across tier-one urban markets.
For Market Incumbents: Secure backward integration into motion platform manufacturing to reduce dependency on Japanese and German component specialists facing ninety-day lead times. Lock proprietary wireless free-roam architectures through patent filings before venture-backed venue operators scale competing deployments. Channel control represents the critical defensive lever as shopping mall revenue-share structures displace outright purchase models. For New Entrants and Emerging Players: Lead with rapid-deployment VR experiences targeting United Arab Emirates shopping mall operators seeking minimal venue retrofit requirements. White-space concentration sits in mid-tier gesture recognition configurations for family entertainment centers in China where MIIT certification accelerates domestic manufacturer timelines. A leasing-first go-to-market angle transfers obsolescence risk while capturing recurring revenue streams. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates with captive VR hardware divisions underutilized within broader consumer electronics portfolios. Long-term viability hinges on content refresh platform economics rather than one-time equipment sales. Monitor venue utilization rate divergence between wireless free-roam installations and tethered cabinet systems as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Free-Roam Architecture Patenting | Proprietary tracking systems lock premium out-of-home positioning against venture-backed venue operators. |
| In-House MIIT Testing Laboratory Investment | Domestic Chinese manufacturers compress certification timelines for motion simulator export contracts. |
| Revenue-Share Leasing Platform Launch | Shopping mall operators in Dubai and Abu Dhabi transfer obsolescence risk while accelerating deployment velocity. |
| Haptic-Audio Convergence R&D Program | Force-feedback seating with spatial arrays enables premium pricing for narrative-driven location-based experiences. |
| Franchised Venue Licensing Expansion | Zero Latency and Sandbox VR models demonstrate scalable geographic replication with reduced capital intensity. |
Research Methodology
Desk research of SEC equipment manufacturer filings, MIIT certification registries, and venue operator procurement databases preceded structured interviews with family entertainment center operations directors, motion platform R&D engineers, and shopping mall asset managers. Primary fieldwork with Japanese METI compliance consultants and German component supplier sales teams validated technical specifications and lead-time assumptions. Secondary sources included customs trade data for VR motion platform exports, FCC equipment authorization records, and GB standard documentation for electronic amusement devices. Bottom-up unit economics modeling triangulated against top-down metropolitan entertainment cluster spend analysis.
Variance decomposition across product type, technology modality, end-user venue category, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from equipment installation unit trajectories, content refresh cycle frequencies, and venue throughput capacity assumptions. Industry-specific forecast inputs incorporated MIIT certification timeline compression effects and shopping mall tenant turnover rate correlations with leasing model adoption.
The analysis sits within stated boundaries; outcomes outside sustained metropolitan foot traffic recovery or accelerated gesture recognition substitution would require recalibration. Forecasts reflect assumptions regarding wireless tracking system FCC authorization timelines and Japanese METI safety guideline stability. Regulatory divergence in China's immersive device content ratings or supply disruption in Bavarian precision servo motor corridors represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market