
 Internet of Things (IoT) in Retail Market | 2026-2036
Internet of Things (IoT) in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) in Retail Market Intelligence
A shift from single-vendor, on-premise systems toward multi-cloud hybrid deployments is repositioning the competitive landscape for IoT retail solutions. Amazon Web Services leverages its vast cloud infrastructure to offer scalable platforms for retailers of all sizes. SAP specializes in integrating IoT data directly into enterprise resource planning and supply chain management systems. Cisco Systems provides the foundational networking hardware and security layers essential for connecting in-store devices.
Internet of Things (IoT) in retail involves a network of interconnected physical devices, from RFID tags to BLE beacons, that collect and exchange data to enhance store operations. Its primary purpose is to transform real-world actions into digital insights for inventory accuracy and customer engagement. While cloud-based deployment models remain standard, edge computing is gaining traction for low-latency applications like payment automation. Within solutions, inventory management represents a foundational use case, whereas customer analytics offers the highest margin potential for specialty outlets.
Data governance is a critical factor, with regulations like Europe's GDPR and China's Personal Information Protection Law (PIPL) setting strict rules for consumer data collection and use. These frameworks compel retailers to adopt privacy-by-design principles in their customer analytics and personalization engines. The key decision for retailers now centers on balancing the quest for granular customer data with the imperative of maintaining consumer trust and regulatory compliance.
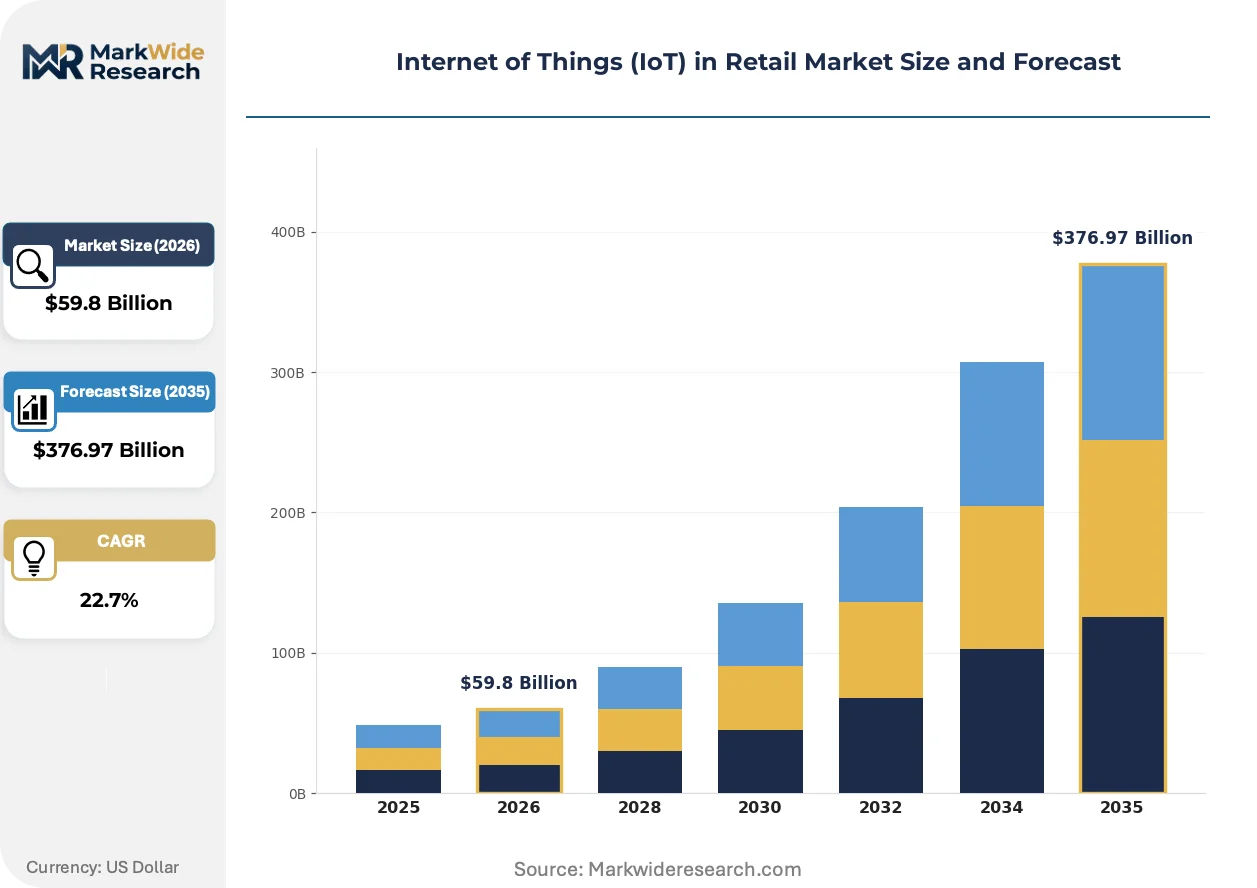
Market Dynamics
The central tension in the IoT retail market is between the drive for granular customer analytics and the tightening grip of data privacy regulations like Europe's GDPR and China's PIPL, forcing a fundamental redesign of personalization strategies.
Growth Catalysts
- Supply Chain Visibility:E-commerce growth necessitates real-time inventory tracking, driving adoption of RFID and BLE beacon technologies to optimize fulfillment from stores and distribution centers.
- Omnichannel Experience:Consumer demand for seamless click-and-collect and checkout-free shopping experiences pushes retailers to invest in smart store infrastructure for operational efficiency.
- Demand Concentration in China:Major Chinese retailers are aggressively integrating IoT, from smart shelves to robotic fulfillment, creating a concentrated hub of innovation and large-scale deployments.
Market Restraints
- High Implementation Costs:Retrofitting existing stores with a full suite of sensors, cameras, and networking hardware requires significant upfront capital investment, deterring smaller retailers.
- Interoperability and Legacy Systems:Lack of standardization across IoT vendor platforms complicates integration with retailers' existing, often proprietary, enterprise resource planning (ERP) systems.
- Regulatory Compliance Burden:Adhering to stringent data privacy frameworks like Europe's GDPR increases the complexity and cost of deploying customer-facing analytics solutions.
Strategic Opportunities
- Edge Computing for Real-Time Action:Deploying compute resources at the store edge enables low-latency applications such as autonomous checkout, dynamic pricing, and immediate loss prevention alerts.
- AI and Predictive Analytics:Converging IoT data streams with artificial intelligence allows retailers to move beyond descriptive analytics to predict stockouts, forecast demand, and identify churn risk.
- Expansion in Southeast Asia:Markets like Vietnam and Indonesia represent underpenetrated regions where rising consumer spending and mobile connectivity create new growth frontiers for retail IoT.
Industry Challenges
- Data Science Talent Scarcity:A persistent shortage of professionals with combined expertise in data analytics, IoT architecture, and the specific nuances of retail operations slows down project execution.
- Securing Device Networks:Protecting thousands of interconnected in-store devices—from sensors to cameras—from cybersecurity threats presents a significant and continuous operational challenge for IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) in Retail Market |
| Market Size in 2026 | $59.8 Billion |
| Market Size in 2035 | $376.97 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Inventory Management, Customer Analytics, Smart Shelves, Supply Chain Optimization, Personalization Engines Deployment: Cloud-based, On-premise, Hybrid, Edge Computing, Fog Computing Use Case: Asset Tracking, Demand Forecasting, Digital Signage, Payment Automation, Loss Prevention Customer Type: Department Stores, Specialty Outlets, E-Commerce Platforms, Convenience Stores, Wholesalers |
| Companies Covered | Cisco Systems, SAP, Amazon Web Services, Intel, Google Cloud, Microsoft, Oracle, NVIDIA, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) in Retail Market Strategic Shifts & Innovations
A fundamental transition is underway from deploying simple connected devices to architecting intelligent, automated retail environments. This evolution is driven by advancements in AI and a stricter regulatory climate governing data use, reshaping operational priorities.
Computer vision systems, using AI-powered cameras, are deployed to monitor on-shelf availability and analyze in-store customer traffic. Large-format grocery and big-box retailers lead adoption to improve operational oversight and reduce labor for manual tasks. This technology is automating core functions like planogram compliance and stock replenishment, allowing staff to focus on customer service.
The EU AI Act introduces risk-based rules for artificial intelligence, impacting solutions for customer profiling and dynamic pricing. The legislation requires vendors to build transparent, auditable algorithms to avoid high-risk classifications. Consequently, retailers in Europe are intensifying due diligence on AI vendor compliance, prioritizing fairness in personalization engines.
Retailers favor integrated IoT platforms that unify data over acquiring separate, single-function point solutions. This model displaces the procurement of siloed tools for inventory and analytics with scalable, cloud-based ecosystems. The preference for platforms is most pronounced among large enterprises seeking to reduce vendor complexity and build a cohesive operational data layer.
Internet of Things (IoT) in Retail Market Segmentation
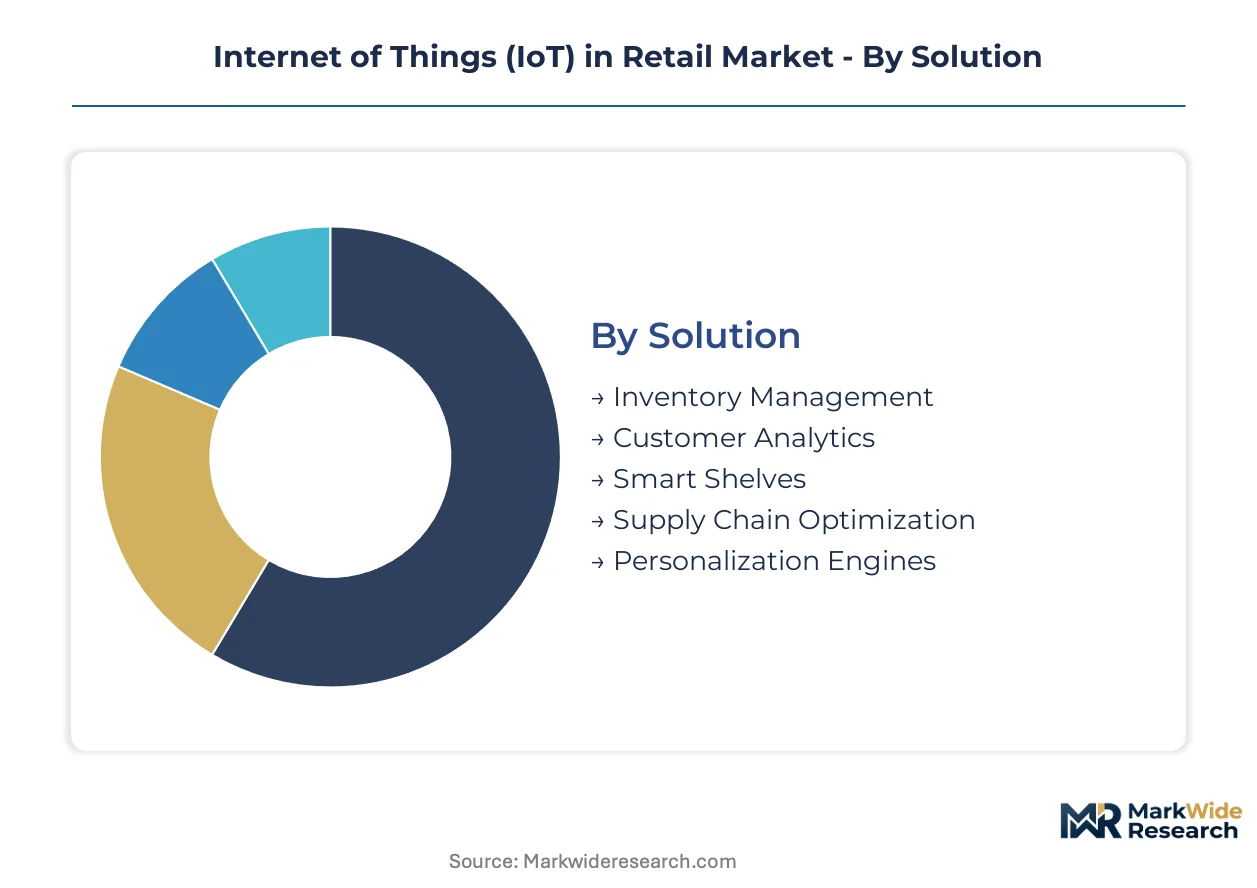
The Internet of Things (IoT) in Retail Market segmentation provides a granular view of how retailers are upgrading their operational capabilities and integrating new technologies. Understanding these distinct categories helps stakeholders identify strategic investment areas and tailor solutions for specific retail environments.
Solution:
Retailers are evaluating IoT solution categories to determine optimal upgrade paths for their existing operational frameworks, from legacy POS systems to modern cloud architectures.
- Inventory Management:RFID tags and BLE beacons provide real-time stock visibility across stores and distribution centers, crucial for maintaining accuracy. E-commerce platforms in China heavily leverage this for efficient order fulfillment and supply chain optimization, minimizing stockouts.
- Customer Analytics:AI-powered cameras and sensors capture in-store customer behavior data for personalization engines and traffic analysis. Europe's GDPR regulations compel retailers to adopt privacy-by-design principles in these solutions to maintain consumer trust.
- Smart Shelves:Integrated sensors monitor product availability and pricing dynamically, automating replenishment alerts in large format grocery stores.
- Supply Chain Optimization:IoT devices track goods in transit and storage, enhancing visibility for global retailers managing complex logistics networks.
- Personalization Engines:These platforms use collected customer data to deliver tailored promotions and product recommendations, particularly in specialty outlets.
Inventory Management sits at the top of the volume ranking, with Customer Analytics climbing the fastest.
Deployment:
The choice of IoT deployment model significantly impacts a retailer's long-term operational costs and data processing capabilities across their network.
- Cloud-based:Centralized platforms host IoT applications and data, offering scalability and reduced infrastructure overhead for retailers of all sizes. Amazon Web Services provides extensive infrastructure for these deployments.
- Edge Computing:Processing data closer to the source, such as in-store servers, enables low-latency applications like payment automation and real-time loss prevention. This model is critical for autonomous checkout systems.
- On-premise:Retailers host IoT infrastructure within their own data centers, offering maximum control but higher capital expenditure.
- Hybrid:This model combines on-premise systems with cloud resources, allowing retailers to balance sensitive data control with scalable cloud services.
- Fog Computing:This extends cloud computing to the edge of the network, distributing processing power closer to IoT devices for distributed intelligence.
Cloud-based solutions dominate the current market, while Edge Computing is demonstrating the steepest expansion trajectory due to real-time application demands.
Use Case:
IoT use cases are evolving beyond basic tracking to encompass advanced predictive capabilities, transforming how retailers manage store operations and customer interactions.
- Loss Prevention:AI-powered computer vision systems monitor store activity to detect theft and reduce shrinkage, providing immediate alerts to staff. These systems are crucial for big-box retailers.
- Payment Automation:Contactless payment systems and autonomous checkout technologies leverage IoT sensors and cameras to streamline transactions. This enhances customer experience and operational efficiency in smart stores.
- Asset Tracking:RFID and BLE tags monitor high-value items and equipment within stores, improving inventory accuracy and reducing misplacement.
- Demand Forecasting:IoT data from sales, foot traffic, and environmental sensors feeds into AI models to predict future product needs for inventory optimization.
- Digital Signage:Connected displays deliver dynamic, personalized content to shoppers based on proximity and real-time store conditions.
Loss Prevention applications are gaining significant traction, with Payment Automation solutions increasingly influencing store design.
Customer Type:
Different customer types prioritize IoT investments based on their unique operational scales, customer engagement models, and existing technological infrastructure.
- E-Commerce Platforms:These entities integrate IoT for end-to-end supply chain visibility and last-mile delivery optimization. They leverage data from distribution centers and fulfillment hubs to meet online order demands.
- Department Stores:Large physical footprints necessitate IoT solutions for comprehensive inventory management, customer flow analysis, and personalized in-store experiences. These retailers often deploy smart shelves and digital signage.
- Specialty Outlets:These retailers focus on customer analytics and personalization engines to enhance targeted marketing and unique shopping experiences.
- Convenience Stores:These implement IoT for automated inventory, loss prevention, and frictionless payment systems to improve operational efficiency.
- Wholesalers:These utilize IoT for large-scale warehouse management, asset tracking, and optimizing logistics for bulk product distribution.
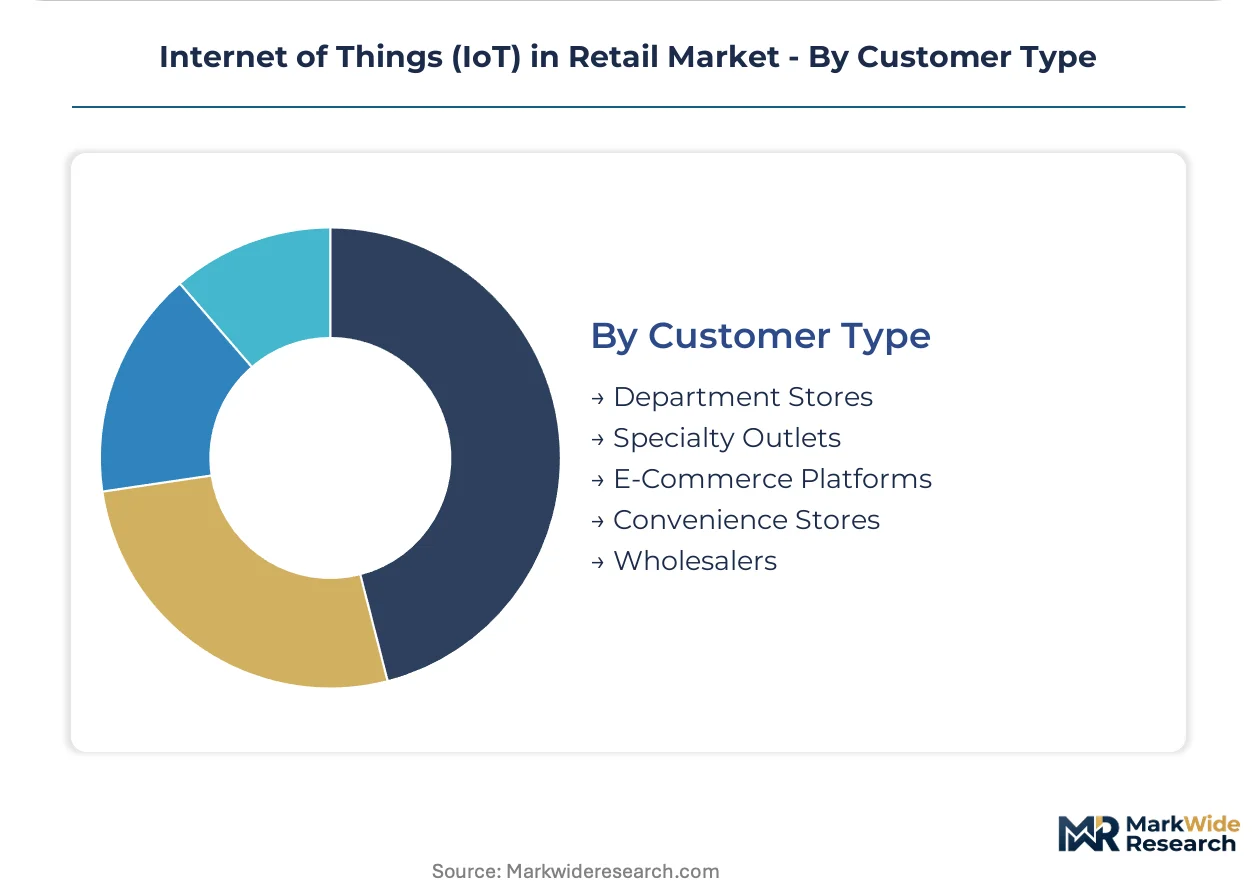
E-Commerce Platforms remain a primary investment driver, while Specialty Outlets are driving innovation in customer personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The evolving landscape of data privacy regulations creates a regulatory-arbitrage dynamic for IoT retail deployments. Retailers in regions with stringent frameworks like Europe's GDPR are adopting privacy-by-design principles, influencing solution development. This shift encourages innovation in anonymized data analytics or redirects investment to less regulated markets.
China
Demand for smart store technologies is high, driven by major retailers integrating IoT for efficiency. China's Personal Information Protection Law (PIPL) mandates strict data handling, influencing customer analytics solutions. Cities like Shenzhen lead in robotic fulfillment and smart shelf deployments, showcasing advanced retail automation.
United States
Omnichannel retail experiences necessitate IoT investments for seamless click-and-collect and inventory management. Federal Trade Commission (FTC) guidelines on data privacy shape how customer data is collected and utilized. Silicon Valley companies and major retail hubs like New York City drive innovation in AI-powered computer vision and payment automation.
Germany
Retailers prioritize supply chain visibility and operational efficiency with IoT, particularly in large-format grocery stores. The EU AI Act introduces risk-based rules for AI solutions, requiring transparent algorithms for customer profiling. Munich and Berlin are centers for developing edge computing applications and secure IoT platforms for retail.
India
E-commerce growth fuels the adoption of IoT for real-time inventory tracking and last-mile delivery optimization. The country's proposed Digital Personal Data Protection Bill will impact how retailers manage consumer data. Bengaluru's tech ecosystem supports the development of scalable cloud-based IoT solutions for retail logistics and customer engagement.
Vietnam
Rising consumer spending and mobile connectivity create new growth frontiers for retail IoT, focusing on localized solutions. Government initiatives to promote digital transformation encourage investment in smart retail infrastructure. Ho Chi Minh City sees increasing integration of IoT for inventory management and personalized in-store experiences.
Internet of Things (IoT) in Retail Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-driven personalization and edge computing solutions. The competitive landscape features a tiered structure, with global technology giants providing foundational infrastructure alongside specialized IoT solution providers. Three distinct strategic archetypes include cloud platform providers, enterprise software integrators, and in-store hardware and security specialists. Many companies engage in portfolio diversification and strategic partnerships to offer comprehensive, integrated retail IoT solutions.
Within the cloud infrastructure and enterprise integration tiers, Amazon Web Services exemplifies scalable cloud platforms for diverse retail needs. SAP occupies a position as a core provider integrating IoT data directly into enterprise resource planning and supply chain management systems. Cisco Systems anchors the foundational networking hardware and security layers essential for connecting in-store devices. These entities represent different yet complementary facets of the retail IoT ecosystem, each contributing specialized capabilities to the market, often through ecosystem partnerships.
| Leading Market Players |
|---|
| Cisco Systems |
| SAP |
| Amazon Web Services |
| Intel |
| Google Cloud |
| Microsoft |
| Oracle |
| NVIDIA |
| IBM |
| Others |
Cost & Logistics Intelligence
Semiconductor component pricing directly influences the cost structure of IoT devices, cascading through the supply chain to shape final solution pricing for retail deployments. This foundational input impacts tiered offerings for hardware, software, and integration services.
Pricing Analysis
Rising semiconductor and cloud infrastructure costs often pass through to retail IoT solution providers. The market primarily uses a hybrid pricing model, combining SaaS-tiered subscriptions for software platforms with project-based fees for hardware integration. Price differentiation stems from solution customization levels and comprehensive after-sales support. Pricing pressure is intensifying due to increasing competition in the basic sensor hardware segment, making convenience stores highly price-sensitive compared to large e-commerce platforms.
Supply Chain Analysis
Reverse logistics for IoT devices involves managing returns for repair, recalibration, and end-of-life recycling, particularly for high-volume sensors manufactured in China and Vietnam. Specialized components often originate from South Korea. The supply chain relies on microcontrollers, advanced sensors, and communication modules, with single-source vulnerability for specialized AI-enabled vision sensors presenting a structural risk. Distribution runs primarily through direct sales teams and specialized IT system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
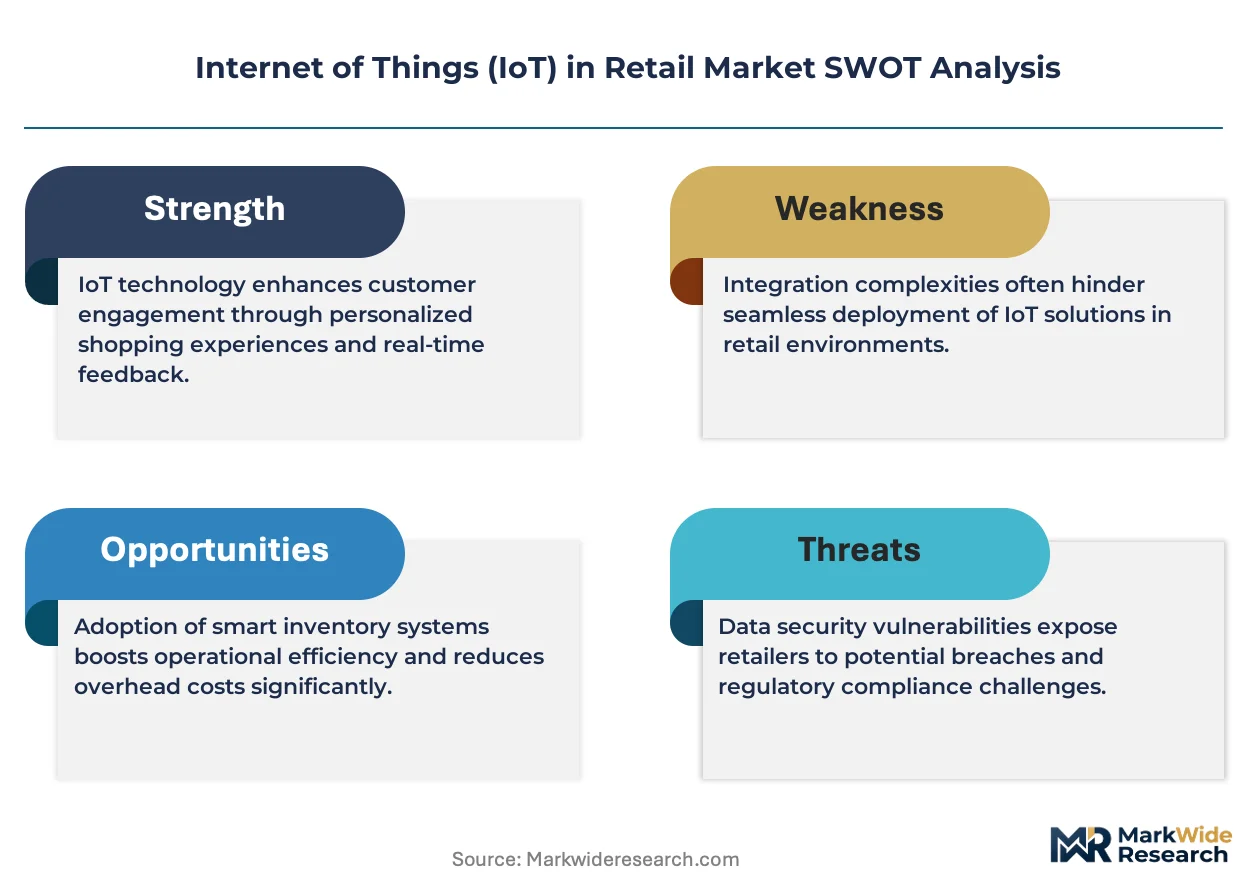
The IoT in Retail market presents a geographic-arbitrage opportunity, where stringent data privacy regulations in Europe contrast with less restrictive frameworks in Southeast Asia. This differential influences solution design and deployment priorities across regions.
For Market Incumbents: Extend existing cloud platform capabilities to encompass advanced edge computing functionalities for low-latency applications. Incumbents should acquire niche AI analytics firms to counter the threat from specialized new entrants. Deepen integration with enterprise resource planning systems to offer comprehensive data unification for large retailers. Invest significantly in R&D for privacy-preserving AI and anonymized data processing to navigate evolving regulations like the EU AI Act.
For New Entrants and Emerging Players: Launch via strategic partnerships with local system integrators in high-growth Southeast Asian markets like Vietnam. Target underpenetrated convenience stores with modular, rapidly deployable payment automation solutions. Focus on specialized outlets seeking high-margin customer analytics by offering privacy-by-design personalization engines. A compelling go-to-market angle involves demonstrating immediate ROI through operational efficiency gains.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized AI-powered computer vision firms offering real-time loss prevention and customer insights. The market demonstrates long-term viability over the next decade, driven by retailers' continuous automation needs. Acquisition targets include mid-sized companies with proven edge AI capabilities or robust data governance platforms. Investors should monitor the global adoption rate of privacy-enhancing computation technologies as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Edge AI Modules | Enables low-latency payment automation and real-time loss prevention for retailers. |
| Integrate IoT Data with ERP Systems | Provides holistic operational visibility and optimizes supply chain management for large enterprises. |
| Partner with Cloud Infrastructure Providers | Leverages scalable platforms like Amazon Web Services for diverse retail IoT deployments. |
| Acquire Niche AI Analytics Companies | Enhances customer profiling capabilities while adhering to data privacy regulations like GDPR. |
| Expand into Southeast Asian Markets | Captures new growth frontiers driven by rising consumer spending in countries like Vietnam. |
Research Approach
Direct dialogue with retail CIOs, IoT solution architects, supply chain managers, and data privacy officers provided critical qualitative insights. This primary research was validated through extensive secondary sources, including SEC filings, retail technology association reports, and academic literature on AI and IoT. A bottom-up approach aggregated data from specific use cases, while a top-down analysis assessed market size projections. This triangulation ensured robust data integrity.
Bottom-up market sizing was cross-referenced with top-down validation to establish the forecast framework across the analysis window. Segmentation dimensions modeled included solution type, deployment model, use case, customer type, and regional regulatory impact. Compound Annual Growth Rates were derived from historical trends and projected adoption rates of smart store technologies. Key forecast inputs included retail technology investment cycles and data privacy compliance costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid shifts in data privacy legislation or unforeseen technological breakthroughs. Forecasts reflect assumptions regarding retail investment priorities and technology adoption curves. Practitioners should monitor new regulatory frameworks and major cybersecurity incidents for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Cash Register Machines Market
Retail Technology
Ticket Machine Market
Retail Technology
Self-Checkout System Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Smart Shelf Market
Retail Technology
Self-Service Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
AR in Retail Market
Retail Technology
America's AI in the Retail Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Smart Shelves Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Global Smart Retail Market